
 Australia Water Treatment Chemicals Market | 2026-2036
Australia Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Water Treatment Chemicals Market Outlook
Municipal water supply is pivoting toward advanced oxidation and membrane-compatible chemistry as Australian cities confront climate-driven source volatility. Ecolab leverages its integrated service model across Sydney and Melbourne utilities to sustain recurring revenue. Kemira Oyj anchors its position in industrial water treatment through specialized coagulant formulations for mining tailings. Solenis competes aggressively in the pulp and paper sector with customized deposit control programs.
Water treatment chemicals encompass coagulants, flocculants, disinfectants, and pH control agents formulated to remove suspended solids, neutralize pathogens, and stabilize water chemistry for industrial and potable applications. Polyacrylamide-based flocculants operate at dosage ranges of 0.5–5 ppm depending on turbidity load and sludge dewatering requirements. Coagulants dominate current volume consumption across municipal and mining applications where alum and ferric chloride remain cost-effective for high-turbidity source waters. pH Control Agents represent the fastest-growing product category as reverse osmosis plants and closed-loop cooling systems proliferate across Australian industrial facilities.
TGA drinking water guidelines and state-based EPA discharge permits collectively shape product registration requirements and residual limits for treatment chemicals. The Australian Drinking Water Guidelines administered by the National Health and Medical Research Council mandate compliance testing that directly influences disinfectant selection and dosing automation investments. Stakeholders must monitor evolving PFAS remediation obligations and emerging contaminants screening protocols as regulatory thresholds tighten across jurisdictions.
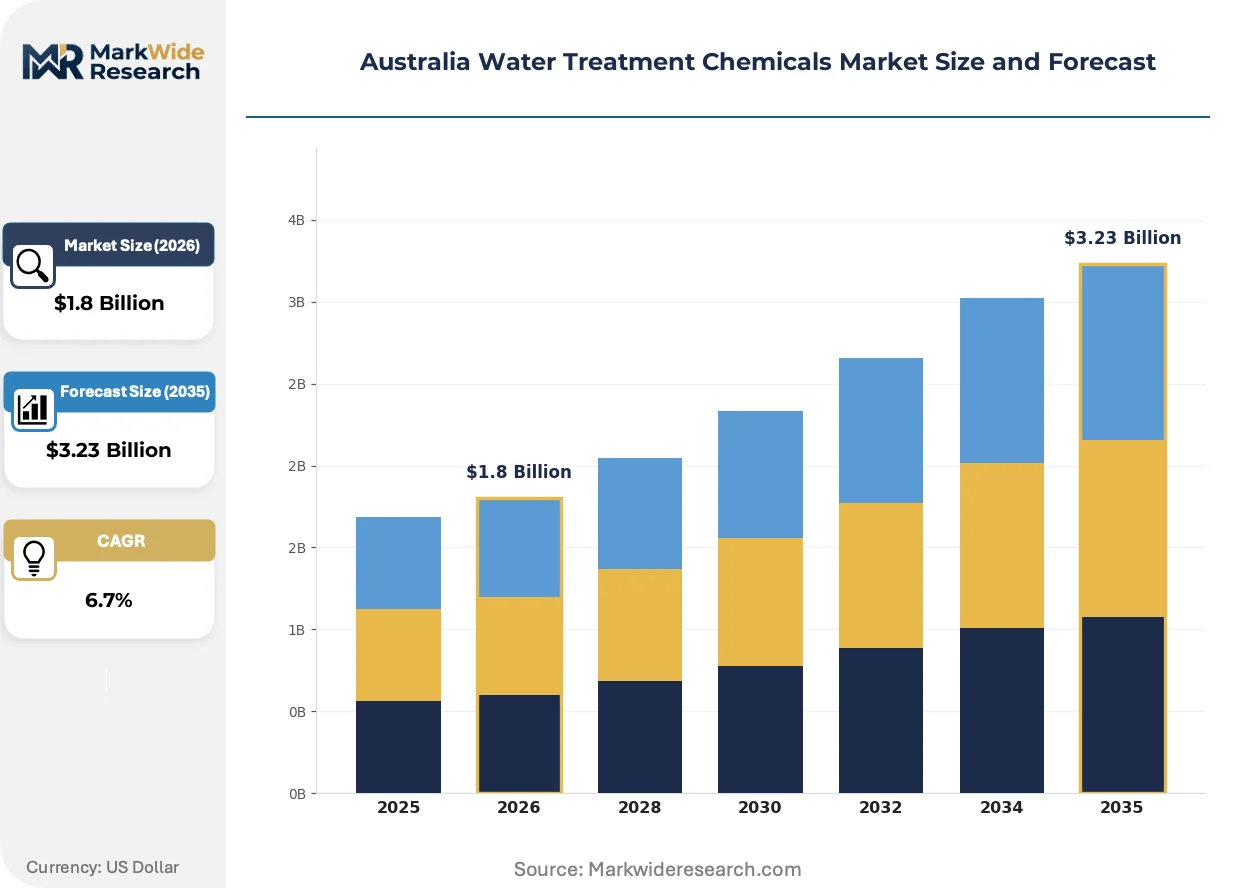
Market Dynamics
Western Australia's mining sector is driving chemical intensity upward as ore processing expands and tailings management standards tighten under state EPA discharge protocols. This structural pull from resource extraction is reshaping supplier priorities across the national market.
Growth Catalysts
- Queensland coal seam gas expansion:Hydraulic fracturing and produced water treatment require specialized biocide and scale inhibitor formulations. Operators are scaling chemical procurement to match drilling permit approvals.
- Perth desalination network dependence:The city's two major reverse osmosis plants consume membrane-compatible antiscalants and pH buffers at volumes tied to rainfall deficit cycles. Municipal procurement cycles are shortening to match climate volatility.
- TGA drinking water guideline updates:Revised residual disinfectant limits are forcing utilities toward automated dosing systems. Equipment upgrades cascade into higher-margin chemical service contracts.
Market Restraints
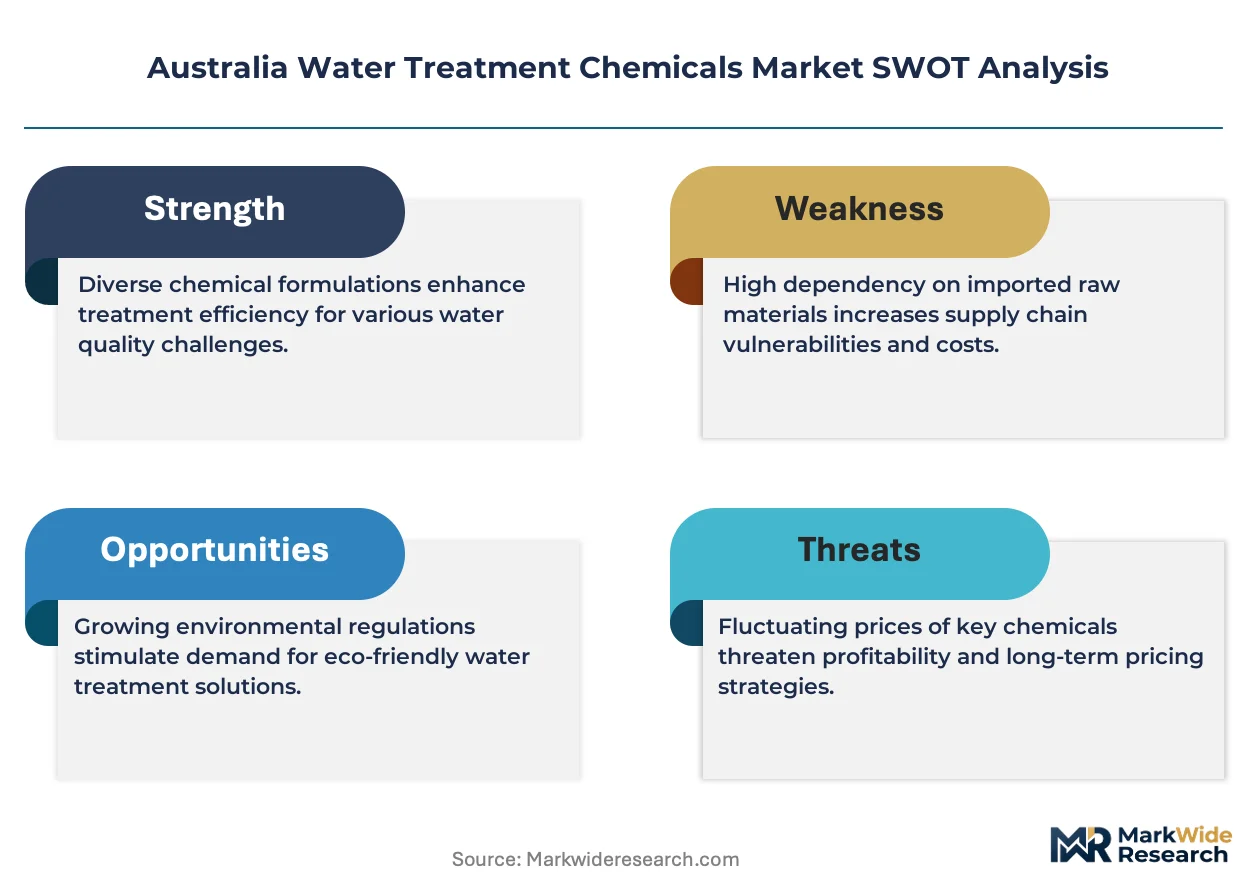
- Alumina and ferric chloride import dependence:Bulk coagulant supply concentrates on Asian chemical manufacturers. Currency fluctuations and shipping bottlenecks transmit directly into municipal treatment cost bases.
- PFAS remediation liability thresholds:Emerging contaminant screening protocols under state EPA frameworks are creating compliance uncertainty. Product registration timelines are extending as residual testing requirements multiply.
- On-site electrochemical generation:Sodium hypochlorite and chlorine dioxide generators at large industrial sites are displacing bulk chemical delivery in mining and power generation end-uses.
Strategic Opportunities
- Remote Indigenous community water security:Northern Territory and Queensland regions lack centralized treatment infrastructure. Packaged chemical dosing systems with telemetry integration address distributed demand.
- Closed-loop cooling chemistry:Data center and LNG facility expansions require corrosion inhibitors and biocides for recirculating systems. Formulation specialization commands premium positioning.
- National Health and Medical Research Council guideline harmonization:Unified testing protocols across states reduce product registration fragmentation. Suppliers with existing multi-jurisdiction compliance records capture first-mover advantage.
Industry Challenges
- Certified water treatment operator scarcity:TAFE pipeline output lags demand for chemists capable of automated system calibration and regulatory reporting. Utilities compete with mining wages for technical staff.
- Legacy dosing equipment incompatibility:Membrane-compatible chemistry requires precision injection systems. Retrofit capex at older plants delays product switching and extends sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Water Treatment Chemicals Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulants, Flocculants, Disinfectants, pH Control Agents Application: Municipal Water Supply, Wastewater Treatment, Industrial Water Treatment, Swimming Pool Treatment End User: Utilities, Industrial Facilities, Commercial Buildings, Residential Areas Distribution Channel: Direct Sales, Distributors, Online Retail, Third-Party Vendors |
| Companies Covered | Ecolab, Kemira Oyj, Solenis, SNF Group, Dow Inc., Accepta Ltd, Buckman Laboratories International Inc., Veolia Environnement SA, BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Water Treatment Chemicals Market Strategic Shifts
Automation and chemistry convergence are compressing the traditional separation between equipment and consumables. Suppliers are bundling sensor networks with formulated products to lock in recurring revenue streams.
Polyacrylamide-based flocculant chemistry is consolidating around high-molecular-weight anionic formulations optimized for mining tailings dewatering. Rio Tinto and BHP are standardizing on single-supplier programs to reduce variability in solids capture efficiency. This specification tightening is compressing the vendor base and elevating technical service intensity as a differentiator.
The Australian Drinking Water Guidelines administered by the National Health and Medical Research Council are tightening residual disinfectant monitoring frequencies. Utilities are responding with automated chlorine analyzer networks and predictive dosing algorithms. Queensland and New South Wales municipal networks are most affected, accelerating capital programs for real-time compliance verification.
Buyer concentration among super-major mining houses is compressing contract negotiation cycles and unbundling after-sales technical support. Procurement teams at BHP and Fortescue Metals Group are demanding fixed-price multi-year chemical supply with embedded laboratory services. This behavior shift is most visible in Western Australia's Pilbara region, where treatment chemical contracts now span five-year horizons with performance-linked pricing clauses.
Australia Water Treatment Chemicals Market Segmentation
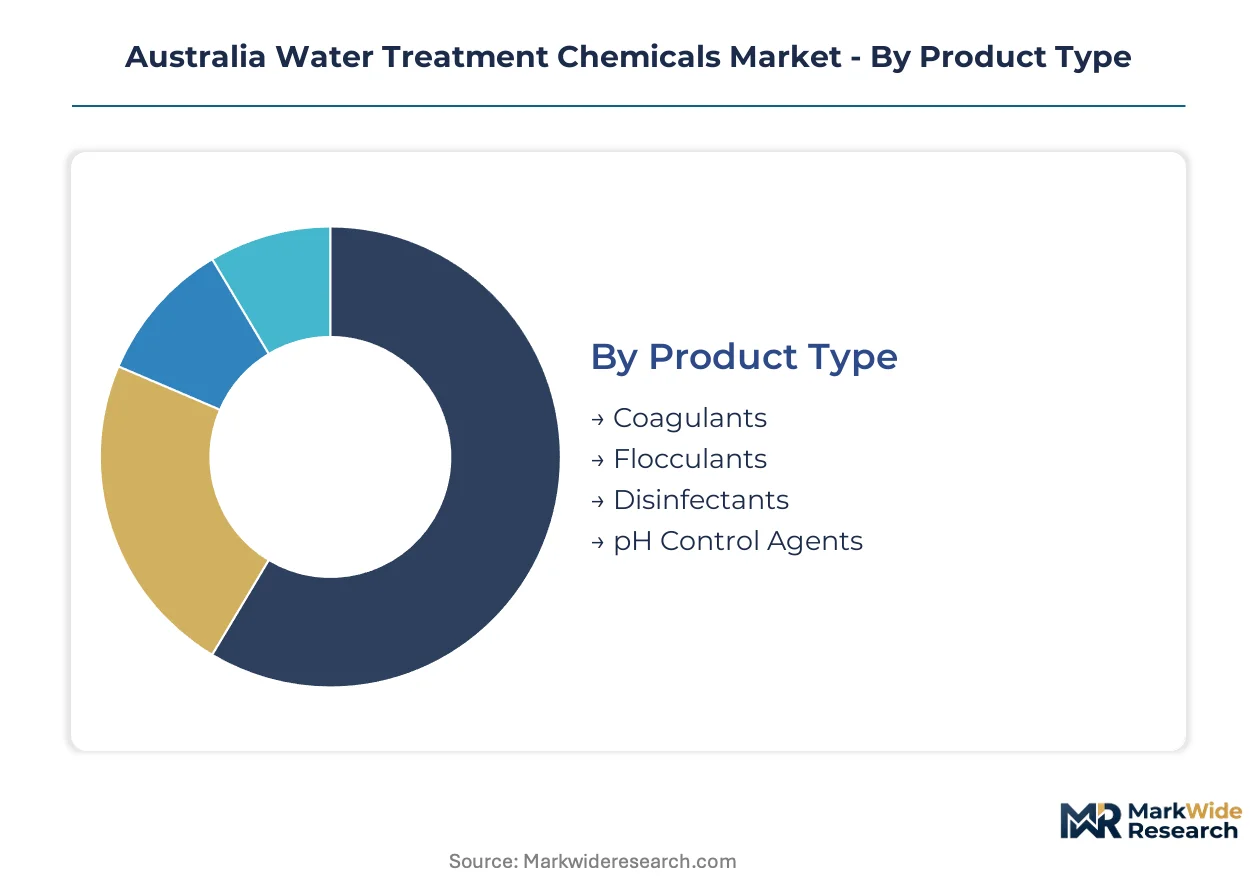
Segmentation reveals how capital deployment and technical requirements diverge across Australia's water treatment landscape. Chemical specification, delivery logistics, and regulatory compliance intensity vary sharply between mining tailings operations and municipal desalination plants.
Product Type:
Capital intensity peaks with pH control agents requiring precision injection infrastructure and continuous monitoring systems.
- pH Control Agents:Sulfuric acid, caustic soda, and carbonate buffers stabilize reverse osmosis membrane performance and cooling tower chemistry. Perth's desalination plants and Queensland LNG facilities consume these at volumes tied to feedwater alkalinity fluctuations. TGA residual limits mandate automated dosing systems that elevate total installed cost.
- Coagulants:Alum and ferric chloride formulations precipitate suspended solids in high-turbidity source waters. Western Australia's iron ore processing circuits and Sydney's Warragamba Dam filtration trains represent concentrated demand nodes. Import dependence on Asian bulk chemical manufacturers exposes municipal utilities to currency and shipping volatility.
- Flocculants:Polyacrylamide-based polymers aggregate fine particles for sludge dewatering.
- Disinfectants:Chlorine, chlorine dioxide, and chloramine formulations neutralize pathogens in potable distribution networks.
Most installed capacity flows through coagulants. Expansion is steepest in pH control agents.
Application:
Customer concentration and contract duration separate industrial procurement from municipal tender cycles.
- Industrial Water Treatment:Mining tailings management, power plant cooling circuits, and manufacturing process water demand specialized corrosion inhibitors, antiscalants, and biocide programs. BHP and Rio Tinto standardize on five-year fixed-price contracts with embedded laboratory services in Western Australia's Pilbara region. Performance-linked pricing clauses tie chemical dosing to solids capture efficiency metrics.
- Municipal Water Supply:Sydney, Melbourne, and Perth utilities operate reverse osmosis plants and conventional filtration trains requiring membrane-compatible antiscalants and automated chlorine dosing. National Health and Medical Research Council guideline revisions are accelerating capital programs for real-time residual monitoring across Queensland and New South Wales networks.
- Wastewater Treatment:Activated sludge and anaerobic digestion processes consume polymers for sludge thickening.
- Swimming Pool Treatment:Residential and commercial aquatics facilities represent fragmented, price-sensitive demand.
Contract value concentrates in industrial water treatment. Procurement velocity is highest in municipal water supply.
End User:
Technical staff availability and compliance burden scale inversely across customer tiers.
- Utilities:State-owned water corporations and municipal authorities operate multi-plant networks with centralized procurement functions. Sydney Water and Melbourne Water maintain qualified operator rosters that automated dosing systems are displacing. TAFE pipeline shortages force competitive wage escalation with mining sector employers.
- Industrial Facilities:Mining houses, LNG plants, and manufacturing sites employ captive water treatment chemists. Fortescue Metals Group and coal seam gas operators in Queensland's Surat Basin demand 24-hour technical support coverage written into supply agreements.
- Commercial Buildings:Office towers and hotels operate cooling towers and potable systems through facilities management contractors.
- Residential Areas:Individual households purchase swimming pool chemicals and point-of-use filtration consumables.
Volume aggregates at utilities. Margin expansion is strongest at industrial facilities.
Distribution Channel:
Service integration requirements and order fragmentation determine channel economics.
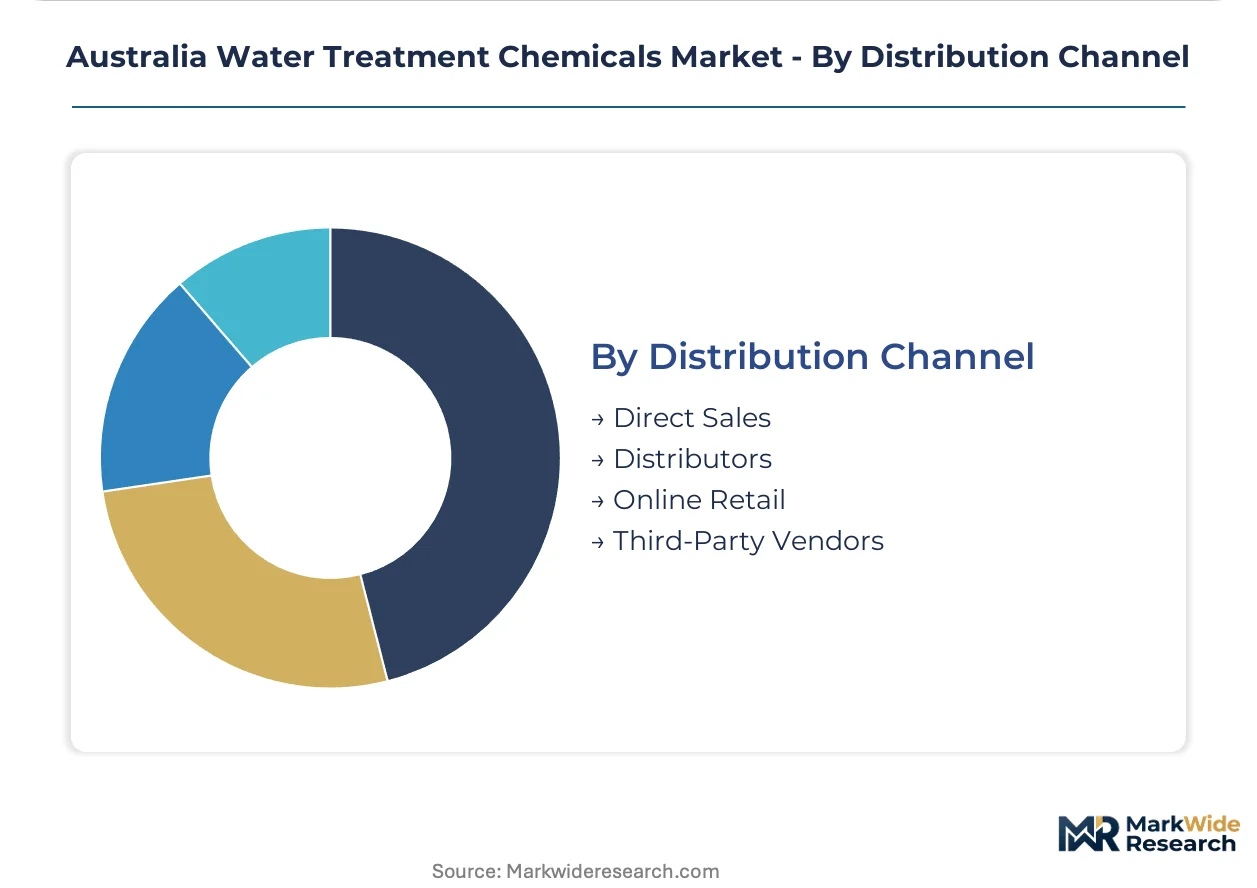
- Direct Sales:Ecolab and Kemira Oyj deploy technical service teams to anchor multi-year chemical and equipment bundles. Sydney and Melbourne utilities receive integrated sensor networks with formulated product supply. Telemetry integration locks in recurring revenue streams and raises switching costs.
- Distributors:Regional chemical wholesalers stock bulk coagulants and disinfectants for municipal tenders. Western Australian mining camps and Queensland coal seam gas fields rely on distributors for just-in-time delivery to remote sites.
- Third-Party Vendors:Independent water treatment consultants specify chemical programs for smaller industrial accounts.
- Online Retail:Packaged swimming pool chemicals and residential filtration consumables move through e-commerce platforms.
Revenue concentration sits with direct sales. Penetration is deepening fastest among distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are minimal in Australian water treatment chemicals given TGA and state EPA alignment, yet cost-of-compliance gaps between jurisdictions still redirect supplier investment toward Queensland and Western Australia where mining discharge standards are most stringent.
Western Australia
Pilbara iron ore operations and lithium processing plants drive antiscalant and pH buffer consumption at volumes tied to ore throughput expansion. State EPA tailings discharge protocols mandate advanced coagulation chemistry that elevates chemical intensity per tonne processed. Perth's two reverse osmosis desalination facilities anchor municipal demand for membrane-compatible formulations.
Queensland
Coal seam gas fields in the Surat Basin require specialized biocide and scale inhibitor programs for produced water treatment as drilling permit approvals accelerate. The state's Department of Environment and Science enforces residual disinfectant monitoring that pushes utilities toward automated dosing infrastructure. Brisbane and Gold Coast municipal networks concentrate procurement for advanced oxidation chemistry.
New South Wales
Sydney Water operates Warragamba Dam filtration trains and desalination capacity that consume ferric chloride and polyacrylamide flocculants at scale. National Health and Medical Research Council guideline revisions are forcing capital programs for real-time residual monitoring across the Hunter Valley and Illawarra regions. Mining operations in the Newcastle area add industrial demand for tailings treatment chemicals.
Victoria
Melbourne Water's multi-plant network sources membrane-compatible antiscalants for the Victorian Desalination Plant and conventional coagulants for Yarra River catchment treatment. State EPA discharge permits for manufacturing clusters in Geelong and the Latrobe Valley mandate corrosion inhibitor programs for closed-loop cooling systems. The TAFE pipeline shortage for certified operators intensifies wage competition with resource sector employers.
South Australia
The Adelaide Desalination Plant consumes sulfuric acid and caustic soda for pH stabilization at volumes linked to Murray-Darling Basin allocation volatility. BHP's Olympic Dam copper-uranium operation anchors industrial demand for specialized flotation and tailings chemistry. Remote Indigenous communities in the Anangu Pitjantjatjara Yankunytjatjara lands require packaged dosing systems with telemetry integration for distributed water security.
Australia Water Treatment Chemicals Market Competitive Environment
Service bundling dominates the current landscape as suppliers integrate sensor networks with formulated products to lock in recurring revenue. The vendor base compresses around three tiers: integrated multinational service providers, regional specialty chemical formulators, and bulk commodity distributors. Strategic archetypes include chemistry-plus-automation bundlers, mining-tailings specialists, and municipal tender-focused commodity suppliers. M&A activity and five-year fixed-price contract negotiations with performance-linked pricing clauses represent the dominant competitive moves reshaping supplier relationships.
Within the integrated service tier, Ecolab anchors multi-year chemical and equipment bundles across Sydney and Melbourne utilities through technical service team deployment. Kemira Oyj occupies a position among mining-tailings specialists with specialized coagulant formulations for Western Australian iron ore processing. Solenis exemplifies the sector-focused archetype competing in pulp and paper deposit control programs. These three represent the strategic positioning vectors—geographic integration, industrial specialization, and sector concentration—that define competitive differentiation in the national market.
| Leading Market Players |
|---|
| Ecolab |
| Kemira Oyj |
| Solenis |
| SNF Group |
| Dow Inc. |
| Accepta Ltd |
| Buckman Laboratories International Inc. |
| Veolia Environnement SA |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
Five-year fixed-price contract demands from BHP and Rio Tinto in Western Australia's Pilbara region are compressing supplier margins and forcing chemical formulators to absorb feedstock volatility through inventory hedging and backward integration into sulfuric acid production.
Pricing Analysis
Distributor margins on bulk alum and ferric chloride shipments to Queensland municipal utilities typically run 12-18 percent above direct-to-mine pricing for equivalent tonnage. Contract-based long-term offtake dominates procurement, with performance-linked pricing clauses tying chemical dosing to solids capture efficiency metrics at tailings facilities. Price differentiation rests on certification grade under TGA drinking water guidelines and embedded technical service coverage. Cost compression in standard-grade coagulants is intensifying because Asian import supply concentrates among three bulk chemical manufacturers. Municipal utilities exhibit highest price sensitivity due to ratepayer scrutiny, while mining houses prioritize reliability over unit cost.
Supply Chain Analysis
Direct-to-mine channels handle hyperscale buyer demand from Pilbara iron ore operations and Surat Basin coal seam gas fields, bypassing regional distributors for antiscalant and biocide volumes. Bulk coagulant supply draws from China, India, and Thailand, with sulfuric acid and caustic soda feedstocks anchored in Australian domestic production. Polyacrylamide polymer supply rests on acrylamide monomer imports from Asian petrochemical complexes. Single-source vulnerability concentrates in membrane-compatible antiscalant formulations where patent-protected chemistries limit qualified suppliers. Distribution runs through integrated service providers for automated dosing system bundles, while regional wholesalers serve remote Indigenous community packaged dosing programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. TGA drinking water guideline harmonization is redirecting procurement toward multi-jurisdiction compliance records and automated residual monitoring infrastructure.
For Market Incumbents: Deepen technical service team deployment to lock in recurring revenue through sensor-chemistry bundles at Sydney and Melbourne utilities. Expand captive sulfuric acid production capacity in Western Australia to defend margin position against currency-driven import volatility. Prioritize certification investment for emerging PFAS remediation protocols before state EPA frameworks finalize residual testing requirements.
For New Entrants and Emerging Players: Begin with remote Indigenous community packaged dosing systems in Northern Territory and Queensland, where centralized infrastructure gaps create distributed demand with limited incumbent presence. Target telemetry-integrated chemical programs for data center cooling chemistry expansions. Pursue partnership routes with regional distributors already embedded in Western Australian mining camp logistics networks.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialty formulators holding mining-tailings chemistry expertise and existing TGA compliance records. Long-term viability hinges on supplier consolidation around automated dosing convergence and five-year contract structures extending across the analysis window. Watch Queensland coal seam gas drilling permit acceleration as inflection indicator for biocide and scale inhibitor procurement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfuric Acid | Captive production insulates Western Australian suppliers from Asian bulk chemical shipping bottlenecks and currency swings. |
| Telemetry-Integrated Dosing Systems | Sensor networks bundled with formulated products raise switching costs at Sydney Water and Melbourne Water utilities. |
| PFAS Remediation Certification | Early compliance with state EPA emerging contaminant protocols captures first-mover advantage in product registration. |
| Remote Community Packaged Systems | Pre-assembled chemical dosing units address Northern Territory water security gaps outside centralized infrastructure reach. |
| Five-Year Fixed-Price Contracts | Performance-linked pricing clauses with BHP and Rio Tino standardize procurement and compress vendor base in Pilbara region. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with water treatment plant managers, mining procurement leads, chemical distribution channel partners, and TGA regulatory affairs specialists with secondary validation against Australian Bureau of Statistics trade data, National Health and Medical Research Council guideline publications, state EPA discharge permit databases, and SEC 10-K filings from listed chemical suppliers. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates across coagulant, flocculant, pH control agent, and disinfectant product categories.
Segment-weighting approaches applied differential growth assumptions across municipal, industrial, and wastewater treatment applications, with additional granularity for mining-tailings chemistry versus desalination membrane-compatible formulations. CAGRs were derived from regression analysis of historical procurement volumes against ore throughput expansion, rainfall deficit cycles, and drilling permit approval rates. Industry-specific forecast inputs incorporated Perth desalination plant utilization rates and Queensland coal seam gas water production ratios.
Several conditions sit outside the modeled scope, including abrupt TGA guideline revisions, currency crisis impacts on Asian import pricing, and breakthrough on-site electrochemical generation adoption displacing bulk chemical delivery. Forecasts reflect documented assumptions about regulatory stability and mining sector capital commitment continuity. Periodic stress-testing of base assumptions is recommended against state EPA enforcement intensity and federal infrastructure funding allocations for remote community water security programs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
South America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
North America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Slurry Homogenizer Tank Market
Water & Sludge Treatment
Process Water Treatment Market
Water & Sludge Treatment
Water Treatment Chemicals Market
Water & Sludge Treatment
Oil and Gas Water Treatment Chemicals Market
Water & Sludge Treatment
Water Treatment Polymers Market
Water & Sludge Treatment
China Water Treatment Chemicals Market
Water & Sludge Treatment
North America Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Feedwater Treatment Chemicals Market
Water & Sludge Treatment
Salt Water Softeners Market
Water & Sludge Treatment
South America Water Treatment Chemicals Market
Water & Sludge Treatment
Industrial Water Treatment Chemicals Market
Water & Sludge Treatment
Sludge Treatment and Disposal Equipment Market
Water & Sludge Treatment
CMP Slurry Blend and Delivery Systems Market
Water & Sludge Treatment
Asia-Pacific Drilling Waste Management Services Market