
 Zinc Hydroxide Market | 2026-2036
Zinc Hydroxide Market Size, Share, and Industry Trends Forecast 2026-2036
Zinc Hydroxide Market Analytics
Modular packaging of zinc hydroxide into pre-weighed, application-specific kits is consolidating buyer choice across pharmaceutical and agricultural channels. US Zinc leverages captive zinc refining to sustain raw material cost advantages in North American industrial-grade supply. Zochem anchors its position through R&D intensity in high-purity precipitation methods. Umicore competes on geographic dominance, operating integrated supply networks that span European pharmaceutical customers.
Zinc hydroxide is an inorganic compound with the formula Zn(OH)₂, typically produced through controlled precipitation of zinc salts with alkali hydroxides at pH 8-11, yielding a white amorphous powder with 59.6% zinc content by mass. It functions primarily as a precursor for zinc oxide production, a pharmaceutical excipient, and an agricultural micronutrient carrier. Industrial grade dominates volume throughput in coatings and plastics applications where technical specifications tolerate broader particle distributions. Pharmaceutical grade commands premium positioning due to stringent USP and EP monograph compliance requirements that constrain supplier pools. Food grade supply is accelerating fastest as fortification programs expand across processed food and beverage channels.
EPA oversight of zinc compound discharge limits shapes manufacturing site location and wastewater treatment investment for domestic producers. FDA pharmaceutical excipient guidelines and EMA GMP standards determine market access tiers, with dual-certified suppliers capturing premium contract positions. REACH substance registration obligations in Europe filter out smaller import competitors lacking dossier preparation resources. Stakeholders must monitor evolving ISO standards for food-grade mineral specifications and assess backward integration into zinc metal refining to secure supply continuity.
Market Dynamics
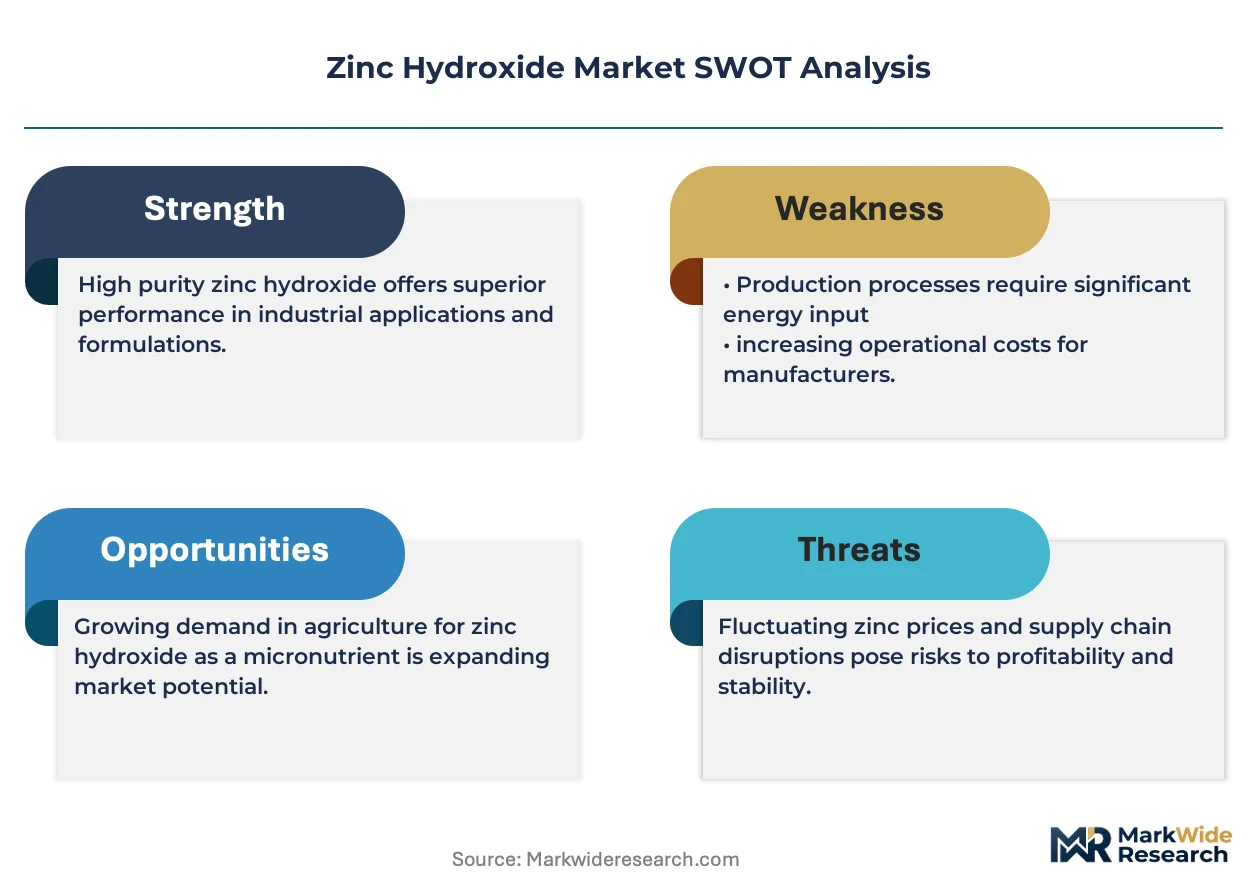
Pharmaceutical-grade certification requirements under USP and EP monographs are compressing supplier pools and redirecting procurement toward dual-certified manufacturers with captive precipitation capabilities.
Growth Catalysts
- EMA GMP enforcement:Tightened excipient purity verification across European formulation plants is disqualifying uncertified imports and consolidating offtake toward REACH-registered suppliers.
- Agricultural micronutrient programs:Soil zinc deficiency mapping in South Asia and Sub-Saharan Africa is accelerating hydroxide-based carrier adoption for controlled-release fertilizer coatings.
- Continuous precipitation systems:Automated pH-controlled reactor technology is reducing batch-to-batch variability and enabling real-time quality verification for pharmaceutical contract manufacturers.
Market Restraints
- Zinc metal price volatility:London Metal Exchange zinc price swings directly compress margin structures for non-integrated precipitators lacking long-term concentrate offtake agreements.
- Chinese supply concentration:Approximately two-thirds of technical-grade powder output originates from Shandong and Hebei provinces, creating single-source vulnerability for coatings compounders.
- Direct zinc oxide substitution:Some agricultural blenders are bypassing hydroxide precursors entirely, sourcing calcined oxide directly for animal feed premix applications.
Strategic Opportunities
- Indian pharmaceutical expansion:CDSCO's alignment with ICH Q3D elemental impurity guidelines is opening contract manufacturing slots for excipient suppliers with dedicated USP-grade lines.
- Food fortification mandates:FSSAI's micronutrient premix requirements for wheat flour and edible oils are creating new food-grade demand channels with distinct packaging specifications.
- Modular kit distribution:Pre-weighed unit-dose packaging for compounding pharmacies is bypassing traditional bulk chemical distributors and capturing premium positioning.
Industry Challenges
- Dual-certification timeline compression:Simultaneous USP and EP compliance audits require 18-24 month validation cycles that strain working capital for mid-cap precipitators.
- Wastewater treatment capex:EPA discharge limits for dissolved zinc in process effluent mandate zero-liquid-disclosure system investments at legacy precipitation sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zinc Hydroxide Market |
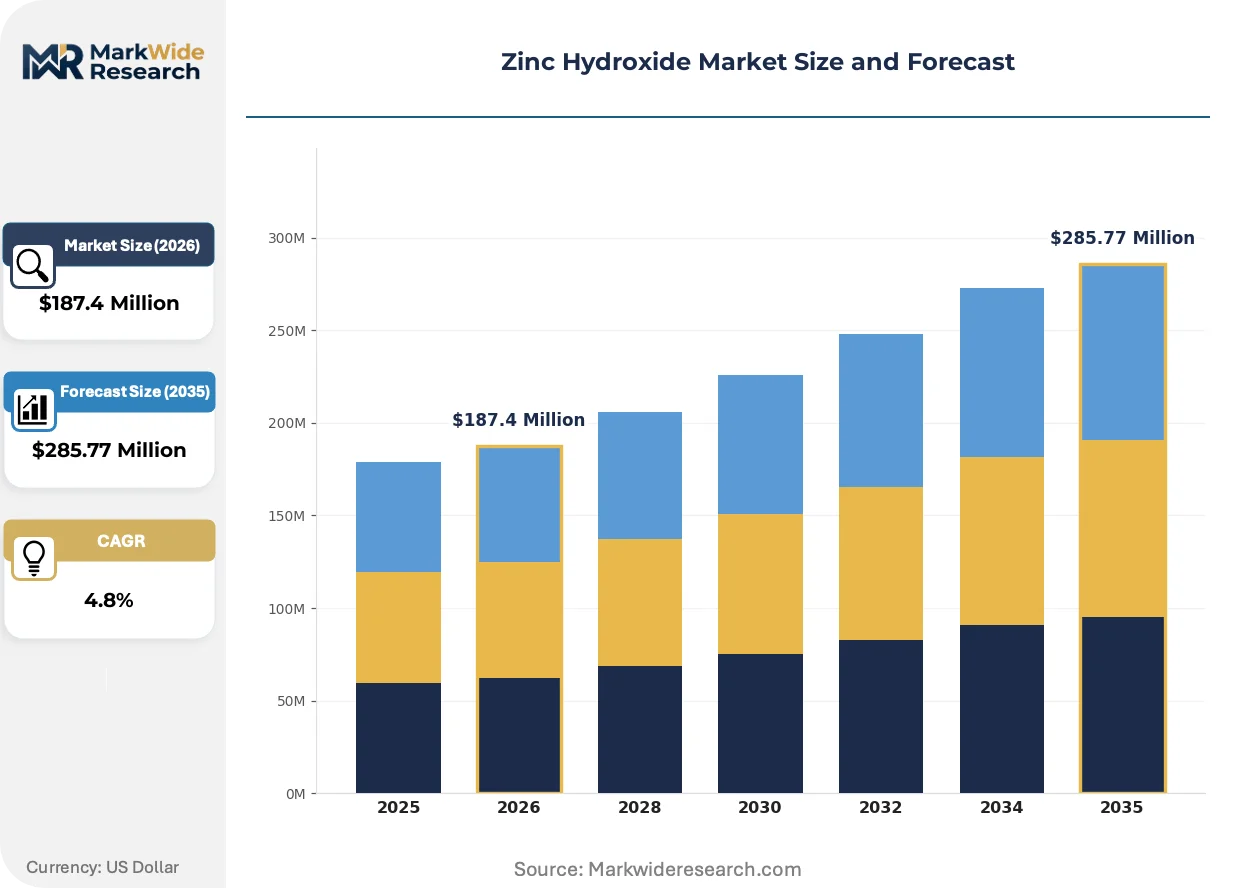
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Food Grade, Cosmetic Grade Application: Coatings, Pharmaceuticals, Agriculture, Plastics End User: Manufacturers, Distributors, Retailers, Exporters Distribution Channel: Direct Sales, Online Sales, Wholesale, Retail |
| Companies Covered | US Zinc, Zochem, Umicore, Zinc Nacional, Zinc Oxide LLC, Silox, GH Chemicals, Rubamin, Grillo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zinc Hydroxide Market Evolving Landscape
Continuous processing technology and regulatory harmonization are converging to reshape how pharmaceutical and food-grade material moves through certification, production, and distribution stages.
Membrane filtration integration with traditional alkali precipitation is electrifying impurity removal efficiency in high-purity lines. European pharmaceutical contract manufacturers are adopting these hybrid systems fastest, compressing validation-to-commercial timelines from months to weeks while locking in monograph-compliant output.
REACH substance evaluation under the 2023-2025 Community Rolling Action Plan is forcing dossier updates for zinc compounds used in polymer stabilization. German and Dutch coating compounders are pre-emptively switching to registered suppliers, while non-EU precipitators without SIEF membership face accelerating market access erosion.
Buyer consolidation among multinational pharmaceutical excipient distributors is compressing supplier panels and unbundling technical service from material supply. Large formulation houses in Germany and Switzerland now demand dedicated quality agreements with audit rights, displacing spot-market purchasing that dominated technical-grade procurement through 2020.
Zinc Hydroxide Market Segmentation
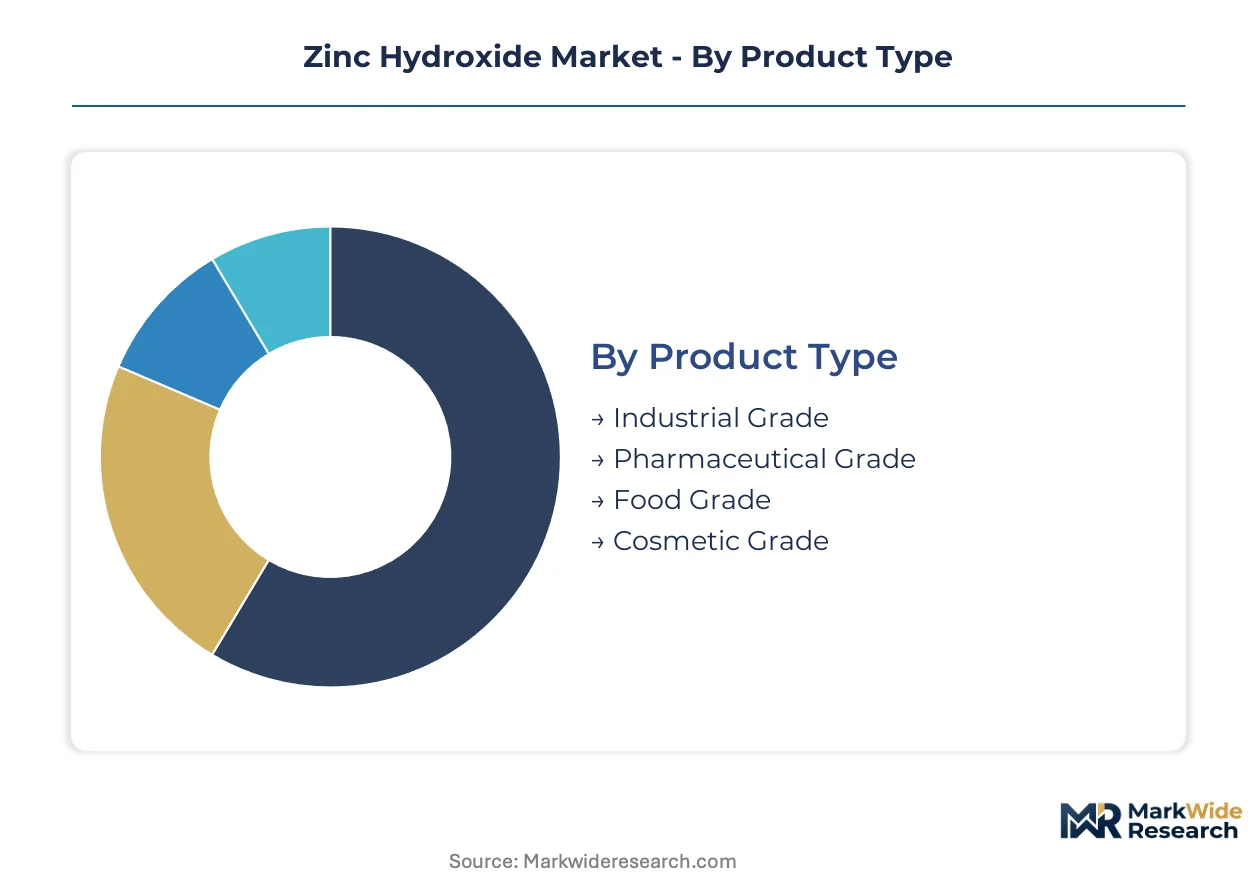
Zinc hydroxide procurement patterns diverge sharply across purity tiers and end-use specifications. Pharmaceutical and food-grade segments command certification premiums that reshape supplier economics, while industrial-grade volume flows through commodity channels with minimal technical service attachment.
Product Type:
Customization intensity escalates from bulk industrial powders to monograph-compliant excipients, with each tier demanding distinct precipitation control and validation protocols.
- Industrial Grade:Amorphous white powder with broader particle distribution tolerances, produced via standard alkali precipitation without stringent impurity controls. Demand concentrates in German coatings compounders and Chinese plastics processors sourcing through spot-market procurement. Margin compression from zinc metal price volatility limits backward integration incentives for non-captive producers.
- Pharmaceutical Grade:USP and EP monograph-compliant material with documented elemental impurity profiles under ICH Q3D guidelines. European formulation plants in Germany and Switzerland anchor offtake, with CDSCO-aligned Indian contract manufacturers emerging as secondary demand nodes. Dual-certification timelines of 18-24 months constrain supplier pool expansion.
- Food Grade:FSSAI-mandated premix applications for wheat flour and edible oil fortification.
- Cosmetic Grade:Specialized precipitation for personal care formulations with heavy metal thresholds below pharmaceutical baselines.
Leading the category by volume: Industrial Grade. Growing fastest: Food Grade.
Application:
Application-specific processing requirements segment zinc hydroxide demand by functional performance rather than chemical purity alone.
- Coatings:Industrial-grade powder functions as corrosion inhibitor and pH buffer in marine and industrial protective systems. German and Dutch compounders pre-emptively switch to REACH-registered suppliers under 2023-2025 Community Rolling Action Plan evaluations. Continuous precipitation adoption lags behind pharmaceutical channels due to lower batch consistency requirements.
- Pharmaceuticals:Excipient and active precursor applications in tablet disintegration and topical formulations. EMA GMP enforcement tightens purity verification protocols, disqualifying uncertified imports from European formulation plants. Membrane filtration integration compresses validation-to-commercial timelines for contract manufacturers.
- Agriculture:Micronutrient carrier for controlled-release fertilizer coatings addressing soil zinc deficiency in South Asia and Sub-Saharan Africa.
- Plastics:Thermal stabilizer and flame retardant synergist in PVC and polyolefin processing.
Coatings absorbs the greatest tonnage. Pharmaceuticals generates the steepest premium expansion.
End User:
Procurement sophistication escalates from spot-market distributors to integrated manufacturers with captive quality audit rights.
- Manufacturers:Formulation plants and compounders with dedicated quality agreements and supplier audit protocols. Large pharmaceutical houses in Germany and Switzerland unbundle technical service from material supply, compressing distributor panels. Continuous precipitation system investments favor direct supplier relationships over intermediated procurement.
- Distributors:Specialty chemical distributors anchoring premium-grade offtake in regional markets, particularly German nutraceutical and coatings channels.
- Retailers:Agricultural supply cooperatives and compounding pharmacy suppliers.
- Exporters:Trade intermediaries bridging Chinese technical-grade production to coatings compounders in import-dependent markets.
Manufacturers command procurement volume leadership. Distributors retain margin capture in certification-intensive tiers.
Distribution Channel:
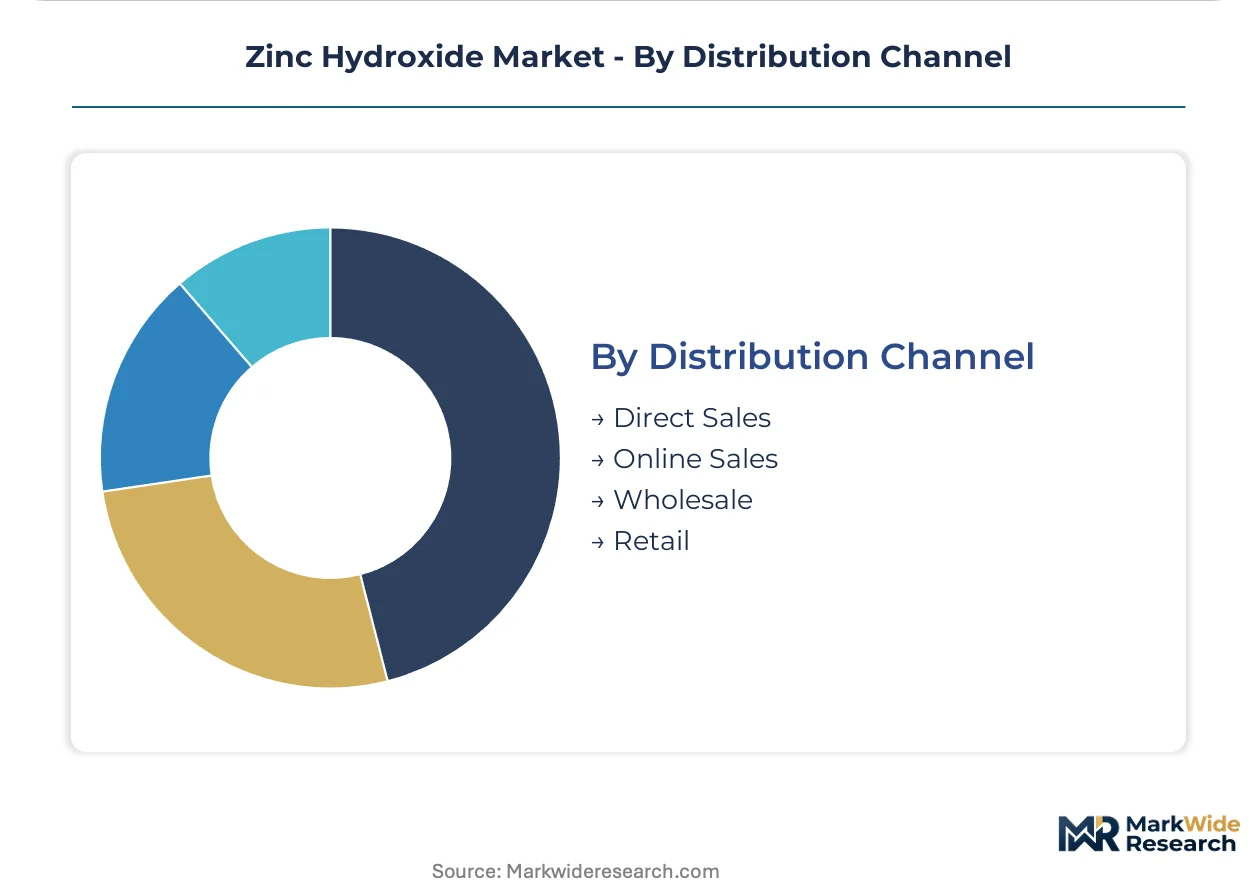
Channel selection correlates with batch size requirements and technical service intensity across purity grades.
- Direct Sales:Long-term offtake agreements between precipitators and large formulation houses, predominant in pharmaceutical and food-grade tiers. Dedicated quality agreements with audit rights displace spot purchasing that dominated technical-grade flows through 2020.
- Wholesale:Bulk industrial-grade movement through specialty chemical distributors with regional warehousing.
- Online Sales:Pre-weighed modular kits for compounding pharmacies and small-batch agricultural blenders.
- Retail:Limited to consumer-facing zinc supplement and cosmetic applications.
Direct Sales handles the largest contract value. Online Sales is climbing the fastest on modular kit adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates production of technical-grade zinc hydroxide while consumption concentrates in pharmaceutical and coatings hubs across Germany, the United States, and India. This geographic split shapes trade flows and certification requirements across supply chains.
China
Shandong and Hebei provinces host approximately two-thirds of global technical-grade powder output, serving coatings compounders and plastics processors through spot-market procurement. MEE discharge standards for dissolved zinc in process effluent are forcing zero-liquid-discharge system investments at legacy precipitation sites. Qingdao and Tianjin anchor export-oriented production clusters facing REACH-registered supplier displacement in European markets.
Germany
Specialty chemical distributors in the Ruhr region and Bavaria anchor premium-grade offtake for coatings and nutraceutical applications. ECHA REACH substance evaluation under the 2023-2025 Community Rolling Action Plan is redirecting procurement toward registered suppliers with complete dossier submissions. Frankfurt and Ludwigshafen host formulation plants demanding dedicated quality agreements with audit rights over excipient suppliers.
United States
Pharmaceutical formulation manufacturers in New Jersey and North Carolina are tightening excipient purity verification under FDA guidance. EPA discharge limits for zinc compound effluent shape manufacturing site location decisions and wastewater treatment capex requirements. Texas and Tennessee house industrial-grade consumers sourcing through captive zinc refining operations.
India
CDSCO alignment with ICH Q3D elemental impurity guidelines is opening contract manufacturing slots for excipient suppliers with dedicated USP-grade lines. FSSAI micronutrient premix requirements for wheat flour and edible oil fortification are creating new food-grade demand channels. Mumbai and Hyderabad pharmaceutical clusters are unbundling technical service from material supply and compressing distributor panels.
Switzerland
Large formulation houses in Basel and Zurich demand dual-certified pharmaceutical-grade material with documented elemental impurity profiles under ICH Q3D. Swissmedic enforcement of GMP standards for excipient suppliers is disqualifying uncertified imports from European procurement networks. The country's contract manufacturers are adopting membrane filtration integration fastest, compressing validation-to-commercial timelines.
Zinc Hydroxide Market Competitive Landscape
The competitive structure tilts toward vertically integrated zinc metal producers with captive precipitation capabilities. Mid-cap specialty chemical precipitators compete on certification breadth rather than scale. Two archetypes dominate: integrated zinc refiners leveraging raw material cost advantages, and R&D-intensive specialists competing on high-purity process control. Capacity expansion in pharmaceutical-grade lines and backward integration into zinc metal refining represent the dominant competitive moves.
Among North American integrated producers, US Zinc exemplifies the captive refining archetype. Zochem occupies a position within the R&D-intensive specialist tier. Umicore anchors the geographic dominance archetype through European network coverage. These three represent the strategic positioning spectrum: raw material security, process technology leadership, and regional market anchoring.
| Leading Market Players |
|---|
| US Zinc |
| Zochem |
| Umicore |
| Zinc Nacional |
| Zinc Oxide LLC |
| Silox |
| GH Chemicals |
| Rubamin |
| Grillo |
| Others |
Value Network & Pricing Analysis
Pharmaceutical-grade certification premiums diverge sharply from industrial-grade commodity pricing, with USP and EP monograph compliance creating a bifurcated procurement landscape where dual-certified suppliers command long-term offtake agreements while technical-grade producers compete on spot-market zinc metal pass-through. This tier divergence manifests in supply chain configurations: high-purity lines integrate membrane filtration and dedicated audit rights, whereas industrial-grade channels flow through distributors with minimal technical service attachment.
Pricing Analysis
Margin tightening in pharmaceutical-grade supply reflects the 18-24 month dual-certification timelines that constrain supplier pool expansion and lock in premium positioning for REACH-registered precipitators. Three-tier pricing structure across pharmaceutical, food, and industrial grades tracks certification burden and elemental impurity documentation requirements. Cost-down pressure on industrial-grade powder accelerates because Chinese technical-grade producers in Shandong and Hebei provinces compete on zinc metal pass-through with minimal value-add. Agricultural blenders show highest price sensitivity, bypassing hydroxide entirely for direct zinc oxide sourcing, while Swiss and German formulation plants absorb premiums for audit-ready supply security.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme for pharmaceutical manufacturing are redirecting excipient procurement toward CDSCO-aligned local producers with dedicated USP-grade precipitation lines. Supply concentrates in China for technical-grade output, Germany for specialty chemical distribution, and India for emerging pharmaceutical contract manufacturing. Raw material flows draw from London Metal Exchange zinc concentrate, alkali hydroxide reagents, and membrane filtration systems. Single-source vulnerability pervades the Shandong-Hebei production cluster that feeds two-thirds of industrial-grade powder. Distribution runs through direct sales agreements for pharmaceutical and food-grade tiers, with wholesale channels handling bulk industrial movement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification timeline compression and wastewater treatment capex requirements are forcing consolidation among mid-cap precipitators lacking captive zinc refining or dual-certification capabilities. Weaker players face displacement as EMA GMP enforcement and EPA discharge limits raise operational barriers.
For Market Incumbents: Acquire membrane filtration assets and continuous precipitation technology to compress batch-to-batch variability and defend against emerging Indian contract manufacturers with CDSCO-aligned lines. Anchor position through backward integration into zinc metal refining or long-term concentrate offtake agreements that buffer London Metal Exchange price volatility. Lock in German and Swiss formulation plants with dedicated quality agreements featuring audit rights, displacing distributor-dependent competitors. For New Entrants and Emerging Players: Specialty chemical distributors in German nutraceutical and coatings channels represent the most accessible entry point for REACH-registered supply without precipitator-level capital intensity. Target FSSAI-mandated food fortification premix applications in India, where micronutrient requirements for wheat flour and edible oils create new demand without entrenched supplier relationships. Deploy modular kit packaging for compounding pharmacies as a go-to-market angle that bypasses traditional bulk chemical distribution. For Investors and Strategic Acquirers: Re-rating potential sits with R&D-intensive specialists possessing hybrid membrane-alkali precipitation systems, given EMA and FDA tightening on excipient purity verification. Long-term viability favors producers with demonstrated dual-certification track records and zero-liquid-discharge compliance at legacy sites. Watch for CDSCO enforcement alignment with ICH Q3D guidelines as the inflection signal for Indian pharmaceutical excipient demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc Refining | Captive concentrate supply buffers London Metal Exchange price swings for precipitators. |
| Dual-Certification Capacity Expansion | Simultaneous USP and EP compliance opens European and Indian pharmaceutical contract manufacturing slots. |
| Continuous Precipitation Technology Deployment | Automated pH-controlled reactors reduce batch-to-batch variability for monograph-compliant output. |
| Modular Kit Distribution Launch | Pre-weighed unit-dose packaging captures compounding pharmacy demand outside bulk channels. |
| Zero-Liquid-Discharge System Investment | EPA and MEE effluent compliance preserves manufacturing site licenses at legacy precipitation facilities. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving precipitation plant managers, pharmaceutical procurement leads at German formulation houses, specialty chemical distribution partners, and EMA regulatory affairs specialists. Secondary sources included REACH dossier submissions, FDA pharmaceutical excipient guidance documents, CDSCO alignment notifications, SEC filings from integrated zinc producers, and customs trade flow data for zinc compound categories. Bottom-up capacity assessments and top-down demand modeling were reconciled through iterative triangulation.
Production volume data, grade-specific pricing trajectories, and end-use consumption patterns were reconciled across the projection horizon to generate segmentation outputs by purity tier, application function, and regional regulatory cluster. CAGRs were derived from weighted average growth contributions across pharmaceutical excipient, agricultural micronutrient, coatings, and food fortification demand nodes. Forecast inputs incorporated ICH Q3D elemental impurity guideline adoption timelines, FSSAI fortification mandate expansion, and REACH substance evaluation waves under the Community Rolling Action Plan.
Several conditions sit outside the modeled scope, including abrupt London Metal Exchange zinc price dislocations, unilateral regulatory suspensions of excipient approvals, and force majeure disruptions to Chinese technical-grade production clusters. Forecasts reflect assumptions regarding certification timeline stability and wastewater treatment capex execution rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Nickel Nano Powder Market
Metals & Minerals
Global Magnesium Carbonate Minerals Market
Metals & Minerals
Solder Materials Market
Metals & Minerals
Global Antimony Market
Metals & Minerals
Pre-Painted Galvanised Iron (PPGI) Market
Metals & Minerals
Dolomite Market
Metals & Minerals
Gold Recycling Market
Metals & Minerals
Garnet Market
Metals & Minerals
North America and EMEA Ferrosilicon Market
Metals & Minerals
Middle East and Africa Aluminum Extrusion Market
Metals & Minerals
Rare Earth Elements Market
Metals & Minerals
Global Magnesium Oxide Market
Metals & Minerals
Global Lithium Market
Metals & Minerals
Diamond Market
Metals & Minerals
India Colored Gemstones Market
Metals & Minerals
Titanium Ore Market