
 Global Mining Metals Market | 2026-2036
Global Mining Metals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mining Metals Market Analysis
Energy sector buyers is reorganizing procurement priorities toward copper and aluminum for grid infrastructure and battery supply chains. BHP Group leverages its Western Australian iron ore and Chilean copper assets to sustain long-term contract volumes with Asian smelters. Rio Tinto anchors its competitive position through autonomous haulage systems and low-carbon aluminum pilot programs in Quebec and Iceland. Vale competes on Brazilian iron ore grade quality while navigating tailings dam remediation requirements.
Mining metals encompass naturally occurring metallic elements and their refined derivatives extracted through open-pit, underground, or in-situ leaching operations, with copper cathodes typically achieving 99.99% purity via solvent extraction and electrowinning for electrical conductivity applications. Iron ore dominates by tonnage across seaborne trade routes, while copper concentrates command premium pricing tied to benchmark treatment charges and refining terms. Aluminum smelting clusters around regions with stranded hydroelectric or geothermal power assets due to energy intensity exceeding 13,500 kWh per metric ton. Sustainable extraction technologies represent the fastest-growing technology segment as pressure mounts to reduce Scope 3 emissions across mineral processing and metal extraction workflows.
The EPA enforces Clean Air Act standards on US smelter emissions, while REACH and the EU Green Deal constrain European import eligibility based on lifecycle carbon footprints. China's MEE implements dual carbon goals through GB emissions standards for domestic mining operations and cross-border concentrate imports. Stakeholders must monitor evolving carbon border adjustment mechanisms and their cascading effects on treatment charges, concentrate blending strategies, and regional smelter competitiveness.
Market Dynamics
Carbon border adjustment mechanisms and Scope 3 emissions accounting are compressing smelter margins and rerouting concentrate flows toward jurisdictions with verifiable low-carbon power sources.
Growth Catalysts
- EU Green Deal carbon border adjustments:European import eligibility rules now reward lifecycle-certified metal shipments, pulling investment toward hydro-powered aluminum smelters in Quebec and Iceland.
- Grid infrastructure electrification:Copper cathode demand from transmission utilities and EV battery manufacturers is tightening concentrate markets and extending long-term offtake contract durations.
- Autonomous haulage deployment:Rio Tinto and BHP Group are retrofitting Western Australian iron ore fleets with driverless trucks, compressing unit operating costs and extending mine life.
Market Restraints
- Energy input cost volatility:Aluminum smelting requires over 13,500 kWh per metric ton, exposing producers to stranded hydroelectric availability and European natural gas price spikes.
- Chilean copper concentrate concentration:Three state-owned and integrated miners control critical porphyry deposits, creating bottleneck risk for Asian custom smelters dependent on spot concentrate markets.
- Tailings dam technical limitations:Brazilian iron ore operations face restricted expansion until dry stacking and filtered tailings systems achieve regulatory approval under stricter dam safety protocols.
Strategic Opportunities
- Indonesian nickel laterite processing:HPAL and RKEF facility construction is attracting battery supply chain investment ahead of projected cathode active material demand expansion.
- US Inflation Reduction Act domestic content bonuses:Critical mineral extraction and processing tax credits are redirecting capital toward Arizona copper projects and North American rare earth separation.
- Blockchain-integrated provenance tracking:Converging distributed ledger technology with assay certification is enabling premium pricing for conflict-free and carbon-labeled metal shipments into German automotive supply chains.
Industry Challenges
- Electrowinning technician scarcity:Solvent extraction and electrowinning operations in Chile and Zambia face recruitment gaps as experienced operators retire without sufficient apprenticeship pipeline replacement.
- Legacy SCADA integration complexity:Autonomous haulage and predictive maintenance systems require retrofitting 1990s-era control architectures without disrupting continuous 24-hour pit operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mining Metals Market |
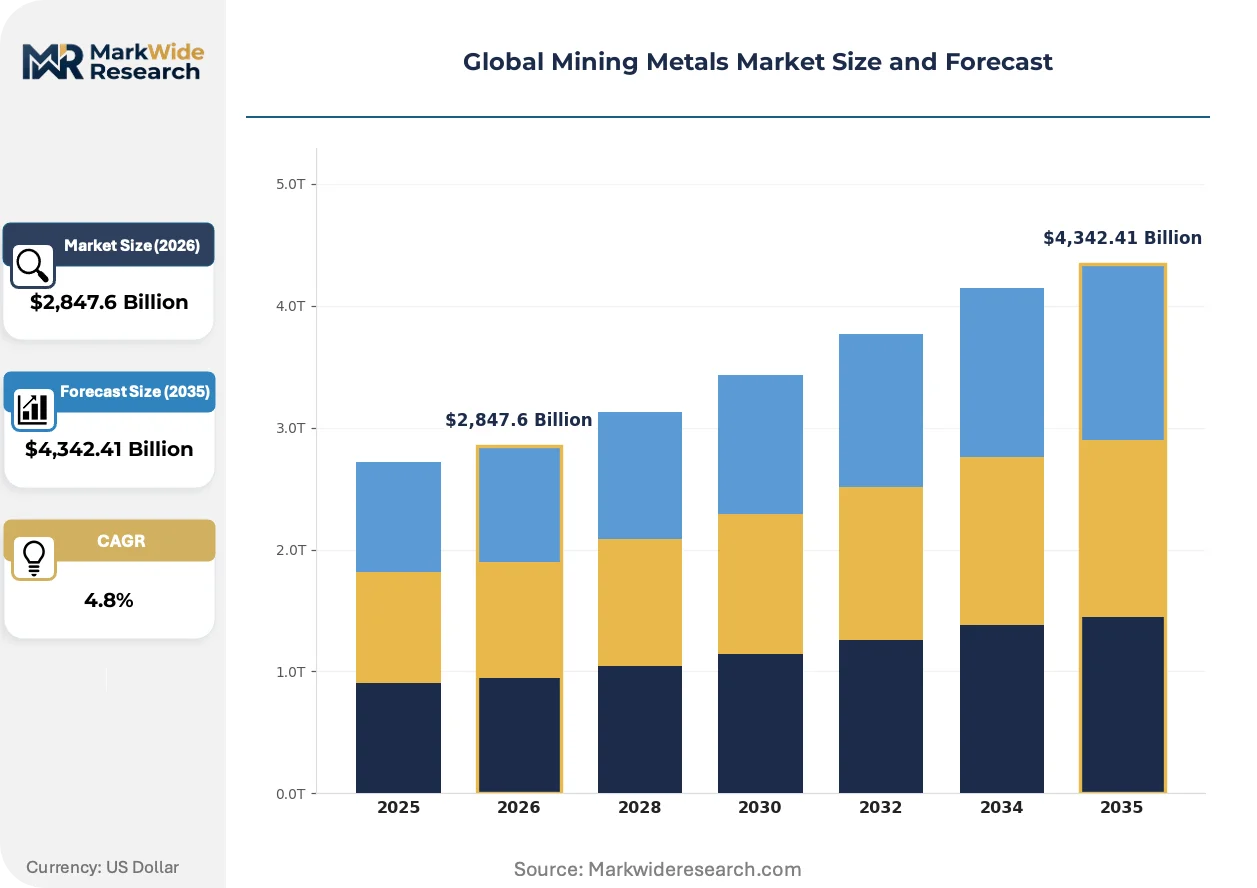
| Market Size in 2026 | $2,847.6 Billion |
| Market Size in 2035 | $4,342.41 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Copper, Iron Ore, Zinc End User: Construction, Automotive, Aerospace, Energy Technology: Hydraulic, Mechanical, Electric, Sustainable Application: Mineral Processing, Metal Extraction, Smelting, Recycling |
| Companies Covered | BHP Group, Glencore, Rio Tinto, Barrick Gold, Zijin Mining, Jiangxi Copper, Anglo American, Vale, Newmont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mining Metals Market Emerging Trajectories
Digital twin implementations and sensor fusion networks are compressing decision cycles from geological modeling through concentrate blending, while regulatory emissions verification is hardening into a tradable attribute.
In-situ recovery and bioleaching circuits for low-grade copper deposits are miniaturizing extraction footprints and reducing surface disturbance. Chilean state miners are piloting these systems at exhausted open-pit margins. The technology is compressing capital intensity thresholds for marginal ore bodies previously classified as subeconomic.
China's MEE dual carbon goals and GB emissions standards are tightening discharge permits for domestic smelters and cross-border concentrate imports. Treatment charges are compressing as Chinese refiners prioritize low-carbon certified feedstock. Indonesian nickel processing investments are accelerating to bypass future carbon-border eligibility restrictions.
Long-term offtake contracting is displacing spot market exposure for battery-grade metal procurement. Automotive OEMs are locking ten-year copper cathode and Class 1 nickel supply directly with miners, bypassing traditional merchant trading houses. This pattern is most visible in German and South Korean EV battery supply chain negotiations.
Global Mining Metals Market Segmentation
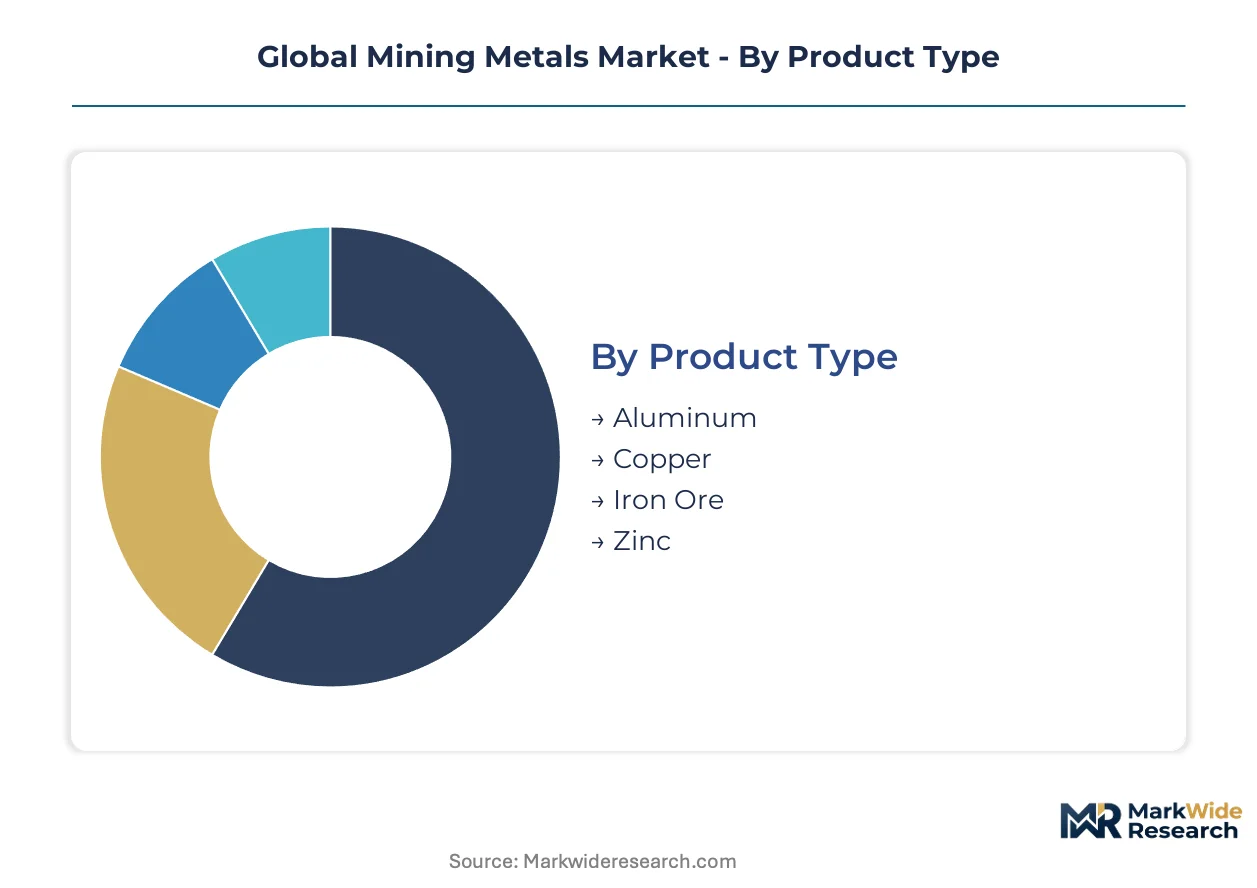
Segmentation in mining metals reveals how margin pools shift between bulk commodities and specialty grades. Procurement patterns diverge sharply across end-use sectors, with energy buyers prioritizing conductivity specifications while construction emphasizes structural tensile strength.
Product Type:
Margin concentration sits with copper and aluminum where energy transition demand compresses treatment charges and smelter premiums.
- Aluminum:Primary metal produced via Hall-Héroult electrolysis with purity grades from 99.5% to 99.99% for aerospace and electrical applications. Demand concentrates in Quebec and Iceland smelters serving German automotive OEMs as EU Green Deal carbon border adjustments tighten import eligibility.
- Copper:Cathode output reaching 99.99% purity through solvent extraction and electrowinning, with concentrate markets tightening around Chilean porphyry deposits. Grid infrastructure electrification in China and battery supply chain procurement are extending long-term offtake contract durations.
- Iron Ore:Hematite and magnetite grades traded on seaborne routes with 62% Fe benchmark pricing.
- Zinc:Refined metal from roast-leach-electrowin circuits serving galvanizing and die-casting applications.
The dominant share belongs to iron ore by tonnage, while copper is closing the gap fastest on value terms.
End User:
Application intensity varies dramatically, with energy sector procurement reorganizing toward grid metals while automotive locks in battery supply chain offtake.
- Construction:Structural steel and rebar consumption driven by urban infrastructure buildouts in China and India.
- Automotive:Battery-grade nickel and copper cathode demand from EV manufacturers. German and South Korean OEMs are negotiating ten-year direct supply contracts with miners, bypassing traditional merchant trading houses.
- Aerospace:High-strength aluminum alloys and titanium specifications requiring certified melt sources.
- Energy:Copper and aluminum procurement for transmission utilities and renewable generation infrastructure. China's State Grid and European TSOs are compressing concentrate markets with accelerated conductor installation timelines.
Construction maintains volume leadership, though energy procurement is expanding most quickly.
Technology:
Capital deployment tilts toward electrification and emissions reduction as power costs and carbon accounting reshape operating economics.
- Hydraulic:Legacy shovel and haul truck systems in mature open-pit operations.
- Mechanical:Conventional crushing, grinding, and flotation circuits with established maintenance protocols.
- Electric:Trolley-assist haulage and battery-electric underground equipment reducing diesel consumption. BHP Group and Rio Tinto are retrofitting Western Australian iron ore fleets with autonomous electric trucks.
- Sustainable:In-situ recovery, bioleaching, and dry-stack tailings technologies miniaturizing extraction footprints. Chilean state miners are piloting these systems at exhausted open-pit margins previously classified as subeconomic.
Electric systems command growing capital allocation, while sustainable extraction is gaining share fastest on investment momentum.
Application:
Downstream value capture concentrates in refining and recycling where purity premiums and circular content requirements create defensible margin positions.
- Mineral Processing:Comminution, flotation, and gravity concentration upgrading run-of-mine ore to concentrate specifications. Chinese smelters are prioritizing low-carbon certified feedstock as MEE dual carbon goals tighten discharge permits.
- Metal Extraction:Hydrometallurgical and pyrometallurgical recovery of payable metals from concentrate. Indonesian HPAL and RKEF facilities are attracting battery supply chain investment ahead of cathode active material demand expansion.
- Smelting:High-temperature reduction and refining producing LME-deliverable cathodes and ingots.
- Recycling:Secondary aluminum and copper recovery from post-consumer and industrial scrap. EU Green Deal circular economy mandates are hardening recycled content requirements for automotive and construction procurement.
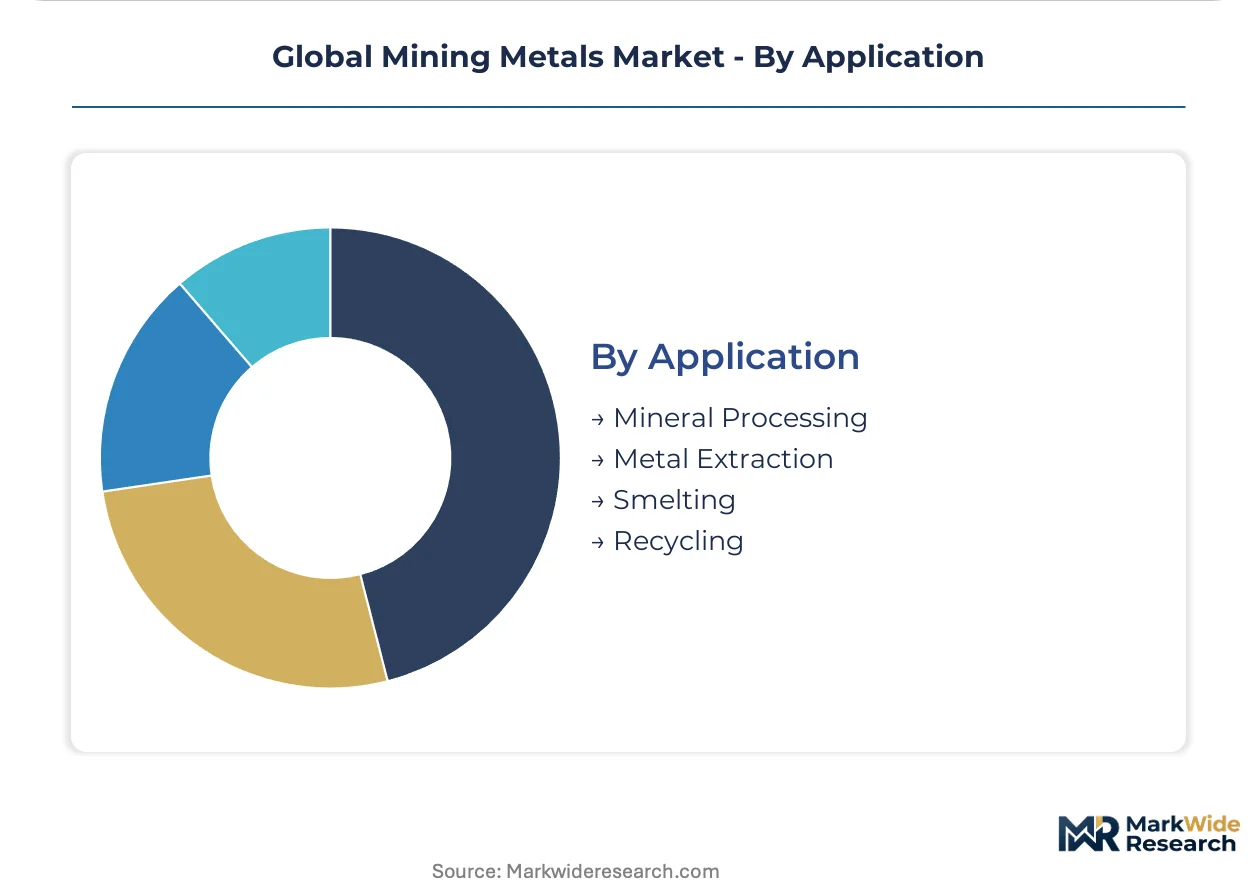
Smelting retains the dominant value-add position, while recycling is climbing the fastest on regulatory-driven capacity expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Critical ore reserves and processing capacity concentrate in Australia, Chile, and China, with these three countries controlling the dominant share of seaborne iron ore trade and copper concentrate supply. Smelter investment is migrating toward jurisdictions with stranded hydroelectric assets as carbon border mechanisms harden import eligibility criteria.
Australia
Western Australia's Pilbara region hosts the world's largest iron ore export infrastructure, with autonomous haulage fleets now operating across multiple mine sites. The country's Clean Energy Regulator administers safeguard mechanisms that tighten emissions baselines for large mining facilities. Perth-based engineering clusters are deploying digital twin systems for predictive maintenance across remote operations.
Chile
State-controlled and integrated miners dominate porphyry copper deposits in the Atacama Desert, supplying Asian custom smelters with concentrate cargoes. The Ministry of Environment enforces stricter tailings dam safety protocols under updated regulations following past failures. Antofagasta and Calama sub-regions concentrate SX-EW operations where electrowinning technician shortages are intensifying.
China
State Grid and battery manufacturers are compressing copper cathode markets through accelerated procurement for transmission and EV supply chains. The Ministry of Ecology and Environment implements dual carbon goals through GB emissions standards that constrain domestic smelter discharge permits. Jiangxi and Yunnan provinces concentrate rare earth separation and copper refining capacity.
Brazil
Vale's Carajás iron ore operations in Pará state compete on grade quality while navigating remediation requirements for legacy tailings infrastructure. The National Mining Agency enforces filtered tailings mandates that restrict expansion until dry stacking systems achieve regulatory approval. Belo Horizonte engineering clusters are developing paste thickening technologies for dam-free waste disposal.
Indonesia
Nickel laterite processing investments in Sulawesi and Halmahera are attracting battery supply chain capital ahead of cathode active material demand expansion. The Ministry of Environment and Forestry coordinates with investment boards to streamline HPAL and RKEF facility permitting. Morowali Industrial Park concentrates integrated stainless steel and battery precursor production.
Global Mining Metals Market Vendor Landscape
Concentration sits with diversified majors controlling multi-commodity portfolios across iron ore, copper, and aluminum value chains. Tier-one players leverage long-term offtake relationships with Asian smelters and state-backed refiners. Three strategic archetypes dominate: integrated miners with captive processing assets, pure-play operators focused on single commodities, and trading houses optimizing logistics and blending arbitrage. Competitive moves center on autonomous fleet deployment and low-carbon smelter partnerships.
Among Anglo-Australian diversified miners, BHP Group and Rio Tinto exemplify the integrated archetype through Western Australian iron ore and Chilean copper asset combinations. Vale anchors the pure-play iron ore tier with Brazilian operations. Glencore occupies a distinct position as a trading-integrated model optimizing concentrate flows between Zambian copperbelt operations and European refiners.
| Leading Market Players |
|---|
| BHP Group |
| Glencore |
| Rio Tinto |
| Barrick Gold |
| Zijin Mining |
| Jiangxi Copper |
| Anglo American |
| Vale |
| Newmont |
| Others |
Supply Flow & Price Mechanics
Western Australian iron ore export capacity exceeding one billion annual tonnes compresses unit operating costs and establishes price floors that marginal producers in West Africa and Canada struggle to match. Chilean copper concentrate premiums and Chinese smelter treatment charges fluctuate inversely with port inventory levels at Qingdao and bonded warehouse stocks in Shanghai.
Pricing Analysis
Three-tier pricing structure across long-term offtake contracts, annual benchmark settlements, and spot cargo auctions differentiates copper concentrate and iron ore transactions. Price differentiation rests on LME-certified cathode purity versus unregistered blister copper, alongside carbon-intensity certification under EU Green Deal border adjustment rules. Pricing pressure stems from Chinese MEE discharge permit tightening that prioritizes low-carbon feedstock procurement. Battery-grade nickel buyers in South Korea and Germany exhibit lowest price sensitivity due to decade-long supply security mandates, while Asian custom smelters face highest cost compression from concentrate scarcity.
Supply Chain Analysis
Inventory cycles at Rotterdam and Singapore warehouses signal lead-time compression for aluminum ingot and copper cathode deliveries into German automotive plants. Geographic supply concentration centers on Australia, Chile, and Indonesia for iron ore, copper concentrate, and nickel laterite respectively. Raw material dependencies include Chilean sulfuric acid for SX-EW operations, Guinean bauxite for Atlantic aluminum smelters, and Mongolian coking coal for Chinese steel mills. Supply chain risk manifests through Panama Canal drought restrictions on concentrate routes from Chilean ports to Asian refiners. Distribution runs through integrated miner-trading house partnerships that optimize blending arbitrage between Zambian copperbelt and DRC cobalt-copper ores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mining metals sector sits in early-cycle expansion as EV battery cathode active material demand accelerates ahead of installed HPAL and RKEF processing capacity in Indonesia.
For Market Incumbents: Shield long-term contract volumes through captive Chilean copper assets and Western Australian iron ore infrastructure as Indonesian nickel laterite entrants erode concentrate trading margins. Prioritize backward integration into Quebec and Iceland hydro-powered aluminum smelters to secure EU Green Deal carbon border eligibility. Accelerate autonomous haulage deployment across Pilbara operations to compress unit costs against Brazilian grade competition. For New Entrants and Emerging Players: Differentiate on blockchain-verified carbon labeling for conflict-free copper cathode shipments into German automotive supply chains. Target Arizona copper projects eligible for US Inflation Reduction Act domestic content tax credits as the most penetrable geography. Pursue direct offtake negotiations with South Korean battery manufacturers bypassing traditional merchant trading house intermediaries. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated miners with captive processing assets and stranded renewable power access over pure-play trading-dependent operators. Long-term viability across the projection horizon hinges on SX-EW technician training pipelines and dry-stack tailings regulatory approval timelines. Watch Chinese State Grid procurement acceleration as the signal for copper concentrate market tightness inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Haulage Fleet Deployment | Rio Tinto and BHP Group retrofit Western Australian iron ore operations with driverless trucks extending mine life. |
| Low-Carbon Aluminum Smelter Partnership | Hydro-powered Quebec and Iceland facilities secure EU Green Deal import eligibility for German automotive OEMs. |
| HPAL Nickel Laterite Capacity Buildout | Indonesian Sulawesi and Halmahera investments attract battery supply chain capital ahead of cathode demand expansion. |
| Blockchain Provenance Tracking Integration | Distributed ledger technology enables premium pricing for carbon-labeled metal shipments into automotive supply chains. |
| Dry-Stack Tailings System Implementation | Brazilian paste thickening technologies achieve regulatory approval under National Mining Agency dam safety protocols. |
Methodological Framework
Desk research of customs trade databases, SEC 10-K filings, and national mining agency production statistics preceded structured interviews with copper smelter procurement directors, iron ore trading house analysts, and SX-EW plant operations managers. Primary fieldwork with Chilean state miner technical teams and Indonesian HPAL project developers validated concentrate market tightness assumptions. Secondary triangulation incorporated LME warehouse stock reports, treatment charge benchmark settlements, and EU carbon border adjustment mechanism draft regulations. Bottom-up project pipeline analysis and top-down macro demand modeling were reconciled across the analytical framework.
Variance decomposition across the projection horizon isolates volume drivers from price elasticity effects within the segmentation model. The forecast framework spans product type, end-use sector, processing technology, and regional regulatory cluster dimensions. CAGRs were derived from installed capacity utilization trajectories and demand penetration curves rather than linear extrapolation. Industry-specific inputs include Chinese State Grid conductor installation timelines and European TSO renewable interconnection backlogs.
The analysis sits within stated boundaries; outcomes outside sustained EV battery chemistry adoption or abrupt carbon border mechanism implementation would require recalibration. Forecasts reflect documented assumptions regarding Indonesian nickel processing ramp schedules and Chilean porphyry deposit grade degradation curves. Commodity price volatility, sovereign resource nationalism, and electrowinning technician scarcity constitute specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Global Nickel Hydroxide Market
Metals & Minerals
Global Magnesium Market
Metals & Minerals
Solder Materials Market
Metals & Minerals
Global Magnesium Carbonate Minerals Market
Metals & Minerals
Metal and Metal Ores Market
Metals & Minerals
Coalingite Market
Metals & Minerals
Zellerite Market
Metals & Minerals
US Lithium Market
Metals & Minerals
Mineral Ingredients Market
Metals & Minerals
Pre-Painted Galvanised Iron (PPGI) Market
Metals & Minerals
Nickel Mining Market
Metals & Minerals
Tantalum Pentoxide Market
Metals & Minerals
Global Chromium Salt Market
Metals & Minerals
Manganese Market
Metals & Minerals
Global Base Metal Mining Market
Metals & Minerals
Sapphire Mining Market