
 Cobalt Sulphate Market | 2026-2036
Cobalt Sulphate Market Size, Share, and Industry Trends Forecast 2026-2036
Cobalt Sulphate Market Intelligence
Margin pools from basic cobalt sulphate refining is narrowing as value shifts toward integrated precursor cathode active material (pCAM) production. Huayou Cobalt dominates this integrated space, linking its refining operations directly to battery material outputs. Glencore leverages its vast upstream mining assets in the Democratic Republic of Congo to control raw material supply. Meanwhile, Umicore differentiates through its focus on high-purity materials and closed-loop recycling technologies.
Cobalt sulphate is an inorganic compound, typically supplied as a pinkish-red crystalline solid (CoSO₄·7H₂O). Its high solubility in water makes it an ideal precursor for synthesizing cathode materials used in lithium-ion batteries. The Battery Grade segment commands the market, with purity levels exceeding 99.8% required by electric vehicle manufacturers. Within applications, demand for Rechargeable Batteries eclipses all other uses, such as catalysts and pigments, which now constitute a niche part of the market.
Compliance with the EU's REACH regulation governs chemical registration and safety data for market access into Europe. In parallel, China’s GB standards define strict purity and impurity limits for battery-grade cobalt sulphate, influencing global production specifications. Future profitability for producers depends on their ability to navigate geopolitical supply risks and demonstrate compliance with increasingly stringent ethical sourcing and carbon footprint standards.
Market Dynamics
The market's dynamic is a conflict between concentrated raw material supply and regulatory pressure from end-markets for diversified, ethically-verified supply chains.
Growth Catalysts
- EV Battery Production:The synthesis of cathodes for electric vehicle batteries requires high-purity cobalt sulphate, tying market growth directly to automotive electrification.
- EU Battery Regulation:Mandates for recycled content and supply chain due diligence create demand for compliant material and spur investment in European recycling.
- Global Quality Standards:China’s GB standards for battery-grade materials set a de facto global benchmark, forcing producers to upgrade processes to meet purity specifications.
Market Restraints
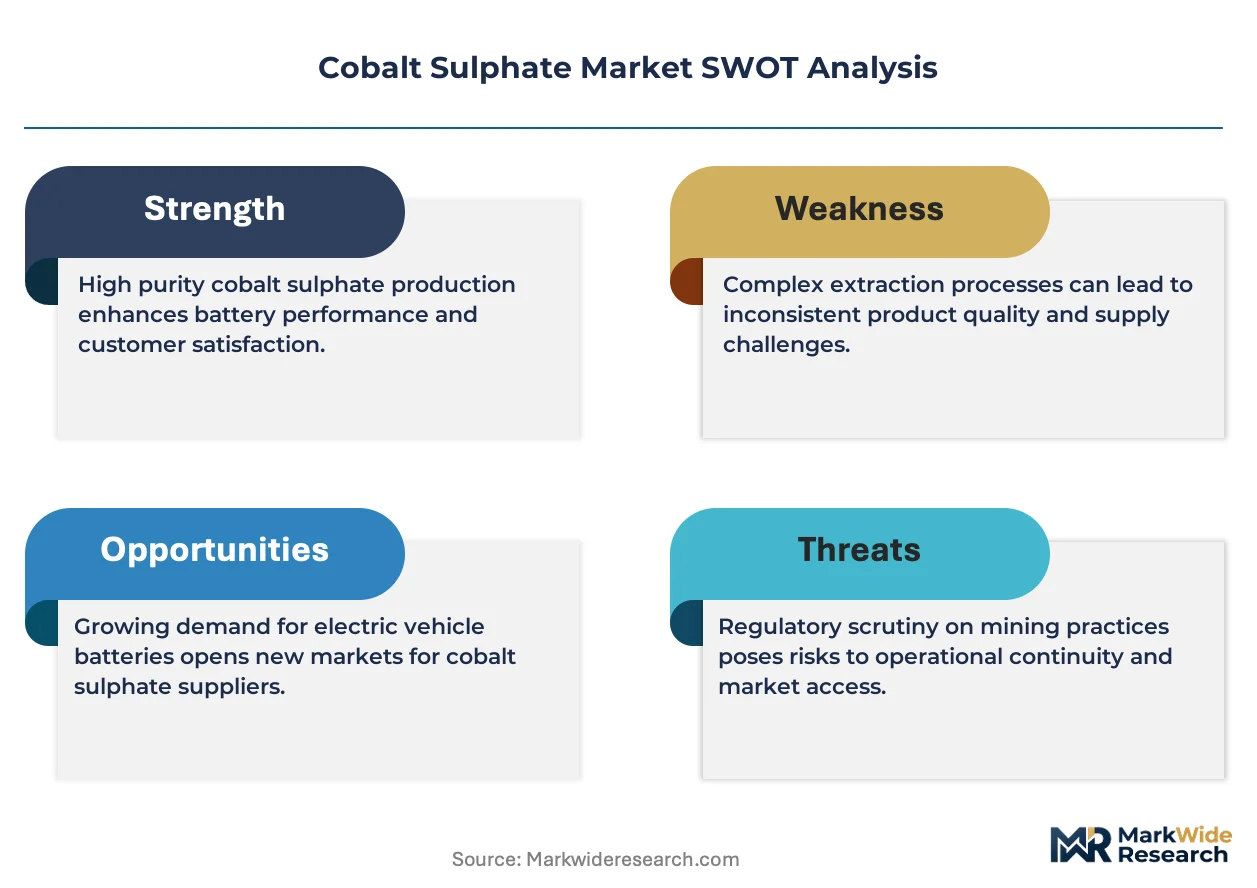
- Supply Concentration:Reliance on the Democratic Republic of Congo for cobalt ore creates significant geopolitical, ethical, and price volatility risks for the value chain.
- Substitution by Chemistry:Adoption of cobalt-free battery chemistries like Lithium Iron Phosphate (LFP) poses a direct long-term threat to demand in some vehicle segments.
- Input Cost Volatility:Extreme price fluctuations of cobalt metal feedstock create unpredictable margins for refiners, hindering long-term investment.
Strategic Opportunities
- Closed-Loop Recycling:Advanced recycling of used batteries to recover high-purity cobalt sulphate offers a secure, circular, and EU-compliant supply source.
- Supply Chain Regionalization:New refining capacity in North America and Europe can serve local gigafactories, de-risking supply and meeting local content mandates.
- Specialty Chemical Applications:A niche opportunity exists in producing ultra-high purity grades for use as high-performance catalysts in the petrochemical sector.
Industry Challenges
- Compliance Burden:Implementing and auditing traceability systems to prove compliance with ethical sourcing and carbon standards represents a significant operational cost.
- Capital Investment Intensity:Constructing new, environmentally sound refining facilities requires substantial upfront capital, particularly in high-cost regions outside of established hubs.
- Technical Integration:Value is shifting to integrated precursor (pCAM) production, requiring refiners to master complex chemical processes beyond basic refining.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cobalt Sulphate Market |
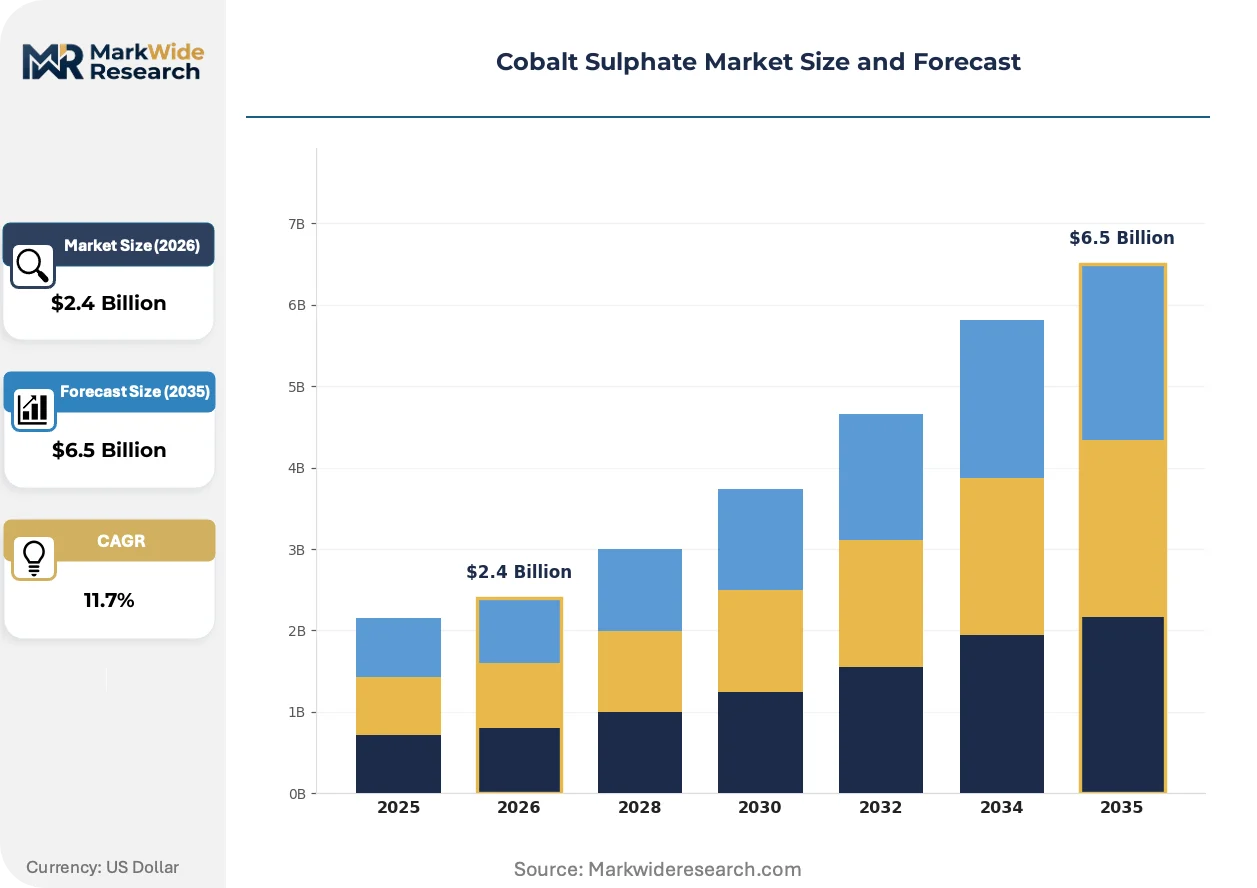
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.5 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monohydrate, Tetrahydrate, Anhydrous, Trihydrate Grade: Battery Grade, Industrial Grade, Pharmaceutical Grade, Food Grade Application: Rechargeable Batteries, Catalysts, Electroplating, Pigments, Ceramics End User Industry: Electric Vehicle Manufacturers, Chemical Producers, Electronics Assemblers, Paint Manufacturers |
| Companies Covered | CMOC, Huayou Cobalt, Glencore, Umicore, Jinchuan Group, Ganzhou Tengyuan Cobalt New Material, Nantong Xinwei Nickel & Cobalt Hightech Development, PJSC MMC Norilsk Nickel, Zhangjiagang Huayi Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cobalt Sulphate Market Strategic Shifts & Innovations
A pivot toward supply chain transparency and accountability is reshaping the market. Technology and regulations are combining to force a re-evaluation of practices from mine to battery cell.
Digital traceability platforms that utilize blockchain and IoT sensors are becoming critical tools. Their function is to provide an immutable record of cobalt's journey, verifying its origin and handling conditions. Automotive OEMs and battery producers are increasingly mandating these systems to meet their due diligence obligations, and this technology is rendering obsolete opaque supply chains that relied on paper-based certification.
Policy instruments like the United States Inflation Reduction Act (IRA) directly influence sourcing decisions through clean vehicle tax credits. The legislation provides incentives for batteries containing critical minerals extracted or processed in the US or by free-trade agreement partners. The battery materials segment is most affected, with producers now planning investments in North American refining capacity to create IRA-compliant supply chains.
Buyer behavior shows a clear shift, with purchasing criteria increasingly prioritizing auditable ESG credentials over raw price. This disrupts traditional commodity trading based on spot markets, creating a preference for long-term offtake agreements with suppliers who can demonstrate ethical sourcing. This trend is most visible among European automakers responding to regulatory and consumer demands.
Cobalt Sulphate Market Segmentation
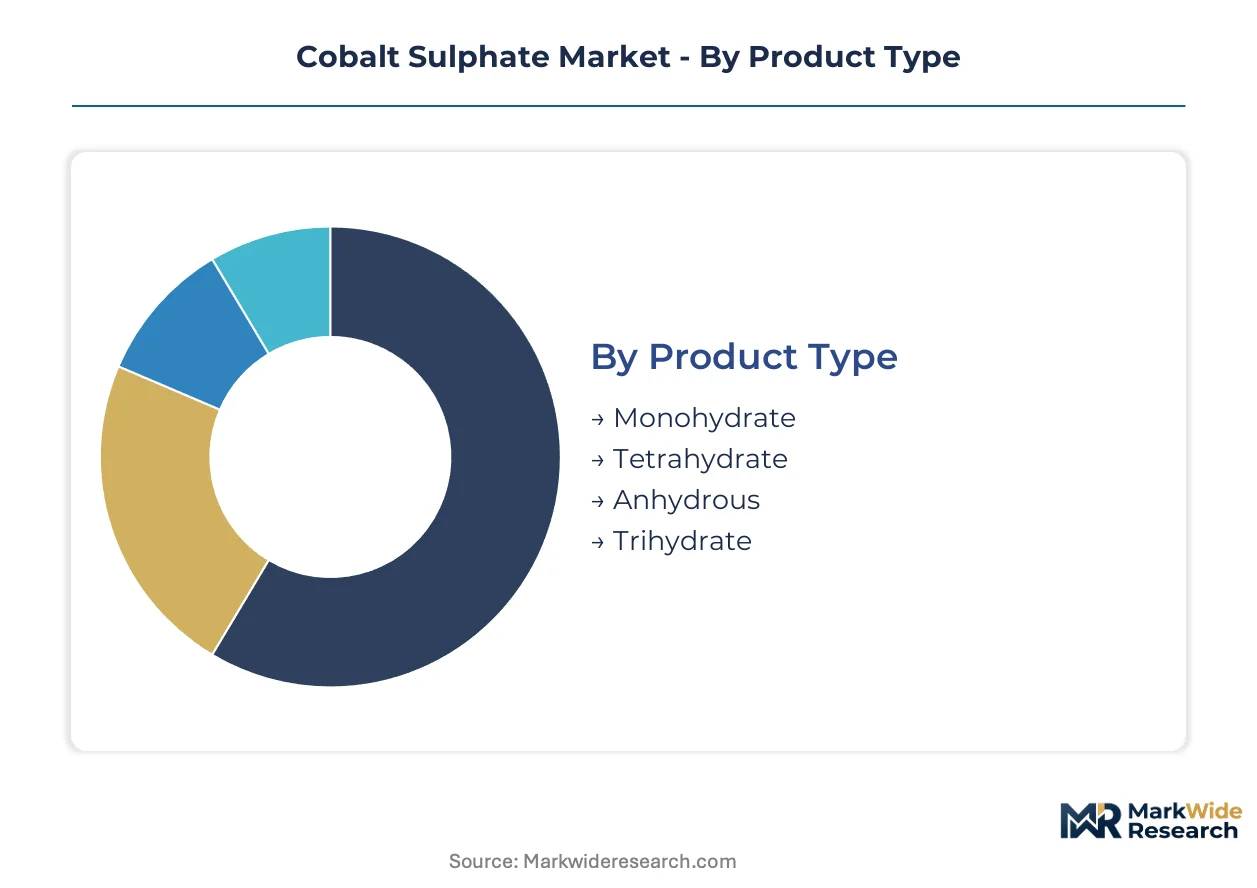
Understanding cobalt sulphate segmentation helps delineate demand patterns and value chain dynamics across diverse applications. This granular analysis reveals where specific product forms and grades are consumed, highlighting varying growth trajectories and purity requirements. Market segmentation provides critical insights for strategic resource allocation and product development within the industry.
Product Type:
Different hydration states of cobalt sulphate exhibit varied stability and processing characteristics, influencing their turnover rates in industrial applications.
- Monohydrate:This form, CoSO₄·H₂O, offers enhanced thermal stability compared to higher hydrates, making it suitable for processes requiring controlled moisture. Demand concentrates in regions with advanced battery material production, where precise chemical specifications are critical for cathode precursor synthesis.
- Tetrahydrate:Cobalt sulphate tetrahydrate (CoSO₄·4H₂O) provides a balance of solubility and stability, often used in electroplating and certain chemical synthesis routes. Its demand is significant in mature industrial sectors requiring consistent material properties for established manufacturing processes.
- Anhydrous:The anhydrous form, CoSO₄, lacks water molecules, offering the highest concentration of cobalt per unit mass for specialized applications.
- Trihydrate:Cobalt sulphate trihydrate (CoSO₄·3H₂O) finds use in specific chemical formulations where its particular hydration level is advantageous.
Monohydrate dominates the installed base of critical chemical processes. Tetrahydrate is where expansion concentrates for broader industrial adoption.
Grade:
The cost tier of cobalt sulphate directly correlates with its purity levels, with premium grades commanding higher prices due to stringent processing requirements.
- Battery Grade:This segment requires purity exceeding 99.8% with ultra-low impurity levels, essential for high-performance lithium-ion battery cathodes. Demand is heavily concentrated in China, driven by its extensive electric vehicle battery manufacturing capacity and global supply chain influence.
- Industrial Grade:Offering a standard purity level, industrial grade cobalt sulphate serves a broad array of manufacturing processes outside of advanced battery production. Its demand is stable across diverse chemical and metallurgical applications, including catalysts and pigments.
- Pharmaceutical Grade:This grade meets specific pharmacological purity standards for use in certain medical and veterinary preparations.
- Food Grade:Cobalt sulphate for food-grade applications adheres to strict safety and purity regulations for use as a micronutrient supplement.
Battery Grade cobalt sulphate exhibits the steepest expansion trajectory. Industrial Grade maintains a foundational market presence.
Application:
Application segments vary significantly in volume, ranging from high-throughput industrial uses to specialized, lower-volume chemical processes.
- Rechargeable Batteries:This application segment represents the primary consumption driver, utilizing cobalt sulphate as a critical precursor for lithium-ion cathode active materials. Demand is directly tied to the accelerating global production of electric vehicles and consumer electronics.
- Catalysts:Cobalt sulphate functions as a catalyst in various chemical reactions, including petroleum refining and organic synthesis, due to its redox properties. This application maintains a consistent demand in the chemical processing sector.
- Electroplating:Cobalt sulphate is used in electroplating baths to produce corrosion-resistant and aesthetically pleasing metal coatings.
- Pigments:This compound provides vibrant blue and green hues in ceramic glazes and glass, serving the decorative and construction industries.
- Ceramics:Cobalt sulphate acts as a coloring agent and additive in ceramic production, enhancing material properties and visual appeal.
Rechargeable Batteries are gaining share fastest. Catalysts represent a stable, significant volume.
End User Industry:
End user industries exhibit diverse procurement patterns, with some sectors directly sourcing and others relying on intermediate chemical producers.
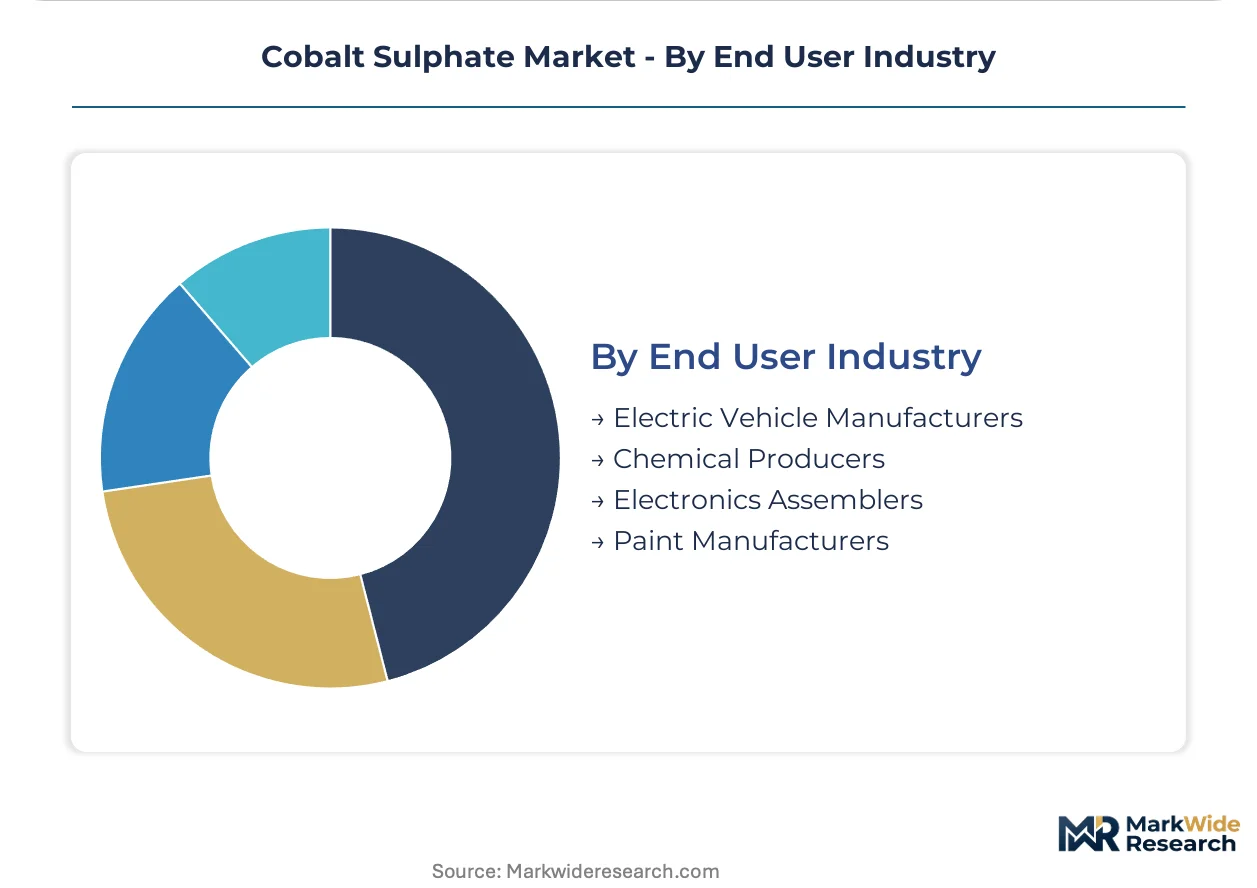
- Electric Vehicle Manufacturers:These manufacturers represent the largest and fastest-growing end-user segment, requiring high-purity cobalt sulphate for their battery supply chains. Procurement emphasizes long-term offtake agreements with ethically compliant suppliers to meet regulatory mandates like the EU Battery Regulation.
- Chemical Producers:This industry uses cobalt sulphate as a feedstock for producing other cobalt compounds, catalysts, and specialized chemicals. Their demand is driven by the overall health and expansion of the global chemical manufacturing sector.
- Electronics Assemblers:These companies utilize cobalt sulphate in the production of various electronic components, including certain types of batteries and specialized coatings.
- Paint Manufacturers:Cobalt sulphate finds application in the paint industry as a pigment or drying agent for specific formulations.
Electric Vehicle Manufacturers drive the largest share of new demand. Chemical Producers maintain substantial consistent consumption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption-mix differentials characterize the global cobalt sulphate market. China's demand centers on battery-grade material for electric vehicles, while European regions balance battery production with stringent recycling mandates. North America prioritizes secure, localized supply chains for critical minerals.
China
Demand for battery-grade cobalt sulphate in China is enormous, driven by its expansive electric vehicle battery manufacturing. China’s GB standards dictate strict purity requirements, influencing global production specifications. Key manufacturing hubs in the Yangtze River Delta and Pearl River Delta drive massive volumes for cathode precursor synthesis.
United States
The United States sees rising demand for domestic battery production, spurred by automotive electrification initiatives. The Inflation Reduction Act (IRA) provides incentives for clean vehicle tax credits, favoring locally sourced materials. Investments in new refining capacity in states like Nevada and Georgia are establishing regional supply chains.
Germany
European demand in Germany focuses on high-purity materials for advanced battery chemistries and circular economy principles. The EU Battery Regulation mandates recycled content and supply chain due diligence for market access. Gigafactories in Brandenburg and Saxony are attracting significant investment for localized battery material production.
South Korea
South Korea's cobalt sulphate market is driven by its strong position in advanced battery cell manufacturing and electronics. METI regulations and local industry standards emphasize material quality and supply chain stability. Major battery producers in Chungcheong and Gyeonggi provinces require consistent, high-purity inputs for their global operations.
Japan
Japan's demand for cobalt sulphate supports its robust automotive and electronics sectors, with a strong emphasis on technological innovation. JIS standards ensure stringent quality control for battery materials and industrial applications. Manufacturing clusters in the Kanto and Kansai regions are critical for both domestic and export-oriented battery component production.
Cobalt Sulphate Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a dynamic market structure. The sector is tiered, with integrated material producers and upstream mining giants dominating the value chain. Strategic archetypes include vertically integrated solution providers, raw material controllers, and specialty chemical innovators. Capacity expansion and strategic partnerships are dominant competitive moves.
Vertically integrated solution providers, exemplified by Huayou Cobalt, link refining operations directly to battery material outputs, securing their position in the precursor cathode active material (pCAM) space. Glencore, leveraging its vast upstream mining assets, occupies a position as a raw material controller, ensuring supply chain influence from the Democratic Republic of Congo. Umicore differentiates through its focus on high-purity materials and closed-loop recycling technologies, representing an archetype of specialty chemical innovation.
| Leading Market Players |
|---|
| CMOC |
| Huayou Cobalt |
| Glencore |
| Umicore |
| Jinchuan Group |
| Ganzhou Tengyuan Cobalt New Material |
| Nantong Xinwei Nickel & Cobalt Hightech Development |
| PJSC MMC Norilsk Nickel |
| Zhangjiagang Huayi Chemical |
| Others |
Cost & Logistics Intelligence
Cobalt metal feedstock volatility acts as a named risk vector, determining both pricing tier spreads and the supply chain shape. This volatility creates unpredictable margins for refiners, influencing investment decisions across the value chain.
Pricing Analysis
Long-term offtake agreements dominate the pricing model for battery-grade cobalt sulphate, favored by automotive OEMs seeking supply stability. Price differentiation stems from purity levels, with Battery Grade commanding a premium, and from auditable ethical sourcing credentials. Margins are tightening due to input cost volatility of raw cobalt. Automotive manufacturers are less price-sensitive for high-purity materials, while industrial users exhibit higher price sensitivity for standard grades.
Supply Chain Analysis
The EU Battery Regulation, a regulatory chokepoint, influences material flows by mandating recycled content and due diligence. Geographic supply concentrates heavily in the Democratic Republic of Congo for cobalt ore and in China for refining capacity. Raw material dependencies include cobalt metal and sulphuric acid. Geopolitical instability in the DRC creates a single-source vulnerability for global supply. Distribution runs through direct contracts from refiners to precursor cathode active material producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a fragmentation opportunity, driven by the demand-side shift towards regionally compliant and ethically sourced materials, creating niches for specialized producers.
For Market Incumbents: Build supply chain resilience by investing in backward integration into mining assets in stable regions. Expand refining capacity in North America and Europe to meet local content mandates and mitigate geopolitical risks. This strategy addresses the threat of LFP substitution and stringent regulatory compliance burdens. Leverage existing scale to achieve cost efficiencies and invest in ESG certification to differentiate offerings.
For New Entrants and Emerging Players: Build out advanced closed-loop recycling technologies to recover high-purity cobalt sulphate from end-of-life batteries. Target the European market, where the EU Battery Regulation creates a strong demand for recycled content. A go-to-market angle focused on verifiable carbon footprint reduction and full digital traceability offers a competitive advantage.
For Investors and Strategic Acquirers: The EU Battery Regulation reshapes the acquisition landscape, favoring companies with robust ethical sourcing and recycling capabilities. Long-term viability over a 5-10 year window favors integrated precursor producers and specialized recycling firms. Acquire technology providers offering digital traceability solutions or regional refining assets with established ESG compliance. The signal to watch is increasing government incentives for localized, circular supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Europe/North America | De-risks supply chains and meets regional content mandates for gigafactories. |
| Investment in Closed-Loop Recycling | Establishes circular supply sources compliant with EU Battery Regulation. |
| Digital Traceability Platform Adoption | Ensures ethical sourcing verification and compliance with due diligence obligations. |
| Long-term Offtake Agreements | Secures stable demand for ethically sourced and high-purity cobalt sulphate. |
| R&D in Ultra-High Purity Materials | Captures niche demand for advanced catalysts and specialized chemical applications. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted during the primary research phase, with findings validated through extensive secondary analysis. Stakeholder roles included battery manufacturers' procurement leads, chemical producers' R&D directors, EV OEM supply chain managers, and cobalt refiners' sales executives. Secondary data sources comprised EU Battery Regulation documents, China's GB standards, US IRA guidelines, and industry association reports. This approach ensured robust bottom-up and top-down triangulation.
The calibration approach involved validating quantitative models against qualitative insights gathered from industry experts across the analysis window. Segmentation dimensions modeled included product type, grade, application, end-user industry, and regional regulatory compliance. Compound annual growth rates were derived from historical trends, projected electric vehicle adoption rates, and regulatory impact assessments. Key forecast inputs included electric vehicle production forecasts and battery chemistry evolution.
The forecast holds incumbent behavior within observed patterns; aggressive moves by major integrated producers or new recycling technology providers would shift outcomes. Forecasts reflect assumptions regarding technological advancements and geopolitical stability. Material shifts in battery chemistry breakthroughs or major policy shifts would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Global Nickel Hydroxide Market
Metals & Minerals
Global Boron Market
Metals & Minerals
Middle-East and Africa Lithium Market
Metals & Minerals
Saudi Arabia and GCC Ferrosilicon Market
Metals & Minerals
Direct Reduced Iron (DRI) Market
Metals & Minerals
Boron Ore Market
Metals & Minerals
Chromium Mining Market
Metals & Minerals
Rare Earth Elements Recycling Market
Metals & Minerals
Gemstones Market
Metals & Minerals
Steel Powder Market
Metals & Minerals
Selenium Mining Market
Metals & Minerals
Middle East and Africa Aluminum Extrusion Market
Metals & Minerals
Zinc Citrate Market
Metals & Minerals
Diamond Market
Metals & Minerals
Global Base Metal Mining Market
Metals & Minerals
Mineral Ingredients Market