
 India Colored Gemstones Market | 2026-2036
India Colored Gemstones Market Size, Share, and Industry Trends Forecast 2026-2036
India Colored Gemstones Market Foresight
Single-source dependency on Sri Lankan and Myanmar rough supplies is realigning toward diversified procurement networks spanning African mines and domestic Rajasthan deposits. Khanna Gems Pvt. Ltd. leverages direct mine partnerships in Zambia and Madagascar to secure ruby and emerald rough. Gemfields Group Ltd. anchors African sourcing through its Kagem emerald mine and Montepuez ruby operations. Navratan competes on precision-cut calibrated stones for jewelry manufacturers in Surat and Coimbatore.
Colored gemstones are non-diamond crystalline minerals valued for hue, saturation, clarity, and carat weight, typically requiring heat treatment, oiling, or lattice diffusion to enhance appearance before faceting. Their primary commercial purpose spans ornamental jewelry, astrological talismans, and portable wealth storage in South Asian households. Sapphires and rubies command the deepest margin pools among product types due to Kashmir and Burmese provenance premiums. Investment Grade material tightens fastest within quality grade tiers as high-net-worth buyers seek GIA-certified stones for portfolio diversification. Online Retail channels fragment fastest among distribution channels, though Jewelry Stores still control bridal and ceremonial transactions.
BIS mandates hallmarking for precious metal settings, while CDSCO oversees heavy metal safety in surface treatments, and DGFT licensing regulates rough import quotas. These frameworks elevate compliance costs for unorganized cutters but create market access barriers that favor certified dealers. Stakeholders must monitor how blockchain traceability requirements and evolving FCRA rules on nonprofit gemological education affect consumer trust and skilled labor pipelines.
Market Dynamics
BIS hallmarking mandates and GIA grading protocols are compressing margins for unorganized cutters while creating tiered market access that favors certified dealers with direct mine partnerships.
Growth Catalysts
- Bridal jewelry demand:Jewelry manufacturers in Surat and Mumbai are expanding certified sapphire and emerald procurement for wedding collections. This pulls volume through Jaipur's cutting cluster.
- DGFT rough import licensing:Quota frameworks are formalizing procurement channels and pushing trade toward documented supply chains with African mine sources.
- Astrological talisman consumption:South Asian households maintain embedded demand for ruby and blue sapphire specimens as portable wealth instruments, insulating the category from discretionary spending cycles.
Market Restraints
- Sri Lankan rough concentration:Historical dependency on Colombo auction houses creates supply vulnerability during export restrictions or currency volatility episodes.
- Heat treatment disclosure gaps:Inconsistent lattice diffusion reporting undermines price discovery and fuels buyer skepticism in secondary markets.
- CDSCO heavy metal compliance:Surface treatment safety testing adds per-unit certification costs that disproportionately burden small-scale lapidaries.
Strategic Opportunities
- Rajasthan deposit development:Systematic exploration of emerald and feldspar-bearing pegmatites in Ajmer and Bhilwara districts could reduce import intensity.
- Blockchain traceability mandates:Provenance verification requirements from European luxury houses are creating first-mover advantages for Indian cutters with documented mine-to-market chains.
- Online retail channel expansion:Digital platforms are capturing investment-grade buyers seeking GIA-certified stones with remote authentication, bypassing traditional jewelry store intermediaries.
Industry Challenges
- Precision-cut skill scarcity:Master faceters capable of producing calibrated stones for Surat jewelry manufacturers command wage premiums that erode cutter margins.
- FCRA compliance complexity:Nonprofit gemological education funding faces tightened foreign contribution scrutiny, constricting skilled labor pipeline development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Colored Gemstones Market |
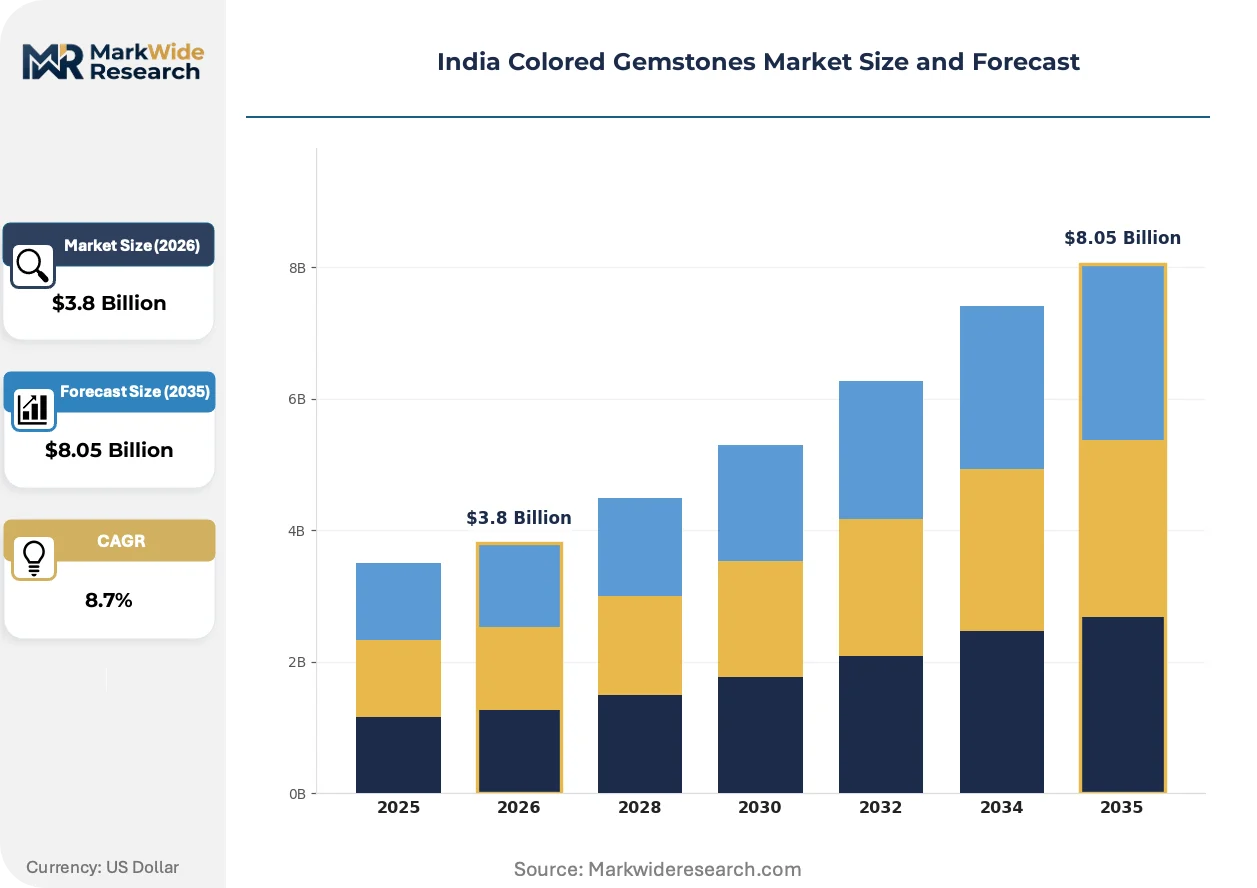
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubies, Sapphires, Emeralds, Alexandrites End User: Retail Consumers, Wholesale Buyers, Designers, Jewelers Quality Grade: Commercial Grade, Investment Grade, Collector’s Grade, High Quality Distribution Channel: Jewelry Stores, Online Retail, Auctions, Trade Shows |
| Companies Covered | Mewar Gem Art, Khanna Gems Pvt. Ltd., Rio Tinto, Swarovski Group, Navratan, RMC Gems India, GemPundit, Gemfields Group Ltd., MyRatna, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Colored Gemstones Market Shifts & Advancements
Synthetic detection protocols and digital grading tools are recalibrating quality verification workflows, while provenance documentation systems reshape competitive differentiation among export-oriented cutters.
Laser-induced breakdown spectroscopy is absorbing quality control functions previously performed by gemological microscopes and traditional refractometers. Mid-size Jaipur cutting houses are deploying portable LIBS units for rapid treatment detection. This technology is absorbing capital allocation that previously supported expanded rough inventory positions.
BIS hallmarking mandates for precious metal settings are tightening documentation requirements across bridal jewelry supply chains. The framework compels integration between gemstone certification and metal purity records. Rajasthan-based exporters are responding by consolidating BIS-registered manufacturing units to streamline compliance overhead.
Investment-grade buyers are rotating toward certified stones with documented mine origins rather than origin-agnostic specimens. This preference compression is displacing uncertified inventory from premium price tiers. The shift concentrates transaction volume through Surat and Mumbai dealers with direct African mine partnerships and GIA laboratory access.
India Colored Gemstones Market Segmentation
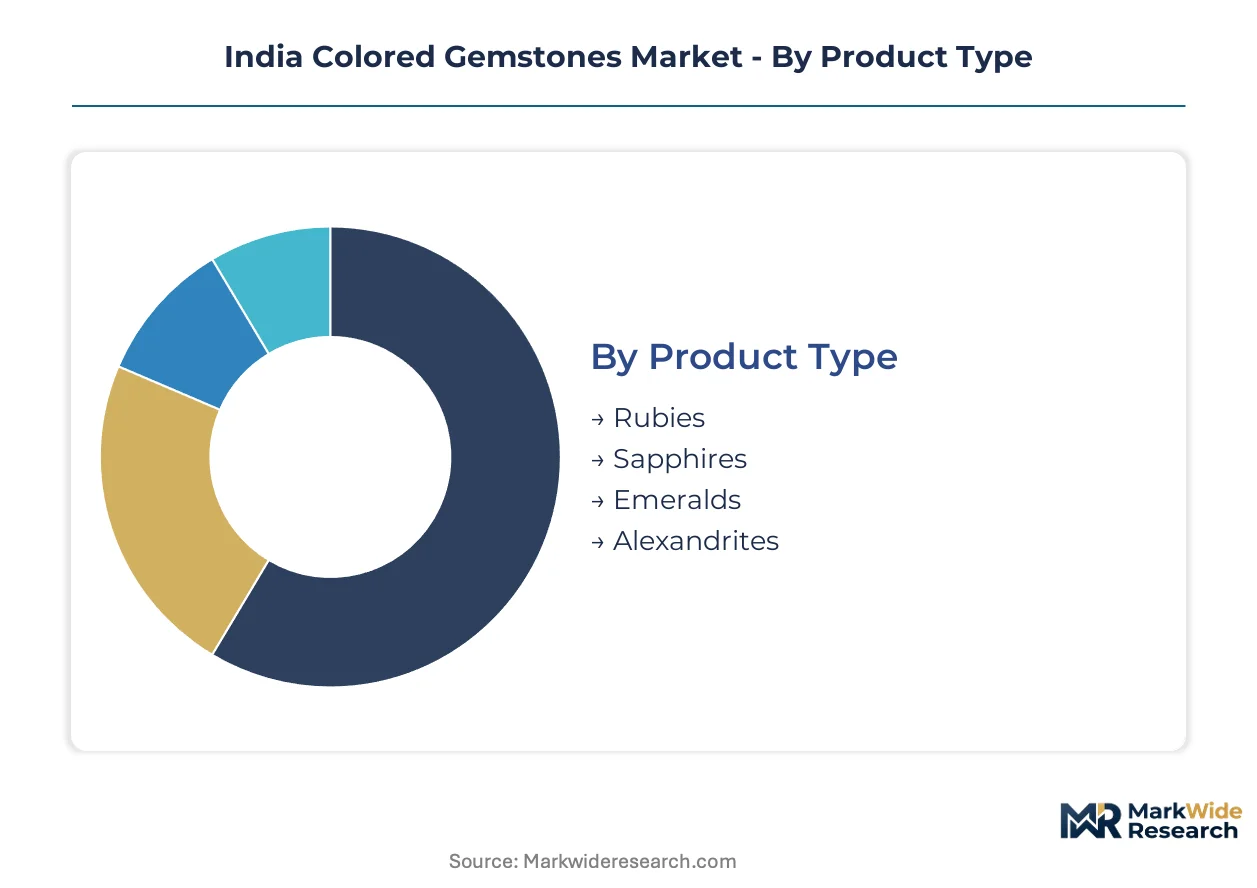
Segmentation in India's colored gemstones market exposes how procurement networks, quality verification standards, and distribution infrastructure shape transaction economics. Each dimension reveals distinct margin structures and compliance burdens that separate organized dealers from artisanal cutters.
Product Type:
Rough sourcing networks concentrate disproportionately around specific mineral species, with Kashmir and Burmese provenance premiums driving divergent procurement strategies across Mumbai and Surat houses.
- Rubies:Corundum specimens with chromium-induced red saturation dominate bridal jewelry demand in Mumbai. Burmese Mogok material commands the steepest provenance premiums, though Zambian and Madagascar rough now supplies Surat manufacturers seeking documented mine-to-market chains.
- Sapphires:Aluminum oxide crystals with iron-titanium blue coloration absorb the deepest margin pools in investment-grade transactions. Kashmir-origin stones with velvet dispersion face acute supply constraints, pushing certified dealers toward Sri Lankan and Madagascar rough auctions.
- Emeralds:Beryl specimens with chromium-vanadium green saturation require oiling disclosure under GIA protocols. African Kagem mine output now challenges Colombian dominance in Jaipur cutting houses.
- Alexandrites:Chrysoberyl with color-change properties under incandescent versus daylight conditions serves niche collector demand. Russian Ural deposits supply premium material, though Brazilian and Indian domestic sources expand commercial-grade availability.
Sapphires absorb the bulk of installed capacity; emeralds are expanding most quickly as African mine partnerships formalize.
End User:
Customer type determines certification requirements and transaction scale, with bridal ceremonial purchases imposing stricter BIS hallmarking integration than bulk rough procurement.
- Retail Consumers:Individual buyers purchasing for personal adornment or astrological purposes drive GIA-certified stone demand through Mumbai and Delhi jewelry stores. BIS hallmarking mandates for precious metal settings elevate documentation costs that filter toward premium price tiers.
- Wholesale Buyers:Volume purchasers supplying domestic retail networks concentrate procurement through Jaipur cutting clusters. CDSCO heavy metal compliance for surface treatments adds per-unit certification overhead that favors consolidated BIS-registered manufacturing units.
- Designers:Creative professionals specifying calibrated stones for bridal collections in Surat and Coimbatore command precision-cut output from master faceters. Skill scarcity for calibrated production concentrates wage premiums that erode cutter margins.
- Jewelers:Finished jewelry manufacturers integrating gemstones with precious metal settings face tightened documentation requirements linking gemstone certification to purity records. Rajasthan-based exporters respond by consolidating manufacturing footprints.
Retail consumers absorb the bulk of transaction volume; designers are climbing the fastest as bridal collections expand certified procurement.
Quality Grade:
Grade tiering separates origin-agnostic commercial material from documented provenance stones, with blockchain traceability mandates from European luxury houses compressing uncertified inventory into lower price bands.
- Commercial Grade:Standard material without origin documentation or treatment disclosure serves mass-market jewelry manufacturers. Price discovery remains volatile due to inconsistent lattice diffusion reporting.
- Investment Grade:GIA-certified stones with documented mine origins attract high-net-worth portfolio diversification. Direct African mine partnerships and laboratory access concentrate transaction volume through Surat and Mumbai dealers.
- Collector's Grade:Exceptional specimens with rare color phenomena or historical provenance bypass standard grading protocols. Auction houses in Jaipur and Mumbai handle discrete transactions outside retail channels.
- High Quality:Premium material with heat treatment disclosure but without investment-grade documentation occupies intermediate price tiers. DGFT import licensing frameworks push trade toward documented supply chains.
Commercial grade absorbs the bulk of cutting throughput; investment grade is gaining share fastest as provenance verification reshapes competitive differentiation.
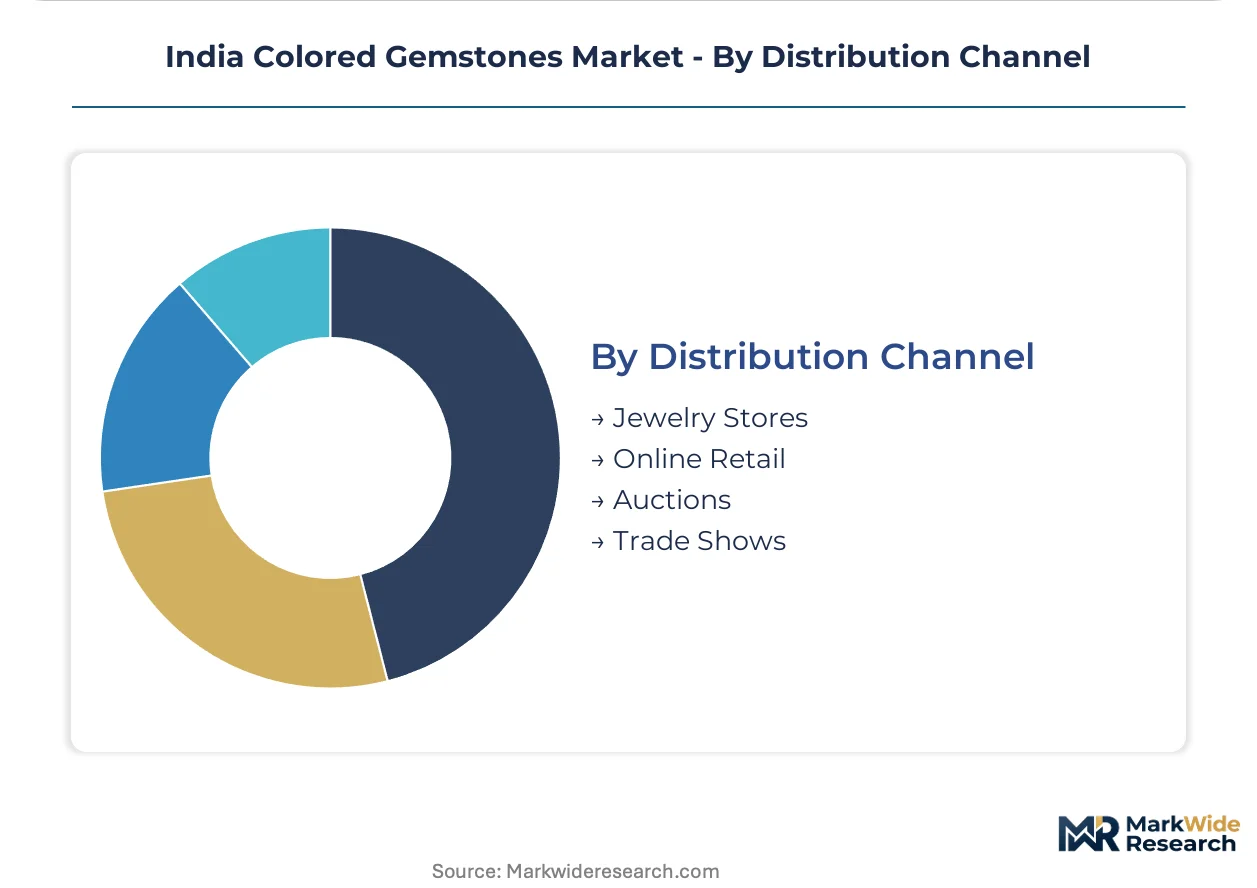
Distribution Channel:
Channel selection determines authentication workflows and customer acquisition economics, with digital platforms fragmenting fastest despite jewelry stores retaining ceremonial transaction control.
- Jewelry Stores:Brick-and-mortar retailers in Mumbai, Surat, and Delhi control bridal and ceremonial purchases requiring physical inspection. BIS hallmarking mandates compel integration between gemstone certification and metal purity records.
- Online Retail:Digital platforms capture investment-grade buyers seeking GIA-certified stones with remote authentication. Blockchain traceability requirements create first-mover advantages for dealers with documented mine-to-market chains.
- Auctions:Colombo and Jaipur auction houses handle rough procurement and collector-grade specimen disposal. Sri Lankan export restrictions or currency volatility create supply vulnerability for dependent buyers.
- Trade Shows:Exhibition events in Jaipur and Mumbai facilitate bulk rough transactions and cutting house networking. DGFT licensing regulations formalize procurement channels toward documented African sources.
Jewelry stores absorb the bulk of bridal transaction value; online retail is expanding most quickly as remote authentication protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bridal jewelry demand concentrates in western and northern manufacturing belts, where Surat and Mumbai houses pull calibrated stones through Jaipur's cutting cluster. State-level mineral policies and BIS enforcement intensity create divergent compliance economics across sub-regional markets.
Rajasthan
Astrological talisman consumption anchors domestic demand in Jaipur's wholesale markets, where artisanal lapidaries supply both retail chains and export houses. The state mining department regulates pegmatite exploration permits in Ajmer and Bhilwara districts under mineral concession frameworks. Jaipur's cutting cluster processes African rough into precision-calibrated output for Surat jewelry manufacturers.
Gujarat
Investment-grade buyers seeking GIA-certified stones drive transaction volume through Surat's diamond-bourse adjacent dealers. DGFT licensing frameworks formalize rough import channels through Mundra and Kandla ports. Surat jewelry manufacturers integrate BIS hallmarking mandates by consolidating manufacturing footprints into registered units.
Maharashtra
Bridal collection designers in Mumbai expand certified sapphire and emerald procurement for wedding-season inventory builds. BIS hallmarking enforcement tightens documentation requirements linking gemstone certification to precious metal purity records. Mumbai's Zaveri Bazaar dealers source through direct African mine partnerships to bypass Colombo auction volatility.
Tamil Nadu
Coimbatore jewelry manufacturers demand calibrated stone supply for South Indian bridal design traditions. CDSCO heavy metal compliance testing for surface treatments adds per-unit certification costs that favor consolidated BIS-registered cutting operations. Chennai-based exporters develop blockchain traceability documentation for European luxury house procurement standards.
Karnataka
Domestic emerald deposit exploration in Hassan district attracts state geological survey investment under mineral development programs. Bangalore retail chains source investment-grade material through Mumbai intermediaries with GIA laboratory access. Mysore's astrological gem traders maintain embedded demand for ruby and blue sapphire specimens as wealth instruments.
India Colored Gemstones Market Competitive Landscape
Direct mine partnerships dominate the current landscape as dealers secure documented supply chains to satisfy blockchain traceability mandates. The vendor base separates into certified dealers with African sourcing networks, Jaipur-based artisanal cutters serving domestic wholesale, and digital-first platforms capturing investment-grade buyers. Three archetypes define positioning: organized houses with laboratory partnerships, traditional family-run cutting operations, and technology-enabled authentication services. Competitive intensity concentrates around procurement exclusivity arrangements and BIS-registered manufacturing consolidation.
Among organized dealers with upstream sourcing control, Khanna Gems Pvt. Ltd. and Gemfields Group Ltd. exemplify the African mine partnership archetype, while Navratan occupies a position within the precision-cut calibrated stone tier serving Surat and Coimbatore manufacturers. These entities anchor the documented supply chain segment as European provenance requirements tighten.
| Leading Market Players |
|---|
| Mewar Gem Art |
| Khanna Gems Pvt. Ltd. |
| Rio Tinto |
| Swarovski Group |
| Navratan |
| RMC Gems India |
| GemPundit |
| Gemfields Group Ltd. |
| MyRatna |
| Others |
Supply & Pricing Matrix
Investment-grade certification premiums separate documented provenance stones from origin-agnostic commercial material, compressing the latter into lower price bands while concentrating procurement power among African mine partnership holders. This bifurcation manifests in divergent supply chain configurations: certified dealers maintain direct Zambia and Madagascar sourcing relationships, while unorganized Jaipur cutters remain tethered to volatile Colombo auction channels.
Pricing Analysis
Volume concentrates in commercial-grade commercial material while margins pool in investment-grade GIA-certified transactions. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth and documented mine origin. Pricing pressure stems from BIS hallmarking compliance costs that disproportionately burden small-scale lapidaries without registered manufacturing consolidation. Retail consumers exhibit highest price sensitivity for astrological talisman purchases, whereas investment-grade buyers demonstrate inelastic demand for documented provenance specimens.
Supply Chain Analysis
Regional distribution centers in Mumbai and Surat function as consolidation hubs for calibrated stone output flowing from Jaipur's cutting cluster. Rough supply draws from Zambia, Madagascar, and Sri Lanka, with African sources gaining share as DGFT licensing formalizes documented procurement channels. Treatment disclosure gaps in lattice diffusion reporting create single-source vulnerability for buyers dependent on Sri Lankan auction volatility. Distribution runs through BIS-registered manufacturing units integrating gemstone certification with precious metal purity records.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master faceter scarcity props pricing for precision-cut calibrated output, constraining Surat jewelry manufacturer procurement and sustaining wage premiums that erode cutter margins.
For Market Incumbents:Acquire direct African mine partnerships to secure documented supply chains satisfying European blockchain traceability mandates. Consolidate BIS-registered manufacturing footprints to streamline hallmarking compliance overhead. Synthetic detection protocol investment defends position against laboratory-grown material substitution threatening origin-based premiums.
For New Entrants and Emerging Players:Launch via online retail channels capturing investment-grade buyers seeking remote GIA-certified authentication. Target underpenetrated Coimbatore bridal design markets demanding calibrated stone supply for South Indian ceremonial traditions. Digital-first provenance documentation offers the most penetrable go-to-market angle against established jewelry store intermediaries.
For Investors and Strategic Acquirers:Re-rating potential sits with organized dealers possessing laboratory partnerships and African sourcing networks given tightening European provenance requirements. Long-term viability hinges on supply chain documentation depth rather than rough inventory scale. Watch DGFT licensing enforcement intensity as the signal indicating formalization velocity for documented procurement channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Mine Partnership Formation | Zambia and Madagascar sourcing relationships secure documented supply chains for European luxury house compliance. |
| BIS-Registered Manufacturing Consolidation | Integrated units streamline hallmarking mandates linking gemstone certification to metal purity records. |
| Precision-Cut Master Faceter Recruitment | Calibrated stone production capability commands premium positioning with Surat and Coimbatore jewelry manufacturers. |
| Blockchain Traceability Implementation | Mine-to-market documentation satisfies emerging European provenance verification procurement standards. |
| Online Retail Platform Development | Digital authentication protocols capture investment-grade buyers bypassing traditional jewelry store intermediaries. |
Research Methodology
Multi-period observation of rough auction pricing volatility, treatment disclosure adoption rates, and certification penetration anchored the trend analysis, supplemented by interviews with Jaipur cutting house operators, Surat jewelry manufacturer procurement leads, Mumbai dealer network managers, and BIS compliance officers. Secondary validation drew from DGFT import licensing records, GIA laboratory throughput disclosures, and Rajasthan state mining department concession frameworks. Bottom-up rough procurement volume estimates triangulated against top-down bridal jewelry demand projections across western and northern manufacturing belts.
Segment-weighting across product type, quality grade, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs derived from trend extrapolation of documented mine partnership formation rates and online retail channel penetration curves. Modeled inputs included BIS hallmarking enforcement intensity trajectories and FCRA compliance complexity impacts on gemological education pipeline development.
Colombo export restriction episodes, currency volatility spikes, and synthetic detection protocol advancement are the dominant revision risks warranting scenario sensitivity analysis. Forecasts reflect documented assumptions regarding DGFT licensing formalization pace and European blockchain mandate adoption timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Global Magnesium Carbonate Minerals Market
Metals & Minerals
Manganese Mining Market
Metals & Minerals
Tantalum Pentoxide Market
Metals & Minerals
Cobalt Sulphate Market
Metals & Minerals
Gregoryite Market
Metals & Minerals
Global Magnesium Oxide Market
Metals & Minerals
Recycled Aluminum Market
Metals & Minerals
Californium Market
Metals & Minerals
Direct Reduced Iron (DRI) Market
Metals & Minerals
Steel Powder Market
Metals & Minerals
Global Fabricated Metal Products Market
Metals & Minerals
Mineral Ingredients Market
Metals & Minerals
Middle-East and Africa Sodium Sulfide Market
Metals & Minerals
Sapphire Mining Market
Metals & Minerals
Colored Gemstones Market
Metals & Minerals
Iron Ore Pellets Market