
 Precious Metals E-Waste Recovery Market | 2026-2036
Precious Metals E-Waste Recovery Market Size, Share, and Industry Trends Forecast 2026-2036
Precious Metals E-Waste Recovery Market Analysis
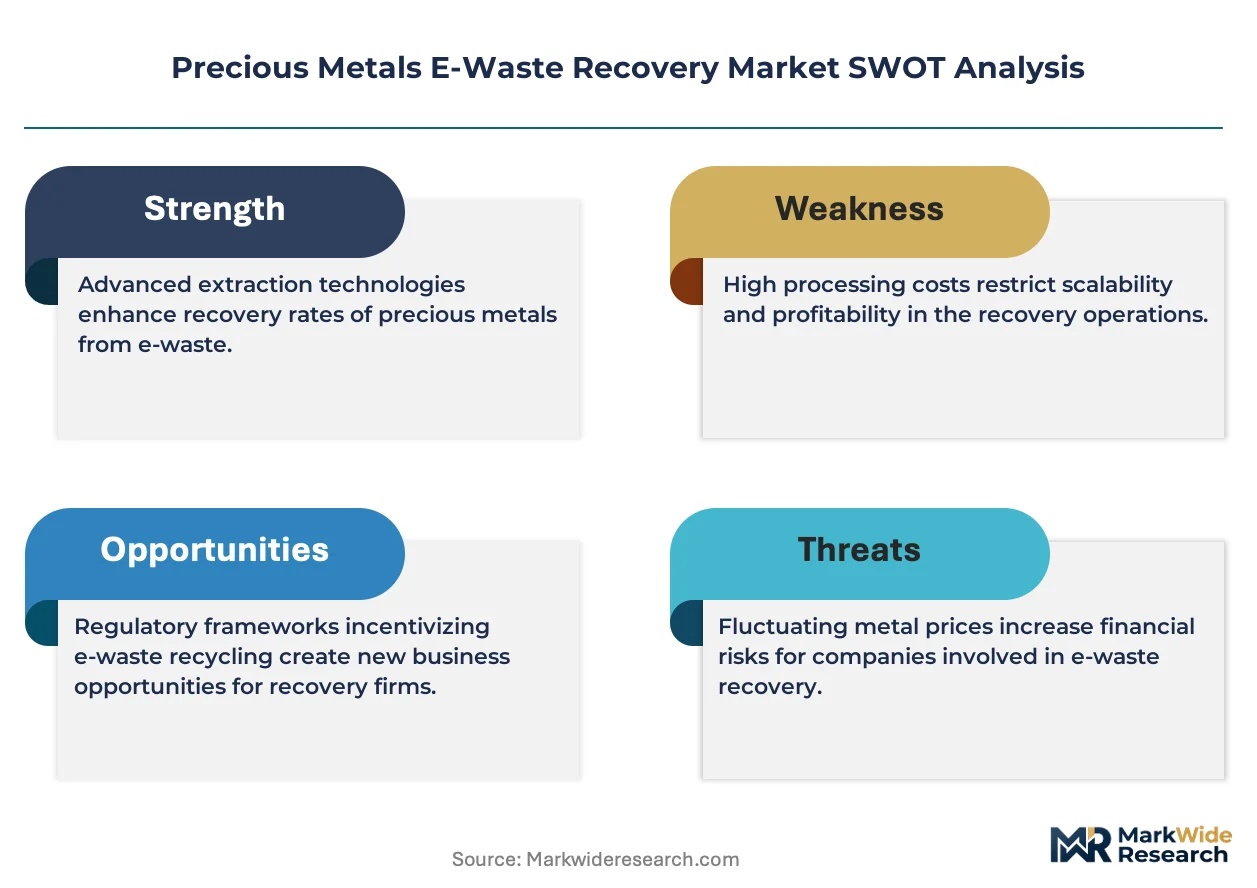
99.99% purity bullion-grade output is collapsing the gap between virgin and recovered metal pricing. Umicore leverages its integrated smelting-refining complex in Belgium to sustain high-throughput precious metal separation. Heraeus Holding anchors German industrial demand through its closed-loop partnerships with automotive electronics suppliers. Aqua Metals differentiates via electrochemical lead recovery technology that extends to silver and gold extraction streams.
Precious metals e-waste recovery encompasses the extraction and refinement of gold, silver, platinum, and palladium from discarded electronic devices through thermal, chemical, or biological processing, typically achieving recovery rates of 95% for gold in professional hydrometallurgical circuits. The primary purpose is to return these elements to industrial supply chains as substitutes for mined concentrates. Recoverable gold commands the dominant value pool due to its concentration in printed circuit boards and connector assemblies. Hydrometallurgical process adoption leads among formal recyclers for its selective leaching precision, while pyrometallurgical process capacity dominates volume throughput in integrated smelters. Mobile phones represent the fastest-growing application feedstock as device replacement cycles compress and emerging market collection networks mature.
The EPA administers e-waste export restrictions under the Resource Conservation and Recovery Act, while the EU's WEEE Directive mandates producer-funded collection targets that expand recovery infrastructure across member states. China's MEE enforces import bans on foreign e-waste that redirect regional feedstock flows toward domestic urban mining operations. Stakeholders must monitor how national critical minerals strategies redefine which recovery technologies qualify for public subsidy and offtake guarantees.
Market Dynamics
The EU's WEEE Directive collection mandates are forcing electronics producers to internalize recovery costs, compressing informal dismantling margins while accelerating formal refinery capacity builds across member states.
Growth Catalysts
- REACH substance restrictions:Limits on hazardous additives in new electronics increase recoverable metal purity in end-of-life streams, improving hydrometallurgical yields.
- Automotive electronics suppliers:Closed-loop partnerships with German industrial conglomerates guarantee offtake volumes for bullion-grade palladium and platinum.
- Guangdong province clustering:Informal circuit board dismantling networks feed formal refineries with pre-concentrated feedstock, reducing logistics costs for urban mining operations.
Market Restraints
- Energy cost volatility:Pyrometallurgical smelters face margin pressure from natural gas price swings, particularly affecting integrated operations in Belgium and Germany.
- China MEE import bans:Foreign e-waste exclusion redirects regional feedstock flows, straining collection infrastructure in neighboring Southeast Asian economies.
- Hydrometallurgical reagent costs:Cyanide alternative chemistry remains economically uncompetitive for small-scale operators despite safety advantages.
Strategic Opportunities
- India's informal sector formalization:BIS standards development for e-waste processing creates first-mover advantage for technology licensors targeting unorganized dismantlers.
- Biological leaching convergence:Biohydrometallurgy integration with conventional circuits offers selective extraction for complex multi-metal assemblies.
- Mobile phone replacement compression:Shortened device cycles in emerging markets expand feedstock availability faster than collection network maturity.
Industry Challenges
- Hydrometallurgical engineer scarcity:Specialized process design expertise concentrates in Belgian and German research institutions, limiting replication speed.
- Smelter capex intensity:Integrated pyrometallurgical facilities require nine-figure capital commitments, favoring incumbent integrated players over new entrants.
- Multi-jurisdiction certification complexity:ISO 14001 alignment with EU CSRD reporting obligations extends compliance timelines for cross-border operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precious Metals E-Waste Recovery Market |
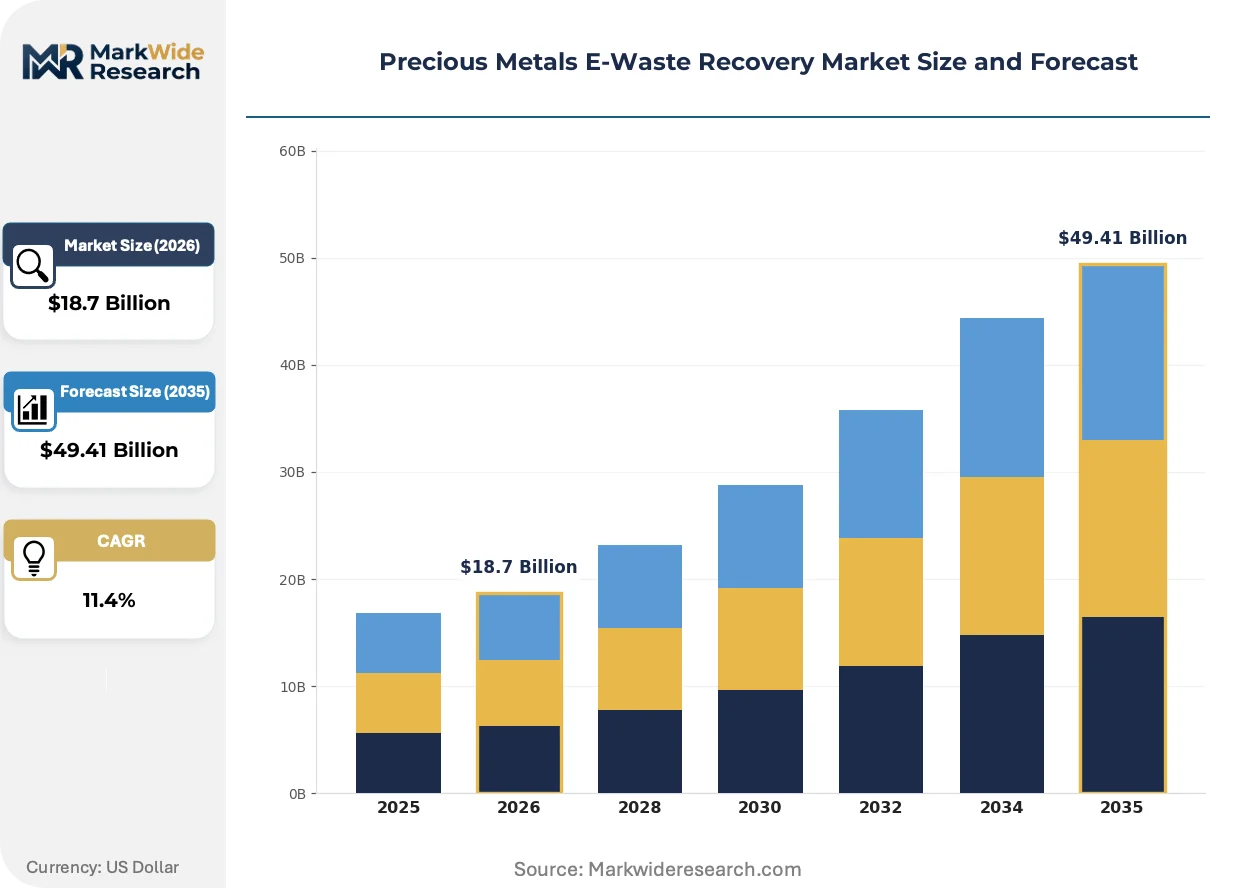
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recoverable Gold, Recoverable Silver, Recoverable Platinum, Recoverable Palladium End User: Electronics Manufacturers, Refineries, Recycling Facilities, Scrap Dealers Technology: Hydrometallurgical Process, Pyrometallurgical Process, Biotechnological Process, Mechanical Process Application: Mobile Phones, Computers, Circuit Boards, Industrial Equipment |
| Companies Covered | Dowa Holdings, Tetronics, Heraeus Holding, Materion Corporation, Boliden Group, Umicore, Sims Limited, Aqua Metals, Johnson Matthey, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precious Metals E-Waste Recovery Market Emerging Trajectories
Recovery technology is splitting between high-volume integrated smelters and distributed selective leaching systems, with regulatory pressure and feedstock geography determining which configuration dominates specific corridors.
Electrochemical precious metal separation is bifurcating the competitive landscape between capital-intensive integrated complexes and modular distributed units. Battery manufacturers and automotive electronics suppliers adopt electrochemical cells for closed-loop silver recovery at medium scale. This technology is bifurcating the market structure, enabling regional processors to compete with centralized smelters on total delivered cost for high-purity output.
The EU CSRD mandates granular supply chain disclosure for recovered material provenance, compelling refiners to deploy blockchain-tracked collection networks. Industrial consequence includes audit cost inflation and supplier consolidation as smaller dismantlers lack documentation infrastructure. German electronics manufacturers and Belgian integrated refiners face the steepest compliance ramps, accelerating partnerships with certified pre-processors.
After-sales service unbundling in consumer electronics compresses manufacturer responsibility windows, shifting end-of-life cost burden toward municipal collection systems and independent recyclers. Retail channel consolidation in North America and Western Europe reduces producer-controlled take-back points, fragmenting feedstock access. This pattern concentrates visible disruption in United States urban recovery networks, where municipal budget constraints delay infrastructure investment relative to regulatory timelines.
Precious Metals E-Waste Recovery Market Segmentation
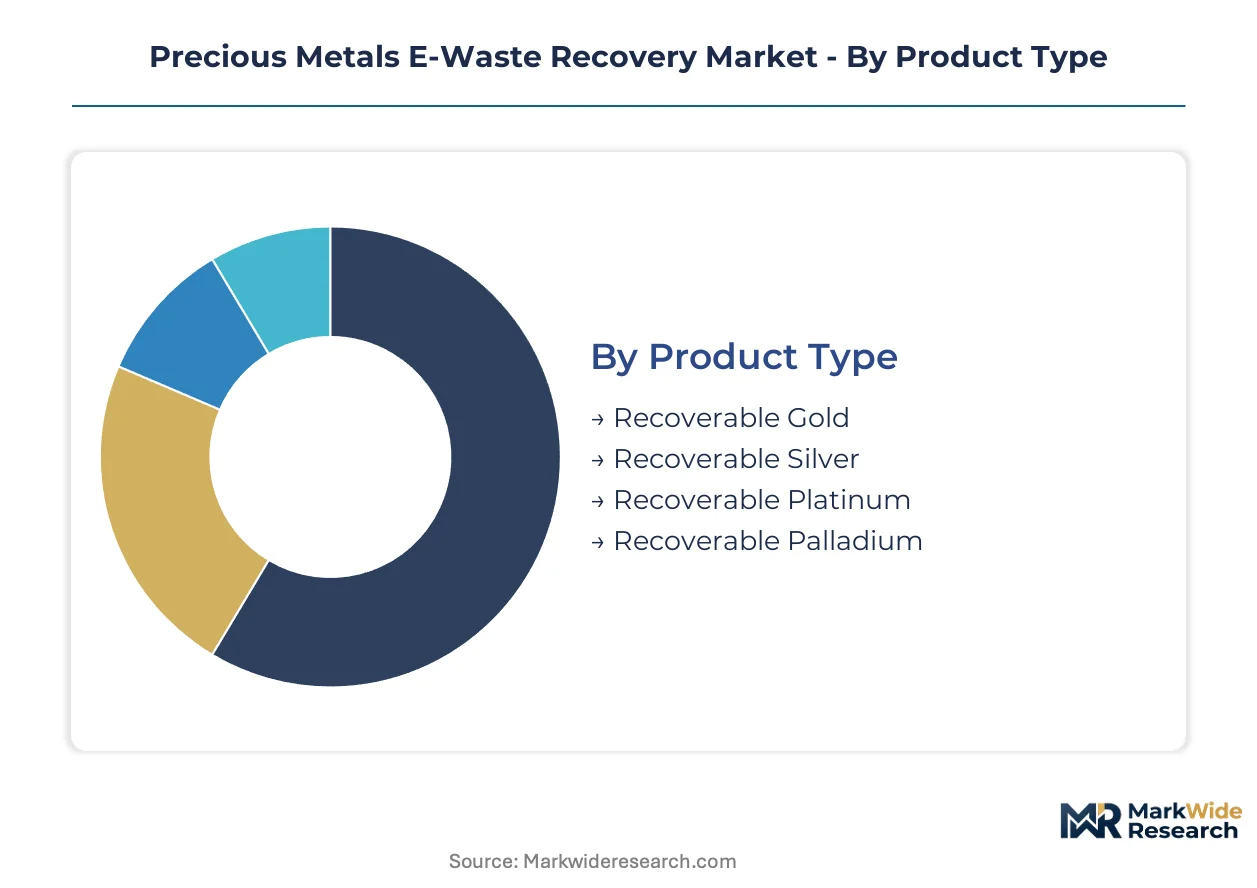
Precious metals e-waste recovery channels fragment by metal value density, processing technology maturity, and feedstock logistics. Channel economics determine which segments capture margin versus volume across formal and informal collection networks.
Product Type:
Channel flows diverge sharply by metal value density, with high-unit-value streams commanding dedicated logistics and low-value metals aggregating through bulk handlers.
- Recoverable Gold:Concentration in printed circuit boards and connector assemblies yields 95% recovery rates in professional hydrometallurgical circuits. Electronics manufacturers in Germany and Belgium capture this stream through closed-loop partnerships with integrated refiners, driven by EU CSRD provenance disclosure mandates.
- Recoverable Silver:Battery manufacturers and automotive electronics suppliers adopt electrochemical cells for medium-scale closed-loop recovery. This segment climbs the fastest as industrial offtake agreements guarantee bullion-grade output volumes.
- Recoverable Platinum:Automotive catalyst residues and industrial equipment feedstock concentrate in German refinery corridors.
- Recoverable Palladium:Connector plating from obsolete electronics flows through Guangdong province dismantling clusters into formal smelter networks.
By volume, recoverable silver leads. By value concentration per kilogram of feedstock, recoverable gold is ahead.
End User:
Cost tier stratification separates capital-intensive integrated operators from distributed collection intermediaries.
- Electronics Manufacturers:Producer responsibility mandates under EU WEEE Directive force internalization of recovery costs. German industrial conglomerates anchor demand through guaranteed offtake volumes for palladium and platinum.
- Refineries:Umicore's integrated smelting-refining complex in Belgium sustains high-throughput precious metal separation. This segment expands most quickly as purity standards tighten and virgin-recovered metal pricing gaps collapse.
- Recycling Facilities:Municipal collection systems in North American urban networks face budget constraints delaying infrastructure investment.
- Scrap Dealers:Informal circuit board dismantlers in China's Guangdong province feed formal refineries with pre-concentrated material.
Electronics manufacturers dominate capital deployment. Refineries gain share fastest on technology integration.
Technology:
Application suitability determines technology selection, with feedstock complexity and scale economics driving process choice.
- Hydrometallurgical Process:Selective leaching precision achieves 95% gold recovery in professional circuits. Belgian and German research institutions concentrate specialized process design expertise, limiting replication speed for new entrants.
- Pyrometallurgical Process:Integrated smelters dominate volume throughput but face margin pressure from natural gas price volatility. Nine-figure capital commitments favor incumbent players over new entrants in Belgium and Germany.
- Biotechnological Process:Biohydrometallurgy integration with conventional circuits offers selective extraction for complex multi-metal assemblies.
- Mechanical Process:Pre-concentration and shredding operations reduce logistics costs for downstream chemical processing.
Pyrometallurgical capacity leads on volume throughput. Hydrometallurgical adoption gains fastest on purity yields and energy efficiency.
Application:
Customer type segmentation aligns with replacement cycle dynamics and collection network maturity across consumer and industrial channels.
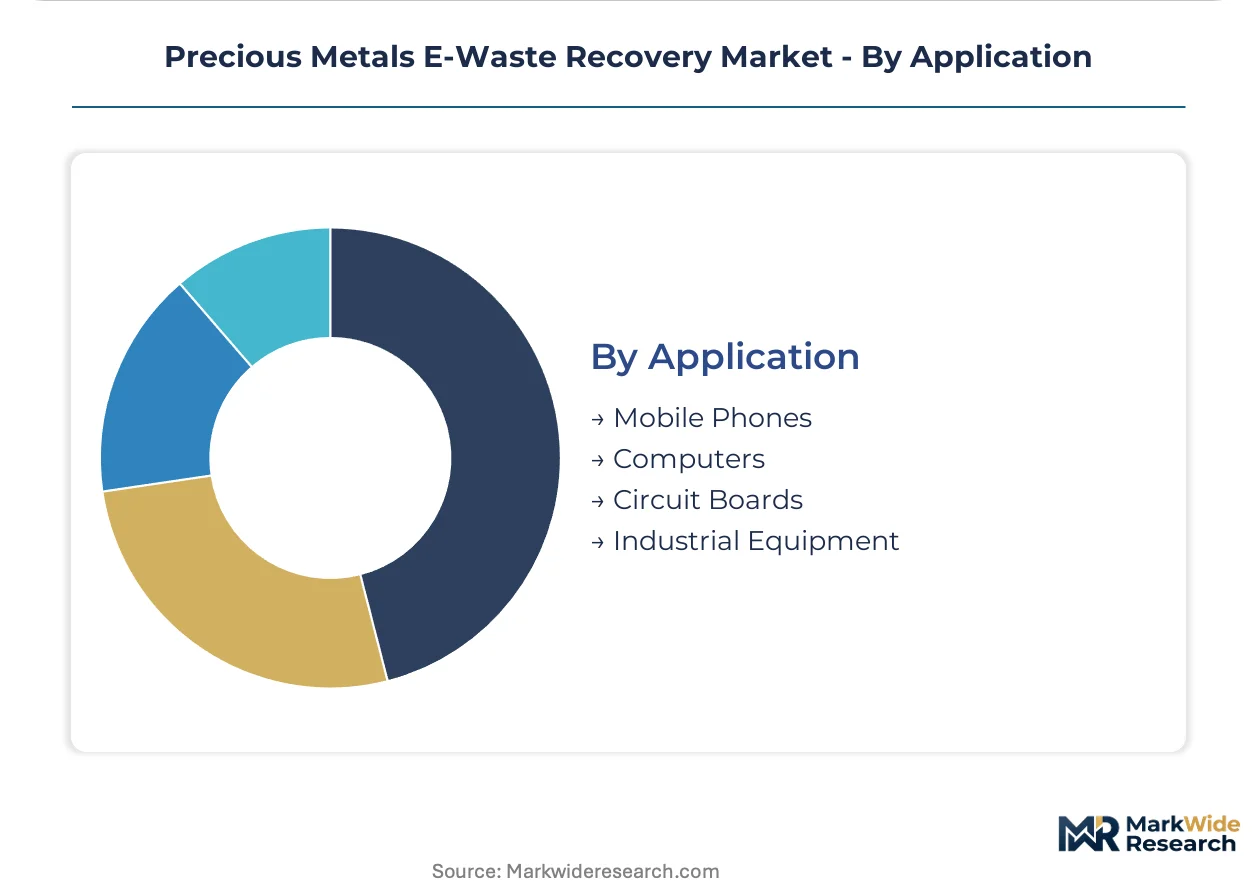
- Mobile Phones:Device replacement cycle compression in emerging markets expands feedstock availability faster than collection network maturity. This application shows the steepest expansion trajectory as urban mining operations scale.
- Circuit Boards:Pre-concentrated dismantling in China's informal clusters feeds formal refinery inputs. Guangdong province networks reduce logistics costs for urban mining operations.
- Computers:Enterprise asset disposition channels concentrate high-value recoverable metals in certified processing streams.
- Industrial Equipment:Automotive electronics suppliers and heavy machinery retirement generate platinum-group metal concentrations.
Circuit boards dominate current feedstock tonnage. Mobile phones outpace all others on collection growth rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated smelting complexes concentrate in Belgium and Germany, while informal dismantling clusters dominate feedstock pre-concentration in southern China. National regulations and energy costs are fragmenting competitive positioning across recovery corridors.
United States
Automotive electronics suppliers and battery manufacturers drive industrial precious metal demand. The EPA administers e-waste export restrictions under the Resource Conservation and Recovery Act. Municipal collection systems in urban recovery networks face budget constraints delaying infrastructure investment relative to regulatory timelines.
Germany
Electronics manufacturers anchor palladium and platinum offtake through closed-loop partnerships. The EU's WEEE Directive mandates producer-funded collection targets that expand recovery infrastructure. Heraeus Holding and industrial conglomerates concentrate operations in German refinery corridors serving automotive supply chains.
Belgium
Umicore leverages its integrated smelting-refining complex for high-throughput precious metal separation. REACH substance restrictions limit hazardous additives in new electronics, improving hydrometallurgical yields. Belgian research institutions concentrate specialized process design expertise for formal refinery circuits.
China
Urban mining demand concentrates in Guangdong province where informal circuit board dismantling clusters feed formal refineries. The MEE enforces import bans on foreign e-waste that redirect regional feedstock flows toward domestic operations. Pre-concentrated feedstock from informal networks reduces logistics costs for urban mining.
India
Mobile phone replacement compression in emerging markets expands feedstock availability faster than collection network maturity. BIS standards development for e-waste processing creates first-mover advantage for technology licensors. Informal sector formalization efforts target unorganized dismantlers with certification pathways.
Precious Metals E-Waste Recovery Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated pyrometallurgical operators commanding volume throughput and electrochemical specialists capturing distributed processing margins. The market structures around three tiers: capital-intensive integrated smelters with nine-figure facility commitments, mid-scale hydrometallurgical refiners serving regional electronics manufacturers, and modular technology licensors targeting informal sector formalization. Dominant competitive moves include strategic partnerships with automotive electronics suppliers for guaranteed offtake and technology licensing to bridge formal-informal collection gaps.
Within the integrated smelter archetype, Umicore and Boliden Group occupy positions anchored by European regulatory compliance and high-purity output capabilities. Heraeus Holding represents the closed-loop partnership model with German industrial conglomerates. Among electrochemical specialists, Aqua Metals exemplifies the distributed processing tier targeting medium-scale silver recovery for battery manufacturers.
| Leading Market Players |
|---|
| Dowa Holdings |
| Tetronics |
| Heraeus Holding |
| Materion Corporation |
| Boliden Group |
| Umicore |
| Sims Limited |
| Aqua Metals |
| Johnson Matthey |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between German electronics manufacturers and Belgian integrated refineries lock in both supply access and price visibility for bullion-grade palladium and platinum streams. These agreements insulate processors from spot market volatility while guaranteeing feedstock flows through formal collection networks.
Pricing Analysis
EU CSRD dictates the pricing tier structure by mandating granular provenance disclosure that fragments the market across certification levels. Three-tier pricing structure across premium, standard, and economy levels separates blockchain-tracked collection networks from uncertified dismantlers. Pricing pressure stems from energy cost volatility hitting pyrometallurgical smelters in Belgium and Germany. Scrap dealers and informal dismantlers show highest price sensitivity due to thin margins on pre-concentrated feedstock.
Supply Chain Analysis
Inventory buffers at Guangdong province dismantling clusters compress lead times for pre-concentrated circuit board feedstock entering formal refinery circuits. Supply draws from China, Belgium, and Germany as primary processing corridors. Key inputs include cyanide alternative reagents, natural gas for smelter operations, and specialized hydrometallurgical equipment. Single-source vulnerability concentrates in Belgian research institutions holding process design expertise. Distribution runs through producer-funded collection networks mandated under EU WEEE Directive.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across formal and informal collection networks creates niche entry points as mobile phone replacement cycles outpace collection infrastructure maturity in emerging markets.
For Market Incumbents: Fortify closed-loop partnerships with automotive electronics suppliers to secure guaranteed offtake volumes for platinum-group metals. Expand hydrometallurgical capacity in Belgian and German corridors to capture margin from purity standard tightening. Counter electrochemical specialist encroachment by integrating modular leaching units into existing smelter complexes. For New Entrants and Emerging Players: Differentiate on biological leaching convergence for complex multi-metal assemblies that resist conventional processing. Target India's informal sector formalization as the most penetrable geography where BIS standards development creates first-mover licensing opportunities. Pursue technology licensing partnerships with unorganized dismantlers seeking certification pathways. For Investors and Strategic Acquirers: Electrochemical technology specialists with modular deployment capabilities offer acquisition exposure to distributed processing growth. Long-term viability hinges on urban mining economics displacing virgin concentrate dependence across the analysis window. Monitor China's MEE enforcement intensity as the inflection signal for regional feedstock flow redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Partnership Expansion | Guarantees offtake volumes for palladium and platinum from German automotive electronics suppliers. |
| Hydrometallurgical Capacity Addition | Captures margin from REACH-driven purity improvements in end-of-life metal streams. |
| Blockchain-Tracked Collection Network Deployment | Meets EU CSRD provenance disclosure mandates for German electronics manufacturers. |
| Biohydrometallurgy Technology Licensing | Bridges formal-informal gaps in India's unorganized dismantler sector under emerging BIS standards. |
| Electrochemical Cell Integration | Enables medium-scale silver recovery for battery manufacturers outside integrated smelter corridors. |
Methodological Framework
Operator-level perspectives from refinery operations managers, electronics manufacturer sustainability officers, informal dismantler network coordinators, and hydrometallurgical process engineers anchored the qualitative base. Secondary validation drew from EPA enforcement records, EU WEEE Directive implementation reports, China MEE import ban documentation, and SEC filings from publicly traded recovery operators. Bottom-up feedstock volume estimates triangulated with top-down precious metal content assumptions across the analysis window.
Sensitivity analysis tested forecast robustness against natural gas price volatility, reagent cost inflation, and collection network maturity lags. Segmentation dimensions modeled include metal type, processing technology, feedstock application, and end-user archetype across the projection horizon. CAGR derivation incorporated urban mining economics evolution and virgin-recovered metal pricing convergence assumptions.
Material uncertainties — regulatory enforcement intensity shifts, informal sector formalization pace, and energy cost trajectories — sit outside the modeled envelope. Forecasts reflect assumptions about collection infrastructure investment and technology adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Bauxite Mining Market
Metals & Minerals
Garnet Market
Metals & Minerals
Recycled Copper Market
Metals & Minerals
Global Gold Potassium Cyanide Market
Metals & Minerals
Lithium Ingots Market
Metals & Minerals
Global Magnesium Oxide Market
Metals & Minerals
Pyroxenite Market
Metals & Minerals
Andalusite Market
Metals & Minerals
Boron Ore Market
Metals & Minerals
Hot Briquetted Iron (HBI) Market
Metals & Minerals
20MnCr5 Steel Market
Metals & Minerals
Cobalt Nitrate Market
Metals & Minerals
India Colored Gemstones Market
Metals & Minerals
Direct Reduced Iron (DRI) Market
Metals & Minerals
Gold Recycling Market
Metals & Minerals
Recycled Aluminum Market