
 Global Feed Minerals Market | 2026-2036
Global Feed Minerals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Feed Minerals Market Analysis
Brazilian soybean processing capacity is realigning the regional supply of mineral premix carriers. Cargill leverages its crushing network to secure captive lecithin and oilseed byproduct streams for mineral blending operations. Nutreco anchors its position through R&D intensity in precision mineral dosing systems for monogastric species. BASF SE competes on chelation technology leadership, controlling proprietary glycinate complexes that improve bioavailability in ruminant diets.
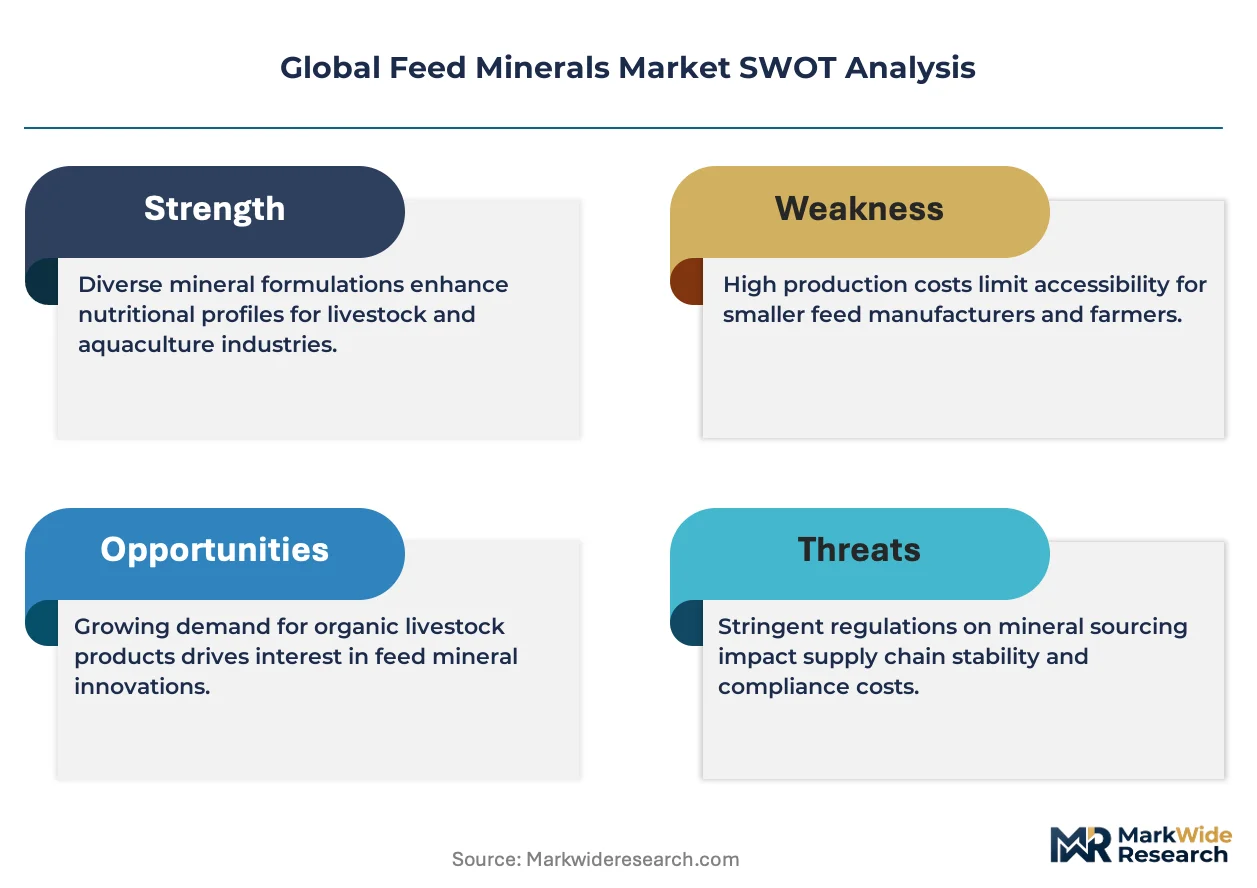
Feed minerals comprise inorganic and organic compounds—copper sulfate, zinc oxide, selenium yeast, and calcium phosphates—formulated to correct dietary deficiencies that constrain growth, immunity, and reproduction in food-producing animals. These inputs are manufactured through crystallization, fermentation, or ligand-binding processes and are metered into complete feeds or delivered as free-choice supplements. Macro minerals, particularly calcium and phosphorus salts, dominate volume due to universal skeletal development requirements across species. Trace minerals, led by zinc and manganese chelates, command premium positioning as producers substitute organic forms for inorganic oxides to meet export residue standards. The aquaculture segment is expanding fastest, driven by mineral-dense diets for shrimp and salmon intensification.
The FDA's Center for Veterinary Medicine enforces food additive petitions and GRAS notifications that govern novel mineral sources entering US feed channels, while the EU's EFSA evaluates additive safety under Regulation 1831/2003, restricting certain copper and zinc maximums to reduce environmental loading. China's Ministry of Agriculture and Rural Affairs implements feed quality standards under GB codes that mandate label disclosure of mineral content and origin. Stakeholders must monitor evolving maximum permitted levels for heavy metals and decide between reformulation investments or geographic portfolio rebalancing as regulatory divergence widens.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is forcing mineral suppliers to reformulate copper and zinc formulations while Brazilian livestock intensification programs pull higher-specification premix volumes into South American supply chains.
Growth Catalysts
- Precision dosing systems:Automated mineral delivery technologies are penetrating monogastric operations in the Netherlands and Denmark, cutting waste and improving feed conversion metrics.
- China's sow herd rebuilding:Disease-driven consolidation in Chinese pork operations is modernizing mineral supplementation protocols across integrated breeding facilities.
- EFSA copper restrictions:Tightening maximum permitted levels in European feed additives are accelerating substitution toward organic chelate forms with lower environmental loading profiles.
Market Restraints
- Phosphate rock concentration:Moroccan and Chinese state-controlled suppliers dominate calcium phosphate feed-grade inputs, exposing premix manufacturers to geopolitical supply interruptions.
- Selenium yeast fermentation capacity:Limited qualified fermentation facilities in North America and Europe constrain organic selenium availability for high-specification ruminant diets.
- Heavy metal testing costs:GB standards enforcement in China and EFSA residue protocols in Europe impose parallel certification burdens that compress margins for multi-territory suppliers.
Strategic Opportunities
- Vietnamese aquaculture expansion:Shrimp and pangasius intensification in the Mekong Delta is creating demand for mineral-dense feeds that domestic compounders cannot yet formulate indigenously.
- Carbon accounting integration:The EU Green Deal's emerging scope 3 reporting requirements for livestock emissions position mineral efficiency as a measurable mitigation lever for feed procurement teams.
- Direct-to-farm digital channels:Brazilian beef producers in Mato Grosso are bypassing traditional distributor networks through platform-based mineral ordering, compressing working capital cycles.
Industry Challenges
- Multi-jurisdiction label compliance:Simultaneous adherence to FDA food additive petitions, EFSA Regulation 1831/2003, and China's GB codes requires dedicated regulatory affairs staffing that mid-tier premixers struggle to maintain.
- Chelate stability validation:Proving glycinate and methionine-complex bioavailability across varying rumen pH conditions demands capital-intensive in-vivo testing protocols that strain R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Feed Minerals Market |
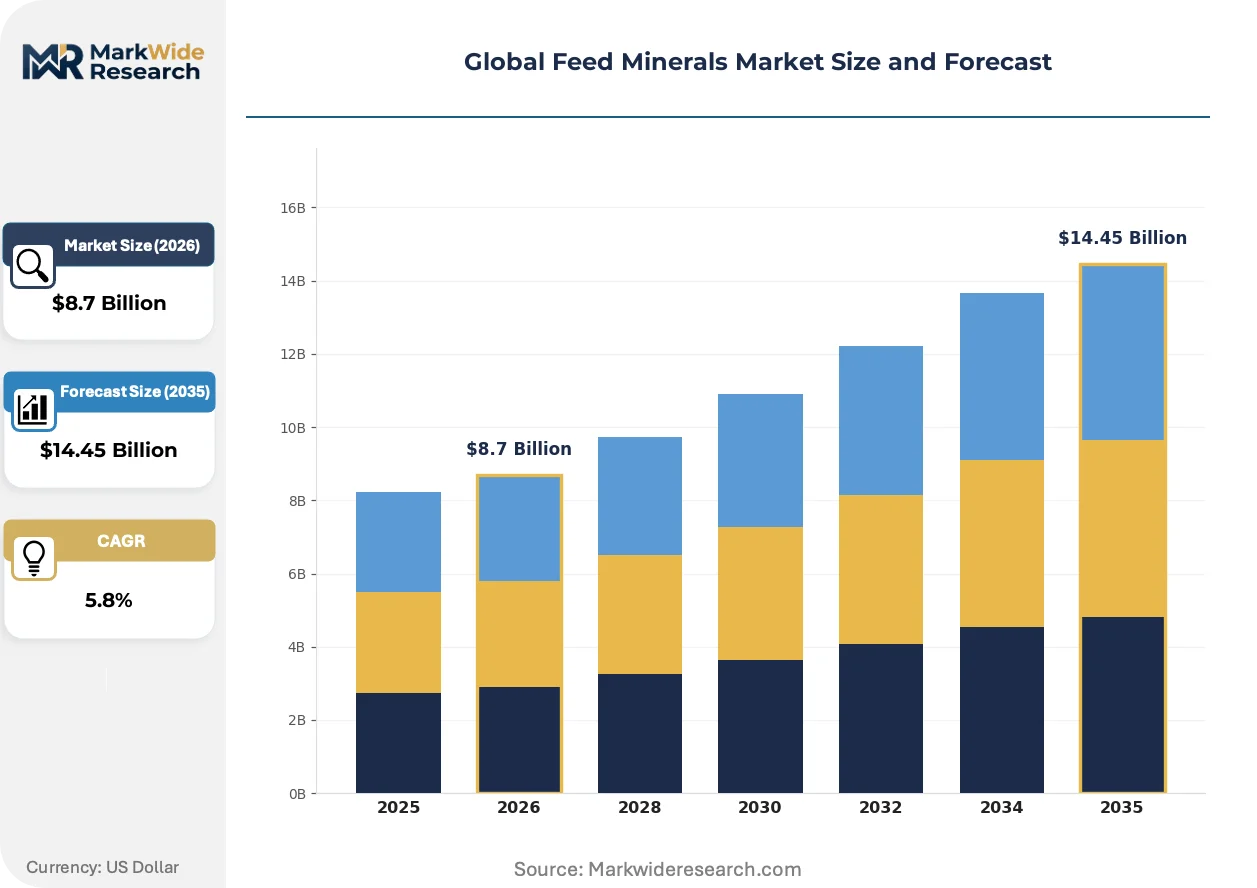
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trace Minerals, Macro Minerals, Mineral Mixtures, Chelated Minerals Animal Type: Ruminants, Poultry, Swine, Aquaculture Form: Powder, Pellet, Liquid, Granule Distribution Channel: Online, Retail Stores, Direct Sales, Wholesalers |
| Companies Covered | Cargill, Nutreco, ADM, DSM, BASF SE, Kemin Industries, Yara International, Solvay, Novus International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Feed Minerals Market Emerging Trajectories
Mineral bioavailability engineering and regulatory-driven formulation shifts are compressing the competitive window for commodity-grade oxide suppliers while rewarding chelation specialists.
Organic trace mineral chelation is consolidating ruminant feed formulation standards as glycinate and methionine complexes demonstrate superior absorption rates under high-concentrate finishing diets. North American beef feedlots and Brazilian integrated operators are adopting these forms at accelerating rates. This technology is consolidating supplier margins around bioavailability-proven portfolios while eroding price premiums for basic sulfate and oxide alternatives.
REACH authorization procedures and the EU F-Gas Regulation are tightening environmental discharge accountability for mineral processing facilities, particularly zinc and copper smelters serving feed-grade streams. Industrial consequence includes mandatory best-available-technique upgrades for European manufacturing assets. Aquaculture mineral blenders in Norway and Scotland face the steepest compliance timelines as their salmon sector export dependence demands uninterrupted EU market access.
Buyer consolidation among Brazilian protein integrators and Chinese pork conglomerates is compressing supplier negotiation leverage and extending payment terms. Traditional mineral distributors in São Paulo and Guangzhou are losing volume to direct mill relationships as procurement teams centralize specification control. This concentration is most visible in Mato Grosso beef operations and Sichuan integrated pork systems where single-source mineral contracts now cover multi-state production footprints.
Global Feed Minerals Market Segmentation
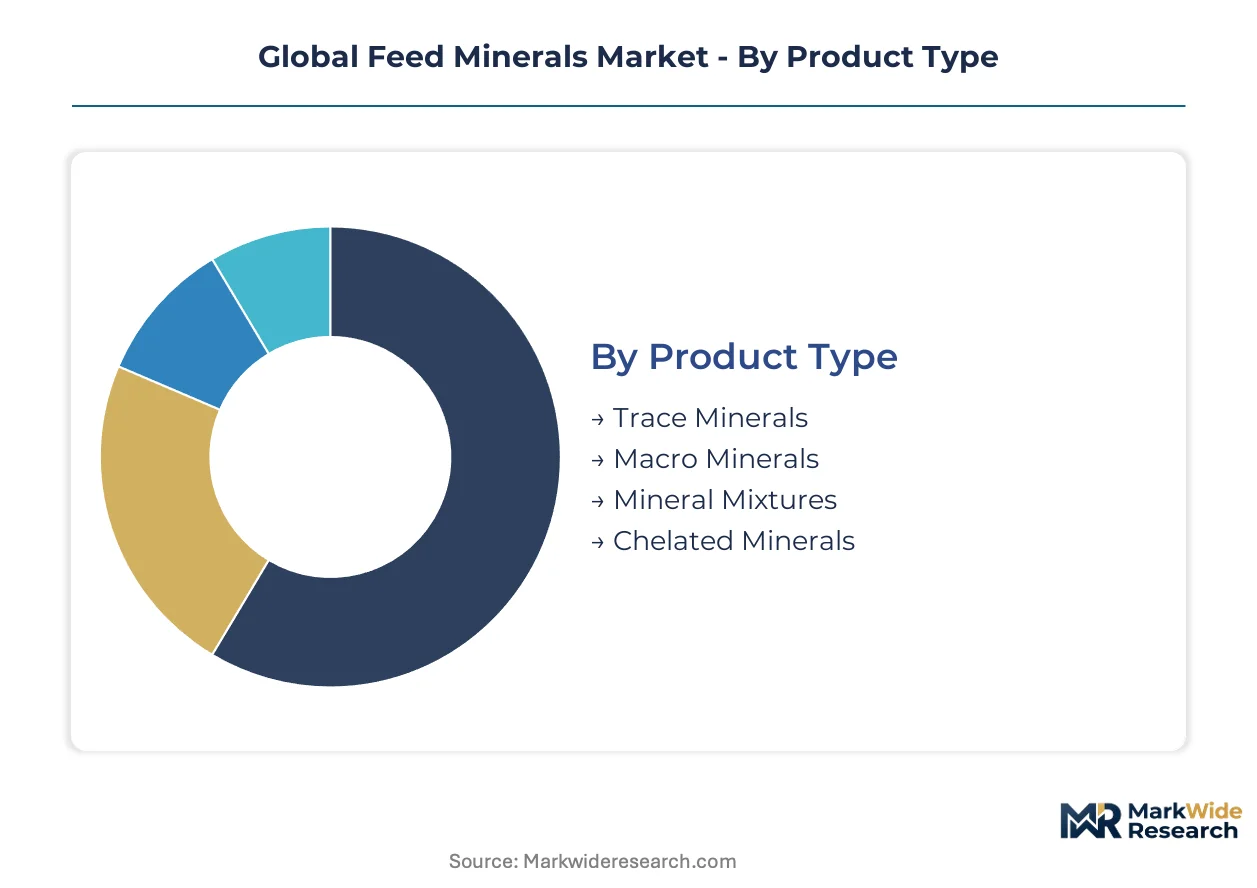
Feed mineral suppliers structure portfolios across four intersecting dimensions that determine pricing power, technical service intensity, and regulatory exposure. Product chemistry dictates manufacturing complexity and bioavailability claims. Animal species segmentation drives formulation specialization and residue compliance requirements.
Product Type:
Macro minerals move in commodity volumes while trace mineral chelates capture formulation premiums through proven absorption metrics.
- Trace Minerals:Zinc, copper, manganese, and selenium compounds administered at parts-per-million levels. Demand concentrates in North American beef feedlots and Brazilian integrated operations where organic chelate substitution accelerates under tightening residue protocols. EFSA copper maximums are forcing rapid formulator migration from sulfates to glycinates.
- Macro Minerals:Calcium phosphates, sodium chloride, and magnesium oxide required in gram-per-kilogram quantities. Moroccan and Chinese state-controlled phosphate rock suppliers dominate upstream supply, exposing premix manufacturers to geopolitical interruption risk. Volume concentration in poultry layer operations drives price sensitivity.
- Mineral Mixtures:Pre-blended complexes combining macro and trace elements for species-specific applications. Brazilian soybean processors leverage captive lecithin streams as carriers for regional premix distribution.
- Chelated Minerals:Glycinate and methionine-bound complexes with documented bioavailability advantages under high-concentrate ruminant diets. Limited qualified fermentation capacity in North America and Europe constrains organic selenium availability.
Mature deployment sits with Macro Minerals. Newer deployment is concentrated in Chelated Minerals.
Animal Type:
Species segmentation determines mineral density requirements, regulatory scrutiny levels, and customer consolidation patterns.
- Ruminants:Beef and dairy cattle requiring calcium-phosphorus balance for skeletal development and reproductive performance. Brazilian Mato Grosso producers are intensifying supplementation programs to improve feed conversion ratios.
- Poultry:Layer and broiler operations with precise trace mineral needs for eggshell quality and growth efficiency. Netherlands and Denmark operations are penetrating automated dosing systems that cut waste and improve conversion metrics.
- Swine:Sow herds and finishing operations with zinc oxide dependency for gut health management. China's pork sector rebuilding is modernizing mineral protocols across Sichuan integrated breeding facilities.
- Aquaculture:Shrimp and salmon intensification demanding mineral-dense feeds with precise water stability. Vietnamese Mekong Delta expansion is climbing the fastest as domestic compounders lack indigenous formulation capability.
Volume concentration remains with Ruminants. Margin expansion is sharpest in Aquaculture.
Form:
Physical presentation determines handling economics, dosing precision, and stability under varying climate conditions.
- Powder:Fine-ground mineral salts and oxides for inclusion in mash feeds and on-farm mixing. Dominates developing market premix applications where pelleting infrastructure is limited.
- Pellet:Compressed mineral concentrates with binding agents for controlled release in automated feeding systems. Norwegian and Scottish salmon operations require uninterrupted EU market access specifications.
- Liquid:Suspended or dissolved mineral solutions for water medication and spray applications. Precision dosing penetration in Netherlands monogastric operations favors this form for waste reduction.
- Granule:Intermediate particle size for free-choice supplementation and reduced dust generation. Brazilian beef producers in pasture systems prefer this form for weather resistance.
Cost efficiency peaks with Powder. Technical sophistication concentrates in Liquid.
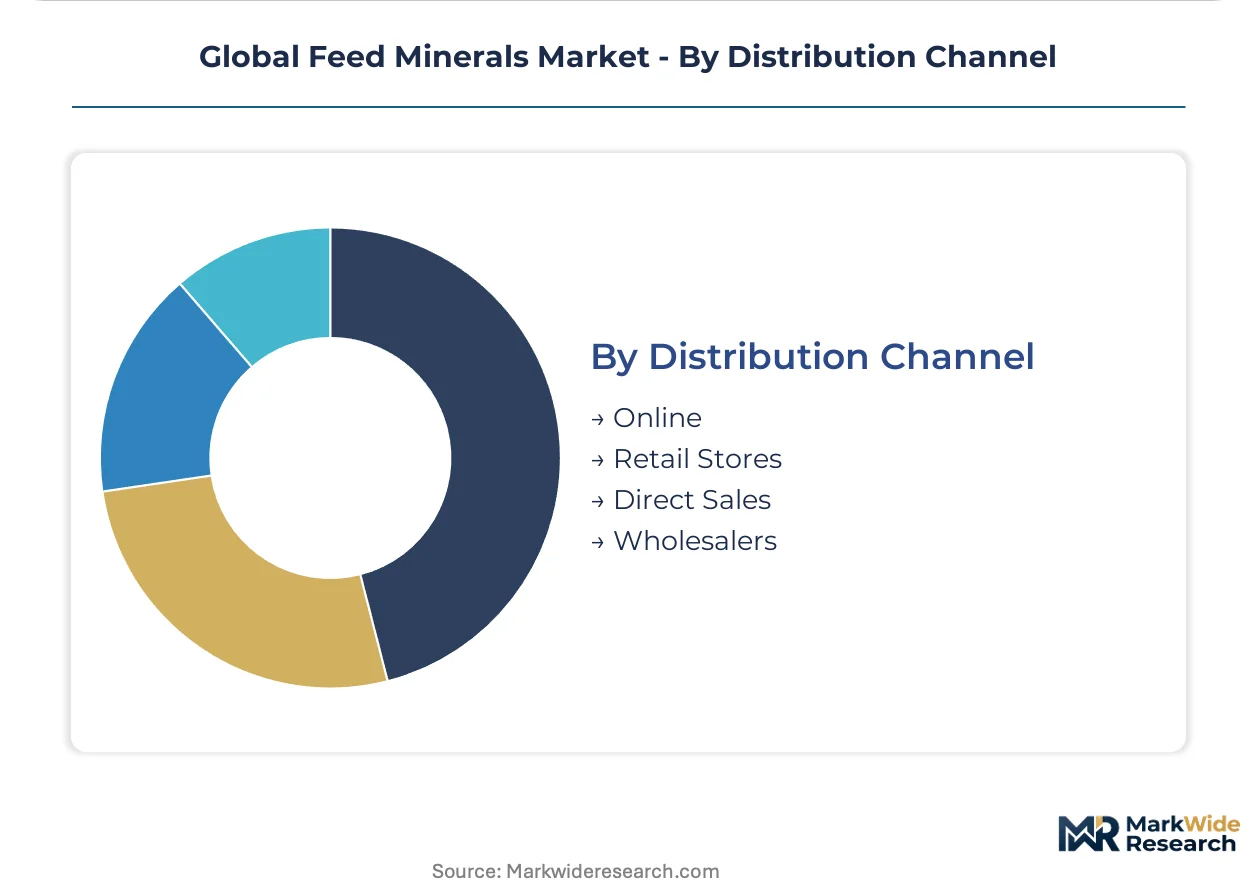
Distribution Channel:
Channel structure is fragmenting as buyer consolidation and digital platforms displace traditional distributor networks.
- Online:Platform-based ordering systems enabling direct mill relationships and compressed working capital cycles. Brazilian Mato Grosso beef producers are bypassing São Paulo distributors through this channel.
- Retail Stores:Agricultural supply cooperatives and farm service centers serving smallholder and hobby farm segments. Margin pressure intensifies as procurement teams centralize specification control.
- Direct Sales:Manufacturer-to-integrator contracts covering multi-state production footprints. Chinese pork conglomerates and Brazilian protein integrators are extending payment terms through this channel.
- Wholesalers:Regional distributors managing inventory and technical service for mid-tier compounders. Guangzhou mineral distributors are losing volume to direct relationships.
Relationship density remains with Direct Sales. Platform penetration is expanding most quickly in Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phosphate rock deposits in Morocco and Chinese state-controlled reserves anchor upstream mineral supply chains. Brazil's Mato Grosso cattle intensification and China's sow herd rebuilding pull differentiated premix demand across divergent regulatory environments.
United States
North American beef feedlots drive organic chelate adoption for residue compliance in export-bound production. The FDA's Center for Veterinary Medicine enforces food additive petitions governing novel mineral sources. Texas Panhandle feedlots concentrate procurement leverage through direct manufacturer contracts covering multi-state operations.
Brazil
Soybean processing capacity in Mato Grosso realigns regional mineral premix carrier supply through captive lecithin streams. ANVISA implements feed quality standards that intersect with EU export requirements for residue limits. São Paulo distributors lose volume to platform-based direct ordering as protein integrators centralize specification control.
China
Sichuan integrated pork facilities modernize mineral protocols during sow herd rebuilding following disease-driven consolidation. The Ministry of Agriculture and Rural Affairs enforces GB standards mandating label disclosure of mineral content and origin. Yangtze River Delta compounders face parallel certification burdens for domestic and export market access.
Germany
Precision dosing system penetration in Lower Saxony monogastric operations cuts mineral waste and improves feed conversion metrics. EFSA evaluates additive safety under Regulation 1831/2003, restricting copper and zinc maximums to reduce environmental loading. Bavarian premix manufacturers upgrade to best-available-technique standards under REACH authorization timelines.
Norway
Salmon intensification in Norwegian fjord systems demands mineral-dense feeds with precise water stability for uninterrupted EU market access. The EU F-Gas Regulation tightens environmental discharge accountability for mineral processing facilities serving feed-grade streams. Bergen-area blenders face compressed compliance timelines as export dependence intensifies.
Global Feed Minerals Market Vendor Landscape
Global majors compete with regional champions across mineral sourcing networks and premix formulation capabilities. Market structure concentrates around diversified agribusiness conglomerates with captive oilseed processing assets, specialized nutrition companies with precision dosing R&D intensity, and chemical manufacturers with chelation technology leadership. Strategic archetypes include backward-integrated processors, bioavailability specialists, and commodity-scale suppliers. Dominant competitive moves encompass direct-to-farm digital channel expansion and reformulation investments responding to tightening EFSA copper restrictions.
Within the chelation technology tier, BASF SE exemplifies glycinate complex capabilities, while Nutreco occupies a position in precision mineral dosing systems for monogastric species. Cargill anchors the backward-integrated archetype through its Brazilian crushing network securing captive lecithin streams for regional mineral blending operations.
| Leading Market Players |
|---|
| Cargill |
| Nutreco |
| ADM |
| DSM |
| BASF SE |
| Kemin Industries |
| Yara International |
| Solvay |
| Novus International |
| Others |
Supply Flow & Price Mechanics
EFSA copper maximums and China's GB standards are forcing mineral suppliers to absorb reformulation costs and dual-certification burdens, compressing margins for multi-territory premix manufacturers and reshaping how suppliers allocate technical service resources across customer tiers.
Pricing Analysis
Technical service bundling separates mineral premix pricing tiers, with organic chelate suppliers including bioavailability validation and residue compliance support while commodity oxide vendors strip these to transactional spot pricing. Price differentiation hinges on certification grade—EFSA-compliant organic forms command substantial premiums over standard sulfate alternatives—and volume scale, with Brazilian integrators extracting favorable terms through multi-state contract consolidation. Cost compression in commodity macro minerals is intensifying because Moroccan and Chinese state-controlled phosphate suppliers wield pricing power over feed-grade calcium inputs. Smallholder cooperatives in developing markets exhibit acute price sensitivity, whereas Norwegian salmon integrators prioritize water stability specifications over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Santos, and Shanghai anchor hub-and-spoke mineral premix distribution, with cold-chain capabilities for organic selenium yeast concentrated in qualified North American and European fermentation facilities. Upstream supply draws from Moroccan phosphate rock deposits, Chinese state-controlled mineral reserves, and Brazilian captive lecithin streams from soybean processing networks. Single-source vulnerability concentrates in selenium yeast fermentation capacity, where limited qualified facilities constrain organic trace mineral availability for high-specification ruminant diets. Distribution runs through direct manufacturer-to-integrator contracts for Brazilian and Chinese protein conglomerates, while mid-tier compounders rely on traditional wholesale networks in São Paulo and Guangzhou.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The feed minerals sector is transitioning from commodity oxide formulations toward bioavailability-engineered chelate technologies, with glycinate and methionine complexes displacing legacy sulfate and oxide standards in ruminant and monogastric applications.
For Market Incumbents: Deepen backward integration into captive oilseed processing assets to secure lecithin carrier supply and regional premix distribution control in Brazil. Invest in precision dosing system R&D to defend against Nutreco's automation penetration in Netherlands and Denmark monogastric operations. Prioritize EFSA pre-submission dossier preparation for organic copper and zinc complexes to maintain market access as maximum permitted levels tighten. For New Entrants and Emerging Players: Launch via direct-to-farm digital platforms targeting Mato Grosso beef producers bypassing São Paulo distributor networks, compressing working capital cycles and capturing specification control relationships. Target Vietnamese aquaculture mineral blending as domestic compounders lack indigenous formulation capability for shrimp and pangasius intensification in the Mekong Delta. Anchor go-to-market strategy through technical partnerships with Norwegian salmon feed manufacturers requiring water-stable mineral solutions for uninterrupted EU market access. For Investors and Strategic Acquirers: The window for entry favors chelation technology specialists with documented bioavailability data and EFSA-compliant organic mineral portfolios. Long-term viability centers on suppliers capable of navigating divergent regulatory frameworks across FDA food additive petitions, EFSA Regulation 1831/2003, and China's GB standards without margin-destroying compliance overhead. Watch EFSA copper and zinc maximum level revisions as the critical inflection signal for accelerated organic substitution timelines and commodity oxide demand destruction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Processing | Cargill's Brazilian crushing network secures captive lecithin streams for regional mineral premix distribution control. |
| Precision Dosing System Development | Automated mineral delivery technologies cut waste and improve feed conversion metrics in Netherlands monogastric operations. |
| Organic Chelate Portfolio Expansion | BASF SE's glycinate complexes demonstrate superior absorption rates under high-concentrate ruminant finishing diets. |
| Direct-to-Farm Digital Channel Buildout | Platform-based ordering enables Brazilian Mato Grosso beef producers to bypass traditional São Paulo distributor networks. |
| EFSA Pre-Submission Dossier Investment | Early regulatory engagement secures market access as copper and zinc maximum permitted levels tighten under EU Green Deal timelines. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with mineral premix formulation directors, livestock procurement managers at Brazilian and Chinese protein integrators, regulatory affairs leads navigating EFSA and FDA pathways, and technical service heads at chelation technology suppliers. Secondary sources encompassed FDA food additive petitions, EFSA scientific opinions under Regulation 1831/2003, China's Ministry of Agriculture GB standards documentation, and Brazilian ANVISA feed quality filings. Bottom-up volume modeling across species segments and top-down value reconciliation against macro mineral trade flows enabled triangulation.
Data-stream reconciliation connected phosphate rock import statistics, organic selenium yeast fermentation capacity utilization, and premix manufacturer production disclosures across the analysis window. Segmentation dimensions modeled included product chemistry tier, animal species application, physical form factor, and distribution channel structure. CAGRs were derived from trend extrapolation of livestock inventory cycles, regulatory implementation timelines, and technology substitution curves in ruminant feedlot and aquaculture mineral supplementation protocols.
Regulatory divergence between FDA, EFSA, and Chinese GB standards, phosphate rock supply interruptions from Moroccan and Chinese state-controlled sources, and organic selenium yeast fermentation capacity constraints are the dominant revision risks to forecast outputs. Disease-driven livestock inventory volatility and buyer consolidation extending payment terms present additional uncertainty vectors. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Industrial Garnet Market
Industrial Minerals
Mineral Salt Ingredients Market
Industrial Minerals
Gluconate Mineral Market
Industrial Minerals
China Feed Minerals Market
Industrial Minerals
Global Graphite Market
Industrial Minerals
Industrial Diamond Market
Industrial Minerals
Oman Industrial Salts Market
Industrial Minerals
Industrial Salts Market
Industrial Minerals
Europe Feed Minerals Market
Industrial Minerals
Global Carbonate Minerals Market
Industrial Minerals
Dolomite Mining Market
Industrial Minerals
Feldspathic Minerals Market
Industrial Minerals
Boron Minerals and Chemicals Market
Industrial Minerals
Calcined Anthracite Market
Industrial Minerals
Mediterranean Sea Salt Micro-Mineral Complexes Market
Industrial Minerals
Potash Ores Market