
 Hydrochloric Acid Electrolysis Market | 2026-2036
Hydrochloric Acid Electrolysis Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrochloric Acid Electrolysis Market Outlook
Food-grade chlorine specification upgrades is unwinding across the hydrochloric acid electrolysis landscape. thyssenkrupp nucera leverages its alkaline water electrolysis heritage to anchor membrane cell deployments in European chemical parks. Covestro AG sustains captive chlorine output through backward integration into electrolysis hardware at its isocyanate complexes. DuPont de Nemours, Inc. differentiates via ion exchange membrane chemistry that extends cell life in high-purity applications.
Hydrochloric acid electrolysis electrochemically decomposes aqueous hydrogen chloride into chlorine gas and hydrogen gas, typically operating at current densities of 2-6 kA/m² with membrane cells achieving 85-95% faradaic efficiency. The process serves chlor-alkali producers seeking to recycle byproduct acid rather than neutralize and dispose. Membrane cell technology leads the product type landscape due to superior energy efficiency and elimination of mercury contamination risks, while bipolar cell configurations represent the fastest-growing architecture for large-scale chlorine recovery. Among applications, chlorine production commands the deepest margin pools as integrated chemical producers value captive supply security over merchant market purchases.
EPA regulations under the Clean Air Act constrain mercury cell operations in the United States, accelerating membrane technology retrofits among domestic producers. REACH and the EU F-Gas Regulation in Europe impose strict emissions accountability on chlorine manufacturing, redirecting capital toward electrolysis-based recycling systems. China's MEE enforces wastewater discharge limits that penalize acid neutralization, creating compliance-driven demand for electrolytic recovery units. Stakeholders must weigh membrane replacement cycles against evolving carbon border adjustments that could revalue low-emission chlorine sourcing.
Market Dynamics
Membrane cell technology is displacing mercury-based chlorine production across integrated chemical complexes, driven by EU F-Gas Regulation emissions accountability and China's MEE wastewater discharge enforcement that penalize legacy acid neutralization.
Growth Catalysts
- EU Green Deal chlorine standards:Chemical manufacturers in Germany scale membrane cell installations to meet binding emissions caps, creating retrofit demand across European chemical parks.
- Captive supply security:Integrated isocyanate producers value backward integration into electrolysis hardware over volatile merchant chlorine markets.
- Shandong province clustering:Chlor-alkali producers in this Chinese industrial corridor integrate electrolysis units for byproduct acid recycling, eliminating disposal liabilities.
Market Restraints
- Ion exchange membrane replacement cycles:Perfluorinated membrane degradation at 2-6 kA/m² operating densities forces capital-intensive refresh schedules every 4-7 years.
- Specialized electrochemical engineering talent:Faradaic efficiency optimization and cell stack design expertise concentrates among legacy chlor-alkali engineering pools, constraining deployment velocity.
- Caustic soda co-production economics:Membrane cell chlorine output ties to caustic market pricing, compressing margins when alkali demand softens.
Strategic Opportunities
- Food-grade chlorine specification upgrades:Pharmaceutical and potable water treatment applications command purity premiums for electrolytic chlorine over diaphragm-cell alternatives.
- Bipolar cell architecture scaling:Large-scale chlorine recovery projects favor compact footprint configurations that halve cell room real estate versus monopolar designs.
- Carbon border adjustment positioning:Low-emission electrolytic chlorine sourcing gains valuation under evolving EU CBAM frameworks for embedded emissions accounting.
Industry Challenges
- Legacy mercury cell decommissioning complexity:EPA Clean Air Act mandated closures require hazardous material remediation and site certification timelines stretching 18-36 months.
- High-purity hydrogen conditioning:Electrolytic hydrogen from acid decomposition carries HCl traces demanding corrosion-resistant compression and drying infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrochloric Acid Electrolysis Market |
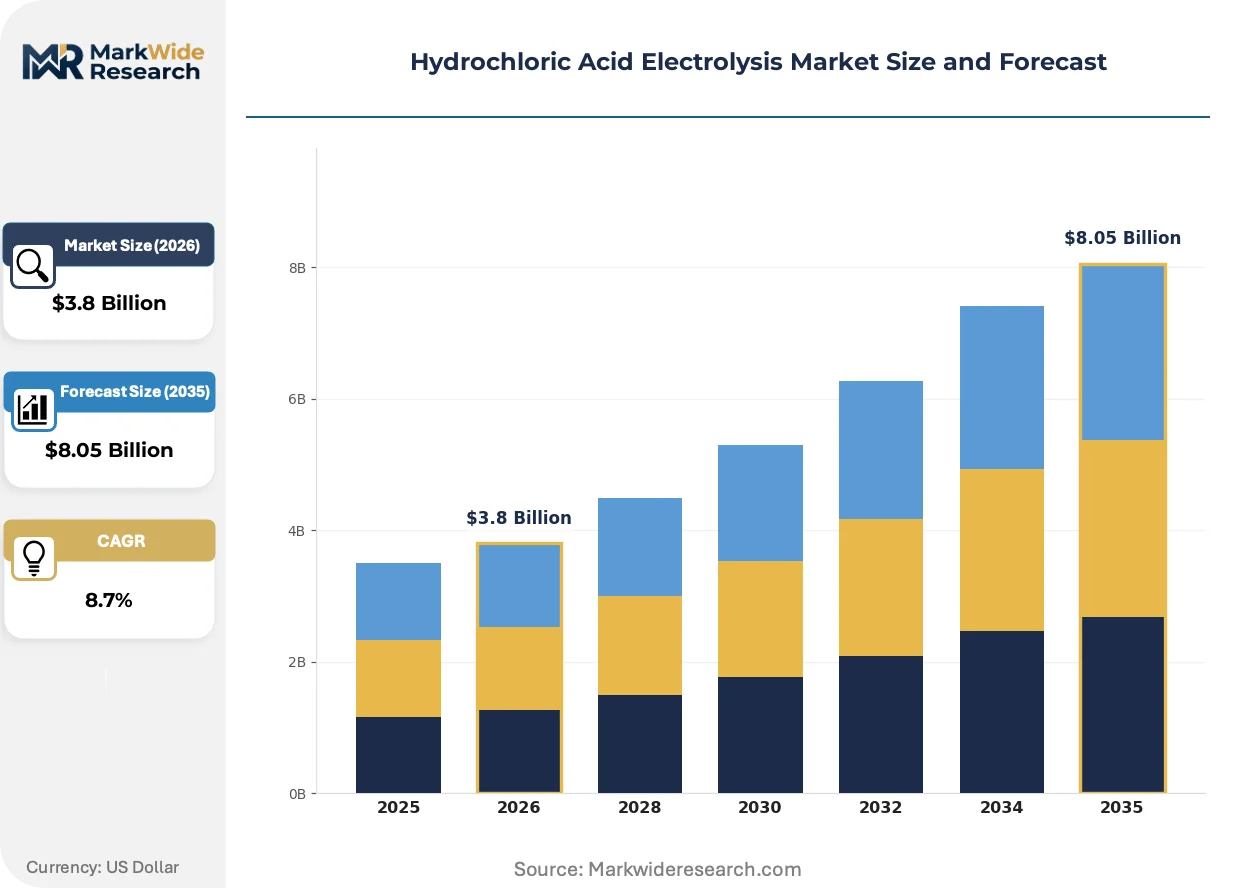
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Cell, Diaphragm Cell, Mercury Cell, Bipolar Cell Application: Metal Recovery, Wastewater Treatment, Chlorine Production, pH Control End User: Chemical Industry, Water Treatment Plants, Mining Sector, Food Processing Technology: Electrolysis, Membrane Separation, Ion Exchange, Hydrometallurgy |
| Companies Covered | Bluestar (Beijing) Chemical Machinery Co. Ltd., Mitsui Chemicals, thyssenkrupp nucera, Wacker Chemie AG, Sumitomo Chemical, Industrie De Nora S.p.A., DuPont de Nemours, Inc., Emerson Electric Co, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrochloric Acid Electrolysis Market Strategic Shifts
Electrochemical process intensification and regulatory emissions accounting are restructuring how chlorine producers source and recycle hydrogen chloride feedstocks across integrated chemical value chains.
Bipolar membrane cell configurations are bifurcating the product type landscape. These compact architectures achieve equivalent chlorine output at half the cell room footprint of monopolar designs. Large-scale chemical complexes in Germany and China adopt bipolar stacks for greenfield installations. The technology is compressing project development timelines and enabling retrofit integration into existing chlor-alkali infrastructure without structural expansion.
REACH and the EU F-Gas Regulation impose strict emissions accountability on chlorine manufacturing operations. Industrial consequence includes mandatory reporting of fluorinated greenhouse gas releases from process equipment and leakage. Integrated producers in the Netherlands and Belgium redirect capital toward electrolysis-based recycling systems that eliminate vented HCl neutralization emissions.
Buyer procurement is consolidating around lifecycle cost contracting for membrane cell systems. Engineering-procurement-construction firms now bundle membrane replacement schedules, energy performance guarantees, and remote monitoring into 10-15 year service agreements. This shift displaces traditional equipment-only sales in European chemical parks where operational certainty outweighs upfront capital minimization.
Hydrochloric Acid Electrolysis Market Segmentation
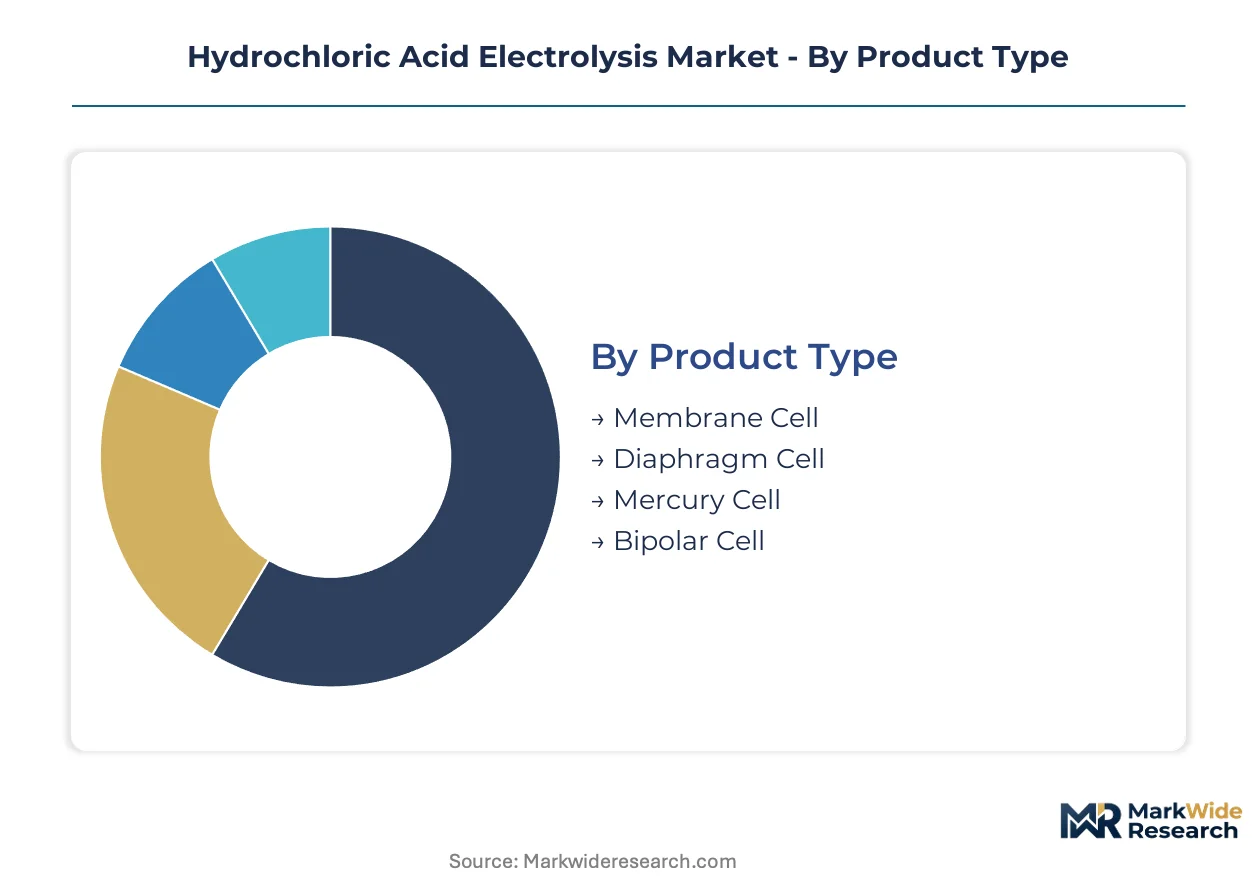
Segmentation in hydrochloric acid electrolysis reveals how technology choices cascade through capital deployment, regulatory compliance, and operational economics. Each dimension—product architecture, application purpose, end-user vertical, and underlying technology—creates distinct procurement patterns and margin structures.
Product Type:
Membrane cell systems flow through engineering-procurement-construction channels with bundled service agreements, while mercury cell retrofits concentrate in regulatory-driven spot procurement.
- Membrane Cell:Perfluorinated ion exchange membranes separate anode and cathode compartments while conducting sodium ions, achieving faradaic efficiencies of 85-95%. Demand concentrates in Germany's chemical parks where EU F-Gas Regulation emissions accountability drives retrofit schedules. Energy efficiency advantages over legacy mercury systems justify 15-20% capital premiums.
- Bipolar Cell:Compact electrode stack architectures halve cell room footprint versus monopolar designs by arranging cells in series electrical connection. China's Shandong province chlor-alkali clusters adopt bipolar configurations for greenfield installations where land constraints bite. Project development timelines compress by 8-12 months versus conventional builds.
- Diaphragm Cell:Asbestos or polymer diaphragms separate electrode compartments at lower capital cost than membrane alternatives. Mining sector applications in Australia and Canada favor diaphragm systems for remote site deployment where membrane logistics prove prohibitive.
- Mercury Cell:Liquid mercury cathodes historically dominated chlorine production but face mandated phase-out under EPA Clean Air Act and EU environmental directives. Remaining installed base concentrates in legacy chemical complexes with 18-36 month decommissioning timelines.
Membrane cell dominates installed base. Bipolar cell is where expansion concentrates.
Application:
Cost tier stratification separates high-purity chlorine production from bulk pH adjustment, with wastewater treatment occupying the mid-tier value band.
- Chlorine Production:Captive chlorine supply for isocyanate and polyurethane value chains demands 99.9%+ purity specifications achievable only through membrane electrolysis. Covestro AG and BASF SE complexes in Belgium and Germany anchor demand through backward integration into electrolysis hardware. Merchant chlorine price volatility reinforces captive supply security preferences.
- Wastewater Treatment:Electrolytic acid decomposition eliminates neutralization chemical costs and sludge disposal liabilities under China's MEE discharge enforcement. Shandong province textile and dyeing clusters integrate recovery units to meet COD and chloride limits. Operating expenditure savings drive 4-6 year payback periods versus conventional treatment.
- Metal Recovery:Hydrometallurgical applications extract copper, nickel, and cobalt from spent acid streams in mining and electronics recycling. Australian and Canadian mining operations deploy mobile electrolysis skids for heap leach acid regeneration.
- pH Control:Bulk acid neutralization in food processing and municipal water treatment favors lower-cost diaphragm configurations where purity requirements relax. Municipal procurement cycles extend 18-24 months versus 12-18 months for industrial buyers.
Chlorine production commands premium pricing. Wastewater treatment is expanding most quickly.
End User:
Customer type determines contract structure, with chemical industry buyers favoring lifecycle service agreements and water treatment plants defaulting to equipment-only procurement.
- Chemical Industry:Integrated chlor-alkali producers value operational certainty over upfront capital minimization, driving 10-15 year bundled service contracts. Germany's Covestro AG and thyssenkrupp nucera partnerships exemplify this procurement shift. Faradaic efficiency guarantees and remote monitoring inclusions displace traditional sales models.
- Water Treatment Plants:Municipal and industrial water utilities face capital budget constraints that favor phased membrane replacement schedules over comprehensive service bundles. China's MEE enforcement creates compliance-driven demand spikes in provincial procurement cycles.
- Mining Sector:Remote site operations prioritize equipment mobility and local maintenance capability over efficiency optimization. Australian copper and nickel producers deploy containerized electrolysis units for acid regeneration at heap leach operations.
- Food Processing:Food-grade chlorine specifications for potable water and sanitation applications command purity premiums. Pharmaceutical-grade requirements in Switzerland and Germany filter procurement toward membrane cell suppliers with FDA and EFSA compliance documentation.
Chemical industry dominates contract value. Water treatment plants are where volume growth concentrates.
Technology:
Maturity gradients separate proven electrolysis deployments from emerging membrane separation and ion exchange applications still scaling from pilot to commercial.
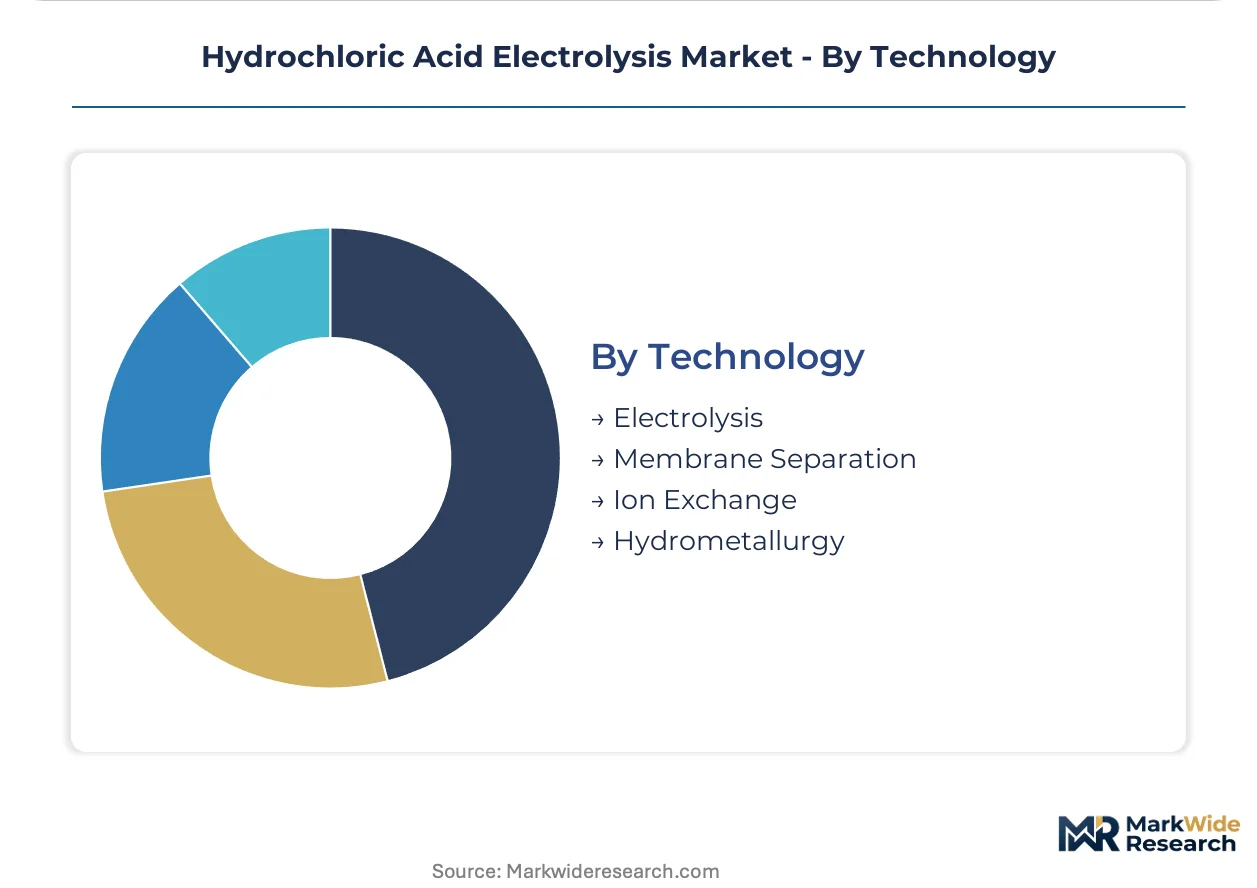
- Electrolysis:Direct electrochemical decomposition of aqueous hydrogen chloride at 2-6 kA/m² current densities represents the commercial standard. Germany's chemical parks and China's Shandong province anchor installed capacity. Faradaic efficiency optimization and cell stack design expertise concentrate among legacy chlor-alkali engineering pools.
- Membrane Separation:Perfluorinated cation exchange membranes from DuPont de Nemours, Inc. and Asahi Kasei Corporation enable selective ion transport while blocking gas crossover. Membrane replacement cycles every 4-7 years create recurring revenue streams for technology licensors.
- Ion Exchange:Resin-based acid recovery systems compete with electrolysis in dilute acid streams below 10% HCl concentration. Water treatment applications in North America favor ion exchange where electricity costs exceed neutralization chemical expenses.
- Hydrometallurgy:Integrated acid regeneration and metal recovery circuits in mining applications combine electrolysis with solvent extraction. Australian and Canadian operations pilot hybrid configurations for copper and rare earth element recovery.
Electrolysis dominates installed base. Membrane separation is where technology investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Germany and China, with regulatory enforcement in both jurisdictions accelerating membrane technology deployment. Chlor-alkali producers in these markets face binding emissions accountability that redirects capital toward electrolytic acid recycling systems.
Germany
Covestro AG and BASF SE complexes in North Rhine-Westphalia drive captive chlorine demand for isocyanate production. EU F-Gas Regulation emissions accountability forces mercury cell phase-outs across chemical parks. thyssenkrupp nucera anchors membrane cell deployments in Leverkusen and Ludwigshafen industrial corridors.
China
Shandong province chlor-alkali clusters integrate electrolysis units for byproduct acid recycling at textile and dyeing operations. MEE wastewater discharge limits penalize neutralization practices, creating compliance-driven procurement. Qingdao and Weifang industrial zones concentrate greenfield bipolar cell installations.
United States
Gulf Coast chemical producers retrofit mercury cell infrastructure under EPA Clean Air Act mandates. Texas and Louisiana chlor-alkali complexes face 18-36 month decommissioning timelines for hazardous material remediation. Merchant chlorine price volatility reinforces backward integration preferences among polyurethane value chain participants.
Belgium
Antwerp-Rotterdam chemical hub hosts integrated producers redirecting capital toward electrolysis-based recycling. REACH enforcement and fluorinated greenhouse gas reporting requirements constrain legacy process equipment. Covestro AG operations exemplify captive supply security strategies across the Scheldt-Rhine corridor.
Japan
Mitsui Chemicals and Sumitomo Chemical operations in Chubu and Kansai regions sustain membrane cell deployments for electronics-grade chlorine. METI industrial decarbonization frameworks revalue low-emission process technologies. Osaka-Kobe chemical complexes prioritize faradaic efficiency optimization in cell stack design.
Hydrochloric Acid Electrolysis Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the hydrochloric acid electrolysis landscape. Engineering-procurement-construction channels concentrate around bundled service agreements, while membrane technology licensors occupy distinct premium positions. Three archetypes dominate: integrated chemical producers with captive chlorine demand, specialized electrochemical engineering firms, and materials science specialists focused on ion exchange membranes. Competitive moves center on strategic partnerships for project development and technology licensing arrangements that extend membrane replacement revenue streams.
Among European engineering specialists, thyssenkrupp nucera and Industrie De Nora S.p.A. exemplify the project-execution archetype with bundled lifecycle contracts. DuPont de Nemours, Inc. occupies a materials science position anchored in perfluorinated membrane chemistry. These three companies represent the tier where technology differentiation and service integration converge most tightly.
| Leading Market Players |
|---|
| Bluestar (Beijing) Chemical Machinery Co. Ltd. |
| Mitsui Chemicals |
| thyssenkrupp nucera |
| Wacker Chemie AG |
| Sumitomo Chemical |
| Industrie De Nora S.p.A. |
| DuPont de Nemours, Inc. |
| Emerson Electric Co |
| Covestro AG |
| Others |
Value Chain & Pricing Dynamics
Four-to-seven year membrane replacement cycles concentrate pricing power with perfluorinated membrane licensors, while EU F-Gas Regulation compliance costs and China's MEE enforcement reshape procurement economics across chemical parks. Inventory turns for ion exchange membranes track regulatory retrofit schedules rather than pure demand signals, tethering working capital to emissions accountability timelines.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across European chemical parks, separating bundled lifecycle service contracts from equipment-only transactions. Pricing stratifies across premium membrane cell systems with faradaic efficiency guarantees, standard bipolar configurations, and economy diaphragm alternatives for remote mining deployment. Cost compression in standard tiers intensifies as Chinese engineering-procurement-construction firms scale bipolar manufacturing. Chemical industry buyers exhibit lowest price sensitivity due to captive chlorine supply security priorities, while municipal water treatment plants face capital budget constraints that favor phased procurement.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for perfluorinated membranes manufactured in Japan and the United States. Supply concentrates in Germany for engineering-procurement-construction integration, China for bipolar cell manufacturing, and Japan for electronics-grade membrane materials. The supply chain draws from fluoropolymer feedstocks, titanium electrode substrates, and specialized electrochemical engineering talent pools. Single-source vulnerability sits with ion exchange membrane chemistry licensors. Distribution runs through engineering-procurement-construction channels with bundled service agreements displacing direct equipment sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane replacement services and remote monitoring subscriptions expand faster than hardware sales, creating service-attach economics that favor long-term contract structures over transactional equipment procurement.
For Market Incumbents: Compound lifecycle service revenue through 10-15 year bundled agreements that lock in membrane replacement schedules and energy performance guarantees. Defend against emerging Chinese bipolar cell manufacturers by deepening captive supply relationships with integrated isocyanate producers in Germany and Belgium. Prioritize faradaic efficiency optimization R&D to maintain technology differentiation as mercury cell retrofits complete. For New Entrants and Emerging Players: Remote monitoring and predictive maintenance under-service by incumbent engineering-procurement-construction firms creates entry space for specialized electrochemical software providers. Target Australia's mining sector with containerized mobile electrolysis units where membrane logistics complexity has suppressed incumbent penetration. Pursue channel partnerships with regional water treatment engineering firms to bypass capital-intensive direct sales infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with captive electrolysis operations outside core strategic focus. Long-term viability hinges on regulatory enforcement durability across EU and Chinese emissions frameworks. Watch membrane replacement cycle pull-through rates as the inflection signal for service revenue quality.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Manufacturing | Captures replacement cycle economics from DuPont and Asahi Kasei licensors. |
| Bipolar Cell Architecture Scale-Up | Compresses project timelines for Shandong province chlor-alkali clusters. |
| Lifecycle Service Contract Expansion | Locks in 10-15 year revenue visibility with Covestro and BASF complexes. |
| Carbon Border Adjustment Positioning | Qualifies low-emission chlorine for EU CBAM-compliant sourcing premiums. |
| Mobile Electrolysis Unit Development | Opens Australian and Canadian mining sectors to remote acid regeneration. |
Study Parameters
Desk research of customs trade databases, chlor-alkali industry association filings, and regulatory enforcement records preceded structured interviews with plant managers at integrated chemical complexes, procurement leads at downstream polyurethane OEMs, and aftermarket service heads at electrochemical engineering firms. Primary fieldwork with membrane cell operators and bipolar stack designers combined with secondary validation against SEC 10-K disclosures and MEE enforcement bulletins. Bottom-up installation counts and top-down chemical industry capex analysis were triangulated to anchor market sizing.
Variance decomposition across product architecture, application purity requirements, end-user procurement models, and regional regulatory clusters shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro chlor-alkali capacity expansion. Modeled inputs included EU F-Gas Regulation retrofit schedules, China's MEE enforcement intensity indices, and membrane replacement cycle pull-through assumptions.
Material uncertainties — regulatory enforcement delays, fluoropolymer feedstock availability shocks, and electrochemical engineering talent migration — sit outside the modeled envelope. Forecasts reflect documented assumptions about emissions accountability durability and bipolar cell adoption velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Sodium Chloride Market
Bulk Chemicals
Bistrifluoromethanesulfonimide Lithium Market
Bulk Chemicals
Asia-Pacific Starch Derivatives Market
Bulk Chemicals
Global Acrolein Market
Bulk Chemicals
Barite Market
Bulk Chemicals
ASEAN Sulfur Market
Bulk Chemicals
Battery Grade Lithium Chloride Market
Bulk Chemicals
Propionic Anhydride Market
Bulk Chemicals
Mercaptan Market
Bulk Chemicals
Methyl Mercaptan Market
Bulk Chemicals
Sodium Permanganate Market
Bulk Chemicals
Asia-Pacific Lithium Chloride Market
Bulk Chemicals
Magnesium Sulfate Market
Bulk Chemicals
Tributyl Citrate Market
Bulk Chemicals
Magnesium Lactate Market
Bulk Chemicals
Castor Oil Derivatives Market