
 Compacted Graphite Iron Market | 2026-2036
Compacted Graphite Iron Market Size, Share, and Industry Trends Forecast 2026-2036
Compacted Graphite Iron Market Intelligence
The modularization of engine block designs is realigning procurement patterns among automotive OEMs, favoring foundries that can deliver complex, pre-machined components. SinterCast AB specializes in the process control technology essential for consistent CGI production quality. Tupy S.A. leverages its large-scale casting capabilities to serve major heavy equipment suppliers across the Americas. Georg Fischer differentiates through its integrated casting and machining solutions for global automakers in Europe and Asia.
Compacted Graphite Iron is a cast iron featuring interconnected, blunted graphite particles, achieving a balance between the properties of gray and ductile iron. This material offers higher tensile strength and thermal conductivity compared to conventional gray iron, making it ideal for components under high stress. Its primary purpose is manufacturing parts subjected to significant thermal and mechanical loads. Automotive engine components, such as cylinder blocks and heads, constitute the largest product type segment, while heavy machinery parts for construction equipment represent a fast-growing area of use.
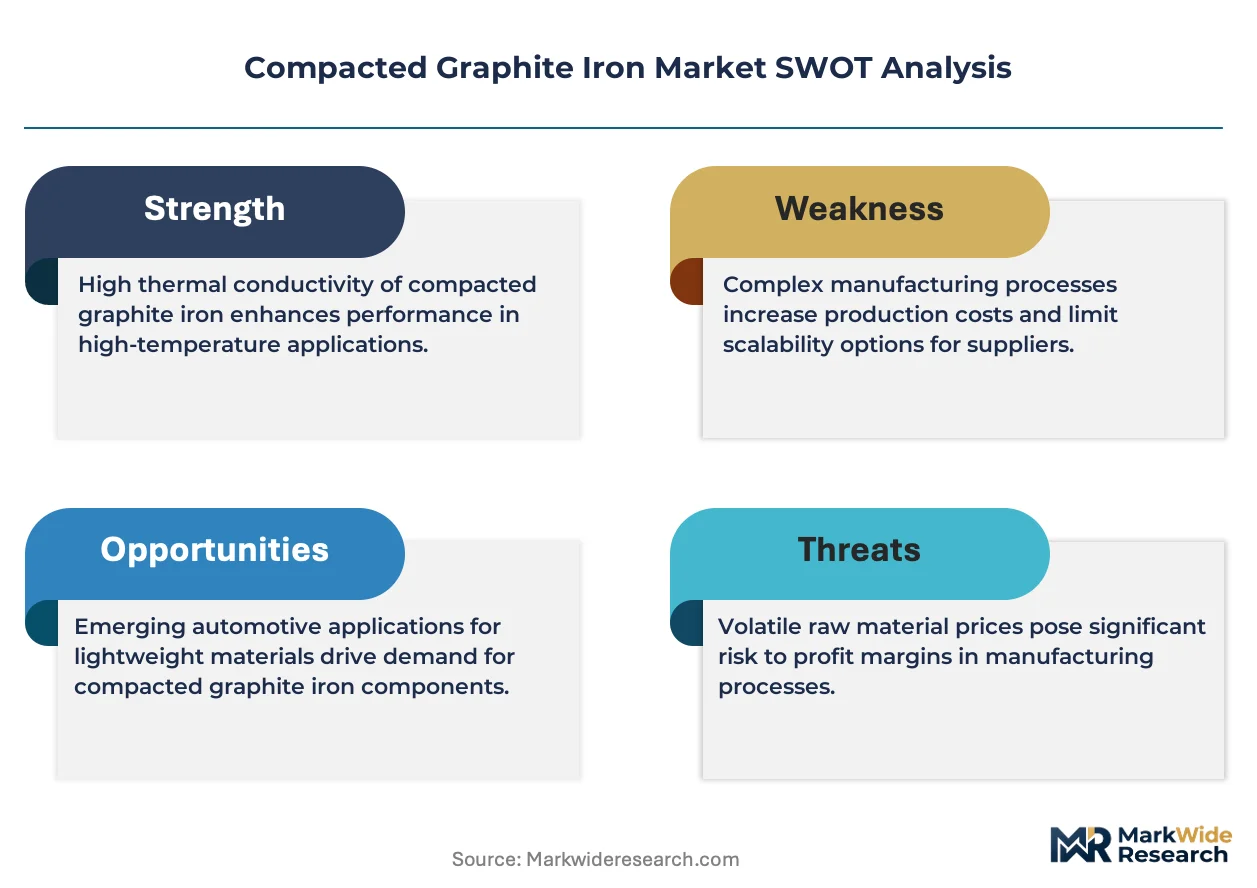
Stricter emissions regulations, including the US EPA's vehicle standards and the EU Green Deal's mandates, compel automakers to adopt lighter, stronger engine materials like CGI. In parallel, China's GB standards for heavy-duty vehicles create similar pressures on its domestic manufacturers. Foundries and material suppliers must now navigate the long-term investment horizon for advanced internal combustion engine components against the accelerating transition to electric powertrains.
Market Dynamics
The central dynamic in the compacted graphite iron market is the structural tension between tightening emissions regulations, which necessitate stronger engine materials like CGI, and the automotive industry's accelerating pivot to electric vehicle powertrains, which threatens the long-term viability of internal combustion engine component investments.
Growth Catalysts
- Stricter Emissions Standards:Regulations such as China's GB standards for heavy-duty vehicles and the US EPA's vehicle standards mandate lower emissions, pushing manufacturers to design higher-pressure engines that require the superior strength and thermal durability of CGI.
- Heavy Machinery Applications:Demand for CGI in non-automotive sectors, including construction, agriculture, and mining equipment, is expanding due to the material's ability to withstand extreme thermal and mechanical loads in large-displacement diesel engines.
- Casting Process Innovation:The development of advanced thermal analysis and automated process control systems improves the consistency and yield of CGI production, lowering manufacturing costs and making the material more competitive against conventional cast irons.
Market Restraints
- Higher Production Costs:CGI manufacturing involves precise metallurgical controls and specialized alloy additions, such as magnesium and rare earth elements, resulting in higher material and processing costs compared to traditional gray or ductile iron castings.
- Substitution from Aluminum Alloys:In certain passenger vehicle engine applications where extreme strength is not the primary requirement, lightweight aluminum alloys present a significant substitution threat, offering greater weight reduction benefits.
- Narrow Processing Window:Achieving the specific interconnected graphite microstructure of CGI requires a very narrow and difficult-to-control processing window, demanding sophisticated foundry technology and rigorous quality assurance that increases operational complexity.
Strategic Opportunities
- Industrial and Marine Engines:The material's high strength and fatigue resistance create opportunities in large-bore engines for marine propulsion and stationary power generation, applications where durability and long service life are critical performance metrics.
- Market Penetration in India:India's growing automotive and industrial manufacturing sectors, coupled with nascent emissions control policies, represent a significant opportunity for CGI adoption as local OEMs upgrade engine technologies.
- Digital Twin Integration:Combining casting simulation software with real-time process control data allows for the creation of digital twins of the production process, enabling predictive quality control and optimization of material properties.
Industry Challenges
- High Capital Expenditure:Foundries face substantial capital investment requirements to upgrade or install the specialized melting furnaces, treatment stations, and automated process control systems necessary for reliable, high-volume CGI production.
- Specialized Talent Scarcity:A shortage of metallurgists and process engineers with the specific expertise required to manage the sensitive CGI production process poses a significant operational challenge for foundries entering the market.
- Investment Justification:The long-term investment horizon for advanced internal combustion engine components clashes with the accelerating industry transition to electric powertrains, creating uncertainty for foundries and their capital allocation strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compacted Graphite Iron Market |
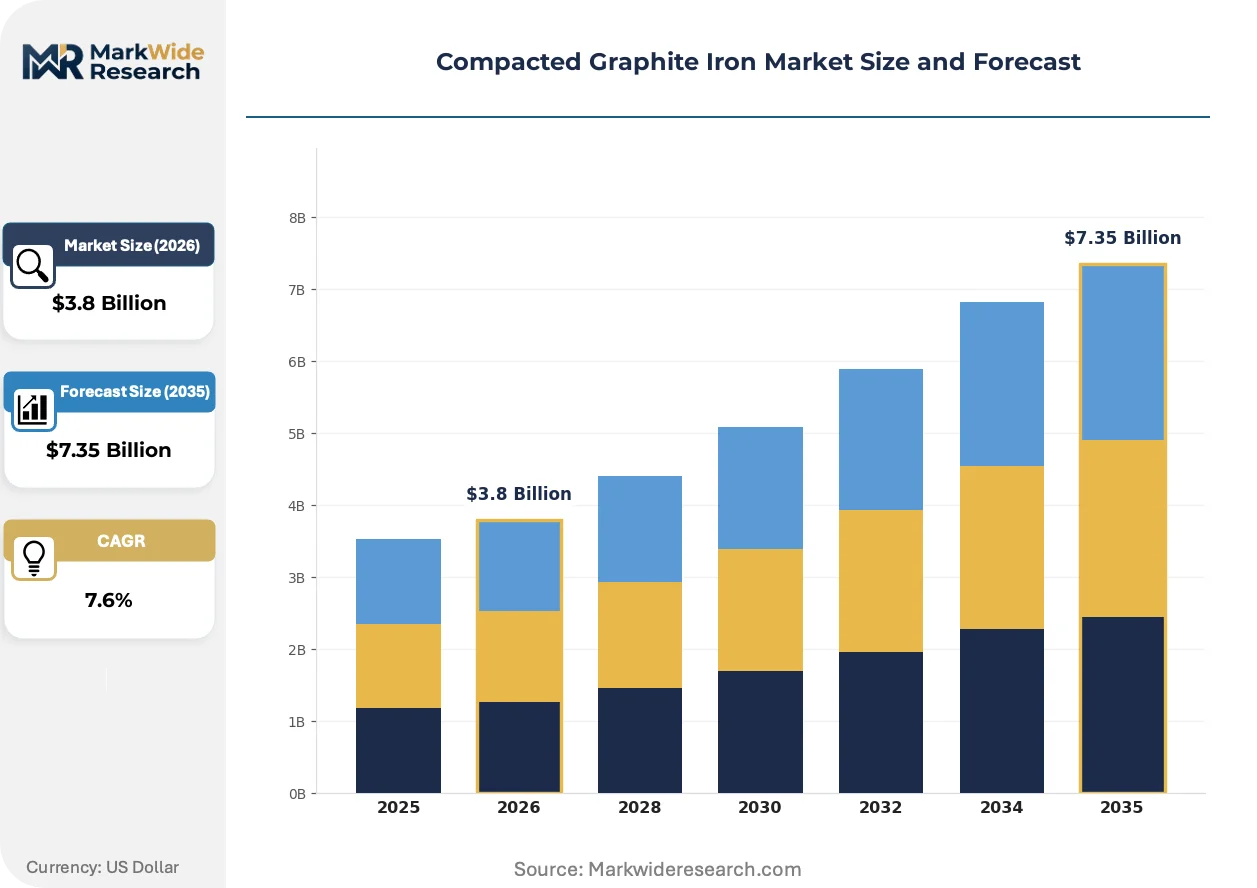
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automotive Engine Components, Heavy Machinery Parts, Pump Housings, Valve Bodies, Turbocharger Components Technology: Spheroidal Graphite Casting, CGI Casting, Thermal Treatment, Surface Coating, Sand Casting Application: Power Generation, Construction Equipment, Agricultural Equipment, Mining Machines, Oilfield Equipment End User: OEMs, Industrial Equipment Manufacturers, Pump Manufacturers, Heavy Equipment Suppliers, Aftermarket Providers |
| Companies Covered | Georg Fischer, YTO Group Corporation, SinterCast AB, Thyssenkrupp AT.PRO tec, Fagor Ederlan, Tupy S.A., FAW Foundry, Ductile Iron Pipe Company, Waupaca Foundry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compacted Graphite Iron Market Strategic Shifts & Innovations
Performance optimization for internal combustion engines is converging with advanced material science, driven by the final wave of emissions regulations. This dynamic forces foundries to adopt new process technologies and business models to serve a market undergoing a fundamental powertrain transition.
Advanced thermal analysis systems provide real-time monitoring of molten iron chemistry and cooling characteristics before casting. Automotive and heavy-duty equipment foundries are the primary adopters, seeking to improve first-pass quality and reduce scrap rates. This technology is automating the complex metallurgical adjustments required for CGI, minimizing variations that were previously managed through manual sampling and operator experience.
China's GB standards for heavy-duty vehicle emissions are a significant regulatory driver. These rules require engine designs that can withstand higher combustion pressures, making conventional materials insufficient. The heavy-duty commercial vehicle segment in China is therefore the most affected, accelerating a design shift from gray iron to CGI for critical components like cylinder blocks and heads.
A preference for integrated, pre-machined components is altering OEM buying behavior. This trend disrupts the traditional foundry model of supplying only raw castings, favoring suppliers who can deliver complex, ready-to-assemble engine blocks. This shift is most pronounced among German automakers, who are using this procurement strategy to simplify their supply chains and reduce final assembly complexity.
Compacted Graphite Iron Market Segmentation
The compacted graphite iron market segments reflect the diverse engineering demands across various industrial applications. Understanding these distinctions helps foundries and material suppliers align their production capabilities with specific performance requirements. Each segment defines unique material property needs, production complexities, and end-user expectations for strength and durability.
Product Type:
Buyers in this category differentiate based on the specific thermal and mechanical stress profiles required for the engine component. Each product type dictates distinct material specifications and post-casting processing.
- Automotive Engine Components:These parts, primarily cylinder blocks and heads, demand high tensile strength and thermal conductivity for internal combustion engines. China and Germany represent major production centers for these high-performance components, driven by stricter emissions standards.
- Heavy Machinery Parts:Components for construction, agriculture, and mining equipment require exceptional fatigue resistance and durability under extreme loads. Demand for these robust parts expands across the Americas, particularly from major heavy equipment suppliers.
- Pump Housings:These components necessitate good wear resistance and pressure containment for industrial and marine fluid handling systems.
- Valve Bodies:Valve bodies require precise dimensional stability and resistance to high temperatures and corrosive fluids.
- Turbocharger Components:Turbocharger parts operate under extreme heat and pressure, demanding CGI's superior thermal fatigue resistance.
Volume sits with Automotive Engine Components; growth tilts toward Heavy Machinery Parts.
Technology:
The maturity of the casting process and the precision required for microstructure control largely define the technology segment. Advanced methods ensure consistent quality and material performance.
- CGI Casting:This process involves precise metallurgical control to achieve interconnected, blunted graphite particles, balancing strength and thermal conductivity. Advanced thermal analysis systems are crucial for consistent CGI production quality in foundries globally.
- Thermal Treatment:Post-casting thermal processes enhance mechanical properties and relieve internal stresses in CGI components, optimizing material performance for high-stress applications. This treatment is critical for cylinder blocks and heads.
- Spheroidal Graphite Casting:This conventional method produces ductile iron with spherical graphite, offering good ductility but lower thermal conductivity than CGI.
- Surface Coating:Applied to cast components, surface coatings improve wear resistance, corrosion protection, and reduce friction in demanding environments.
- Sand Casting:A traditional and versatile casting method, sand casting forms the basis for many iron component production processes, including initial CGI shapes.
CGI Casting technology continues to advance, driving material adoption across high-performance applications.
Application:
The operating environment and load demands primarily define the application segments for compacted graphite iron. Each sector presents unique challenges for material durability and component longevity.
- Construction Equipment:This sector utilizes CGI for large-displacement diesel engines and hydraulic components requiring high strength and resistance to mechanical shock. Demand is strong in markets upgrading infrastructure, including China and India.
- Power Generation:Large-bore industrial and marine engines for stationary power generation and propulsion benefit from CGI's high strength and fatigue resistance. These applications demand long service life and robust performance.
- Agricultural Equipment:Components for tractors and other farm machinery require robust materials to withstand continuous operation and environmental exposure.
- Mining Machines:Heavy-duty mining equipment uses CGI for engine and structural parts that endure extreme abrasive conditions and high stresses.
- Oilfield Equipment:CGI finds use in components for drilling and extraction machinery, where durability under high pressure and corrosive conditions is essential.
Demand for CGI in construction equipment is robust, while power generation applications offer significant future expansion.
End User:
The level of integration and component complexity required differentiates end-users in the compacted graphite iron market. Procurement patterns vary significantly between direct manufacturers and parts suppliers.
- OEMs:Automotive and heavy equipment OEMs increasingly favor foundries that can deliver complex, pre-machined CGI components directly for assembly. German automakers demonstrate a strong preference for these integrated solutions.
- Heavy Equipment Suppliers:These companies procure CGI castings for large-scale machinery used in construction, mining, and agriculture. Tupy S.A. leverages its casting capabilities to serve major heavy equipment suppliers across the Americas.
- Industrial Equipment Manufacturers:Manufacturers of pumps, compressors, and other industrial machinery utilize CGI for its superior strength and wear resistance.
- Pump Manufacturers:Specialized pump manufacturers require CGI for housings and impellers that can withstand high pressures and abrasive fluids.
- Aftermarket Providers:These suppliers provide replacement CGI components for maintenance and repair across various industries.
OEMs are central to direct procurement, with heavy equipment suppliers representing a rapidly expanding end-user segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global compacted graphite iron market exhibits a clear divide between major production hubs and rapidly expanding consumption centers. Foundries in established automotive manufacturing regions often lead in advanced CGI casting technologies. Emerging economies increasingly drive demand for heavy machinery and industrial applications, necessitating localized production or efficient import channels.
China
China's demand for compacted graphite iron stems from its vast automotive and heavy-duty vehicle manufacturing base. The nation's GB standards for heavy-duty vehicle emissions mandate higher-pressure engines requiring CGI's superior strength. Production in the Yangtze River Delta region, particularly in cities like Shanghai and Nanjing, focuses on supplying critical engine components to domestic and international OEMs.
Germany
German automakers and industrial equipment manufacturers are significant adopters of compacted graphite iron, valuing its performance in high-stress applications. The EU Green Deal's mandates for lower emissions compel German engineering firms to optimize engine efficiency with advanced materials. The industrial clusters in Bavaria and Baden-Württemberg lead in integrated casting and machining solutions for global automakers.
United States
United States demand for CGI is driven by its robust heavy machinery sector and ongoing efforts to meet stricter emissions regulations for commercial vehicles. The US EPA's vehicle standards encourage the adoption of stronger, lighter engine components. Foundries in the Midwest, particularly around Michigan and Ohio, specialize in supplying large-displacement diesel engine parts for agricultural and construction equipment.
India
India's growing automotive and construction equipment sectors represent a significant opportunity for compacted graphite iron market penetration. Nascent emissions control policies, coupled with a push for domestic manufacturing, will accelerate material adoption. Industrial hubs like Pune and Chennai are becoming centers for engine component production, serving both local and export markets.
Brazil
Brazil's heavy equipment manufacturing for agriculture and mining drives its demand for compacted graphite iron, particularly for large diesel engines. The country's strong industrial base in states like São Paulo supports foundries with significant casting capabilities. Tupy S.A., based in Joinville, leverages its scale to serve major heavy equipment suppliers across the Americas.
Compacted Graphite Iron Market Key Industry Players
The competitive structure tilts toward specialized foundries and material technology providers that can manage the complex production of compacted graphite iron. This market is characterized by a tiered structure, with a few large integrated players and numerous specialized foundries. Strategic archetypes include technology licensors, large-scale casting specialists, and integrated solution providers. Dominant competitive moves involve capacity expansion in key geographic markets and strategic partnerships for technology transfer.
Within the large-scale casting specialist tier, Tupy S.A. from Brazil exemplifies a major heavy equipment supplier. Germany-based Georg Fischer differentiates through its integrated casting and machining solutions, serving global automakers. SinterCast AB, a Swedish company, represents a technology licensor, specializing in process control for consistent CGI production quality across foundries worldwide.
| Leading Market Players |
|---|
| Georg Fischer |
| YTO Group Corporation |
| SinterCast AB |
| Thyssenkrupp AT.PRO tec |
| Fagor Ederlan |
| Tupy S.A. |
| FAW Foundry |
| Ductile Iron Pipe Company |
| Waupaca Foundry |
| Others |
Cost & Logistics Intelligence
OEMs' preference for integrated, pre-machined components drives demand for foundries capable of complex manufacturing, influencing pricing strategies and supply chain configurations. This shift requires suppliers to invest in advanced capabilities, which impacts material and processing costs across the value chain.
Pricing Analysis
Cost-down pressure on specialized foundries intensifies as automotive OEMs seek to optimize their supply chains amid powertrain transitions. The dominant pricing model involves contract-based long-term offtake agreements with major buyers. Price differentiation stems from CGI microstructure consistency, specialized post-casting treatments, and the level of pre-machining provided. Buyer price sensitivity is highest among passenger vehicle OEMs, who balance performance with weight reduction, while heavy machinery suppliers prioritize durability over marginal cost savings.
Supply Chain Analysis
Domestic manufacturing mandates in key regions like China and India reshape sourcing patterns for compacted graphite iron components. Geographic supply concentration centers in China, Germany, and Brazil, which possess large-scale casting capabilities. The supply chain draws from critical raw materials such as magnesium and rare earth elements, essential for CGI's unique properties. Single-source vulnerability for specialized process control technology and commodity price volatility for alloy additions pose structural risks. Distribution runs through direct supply channels to automotive and heavy equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The compacted graphite iron market is fundamentally a vertical-integration race, with foundries pursuing integrated casting and machining solutions to meet evolving OEM demands.
For Market Incumbents: Lock in long-term supply agreements with major automotive and heavy equipment OEMs to secure volume against the accelerating electric powertrain transition. Invest in advanced thermal analysis and automated process control systems to maintain consistent CGI quality and reduce scrap rates. Expand integrated casting and machining capabilities, particularly in regions like Germany, to deliver ready-to-assemble components. Pursue certification investments for high-stress, non-automotive applications, diversifying revenue streams.
For New Entrants and Emerging Players: Enter via strategic partnerships with local OEMs in rapidly industrializing markets like India, leveraging nascent emissions control policies. Target non-automotive heavy machinery applications, such as construction and agricultural equipment, where demand for durability remains robust. Focus on developing specialized expertise in CGI casting for large-displacement diesel engines, offering a performance advantage. Prioritize advanced process control technology to ensure consistent quality from the outset, overcoming entry barriers.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized foundries demonstrating advanced process control and integrated machining capabilities, given the ongoing demand for high-performance ICE components. Over the next decade, CGI remains critical for applications requiring superior strength and thermal durability in internal combustion engines. Monitor increased adoption in marine propulsion or stationary power generation engines as a signal of market diversification. Evaluate companies with strong intellectual property in casting process innovation or those expanding into high-growth regions like India.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Key Regions | Increases ability to meet growing demand from construction equipment and automotive sectors in markets like India. |
| Technology Licensing for Process Control | Enhances production consistency and reduces manufacturing costs for foundries adopting CGI casting methods. |
| Integrated Casting and Machining Solutions | Simplifies OEM supply chains by providing complex, ready-to-assemble engine components, reducing final assembly complexity. |
| Joint Ventures with Heavy Equipment OEMs | Secures long-term contracts and aligns product development with specific needs of large-displacement diesel engines. |
| Investment in Green Foundry Technologies | Aligns with global sustainability mandates and attracts environmentally conscious automotive manufacturers and industrial clients. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a foundational understanding of the compacted graphite iron market landscape. Primary interviews with foundry managers, automotive OEM procurement leads, heavy equipment R&D engineers, and material scientists validated market dynamics. This approach combined bottom-up data aggregation with top-down market sizing for comprehensive analysis.
Market volume and value were modeled at a granular level across the analysis window, segmenting by product type, technology, application, end-user, and regional production capacity. Compound Annual Growth Rates (CAGRs) were derived from historical trends, projected material adoption rates, and anticipated shifts in internal combustion engine production. Emissions regulation timelines and heavy machinery production forecasts served as key industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of accelerating EV transition or severe raw material price volatility. Forecasts reflect assumptions regarding technological advancements and regulatory enforcement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Tantalum Pentoxide Market
Metals & Minerals
Andalusite Market
Metals & Minerals
Pyroxenite Market
Metals & Minerals
Recycled Lead Market
Metals & Minerals
Frac Sand Market
Metals & Minerals
Manganese Mining Market
Metals & Minerals
Zinc Sulphate Market
Metals & Minerals
North America and EMEA Ferrosilicon Market
Metals & Minerals
Diamond Market
Metals & Minerals
Global Magnesium Oxide Market
Metals & Minerals
Californium Market
Metals & Minerals
Ilmenite Market
Metals & Minerals
Zinc Hydroxide Market
Metals & Minerals
Global Ferrous Scrap Recycling Market
Metals & Minerals
Bauxite Mining Market
Metals & Minerals
Recycled Copper Market