
 Pyroxenite Market | 2026-2036
Pyroxenite Market Size, Share, and Industry Trends Forecast 2026-2036
Pyroxenite Market Analytics
Steelmakers and chemical manufacturers is redrawing procurement patterns in the pyroxenite market as fluxing-grade material gains priority over construction aggregate. Tata Steel Ltd. leverages captive mining assets in India to secure consistent feedstock for its integrated steel operations. Foskor Ltd anchors Southern African supply through its Phalaborwa complex, specializing in pyroxenite with high olivine content for metallurgical flux. Anglo American plc competes across multiple continents with vertically controlled extraction and beneficiation infrastructure.
Pyroxenite is an ultramafic igneous rock composed predominantly of pyroxene group minerals, typically containing 40-90% pyroxene alongside olivine and spinel, with magnesium oxide content often exceeding 15% in ore-grade deposits; manufacturers crush and screen it for fluxing in steelmaking or grind it to powder for refractory linings. Natural pyroxenite dominates volume due to established quarry economics, while pyroxenite powder captures expanding value as steelmakers seek finer grain sizes for submerged-arc furnace efficiency. The metallurgy application leads absolute consumption, though soil stabilization is accelerating in environmental remediation contracts where pyroxenite's high pH buffering capacity replaces synthetic additives.
China's MEE enforces emissions caps on ferroalloy production that elevate demand for low-sulfur pyroxenite flux, while India's CEA mandates beneficiation standards for mine waste reuse that directly affect pyroxenite tailings processing. ISO 9001 quality certification and REACH compliance in Europe restrict heavy-metal leaching from construction-grade aggregate, filtering market access for unprocessed exports. Stakeholders must monitor evolving carbon-border adjustments and ore-grade specifications to align inventory positioning with regulatory thresholds.
Market Dynamics
Steelmakers' pivot toward submerged-arc furnace efficiency is compressing pyroxenite grain-size specifications and rewiring supplier qualification criteria across metallurgical procurement desks.
Growth Catalysts
- China's MEE emissions caps:Ferroalloy producers must source low-sulfur flux materials, elevating pyroxenite with sub-0.05% sulfur content to premium tier status in procurement protocols.
- Soil stabilization demand:Environmental remediation contractors in mining-heavy jurisdictions are specifying pyroxenite for pH buffering in acid mine drainage treatment, displacing synthetic lime additives.
- India's CEA beneficiation mandate:Mine waste reuse standards require pyroxenite tailings processing, creating captive supply loops for integrated steel operations with in-house crushing and magnetic separation.
Market Restraints
- Diesel and explosives input volatility:Open-pit quarry economics tie directly to fuel and blasting agent costs, squeezing margins for independent producers without long-term energy contracts.
- Deposit concentration in Southern Africa:The Phalaborwa Igneous Complex and Bushveld fringe deposits control high-olivine metallurgical grades, creating single-source vulnerability for flux-grade procurement.
- Serpentine substitution in refractory:Lower-cost ultramafic alternatives with comparable magnesia content are capturing construction-grade aggregate demand in price-sensitive Middle Eastern markets.
Strategic Opportunities
- Indonesia's nickel-pig-iron expansion:Pyrometallurgical complexes in Sulawesi and Halmahera require magnesia-rich flux for laterite smelting, opening import demand for screened pyroxenite lump.
- EU Carbon Border Adjustment Mechanism:Embodied carbon tracking favors low-transport-distance sourcing, advantaging Mediterranean and Baltic quarry operators with kiln-drying and bulk-shipping infrastructure.
- Digital assay integration:Portable XRF and LIBS analyzers at mine mouth enable real-time grade sorting, collapsing the information asymmetry that previously favored long-term offtake contracts.
Industry Challenges
- ISO 9001 certification timelines:European refractory buyers now require third-party quality system validation for construction aggregate, extending supplier onboarding from six to eighteen months.
- Magnetic separation capex:Beneficiation infrastructure for olivine-pyroxene separation demands significant capital deployment, stranding artisanal quarries without integrated processing capability.
- REACH heavy-metal documentation:Chromium and nickel leaching test protocols for construction-grade material require specialized laboratory partnerships that smaller exporters struggle to secure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pyroxenite Market |
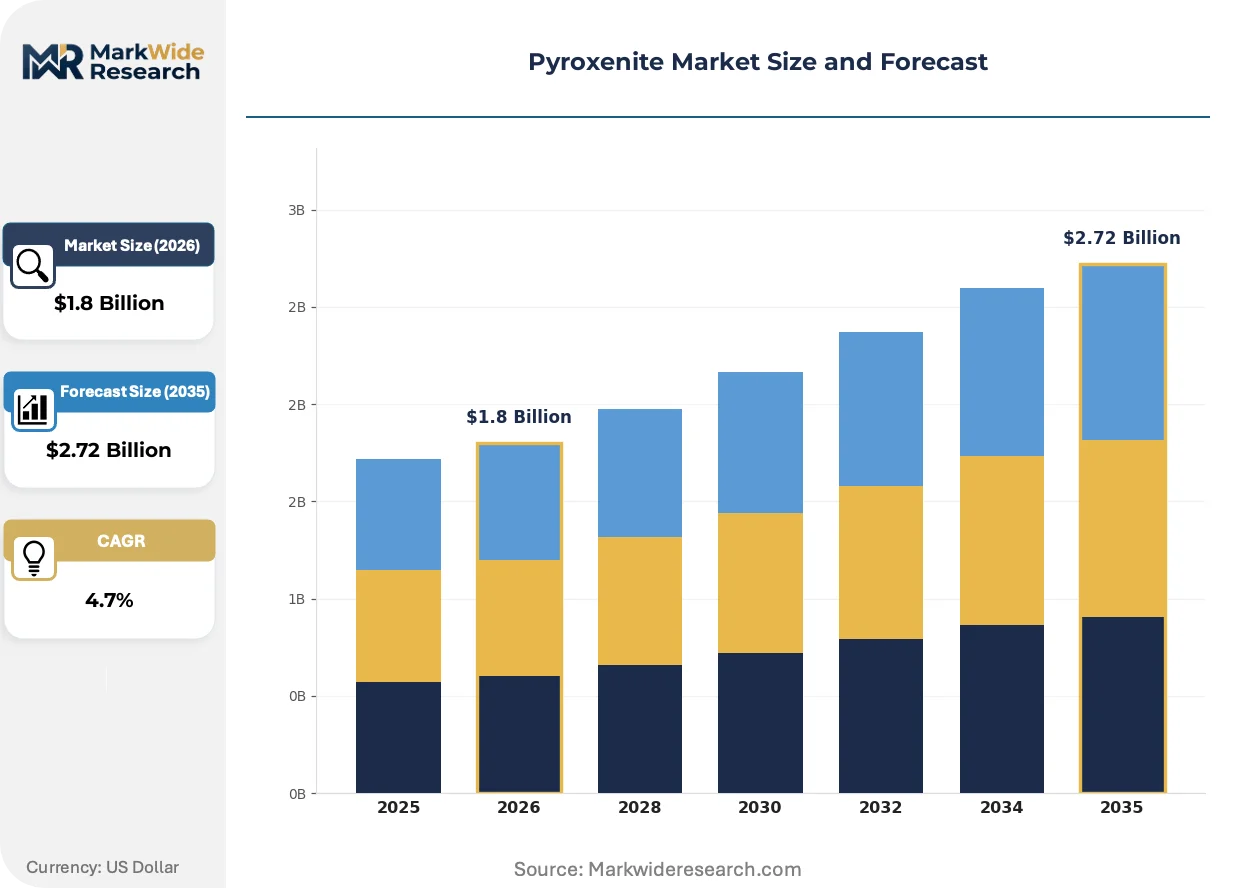
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Pyroxenite, Synthetic Pyroxenite, Pyroxenite Powder, Pyroxenite Aggregate Application: Construction, Metallurgy, Soil Stabilization, Abrasives End User: Construction Companies, Mining Industries, Chemical Manufacturers, Environmental Services Distribution Channel: Direct Sales, Online Sales, Distributors, Retail Stores |
| Companies Covered | Tata Steel Ltd., Bharat Mining Company, Foskor Ltd, Anglo American plc, Glencore Plc, Aegis Group, TVI Resource Development Philippines Inc., Omya International AG, Rio Tinto Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pyroxenite Market Evolving Landscape
Digital tools and regulatory transparency mandates are collapsing traditional information asymmetries between quarry operators and metallurgical buyers, compressing contract structures and accelerating grade verification cycles.
Real-time mineralogical analysis is fragmenting long-term supply relationships. Portable XRF and hyperspectral imaging units at mine mouths enable instantaneous pyroxene-olivine ratio reporting. Steel procurement desks in Jiangsu and Shandong provinces now demand assay certificates tied to specific blast dates rather than quarterly composite samples. This compression favors quarries with in-house analytical capability and disadvantages traders reliant on third-party laboratory turnaround.
REACH heavy-metal leaching protocols are tightening construction-grade market access. ECHA documentation requirements for chromium and nickel migration in aggregate applications now extend to pyroxenite sourced outside the European Economic Area. Indian and Brazilian exporters face extended certification timelines as notified bodies accumulate testing backlogs. Buyers with pre-qualified supplier pools are locking in multi-year offtake to bypass queue congestion.
Buyer concentration around integrated steel complexes is rewiring distribution economics. Procurement desks at coastal Chinese mills now coordinate direct vessel chartering from South African and Australian quarries, bypassing traditional bulk-terminal intermediaries. This disintermediation compresses logistics margins and places inventory risk squarely on mill balance sheets rather than trading houses. Smaller refractory manufacturers without chartering capability face sourcing premiums or extended lead times.
Pyroxenite Market Segmentation
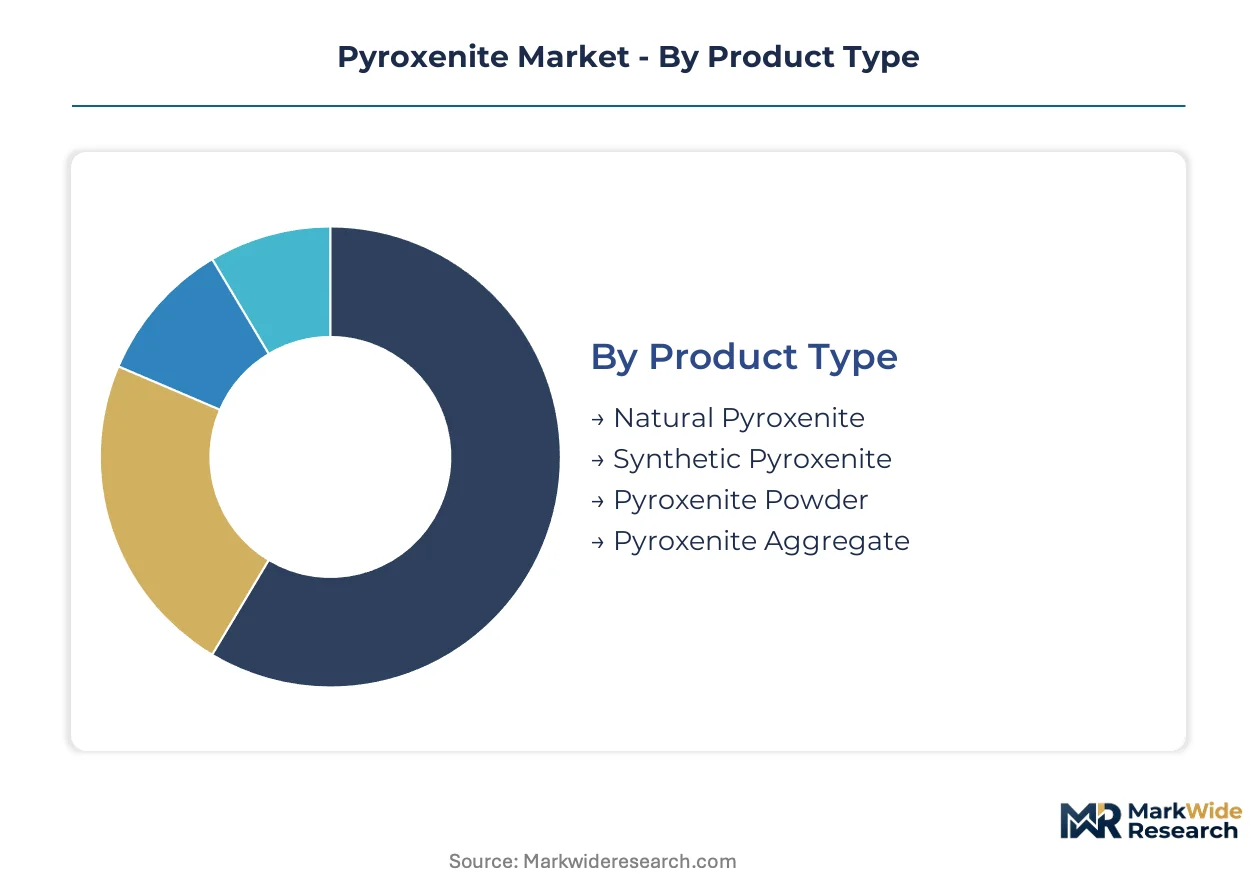
Pyroxenite procurement patterns diverge sharply across product forms and customer types, with metallurgical buyers demanding assay-certified material while construction contractors prioritize bulk logistics over grade precision. Understanding these segment boundaries clarifies where margin pools concentrate and which channels warrant capital deployment.
Product Type:
Natural pyroxenite dominates domestic quarry output across India and South Africa, while synthetic variants and refined powders flow through export-oriented beneficiation circuits in China and Australia.
- Natural Pyroxenite:Run-of-mine material with 40-90% pyroxene content serves as the baseline feedstock for steel fluxing, with Indian captive mines supplying Tata Steel's Jamshedpur complex and Foskor's Phalaborwa operations anchoring Southern African metallurgical grades. Procurement desks at Jiangsu mills specify sub-0.05% sulfur thresholds that filter accessible supply pools.
- Pyroxenite Powder:Finely ground material below 75 microns enables submerged-arc furnace efficiency gains, with Chinese ferroalloy producers in Shandong province driving import demand for screened, kiln-dried powder. MEE emissions caps on sulfur and particulate matter elevate low-impurity powder to premium tier status.
- Synthetic Pyroxenite:Slag-based engineered material replicates ultramafic chemistry for specialized refractory applications where natural deposit chemistry varies.
- Pyroxenite Aggregate:Crushed construction-grade material competes with serpentine and dolomite in Middle Eastern infrastructure projects where REACH documentation requirements do not apply.
Natural pyroxenite holds the largest share; momentum sits with pyroxenite powder.
Application:
Cost tiers separate metallurgical fluxing from construction aggregate, with soil stabilization emerging as a mid-tier environmental services play between commodity bulk and certified specialty.
- Metallurgy:Flux-grade pyroxenite with high olivine content reduces slag viscosity in basic oxygen furnaces and submerged-arc ferroalloy production. Indonesian nickel-pig-iron smelters in Sulawesi and Halmahera now specify magnesia-rich lump for laterite processing, opening new import corridors from Australian and South African quarries.
- Soil Stabilization:Pyroxenite's high pH buffering capacity displaces synthetic lime in acid mine drainage treatment, with environmental remediation contractors in mining-heavy Brazilian and Australian jurisdictions specifying ultramafic rock for tailings cap rehabilitation.
- Construction:Aggregate applications face serpentine substitution pressure in price-sensitive Gulf markets where ECHA leaching protocols do not constrain procurement.
- Abrasives:Hardness characteristics suit specialized grinding media applications with limited volume scale.
Metallurgy commands the dominant value pool; soil stabilization is expanding most quickly.
End User:
Customer type dictates contract structure, with integrated steel mills pursuing captive supply while environmental services firms bid on project-based spot procurement.
- Mining Industries:Captive quarry operations at major ferroalloy and base metal producers internalize pyroxenite supply for process fluxing, with Anglo American's vertically controlled extraction infrastructure spanning Southern Africa and South America.
- Construction Companies:Bulk aggregate buyers prioritize delivered cost per ton over grade certification, sourcing through regional distributors rather than direct quarry relationships.
- Chemical Manufacturers:Refractory and specialty chemical producers require consistent MgO and SiO2 ratios, locking in multi-year offtake with pre-qualified suppliers to bypass ISO 9001 certification queues.
- Environmental Services:Remediation contractors specify pyroxenite for pH buffering in mine closure projects, with procurement tied to regulatory enforcement timelines rather than production schedules.
Mining industries anchor volume commitment; environmental services show the steepest expansion trajectory.
Distribution Channel:
Channel selection tracks customer scale and certification burden, with direct sales capturing metallurgical procurement while distributors serve fragmented construction demand.
- Direct Sales:Steel mills and ferroalloy producers charter vessels directly from South African and Australian quarries, bypassing bulk-terminal intermediaries and compressing logistics margins. This disintermediation places inventory risk on mill balance sheets.
- Distributors:Regional bulk-material handlers aggregate construction-grade demand across multiple small contractors, extending payment terms and absorbing freight consolidation complexity.
- Online Sales:Digital platforms facilitate spot procurement for standardized aggregate grades where assay documentation is not required.
- Retail Stores:Limited to specialty refractory and hobbyist applications with minimal market presence.
Direct sales capture the dominant contract value; distributors retain relevance in fragmented construction segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated steel mills and ferroalloy producers cluster procurement around coastal metallurgical hubs, with regulatory emissions standards and captive mining economics dictating regional supply flows.
China
MEE emissions caps on ferroalloy production elevate demand for low-sulfur pyroxenite flux below 0.05% sulfur content. The country's dual carbon goals redirect sourcing toward lower-impurity deposits for submerged-arc furnace operations. Jiangsu and Shandong provinces concentrate steelmaking capacity where procurement desks coordinate direct vessel chartering from overseas quarries.
India
CEA beneficiation mandates for mine waste reuse create captive supply loops at integrated steel operations with in-house crushing infrastructure. Captive mining assets in eastern states secure consistent feedstock for basic oxygen furnace fluxing. Tata Steel's Jamshedpur complex anchors domestic metallurgical consumption with vertically controlled extraction.
South Africa
The Phalaborwa Igneous Complex controls high-olivine metallurgical grades for export to Asian steel mills. Foskor Ltd anchors regional supply through specialized pyroxenite with elevated magnesia content. Durban and Richards Bay bulk terminals handle vessel loading for direct charter routes to Chinese coastal mills.
Indonesia
Nickel-pig-iron smelter expansion in Sulawesi and Halmahera drives import demand for magnesia-rich pyroxenite lump in laterite processing. Pyrometallurgical complexes require flux materials compatible with high-iron laterite feeds. Morowali Industrial Park concentrates new smelting capacity with coordinated bulk material procurement.
Australia
Western Australian quarries supply screened pyroxenite to Indonesian nickel smelters and domestic ferroalloy producers. Port Hedland and Dampier bulk terminals enable direct vessel chartering to Asian metallurgical clusters. Environmental remediation contractors in Queensland specify ultramafic rock for acid mine drainage treatment.
Pyroxenite Market Competitive Landscape
Player mix skews toward vertically integrated mining conglomerates with captive quarry operations and specialized ultramafic producers serving export metallurgical markets. Market structure concentrates around Southern African and Indian deposit holders with established beneficiation infrastructure. Two strategic archetypes dominate: integrated steelmakers with backward mining control, and independent ultramafic specialists with regional deposit access. Competitive moves center on direct charter logistics coordination and ISO 9001 certification pre-qualification to bypass European buyer onboarding queues.
Among India-based mining operators, Tata Steel Ltd. and Bharat Mining Company occupy positions within the captive supply archetype, leveraging domestic quarry assets for integrated steel fluxing. Southern African deposit specialists include Foskor Ltd and Anglo American plc, representing the export-oriented ultramafic tier with established Phalaborwa and Bushveld fringe extraction infrastructure. These named entities exemplify the geographic bifurcation between Asian integrated steelmakers and African export specialists.
| Leading Market Players |
|---|
| Tata Steel Ltd. |
| Bharat Mining Company |
| Foskor Ltd |
| Anglo American plc |
| Glencore Plc |
| Aegis Group |
| TVI Resource Development Philippines Inc. |
| Omya International AG |
| Rio Tinto Ltd. |
| Others |
Value Network & Pricing Analysis
Scale economies at integrated steel operations compress procurement costs below independent quarry thresholds, anchoring price floors to captive mining infrastructure while marginal producers face diesel and explosives input volatility. This concentration of beneficiation capability in India and South Africa shapes tiered contract structures where metallurgical buyers with direct charter logistics command sub-0.05% sulfur premiums.
Pricing Analysis
Cost-plus contracts with diesel indexation dominate long-term offtake agreements between South African quarries and Chinese coastal mills. Price differentiation rests on sulfur certification tiers and ISO 9001 documentation status, with low-impurity flux material capturing substantial premiums over construction-grade aggregate. Pricing pressure stems from serpentine substitution in Middle Eastern refractory markets where REACH compliance is absent. Construction contractors exhibit highest price sensitivity, while ferroalloy producers in Shandong province prioritize assay consistency over unit cost.
Supply Chain Analysis
Inventory cycles at Chinese coastal mills have compressed from quarterly to blast-date specificity, eliminating buffer stock tolerance for chartered vessel delays. Supply concentrates in South Africa's Phalaborwa complex, India's eastern captive mines, and Western Australian export quarries. Raw material flows draw from open-pit olivine-pyrocene deposits, diesel fuel contracts, and magnetic separation reagents. Single-source vulnerability around high-olivine metallurgical grades creates procurement risk for flux-dependent smelters. Distribution runs through direct vessel chartering to mill berths, bypassing traditional bulk-terminal intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pyroxenite incumbents face a substitution defense against serpentine and synthetic magnesia in construction-grade and specialty refractory applications, requiring strategic positioning around certification moats and captive supply loops.
For Market Incumbents: Compound ISO 9001 pre-qualification advantages by accelerating third-party certification timelines for tailings beneficiation, locking in multi-year offtake before ECHA documentation backlogs clear. Deepen upstream control over magnetic separation infrastructure to strand artisanal competitors without integrated processing capability. Serpentine price undercutting in Gulf markets demands defensive grade-tier specialization rather than volume competition. For New Entrants and Emerging Players: Anchor in Indonesia's nickel-pig-iron corridor where laterite smelter expansion outpaces domestic flux supply, targeting magnesia-rich lump specifications for Sulawesi and Halmahera pyrometallurgical complexes. Soil stabilization contracts in Brazilian and Australian mining remediation offer project-based entry with lower certification barriers than European refractory supply. A go-to-market angle emphasizing real-time XRF assay integration at mine mouth addresses Jiangsu procurement desks' compressed verification cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated quarry-to-vessel operators with established Phalaborwa or Bushveld fringe deposit access over trading-dependent intermediaries. Long-term viability hinges on carbon-border adjustment readiness and low-sulfur reserve quality rather than volume scale. Watch for MEE emissions cap tightening as inflection signal for premium flux demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Mining | Tata Steel's Jamshedpur complex secures flux supply against diesel volatility and charter rate spikes. |
| ISO 9001 Certification Pre-Qualification | European refractory buyers now require eighteen-month validation timelines that favor incumbent certification holders. |
| Direct Vessel Chartering Infrastructure | Chinese coastal mills bypass bulk-terminal margins by coordinating quarry-to-berth logistics through Richards Bay. |
| Real-Time Assay Technology Deployment | Portable XRF units at Phalaborwa mine mouth collapse information asymmetry favoring long-term offtake contracts. |
| Tailings Beneficiation Capacity Expansion | India's CEA mandates create captive supply loops for integrated steel operations with magnetic separation infrastructure. |
Research Methodology
Cross-validation between customs trade data and ferroalloy procurement desk interviews anchors the qualitative findings in observable transaction patterns. Primary fieldwork engaged quarry operations managers, steel mill procurement leads, environmental remediation contractors, and bulk terminal logistics coordinators across India, South Africa, China, and Indonesia. Secondary sources included customs export records, MEE emissions compliance filings, CEA beneficiation standards documentation, and ISO certification registry data. Bottom-up volume estimates from individual quarry output reconciled against top-down steel production flux intensity metrics.
Sensitivity analysis around sulfur threshold compliance costs and diesel price scenarios tested forecast robustness across the projection horizon. Segmentation modeling incorporated product form, application tier, end-user archetype, and distribution channel dimensions alongside regional regulatory cluster variations. CAGRs derived from production capacity expansion announcements, smelter commissioning timelines, and import corridor development patterns. Key inputs included nickel-pig-iron smelter buildout schedules in Sulawesi and MEE emissions cap enforcement intensity.
Decision-makers should treat outputs as directional under sustained Chinese ferroalloy output and Indonesian laterite processing expansion assumptions; material deviation in carbon-border adjustment implementation or serpentine substitution rates would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Mexico Mining Market
Metals & Minerals
Diamond Market
Metals & Minerals
Global Mining Metals Market
Metals & Minerals
Flake Graphite Market
Metals & Minerals
Global Gold Potassium Cyanide Market
Metals & Minerals
Rare Earth Elements Recycling Market
Metals & Minerals
Cobalt Carbonate Market
Metals & Minerals
Direct Reduced Iron (DRI) Market
Metals & Minerals
Colored Gemstones Market
Metals & Minerals
Cobalt Sulphate Market
Metals & Minerals
Gemstones Market
Metals & Minerals
Cesium Market
Metals & Minerals
Pre-Painted Galvanised Iron (PPGI) Market
Metals & Minerals
Zellerite Market
Metals & Minerals
Electrolytic Manganese Dioxide Market
Metals & Minerals
Manganese Mining Market