
 Military Land Vehicles Market | 2026-2036
Military Land Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Military Land Vehicles Market Insights
Poland's military industrial expansion is reconfiguring European armored vehicle supply chains. BAE Systems plc sustains long-term production commitments through its Swedish and Czech facilities. Rheinmetall AG anchors Central European capacity with its new plant in Zalaegerszeg, Hungary. General Dynamics Corporation leverages its ELS program to dominate tracked platform deliveries across NATO's eastern flank.
Military land vehicles encompass wheeled and tracked platforms engineered for protected mobility, direct fire engagement, and battlefield logistics, typically incorporating steel or composite armor rated against ballistic and blast threats while operating across unprepared terrain. Their primary purpose centers on force projection, crew survivability, and mission flexibility under contested conditions. Armored Personnel Carriers and Mine-Resistant Ambush Protected Vehicles command the largest procurement volumes as asymmetric conflict patterns persist, while Hybrid Electric propulsion represents the fastest-growing segment as militaries confront fuel logistics vulnerability and signature management requirements. Main Battle Tanks retain concentrated margin pools despite contracting unit demand, reflecting extreme technical complexity and long program lifecycles.
The US Department of Defense defends platform modernization through NHTSA-derived safety benchmarks adapted for military transport, while the EU Green Deal's F-Gas Regulation constrains refrigerant choices in vehicle climate systems. Germany's KBA enforces stringent type-approval protocols for armored vehicles operating on federal road networks, creating compliance cost layers for cross-border NATO logistics. Stakeholders must weigh diesel-to-hybrid transition timelines against operational energy resilience requirements before committing next-generation propulsion architectures.
Market Dynamics
Mechanized infantry divisions across NATO's eastern flank are accelerating armored vehicle procurement as Soviet-era platforms reach obsolescence, while the EU Green Deal's emissions mandates force concurrent propulsion transitions toward hybrid architectures.
Growth Catalysts
- EU Green Deal mandates:Stricter emissions standards under the F-Gas Regulation and broader decarbonization frameworks are compelling defense ministries to fund hybrid-electric development programs.
- Poland:The government's commitment to replacing Soviet-era platforms with Western designs is generating sustained procurement volume for tracked and wheeled armored vehicles.
- Asymmetric conflict patterns:Persistent irregular warfare requirements are elevating Mine-Resistant Ambush Protected Vehicle procurement above traditional platform categories.
Market Restraints
- Steel and composite armor input costs:Ballistic-grade steel plate and ceramic composite prices fluctuate with energy-intensive smelting costs, compressing margin predictability for vehicle integrators.
- German KBA type-approval protocols:Armored vehicles operating on federal road networks face stringent cross-border certification requirements that add compliance layers to NATO logistics chains.
- Battery energy density limitations:Current lithium-ion cell performance constrains hybrid military vehicle range and silent-watch duration below operational thresholds for deep-penetration missions.
Strategic Opportunities
- Hungary:Rheinmetall's new Zalaegerszeg facility positions the country as an emerging hub for Central European armored vehicle assembly and subsystem integration.
- Silent mobility requirements:Signature management demands for contested electromagnetic environments are accelerating investment in hybrid-electric drivelines with export potential beyond NATO.
- Climate system refrigerant transition:The F-Gas Regulation's phasedown of high-global-warming-potential refrigerants creates retrofit and redesign opportunities for vehicle HVAC suppliers.
Industry Challenges
- Power electronics engineering talent:Military-grade inverter and motor control design expertise remains concentrated among a small pool of defense-aerospace specialists, constraining program staffing.
- Legacy platform integration complexity:Hybrid propulsion retrofits into existing vehicle architectures require extensive structural modification and software recertification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Land Vehicles Market |
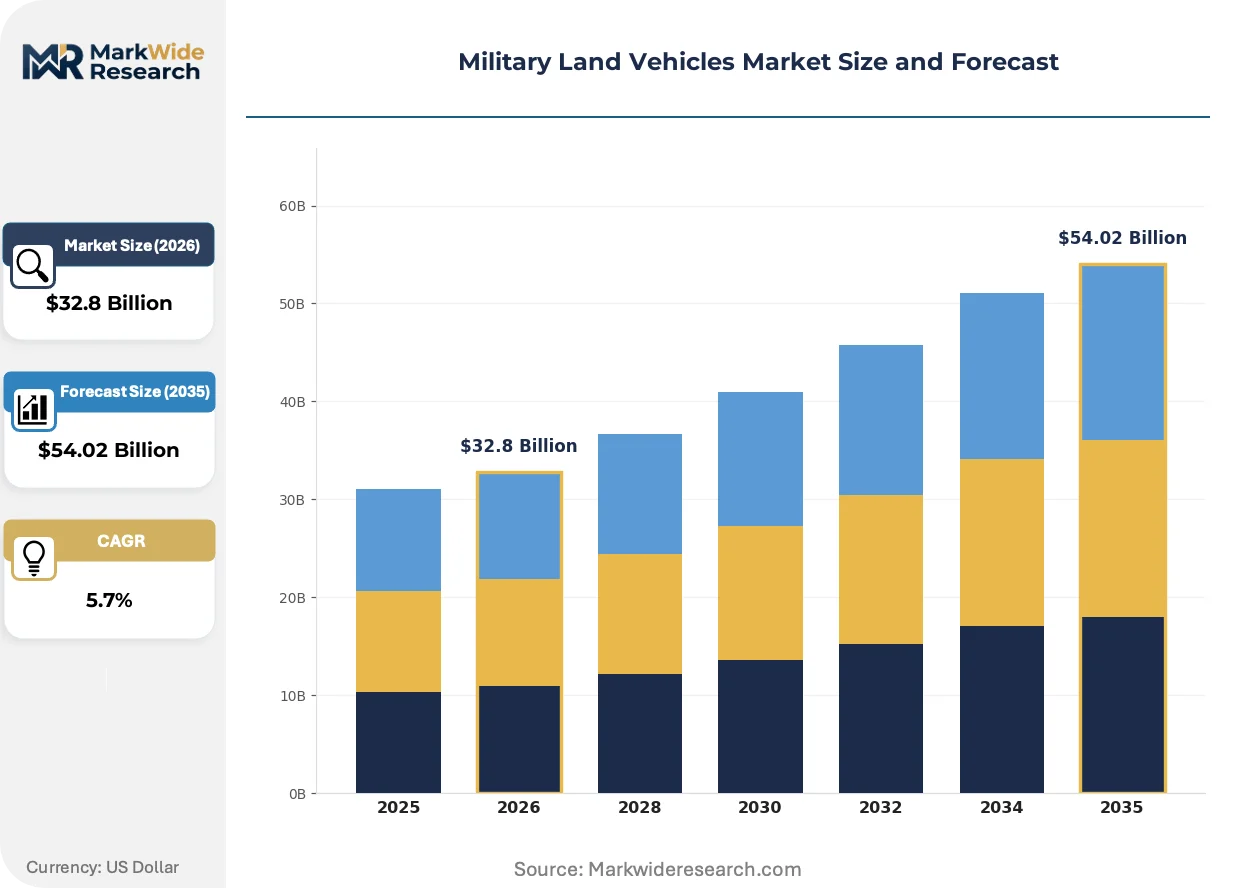
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $54.02 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Armored Personnel Carriers, Main Battle Tanks, Light Utility Vehicles, Mine-Resistant Ambush Protected Vehicles, Self-Propelled Artillery Propulsion: Diesel, Gasoline, Hybrid Electric, Fully Electric, Turbine Application: Reconnaissance, Combat Support, Troop Transport, Engineering, Command and Control End User: Ground Force Divisions, Special Forces, Border Security, Military Engineers |
| Companies Covered | General Dynamics Corporation, BAE Systems plc, Rheinmetall AG, Oshkosh Corporation, ST Engineering Ltd., Lockheed Martin Corporation, Krauss-Maffei Wegmann GmbH & Co. KG, Hyundai Rotem Company, Textron Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Land Vehicles Market Trends and Innovations
Active protection systems and signature management technologies are compressing traditional platform life cycles as militaries prioritize survivability over incremental armor upgrades.
Silicon carbide power semiconductors are replacing silicon IGBTs in traction inverters, enabling higher switching frequencies and reduced thermal loads. Armored vehicle electrification programs in Poland and Germany are adopting these devices for next-generation hybrid drivelines. Wide-bandgap electronics is collapsing the volume and cooling requirements for onboard power conversion, freeing hull space for mission equipment or additional protection.
The EU Green Deal's F-Gas Regulation is prohibiting refrigerants with global warming potential above specified thresholds in vehicle climate systems. Defense contractors must redesign HVAC packages using hydrofluoroolefin or natural refrigerant alternatives before phaseout deadlines. Tracked platform programs face the steepest redesign burden due to sealed hull environments and extreme operating temperature ranges.
Buyer concentration among NATO procurement agencies is consolidating requirements into multi-national framework contracts. Traditional bilateral negotiations between single nations and prime contractors are yielding to pooled acquisition structures led by the NATO Support and Procurement Agency. This pattern is most visible in Poland, where the Ministry of National Defense coordinates requirements with the Czech Republic and Slovakia under regional defense cooperation agreements.
Military Land Vehicles Market Segmentation
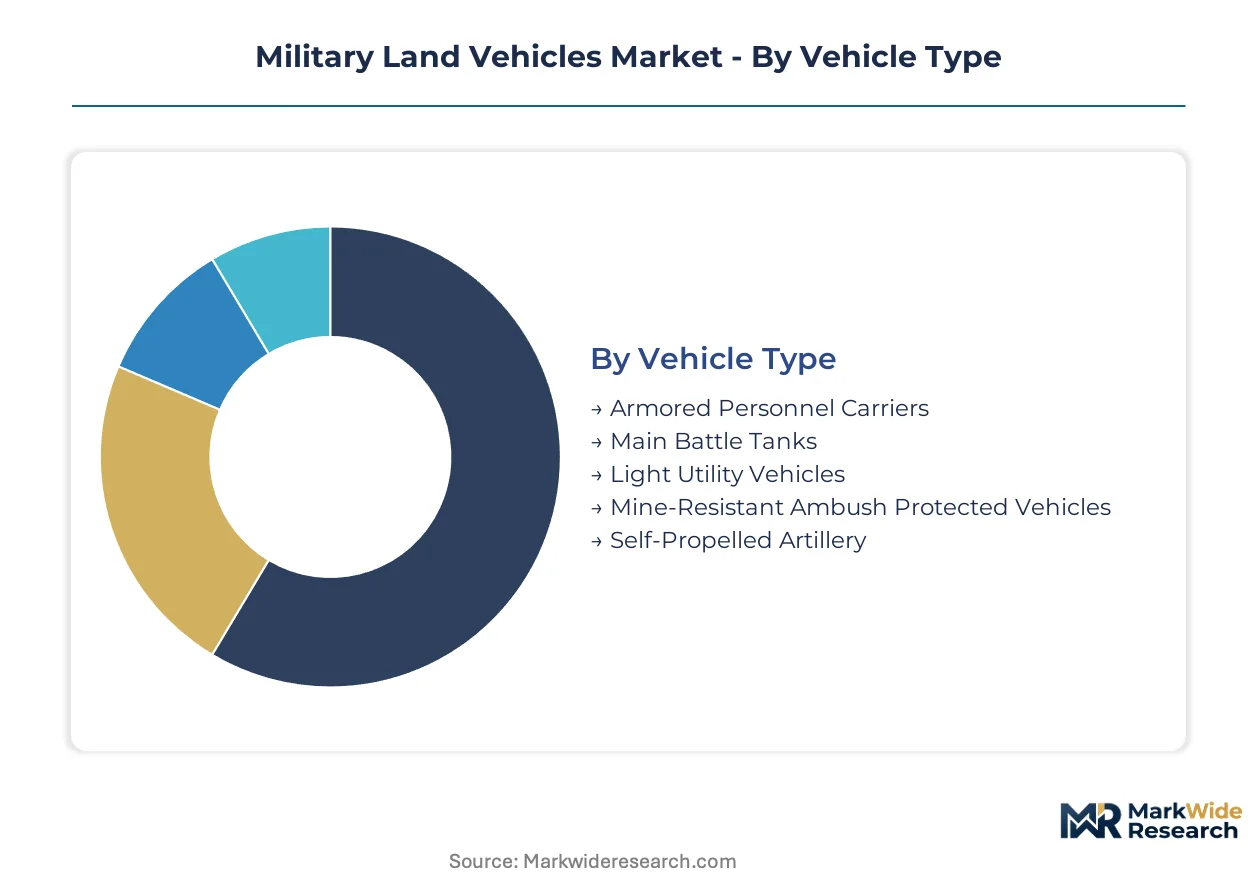
Segmentation in military land vehicles reveals how procurement priorities split across platform maturity, propulsion risk tolerance, and mission specialization. Buyers optimize fleet composition by balancing proven combat performance against emerging signature management requirements.
Vehicle Type:
Mature heavy platforms anchor defense budgets while emerging protected mobility concepts reshape procurement patterns.
- Armored Personnel Carriers:Steel or composite-hulled platforms rated against 7.62mm ball and artillery fragmentation threats, typically configured for 6-12 dismounts with overhead protection against top-attack munitions. Mechanized infantry divisions in Poland and the Baltic states are prioritizing these for Soviet-era fleet replacement under NATO standardization pressure.
- Mine-Resistant Ambush Protected Vehicles:V-hull or double-chassis architectures engineered to deflect blast energy from under-vehicle mines and improvised explosive devices. Persistent asymmetric conflict patterns in contested stabilization operations sustain procurement volume above traditional platform categories despite peace dividend pressures elsewhere.
- Main Battle Tanks:Tracked platforms integrating 120-125mm smoothbore guns with composite armor arrays and ballistic computers for direct fire engagement. Germany's KBA type-approval requirements constrain cross-border logistics for these heavy systems.
- Light Utility Vehicles:Unarmored or lightly protected wheeled platforms optimized for tactical mobility and payload flexibility across unprepared terrain. Special Forces procurement emphasizes air-transportability and modular mission kit integration.
- Self-Propelled Artillery:Tracked chassis mounting 155mm howitzers with automated ammunition handling and inertial navigation for rapid displacement. NATO's eastern flank members are recapitalizing these capabilities through framework contracts coordinated by the NATO Support and Procurement Agency.
Armored Personnel Carriers retain volume leadership; Mine-Resistant Ambush Protected Vehicles hold the steepest expansion curve.
Propulsion:
Cost tiers stratify across conventional diesel dominance, transitional hybrid architectures, and speculative full-electric platforms with unproven battlefield endurance.
- Diesel:Compression-ignition engines delivering high torque at low RPM for tracked vehicle traction, with established supply chains for military-grade fuel filtration and cold-start systems. Poland's current fleet modernization retains diesel for operational energy resilience during deep-penetration missions.
- Hybrid Electric:Series or parallel architectures combining diesel prime movers with battery-electric traction motors for silent-watch and low-speed mobility. The EU Green Deal's emissions mandates are accelerating German and Polish development programs despite lithium-ion energy density limitations.
- Gasoline:Spark-ignition engines confined to light utility and special operations platforms where power-to-weight ratio outweighs fuel logistics burden. These systems face refrigerant compliance challenges under the F-Gas Regulation's climate system requirements.
- Fully Electric:Battery-dominant propulsion with zero exhaust signature, currently constrained by range and recharging infrastructure for armored combat operations. Silicon carbide power semiconductors are reducing thermal management penalties for experimental programs.
- Turbine:Gas turbine engines offering power density advantages for extreme mobility requirements, limited by fuel consumption rates and thermal signature. Niche applications include rapid-response air-portable platforms.
Diesel retains volume leadership; Hybrid Electric holds the steepest expansion curve.
Application:
Customer mission profiles range from high-intensity combined arms maneuver through specialized engineering support to command survivability in contested electromagnetic environments.
- Combat Support:Ammunition resupply, medical evacuation, and forward repair platforms operating within direct fire engagement zones. These applications prioritize armor protection over payload capacity in NATO eastern flank procurement.
- Troop Transport:Protected mobility for infantry squads between assembly areas and dismount points under artillery and small arms threat. Poland's mechanized divisions are replacing Soviet-era BMP variants with Western designs in this category.
- Reconnaissance:Low-signature platforms with mast-mounted sensors and beyond-line-of-sight communications for target acquisition. Hybrid-electric drivelines are gaining traction here for silent infiltration and exfiltration.
- Command and Control:Hardened hulls integrating battle management systems, electromagnetic shielding, and climate-controlled environments for staff operations. The F-Gas Regulation's refrigerant phaseout is forcing HVAC redesign for these sealed systems.
- Engineering:Mine clearance, obstacle breaching, and route proving vehicles with specialized equipment mounts. These platforms face unique structural loading from dozer blades and excavator arms.
Troop Transport retains volume leadership; Combat Support holds the steepest expansion curve.
End User:
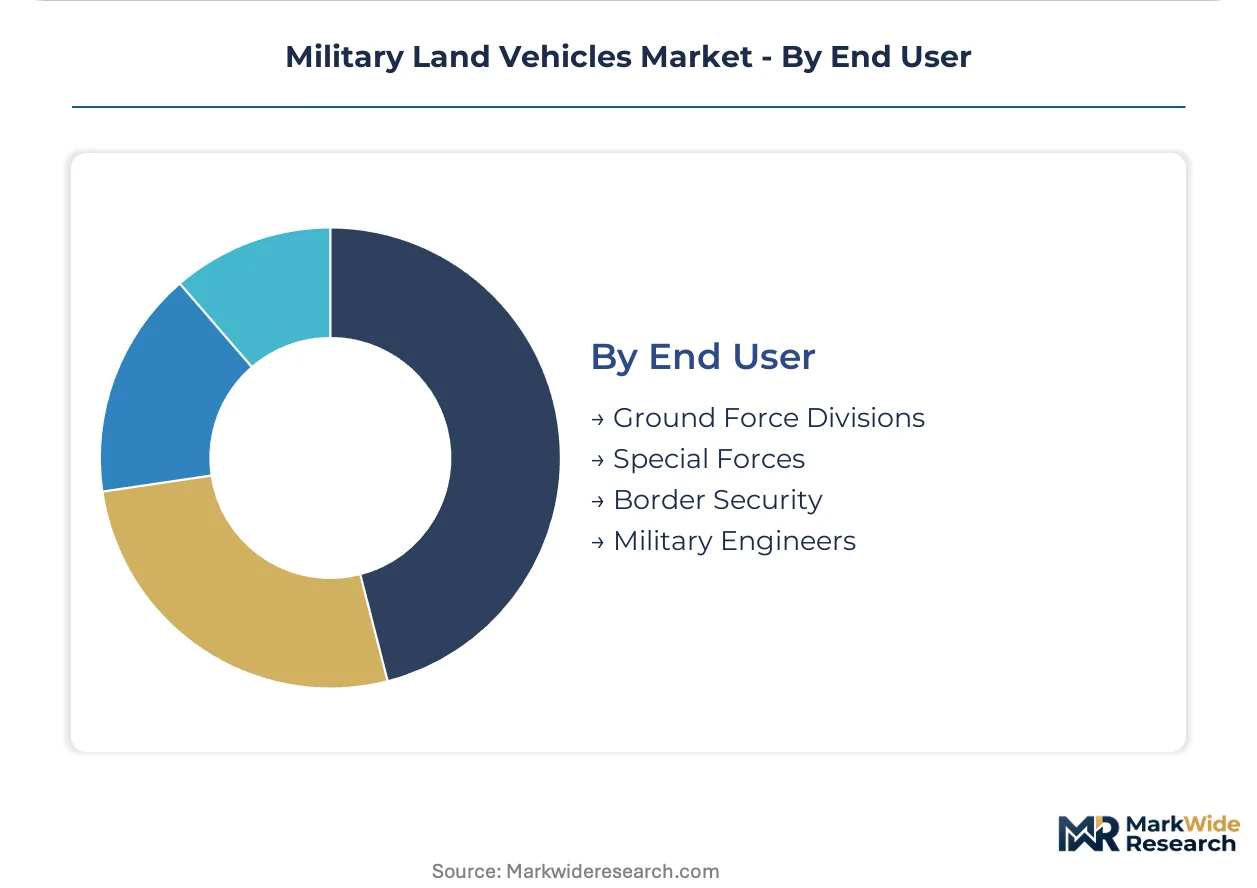
Volume concentrates in conventional ground force formations while margin pools shift toward specialized users with bespoke survivability requirements.
- Ground Force Divisions:Mechanized and armored brigades operating combined arms formations with standardized fleet architectures. Poland's Ministry of National Defense coordinates these requirements with Czech and Slovak counterparts under regional defense cooperation frameworks.
- Special Forces:Small-unit formations requiring air-portable, low-signature platforms with rapid reconfiguration for direct action or special reconnaissance. These users drive demand for hybrid-electric silent mobility and advanced signature management.
- Border Security:Paramilitary formations operating patrol and interdiction missions with lighter protection requirements than conventional military units. Procurement here emphasizes cost efficiency and interoperability with national police vehicle standards.
- Military Engineers:Specialized formations requiring armored earthmoving, bridging, and mine countermeasure platforms. German KBA road network certification creates compliance complexity for these heavy engineering vehicles.
Ground Force Divisions retain volume leadership; Special Forces holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal anchors European defense industrial policy, compelling NATO members to reconcile fleet modernization with emissions compliance across divergent national procurement timelines.
Poland
Mechanized infantry divisions are replacing Soviet-era BMP variants with Western armored personnel carriers under the Ministry of National Defense's technical modernization plan. The EU Green Deal's F-Gas Regulation constrains refrigerant choices for vehicle climate systems in these new acquisitions. Production activity concentrates in southwestern industrial corridors near Wrocław and Poznań, where subsystem suppliers are establishing co-location with prime integrators.
Germany
Krauss-Maffei Wegmann anchors tracked platform development for NATO's heavy armor requirements, while the KBA enforces stringent type-approval protocols for armored vehicles operating on federal road networks. These certification requirements add compliance cost layers to cross-border logistics chains for multinational exercises. Manufacturing clusters in Bavaria and North Rhine-Westphalia coordinate hybrid-electric driveline development with Polish and Czech partners under regional framework agreements.
United States
The Department of Defense defends platform modernization through NHTSA-derived safety benchmarks adapted for military transport, while ground force divisions prioritize mine-resistant ambush protected vehicles for persistent asymmetric operations. Procurement concentrates in Michigan and Wisconsin industrial belts, where Oshkosh Corporation maintains specialized production lines for tactical wheeled platforms.
Hungary
Rheinmetall's new Zalaegerszeg facility positions the country as an emerging hub for Central European armored vehicle assembly and subsystem integration. EU Green Deal emissions mandates are accelerating hybrid-electric development programs at this greenfield site. The facility draws engineering talent from across the Visegrád Group, consolidating previously dispersed supply chain nodes.
United Kingdom
BAE Systems plc sustains long-term production commitments through its Swedish and Czech facilities, extending British industrial influence into continental NATO procurement networks. The UK's departure from EU regulatory frameworks creates parallel compliance tracks for export-bound platforms. Specialist engineering concentrates in Lancashire and Yorkshire clusters, where armored vehicle survivability systems undergo integration testing.
Military Land Vehicles Market Competitive Landscape
Systems integrators and subsystem specialists split the market between platform-level contracts and component supply arrangements. Consolidation concentrates around prime contractors with established NATO certification pathways, while tier-two suppliers compete on thermal management and power electronics specialization. Two archetypes dominate: full-spectrum platform houses with end-to-end design authority, and focused technology suppliers capturing margin pools in electrification and active protection. Competitive moves center on capacity expansion in Central European industrial zones and strategic partnerships for hybrid driveline co-development.
Within the full-spectrum platform tier, General Dynamics Corporation, BAE Systems plc, and Rheinmetall AG occupy positions defined by geographic production footprints and NATO framework contract access. General Dynamics exemplifies the scale-driven archetype through its ELS program dominance across tracked platform deliveries. BAE Systems represents transnational production architecture, anchoring capacity across multiple European regulatory jurisdictions. Rheinmetall sits within the Central European expansion vector, leveraging its Hungarian facility to capture procurement flows from NATO's eastern flank members.
| Leading Market Players |
|---|
| General Dynamics Corporation |
| BAE Systems plc |
| Rheinmetall AG |
| Oshkosh Corporation |
| ST Engineering Ltd. |
| Lockheed Martin Corporation |
| Krauss-Maffei Wegmann GmbH & Co. KG |
| Hyundai Rotem Company |
| Textron Inc. |
| Others |
Pricing and Supply Chain Analysis
Ballistic-grade steel plate tariff exposure from energy-intensive European smelting operations determines both pricing tier spreads and supply chain shape in military land vehicles, compressing margin predictability for vehicle integrators while forcing geographic sourcing diversification.
Pricing Analysis
Poland commands premium pricing for NATO-standard armored personnel carriers compared to legacy Soviet-era refurbishment tiers. Three-tier pricing structure across NATO-certified, national-standard, and export-economy levels reflects certification grade and volume scale differentiation. Cost compression in mid-tier tracked platforms is intensifying because KBA type-approval compliance layers add certification overhead. Border security agencies exhibit highest price sensitivity, while special forces units prioritize capability over unit cost.
Supply Chain Analysis
Rheinmetall's Zalaegerszeg facility, BAE Systems' Swedish and Czech plants, and General Dynamics' ELS program network hold concentrated contract-manufacturing capacity for NATO framework deliveries. Supply concentrates in Germany, Poland, and Hungary for final assembly, with steel plate and ceramic composite armor drawing from German and Czech metallurgical suppliers. Single-source vulnerability in silicon carbide power semiconductor fabrication for hybrid-electric drivelines threatens program timelines. Distribution runs through NATO Support and Procurement Agency framework contracts and bilateral national defense ministry channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where NATO certification pathways and KBA type-approval protocols create decade-long switching costs for defense ministries.
For Market Incumbents: Entrench position through backward integration into silicon carbide power electronics and captive armor plate supply from Czech metallurgical partners. Capacity addition in Hungary's Zalaegerszeg corridor captures eastern flank procurement flows. Threat from Korean and Turkish emerging platform houses demands accelerated hybrid-electric R&D lock-in with Polish Ministry of National Defense.
For New Entrants and Emerging Players: NATO special forces silent mobility requirements in the Baltic states represent the most penetrable entry point for hybrid-electric subsystem specialists. Retrofit HVAC packages for F-Gas Regulation compliance in existing German and Polish fleets offer service-based recurring revenue. Go-to-market through tier-two supplier partnerships with Rheinmetall or Krauss-Maffei Wegmann bypasses prime contractor certification barriers.
For Investors and Strategic Acquirers: The market sits at a platform electrification phase that favors power electronics specialists with military-grade inverter design authority. Long-term viability hinges on five-to-ten-year NATO modernization budget continuity and EU Green Deal emissions mandate durability. Acquisition targets with silicon carbide traction inverter programs and active protection system integration capability command structural scarcity premiums. Signal to watch: Polish-Czech-Slovak framework contract award velocity as eastern flank procurement coordination deepens.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Driveline Development | EU Green Deal emissions mandates accelerate Polish and German program funding for silent-watch capability. |
| Active Protection System Integration | Survivability prioritization over armor upgrades compresses platform life cycles across NATO eastern flank. |
| Central European Capacity Expansion | Rheinmetall's Hungarian facility consolidates previously dispersed Visegrád Group supply chain nodes. |
| Silicon Carbide Power Electronics Investment | Wide-bandgap semiconductors collapse thermal management volume for next-generation hybrid architectures. |
| NATO Framework Contract Positioning | Pooled acquisition structures through NSPA displace bilateral national negotiations for tracked platforms. |
Research Methodology
A spread of perspectives from platform engineering directors at prime contractors, procurement officers at NATO Support and Procurement Agency, KBA type-approval specialists, and subsystem tier-two suppliers converged on the working assumptions. Primary fieldwork combined with secondary validation from SEC 10-K filings, EU defense procurement databases, national ministry technical modernization plans, and trade flow data. Bottom-up platform delivery forecasts triangulated against top-down NATO budget allocation analysis.
Demand-supply balance framing anchored the analytical framework across the analysis window, with segmentation modeled across vehicle type, propulsion architecture, application mission profile, and end-user formation type. CAGRs derived from polynomial trend fitting of historical procurement volumes adjusted for policy inflection points. Forecast inputs incorporated EU Green Deal implementation timelines and Polish Ministry of National Defense technical modernization plan revisions.
Practitioners should monitor NATO framework contract award velocity, KBA regulatory amendment trajectories, and lithium-ion cell energy density breakthrough announcements for early signals. Forecasts reflect assumptions about continued eastern flank threat perception and emissions mandate durability. Quarterly review of Polish-Czech-Slovak defense cooperation agreement implementation and hybrid-electric program milestone achievement is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Vehicles
Military Tank Container Market
Military Vehicles
Combat Support Vehicle Market
Military Vehicles
Main Battle Tank Market
Military Vehicles
Iran Defense Market
Military Vehicles
Taiwan Defense Market
Military Vehicles
Military Vehicle & Aircraft Protection Systems Market
Military Vehicles
Russia Defense Market
Military Vehicles
Destroyers Market
Military Vehicles
Infantry Fighting Vehicle (IFV) Market
Military Vehicles
Global Military Vehicle Electrification Market
Military Vehicles
Japan Defense Market
Military Vehicles
Robotic Combat Vehicle (RCV) Market
Military Vehicles
Riot Control Vehicle Market
Military Vehicles
Military Ground Robots Market
Military Vehicles
Colombia Defense Market
Military Vehicles
Indonesia Defense Market