
 Space Power System Hardware-in-the-Loop Test Platforms Market | 2026-2036
Space Power System Hardware-in-the-Loop Test Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Space Power System Hardware-in-the-Loop Test Platforms Market Insights
ECSS-E-ST-10-04C qualification is reorganizing vendor eligibility for space power HIL platforms, forcing suppliers to demonstrate traceable verification protocols before contract eligibility. dSPACE leverages its automotive real-time heritage to compete in satellite power bus emulation, while OPAL-RT Technologies anchors its position through FPGA-based power electronics specialization for orbital applications. Siemens extends its digital twin portfolio into spacecraft system validation, occupying a distinct tier against focused aerospace specialists.
Space Power System Hardware-in-the-Loop Test Platforms integrate real-time processors, FPGA arrays, and power interface modules to replicate satellite electrical environments under dynamic load and fault conditions, typically operating at sub-millisecond loop latency for stability-critical power converter validation. Their primary purpose is to de-risk flight hardware by substituting physical space segments with validated mathematical models during ground-based verification. Simulators dominate current procurement volumes due to their flexibility across mission profiles, while Digital Twins represent the fastest-expanding technology dimension as agencies mandate predictive maintenance capabilities for extended orbital operations. Satellite Power Testing commands the largest application share, though Orbital Maneuver Simulation generates premium pricing due to thruster power transient complexity.
NASA's Glenn Research Center enforces test fidelity protocols that shape domestic procurement specifications, while ESA's ECSS framework governs European vendor qualification pathways and ISO 19683 provides international baseline requirements for space system simulation integrity. The EU AI Act introduces emerging compliance dimensions for autonomous power management algorithms tested through HIL environments, particularly for European defense space programs. Stakeholders must monitor how emerging nuclear propulsion power architectures reshape simulator bandwidth and thermal modeling requirements before committing to platform refresh cycles.
Market Dynamics
The proliferation of megaconstellations and NASA's Artemis qualification mandates are compressing test cycle timelines while elevating fidelity requirements for power system validation.
Growth Catalysts
- ECSS-E-ST-10-04C qualification:ESA's tightened verification protocols force satellite prime contractors to upgrade ground test infrastructure, expanding addressable demand for traceable HIL platforms.
- Nuclear electric propulsion development:Emerging thruster architectures require multi-megawatt power emulation capabilities that exceed legacy simulator bandwidth, opening premium procurement tiers.
- Germany:Concentrated aerospace electronics expertise around Munich and Stuttgart clusters anchors European supply chain localization for flight-qualified power interface modules.
Market Restraints
- FPGA silicon supply concentration:Xilinx and Intel dominate radiation-tolerant programmable logic, creating single-source vulnerability for real-time processor subsystems.
- Specialized engineering labor scarcity:Power electronics firmware developers with orbital radiation effects expertise command compensation premiums that inflate platform development costs.
- ISO 19683 compliance friction:Third-party validation of simulation integrity models adds 8-14 month pre-contract qualification timelines for new vendor entrants.
Strategic Opportunities
- Digital twin integration:Convergence of predictive maintenance algorithms with HIL environments creates recurring software revenue streams beyond hardware procurement.
- India:ISRO's commercial launch cost advantages are attracting constellation operators requiring localized power bus emulation capabilities for domestic satellite assembly.
- EU AI Act compliance services:Autonomous power management algorithm testing mandates open consulting and certification adjacencies for European defense space programs.
Industry Challenges
- Real-time latency engineering:Sub-millisecond loop closure for stability-critical converter validation demands scarce hardware-software co-design expertise.
- Multi-mission model portability:Customer expectations for simulator reuse across geostationary, low-earth orbit, and cislunar profiles strain platform architecture flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Power System Hardware-in-the-Loop Test Platforms Market |
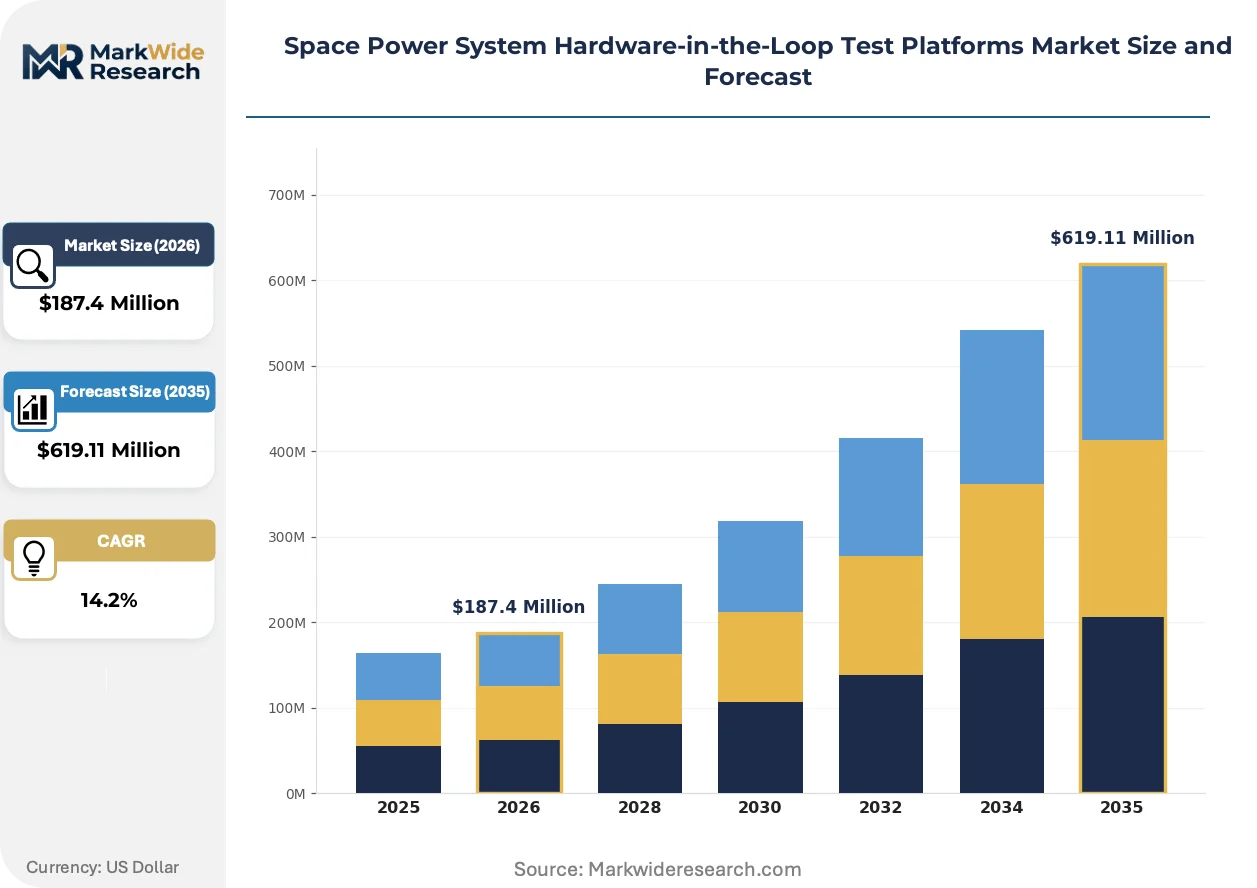
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Simulators, Emulators, Controllers, Signal Processors, Data Acquisition Units Technology: Real-Time Simulation, FPGA-Based Systems, Software-in-the-Loop, Hardware Abstraction, Digital Twins Application: Satellite Power Testing, Spacecraft System Validation, Payload Verification, Orbital Maneuver Simulation, Ground Station Integration End User: Satellite Manufacturers, Space Research Institutes, Defense Space Programs, Academic Laboratories, Launch Service Providers |
| Companies Covered | dSPACE, OPAL-RT Technologies, Typhoon HIL, Speedgoat, Siemens, Vector Informatik, Keysight Technologies, MathWorks, Emerson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Power System Hardware-in-the-Loop Test Platforms Market Trends and Innovations
Power system emulation technology is fragmenting into distinct performance tiers as constellation operators prioritize cost-per-test metrics against deep-space mission fidelity requirements.
FPGA-based power electronics simulation is bifurcating the competitive landscape. These architectures deliver nanosecond-resolution gate-level modeling for wide-bandgap converter validation. Smallsat prime contractors are adopting mid-range FPGA arrays for rapid iteration cycles. Deep-space mission suppliers retain discrete-analog hybrid systems for radiation-effects fidelity, compressing addressable overlap between tier-one and tier-two platform vendors.
REACH substance restrictions are reshaping component sourcing for space-qualified power interface modules. ESA's ban on specific flame retardants in crewed spacecraft electronics is forcing redesign of thermal management subassemblies. German and French satellite manufacturers are accelerating qualification of alternative potting compounds, with procurement specifications now mandating full material disclosure documentation.
Buyers are unbundling hardware procurement from ongoing model maintenance contracts. Satellite operators now separately negotiate simulator platform acquisition, orbital scenario library subscriptions, and mission-specific model validation services. This trifurcation is most visible in US commercial constellation programs, where venture-funded operators prioritize operational expenditure flexibility over capital-intensive integrated system purchases.
Space Power System Hardware-in-the-Loop Test Platforms Market Segmentation
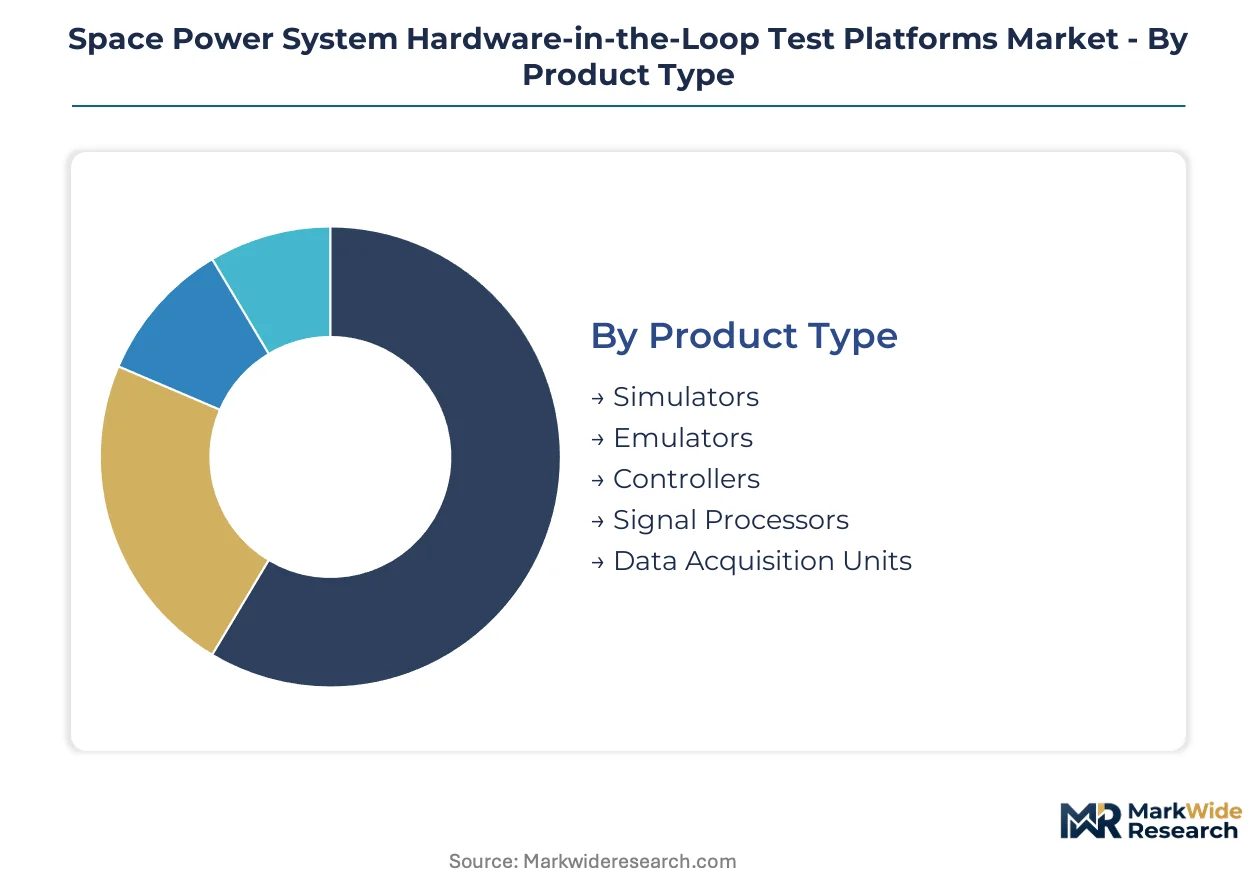
Segmentation in space power HIL platforms reveals distinct procurement patterns across mission profiles, with constellation operators prioritizing cost-per-test metrics while deep-space programs demand radiation-effects fidelity. The analysis traces how technology choices cascade through application requirements and end-user constraints.
Product Type:
Simulators face mounting substitution pressure from software-based alternatives in low-fidelity applications, while hardware-intensive segments defend their position through ECSS-E-ST-10-04C traceability mandates.
- Simulators:These platforms integrate real-time processors with configurable power interface modules to replicate satellite electrical bus dynamics under variable load conditions. Demand concentrates among German satellite prime contractors qualifying megaconstellation power subsystems, where NASA Artemis timeline compression elevates procurement priority for rapid test cycle platforms.
- Emulators:Hardware-specific replication systems duplicate proprietary flight component behaviors at gate-level resolution, commanding premium positioning for radiation-hardened power converter validation. European defense space programs anchor procurement volumes, driven by ESA's tightened verification protocols requiring traceable hardware substitution.
- Controllers:Closed-loop regulation modules manage power flow between simulated sources and hardware-under-test.
- Signal Processors:High-bandwidth conditioning units translate between digital simulation domains and analog power levels.
- Data Acquisition Units:Multi-channel measurement subsystems capture transient power phenomena for post-test analysis.
Simulators anchor the volume base while Digital Twins gains share at the steepest rate.
Technology:
Cost tier stratification separates premium FPGA architectures from mid-range real-time simulation platforms, with customer mission class determining technology selection thresholds.
- Real-Time Simulation:Processor-based architectures achieve sub-millisecond loop latency through optimized solver algorithms running on multicore CPU arrays. Satellite manufacturers in Germany dominate procurement, leveraging Munich aerospace clusters for localized integration support.
- FPGA-Based Systems:Field-programmable gate arrays deliver nanosecond-resolution gate-level modeling essential for wide-bandgap power converter validation. Deep-space mission suppliers retain this technology tier despite Xilinx and Intel supply concentration vulnerabilities.
- Software-in-the-Loop:Pure computational validation without hardware interfacing serves early design phase algorithm verification.
- Hardware Abstraction:Intermediate software layers decouple simulation models from specific power interface hardware.
- Digital Twins:Predictive maintenance convergence creates recurring revenue streams beyond initial platform procurement.
Real-Time Simulation commands the largest installed base while FPGA-Based Systems expands most quickly in premium defense applications.
Application:
Application segmentation follows customer volume-maturity patterns, with high-flight-rate programs driving standardization and bespoke missions sustaining specialist margins.
- Satellite Power Testing:Bus regulation, battery management, and solar array emulation form the core validation workload for commercial constellation operators. Procurement concentrates among venture-funded US operators prioritizing operational expenditure flexibility over capital-intensive integrated purchases.
- Orbital Maneuver Simulation:Thruster power transient replication demands multi-megawatt emulation bandwidth exceeding standard platform specifications. NASA Glenn Research Center protocols shape domestic procurement specifications for this premium tier.
- Spacecraft System Validation:Integrated power-thermal-structural verification across mission profiles.
- Payload Verification:Instrument-specific power quality and electromagnetic compatibility testing.
- Ground Station Integration:End-to-end power flow validation between spacecraft and terrestrial infrastructure.
Satellite Power Testing anchors the volume base while Orbital Maneuver Simulation commands the steepest pricing premiums.
End User:
Supply concentration among specialized engineering labor pools shapes end-user accessibility, with scarce firmware expertise inflating platform development costs for smaller institutions.
- Satellite Manufacturers:Prime contractors and constellation operators drive procurement scale through multi-platform fleet purchases. ISRO's commercial launch cost advantages are attracting operators requiring localized power bus emulation capabilities for domestic satellite assembly in India.
- Defense Space Programs:Classified mission requirements mandate air-gapped test facilities with enhanced cybersecurity protocols. EU AI Act compliance mandates for autonomous power management algorithm testing open consulting adjacencies for European defense programs.
- Space Research Institutes:Government laboratories with sustained funding for fundamental power architecture development.
- Academic Laboratories:University programs with constrained budgets prioritizing educational access over flight qualification fidelity.
- Launch Service Providers:Pre-flight integration verification for payload-spacecraft compatibility.
Satellite Manufacturers anchor the volume base while Defense Space Programs demonstrate the steepest budget expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes cluster around three dominant profiles: German satellite prime contractors qualifying megaconstellation power subsystems, US venture-funded operators prioritizing operational expenditure flexibility, and Indian constellation assemblers leveraging ISRO's commercial launch cost advantages. Each geography exhibits distinct procurement specifications shaped by local regulator mandates and industrial cluster capabilities.
United States
NASA's Glenn Research Center enforces test fidelity protocols that shape domestic procurement specifications for orbital maneuver simulation platforms. The FAA's emerging commercial space launch regulations are tightening ground verification documentation requirements for power system HIL environments. Houston and Denver aerospace clusters anchor satellite manufacturer demand, with venture-funded constellation operators driving volume procurement for rapid test cycle platforms.
Germany
ESA's ECSS-E-ST-10-04C qualification mandates are reorganizing vendor eligibility and expanding addressable demand for traceable HIL platforms among satellite prime contractors. REACH substance restrictions are forcing redesign of thermal management subassemblies for space-qualified power interface modules. Munich and Stuttgart industrial clusters concentrate aerospace electronics expertise, with dSPACE and Siemens anchoring European supply chain localization for flight-qualified components.
India
ISRO's commercial launch cost advantages are attracting constellation operators requiring localized power bus emulation capabilities for domestic satellite assembly. The country's national space regulator is tightening indigenous content requirements for ground test infrastructure procurement. Bengaluru and Hyderabad aerospace corridors concentrate satellite manufacturing activity, with emerging demand for mid-range FPGA arrays supporting rapid iteration cycles.
France
EU AI Act compliance mandates for autonomous power management algorithm testing are opening consulting adjacencies for European defense space programs. ANSM and CNIL data governance frameworks are shaping cybersecurity protocols for air-gapped test facilities handling classified mission requirements. Toulouse and Paris-Saclay aerospace clusters sustain deep-space mission supplier activity, with premium procurement for radiation-effects fidelity systems.
Japan
METI's national space development roadmap is accelerating investment in nuclear electric propulsion power architectures requiring multi-megawatt emulation capabilities. JIS standards for space system simulation integrity are converging with ISO 19683 international baselines. Tsukuba and Nagoya industrial zones concentrate power electronics firmware expertise, though specialized engineering labor scarcity inflates platform development costs.
Space Power System Hardware-in-the-Loop Test Platforms Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with digital twin portfolios competing against focused aerospace specialists with FPGA-based power electronics heritage. Market structure exhibits tiered consolidation: premium-tier vendors defend position through ECSS qualification traceability, mid-range suppliers compete on cost-per-test metrics for constellation operators, and emerging entrants face 8-14 month ISO 19683 pre-contract qualification timelines. Dominant competitive moves include strategic partnerships for radiation-tolerant programmable logic access and portfolio diversification into predictive maintenance software subscriptions.
Within the diversified industrial tier, Siemens occupies a position distinct from focused aerospace specialists through digital twin portfolio extension. Among FPGA-based specialists, OPAL-RT Technologies and Typhoon HIL exemplify the premium defense application tier with nanosecond-resolution gate-level modeling capabilities. dSPACE, a GmbH-structured entity, represents the automotive heritage crossover archetype competing in satellite power bus emulation through real-time processor specialization.
| Leading Market Players |
|---|
| dSPACE |
| OPAL-RT Technologies |
| Typhoon HIL |
| Speedgoat |
| Siemens |
| Vector Informatik |
| Keysight Technologies |
| MathWorks |
| Emerson |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month FPGA procurement lead times now govern contract structuring across the Space Power System Hardware-in-the-Loop Test Platforms Market, compressing vendor margins while amplifying pricing power for radiation-tolerant programmable logic suppliers. This temporal constraint cascades through platform pricing, forcing satellite prime contractors to accept cost-plus terms with semiconductor price indexation clauses.
Pricing Analysis
Cost-plus contracts with Xilinx and Intel price indexation dominate procurement frameworks for real-time processor subsystems. Pricing stratifies across ECSS-E-ST-10-04C certified platforms, mid-range constellation-grade systems, and academic-tier configurations lacking flight qualification traceability. Cost compression in mid-range tiers intensifies because venture-funded operators prioritize operational expenditure flexibility over capital-intensive integrated purchases. Satellite manufacturers anchor volume demand with moderate price sensitivity, while defense space programs demonstrate minimal elasticity for radiation-effects fidelity systems.
Supply Chain Analysis
Xilinx and Intel's radiation-tolerant FPGA chokepoint underwrites single-source vulnerability across real-time processor subsystems. German and US suppliers draw from Taiwanese silicon foundries, Japanese precision analog components, and domestic power electronics assembly. Tariff exposure on Chinese-sourced thermal management materials compounds sourcing complexity. Distribution runs through authorized aerospace distributors with ECSS traceability documentation, bypassing generalist electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Space Power System Hardware-in-the-Loop Test Platforms Market sits in cyclical recovery as NASA's Artemis qualification mandates compress test cycle timelines and force infrastructure refresh investments.
For Market Incumbents: Compound defensive positioning through backward integration into radiation-tolerant FPGA supply agreements and predictive maintenance software subscription bundling. Lock in multi-year ECSS-E-ST-10-04C certification roadmaps before ISO 19683 compliance timelines extend further. Counter emerging entrants by accelerating model library portability across geostationary, low-earth orbit, and cislunar mission profiles. For New Entrants and Emerging Players: Lead with EU AI Act compliance consulting services for European defense space programs, where algorithm testing mandates remain underserved by hardware-focused incumbents. Target India's Bengaluru and Hyderabad aerospace corridors, where ISRO's commercial launch cost advantages are attracting constellation operators requiring localized power bus emulation. Differentiate through rapid-deployment FPGA arrays for smallsat prime contractor iteration cycles rather than competing on radiation-effects fidelity. For Investors and Strategic Acquirers: Long-term, this sits as a defense-digital convergence play because autonomous power management algorithm testing mandates are hardening into procurement specifications across NATO space programs. Prioritize acquisition targets with existing ECSS qualification traceability and FPGA-based power electronics specialization. Monitor nuclear electric propulsion development milestones as the inflection signal for multi-megawatt emulation capability demand.| Strategic Initiative | Industry Significance |
|---|---|
| FPGA Supply Agreement | Secures radiation-tolerant programmable logic access against Xilinx-Intel concentration risk. |
| Digital Twin Integration | Creates recurring software revenue streams beyond initial HIL platform hardware procurement. |
| ECSS Certification Investment | Establishes vendor eligibility for ESA-mandated satellite prime contractor contracts. |
| India Market Entry | Captures ISRO-linked constellation operator demand for localized power bus emulation. |
| Predictive Maintenance Subscription | Converges HIL environments with autonomous power management algorithm validation services. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ESA procurement databases, NASA Glenn Research Center technical publications, and satellite manufacturer SEC filings. Interviews with power electronics firmware developers, satellite prime contractor procurement directors, and ESA qualification officers grounded demand-side validation. Top-down market sizing from national space agency budget allocations triangulated against bottom-up platform shipment estimates from German and US industrial cluster observations.
Segmentation dimensions modeled span product type, technology tier, application workload, and end-user category across the projection horizon. CAGRs derive from installed base replacement cycles, megaconstellation deployment schedules, and nuclear electric propulsion development trajectories. Industry-specific inputs include ECSS-E-ST-10-04C qualification timeline compression effects and REACH substance restriction compliance costs for thermal management subassemblies.
The analysis sits within stated boundaries; outcomes outside sustained Artemis program funding or stable FPGA silicon supply would require recalibration. Forecasts reflect documented assumptions regarding satellite constellation deployment rates and defense space program budget trajectories. Practitioners should keep alternative scenarios live as nuclear propulsion power architecture specifications and EU AI Act enforcement protocols evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Aircraft Turboprop Propeller System Market
Aircraft Power Systems
Aircraft Battery Market
Aircraft Power Systems
Aircraft Electronic Ignition System Market
Aircraft Power Systems
Low-Carbon Propulsion Market
Aircraft Power Systems
Aircraft Electrical Systems Market
Aircraft Power Systems
Air Independent Propulsion Systems (AIP) Market
Aircraft Power Systems
Aerospace Electrical Inserts Market
Aircraft Power Systems
More Electric Aircraft Market
Aircraft Power Systems
Aircraft Drive Shaft and Couplings Market
Aircraft Power Systems
Military Aircraft Actuation System Market
Aircraft Power Systems
Commercial Aircraft Propeller Systems Market
Aircraft Power Systems
Aircraft Thrust Reverser Actuation Systems Market
Aircraft Power Systems
Electrified Aircraft Propulsion Market
Aircraft Power Systems
Aviation Actuator System Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Market