
 Aircraft Thrust Reverser Market | 2026-2036
Aircraft Thrust Reverser Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Thrust Reverser Market Analysis
REACH compliance is expanding material qualification burdens for European suppliers while simultaneously creating preferential access for firms with pre-certified composite supply chains. Collins Aerospace leverages in-house thermoplastic manufacturing to sustain margin control across cascade thrust reverser programs. Safran anchors European aftermarket demand through its CFM56 and LEAP engine installed base, which locks in paired thrust reverser overhaul contracts. GKN Aerospace Services Limited dominates hot-section titanium fabrication, positioning its clamshell offerings against aluminum alternatives in next-generation narrowbody platforms.
An aircraft thrust reverser is a aerodynamic braking device installed on jet engines that redirects fan airflow forward through cascades or blocker doors to generate reverse thrust, typically achieving deceleration forces equivalent to 40-50% of forward thrust ratings during landing roll. The assembly integrates translating sleeves, blocker doors, and cascade vanes manufactured through superplastic forming and resin transfer molding to withstand cyclic thermal loads exceeding 200°C while maintaining sub-1mm aerodynamic tolerances. Cascade designs lead commercial aviation deployments due to their superior flow efficiency and lower acoustic signature on high-bypass turbofans. Composite materials represent the fastest-expanding segment as OEMs pursue weight reductions of 15-25% versus legacy aluminum architectures, though titanium retains critical applications in military thrust reversers where ballistic tolerance requirements persist.
FAA airworthiness standards under 14 CFR Part 25.933 mandate thrust reverser containment and inadvertent deployment prevention systems, while EASA CS-25 imposes equivalent certification rigor that shapes dual-qualification strategies for transatlantic suppliers. The EU Green Deal's Sustainable Aviation Fuel mandates indirectly pressure thrust reverser efficiency as airlines optimize landing profiles to minimize fuel burn during approach and ground operations. China's CAAC certification reciprocity agreements with FAA and EASA determine market access for Western thrust reverser OEMs serving COMAC C919 production ramp-ups. Stakeholders must monitor evolving noise certification thresholds at ICAO Chapter 14 levels and corresponding cascade acoustic liner technology commitments.
Market Dynamics
FAA airworthiness directives on carbon brake compatibility are forcing simultaneous redesigns of thrust reverser actuation systems across narrowbody platforms, compressing supplier development cycles while expanding qualification scopes for cascade vane materials.
Growth Catalysts
- Retrofit Cycles at Legacy Carriers:Delta and United are accelerating aftermarket demand through narrowbody jet modernization programs that mandate thrust reverser overhaul or replacement.
- 14 CFR Part 25.933:FAA containment and inadvertent deployment prevention standards are expanding addressable market for integrated thrust reverser control systems.
- Thermoplastic Composites:REACH compliance burdens are advantaging suppliers with pre-certified composite supply chains, locking in material qualification pathways.
Market Restraints
- Titanium Input Volatility:Hot-section titanium fabrication concentrates among limited qualified suppliers, exposing clamshell program margins to aerospace-grade sponge price swings.
- Dual-Qualification Costs:EASA CS-25 certification rigor layered atop FAA mandates imposes redundant testing burdens on transatlantic suppliers serving both jurisdictions.
- Acoustic Liner Substitution:Advanced turbofan designs with integrated noise reduction are compressing standalone cascade acoustic liner attach rates on next-generation platforms.
Strategic Opportunities
- COMAC C919 Ramp-Up:CAAC certification reciprocity agreements with FAA and EASA are opening access for Western thrust reverser OEMs to serve Chinese narrowbody production.
- Sustainable Aviation Fuel Mandates:EU Green Deal landing profile optimization requirements are creating demand for thrust reverser efficiency upgrades that minimize ground operation fuel burn.
- Resin Transfer Molding Convergence:Superplastic forming process integration with automated fiber placement is enabling single-source cascade manufacturing for weight-critical applications.
Industry Challenges
- Superplastic Forming Talent Scarcity:Cyclic thermal load engineering expertise for 200°C+ operating environments concentrates among aging workforce cohorts at tier-one fabricators.
- ICAO Chapter 14 Certification Timelines:Evolving noise thresholds demand cascade acoustic liner technology commitments that outpace standard product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Thrust Reverser Market |
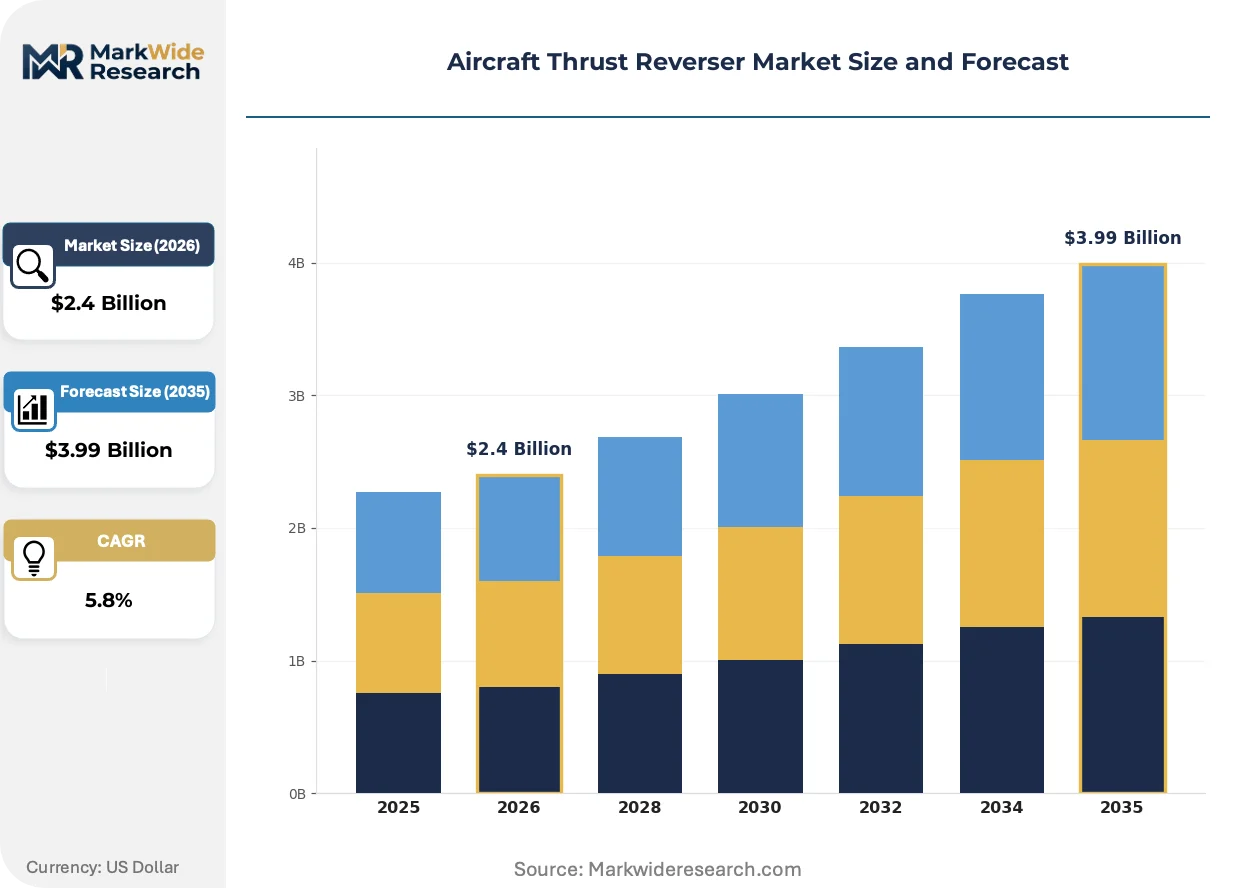
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cascade, Bucket, Clamshell, Doors Deployment Type: Commercial Aviation, Military Aviation, Business Aviation, General Aviation Material: Composite, Aluminum, Titanium, Steel End User: Aerospace Manufacturers, Airlines, Maintenance Repair Organizations, Aftermarket Providers |
| Companies Covered | Collins Aerospace, Safran, The NORDAM Group LLC, GKN Aerospace Services Limited, FACC AG, Spirit AeroSystems, Woodward Inc, Triumph Group, Parker Hannifin Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Thrust Reverser Market Emerging Trajectories
Active material substitution and regulatory harmonization pressures are compressing traditional aluminum-titanium supply hierarchies while accelerating composite process automation investments.
Thermoplastic composite manufacturing is consolidating cascade thrust reverser production around in-house resin transfer molding capabilities. Collins Aerospace and Safran are internalizing thermoplastic fabrication to capture margin control previously ceded to sub-tier suppliers. This vertical integration is consolidating the supplier base and compressing qualification timelines for weight-reduced architectures.
REACH material qualification expansion is reshaping European supplier competitive positioning. ECHA substance restriction updates are forcing requalification of legacy resin systems used in cascade vane production, advantaging firms with pre-certified sustainable chemistry portfolios. French and German suppliers with established green chemistry pathways are capturing specification authority on next-generation narrowbody programs.
Airline procurement functions are unbundling thrust reverser overhaul contracts from engine maintenance agreements. Carriers with dense 737 MAX fleets at Dallas-Fort Worth and similar hubs are negotiating direct cascade replacement schedules separate from CFM56 or LEAP shop visits. This contract fragmentation is visible most acutely among US legacy carriers optimizing working capital against fleet age profiles.
Aircraft Thrust Reverser Market Segmentation
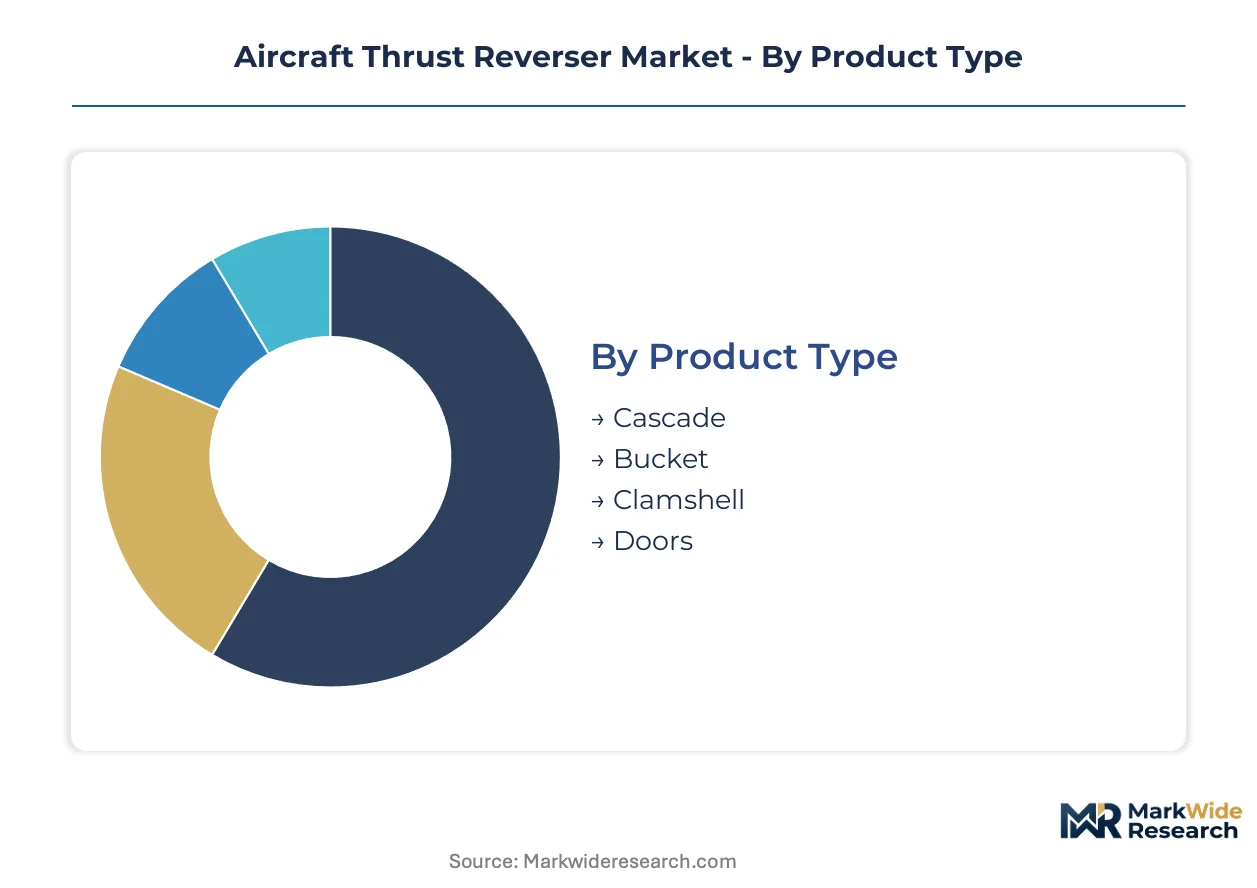
Thrust reverser procurement patterns diverge sharply across product architectures, operator types, and material specifications. Capital deployment intensity varies by segment, with composite-intensive cascade systems demanding substantially higher upfront tooling investment than metallic alternatives.
Product Type:
Capital intensity peaks with cascade designs due to superplastic forming dies and resin transfer molding infrastructure, while bucket and clamshell variants require lower fixed-asset commitments but carry higher variable labor content.
- Cascade:Redirects fan airflow through fixed vanes arranged in circumferential arrays, achieving superior aerodynamic efficiency on high-bypass turbofans. Demand concentrates at Dallas-Fort Worth and Seattle-Tacoma MRO clusters serving 737 MAX fleets, where acoustic signature requirements under FAA Part 36 Stage 5 drive specification authority. Composite cascade architectures absorb 15-25% weight reductions versus aluminum, though qualification timelines extend 18-24 months for new resin systems.
- Bucket:Utilizes pivoting deflector panels that swing into the exhaust stream, historically dominant on military platforms where ballistic tolerance outweighs flow efficiency. Procurement from the US Department of Defense and NATO allies sustains titanium-intensive fabrication at limited qualified suppliers, with hot-section sponge price volatility compressing program margins.
- Clamshell:Hinged door assemblies that close around the exhaust nozzle, prevalent on regional jets and legacy narrowbodies. GKN Aerospace Services Limited anchors European supply through hot-section titanium fabrication capabilities.
- Doors:Translating sleeve configurations with blocker door mechanisms, common on older Airbus A320ceo and Boeing 737NG platforms. Airlines at Delta and United are accelerating retrofit demand as these fleets approach mid-life overhaul cycles.
Cascade designs absorb the bulk of installed capacity across next-generation narrowbody platforms; composite material variants are expanding most quickly as REACH compliance advantages pre-certified supply chains.
Deployment Type:
Application context determines certification burden and aftermarket attach rates, with commercial operators demanding integrated control systems while military procurement prioritizes damage tolerance.
- Commercial Aviation:Encompasses narrowbody, widebody, and regional jet operators subject to FAA 14 CFR Part 25.933 and EASA CS-25 containment mandates. Airlines unbundle thrust reverser overhaul from engine maintenance agreements, negotiating direct cascade replacement schedules at Dallas-Fort Worth and similar hub densities.
- Military Aviation:Fighter and transport platforms requiring ballistic tolerance and rapid deployment reliability. Procurement concentrates at US Air Force and Navy programs, with titanium retention driven by foreign object damage resistance.
- Business Aviation:Corporate and fractional ownership fleets with lower cycle counts but premium turnaround requirements. Gulfstream and Bombardier specifications drive demand for weight-minimized composite configurations.
- General Aviation:Private and training aircraft with limited thrust reverser penetration, primarily turboprop conversions and light jet categories.
Commercial Aviation carries the dominant share of procurement volume; Business Aviation is climbing the fastest as fractional ownership fleets expand long-range jet deployments.
Material:
Material selection trades weight reduction against thermal tolerance and qualification pathway complexity, with thermoplastic composites requiring substantial resin system certification investment.
- Composite:Carbon fiber-reinforced polymers manufactured through resin transfer molding and automated fiber placement. Collins Aerospace leverages in-house thermoplastic production to sustain margin control across cascade programs, while REACH compliance expansion advantages firms with pre-certified sustainable chemistry portfolios at French and German suppliers.
- Aluminum:Legacy sheet metal and extrusion architectures, still specified for cost-sensitive regional jet applications and replacement part production. Boeing 737 MAX supply chains retain aluminum content in non-critical structural elements.
- Titanium:Hot-section fabrication for clamshell and military bucket applications requiring 200°C+ cyclic thermal load tolerance. Sponge price volatility and limited qualified supplier concentration expose program margins.
- Steel:Actuation system components and hinge mechanisms where fatigue resistance outweighs weight penalties.
Composite architectures command the steepest expansion trajectory as OEMs pursue fuel efficiency targets; titanium retains critical military and hot-section applications.
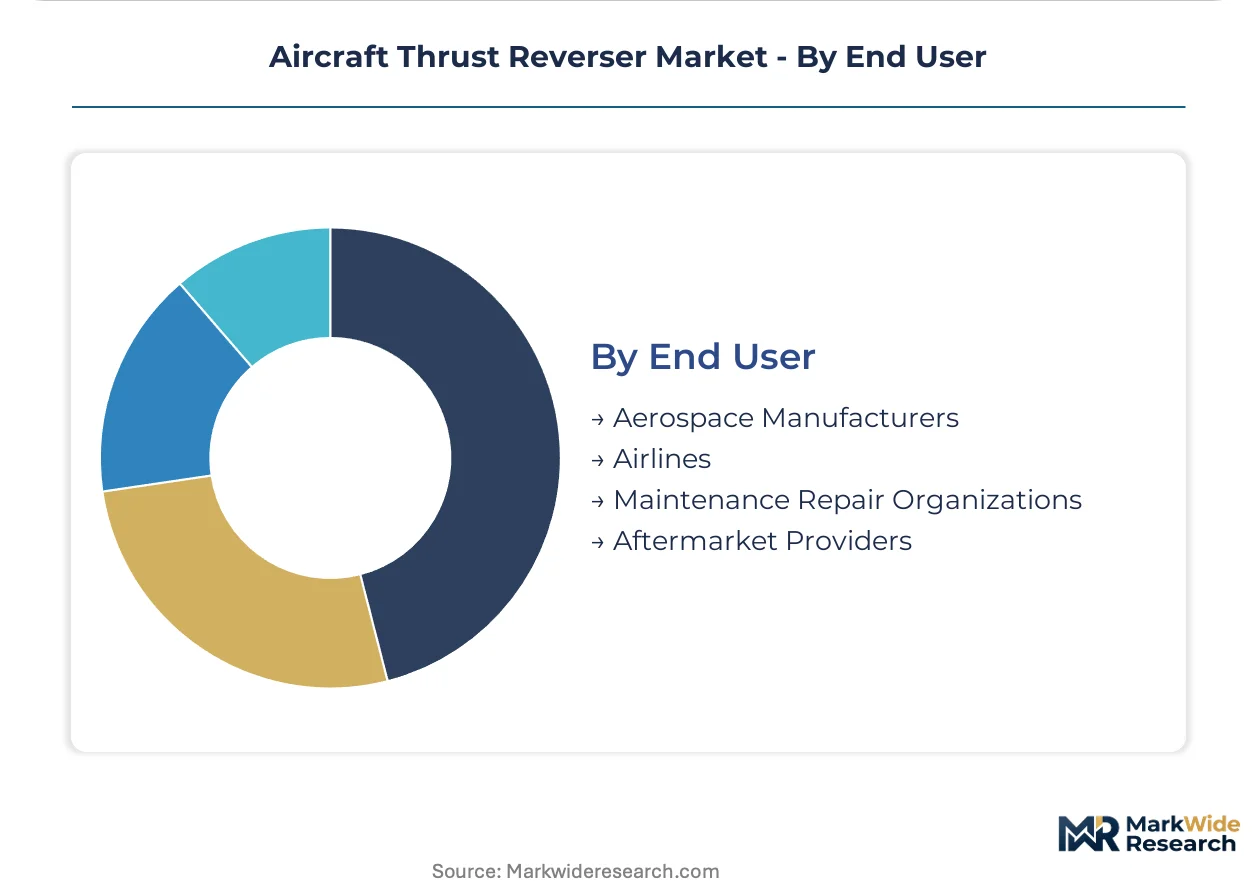
End User:
Procurement authority fragmentation separates OEM new-build specifications from airline aftermarket decisions and MRO intermediary roles.
- Aerospace Manufacturers:Boeing, Airbus, and COMAC specify thrust reverser systems at airframe integration, locking in cascade or clamshell architectures for production runs. CAAC certification reciprocity with FAA and EASA determines Western OEM access to C919 production ramp-ups.
- Airlines:Legacy carriers at Delta and United drive retrofit demand through narrowbody modernization programs, unbundling overhaul contracts from engine maintenance agreements to optimize working capital.
- Maintenance Repair Organizations:Dallas-Fort Worth and Singapore hub densities create procurement pull for replacement cascades and actuation system components, with MROs capturing specification authority on aging fleet segments.
- Aftermarket Providers:Independent distributors and surplus parts specialists serving non-warranty repairs and lease return preparation.
Aerospace Manufacturers anchor specification authority for new platforms; Airlines are gaining procurement autonomy fastest as fleet unbundling accelerates direct cascade replacement scheduling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign Trade Zone 196 around Dallas-Fort Worth International Airport concentrates thrust reverser MRO capacity and procurement pull from legacy carrier fleets undergoing narrowbody retrofits. FAA airworthiness directives on carbon brake compatibility cascade through regional supply chains, forcing simultaneous actuation system redesigns at fabrication clusters.
United States
Boeing 737 MAX production ramp-ups at Renton and legacy carrier retrofit programs at Delta and United drive aftermarket demand concentration. FAA 14 CFR Part 25.933 containment mandates expand addressable market for integrated control systems. Dallas-Fort Worth MRO hub density creates sustained procurement pull for cascade replacement schedules.
France
Safran's CFM56 and LEAP engine installed base locks in paired thrust reverser overhaul contracts across European airline fleets. EASA CS-25 certification rigor shapes dual-qualification strategies for transatlantic suppliers. French suppliers with pre-certified sustainable chemistry portfolios capture specification authority on next-generation narrowbody programs.
China
COMAC C919 production ramp-ups create procurement openings for Western thrust reverser OEMs as domestic narrowbody output scales. CAAC certification reciprocity agreements with FAA and EASA determine market access conditions. Shanghai and Tianjin aerospace clusters concentrate MRO infrastructure serving inbound Western platform fleets.
United Kingdom
GKN Aerospace Services Limited anchors European supply through hot-section titanium fabrication capabilities for clamshell architectures. REACH compliance expansion forces requalification of legacy resin systems, advantaging firms with established green chemistry pathways. Bristol and Midlands aerospace corridors concentrate qualified superplastic forming expertise.
Germany
EU Green Deal Sustainable Aviation Fuel mandates pressure thrust reverser efficiency optimization for landing profile fuel burn reduction. ECHA substance restriction updates accelerate material qualification burdens for cascade vane production. Hamburg and Munich industrial clusters house automated fiber placement and resin transfer molding infrastructure.
Aircraft Thrust Reverser Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the thrust reverser supply base. Tier-one systems integrators with in-house thermoplastic manufacturing capabilities capture margin control previously ceded to sub-tier suppliers. Three strategic archetypes dominate: aerospace conglomerates with engine-airframe integration authority, composite specialists with REACH-pre-certified supply chains, and titanium fabricators with hot-section qualification. Consolidation pressure manifests through backward integration into resin transfer molding and strategic partnerships for superplastic forming capacity access.
Among transatlantic systems integrators, Collins Aerospace and Safran occupy positions anchored by engine-airframe pairing contracts and in-house composite production. GKN Aerospace Services Limited exemplifies the hot-section fabrication archetype with European clamshell supply concentration. These three represent the dominant competitive anchors shaping procurement authority across narrowbody platform specifications.
| Leading Market Players |
|---|
| Collins Aerospace |
| Safran |
| The NORDAM Group LLC |
| GKN Aerospace Services Limited |
| FACC AG |
| Spirit AeroSystems |
| Woodward Inc |
| Triumph Group |
| Parker Hannifin Corp |
| Others |
Supply Flow & Price Mechanics
Airline unbundling of thrust reverser overhaul contracts from engine maintenance agreements is forcing suppliers to restructure pricing models around direct cascade replacement schedules rather than bundled service tiers. This procurement shift concentrates pricing power at Dallas-Fort Worth and Seattle-Tacoma MRO hubs where legacy carrier fleet density creates volume leverage.
Pricing Analysis
Lead-time compression commands premium positioning in thrust reverser procurement, with airlines paying marked-up rates for certified cascade assemblies deliverable under standard overhaul windows versus discounted spot inventory from surplus dealers. Three-tier pricing structure across premium certified-new, standard OEM-overhauled, and economy surplus-recertified levels separates procurement tiers by traceability documentation and warranty coverage. Cost compression in the economy tier is intensifying because independent distributors are consolidating surplus inventories from lease-return teardowns. Regional jet operators exhibit highest price sensitivity due to thinner operating margins, while widebody fleet managers prioritize specification compliance over unit cost.
Supply Chain Analysis
Domestic-content mandates under Buy American provisions for US Department of Defense procurement are reshaping sourcing patterns for military bucket thrust reversers, restricting qualified supplier pools to North American titanium fabricators. Geographic supply concentration centers on the United States for composite cascade production, France for paired engine-thrust reverser integration, and the United Kingdom for hot-section clamshell fabrication. Raw material dependencies draw from aerospace-grade carbon fiber prepreg, titanium sponge, and thermoplastic resin systems. Single-source vulnerability persists for superplastic forming dies capable of 200°C+ thermal tolerance. Distribution runs through tier-one systems integrators with captive MRO networks and independent aftermarket distributors serving non-warranty demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where FAA 14 CFR Part 25.933 containment mandates and EASA CS-25 certification rigor erect substantial barrier-to-entry moats favoring incumbent suppliers with pre-qualified resin systems and established dual-jurisdiction testing protocols.
For Market Incumbents: Acquire superplastic forming engineering talent pools before demographic retirement erodes critical capability. Consolidate backward integration into automated fiber placement infrastructure to capture margin control previously ceded to sub-tier composite suppliers. Defend against emerging thermoplastic specialists by accelerating REACH-pre-certified sustainable chemistry qualification timelines. For New Entrants and Emerging Players: Capture specification authority on COMAC C919 production ramp-ups where CAAC certification reciprocity agreements create access windows for Western-qualified suppliers. Target business aviation fractional ownership fleets as the most penetrable segment, where lower cycle counts and premium turnaround requirements favor weight-minimized composite configurations. Pursue direct airline procurement relationships at Dallas-Fort Worth hub densities where contract unbundling has fragmented traditional engine-OEM channel control. For Investors and Strategic Acquirers: The window for entry favors composite specialists with pre-certified supply chains and established resin transfer molding capabilities over metallic fabrication pure-plays. Long-term viability rests on positioning for sustained narrowbody platform demand and aftermarket retrofit cycles rather than new widebody program exposure. Watch ICAO Chapter 14 noise certification timeline acceleration as the inflection signal indicating cascade acoustic liner technology commitment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Resin Transfer Molding Capacity Expansion | Captures margin control from sub-tier suppliers for composite cascade production at Collins Aerospace and Safran. |
| Dual-Jurisdiction Qualification Investment | Locks in specification authority for transatlantic suppliers serving both FAA Part 25.933 and EASA CS-25 mandates. |
| Superplastic Forming Talent Acquisition | Secures scarce 200°C+ cyclic thermal load engineering expertise concentrated among aging workforce cohorts. |
| REACH-Pre-Certified Chemistry Portfolio | Advantages French and German suppliers against legacy resin requalification burdens under ECHA substance restrictions. |
| Direct Airline Procurement Channel Development | Exploits overhaul contract unbundling at Delta and United to bypass traditional engine-OEM distribution control. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with thrust reverser program managers at tier-one systems integrators, MRO procurement directors at Dallas-Fort Worth hub facilities, airline fleet engineering leads, composite materials specialists, and superplastic forming process engineers. FAA airworthiness directive databases, EASA certification documentation, and REACH substance restriction updates provided regulatory trajectory inputs. Bottom-up cascade replacement volume estimates triangulated against top-down OEM production forecasts and airline fleet age profiles.
Granularity-level modeling disaggregated demand across product architecture, material specification, deployment type, and end-user procurement authority dimensions. Segment-level CAGRs derived from fitted growth curves calibrated to narrowbody platform delivery schedules, retrofit cycle timing, and MRO hub density expansion. Industry-specific forecast inputs incorporated Boeing 737 MAX production ramp-ups, COMAC C919 certification reciprocity progress, and EU Green Deal Sustainable Aviation Fuel mandate implementation timelines across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to titanium sponge price volatility, ICAO noise certification threshold evolution, and CAAC market access policy shifts. Forecasts reflect documented assumptions regarding fleet retirement patterns and supplier consolidation trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Aircraft Hydraulic Actuators Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Gearbox Market
Aircraft Power Systems
Aerospace Electrical Inserts Market
Aircraft Power Systems
Low-Carbon Propulsion Market
Aircraft Power Systems
Aircraft Drive Shaft and Couplings Market
Aircraft Power Systems
Aircraft Thrust Reverser Actuation Systems Market
Aircraft Power Systems
Aircraft Electronic Ignition System Market
Aircraft Power Systems
Commercial Aviation Electrical Wiring Interconnection System (EWIS) Market
Aircraft Power Systems
Aircraft Cooling Turbines Market
Aircraft Power Systems
Aircraft Generators Market
Aircraft Power Systems
More Electric Aircraft Market
Aircraft Power Systems
Aircraft Hydraulic System Market
Aircraft Power Systems
Aviation Actuator System Market
Aircraft Power Systems
Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Market
Aircraft Power Systems
Aircraft Electrical Systems Market