
 Aircraft Generators Market | 2026-2036
Aircraft Generators Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Generators Market Analysis
FAA Part 25 airworthiness standards for electrical power systems is pivoting the cost-of-entry calculus toward brushless and permanent magnet architectures that deliver higher power density. Safran S.A. leverages its integrated drive generator portfolio to anchor positions on narrow-body and wide-body platforms. General Electric Company sustains technology leadership through vertical integration into thermal management and power electronics. Honeywell International Inc. differentiates via generator control units that interface with fly-by-wire flight control architectures.
Aircraft generators are electromechanical devices that convert mechanical energy from turbine engines into electrical power, typically producing 115 VAC at 400 Hz for onboard avionics, environmental controls, and actuation systems. Modern units achieve power densities exceeding 10 kW/kg through liquid-cooled stator windings and composite rotor enclosures. The alternator segment dominates installed base volumes across commercial and military fleets, while permanent magnet technology captures the fastest growth trajectory owing to elimination of excitation losses and reduced maintenance intervals. Brushless architectures command premium positioning in above-300 kVA ratings for twin-aisle aircraft, whereas conventional designs retain cost advantages in below-100 kVA auxiliary power units.
FAA, EASA, and the EU Aviation Safety Agency's CS-25 certification framework mandate dual independent electrical channels and fault containment for extended-range twin-engine operations, directly shaping generator redundancy requirements and product development roadmaps. The EU Green Deal's trajectory for sustainable aviation fuels and hybrid-electric propulsion is forcing manufacturers to redesign generators for variable-frequency operation and regenerative loading. Stakeholders must monitor how airworthiness authorities reconcile legacy certification pathways with novel power architectures before committing capital to next-generation platforms.
Market Dynamics
The transition to more electric aircraft architectures is compressing generator power density requirements while FAA and EASA tighten electrical redundancy mandates for extended-range operations. This dual pressure is restructuring supplier qualification pathways and capital allocation across the value chain.
Growth Catalysts
- CS-25 Certification Framework:EASA's updated electrical system fault containment requirements for twin-engine extended operations are mandating dual-channel generator architectures on new platform introductions.
- Permanent Magnet Technology:Elimination of excitation losses and extended maintenance intervals are accelerating fleet retrofit programs and new equipment specifications across narrow-body programs.
- United States Supply Concentration:Boeing's integrated procurement and Tier 1 supplier clustering around Seattle and Wichita create dense technical feedback loops for specification refinement.
Market Restraints
- Raw Material Volatility:Neodymium and dysprosium price swings for permanent magnet rotors compress margin predictability for manufacturers without long-term rare earth supply agreements.
- Single-Source Concentration:Precision wound stator coil production concentrates in specialized Japanese and German facilities, creating geographic vulnerability for above-200 kVA units.
- Legacy Excitation Architectures:Brush-type generator installed bases in regional turboprop fleets create substitution resistance due to airframe modification certification costs.
Strategic Opportunities
- Hybrid-Electric Propulsion:Variable-frequency generator designs for turboelectric distributed thrust architectures open white space in the 500 kW to 2 MW power class for urban air mobility and regional platforms.
- EU Green Deal Trajectory:Sustainable aviation fuel compatibility mandates and carbon border adjustments are incentivizing European airframers to specify regenerative-capable electrical systems.
- Aftermarket Digitalization:Generator health monitoring via embedded sensors creates recurring revenue streams through predictive maintenance contracts with low-cost carrier fleets.
Industry Challenges
- Specialized Winding Expertise Gap:Liquid-cooled stator design and high-frequency insulation systems require electromechanical engineering talent that concentrates at a handful of aerospace-focused universities.
- DO-160G Environmental Qualification:Lightning strike and electromagnetic interference testing timelines for new generator control units routinely extend program schedules by 18-24 months.
- Legacy Interface Compatibility:New permanent magnet generators must integrate with existing 115 VAC 400 Hz distribution buses and voltage regulation architectures without airframe rewiring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Generators Market |
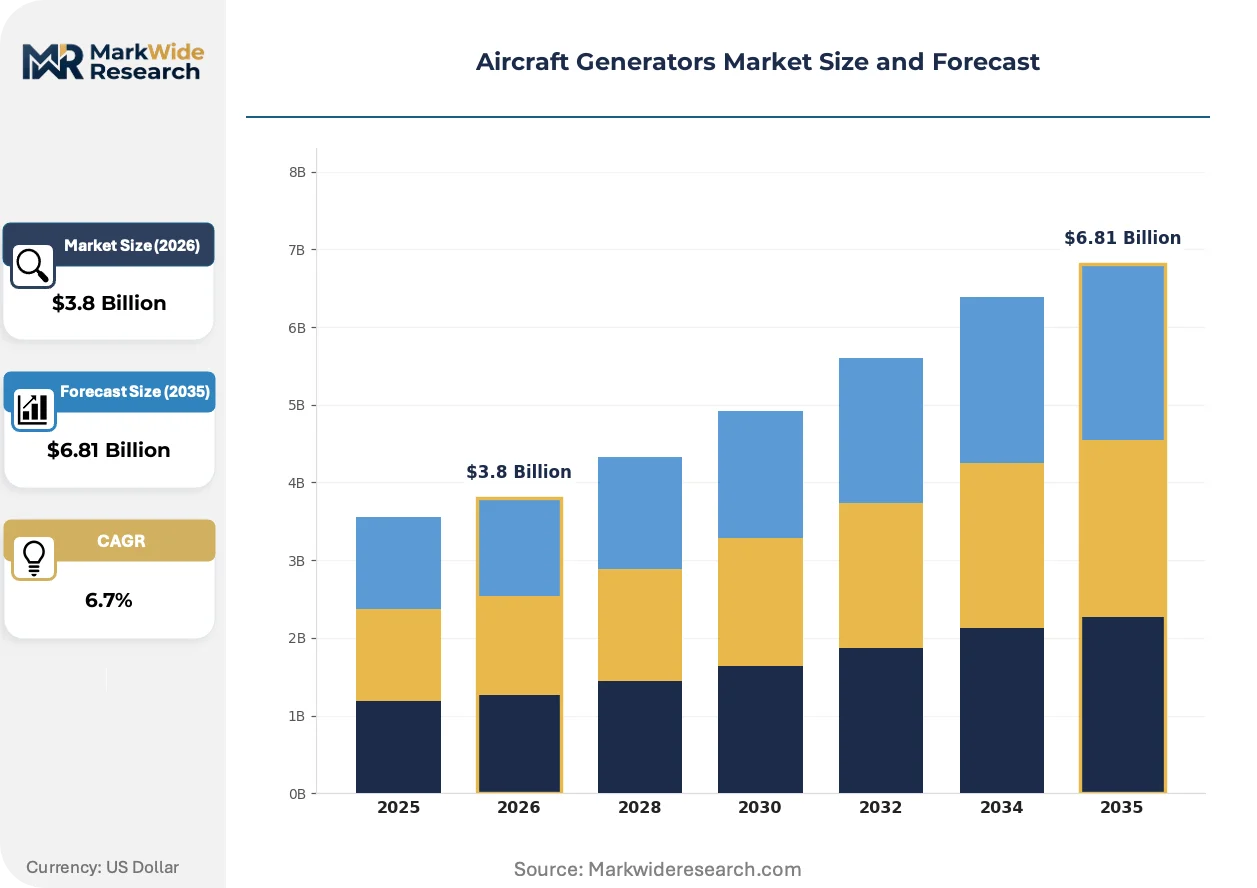
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Alternator, Integrated Drive Generator, Generator Control Unit, Starter Generator End User: Commercial Aviation, Military Aviation, Maintenance, Repair & Overhaul, Aftermarket Providers Power Rating: Below 100 kVA, 100-200 kVA, 200-300 kVA, Above 300 kVA Technology: Brushless, Permanent Magnet, Axial Flux, Conventional |
| Companies Covered | Safran S.A., Thales Group, General Electric Company, HEICO Corporation, TransDigm Group Inc., RTX Corporation, AMETEK Inc., Crane Aerospace & Electronics LLC, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Generators Market Emerging Trajectories
Power electronics integration and thermal management convergence are rewriting generator system boundaries, collapsing what were separate subsystems into unified electromechanical packages. This compression demands new supplier competencies and certification approaches.
Silicon carbide power semiconductors in generator control units are rewriting thermal efficiency benchmarks for variable-frequency operation. Narrow-body platform integrators at Airbus and Boeing are specifying these architectures for next-generation single-aisle programs. The technology is rewriting supplier qualification criteria by mandating semiconductor packaging expertise alongside traditional electromagnetic design.
EU Aviation Safety Agency's evolving CS-25 electrical system interpretation for hybrid-electric aircraft is forcing manufacturers to submit variable-frequency generators under novel certification pathways. The industrial consequence is extended validation timelines and parallel compliance documentation for both legacy constant-frequency and emerging variable-frequency standards. European regional aircraft programs are most affected, with ATR and Dornier derivative platforms requiring dual-track certification strategies.
Airline procurement departments are consolidating generator purchases into airframe-level electrical system contracts rather than component-level sourcing. This behavior disrupts traditional component distributor channels and replaces them with Tier 1 system integrator relationships. The shift is most visible among United States ultra-low-cost carriers seeking lifecycle cost predictability through power-by-the-hour arrangements with electrical system providers.
Aircraft Generators Market Segmentation
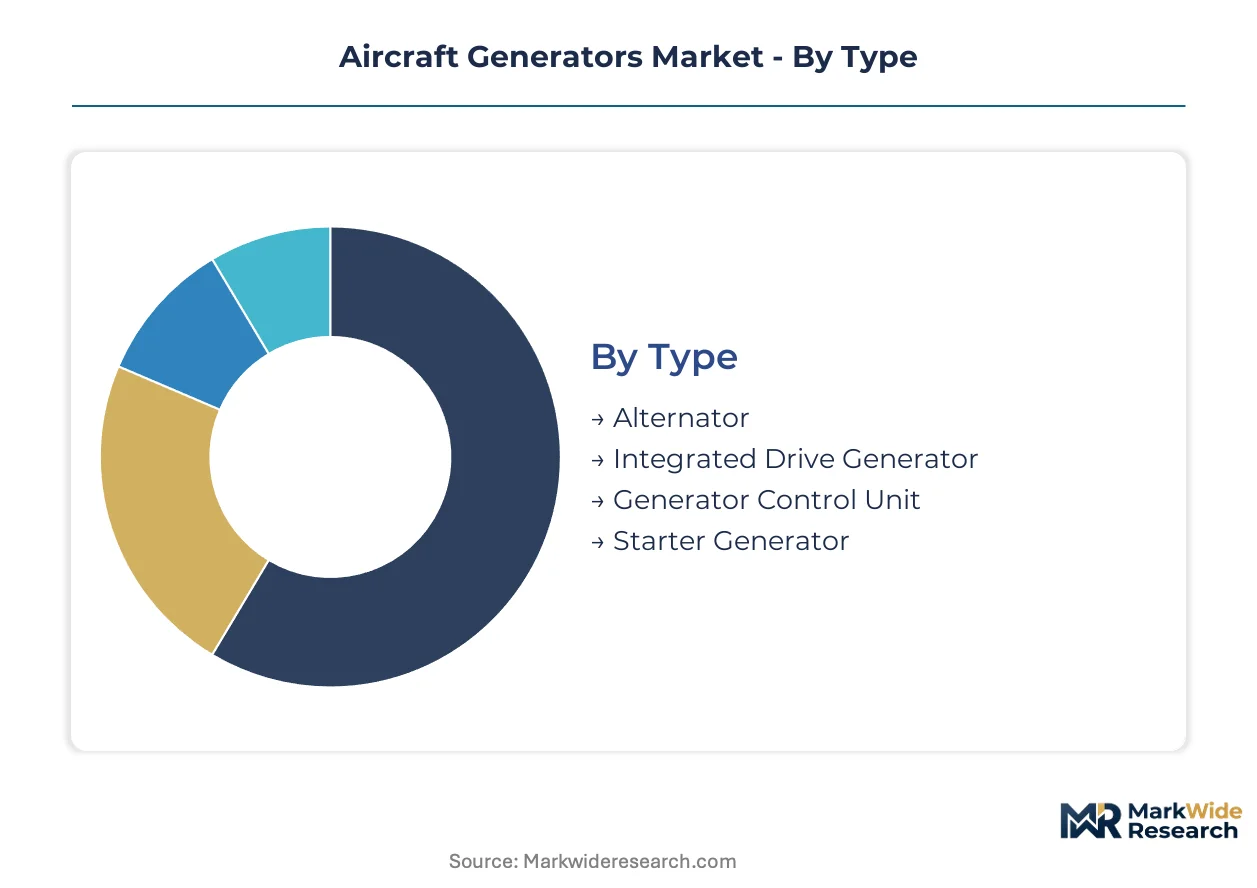
Segmentation in aircraft generators reveals how certification pathways and power density requirements fragment procurement decisions across airframe programs. Each dimension carries distinct regulatory burdens that reshape supplier economics and technology roadmaps.
Type:
Certification intensity varies sharply by generator architecture, with integrated drive generators facing the most rigorous FAA Part 25 and EASA CS-25 electrical system redundancy validation, while control units navigate DO-160G environmental qualification timelines.
- Alternator:Electromechanical units producing 115 VAC at 400 Hz through rotating electromagnetic fields dominate installed base volumes across narrow-body and wide-body commercial fleets. Demand concentrates in United States final assembly lines where Boeing specifications anchor industry standards, though EASA's updated fault containment mandates are forcing redesigns for European-registered aircraft.
- Integrated Drive Generator:Self-contained constant-speed drive and generator packages maintain precise 400 Hz output across variable engine speeds, commanding premium positioning on twin-aisle platforms. United States-based Tier 1 integrators cluster procurement around Wichita and Seattle technical centers, creating dense specification feedback loops with airframers.
- Generator Control Unit:Power electronics packages regulating voltage, frequency, and load sharing face extended DO-160G electromagnetic interference and lightning strike testing that routinely extends development schedules.
- Starter Generator:Combined motor-generator units for auxiliary power and engine starting applications serve regional turboprop and business jet segments where weight reduction drives specification.
Leading the category by volume: Alternator. Growing fastest: Integrated Drive Generator.
End User:
Procurement authority concentrates differently across end-user categories, with commercial aviation fleets consolidating electrical system contracts at airframe level while military programs fragment sourcing across platform primes.
- Commercial Aviation:Airlines and lessors purchasing new aircraft specify generators through airframe-level electrical system contracts rather than component-level sourcing, compressing distributor margins and elevating Tier 1 integrator relationships. United States ultra-low-cost carriers drive this consolidation through power-by-the-hour arrangements seeking lifecycle cost predictability.
- Military Aviation:Defense procurement mandates MIL-STD-704 power quality standards and MIL-STD-810 environmental qualification, creating parallel certification tracks that extend supplier qualification timelines compared to commercial equivalents.
- Maintenance, Repair & Overhaul:Independent MRO facilities in Germany and Singapore specialize in high-time generator overhauls for leased aircraft returning to lessors.
- Aftermarket Providers:Spare parts distributors and surplus dealers serve aging regional fleets with refurbished units and PMA alternatives.
Commercial Aviation captures the largest revenue share. Military Aviation shows the steepest technology premium.
Power Rating:
Power class determines cooling architecture and winding complexity, with above-300 kVA units requiring liquid-cooled stator designs that concentrate specialized manufacturing capability in Japanese and German facilities.
- Below 100 kVA:Air-cooled designs with conventional excitation architectures serve auxiliary power units and regional turboprop applications where cost sensitivity outweighs power density requirements. Legacy brush-type generators retain installed base positions due to airframe modification certification costs that block retrofit economics.
- 100-200 kVA:Intermediate ratings bridge narrow-body main engine generators and wide-body auxiliary systems, with brushless architectures displacing conventional designs across new equipment specifications.
- 200-300 kVA:Single-aisle main engine ratings where permanent magnet technology is gaining specification share through elimination of excitation losses.
- Above 300 kVA:Twin-aisle and cargo aircraft main generators demanding liquid-cooled stator windings and composite rotor enclosures to achieve power densities exceeding 10 kW/kg.
Above 300 kVA commands the highest unit value. Below 100 kVA moves the largest unit volumes.
Technology:
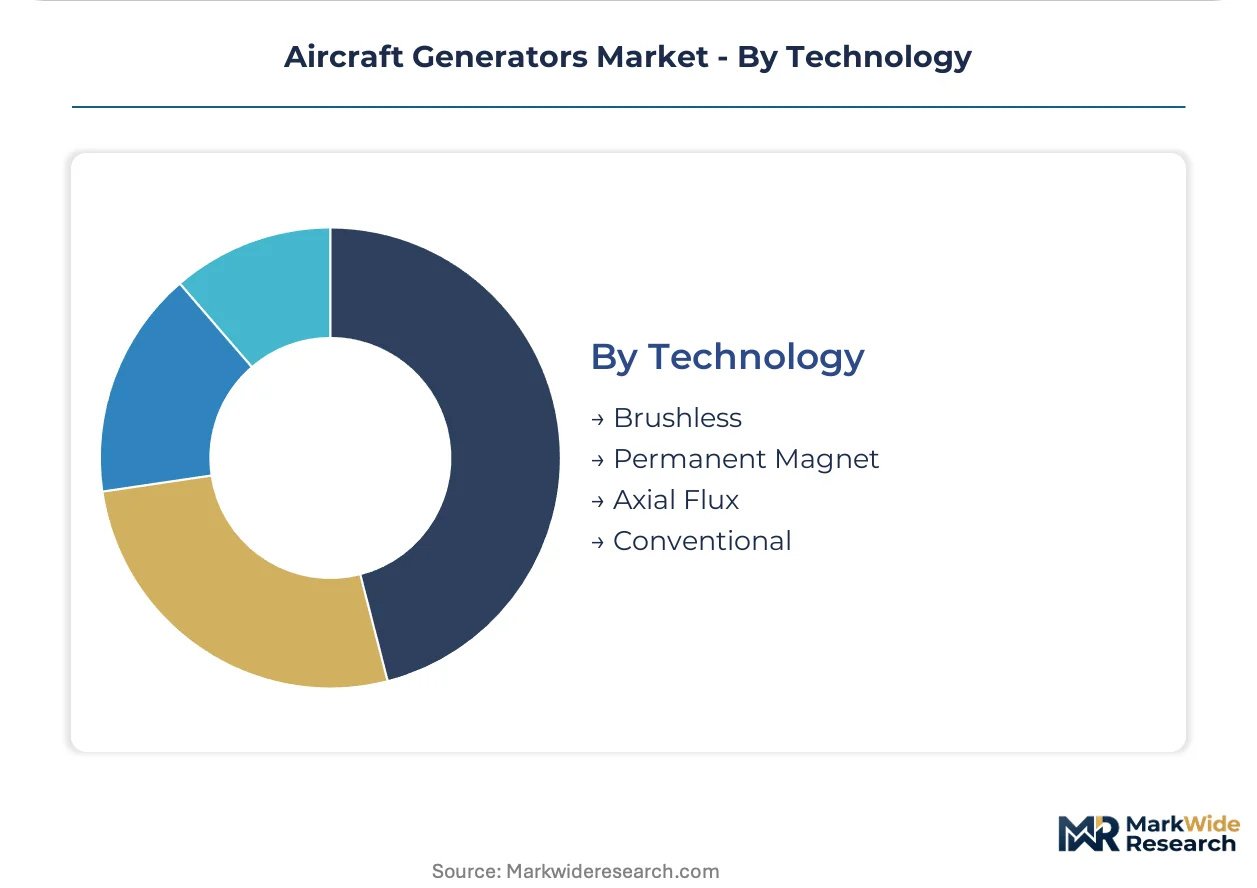
Technology selection pivots on the trade-off between maintenance interval extension and rare earth supply security, with permanent magnet designs accelerating despite neodymium and dysprosium price volatility.
- Brushless:Elimination of slip rings and brushes through rotating rectifier excitation extends mean time between overhauls and reduces particulate contamination in avionics bays. FAA and EASA mandates for electrical system redundancy on extended-range twin-engine operations accelerate fleet retrofit specifications.
- Permanent Magnet:Neodymium-iron-boron rotor configurations eliminate excitation losses entirely, delivering the highest power density for hybrid-electric propulsion architectures. European regional aircraft programs under EU Green Deal pressure specify these for variable-frequency operation compatibility.
- Axial Flux:Flat disc-shaped magnetic circuits enable compact packaging for urban air mobility and distributed electric propulsion applications.
- Conventional:Wound-field rotor designs with carbon brush excitation retain cost advantages in below-100 kVA auxiliary applications and legacy fleet support.
Brushless technology holds the largest installed base. Permanent Magnet expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States commercial aviation procurement concentrates generator demand through Boeing's integrated supply chain, while European regulatory pressure and Asian fleet expansion reshape regional competitive dynamics across the forecast window.
United States
FAA Part 25 airworthiness standards for electrical redundancy drive specification intensity for brushless and permanent magnet architectures on narrow-body and wide-body platforms. Boeing's procurement clustering around Seattle and Wichita technical centers creates dense feedback loops between airframers and Tier 1 electrical system integrators. United States ultra-low-cost carriers consolidate purchases into airframe-level power-by-the-hour contracts, compressing traditional component distributor channels.
France
EASA CS-25 certification mandates for fault containment on extended-range twin-engine operations accelerate fleet retrofit specifications across Air France-KLM and Transavia fleets. The EU Green Deal's sustainable aviation fuel trajectory forces redesigns for variable-frequency generator compatibility on regional platforms. Safran S.A. anchors integrated drive generator production at its Paris-region facilities, supplying both Airbus narrow-body programs and export markets.
Germany
Precision-wound stator coil manufacturing concentrates in specialized Bavarian and Baden-Württemberg facilities serving above-200 kVA applications for twin-aisle aircraft. German regional aircraft programs under EU decarbonization pressure specify permanent magnet generators for ATR derivative platforms. Lufthansa Technik's Hamburg and Frankfurt MRO hubs specialize in high-time generator overhauls for leased aircraft returning to lessors.
Japan
Japan Airlines and ANA Holdings fleet renewal programs drive demand for liquid-cooled stator designs in the 200-300 kVA power class. METI industrial policy supports domestic aerospace supplier development through targeted R&D subsidies for power electronics integration. Tokyo and Nagoya industrial corridors host specialized winding expertise for composite rotor enclosures achieving power densities exceeding 10 kW/kg.
Singapore
Singapore Airlines Group and low-cost carrier Scoot consolidate electrical system procurement through airframe-level contracts seeking lifecycle cost predictability. The Civil Aviation Authority of Singapore enforces EASA-aligned certification requirements for generators on aircraft registered under its oversight. Seletar Aerospace Park and Changi-based MRO facilities specialize in generator health monitoring and predictive maintenance for Asia-Pacific lessor fleets.
Aircraft Generators Market Vendor Landscape
United States producers anchor the premium-tier integrated drive generator segment; French specialists hold dominant positions on Airbus platform specifications. Market structure consolidates around aerospace conglomerates with captive airframer relationships, while specialized power electronics firms compete on control unit differentiation. Three archetypes define competitive positioning: full-system integrators owning generator-drive packages, component specialists in thermal management and semiconductors, and aftermarket service providers with predictive maintenance platforms. Capacity expansion and strategic technology licensing represent the dominant competitive moves across the value chain.
Within the full-system integrator tier, Safran S.A., General Electric Company, and Honeywell International Inc. occupy positions defined by airframer relationship depth and certification portfolio breadth. These companies exemplify how backward integration into power electronics and thermal management creates qualification barriers for challengers. Their geographic distribution across French, United States, and diversified multinational structures reflects the market's transatlantic supply chain configuration.
| Leading Market Players |
|---|
| Safran S.A. |
| Thales Group |
| General Electric Company |
| HEICO Corporation |
| TransDigm Group Inc. |
| RTX Corporation |
| AMETEK Inc. |
| Crane Aerospace & Electronics LLC |
| Honeywell International Inc. |
| Others |
Supply Flow & Price Mechanics
Neodymium and dysprosium prices cascade through permanent magnet rotor costs into generator tier pricing, with rare earth volatility compressing margin predictability for manufacturers lacking long-term supply agreements with Chinese or Australian mining consortiums.
Pricing Analysis
Lead-time premiums of 40-60 percent apply to above-300 kVA liquid-cooled units with sub-26-week delivery windows, while spot inventory of refurbished below-100 kVA auxiliary power units trades at 15-25 percent discounts. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified brushless architectures from EASA-aligned conventional designs and PMA aftermarket alternatives. Cost compression in the permanent magnet segment is intensifying because Japanese and German winding facilities face capacity constraints. Ultra-low-cost carriers in the United States exhibit highest price sensitivity through power-by-the-hour contract negotiations, while sovereign military procurement shows lowest sensitivity due to MIL-STD qualification requirements.
Supply Chain Analysis
Refurbishment flows from high-time generator returns in Germany and Singapore feed secondary markets with certified-overhaul units, bypassing new equipment lead times for regional turboprop operators. Precision-wound stator coil production concentrates in Japan and Germany, while rare earth magnet processing anchors in China. Raw material dependencies span neodymium-iron-boron magnets, high-temperature insulation films, and silicon carbide semiconductors. Single-source vulnerability in specialized winding expertise creates geographic chokepoints for above-200 kVA ratings. Distribution runs through Boeing and Airbus Tier 1 integrators rather than component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Permanent magnet technology is displacing brush-type excitation architectures across narrow-body and hybrid-electric platforms, compressing supplier transition windows for legacy equipment portfolios.
For Market Incumbents: Anchor defensive positions through backward integration into silicon carbide power electronics and thermal management subsystems, closing qualification gaps that challengers exploit. Deepen certification investment in EASA's evolving CS-25 variable-frequency pathways before parallel compliance documentation becomes mandatory. Defend against emerging power electronics specialists by capturing airframe-level electrical system contract consolidation. For New Entrants and Emerging Players: Capture white space in 500 kW to 2 MW variable-frequency generators for urban air mobility and regional turboelectric architectures where incumbent certification portfolios remain thin. Target aftermarket digitalization through predictive maintenance platforms for Asia-Pacific lessor fleets. Enter via health monitoring sensor integration partnerships with Singapore and Hamburg MRO hubs. For Investors and Strategic Acquirers: EASA's publication of definitive hybrid-electric certification guidance is the leading indicator that variable-frequency generator demand will inflect within the mid-horizon window. Focus acquisition screening on specialized winding houses with liquid-cooled stator expertise in Japan or Germany. Monitor FAA Part 25 amendment timelines for electrical system redundancy as the signal for brushless retrofit program acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Technology Licensing | Eliminates excitation losses for Safran and GE on next-generation narrow-body platforms. |
| Silicon Carbide Power Electronics Integration | Enables variable-frequency operation for Honeywell's generator control unit roadmaps. |
| Airframe-Level Electrical System Contracting | Compresses distributor margins while elevating RTX and AMETEK integrator relationships. |
| Predictive Maintenance Platform Deployment | Creates recurring revenue streams through embedded sensor health monitoring at Crane Aerospace. |
| Rare Earth Supply Agreement Structuring | Reduces neodymium price volatility exposure for Thales and HEICO magnet sourcing. |
Methodological Framework
Document review covered FAA Part 25 and EASA CS-25 certification filings, aircraft production databases, and rare earth trade customs records, complemented by interviews with electrical system engineering directors at Tier 1 integrators, procurement leads at Boeing and Airbus, MRO facility managers in Germany and Singapore, and power electronics R&D heads at semiconductor suppliers. Secondary validation drew from DO-160G environmental qualification test reports, MIL-STD-704 power quality specifications, and EU Green Deal sustainable aviation fuel policy documents. Bottom-up generator unit forecasts triangulated against top-down airframe delivery projections.
Installed base and revenue estimates across the projection horizon reflect segmentation by generator type, power rating tier, technology architecture, and end-user category, with specific modeling of alternator versus integrated drive generator substitution patterns. CAGRs were derived from airframe production schedules, fleet retrofit timelines, and regulatory mandate implementation phases. Industry-specific forecast inputs included EASA's CS-25 electrical system interpretation evolution and FAA extended-range twin-engine operational rulemaking.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth supply disruptions, airworthiness authority harmonization delays, and hybrid-electric platform program cancellations. Forecasts reflect documented assumptions on certification timeline probabilities and airframer specification trajectories. Practitioners should monitor EASA CS-25 amendment publication schedules and Chinese rare earth export quota announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
More Electric Aircraft Market
Aircraft Power Systems
Asia-Pacific Aircraft Circuit Breakers Market
Aircraft Power Systems
Aircraft Fluid Power Components Market
Aircraft Power Systems
Air Independent Propulsion Systems (AIP) Market
Aircraft Power Systems
Electrified Aircraft Propulsion Market
Aircraft Power Systems
Commercial Aviation Electrical Wiring Interconnection System (EWIS) Market
Aircraft Power Systems
Aircraft Turbocharger Market
Aircraft Power Systems
Thrust Vector Control (TVC) Systems Market
Aircraft Power Systems
Aircraft Thrust Reverser Market
Aircraft Power Systems
Commercial Aircraft Propeller Systems Market
Aircraft Power Systems
Liquid Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Space Power System Hardware-in-the-Loop Test Platforms Market
Aircraft Power Systems
Aircraft Propeller System Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Market
Aircraft Power Systems
Aircraft Electrical Systems Market
Aircraft Power Systems
Aerospace Battery Technology Market