
 Fly-By-Wire System Market | 2026-2036
Fly-By-Wire System Market Size, Share, and Industry Trends Forecast 2026-2036
Fly-By-Wire System Market Analysis
Consolidation among commercial airframe OEMs is recalibrating supplier bargaining power across the fly-by-wire value chain. Moog Inc. leverages its actuator specialization to secure long-term platform contracts with Boeing and Airbus. Honeywell International Inc. sustains flight control computer leadership through embedded software differentiation. BAE Systems Plc anchors military fly-by-wire demand via its Eurofighter Typhoon and F-35 workshare.
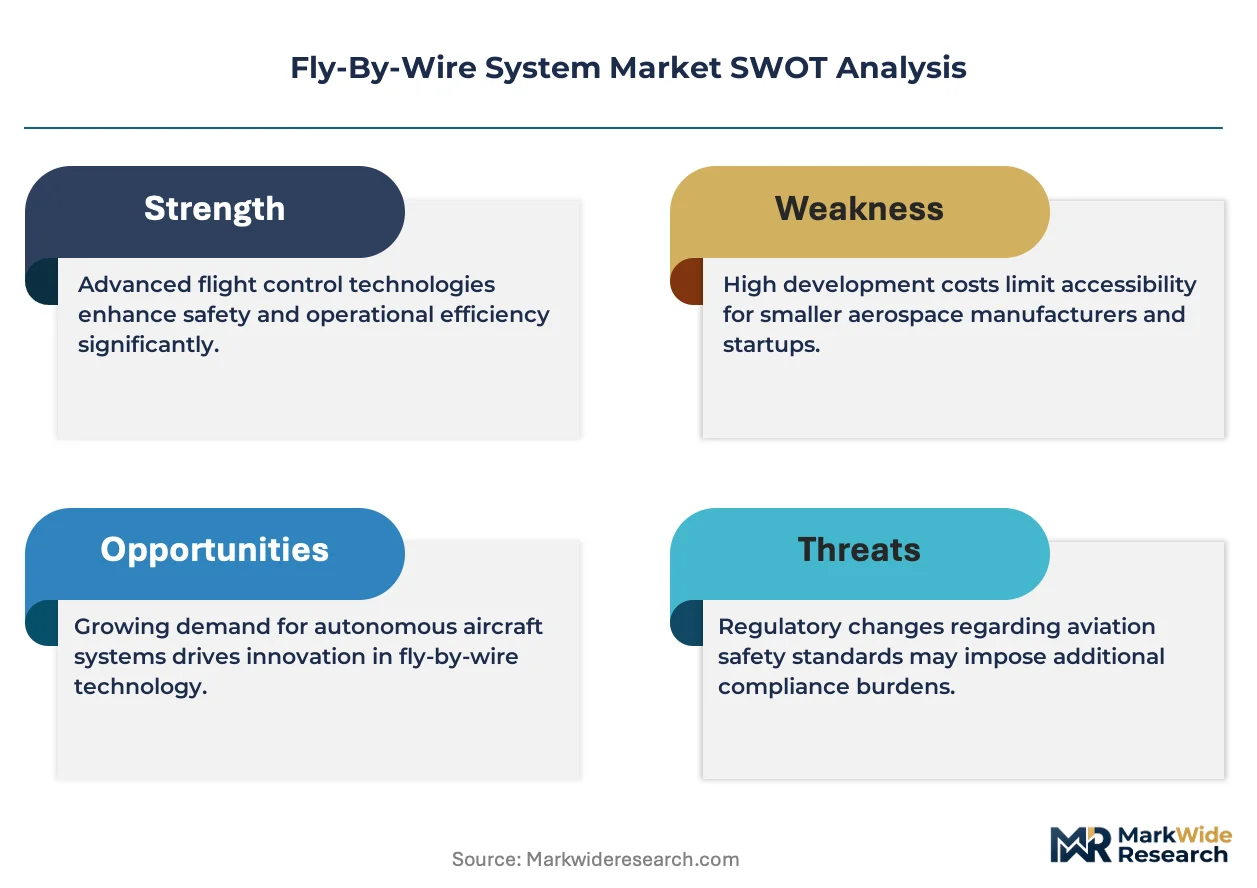
Fly-by-wire systems replace mechanical flight controls with electronic interfaces that transmit pilot inputs through digital signals to surface actuators, typically requiring triplex or quadruplex redundancy architectures with failure probabilities below 10^-9 per flight hour. These systems enable active stability augmentation, envelope protection, and handling quality optimization for modern aircraft. Flight control computers command the highest engineering margins due to safety-critical software certification burdens, while actuator demand scales with airframe production rates across commercial and military platforms. Electromechanical actuation is displacing legacy hydraulic architectures in next-generation designs, though hydraulic backup channels persist in wide-body applications.
FAA Part 25 airworthiness standards and EASA CS-25 certification requirements mandate exhaustive failure mode analysis for electronic flight control systems, creating multi-year qualification barriers for new entrants. The EU AI Act and emerging machine-learning guidance from EASA are beginning to shape adaptive control algorithm validation protocols. Stakeholders must monitor how civil and military regulators reconcile autonomous flight autonomy thresholds with existing redundancy doctrines.
Market Dynamics
Electromechanical actuation architectures are displacing hydraulic flight control systems across next-generation commercial and military platforms, compressing supplier lead times while elevating software certification burdens for flight control computers.
Growth Catalysts
- FAA Part 25 Certification Standards:Tightened redundancy mandates for commercial aircraft flight control systems are forcing platform upgrades across aging fleets, generating replacement demand for triplex and quadruplex architectures.
- Defense Modernization Cycles:Fighter fleet recapitalization programs in the United States, United Kingdom, and Japan are accelerating procurement of integrated flight control suites with embedded electronic warfare interfaces.
- Active Stability Augmentation:Relaxed static stability designs in commercial airframes depend on continuous fly-by-wire intervention, embedding these systems as non-optional infrastructure in new aircraft programs.
Market Restraints
- Rare Earth Magnet Supply Concentration:Electromechanical actuator motors depend on neodymium and dysprosium supply chains concentrated in Chinese processing facilities, exposing OEMs to export restriction volatility.
- Software Certification Burden:DO-178C compliance for flight control computer software requires multi-year validation cycles that extend program timelines and freeze architecture decisions early in development.
- Skilled Systems Engineering Scarcity:The intersection of aerospace mechanical design, embedded software, and safety-critical verification creates talent bottlenecks at prime contractors and Tier 1 suppliers.
Strategic Opportunities
- Urban Air Mobility Certification Pathways:EASA's SC-VTOL special condition framework for electric vertical take-off aircraft creates a regulatory opening for simplified fly-by-wire architectures with reduced redundancy requirements.
- Retrofit Markets in Emerging Economies:Secondary operators in India and Brazil seek avionics modernization packages that upgrade mechanical control systems to digital interfaces without full platform replacement.
- Adaptive Control Algorithm Integration:Convergence of model-predictive control with real-time sensor fusion enables envelope protection systems that adjust dynamically to degraded flight conditions.
Industry Challenges
- Cross-Domain Cybersecurity Verification:Flight control networks must demonstrate isolation from passenger connectivity systems under evolving airworthiness security guidelines, complicating system integration.
- Legacy Platform Interoperability:Hybrid architectures combining new digital controls with existing hydraulic backups require extensive regression testing that strains qualification resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fly-By-Wire System Market |
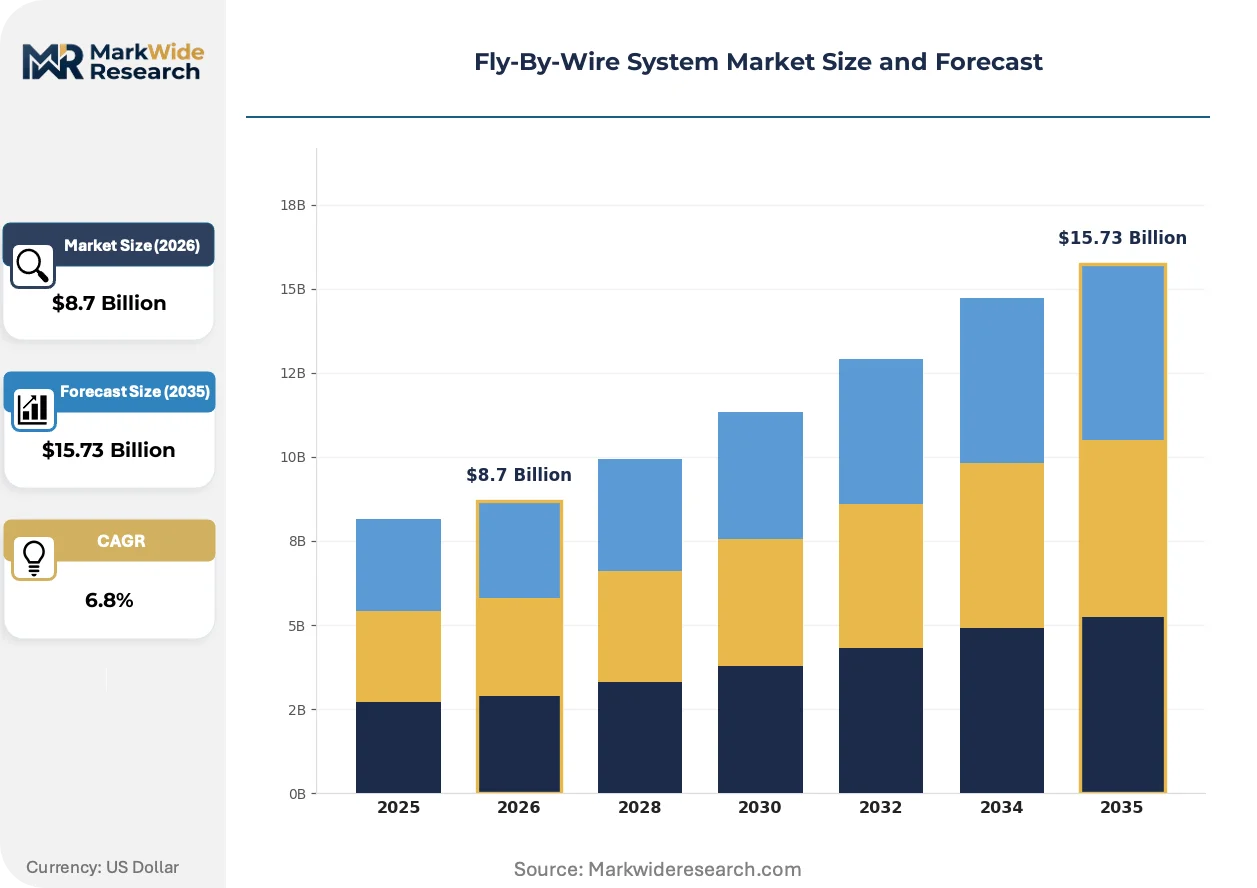
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
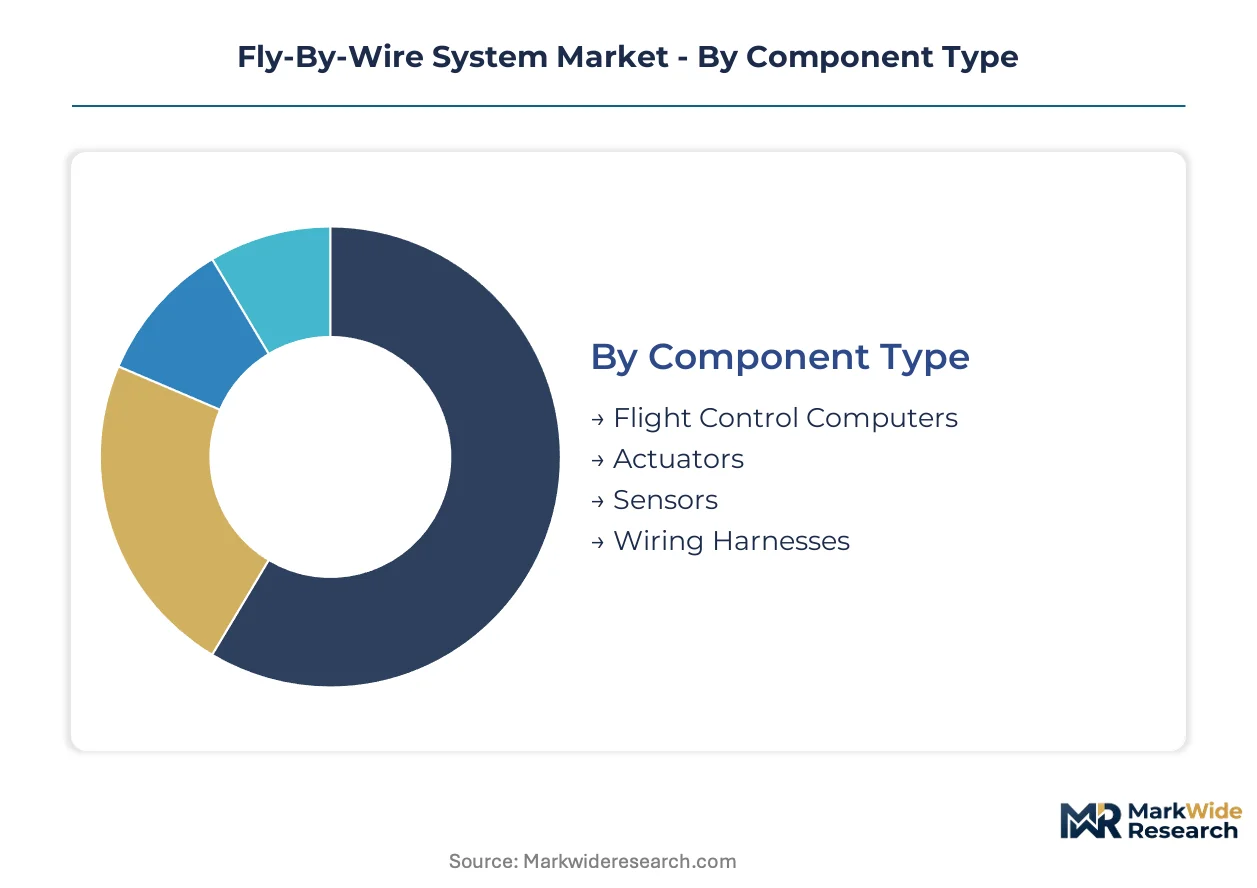
| Segmentation | Component Type: Flight Control Computers, Actuators, Sensors, Wiring Harnesses End User: Commercial Aviation, Military Aviation, General Aviation, Unmanned Aerial Vehicles Technology: Electromechanical, Hydraulic, Fly-By-Wire, Fly-By-Light Application: Aerospace, Avionics, Defense, Civil Aviation |
| Companies Covered | Dassault Aviation SA, Liebherr International AG, BAE Systems Plc, Moog Inc., Lockheed Martin Corp., Collins Aerospace, Honeywell International Inc., Parker Hannifin Corp., Curtiss Wright Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fly-By-Wire System Market Emerging Trajectories
Digital flight control architectures are penetrating deeper into aircraft subsystems, extending beyond primary flight surfaces to thrust vectoring, landing gear, and braking systems. This expansion is compressing the boundary between avionics and mechatronics.
Electromechanical actuators with brushless DC motors and integrated motor control electronics are automating surface positioning commands that previously required hydraulic pressure distribution. Narrow-body OEMs are adopting these units for aileron and elevator control, eliminating centralized hydraulic pumps and reducing weight penalties. The shift is automating maintenance scheduling through built-in health monitoring that transmits actuator wear data directly to ground operations centers.
EASA's emerging guidance on machine learning in safety-critical systems is creating validation protocols for neural-network-based adaptive control laws. The agency's interpretive material requires deterministic bounding of algorithm outputs under all foreseeable input conditions, forcing developers to maintain traditional redundancy overlays even where AI handles nominal control. Military programs with existing autonomous flight testbeds are most affected, as they must reconcile experimental control architectures with civil certification precedents for any dual-use technology transfer.
Airframe OEMs are consolidating flight control procurement under long-term sole-source agreements that bundle hardware, software, and lifecycle support. This pattern concentrates supplier relationships around incumbent platforms while raising barriers for entrants lacking established certification histories. The concentration is most visible in single-aisle programs, where production rate commitments spanning decades lock in actuator and computer suppliers early in development cycles.
Fly-By-Wire System Market Segmentation
Fly-by-wire system segmentation reveals how component specialization, end-use requirements, and technology maturity create distinct procurement patterns across the aerospace value chain. Understanding these divisions clarifies where engineering margins concentrate versus where volume manufacturing dominates.
Component Type:
Flight control computers operate as embedded subsystems within broader avionics architectures, while actuators and sensors frequently ship as standalone line-replaceable units with independent certification paths.
- Flight Control Computers:Triplex and quadruplex redundant processing units executing control laws with deterministic timing constraints. DO-178C software certification burdens concentrate value capture with incumbents holding established FAA and EASA qualification histories. Demand clusters in United States and European commercial OEM programs where failure probability thresholds below 10^-9 per flight hour are mandatory.
- Actuators:Electromechanical and electrohydraulic units converting digital commands to surface movement, incorporating position feedback loops and health monitoring electronics. Surface control actuator procurement scales directly with airframe production rates at Boeing and Airbus final assembly lines, with military fighter programs in Japan and United Kingdom contributing specialized thrust vectoring variants.
- Sensors:Inertial reference units, air data modules, and angle-of-attack vanes providing flight state feedback to control computers. Miniaturized MEMS-based architectures are penetrating general aviation retrofit markets.
- Wiring Harnesses:Shielded copper and fiber optic cable assemblies transmitting power and data between distributed control nodes. Weight reduction pressures favor composite jacketing materials.
Volume placements concentrate in actuators; the faster expansion belongs to flight control computers as software-defined functionality displaces hardware redundancy.
End User:
Procurement scale and certification stringency diverge sharply between passenger-carrying platforms and unmanned systems, reshaping supplier qualification requirements.
- Commercial Aviation:Narrow-body and wide-body airliners requiring full Part 25/CS-25 certification with quadruplex redundancy. Single-aisle production rates at Airbus and Boeing facilities in Alabama and Washington State drive the largest absolute component demand.
- Military Aviation:Fighter, transport, and rotary-wing platforms with embedded electronic warfare interfaces and damage-tolerant control reconfiguration. United States F-35 and United Kingdom Eurofighter Typhoon programs anchor procurement volumes.
- General Aviation:Business jets and turboprops adopting simplified digital control architectures as retrofit packages. Brazil and India host emerging demand for avionics modernization without full platform replacement.
- Unmanned Aerial Vehicles:Remotely piloted and autonomous systems with reduced redundancy requirements under special condition frameworks. EASA SC-LUAS and FAA Part 89 pathways are creating simplified certification routes.
Commercial aviation commands the largest revenue pool; unmanned aerial vehicles are climbing the fastest as regulatory frameworks mature for beyond-visual-line-of-sight operations.
Technology:
Architecture transitions from hydraulic to electromechanical systems are compressing maintenance intervals while elevating power electronics content.
- Electromechanical:Brushless DC motor-driven actuators with integrated motor control electronics eliminating centralized hydraulic distribution. Narrow-body programs from Airbus and Boeing in Toulouse and Renton have adopted these units for primary flight controls, removing hydraulic pumps and reducing weight penalties.
- Hydraulic:Legacy servo-valve architectures with high power density for wide-body applications requiring substantial surface hinge moments. Persisting as backup channels in triple-redundant designs.
- Fly-By-Wire:Conventional electronic flight control with digital signal transmission replacing mechanical linkages. Standard architecture for all modern transport category aircraft.
- Fly-By-Light:Fiber optic data transmission offering electromagnetic interference immunity and weight reduction. Military stealth applications in United States programs exploit this technology for reduced observability signatures.
Electromechanical placements dominate new program wins; fly-by-light is gaining share fastest in defense applications where electromagnetic hardening is critical.
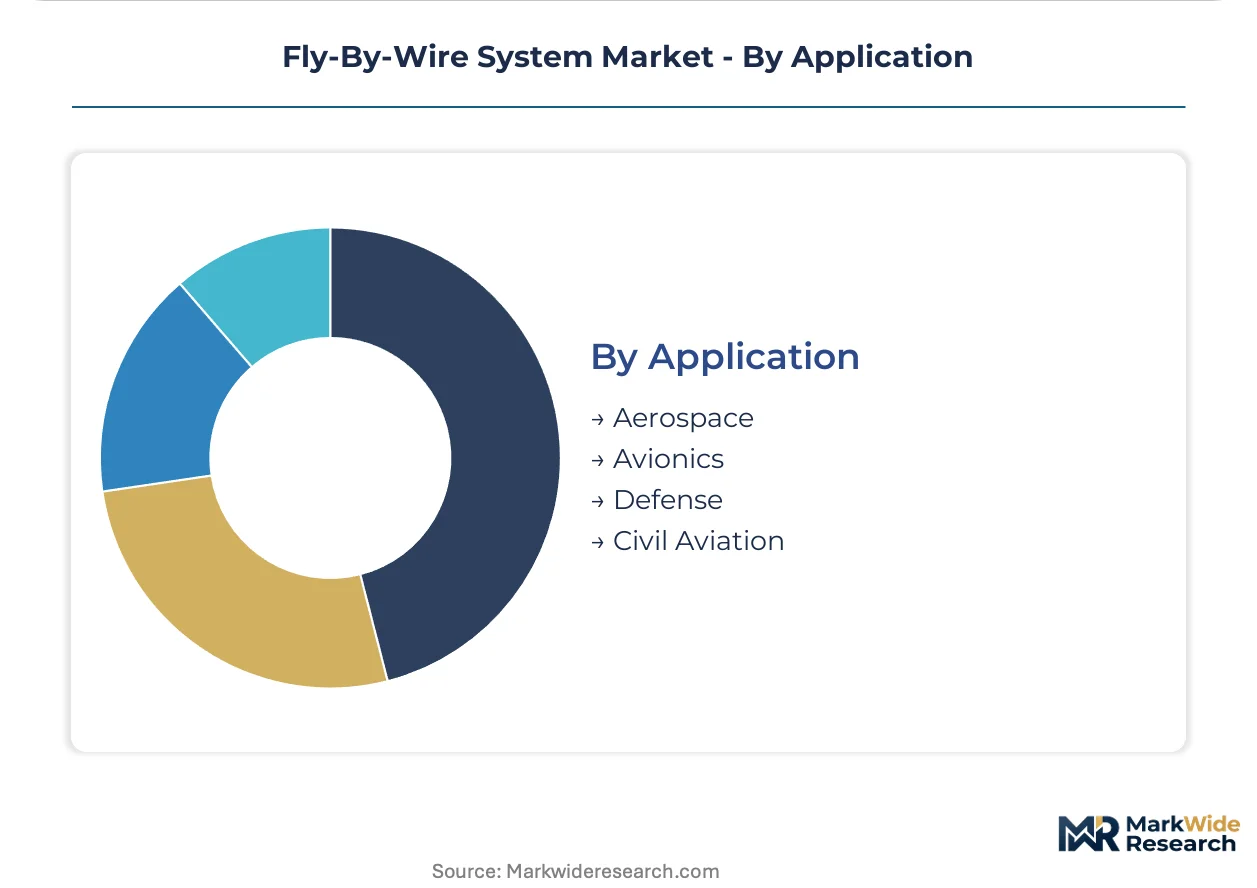
Application:
Integration depth varies from standalone flight control to unified vehicle management systems spanning propulsion and landing gear.
- Aerospace:Primary flight surface control as core aircraft function. Airbus A320 family production in Hamburg and Mobile represents the largest single application demand.
- Avionics:Integrated flight management and control law computation within broader cockpit electronics suites. United States and French suppliers dominate this embedded software-intensive segment.
- Defense:Mission-adaptive control with reconfiguration for battle damage and electronic countermeasures. United Kingdom and Japanese fighter modernization programs are expanding procurement.
- Civil Aviation:Regulatory-compliant systems for passenger and cargo transport under FAA and EASA oversight. Certification reciprocity agreements between United States and European authorities streamline cross-border approvals.
Aerospace captures the highest unit volumes; defense applications are expanding most quickly as Indo-Pacific military procurement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement and commercial OEM activity concentrate demand in the United States, while European regulatory frameworks and Asian fleet modernization programs shape secondary growth centers.
United States
F-35 production at Lockheed Martin facilities in Fort Worth and sustained defense budgeting anchor military fly-by-wire procurement. FAA Part 25 certification standards tighten redundancy mandates for commercial platforms, forcing fleet upgrades. Boeing's final assembly lines in Everett and Renton drive actuator demand for narrow-body and wide-body programs.
United Kingdom
Eurofighter Typhoon workshare agreements and F-35 component manufacturing sustain BAE Systems flight control activity. EASA CS-25 certification requirements align with FAA standards, streamlining transatlantic approvals. Aerospace clusters in Lancashire and Bristol concentrate electronic warfare-integrated control system development.
Japan
F-X fighter development and F-35 procurement under the Japan Air Self-Defense Force modernization program expand integrated flight control demand. METI industrial policy supports domestic aerospace supply chain deepening. Nagoya aerospace corridors host Mitsubishi Heavy Industries assembly activity linking to global OEM networks.
Germany
Airbus Hamburg final assembly lines for A320 family aircraft generate electromechanical actuator procurement at scale. EU AI Act emerging guidance shapes validation protocols for adaptive control algorithms. Bavaria and Baden-Württemberg host Tier 1 suppliers specializing in motor control electronics for brushless DC architectures.
France
Dassault Aviation Rafale production and Airbus Toulouse wide-body assembly sustain dual military-commercial demand. EASA headquarters in Cologne influences certification harmonization across member states. Occitanie aerospace clusters concentrate flight control computer software development for envelope protection systems.
Fly-By-Wire System Market Vendor Landscape
United States producers anchor the defense-tier supply base; European specialists hold commercial aviation integration roles. The vendor structure concentrates around long-term sole-source agreements with airframe OEMs, compressing entry opportunities for unqualified entrants. Three archetypes dominate: actuator-focused hardware suppliers, flight control computer incumbents with certification histories, and diversified aerospace primes bundling subsystem integration. Competitive moves center on backward integration into motor control electronics and geographic expansion through platform workshare agreements.
Within the diversified prime tier, BAE Systems Plc and Lockheed Martin Corp. exemplify military platform integration, anchoring fighter program workshare across transatlantic supply chains. Moog Inc. and Honeywell International Inc. occupy positions spanning actuator hardware and embedded software domains, representing the specialized subsystem archetype. These four entities illustrate how certification barriers and long-term OEM relationships stratify competitive positioning.
| Leading Market Players |
|---|
| Dassault Aviation SA |
| Liebherr International AG |
| BAE Systems Plc |
| Moog Inc. |
| Lockheed Martin Corp. |
| Collins Aerospace |
| Honeywell International Inc. |
| Parker Hannifin Corp. |
| Curtiss Wright Corp. |
| Others |
Supply Flow & Price Mechanics
Electromechanical actuation transitions from centralized hydraulic distribution to distributed brushless DC motor architectures are compressing manufacturing lead times while elevating power electronics content costs. This technology shift simultaneously concentrates supplier bargaining power among motor control specialists in Germany and Japan while forcing airframe OEMs into long-term sole-source agreements that lock in pricing tiers early in development cycles.
Pricing Analysis
Volume placements in electromechanical actuators run on thin margins tied to Airbus and Boeing production schedules, while flight control computers capture premium pricing through DO-178C certification barriers. Price differentiation hinges on software qualification history and redundancy architecture tier—triplex systems command substantial premiums over duplex configurations for general aviation retrofit markets. Cost compression in actuator hardware is intensifying as Moog and Honeywell consolidate procurement under decade-long platform contracts. Military buyers at the United States Department of Defense exhibit lowest price sensitivity due to embedded electronic warfare requirements, whereas secondary operators in Brazil and India driving avionics modernization packages face acute budget constraints.
Supply Chain Analysis
Reverse-logistics flows for flight control computers center on refurbishment cycles at BAE Systems facilities in Lancashire and Honeywell service centers in Arizona, where remanufactured units re-enter military supply chains under performance-based logistics contracts. Geographic supply concentration clusters in the United States, Germany, and the United Kingdom for flight control computers, while electromechanical actuator motor magnets draw from Chinese rare earth processing facilities. Raw material dependencies span neodymium and dysprosium for brushless motors, high-reliability semiconductors for motor control electronics, and aerospace-grade aluminum forgings for actuator housings. Single-source vulnerability in Chinese rare earth supply exposes OEMs to export restriction volatility. Distribution runs through airframe OEM final assembly lines at Airbus facilities in Hamburg and Toulouse, Boeing plants in Everett and Renton, and Lockheed Martin operations in Fort Worth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in fly-by-wire systems is hardening into a vertical-integration race, with incumbent suppliers pursuing backward integration into motor control electronics and rare earth magnet recycling to secure input cost control.
For Market Incumbents: To counter rare earth supply disruption threats, Moog and Honeywell should deepen captive supply of brushless DC motor windings through acquisition of specialized coil manufacturers in Bavaria and Baden-Württemberg. Certification investment in EASA SC-VTOL adaptive control pathways creates defensive moats against emerging urban air mobility entrants lacking established airworthiness histories. Lock-in of sole-source agreements with Airbus and Boeing for next-generation narrow-body programs remains the priority lever for volume retention. For New Entrants and Emerging Players: The premium-to-economy price gap in flight control computers—between quadruplex Part 25-certified units and simplified duplex architectures—opens viable entry space in EASA SC-LUAS unmanned aerial vehicle certification pathways. Brazil and India avionics retrofit markets present the most penetrable geographies, where mechanical-to-digital control upgrades bypass full platform replacement economics. A go-to-market angle bundling hardware with predictive maintenance software subscriptions addresses secondary operator total-cost-of-ownership sensitivity. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified aerospace primes seeking flight control subsystem integration capabilities. Long-term viability over a five-to-ten year horizon hinges on positioning within F-35 and next-generation fighter program workshares, where production rate commitments span multiple decades. Acquisition targets should display established FAA and EASA qualification histories plus active military platform integration. The signal to watch is EASA machine-learning guidance finalization, which will determine whether adaptive control algorithm developers can bypass traditional redundancy overlays.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Control Electronics | Captures margin from brushless DC actuator production at Airbus and Boeing narrow-body lines. |
| EASA SC-VTOL Certification Investment | Unlocks urban air mobility demand from Lilium and Archer electric vertical take-off programs. |
| Rare Earth Magnet Recycling Partnership | Reduces Chinese supply concentration exposure for neodymium-dependent actuator motors. |
| Long-Term Sole-Source Agreement Extension | Locks in actuator and computer supply for next-generation single-aisle development cycles. |
| Adaptive Control Algorithm Validation | Positions for EASA machine-learning guidance compliance in envelope protection systems. |
Methodological Framework
Multi-period observation of airframe production rates at Airbus and Boeing facilities, defense procurement disclosures from the United States Department of Defense and Japan Ministry of Defense, and regulatory filing patterns at FAA and EASA anchored the trend analysis, supplemented by interviews with flight control system engineering directors, airframe OEM procurement managers, Tier 1 supplier program directors, and military platform integration leads. Secondary validation drew from FAA Part 25 certification databases, EASA CS-25 type certificate records, SEC 10-K aerospace segment disclosures, and customs trade data for electromechanical actuator components. Bottom-up component demand modeling triangulated against top-down airframe production forecasts.
Input-output matrices mapped flight control computer, actuator, and sensor placements to specific airframe programs across commercial, military, and unmanned segments. Segmentation dimensions modeled included component type, end user category, technology architecture, and application depth. CAGRs were derived from production rate commitments at named final assembly lines and defense modernization program timelines. Industry-specific forecast inputs incorporated F-35 lot procurement schedules, A320 family production rate adjustments at Hamburg and Mobile, and METI industrial policy support levels for Japanese aerospace supply chain deepening.
Inputs from FAA certification databases and EASA type certificate records were available through the study window; gaps in classified military program specifications introduce uncertainty bands around fighter platform integration forecasts. Forecasts reflect assumptions regarding sustained defense budgeting in the United States and United Kingdom, continued Airbus and Boeing single-aisle production rate stability, and EASA machine-learning guidance timeline adherence. Practitioners should monitor rare earth export policy shifts from Chinese regulatory authorities and EASA adaptive control algorithm interpretive material publication for early signals of supply cost and certification pathway revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Military Aircraft Actuation System Market
Aircraft Power Systems
Aircraft Electrical Power Distribution Systems Market
Aircraft Power Systems
Commercial Aircraft Actuation System Market
Aircraft Power Systems
Air Independent Propulsion Systems (AIP) Market
Aircraft Power Systems
Aviation High Speed Motor Market
Aircraft Power Systems
Aircraft Drive Shaft and Couplings Market
Aircraft Power Systems
Aircraft Actuator Market
Aircraft Power Systems
Americas Aircraft Lighting Market
Aircraft Power Systems
Low-Carbon Propulsion Market
Aircraft Power Systems
Aircraft Propeller System Market
Aircraft Power Systems
Space Power System Hardware-in-the-Loop Test Platforms Market
Aircraft Power Systems
Thrust Vector Control (TVC) Systems Market
Aircraft Power Systems
Aircraft Hydraulic Seat Actuation Systems Market
Aircraft Power Systems
Commercial Aircraft Propeller Systems Market
Aircraft Power Systems
Aircraft Lift Control Devices Market
Aircraft Power Systems
Hydrogen-Powered Aircraft Market