
 Commercial Airframe Component Market | 2026-2036
Commercial Airframe Component Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Airframe Component Market Insights
The EU Green Deal's aviation decarbonization targets is realigning procurement priorities across European tier-one suppliers. Airbus SE leverages its integrated composite manufacturing footprint in Toulouse and Hamburg to sustain fuselage section output for the A350 program. Spirit AeroSystems anchors North American wing assembly supply through its Wichita operations, while GKN Aerospace differentiates via thermoplastic composite expertise for next-generation engine nacelles.
Commercial airframe components encompass structural and aerodynamic elements—wing spars, fuselage barrels, empennage assemblies, and landing gear struts—fabricated through automated fiber placement, superplastic forming, and high-speed machining to achieve specific strength-to-weight ratios and fatigue life thresholds. These elements constitute the primary load-bearing architecture of civil aircraft, directly influencing fuel efficiency, payload capacity, and operational economics. Composite materials command the fastest expansion trajectory as Boeing and Airbus embed carbon fiber-reinforced polymers into wing boxes and tail units to reduce mass. Aluminum alloys retain dominance in single-aisle fuselage applications where cost and repairability outweigh weight savings, while titanium alloys concentrate in high-temperature engine nacelle interfaces and landing gear forgings where specific strength requirements are non-negotiable.
FAA certification standards under 14 CFR Part 25, EASA CS-25 airworthiness codes, and China's CAAC CCAR-25 framework collectively govern structural integrity, flammability resistance, and damage tolerance for commercial airframe components entering service. These regulatory architectures mandate extensive test campaigns and traceable manufacturing records, elevating barriers for non-incumbent suppliers and embedding compliance costs into long-term contracts. Stakeholders must monitor evolving sustainability-linked procurement criteria from airlines and lessors, as Scope 3 emissions disclosure requirements begin penetrating supplier qualification protocols ahead of formal mandates.
Market Dynamics
Boeing and Airbus production rate adjustments for narrow-body platforms are compressing order backlogs and forcing tier-one suppliers to absorb volume volatility through flexible manufacturing contracts.
Growth Catalysts
- FAA 14 CFR Part 25 Certification Alignment:Harmonized airworthiness standards between US and European regulators accelerate dual-certification timelines for new composite wing architectures.
- Single-Aisle Fleet Renewal Cycles:North American and Chinese airlines are retiring aging 737NG and A320ceo aircraft, triggering replacement demand for next-generation fuselage sections.
- Thermoplastic Composite Maturation:Out-of-autoclave processing techniques reduce cure cycles from hours to minutes, enabling throughput gains at wing assembly facilities.
Market Restraints
- Titanium Sponge Supply Concentration:Russian and Chinese smelters control roughly two-thirds of aerospace-grade titanium feedstock, exposing landing gear forgers to geopolitical supply interruptions.
- Dual-Certification Cost Burden:Parallel FAA and EASA test campaigns for damage tolerance validation add 18-24 months to new material qualification timelines.
- Aluminum-Lithium Substitution Limits:Third-generation Al-Li alloys remain confined to fuselage skins due to repairability constraints in wing box applications.
Strategic Opportunities
- India MRO Infrastructure Buildout:The country's PLI scheme for aerospace components attracts foreign joint ventures targeting narrow-body overhaul demand from Middle Eastern carriers.
- Sustainable Aviation Fuel-Compatible Material Sets:EASA CS-25 amendments for SAF compatibility create first-mover advantage for suppliers certifying elastomeric seals and fuel tank coatings.
- Additive Manufacturing-Tribology Convergence:Hybrid processes combining directed energy deposition with precision machining unlock topology-optimized brackets for engine nacelle installations.
Industry Challenges
- Composite Repair Technician Scarcity:Airlines and MROs face 12-18 month training pipelines for bonded patch certification under OEM-approved procedures.
- Automated Fiber Placement Capital Intensity:Multi-axis gantry systems for wing spar fabrication require $40-60 million facility investments with 7-year depreciation cycles.
- Legacy Alloy Obsolescence Management:2000-series aluminum plate specifications from original 737 certifications conflict with modern corrosion-resistant temper requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Airframe Component Market |
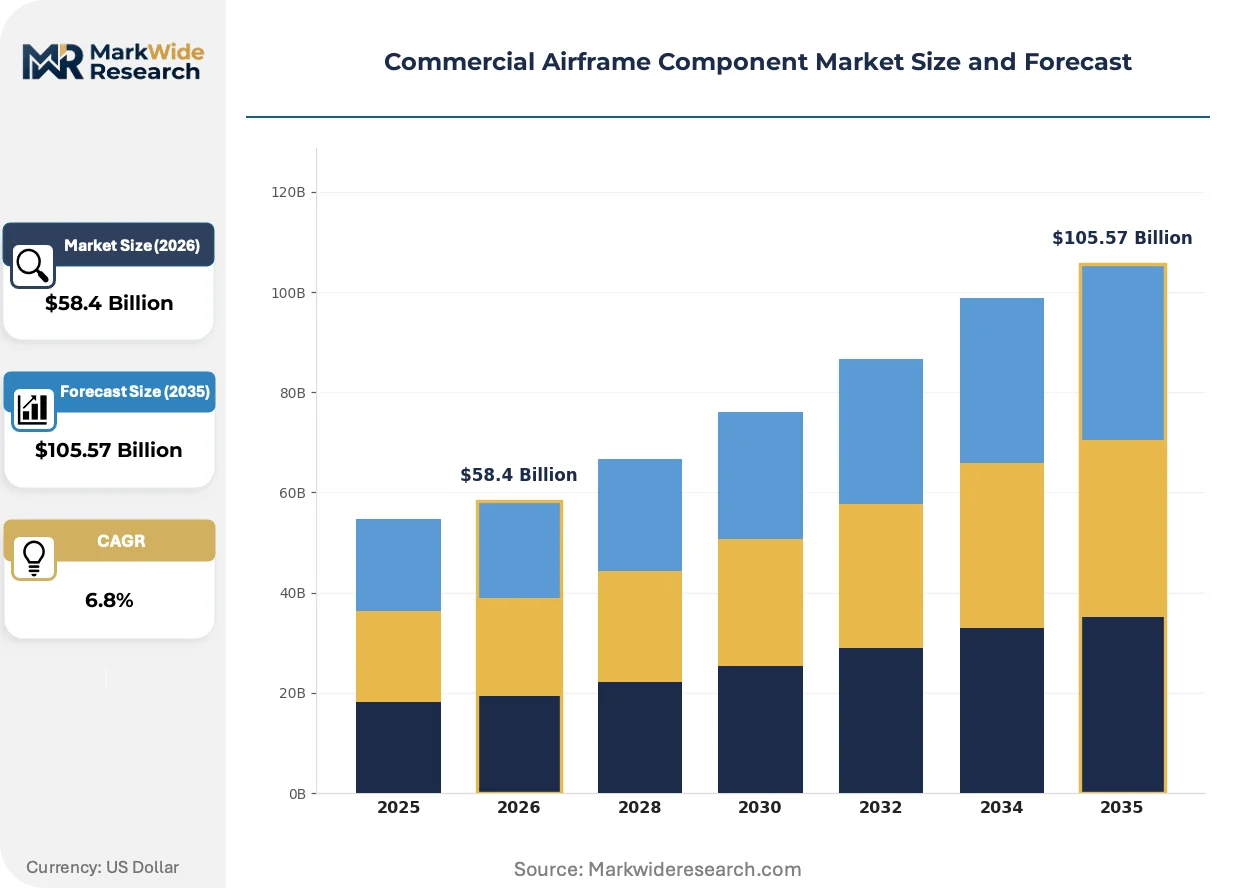
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $105.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Wing Assemblies, Fuselage Sections, Landing Gear, Engine Nacelles, Tail Units Material: Aluminum Alloys, Titanium Alloys, Composite Materials, Steel Alloys, Carbon Fiber Application: Passenger Jets, Cargo Aircraft, Regional Jets, Business Jets, Military Transports End User: Aircraft Manufacturers, Airlines, Maintenance Providers, Aerospace Suppliers, Leasing Firms |
| Companies Covered | Spirit AeroSystems, Airbus SE, The Boeing Company, Mitsubishi Heavy Industries, GKN Aerospace, Triumph Group, Precision Castparts, Leonardo, LISI Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Airframe Component Market Trends and Innovations
Digital thread integration across design-to-manufacturing workflows is compressing development cycles and enabling real-time quality traceability for critical structural assemblies.
Thermoplastic composites are consolidating their position in next-generation engine nacelles and wing leading edges. Airbus and tier-one aerostructures suppliers are qualifying carbon fiber/PEKK laminates for 30% weight reduction versus thermoset alternatives. This material transition is consolidating supplier bases around processors with in-situ consolidation expertise.
EASA's CS-25 amendment process for damage tolerance under fatigue loading is tightening inspection interval requirements for aging narrow-body fleets. European operators must now demonstrate equivalent safety for repaired composite panels versus original equipment. The regulation most affects regional carriers with mixed-generation A320 family fleets operating high-cycle routes.
Airline technical procurement teams are unbundling long-term component contracts into discrete lot purchases with performance guarantees. Lessors now specify residual value clauses tied to OEM traceability documentation rather than blanket supplier warranties. This behavioral shift concentrates in North American and Chinese markets where operating lease penetration exceeds 50% of installed narrow-body capacity.
Commercial Airframe Component Market Segmentation
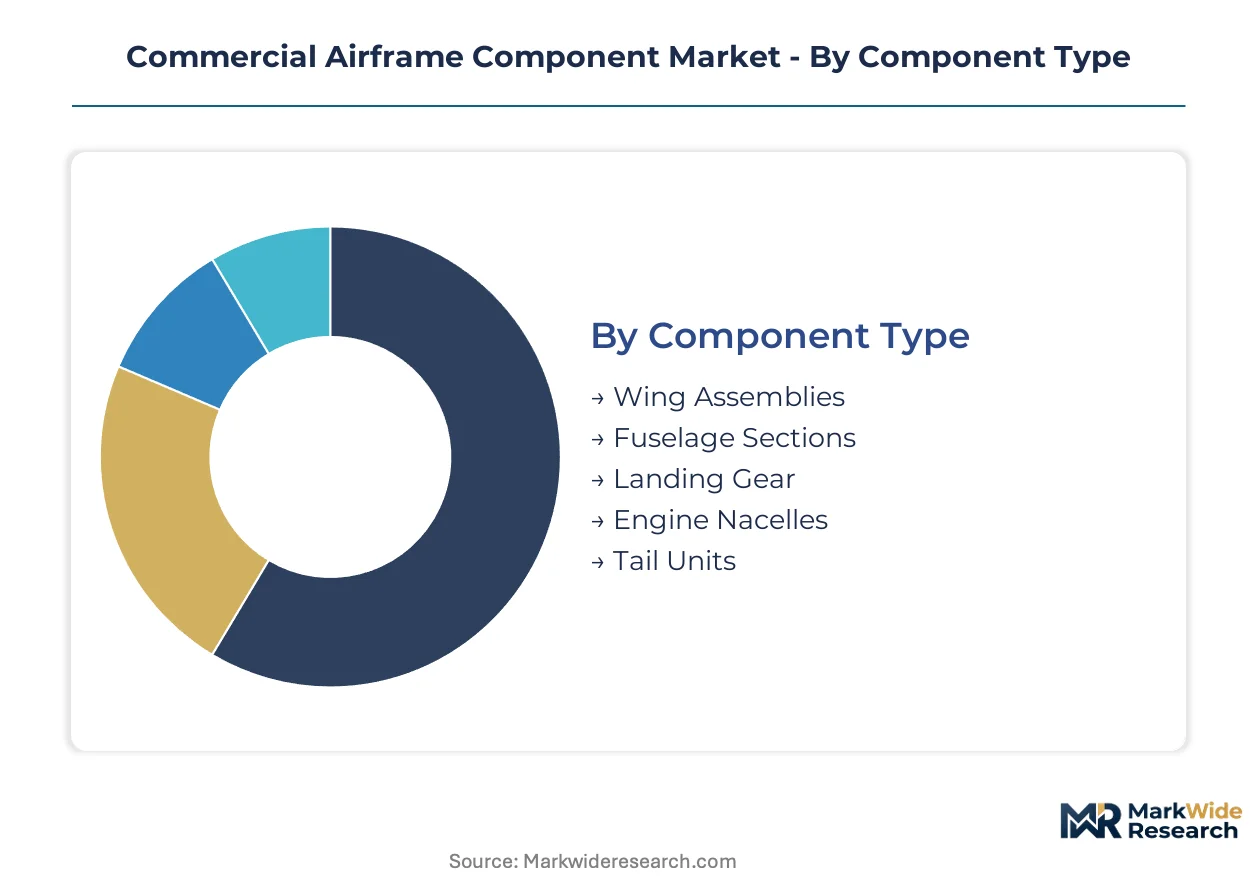
Airframe component procurement patterns diverge sharply across structural roles, material classes, and end-user business models. Understanding these fault lines reveals where pricing power concentrates and where supplier margins compress under volume volatility.
Component Type:
Wing assemblies and fuselage sections operate as integrated structural systems demanding synchronized tier-one supply chains, while landing gear and nacelles embed as modular subassemblies with discrete certification pathways.
- Wing Assemblies:Carbon fiber-reinforced wing boxes and spar assemblies constitute the largest structural mass on modern narrow-body platforms. Boeing 737 MAX and A320neo programs in the United States and France anchor procurement volumes, with Spirit AeroSystems and Airbus Atlantic capturing multi-year fabrication contracts.
- Fuselage Sections:Aluminum-lithium barrels for single-aisle jets and composite forward sections for wide-bodies represent divergent manufacturing footprints. Toulouse and Hamburg final assembly lines drive barrel section demand, while Wichita and Kinston facilities supply North American narrow-body programs.
- Landing Gear:Titanium forgings for strut assemblies concentrate among specialized forgers with heat-treatment and non-destructive testing capabilities.
- Engine Nacelles:Thrust reverser cascades and acoustic liners integrate composite sandwich panels with metallic attachment structures.
- Tail Units:Horizontal and vertical stabilizers leverage automated fiber placement for complex aerodynamic profiles.
Volume placements concentrate in wing assemblies; the faster expansion belongs to engine nacelles as re-engining programs proliferate.
Material:
Material selection trades manufacturing cost against operational weight savings, with procurement patterns splitting between legacy alloy specifications and next-generation composite architectures.
- Composite Materials:Thermoset and thermoplastic matrices reinforced with carbon fiber dominate wing skins, tail cones, and floor beams. Out-of-autoclave processing adoption in Germany and Japan is compressing cure cycle economics for tier-two processors.
- Aluminum Alloys:Third-generation Al-Li alloys and conventional 2xxx/7xxx series retain cost advantages for fuselage skins and frames where damage tolerance and field repairability outweigh mass reduction.
- Titanium Alloys:Aerospace-grade sponge supply from Russian and Chinese smelters feeds landing gear and engine mount forgings requiring specific strength at elevated temperatures.
- Carbon Fiber:PAN-based precursor tow qualifies for primary structure applications under FAA 14 CFR Part 25 damage tolerance mandates.
- Steel Alloys:High-strength steels concentrate in actuator linkages and emergency exit mechanism forgings.
Procurement weight tilts toward aluminum alloys for narrow-body programs; composite materials gain share fastest in wide-body wing architectures.
Application:
Platform scale and mission profile dictate component specification intensity, with single-aisle frequency driving volume and wide-body specialization commanding premium pricing.
- Passenger Jets:Narrow-body platforms generate the absolute unit demand for fuselage barrels and wing boxes, with A320neo and 737 MAX families in China and the United States absorbing tier-one capacity.
- Cargo Aircraft:Freighter conversions and factory-built cargo variants require reinforced floor beams and larger cargo door cutouts, concentrating demand among express logistics operators.
- Regional Jets:Embraer E-Jet and ATR programs in Brazil and France sustain demand for scaled-down wing and tail assemblies.
- Business Jets:Low-volume, high-customization programs emphasize hand-laid composite finishes and premium interior integration.
- Military Transports:Defense procurement cycles operate on separate certification frameworks with hardened specifications for rough-field operations.
Order backlogs stack deepest in passenger jets; cargo applications expand most quickly as e-commerce logistics reshape fleet planning.
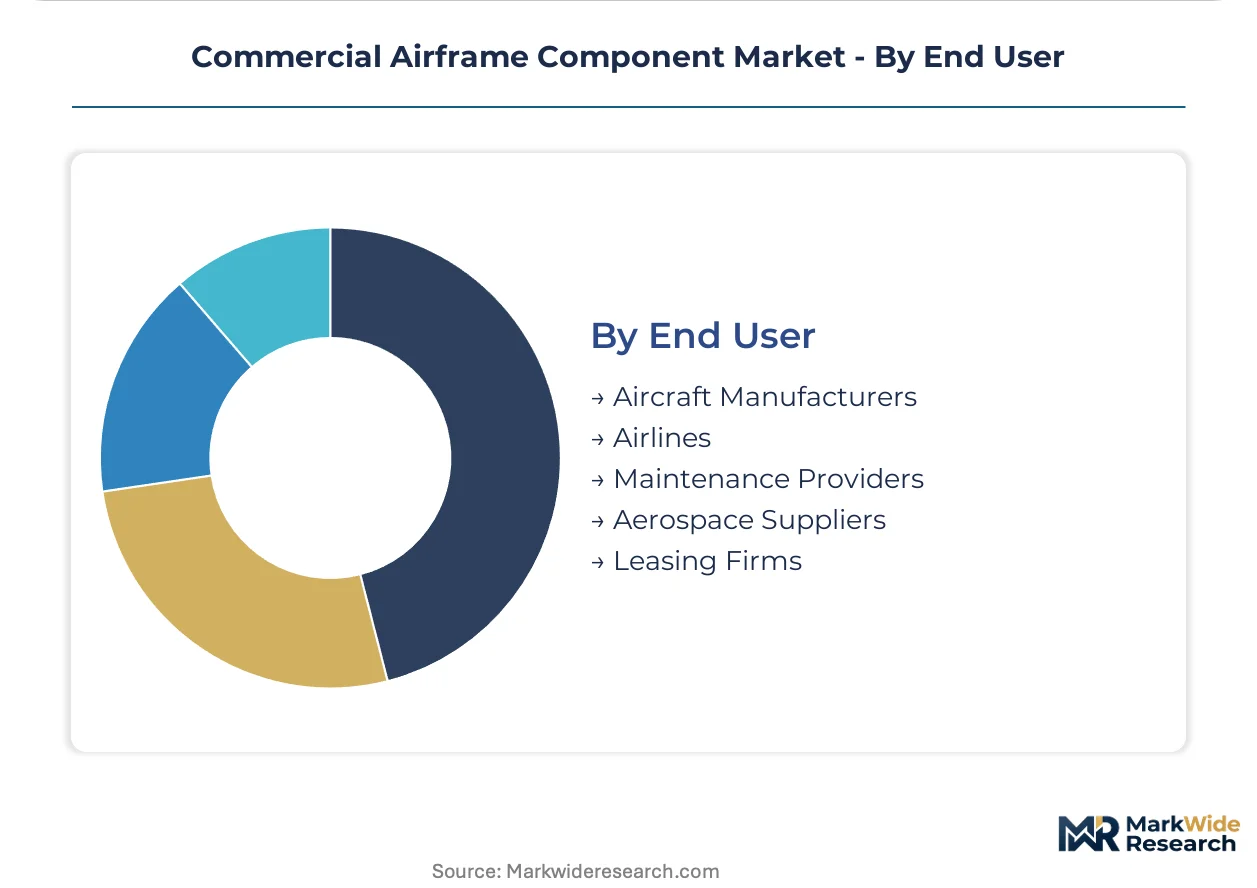
End User:
Procurement authority fragments across OEM new-build programs, airline direct purchases, and lessor specification influence, each imposing distinct contractual and traceability requirements.
- Aircraft Manufacturers:Boeing and Airbus exercise direct control over tier-one aerostructures sourcing, embedding long-term agreements with Spirit AeroSystems, GKN Aerospace, and Leonardo.
- Airlines:Legacy carriers and low-cost operators increasingly specify component traceability and residual value clauses in sale-leaseback arrangements.
- Maintenance Providers:MRO facilities in Singapore and the United Arab Emirates drive aftermarket demand for replacement panels, repair kits, and rotable assemblies.
- Aerospace Suppliers:Tier-two and tier-three fabricators purchase raw materials and semi-finished forms for subassembly production.
- Leasing Firms:AerCap and Air Lease Corporation influence OEM specification standards through fleet placement commitments and residual value guarantees.
Contract value concentrates with aircraft manufacturers; leasing firms are gaining procurement influence fastest as operating lease penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Toulouse anchors the most concentrated aerospace manufacturing corridor in Europe, with Airbus final assembly lines driving tier-one procurement volumes across the continent. Production networks in Wichita and Hamburg sustain parallel supply ecosystems for narrow-body and wide-body platforms respectively.
United States
Boeing's 737 MAX production in Renton and 787 assembly in Charleston sustain demand for composite wing boxes and aluminum fuselage sections. FAA 14 CFR Part 25 certification requirements govern all structural component qualifications. Wichita's aerostructures cluster hosts Spirit AeroSystems fabrication facilities supplying integrated wing assemblies.
France
Airbus SE operates final assembly lines in Toulouse and Hamburg, procuring fuselage barrels and tail units from integrated Atlantic facilities. EASA CS-25 airworthiness codes mandate damage tolerance validation for composite primary structures. The Occitanie region concentrates automated fiber placement capacity for A350 wing spar production.
China
COMAC C919 narrow-body certification is expanding domestic supply chain capacity for aluminum-lithium fuselage sections. CAAC CCAR-25 structural standards align with FAA and EASA frameworks to enable export qualification. Shanghai and Xi'an host emerging tier-one fabrication facilities serving both indigenous and Western OEM programs.
Germany
Premium A320 family output in Hamburg drives procurement of thermoplastic composite tail cones and engine nacelles. EU Green Deal aviation decarbonization targets are reshaping material specifications toward sustainable manufacturing processes. Bavaria's aerospace suppliers specialize in out-of-autoclave processing for reduced cure cycle economics.
Japan
Mitsubishi Heavy Industries and Subaru Corporation supply composite wing boxes for Boeing platforms under long-term risk-sharing partnerships. METI industrial policy supports carbon fiber precursor capacity expansion for aerospace-grade PAN-based tow. Nagoya's Chubu region concentrates automated fiber placement expertise for complex aerodynamic profiles.
Commercial Airframe Component Market Competitive Landscape
The competitive structure tilts toward integrated tier-one aerostructures specialists with captive composite manufacturing footprints. Boeing and Airbus exercise direct procurement control through multi-year fabrication contracts, embedding long-term agreements with Spirit AeroSystems, GKN Aerospace, and Leonardo. Three archetypes dominate: integrated OEM-captive suppliers, independent tier-one fabricators with multi-platform exposure, and specialized material processors with thermoplastic expertise. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as suppliers absorb production rate volatility through flexible manufacturing contracts.
Among North American-based fabricators, Spirit AeroSystems and Triumph Group occupy positions within the independent tier-one archetype, supplying wing assemblies and aerostructures across multiple OEM programs. GKN Aerospace exemplifies the specialized processor category, with thermoplastic composite capabilities for next-generation engine nacelles. Mitsubishi Heavy Industries anchors the risk-sharing partner archetype for Japanese supply into Western platforms. Leonardo represents the European integrated aerostructures model, spanning fixed-wing and rotorcraft applications from Italian facilities.
| Leading Market Players |
|---|
| Spirit AeroSystems |
| Airbus SE |
| The Boeing Company |
| Mitsubishi Heavy Industries |
| GKN Aerospace |
| Triumph Group |
| Precision Castparts |
| Leonardo |
| LISI Aerospace |
| Others |
Pricing and Supply Chain Analysis
Thermoplastic composite maturation is simultaneously compressing cure cycle economics and concentrating supplier bases around processors with in-situ consolidation expertise. Out-of-autoclave processing adoption in Germany and Japan is eliminating traditional autoclave bottlenecks while embedding new capital barriers that reshape tier-two competitive dynamics.
Pricing Analysis
Outcome-based pricing anchors wing assembly contracts, with Spirit AeroSystems and Airbus Atlantic negotiating multi-year fabrication agreements tied to production rate guarantees rather than unit spot prices. Price differentiation separates OEM-captive tier-one suppliers from independent fabricators based on certification depth and traceability documentation quality. Pricing pressure stems from Boeing and Airbus production rate adjustments forcing volume volatility absorption through flexible manufacturing contracts. Low-cost carriers and regional airlines exhibit highest price sensitivity in aftermarket procurement, while lessors prioritize residual value clauses over upfront unit economics.
Supply Chain Analysis
Regional distribution centers in Wichita, Toulouse, and Hamburg coordinate hub-and-spoke patterns for wing spar and fuselage barrel logistics. Geographic supply concentration centers on the United States, France, and China where final assembly lines anchor component procurement volumes. Raw material dependencies draw from Russian and Chinese titanium sponge smelters, Japanese carbon fiber precursor capacity, and German out-of-autoclave processing equipment. Single-source vulnerability in aerospace-grade titanium feedstock exposes landing gear forgers to geopolitical interruption. Distribution runs through tier-one aerostructures specialists with captive composite manufacturing footprints before OEM final assembly integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained, with automated fiber placement capital intensity propping pricing power among incumbent tier-one fabricators. Boeing and Airbus production rate volatility compresses order backlogs while elevating barriers for non-incumbent suppliers.
For Market Incumbents: Deepen thermoplastic composite expertise to capture next-generation engine nacelle and wing leading edge qualification cycles. Expand in-situ consolidation capacity in Germany or Japan to exploit out-of-autoclave processing economics. Secure long-term titanium sponge supply agreements independent of Russian and Chinese smelter concentration. Defend against emerging Asian tier-two processors by embedding FAA-EASA dual-certification documentation into standard contract terms.
For New Entrants and Emerging Players: Capture India MRO infrastructure buildout opportunities under the country's PLI scheme for aerospace components. Target narrow-body overhaul demand from Middle Eastern carriers seeking regional repair capacity. Exploit composite repair technician scarcity by developing bonded patch certification training pipelines approved under OEM procedures. Position through joint ventures with established European tier-two fabricators to bypass 18-24 month dual-certification timelines.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized thermoplastic composite processors given EASA CS-25 SAF compatibility amendments. Long-term viability favors suppliers certifying elastomeric seals and fuel tank coatings for sustainable aviation fuel exposure. Acquisition focus should center on tier-two fabricators with out-of-autoclave processing expertise in Bavaria or Nagoya. Monitor Boeing 737 MAX and Airbus A320neo production rate announcements as inflection indicators for capacity utilization across tier-one supplier bases.
| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Composite Qualification | Carbon fiber/PEKK laminates for A350 wing spars enable 30% weight reduction versus thermoset alternatives. |
| Dual-Certification Investment | Parallel FAA 14 CFR Part 25 and EASA CS-25 validation accelerates market access for new material architectures. |
| Backward Integration into Titanium Feedstock | Captive sponge sourcing insulates landing gear forgers from Russian and Chinese supply concentration risks. |
| India MRO Joint Venture | PLI scheme incentives attract foreign partnerships targeting narrow-body overhaul demand from Gulf carriers. |
| Composite Repair Training Pipeline | OEM-approved bonded patch certification addresses 12-18 month technician scarcity constraining airline MRO capacity. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with tier-one aerostructures procurement managers, composite manufacturing engineers, airline fleet planning directors, MRO facility operations heads, and lessor technical asset managers combined with FAA airworthiness directive databases, EASA certification records, and Boeing-Airbus production disclosures. Bottom-up segment modeling triangulated against top-down OEM delivery forecasts across the analysis window.
Granularity-level modeling disaggregated wing assemblies, fuselage sections, landing gear, and engine nacelles by material class and end-user business model throughout the projection horizon. Component-type splits integrated with platform-specific production rates for narrow-body and wide-body programs. CAGRs derived from regression analysis against Boeing and Airbus order backlogs, fleet renewal cycle timing, and composite material substitution curves. Forecast inputs incorporated thermoplastic adoption trajectories, SAF-compatible material certification timelines, and India PLI scheme implementation progress.
The model holds under stable OEM production rate assumptions and sustained dual-certification harmonization; deviation in titanium supply geopolitics or EASA damage tolerance amendment timing would shift component procurement patterns. Forecasts reflect documented assumptions regarding Boeing 737 MAX and Airbus A320neo delivery schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Inlet Lip Anti-Icing and De-Icing Component Systems Market
Aircraft and Aerospace Components
Impact-Resistant Composite Radome Structures for High-Bandwidth Antennas Market
Aircraft and Aerospace Components
Aerospace Pressure Bulkheads Market
Aircraft and Aerospace Components
Europe Passive Electronic Components in Aerospace and Defense Market
Aircraft and Aerospace Components
Global Aerospace Pressure Gauge Market
Aircraft and Aerospace Components
Aircraft Brake Calipers Market
Aircraft and Aerospace Components
Advanced Turbine Blade Design Market
Aircraft and Aerospace Components
Air Taxi Exterior Component Systems Market
Aircraft and Aerospace Components
Europe Rotor Blade Market
Aircraft and Aerospace Components
Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Solenoid Valves in Aerospace Market
Aircraft and Aerospace Components
Global Aircraft Nacelle and Thrust Reverser Market
Aircraft and Aerospace Components
Commercial Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Helicopter Blades Market
Aircraft and Aerospace Components
Aircraft Vertical Stabilizer Market
Aircraft and Aerospace Components
Composite Wing-to-Body Fairing Structures for Wide-Body Aircraft Market