
 Aircraft Propeller System Market | 2026-2036
Aircraft Propeller System Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Propeller System Market Intelligence
The EU Green Deal's emphasis on aviation efficiency and emissions reduction is shifting demand toward advanced composite propeller systems. Hartzell Propeller leverages its extensive portfolio in general aviation to maintain a significant market presence. MT-Propeller Entwicklung GmbH specializes in composite variable pitch propellers for a wide range of aircraft. Separately, Dowty Propellers leads in the development of complex, all-composite systems for large military and commercial turboprop applications.
An aircraft propeller system is a mechanical assembly that converts an engine's rotational power into aerodynamic thrust. This system typically includes a central hub, multiple blades with specific airfoil cross-sections, and a pitch control mechanism. Its primary commercial purpose is to propel piston-engine and turboprop aircraft. Variable pitch propellers command the largest market share due to their efficiency, while the material segment shows a clear transition from aluminum alloys toward carbon fiber reinforced polymers.
Product certification is governed by stringent airworthiness standards from regulators like the FAA in the United States, EASA in Europe, and national bodies such as Transport Canada. These organizations mandate rigorous ground and flight testing for new designs and materials before granting a Type Certificate. Future development hinges on certifying novel material combinations that can meet the demanding performance and safety requirements of next-generation aircraft platforms.
Market Dynamics
The central dynamic shaping the aircraft propeller system market is the regulatory pressure for decarbonization, particularly from the EU Green Deal. This is forcing a fundamental shift in material science and aerodynamic design, pushing manufacturers away from traditional aluminum alloys and toward lighter, more efficient composite structures to meet stringent emissions and noise standards.
Growth Catalysts
- UAV Expansion:The rapid expansion of the Unmanned Aerial Vehicle (UAV) sector for commercial and military applications creates substantial demand for specialized, lightweight, and highly reliable propeller systems tailored for electric and hybrid-electric propulsion.
- Flight Training Demand:Sustained demand for new pilots, concentrated in flight training schools across the United States and Brazil, supports a consistent order book for piston-engine aircraft, which are primary users of fixed-pitch and simple variable-pitch propellers.
- Sustainable Aviation Mandates:The EU Green Deal and similar global initiatives focused on sustainable aviation are accelerating research and development into advanced propeller designs that improve fuel efficiency and reduce the acoustic footprint of turboprop and piston aircraft.
Market Restraints
- High Certification Costs:The rigorous and expensive certification processes mandated by airworthiness authorities like the FAA and EASA for new materials and complex designs act as a significant barrier to entry and slow the pace of innovation.
- Composite Material Costs:The higher upfront cost of carbon fiber reinforced polymers and associated advanced manufacturing processes, compared to traditional aluminum alloys, constrains adoption in cost-sensitive segments of the general aviation market.
- Integration with Legacy Platforms:Technical challenges associated with retrofitting advanced, digitally controlled propeller systems onto older aircraft with legacy engine and cockpit architectures limit the addressable market for aftermarket upgrades.
Strategic Opportunities
- Urban Air Mobility (UAM):The emerging UAM and eVTOL aircraft markets present a significant opportunity for developing novel, ultra-quiet, and highly responsive distributed electric propulsion systems, creating an entirely new product category.
- Hybrid-Electric Propulsion:The convergence of advanced propeller aerodynamics with electric motor technology opens opportunities to develop integrated hybrid-electric propulsion units for regional aircraft, promising major gains in fuel efficiency and emissions reduction.
- Noise Reduction Incentives:Government incentives aimed at reducing airport community noise, particularly in Europe and North America, can create a premium market for propellers with advanced acoustic-damping designs and sophisticated blade geometries.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of engineers with combined expertise in composite materials science, advanced aerodynamics, and digital control systems hinders the development capacity of propeller manufacturers.
- Supply Chain Qualification:Transitioning from established metal alloy supply chains to new sources for high-grade carbon fiber and resins requires a lengthy and complex process of supplier qualification to meet stringent aerospace quality standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Propeller System Market |
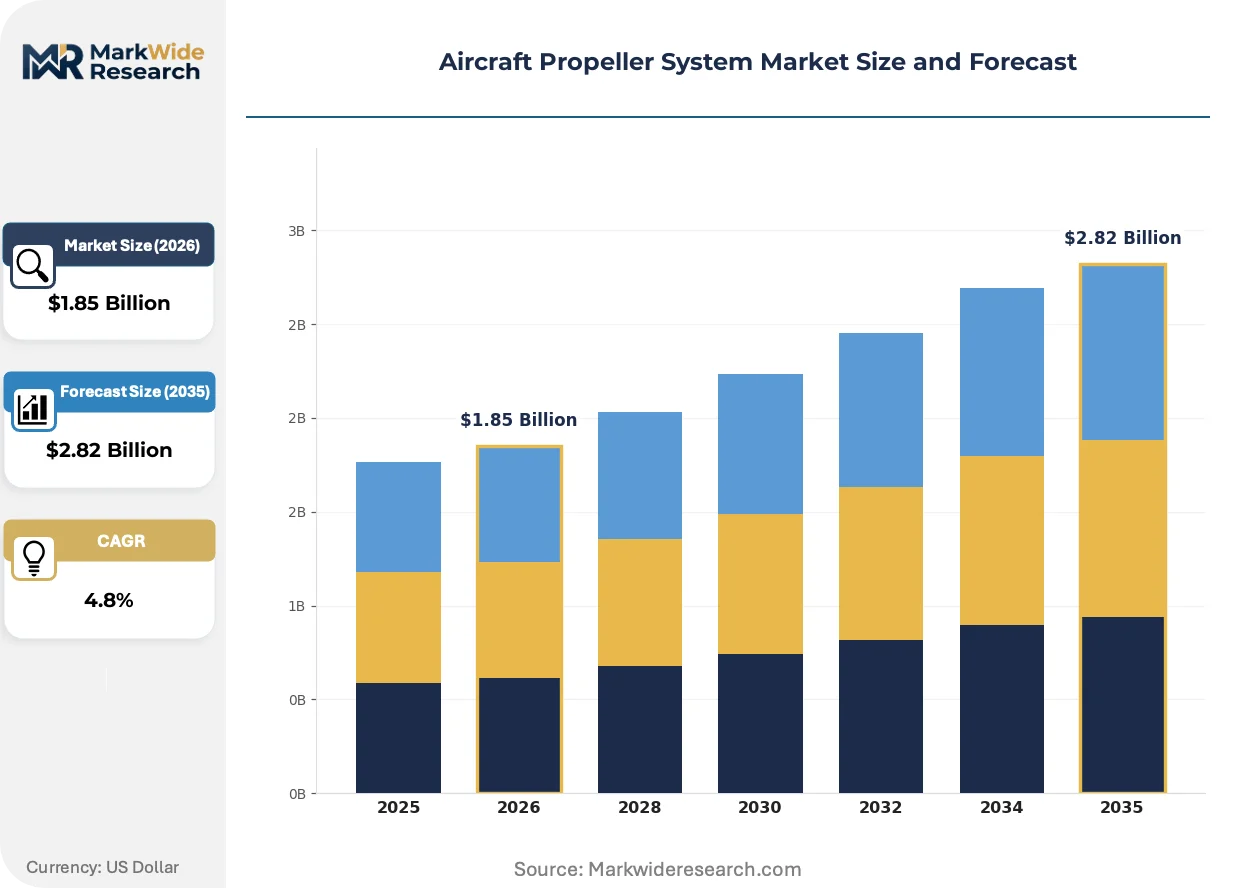
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.82 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Propeller Type: Fixed Pitch, Variable Pitch, Constant Speed, Controllable Pitch Material: Aluminum Alloy, Composite, Wood, Carbon Fiber Reinforced Polymer Application: General Aviation, Unmanned Aerial Vehicles, Seaplanes, Personal Air Transport End User: Commercial Airlines, Military Operators, Flight Training Schools, Charter Services |
| Companies Covered | Hartzell Propeller, MT-Propeller Entwicklung GmbH, Dowty Propellers, McCauley Propeller Systems, Airmaster Propellers, Sensenich Propeller Company, Aerosila, FP Propeller, Ratier-Figeac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Propeller System Market Strategic Shifts & Innovations
The convergence of material science advancements and digital design tools is fundamentally altering propeller system development. Manufacturers are moving beyond simple aerodynamic improvements, focusing instead on fully integrated systems that balance performance, weight, acoustic signature, and lifecycle cost under increasing regulatory scrutiny for environmental impact.
Digital twin technology creates a virtual replica of a physical propeller system, allowing for detailed simulation of aerodynamic performance, material fatigue, and acoustic properties. Military and commercial airline operators are the primary adopters, using it for predictive maintenance scheduling and optimizing flight operations. This technology is integrating with onboard health and usage monitoring systems (HUMS) to enable real-time performance adjustments and fault detection, reducing unscheduled maintenance events.
European Union Aviation Safety Agency (EASA) regulations on aircraft noise are becoming a primary design constraint for new propeller systems. This forces manufacturers to invest heavily in computational fluid dynamics and wind tunnel testing to create complex, scimitar-shaped blades and other geometries that minimize noise generation. The regional turboprop and general aviation sectors are most affected, responding with new product lines specifically marketed on their low-noise characteristics.
Aviation procurement patterns are evolving toward the acquisition of complete propulsion modules, which include the engine, propeller, and control systems from a single source. This model disrupts the traditional component-level sales channel, favoring partnerships between engine and propeller manufacturers who can deliver a pre-integrated, performance-optimized package. This trend is most pronounced in the development of new clean-sheet aircraft designs, including advanced air mobility platforms.
Aircraft Propeller System Market Segmentation
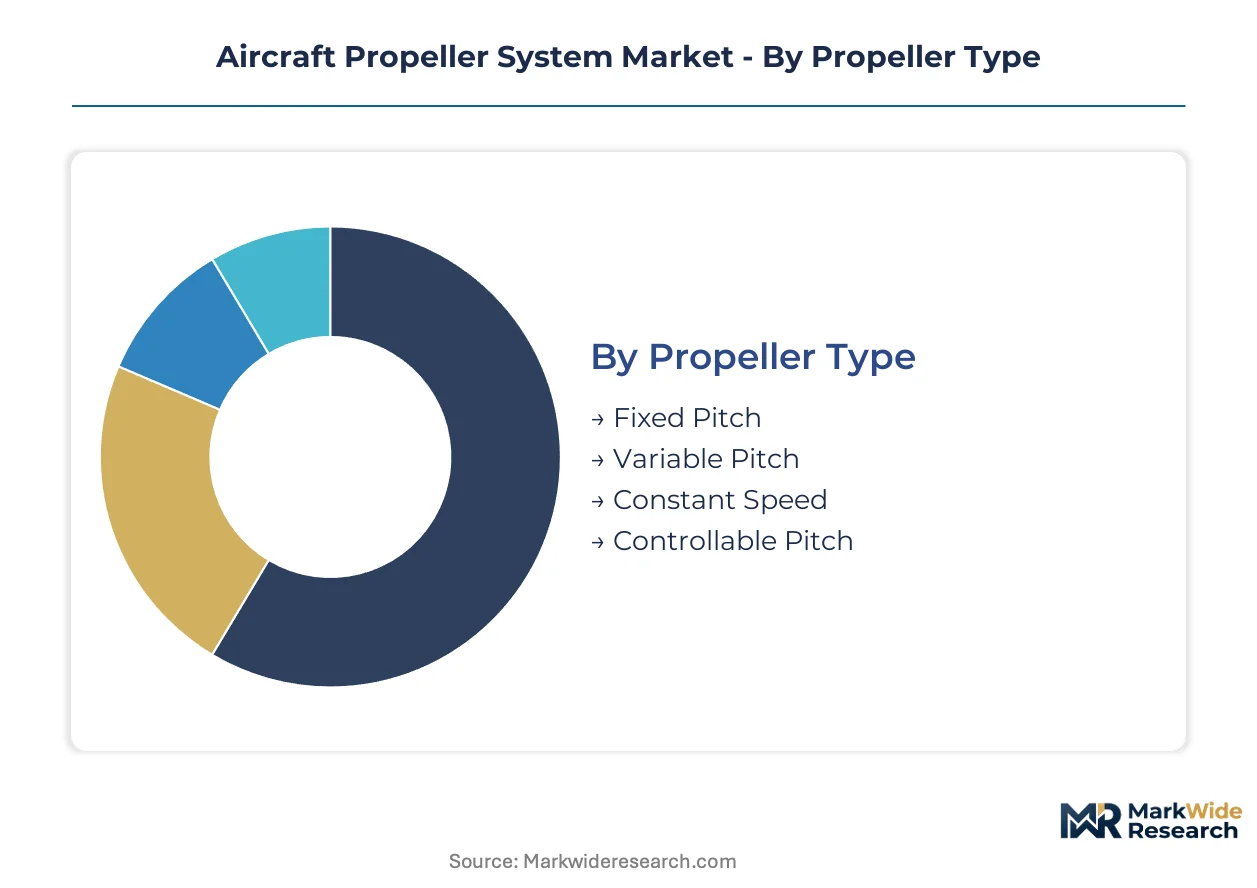
Market segmentation provides a granular view of the aircraft propeller system landscape, illuminating specialized requirements across diverse operational contexts. Understanding these distinct segments helps manufacturers tailor product development and strategic market penetration. Each category reveals unique demand drivers and technological preferences within the broader market.
Propeller Type:
This segment differentiates propeller systems by their integration depth, reflecting the complexity of their pitch control mechanisms and their embeddedness within the aircraft's propulsion architecture.
- Fixed Pitch:A propeller with blades permanently set at a fixed angle, offering simplicity and low cost for light aircraft operations. This type is prevalent in entry-level general aviation aircraft.
- Variable Pitch:Allows pilots to adjust blade angle during flight for optimal engine efficiency across different flight phases. This system commands the largest market share due to its efficiency benefits across various flight envelopes.
- Constant Speed:An advanced variable pitch system that automatically maintains a set engine RPM by adjusting blade angle. Demand for these systems is driven by turboprop aircraft seeking maximum fuel efficiency.
- Controllable Pitch:A propeller where the pilot manually adjusts blade pitch settings, providing more control than fixed pitch but less automation than constant speed.
Volume placements concentrate in Variable Pitch systems; the faster expansion belongs to Constant Speed designs.
Material:
Material choices within propeller systems define different cost tiers, influencing both manufacturing complexity and overall aircraft acquisition costs.
- Aluminum Alloy:Traditional material for propeller blades, offering a balance of strength, durability, and cost-effectiveness for general aviation. Regulatory bodies like the FAA have extensive certification for these alloys.
- Carbon Fiber Reinforced Polymer:Represents a specific, high-performance type of composite, offering superior strength-to-weight ratios and fatigue resistance. This material is crucial for next-generation turboprops and UAVs, driven by performance demands.
- Composite:Lighter and stronger than aluminum, these materials enable more complex blade geometries for improved aerodynamic efficiency and noise reduction. The EU Green Deal mandates drive demand for these advanced structures.
- Wood:Used primarily in older aircraft and niche applications, wood propellers offer good vibration damping and are cost-effective for specific light aircraft.
Pricing is differentiated by material processing complexity, while Carbon Fiber Reinforced Polymer offers the most performance for advanced applications.
Application:
Application segments are distinguished by their operational volume requirements, ranging from high-frequency commercial flights to specialized niche operations.
- General Aviation:Encompasses private aircraft, flight training, and small commercial operations, representing a consistent market for piston-engine and light turboprop propellers. Demand concentrates in the United States and Brazil.
- Unmanned Aerial Vehicles:Requires specialized, lightweight, and highly reliable propeller systems tailored for electric and hybrid-electric propulsion. The rapid expansion of this sector creates substantial demand for tailored solutions.
- Seaplanes:Demands propellers designed for amphibious operations, often requiring specialized coatings and robust construction to withstand water spray and corrosion.
- Personal Air Transport:Emerging market segment for small, often electric or hybrid-electric aircraft, requiring novel, ultra-quiet, and highly responsive propulsion systems for urban air mobility.
The largest installed base resides in General Aviation, with Unmanned Aerial Vehicles demonstrating the highest growth potential.
End User:
End user segments are characterized by distinct operational requirements and procurement patterns, reflecting their diverse mission profiles.
- Commercial Airlines:Primarily uses turboprop aircraft in regional fleets, requiring highly efficient and durable propeller systems certified by agencies like EASA. These operators focus on operational cost reduction.
- Military Operators:Demands robust, high-performance propeller systems capable of operating in extreme conditions and often integrated into complex turboprop platforms. Dowty Propellers leads in this segment.
- Flight Training Schools:A significant end-user for piston-engine aircraft, driving consistent demand for durable and cost-effective fixed-pitch and simple variable-pitch propellers. This segment is strong in the United States.
- Charter Services:Utilizes a mix of piston and turboprop aircraft, seeking reliable and efficient propeller systems to maximize operational uptime and passenger comfort.
Demand from Flight Training Schools drives consistent orders, while Military Operators seek specialized performance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The production and consumption dynamics for aircraft propeller systems exhibit a notable geographical split, with specialized manufacturing clusters concentrated in aviation-heavy nations while demand broadens across diverse global regions. This market structure reflects both established aerospace hubs and rapidly growing aviation sectors. Regulatory pressures for decarbonization also influence regional market development.
United States
Demand for aircraft propeller systems in the United States stems from robust flight training activities and the expanding Unmanned Aerial Vehicle (UAV) sector. FAA airworthiness standards rigorously govern new product certification and material qualifications for aviation components. The Wichita, Kansas, aerospace cluster continues to drive significant manufacturing and innovation for general aviation propellers.
Germany
Germany's demand for advanced propeller systems is influenced by the EU Green Deal's emphasis on sustainable aviation and the strong turboprop aircraft segment. EASA regulations push for quieter, more efficient designs, favoring advanced composite materials. The Bavaria region serves as a hub for aerospace research and development, supporting specialized propeller manufacturers.
Brazil
Brazil experiences consistent demand for piston-engine aircraft propellers, primarily from its active flight training schools and general aviation sector. The national aviation authority, ANAC, ensures compliance with airworthiness directives for all aircraft components. São José dos Campos remains a significant aerospace cluster, fostering both manufacturing and maintenance capabilities for aviation systems.
China
China's market for aircraft propeller systems is rapidly expanding, fueled by the substantial growth of its UAV industry and emerging regional commercial aviation. The Civil Aviation Administration of China (CAAC) sets stringent certification requirements for both domestic and imported systems. Xi'an, with its established aerospace manufacturing base, is a key center for propeller production and development.
France
France demonstrates strong demand for sophisticated propeller systems within its aerospace sector, particularly for military and commercial turboprop applications. European Union Aviation Safety Agency (EASA) mandates drive manufacturers towards advanced aerodynamic designs and noise reduction technologies. Toulouse, a major European aerospace hub, hosts significant research and manufacturing facilities for propulsion components.
Aircraft Propeller System Market Key Industry Players
The competitive structure tilts toward specialized manufacturers and established general aviation suppliers rather than broad, integrated conglomerates. This market features a mix of long-standing players with extensive product portfolios and niche innovators focusing on advanced materials. Strategic partnerships between engine and propeller manufacturers are becoming prevalent, especially for new clean-sheet aircraft designs. Technology licensing agreements also facilitate the adoption of advanced composite blade geometries.
Specialized manufacturers like MT-Propeller Entwicklung GmbH, a German entity, exemplify the focus on advanced composite variable pitch propellers for a diverse range of aircraft. Hartzell Propeller, with its extensive portfolio, represents the legacy general aviation suppliers maintaining a significant market presence across the United States and international markets. Dowty Propellers, a UK-based entity, anchors the segment for complex, all-composite systems catering to large military and commercial turboprop applications. These companies strategically position themselves by addressing specific performance and material requirements, from piston-engine efficiency to turboprop noise reduction.
| Leading Market Players |
|---|
| Hartzell Propeller |
| MT-Propeller Entwicklung GmbH |
| Dowty Propellers |
| McCauley Propeller Systems |
| Airmaster Propellers |
| Sensenich Propeller Company |
| Aerosila |
| FP Propeller |
| Ratier-Figeac |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's stringent emissions targets gate both qualified supply chains for advanced materials and access to premium-tier pricing for compliant propeller systems. This mandate drives investment in certified composite solutions.
Pricing Analysis
Propeller system pricing anchors to operational efficiency and acoustic performance, directly impacting aircraft fuel burn and regulatory compliance. The dominant pricing model is per-unit transactional, with price differentiation driven by certification level (FAA, EASA) and the complexity of composite materials. Pricing softness stems from general aviation's cost sensitivity, particularly for fixed-pitch models. Flight training schools represent the most price-sensitive buyers, while military operators prioritize performance over cost.
Supply Chain Analysis
National procurement mandates in countries like the United States and France are reshaping sourcing for critical propeller components. Supply concentrates in aerospace manufacturing hubs such as Wichita, Kansas, and Toulouse, France, drawing from specialized carbon fiber and resin suppliers globally. Single-source vulnerability for certified composite prepregs presents a structural risk. Distribution runs through direct sales channels to OEMs and a network of MRO providers for aftermarket support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
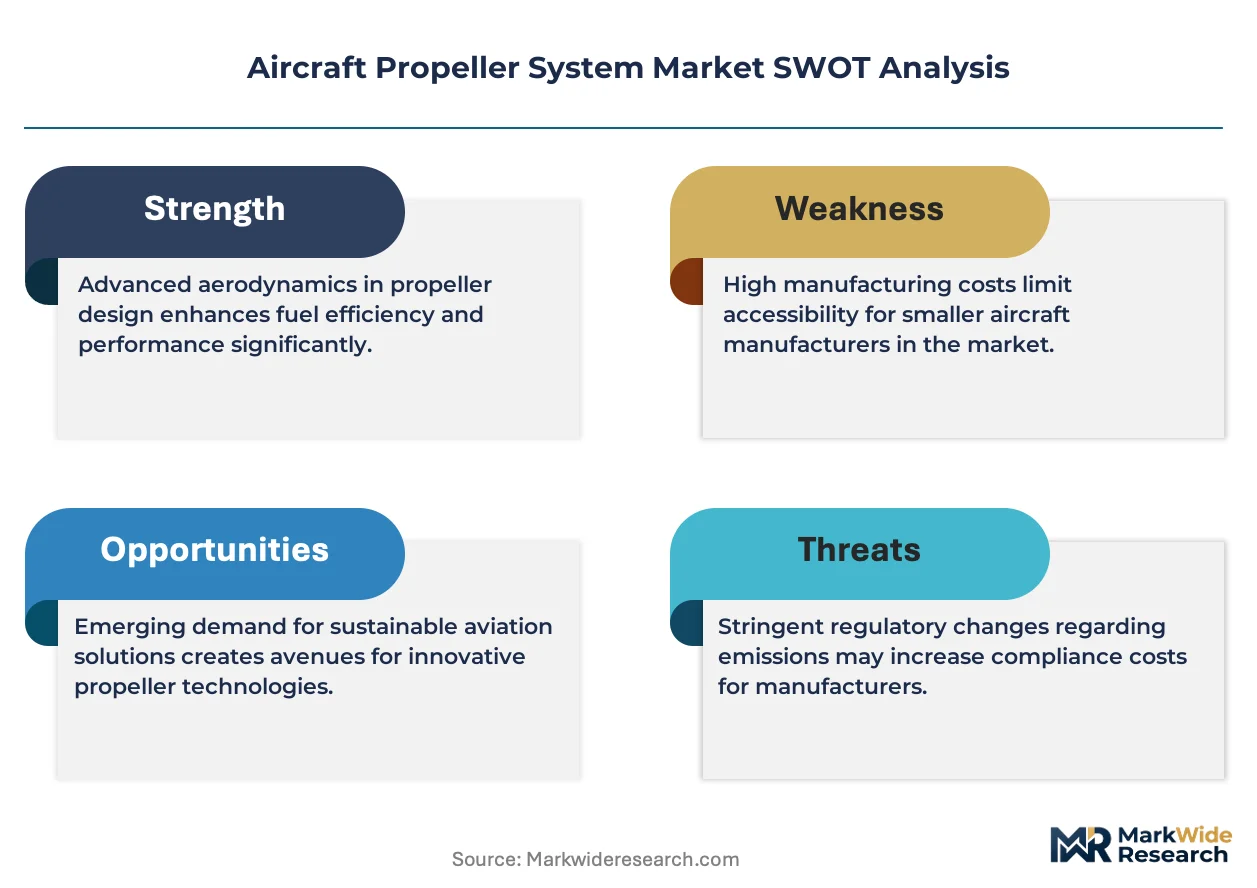
This market is undergoing a vertical-integration race, with manufacturers pursuing deeper control over advanced material processing to secure competitive advantages. This strategic move aims to optimize performance and reduce costs.
For Market Incumbents:Acquire specialized composite manufacturing capabilities to internalize advanced material production and mitigate supply chain risks. Consolidate market share through strategic partnerships with turboprop engine manufacturers, countering the threat from integrated electric propulsion systems. Invest in advanced acoustic design R&D to meet evolving EASA noise regulations, securing long-term product relevance.
For New Entrants and Emerging Players:Price-point gaps exist in the rapidly expanding Unmanned Aerial Vehicle (UAV) and Personal Air Transport segments, which require specialized, lightweight, and cost-effective propellers. Target the electric and hybrid-electric propulsion market with novel, ultra-quiet designs. A direct-to-OEM go-to-market angle focusing on performance and customization can establish early partnerships.
For Investors and Strategic Acquirers:EASA Type Certification of new composite propeller systems is the leading indicator that validates advanced material science and design for long-term viability. Focus on mid-cap specialists with strong intellectual property in digital twin technology and advanced aerodynamics. These firms offer compelling acquisition targets for expanding portfolios beyond the next decade.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Digital Twin Technology | Enables predictive maintenance and performance optimization for commercial airline operators. |
| Develop Integrated Propulsion Modules | Fosters partnerships with engine manufacturers for clean-sheet aircraft designs. |
| Expand Composite Manufacturing Capacity | Addresses rising demand for lightweight, efficient propellers in turboprop and UAV sectors. |
| Pursue Advanced Noise Reduction Designs | Meets stringent EASA regulations and creates premium products for regional aviation. |
| Secure Long-Term Material Supply Contracts | Mitigates commodity price volatility and ensures consistent production for key components. |
Research Approach
Independent corroboration across industry reports, aerospace regulatory filings, and academic research underwrites the qualitative findings within this study. Primary interviews involved propeller design engineers, MRO facility managers, and procurement specialists from general aviation and military operators. This insight was cross-referenced with secondary data from FAA and EASA airworthiness directives. Bottom-up market sizing was then triangulated with top-down validation.
The forecast window was anchored to comparable historical periods, establishing a baseline for future projections across the analysis window. The analytical framework modeled segmentation dimensions including propeller type, material, application, end-user, and regional regulatory clusters. Compound Annual Growth Rates (CAGRs) were derived from projected shifts in demand and technological advancements. Key forecast inputs included UAV expansion rates and composite material adoption.
Inputs from certified propeller manufacturers and airworthiness authorities were available through the study window; gaps in emerging market data introduce uncertainty bands. Forecasts reflect assumptions concerning regulatory stability and technological progress, though geopolitical instability or material supply disruptions could revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Aircraft Circuit Breakers Market
Aircraft Power Systems
Aircraft Hydraulic Seat Actuation Systems Market
Aircraft Power Systems
Aircraft Battery Market
Aircraft Power Systems
Aircraft Turboprop Propeller System Market
Aircraft Power Systems
Aircraft Propulsion System Market
Aircraft Power Systems
Space Power System Hardware-in-the-Loop Test Platforms Market
Aircraft Power Systems
Aerospace and Military Auxiliary Power Unit (APU) Market
Aircraft Power Systems
Aircraft Actuator Market
Aircraft Power Systems
Commercial Aircraft Propeller Systems Market
Aircraft Power Systems
Commercial Aviation Electrical Wiring Interconnection System (EWIS) Market
Aircraft Power Systems
Aircraft Turbocharger Market
Aircraft Power Systems
Military Aircraft Actuation System Market
Aircraft Power Systems
Aircraft Generators Market
Aircraft Power Systems
Aircraft Thrust Reverser Actuation Systems Market
Aircraft Power Systems
Aerospace Electrical Inserts Market
Aircraft Power Systems
More Electric Aircraft Market