
 Autonomous Aircraft Propulsion Systems Market | 2026-2036
Autonomous Aircraft Propulsion Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Aircraft Propulsion Systems Market Analysis
Aftermarket service revenue for legacy propulsion overhaul is fragmenting as fleet operators redirect maintenance budgets toward autonomous electric architectures. Boeing anchors this transition through in-house production of integrated electric propulsion units for unmanned platforms. Lockheed Martin Corporation leverages its Skunk Works division to sustain classified R&D programs on hybrid-electric propulsion for next-generation autonomous systems. RTX Corporation competes across the supply chain with specialized thermal management solutions that address high-discharge battery requirements.
Autonomous aircraft propulsion systems encompass electric motors, hybrid architectures, and fuel cell assemblies engineered to deliver thrust without direct human control inputs, typically operating at power densities exceeding 5 kW/kg for urban air mobility applications. These systems integrate autonomous control algorithms with battery management systems to enable real-time thrust modulation during GPS-denied navigation scenarios. Electric motors and hybrid systems currently occupy distinct margin pools, with the former capturing volume in short-range commercial aviation and the latter commanding premium positioning in extended-range military platforms. AI Navigation and Autonomous Control technologies are accelerating fastest within the technology segment as certifying authorities demand redundant decision-making pathways for uncrewed flight operations.
The FAA's powered-lift SFAR and EASA's special condition frameworks for VTOL certification are reshaping product standards, forcing manufacturers to demonstrate autonomous fault detection across propulsion chains before market entry. China's MIIT dual carbon goals and NMPA airworthiness directives are similarly constraining fossil-fuel-dependent architectures while channeling state support toward hydrogen fuel cell propulsion development. Stakeholders must monitor divergence between FAA and EASA autonomy certification timelines, as asynchronous approvals will fragment addressable markets and strand development investments in non-compliant architectures.
Market Dynamics
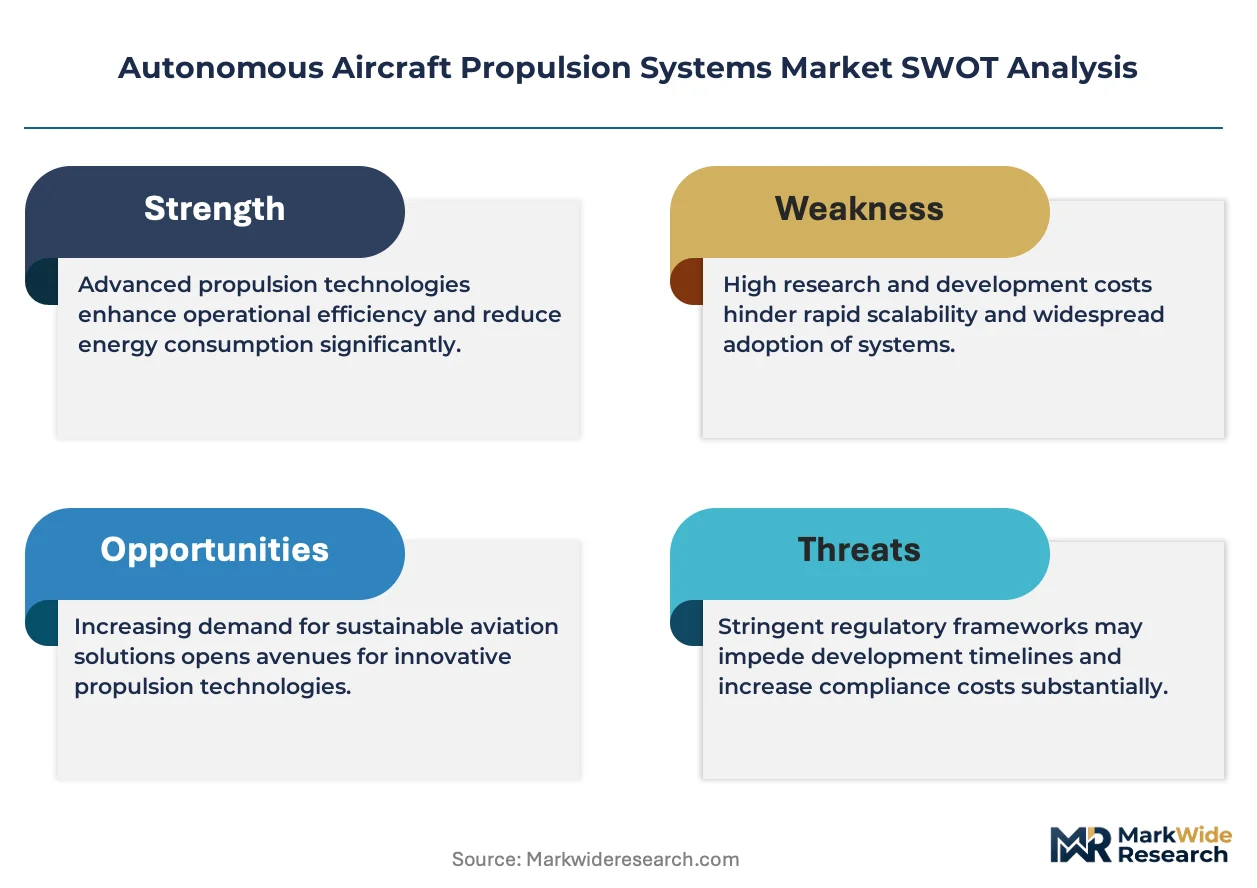
The FAA's Special Federal Aviation Regulation for powered-lift aircraft is compressing certification timelines while fragmenting development budgets between electric and hybrid architectures. This regulatory acceleration forces manufacturers to demonstrate autonomous fault detection across propulsion chains before commercial entry, creating a structural bottleneck that favors vertically integrated producers with captive testing infrastructure.
Growth Catalysts
- Urban Air Mobility Demand:California and Texas aerospace clusters are absorbing expanded orders for electric vertical take-off and landing platforms, concentrating manufacturing investment in these coastal and southwestern production zones.
- SFAR Certification Pathway:The FAA's powered-lift framework accelerates type certification for autonomous propulsion systems, reducing time-to-market for compliant architectures against legacy manned-aircraft standards.
- Dual Carbon Mandates:China's MIIT dual carbon goals channel state support toward hydrogen fuel cell propulsion development, constraining fossil-fuel-dependent architectures in the world's second-largest aviation market.
Market Restraints
- High-Discharge Battery Supply Concentration:Lithium-nickel-manganese-cobalt cathode supply concentrates in East Asian processing facilities, exposing Western propulsion manufacturers to raw material bottlenecks and geopolitical friction.
- Power Density Ceiling:Current solid-state battery architectures fail to achieve the 5 kW/kg threshold required for extended-range military platforms, forcing continued reliance on hybrid-electric systems with higher thermal management complexity.
- Asynchronous Certification Timelines:Divergence between FAA and EASA autonomy approval schedules fragments addressable markets and strands development investments in architectures compliant with only one regulatory jurisdiction.
Strategic Opportunities
- GPS-Denied Navigation:AI Navigation and Autonomous Control technologies represent white space for redundant decision-making pathways in uncrewed flight operations, particularly for defense applications requiring jam-resistant propulsion modulation.
- EASA Special Condition Alignment:Early harmonization with EASA's VTOL certification frameworks enables first-mover positioning in European urban air mobility corridors before competitors complete dual-approval strategies.
- Thermal Management Convergence:Integration of specialized cooling systems with battery management platforms creates bundled solution opportunities for high-discharge applications in commercial and military segments.
Industry Challenges
- Autonomous Control Algorithm Talent Scarcity:The intersection of aerospace propulsion engineering and machine learning expertise remains underdeveloped, forcing manufacturers to poach from autonomous ground vehicle programs or build training pipelines.
- Legacy Fleet Maintenance Budget Reallocation:Operators redirecting overhaul spending toward autonomous electric architectures fragment aftermarket service revenue, stranding specialized MRO providers dependent on turbine engine service contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Aircraft Propulsion Systems Market |
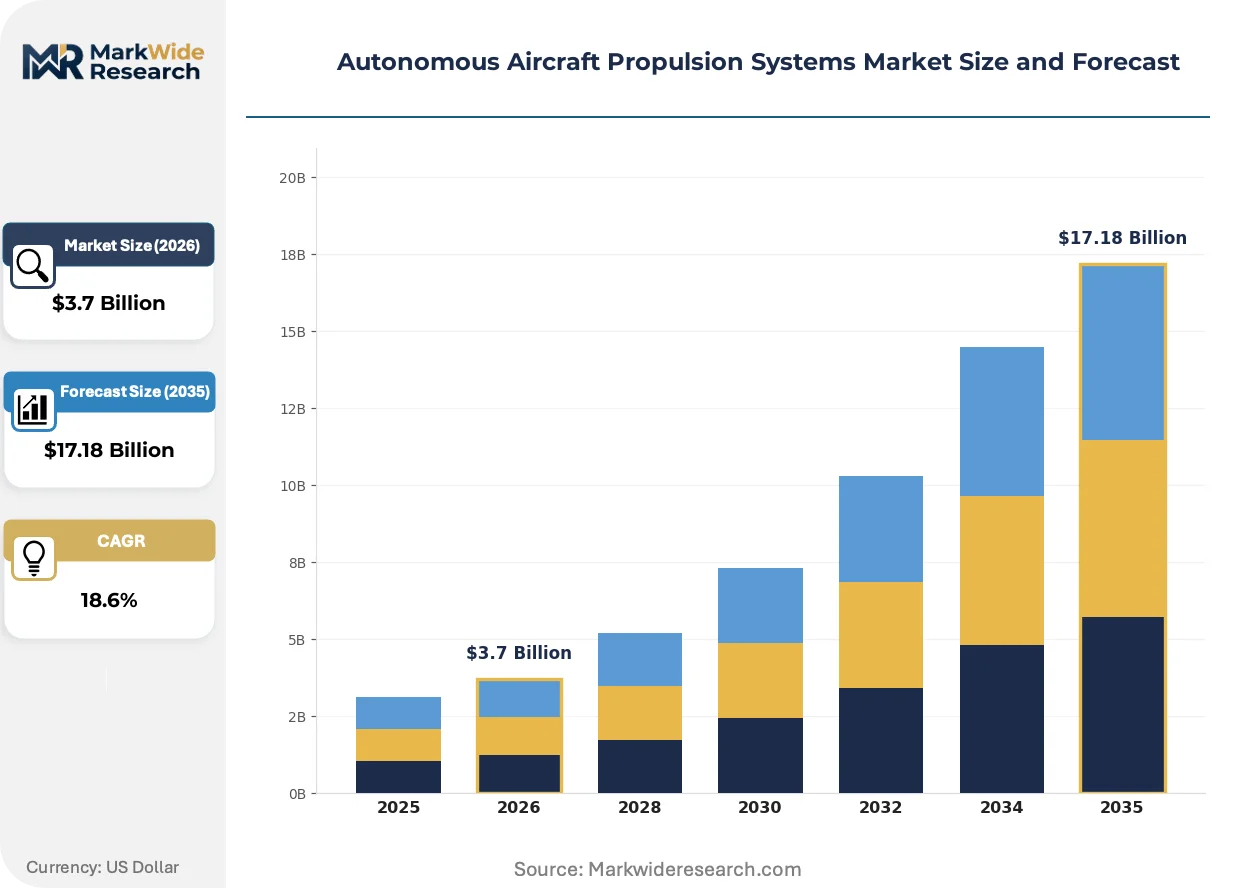
| Market Size in 2026 | $3.7 Billion |
| Market Size in 2035 | $17.18 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Motors, Jet Engines, Hybrid Systems, Turboprops Technology: AI Navigation, Battery Management Systems, Fuel Cells, Autonomous Control End User: Commercial Aviation, Military Use, Cargo Transport, Research Institutions Installation: Retrofit, OEM Integration, Ground Testing, In-Flight Trials |
| Companies Covered | Boeing, Lockheed Martin Corporation, Northrop Grumman Corporation, Airbus, BAE Systems, Textron, RTX Corporation, Saab AB, Elbit Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Aircraft Propulsion Systems Market Emerging Trajectories
Digital twin architectures are virtualizing propulsion system development cycles, compressing physical prototype requirements while accelerating fault-scenario testing. This simulation-first approach reshapes R&D expenditure allocation and supplier qualification timelines.
Solid-state battery chemistries with silicon-anode configurations are virtualizing energy density assumptions that have constrained electric propulsion range envelopes for a decade. Urban air mobility developers in California are adopting these architectures at pilot scale ahead of military platform integrators, compressing the traditional defense-to-commercial technology transfer sequence.
EASA's special condition frameworks for VTOL certification are mandating redundant autonomous fault detection across propulsion chains before market entry. This regulatory stringency forces manufacturers to redesign control system architectures for European compliance, creating product variants that diverge from FAA-optimized designs and complicating global fleet standardization.
Defense procurement offices are unbundling propulsion system acquisition from platform integrator contracts, creating direct purchasing relationships with specialized electric motor and thermal management suppliers. This channel disintermediation concentrates in United States Department of Defense programs, where classified performance requirements demand supplier-level security clearances that platform primes cannot efficiently intermediate.
Autonomous Aircraft Propulsion Systems Market Segmentation
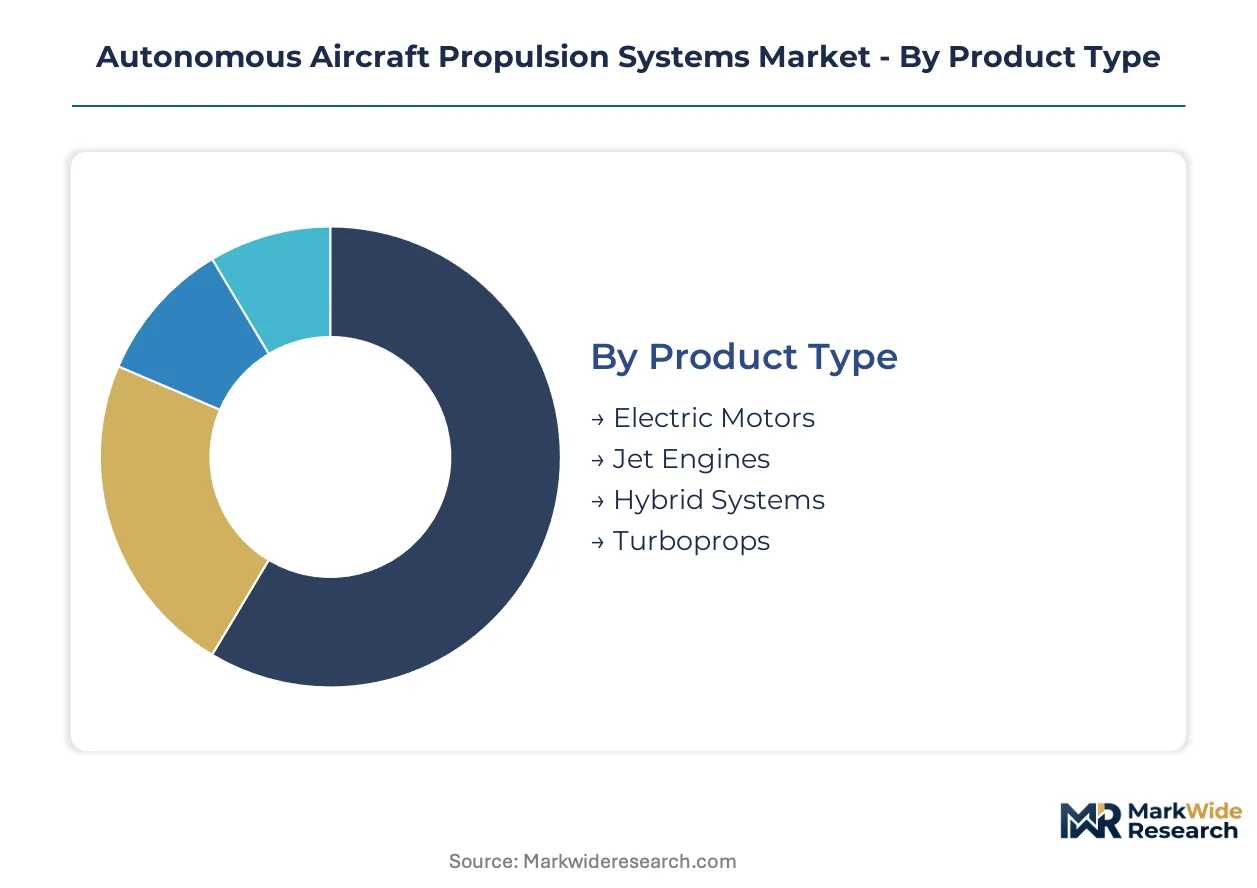
Segmentation in autonomous aircraft propulsion reveals divergent margin structures across electric and hybrid architectures. After-sales service intensity varies sharply between retrofit installations requiring ongoing calibration support and OEM-integrated systems with embedded predictive maintenance. Understanding these segment boundaries enables targeted resource allocation across development, certification, and fleet support functions.
Product Type:
After-sales service intensity runs highest for hybrid systems demanding integrated thermal management oversight across dual power paths.
- Electric Motors:Permanent magnet synchronous and axial flux architectures deliver power densities exceeding 5 kW/kg for urban air mobility platforms. Demand concentrates in California aerospace clusters where eVTOL developers prioritize compact, scalable motor configurations for multi-rotor designs.
- Hybrid Systems:Series-parallel architectures combine turbine generators with battery buffers to extend range beyond pure-electric limitations. Military procurement offices in the United States favor these configurations for uncrewed combat air vehicles requiring sustained loiter capability.
- Jet Engines:Micro-turbine derivatives adapted for autonomous throttle modulation serve extended-range cargo applications.
- Turboprops:Modified regional turbofans with autonomous fuel control systems address medium-haul autonomous freight routes.
Electric motors hold the largest share; momentum sits with hybrid systems as defense requirements outpace commercial range limitations.
Technology:
Cost tier stratification separates commodity battery management components from premium autonomous control algorithms requiring specialized aerospace-software engineering talent.
- Autonomous Control:Redundant flight control computers execute thrust commands without human intervention through deterministic real-time operating systems. FAA certification timelines for powered-lift SFAR compliance drive investment in fault-tolerant architectures with triple-modular redundancy.
- AI Navigation:Machine learning inference engines process sensor fusion inputs for GPS-denied trajectory planning in contested electromagnetic environments. Defense applications in the United States absorb early production volumes before commercial urban air mobility adoption.
- Battery Management Systems:Cell balancing and thermal runaway prevention electronics protect high-discharge lithium-ion packs.
- Fuel Cells:Proton-exchange membrane stacks convert hydrogen to electricity for zero-emission extended-range platforms.
Autonomous control commands premium pricing; AI navigation is expanding most quickly as jam-resistant requirements proliferate across defense portfolios.
End User:
Application maturity separates established military test programs from emerging commercial certification pathways with divergent risk tolerances.
- Military Use:Classified programs through Skunk Works and comparable divisions demand propulsion systems with hardened electronics against electromagnetic pulse threats. The United States Department of Defense unbundles propulsion acquisition from platform primes, creating direct supplier relationships requiring security clearances.
- Commercial Aviation:Urban air mobility operators in Texas and California place volume orders for electric vertical take-off and landing platforms. FAA SFAR certification acceleration reduces time-to-market against legacy manned-aircraft standards.
- Cargo Transport:Autonomous freight operators pilot middle-mile drone networks with payload-optimized propulsion configurations.
- Research Institutions:University and government laboratory programs validate novel propulsion chemistries before commercial scaling.
Military use dominates current revenue; commercial aviation shows steepest expansion trajectory as certification barriers lower.
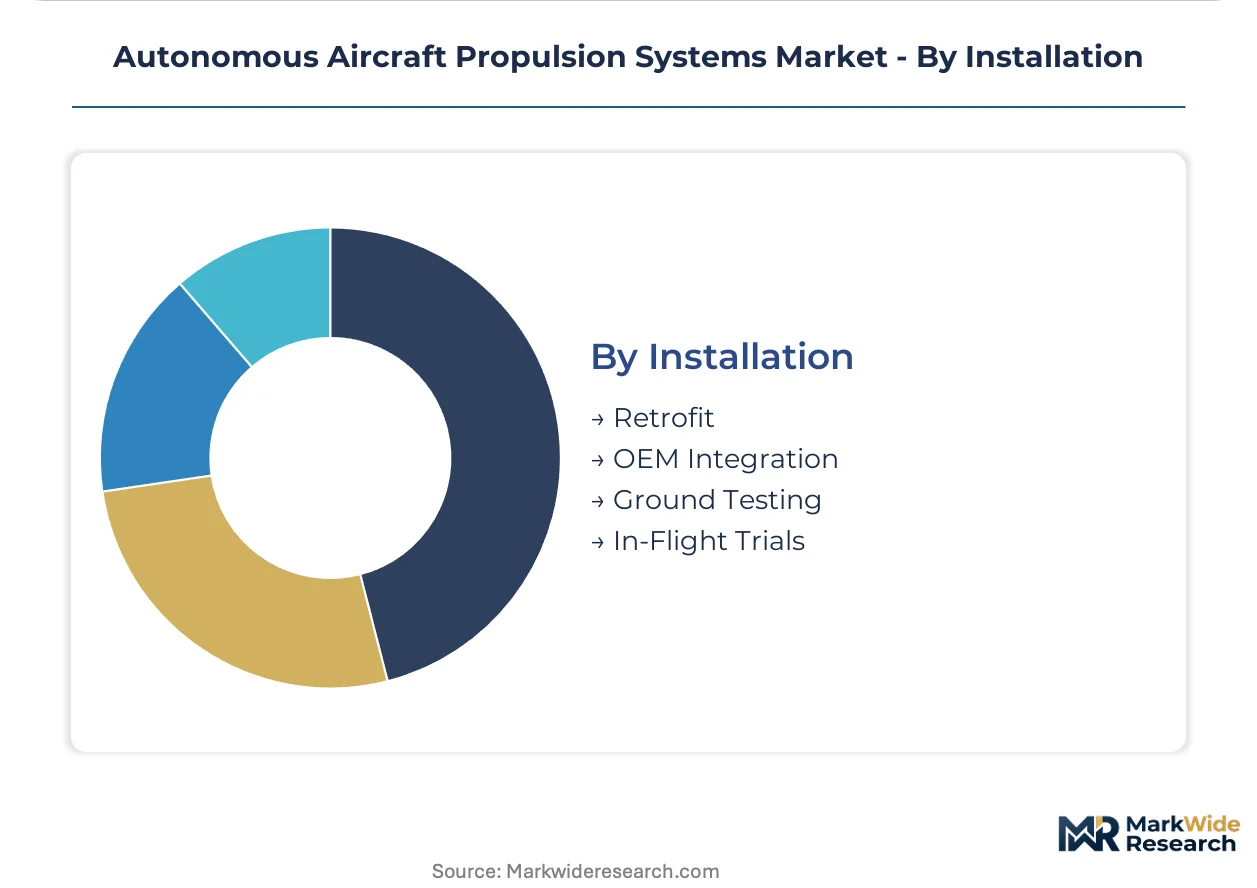
Installation:
Customer type bifurcation separates fleet operators managing legacy conversions from airframers integrating propulsion at the design stage.
- OEM Integration:Airframe manufacturers embed propulsion systems during initial assembly with unified thermal management and control electronics. Boeing's in-house electric propulsion production exemplifies captive integration strategies for unmanned platforms.
- Retrofit:Existing airframe modification programs convert manned or remotely piloted vehicles to autonomous operation. Operators redirect legacy maintenance budgets toward these electric architecture transitions, fragmenting traditional turbine overhaul revenue.
- Ground Testing:Static test cell validation precedes flight certification for all autonomous propulsion variants.
- In-Flight Trials:Experimental operating certificates enable envelope expansion testing under restricted airspace clearances.
OEM integration captures margin concentration; retrofit programs are gaining share fastest as fleet operators accelerate sustainability transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with military procurement dominating United States demand while commercial urban air mobility concentrates in China and European certification corridors. Regulatory frameworks in each jurisdiction are shaping distinct propulsion architecture preferences.
United States
Defense procurement offices unbundle propulsion acquisition from platform primes, creating direct supplier relationships for uncrewed combat air vehicles. The FAA's powered-lift SFAR accelerates type certification timelines for autonomous electric architectures. California and Texas aerospace clusters absorb expanded eVTOL manufacturing investment, with Skunk Works divisions in California sustaining classified hybrid-electric R&D programs.
China
MIIT dual carbon goals channel state support toward hydrogen fuel cell propulsion development while constraining fossil-fuel-dependent architectures. NMPA airworthiness directives establish certification pathways for autonomous VTOL platforms in the world's second-largest aviation market. Yangtze River Delta manufacturing hubs concentrate battery management system production for domestic eVTOL developers.
Germany
EASA special condition frameworks for VTOL certification mandate redundant autonomous fault detection across propulsion chains. German automotive suppliers leverage thermal management expertise to enter aircraft battery cooling markets. Bavaria's aerospace engineering clusters host testing infrastructure for European urban air mobility corridor development.
United Kingdom
BAE Systems anchors defense-oriented autonomous propulsion demand through classified uncrewed platform programs. The UK Civil Aviation Authority aligns with EASA timelines for VTOL certification, reducing regulatory friction for dual-approval strategies. Southwest England manufacturing zones concentrate on micro-turbine derivatives for extended-range cargo applications.
Israel
Elbit Systems drives demand for GPS-denied navigation capabilities in contested electromagnetic environments. Israeli defense procurement prioritizes jam-resistant propulsion modulation for autonomous surveillance platforms. Tel Aviv metropolitan engineering clusters specialize in AI navigation software for uncrewed flight operations.
Autonomous Aircraft Propulsion Systems Market Vendor Landscape
Capability concentration sits with defense-integrated primes possessing captive testing infrastructure; scale advantage sits with commercial aerospace conglomerates with multi-platform certification experience. The vendor base separates into three tiers: vertically integrated primes controlling end-to-end propulsion production, specialized thermal management suppliers addressing high-discharge battery requirements, and emerging eVTOL-native electric motor developers. Dominant competitive moves include strategic partnerships between airframers and battery chemistry specialists, plus backward integration into electric motor production.
Within the defense-integrated tier, Boeing and Lockheed Martin Corporation exemplify captive propulsion development strategies for unmanned platforms. RTX Corporation occupies a position among specialized suppliers addressing thermal management convergence opportunities. These three entities represent distinct archetypes: the prime with in-house electric propulsion production, the classified R&D program sponsor, and the supply-chain thermal specialist.
| Leading Market Players |
|---|
| Boeing |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Airbus |
| BAE Systems |
| Textron |
| RTX Corporation |
| Saab AB |
| Elbit Systems |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta battery processing clusters anchor global lithium-nickel-manganese-cob cathode capacity, translating raw material bottlenecks into asymmetric pricing power for East Asian suppliers serving Western propulsion manufacturers. Cost pass-through mechanics concentrate in high-discharge cell contracts, where spot lithium carbonate volatility feeds directly into electric motor system quotations.
Pricing Analysis
Long-term offtake contracts dominate procurement between eVTOL developers and battery management system suppliers, insulating California aerospace clusters from spot mineral volatility while locking in volume commitments across 18-36 month horizons. Price differentiation separates FAA-certified fault-tolerant architectures from experimental-grade components lacking redundant control pathways. Cost compression in commercial electric motor tiers intensifies as Chinese producers scale axial flux manufacturing for urban air mobility platforms. Military procurement offices show lowest price sensitivity, absorbing premium positioning for electromagnetic-hardened hybrid systems.
Supply Chain Analysis
Export control regimes under US International Traffic in Arms Regulations and EU dual-use technology frameworks restrict autonomous control algorithm transfers, fragmenting supplier relationships across jurisdictional boundaries. Manufacturing concentration spans China, South Korea, and Japan for solid-state electrolyte precursors and silicon-anode substrates. Western propulsion developers draw from Taiwanese semiconductor foundries for real-time flight control processors. Single-source vulnerability concentrates in rare-earth permanent magnet supply, with neodymium-dysprosium processing tethered to Chinese state-owned refineries. Distribution runs through defense procurement channels requiring security clearances and commercial aerospace tier-one supplier networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent propulsion manufacturers face substitution pressure from hydrogen fuel cell architectures favored under China's MIIT dual carbon mandates, requiring defensive repositioning before state-backed competitors capture extended-range platform contracts.
For Market Incumbents: Pre-empt hydrogen fuel cell encroachment by accelerating hybrid-electric certification timelines under FAA powered-lift SFAR pathways. Lock in long-term offtake agreements with Yangtze River Delta cathode processors before export licensing tightens. Vertical integration into thermal management subsystems defends margin pools against specialized suppliers like RTX Corporation. For New Entrants and Emerging Players: Build out GPS-denied navigation software stacks for defense applications, where jam-resistant propulsion modulation commands premium positioning absent in commercial urban air mobility. Target Israeli and German engineering clusters for AI navigation talent acquisition. Pursue direct supplier relationships with US Department of Defense procurement offices unbundling propulsion from platform primes. For Investors and Strategic Acquirers: Long-term, this sits as a defense-technology convergence play because autonomous control algorithms for contested electromagnetic environments transfer across uncrewed surface, subsurface, and aerial platforms. Acquisition targets should combine aerospace propulsion engineering with machine learning inference capabilities. Monitor EASA-FAA certification timeline divergence as inflection signal for stranded architecture risk.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Positioning | Early FAA powered-lift SFAR compliance accelerates type approval against asynchronous EASA timelines. |
| Dual-Use Technology Licensing | Autonomous control algorithm exports to allied defense programs navigate ITAR restriction complexity. |
| Thermal Management Integration | Bundled battery cooling solutions capture margin from high-discharge commercial and military applications. |
| Hydrogen Fuel Cell Pivot | Proton-exchange membrane development aligns with China's MIIT dual carbon state support channels. |
| Talent Pipeline Construction | Machine learning propulsion engineering programs reduce poaching costs from autonomous ground vehicle competitors. |
Methodological Framework
A standing panel of eVTOL program directors, FAA certification engineers, defense procurement officers, and battery management system technical leads provided ongoing calibration against secondary validation from FAA SFAR docket filings, EASA special condition frameworks, MIIT policy circulars, and SEC 10-K aerospace segment disclosures. Bottom-up triangulation across electric motor shipment data and top-down reconciliation against urban air mobility fleet announcements anchored volume estimates.
Scenario-bracketing framed conservative, baseline, and accelerated adoption pathways across the projection horizon, with segmentation dimensions spanning propulsion architecture type, autonomy technology tier, end-use application maturity, and regional regulatory cluster. CAGRs derived from installed base growth rates and replacement cycle assumptions, incorporating solid-state battery energy density roadmaps and hydrogen fuel cell stack cost curves as technology-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed Chinese eVTOL platforms or accelerated EASA-FAA harmonization would shift outcomes. Material shifts in export control regime stringency or rare-earth processing concentration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Global Helicopter Market
Aircraft
Aircraft Leasing and Rental Market
Aircraft
Fixed Wing Turbine Aircraft Market
Aircraft
North America Business Jet Market
Aircraft
North America General Aviation Market
Aircraft
Europe Fighter Aircraft Market
Aircraft
Japan Aviation Market
Aircraft
Global Business Aircraft Market
Aircraft
Aircraft Container & Pallet Loader Market
Aircraft
Southeast Asia Aviation Market
Aircraft
Electric Aircraft Market
Aircraft
Global Aircraft Transparencies Market
Aircraft
Strategic Bomber Market
Aircraft
US Military Aviation Market
Aircraft
Aircraft Autopilot System Market
Aircraft
Global Aircraft Tugs Market