
 Motherboard Battery Market | 2026-2036
Motherboard Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Motherboard Battery Market Insights
The EU Battery Directive is repositioning procurement standards across European electronics supply chains. Panasonic Holdings Corp leverages its vertical integration in lithium cell production to sustain cost advantages in OEM supply agreements. Murata Manufacturing anchors its position through ceramic-sealed battery architectures that dominate industrial motherboard applications. Maxell competes on long-cycle reliability metrics that appeal to server and medical device builders.
A motherboard battery is a compact electrochemical cell, typically a coin-type lithium manganese dioxide unit rated at 3 volts, that maintains CMOS memory, real-time clock functions, and BIOS settings when main power is disconnected. Lithium-Ion battery types command the largest volume share due to superior energy density and shelf stability in compact form factors. Smart Battery technology is gaining traction fastest among enterprise server OEMs seeking predictive failure monitoring and remote asset management capabilities. OEM end users represent the most concentrated margin pool, as direct supply contracts with motherboard manufacturers reduce channel fragmentation and support multi-year qualification cycles.
The EPA governs lithium battery disposal and recycling thresholds in the United States, while REACH restricts hazardous substance content in batteries sold across European Union member states. Japan's METI enforces voluntary safety standards that many Asian exporters adopt as de facto benchmarks for regional trade compliance. Stakeholders should monitor how evolving extended producer responsibility frameworks reshape cost structures and supplier qualification requirements across major manufacturing geographies.
Market Dynamics
The motherboard battery market is restructuring around data center server refresh cycles and tightening material recovery mandates, with enterprise IT procurement patterns now prioritizing predictive failure monitoring and multi-year qualification stability over unit cost minimization.
Growth Catalysts
- EU Battery Directive material recovery mandates:Extended producer responsibility frameworks are compelling motherboard manufacturers to source batteries from suppliers with certified closed-loop recycling capabilities, tightening OEM qualification criteria.
- Enterprise server predictive maintenance:Smart Battery technology with embedded telemetry is unifying real-time clock backup with remote asset management functions, accelerating replacement of passive coin cells in hyperscale facilities.
- Shenzhen-Dongguan manufacturing concentration:Proximity to motherboard assembly clusters reduces logistics friction for lithium manganese dioxide cell suppliers, compressing lead times for global electronics brands.
Market Restraints
- Lithium carbonate price volatility:Raw material cost swings for lithium manganese dioxide chemistry compress margins for battery assemblers lacking backward integration into cell production.
- Single-source ceramic sealing technology:Industrial-grade battery architectures depend on specialized Japanese ceramic-to-metal feedthroughs, creating geographic concentration risk in the high-reliability segment.
- REACH substance restriction thresholds:European hazardous content limits complicate formulation adjustments for legacy mercury-free designs, extending requalification timelines for existing OEM contracts.
Strategic Opportunities
- Medical device battery qualification:Long-cycle reliability specifications from server applications transfer directly to implantable and diagnostic equipment, opening adjacent revenue pools with premium pricing tolerance.
- India electronics manufacturing incentives:Production-linked incentive schemes for semiconductor and component assembly are attracting motherboard fabrication investment, creating localized demand for CMOS backup cells.
- Edge computing node proliferation:Distributed micro-datacenters in telecommunications infrastructure require maintenance-free power backup for BIOS retention, expanding addressable unit volumes beyond traditional PC motherboards.
Industry Challenges
- Electrochemical engineer scarcity:Specialized expertise in lithium primary cell chemistry and ceramic hermetic sealing is concentrating at established Japanese and Korean suppliers, constraining new entrant technical staffing.
- OEM qualification cycle duration:Multi-year validation protocols for motherboard-integrated power sources delay revenue recognition from design wins, pressuring working capital efficiency for component suppliers.
- Legacy CMOS voltage standard persistence:3-volt nominal architecture constraints limit energy density gains from newer lithium chemistries, forcing innovation into form factor and smart functionality rather than capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motherboard Battery Market |
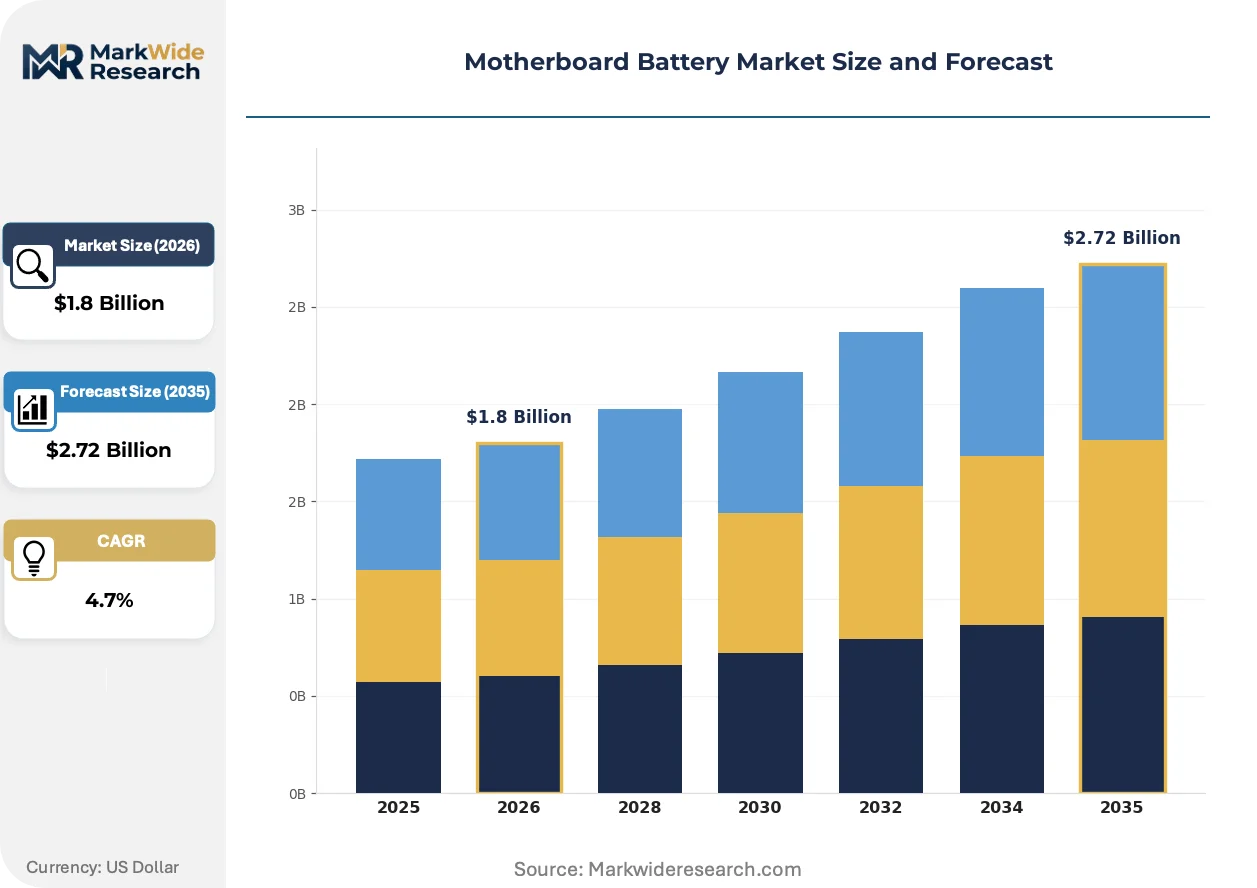
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-Ion, Nickel-Metal Hydride, Lead-Acid, Lithium Polymer Use Case: Consumer Electronics, Industrial Applications, Automotive, Medical Devices Technology: Standard, Fast Charging, Smart Battery, Wireless Charging End User: OEMs, Aftermarket Providers, Retailers, System Integrators |
| Companies Covered | Panasonic Holdings Corp, Murata Manufacturing, Maxell, Sony Corporation, Golden Power Group Holdings, VARTA AG, ASUS, Hitachi, Hoperf, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motherboard Battery Market Trends and Innovations
Active unification of hardware telemetry with cloud-based asset management is compressing the traditional divide between passive backup power and intelligent infrastructure monitoring. This convergence is reshaping supplier capability requirements and buyer evaluation criteria simultaneously.
Smart Battery System (SBS) protocol implementations are unifying voltage monitoring, temperature sensing, and cycle counting within the compact footprint of standard coin cell replacements. Hyperscale cloud operators are mandating these capabilities in new server motherboard specifications, forcing battery suppliers to integrate microcontroller firmware and I2C communication layers previously external to the power component. This functional compression is unifying what were separate subsystem procurements into single-source battery contracts.
REACH Annex XVII restrictions on cadmium and mercury content are accelerating substitution of legacy alkaline backup cells with lithium primary chemistry across European electronics supply chains. Industrial motherboard builders serving medical and aerospace verticals face the strictest substance documentation requirements, with ECHA SCIP database obligations now extending to coin cell-level component declarations. German automotive electronics suppliers are responding by pre-qualifying only batteries with full material disclosure passports.
Enterprise procurement teams are consolidating motherboard battery sourcing through direct OEM contracts rather than distribution channels, compressing the traditional two-tier supply structure. Server manufacturers with captive motherboard divisions are negotiating multi-year supply agreements that bundle CMOS backup cells with primary power supply purchases, displacing independent battery distributor relationships. This channel consolidation is most visible in North American hyperscale datacenter builds, where procurement centralization has reduced qualified vendor lists to three or fewer approved cell suppliers per motherboard platform.
Motherboard Battery Market Segmentation
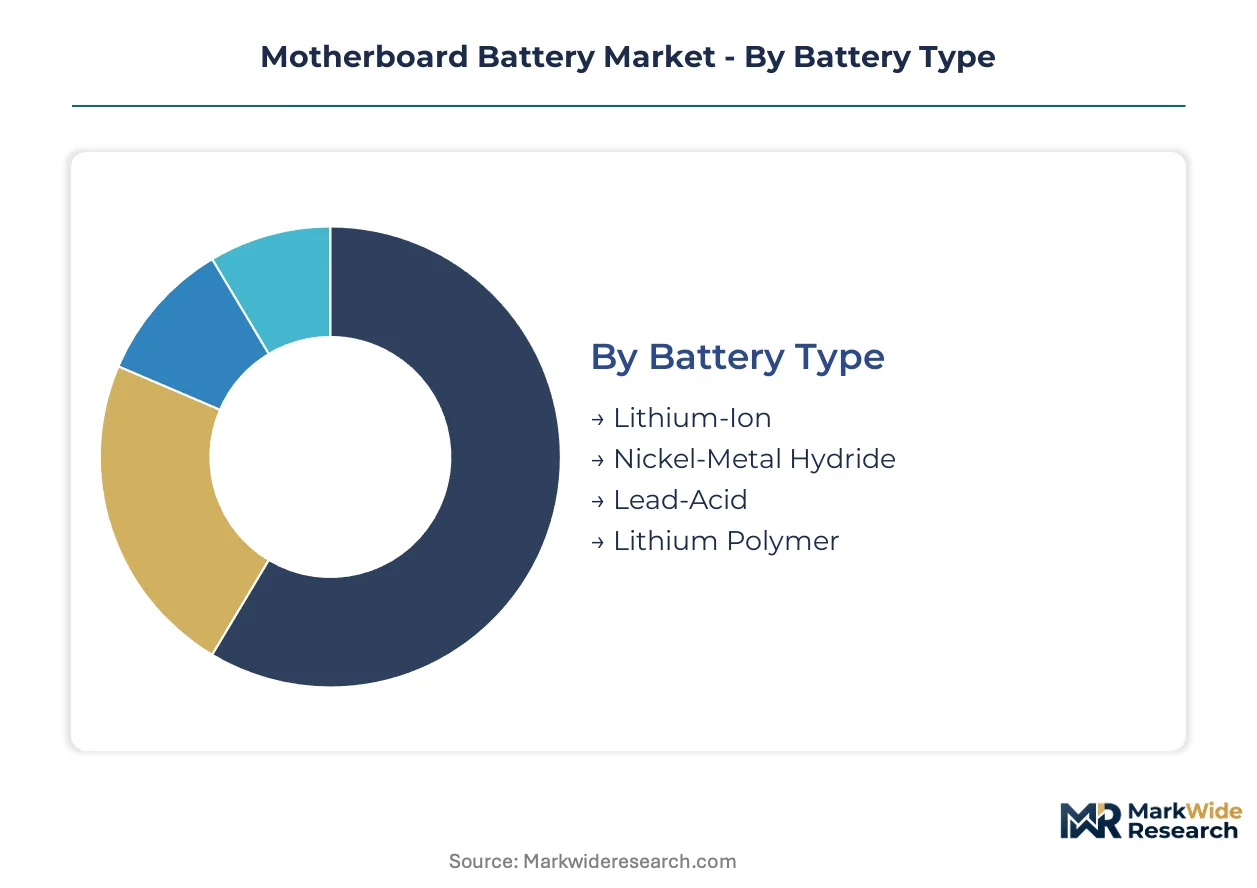
Motherboard battery procurement patterns diverge sharply across chemistry types, application environments, and integration depths. Each segmentation axis reveals distinct margin structures, qualification barriers, and supplier capability requirements that shape competitive positioning.
Battery Type:
Capital intensity concentrates in electrode material synthesis and cell formation equipment, with lithium-based chemistries demanding the highest upfront facility investment.
- Lithium-Ion:Lithium manganese dioxide coin cells dominate CMOS backup applications with superior shelf stability and 3-volt nominal output. Demand clusters in Shenzhen-Dongguan motherboard manufacturing corridors where Panasonic and Murata maintain direct OEM supply relationships.
- Lithium Polymer:Pouch-form factor variants enable flexible PCB integration for compact embedded systems and edge computing nodes. Adoption is accelerating in telecommunications infrastructure where space-constrained designs prioritize thickness reduction over cylindrical cell energy density.
- Nickel-Metal Hydride:Legacy chemistry persists in cost-sensitive consumer motherboard segments requiring minimal backup duration. Japanese suppliers retain residual production capacity for replacement markets and industrial equipment with legacy voltage compatibility requirements.
- Lead-Acid:Sealed AGM variants serve niche industrial motherboard applications requiring extended backup duration beyond standard coin cell specifications. Demand localizes in heavy machinery and process control systems with extended offline retention requirements.
Most installed capacity flows through Lithium-Ion. Expansion is steepest in Lithium Polymer.
Use Case:
Application environments dictate reliability specifications, with industrial and medical verticals imposing the most stringent qualification protocols and documentation requirements.
- Industrial Applications:Ceramic-hermetic sealed cells withstand temperature cycling and mechanical shock in factory automation controllers. German automotive electronics suppliers now mandate ECHA SCIP database compliance for all coin cell components.
- Consumer Electronics:Standard lithium coin cells serve desktop and laptop motherboard replacement markets through distributor and retail channels. Price compression is most severe in this segment where unbranded Asian suppliers compete on unit cost.
- Medical Devices:Implantable and diagnostic equipment requires 10-year minimum shelf life with failure rates below 1 ppm. FDA 21 CFR Part 820 quality system documentation extends qualification timelines to 18-24 months for new cell designs.
- Automotive:Infotainment and ECU motherboard backup must survive under-hood temperature extremes and vibration profiles. AEC-Q200 stress test compliance is becoming mandatory for tier-1 supplier qualification.
Industrial Applications capture the highest average selling prices. Medical Devices show the steepest expansion trajectory.
Technology:
Functional integration depth separates commodity replacement markets from value-added embedded systems procurement.
- Smart Battery:Embedded microcontrollers with I2C telemetry unify voltage monitoring, temperature sensing, and predictive failure alerting within standard coin cell footprints. Hyperscale cloud operators in North American datacenters now specify SBS protocol compliance in server motherboard RFPs.
- Standard:Passive lithium manganese dioxide cells without communication capability serve cost-minimized consumer and legacy industrial applications. Volume concentrates in replacement markets and emerging economy electronics manufacturing.
- Fast Charging:Specialized anode formulations enable rapid replenishment of backup cells in field-serviceable industrial equipment. Adoption remains limited by the infrequent cycling typical of CMOS backup applications.
- Wireless Charging:Inductive power transfer integration eliminates physical connector wear in sealed medical and aerospace enclosures. Technical feasibility demonstrations are advancing through ISO 15118 derivative protocols for sealed device maintenance.
Standard technology retains the largest installed base. Smart Battery is gaining share fastest.
End User:
Channel structure determines margin capture, with direct OEM relationships offering multi-year contract stability at the cost of extended qualification investment.
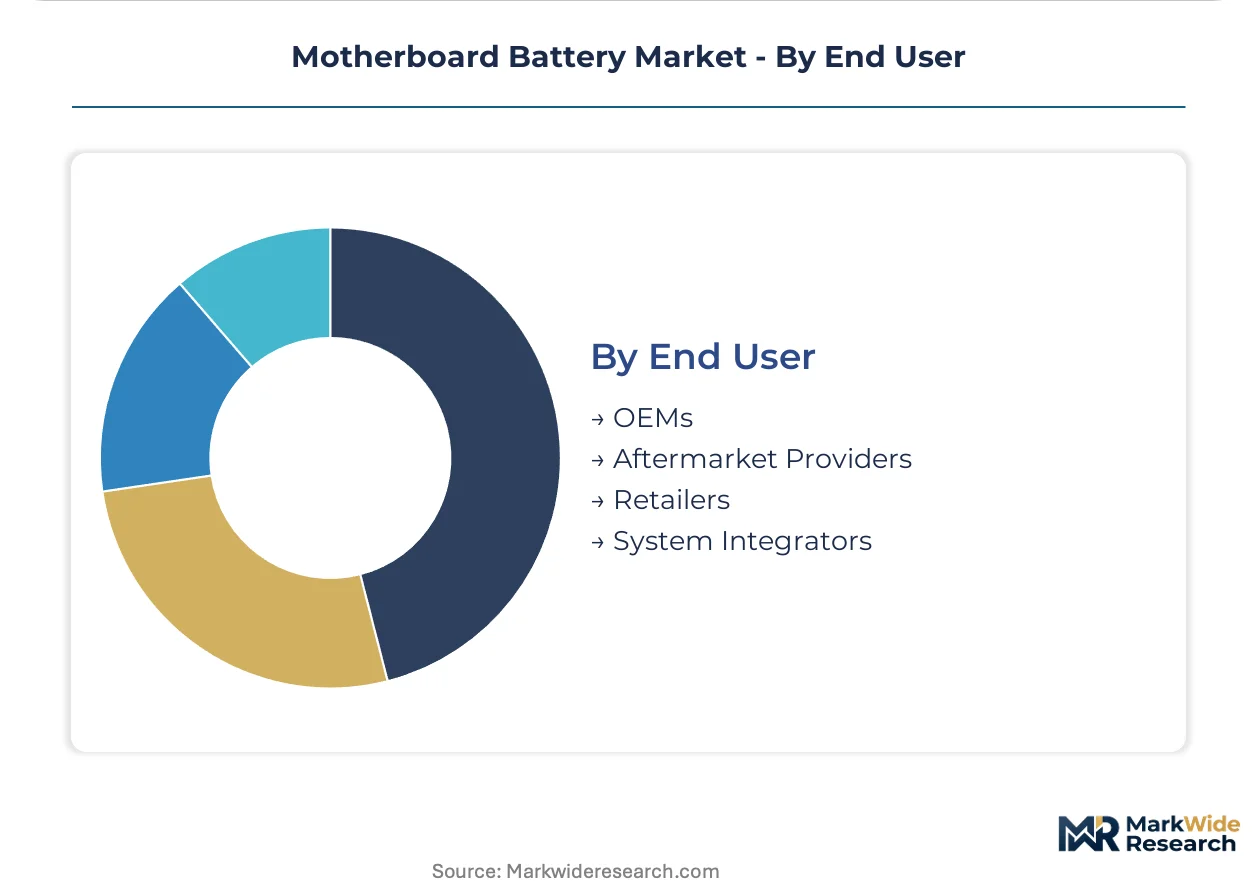
- OEMs:Direct supply agreements with motherboard manufacturers bundle CMOS backup cells with primary power supply purchases. Server builders with captive motherboard divisions in Taiwan and China have reduced qualified vendor lists to three approved cell suppliers per platform.
- System Integrators:Custom industrial PC builders source batteries through authorized distributors with application engineering support. This channel captures premium pricing for small-batch configurations with non-standard form factors.
- Aftermarket Providers:Independent service organizations and repair shops purchase replacement cells through electronics distributors. REACH substance documentation requirements now extend to component-level declarations for European refurbishment operations.
- Retailers:Consumer-facing channels serve DIY replacement and emergency purchase occasions. Online marketplaces are compressing price transparency and accelerating commoditization of standard CR2032-equivalent cells.
OEMs absorb the majority of production volume. System Integrators deliver the highest margin per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Motherboard battery manufacturing traces its industrial lineage to post-war Japan, where precision ceramic sealing techniques developed for vacuum tubes migrated into compact electrochemical cells. This technical foundation diffused to South Korea and China through the 1980s and 1990s, establishing the current tripolar production geography.
China
Shenzhen and Dongguan manufacturing clusters absorb the majority of global CMOS backup cell demand through proximity to motherboard assembly lines. The Ministry of Industry and Information Technology enforces GB standards for lithium battery safety that many exporters adopt as baseline compliance. Dongguan's component ecosystem compresses logistics lead times for Panasonic and Murata direct supply operations serving Taiwanese server OEMs.
Japan
Japanese suppliers anchor the high-reliability segment through proprietary ceramic-to-metal feedthrough technology developed for aerospace applications. METI voluntary safety standards have become de facto benchmarks for Asian trade compliance, extending Japanese regulatory influence beyond national borders. Osaka-based manufacturing maintains concentration in electrochemical engineering expertise that constrains new entrant technical staffing.
United States
Hyperscale cloud operators in North American datacenters now mandate Smart Battery System protocol compliance in server motherboard specifications, reshaping procurement criteria. EPA lithium battery disposal thresholds govern end-of-life handling for enterprise IT asset refreshes. Texas and Arizona datacenter construction is expanding addressable demand for predictive failure monitoring capabilities.
Germany
German automotive electronics suppliers pre-qualify only batteries with full material disclosure passports to satisfy ECHA SCIP database obligations. REACH Annex XVII substance restrictions accelerate substitution of legacy alkaline cells with lithium primary chemistry across European supply chains. Bavarian industrial motherboard builders serving medical verticals face the strictest documentation requirements.
South Korea
Korean battery assemblers leverage electrode material synthesis capabilities developed for consumer electronics to serve CMOS backup applications. The Ministry of Trade, Industry and Energy enforces alignment with international IEC standards for portable power sources. Seoul-based suppliers compete on volume scale for standard coin cell replacements while building smart battery firmware competencies.
Motherboard Battery Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the motherboard battery landscape, with electrode material synthesis and ceramic hermetic sealing requiring substantial facility investment while firmware and telemetry integration demand specialized engineering talent. The market structure concentrates in three tiers: integrated cell manufacturers with backward control over lithium chemistry, specialized ceramic sealing houses serving industrial reliability segments, and assembly operations sourcing cells for cost-minimized consumer applications. Dominant competitive moves include capacity expansion in Shenzhen-Dongguan corridors and strategic partnerships between cell suppliers and server OEMs for multi-year qualification cycles.
Within the integrated manufacturing tier, Panasonic Holdings Corp and Murata Manufacturing exemplify producers with captive control over lithium manganese dioxide cell production and ceramic sealing architectures. Maxell occupies a position representing long-cycle reliability specialists competing on qualification stability for medical and server applications. These three Japanese entities anchor the premium segment through technical heritage in precision electrochemistry, while VARTA AG and Golden Power Group Holdings represent European and Asian competitors respectively, serving regional qualification requirements and cost-optimized replacement markets.
| Leading Market Players |
|---|
| Panasonic Holdings Corp |
| Murata Manufacturing |
| Maxell |
| Sony Corporation |
| Golden Power Group Holdings |
| VARTA AG |
| ASUS |
| Hitachi |
| Hoperf |
| Others |
Pricing and Supply Chain Analysis
EU Battery Directive material recovery mandates gate qualified supply and premium-tier pricing access, compelling motherboard manufacturers to source only from suppliers with certified closed-loop recycling capabilities while compressing margins for uncertified competitors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale. Industrial-grade ceramic-sealed cells command premium positioning through AEC-Q200 and FDA 21 CFR Part 820 documentation, while unbranded Asian suppliers compete on unit cost in consumer replacement channels. Cost compression in standard lithium coin cells is intensifying because Shenzhen-Dongguan manufacturing clusters concentrate assembly capacity. Consumer electronics retailers exhibit the highest price sensitivity, whereas medical device OEMs tolerate premium pricing for qualification stability.
Supply Chain Analysis
India's Production-Linked Incentive schemes and China's MIIT domestic-content frameworks are reshaping sourcing patterns for non-Japanese suppliers. Electrode material synthesis and ceramic-to-metal feedthroughs draw from Japan, South Korea, and China. Raw material dependencies center on lithium carbonate, manganese dioxide, and specialized ceramic substrates. Single-source vulnerability concentrates in Japanese ceramic sealing technology for industrial applications. Distribution runs through direct OEM contracts for server manufacturers and authorized distributors for industrial system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through smart battery firmware premiumization and predictive maintenance bundling, offsetting lithium carbonate cost volatility.
For Market Incumbents: Acquire ceramic-sealing technology specialists to defend against Korean electrode-material competitors and consolidate high-reliability segment positioning. Deepen backward integration into lithium manganese dioxide cell production to buffer raw material cost swings. Invest in SBS protocol firmware engineering to capture hyperscale cloud operator specifications before qualification windows close. For New Entrants and Emerging Players: Launch via system integrator channels targeting Indian electronics manufacturing incentive zones with localized CMOS backup cell assembly. Exploit underpenetrated edge computing node deployments in telecommunications infrastructure. Pursue medical device battery qualification as the most penetrable premium segment with 18-24 month timeline tolerance. For Investors and Strategic Acquirers: Roll-up economics work for regional battery assemblers with captive OEM relationships because multi-year qualification cycles create sticky revenue streams and high switching costs. Long-term viability over the mid-decade horizon favors specialists with dual competency in electrochemical cell production and embedded telemetry firmware. Monitor EU Battery Directive enforcement intensity as the inflection signal for accelerated consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Battery Firmware Development | Panasonic and Murata embed SBS protocol compliance to capture hyperscale datacenter specifications. |
| Ceramic Sealing Technology Acquisition | Industrial-grade hermetic feedthroughs anchor medical and aerospace qualification stability. |
| India Manufacturing Localization | PLI scheme incentives attract motherboard fabrication investment and CMOS cell demand. |
| Closed-Loop Recycling Certification | ECHA SCIP database compliance becomes mandatory for European electronics supply chain access. |
| Predictive Maintenance Platform Integration | Embedded telemetry unifies backup power with cloud-based asset management for server OEMs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with electrochemical engineers at Japanese and Korean cell manufacturers, procurement leads at Taiwanese server OEMs, firmware architects at hyperscale cloud operators, and regulatory affairs specialists at German automotive electronics suppliers. Secondary validation drew from EPA lithium battery disposal guidelines, ECHA SCIP database documentation, MIIT GB standards filings, and SEC 10-K disclosures from listed battery producers. Bottom-up unit demand modeling and top-down value triangulation cross-checked segment outputs.
Segment-weighting across battery chemistry, use case environment, technology integration depth, and end-user channel structure drove the analytical framework over the projection horizon. CAGRs derived from fitted growth curves applied to each segment's baseline and projected penetration. Forecast inputs incorporated server refresh cycle timing from hyperscale capex disclosures and REACH substance restriction implementation phasing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium carbonate price volatility and ceramic feedthrough supply disruption scenarios. Forecasts reflect documented assumptions about OEM qualification cycle duration and EU extended producer responsibility enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
PTC Resettable Device Market
Electronic Components
Frequency Control and Timing Devices Market
Electronic Components
Switch Diode Market
Electronic Components
Audio CODEC Market
Electronic Components
USB Charger Market
Electronic Components
Global Tantalum Capacitors Market
Electronic Components
Silicon Capacitors Market
Electronic Components
Microspeaker Market
Electronic Components
United States Radiation-Hardened Electronics Market
Electronic Components
North America Touch Screen Controllers Market
Electronic Components
Global Flexible Electronics and Circuit Market
Electronic Components
Pneumatic Components Market
Electronic Components
Multi-Layer Ceramic Capacitor (MLCC) Market
Electronic Components
Conductive Polymer Capacitor Market
Electronic Components
High-Voltage Interlock Loop Wiring Components Market
Electronic Components
Data Acquisition Hardware Market