
 Multilayer Chip Bead Market | 2026-2036
Multilayer Chip Bead Market Size, Share, and Industry Trends Forecast 2026-2036
Multilayer Chip Bead Market Insights
The premium-commodity split in multilayer chip beads is repositioning around automotive-grade AEC-Q200 qualification versus standard consumer-tier supply. Murata Electronics dominates high-reliability ferrite formulations for powertrain modules. TDK leverages its materials science heritage to sustain pricing power in RF noise suppression for 5G base stations. Samsung Electro-Mechanics anchors volume production through captive demand from its parent group's smartphone and display divisions.
A multilayer chip bead is a surface-mount passive component constructed from alternating layers of ferrite ceramic material and internal silver-palladium electrodes, sintered into a monolithic body typically measuring 0402 to 1206 in EIA case size, engineered to attenuate high-frequency electromagnetic interference across megahertz to gigahertz ranges. Its primary purpose is to suppress conducted noise in power and signal lines without significant DC resistance penalty in compact electronic assemblies. The automotive application segment leads absolute consumption as electrified powertrains and domain controllers multiply filtering nodes per vehicle. Ceramic material formulations command the deepest margin pools due to proprietary ferrite compositions and firing process control that determine impedance curves across temperature extremes.
The US FCC Part 15 emissions framework and the EU's CE marking under the EMC Directive constrain market access for unqualified chip bead suppliers in consumer and industrial electronics. China's SAMR enforces GB/T electromagnetic compatibility standards that increasingly mirror automotive OEM test protocols, tightening certification burdens for aftermarket entrants. Stakeholders must monitor how regional divergence in EV charging infrastructure standards reshapes impedance specification requirements across export markets.
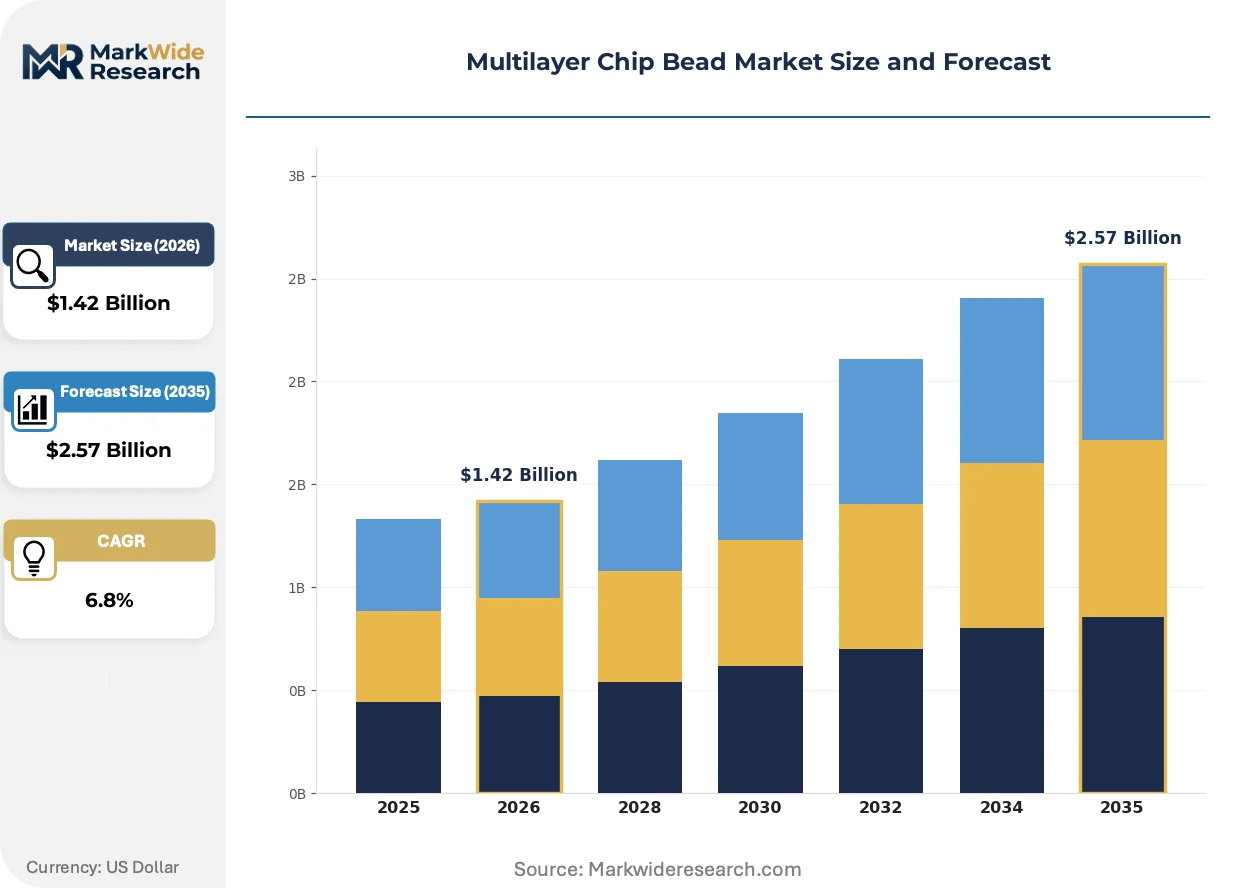
Market Dynamics
Automotive electrification is compressing impedance specification cycles as EV powertrains multiply filtering nodes per vehicle, forcing ferrite suppliers to synchronize AEC-Q200 qualification timelines with OEM platform launches.
Growth Catalysts
- MIIT EMC Certification Tightening:China's Ministry of Industry and Information Technology has hardened electromagnetic compatibility mandates for onboard electronics, pushing domestic and foreign OEMs toward qualified ferrite bead suppliers with proven automotive-grade track records.
- ADAS Domain Controllers:Advanced driver-assistance systems integrate radar, lidar, and camera modules that each require dedicated noise suppression, multiplying chip bead consumption per vehicle architecture.
- East Asian Manufacturing Cluster Density:Component ecosystems around Shenzhen and Seoul concentrate sintering expertise, silver-palladium electrode deposition, and testing infrastructure within tight logistics radii.
Market Restraints
- Silver-Palladium Input Volatility:Precious metal electrode materials expose margins to London Bullion Market Association pricing swings that contract manufacturers cannot fully hedge.
- Ferrite Formulation Concentration:Proprietary high-temperature coefficient ferrites remain concentrated among Japanese and Korean materials science houses, creating single-source risk for AEC-Q200 qualified supply.
- Low-Frequency Substitution:Common-mode chokes and integrated EMI filters displace discrete chip beads in sub-100 MHz applications where board space permits larger components.
Strategic Opportunities
- Indian EV Component Localization:The country's Production-Linked Incentive scheme for automotive electronics creates first-mover advantage for ferrite suppliers establishing local sintering and electrode printing operations.
- GB/T Standard Convergence:China's State Administration for Market Regulation is aligning consumer electronics EMC certification with automotive test protocols, opening cross-selling pathways for dual-qualified suppliers.
- 5G mmWave Infrastructure:Base station deployments in the 24-71 GHz range demand ultra-low DC resistance beads with tight impedance tolerance, commanding performance-tier pricing premiums.
Industry Challenges
- Multi-Physics Simulation Talent Scarcity:Ferrite electromagnetic-thermal-mechanical modeling requires rare cross-disciplinary expertise combining materials science, RF engineering, and finite element analysis.
- AEC-Q200 Timeline Compression:Automotive qualification cycles spanning 18-24 months now overlap with 12-month EV platform redesign windows, forcing parallel rather than sequential testing investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multilayer Chip Bead Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MLCC, Ferrite Beads, Inductors, Capacitors Application: Consumer Electronics, Automotive, Telecommunications, Industrial Equipment Material: Ceramic, Metal Oxide, Polymer, Composite End User: OEMs, Aftermarket Suppliers, Distributors, Engineers |
| Companies Covered | TDK, Murata Electronics, Samsung Electro-Mechanics, Vishay, Würth Elektronik, TAIYO YUDEN, Yageo, Bourns, Laird Performance Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multilayer Chip Bead Market Trends and Innovations
Materials science advances and procurement model evolution are compressing traditional supplier hierarchies, enabling specialized ferrite houses to bypass tiered distribution and contract directly with EV platform architects.
Nickel-zinc ferrite formulations with engineered permeability temperature coefficients are integrating into 800V silicon carbide inverter modules, where thermal cycling demands stable impedance across -40°C to 150°C extremes. European powertrain suppliers are accelerating adoption ahead of 2025 platform freezes. This integration is compressing the historical gap between consumer-grade and automotive-grade supplier tiers.
The EU's F-Gas Regulation and associated delegated acts are tightening fluorinated greenhouse gas controls in manufacturing processes, forcing ferrite sintering operations to retrofit thermal treatment systems or relocate to jurisdictions with looser emissions frameworks. German automotive suppliers are absorbing compliance costs while pressing suppliers for documented carbon footprint data across raw material extraction to finished component.
Consolidated procurement by EV platform architects is disintermediating traditional electronics distributors, with BYD, Tesla, and Hyundai Motor Group establishing direct ferrite bead supply agreements specifying impedance curves, temperature coefficients, and lot traceability protocols. This behavior concentrates volume among qualified suppliers while marginalizing catalog distributors in high-reliability segments. The shift is most visible in South Korea and China's Yangtze River Delta manufacturing corridors.
Multilayer Chip Bead Market Segmentation
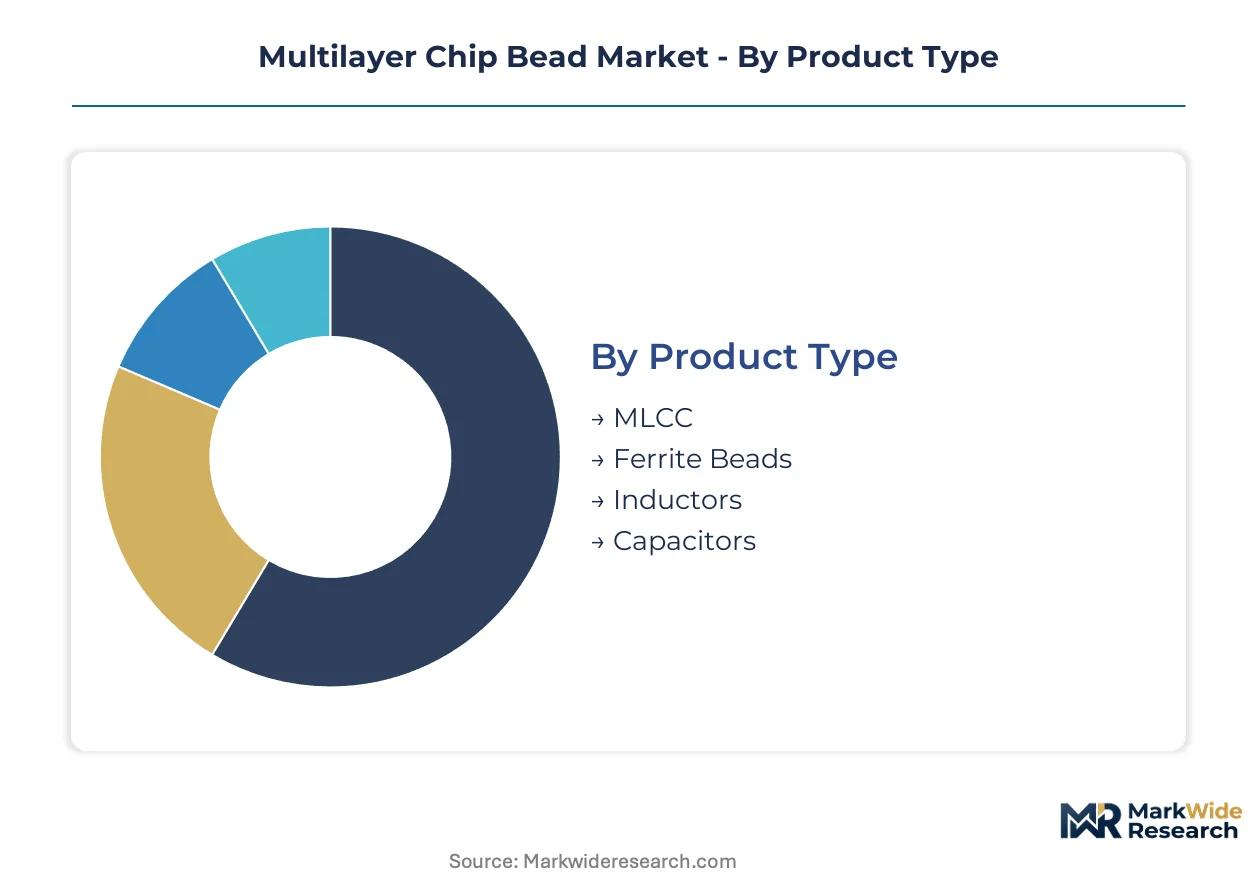
Multilayer chip bead procurement diverges sharply across certification tiers, with AEC-Q200 automotive qualification commanding 40-60% price premiums over consumer-grade equivalents. Specification cycles compress as EV platform architects impose custom impedance curves and temperature coefficient requirements that fragment traditional catalog-based supply.
Product Type:
Ferrite composition and electrode architecture determine insertion loss characteristics across the megahertz-to-gigahertz spectrum.
- MLCC:Multilayer ceramic capacitors integrate Class I and Class II dielectric formulations for decoupling applications requiring low equivalent series resistance. Demand concentrates in 5G smartphone RF modules and automotive ADAS camera systems where miniaturization pressures dominate board design constraints.
- Ferrite Beads:Nickel-zinc and manganese-zinc ferrite cores with silver-palladium internal electrodes attenuate conducted EMI across power distribution networks. Automotive 800V silicon carbide inverters drive qualification investments for -40°C to 150°C stable impedance specifications.
- Inductors:Wire-wound and multilayer ceramic inductors store magnetic energy in switching regulator circuits.
- Capacitors:Tantalum, aluminum electrolytic, and film capacitors complement chip beads in bulk filtering stages.
Mature deployment sits with MLCC in consumer smartphones. Newer deployment is concentrated in ferrite beads for electrified powertrain noise suppression.
Application:
End-use specifications cascade backward into ferrite formulation requirements and electrode deposition tolerances.
- Consumer Electronics:Smartphones, tablets, and wearables demand 0402 and 0201 case sizes with tight tolerance for high-density PCB assembly. Shenzhen manufacturing clusters absorb volume production through captive demand from domestic OEMs.
- Automotive:Domain controllers, battery management systems, and onboard chargers multiply filtering nodes per vehicle architecture. MIIT EMC certification tightening pushes OEMs toward qualified suppliers with proven AEC-Q200 track records.
- Telecommunications:5G base stations and optical transceivers require ultra-low DC resistance beads for millimeter-wave signal integrity.
- Industrial Equipment:Motor drives and programmable logic controllers tolerate larger case sizes where board space permits integrated EMI filters.
Automotive applications climb the fastest as electrification multiplies noise suppression nodes per vehicle platform.
Material:
Magnetic permeability and temperature coefficient stability separate premium formulations from commodity supply.
- Ceramic:Proprietary nickel-zinc ferrite sintered with controlled grain structure delivers stable impedance across thermal cycling extremes. Korean and Japanese materials science houses concentrate high-temperature coefficient formulations for automotive qualification.
- Metal Oxide:Manganese-zinc ferrite offers higher permeability for low-frequency suppression in consumer power adapters.
- Polymer:Organic binders enable flexible substrate integration for wearable and medical device applications.
- Composite:Hybrid ceramic-polymer matrices balance magnetic performance with mechanical compliance.
Volume leadership rests with ceramic formulations. Polymer composites are gaining share fastest in flexible electronics segments.
End User:
Procurement authority is consolidating toward platform architects with direct supplier qualification capabilities.
- OEMs:BYD, Tesla, and Hyundai Motor Group establish direct ferrite bead supply agreements specifying impedance curves, temperature coefficients, and lot traceability protocols. This behavior concentrates volume among qualified suppliers while marginalizing catalog distributors in high-reliability segments.
- Aftermarket Suppliers:Independent distributors serve repair and replacement demand with standard-grade components lacking automotive qualification.
- Distributors:Arrow, Avnet, and WPG Holdings maintain inventory buffers for consumer and industrial tier supply.
- Engineers:Design teams specify components during prototype phases before procurement locks in qualified supply.
Established relationships dominate OEM procurement. Engineering-led specification is expanding most quickly in EV startup ecosystems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the densest concentration of multilayer chip bead fabrication, with sintering facilities and silver-palladium electrode deposition lines clustering within the Pearl River Delta electronics corridor.
China
MIIT EMC certification tightening for onboard electronics pushes BYD and domestic OEMs toward qualified ferrite suppliers. SAMR enforces GB/T electromagnetic compatibility standards that increasingly mirror automotive test protocols. Yangtze River Delta manufacturing corridors concentrate captive supply agreements with EV platform architects specifying impedance curves and lot traceability.
South Korea
Hyundai Motor Group and Samsung-affiliated electronics divisions multiply filtering nodes per electrified vehicle architecture. MFDS oversees medical device EMC requirements that cross-apply to automotive-grade component qualification. Seoul Capital Area ecosystems integrate sintering expertise with RF module design for 5G base station exports.
Japan
METI industrial policy supports nickel-zinc ferrite formulation R&D for 800V silicon carbide inverter thermal cycling demands. AEC-Q200 qualification timelines compress against 12-month EV platform redesign windows. Chubu region materials science houses concentrate proprietary high-temperature coefficient ferrite production.
Germany
BMW and Volkswagen procurement teams establish direct ferrite bead supply agreements bypassing traditional distributors. EU F-Gas Regulation tightens fluorinated greenhouse gas controls in sintering thermal treatment systems. Bavaria-based automotive suppliers absorb compliance costs while pressing for documented carbon footprint data from raw material extraction.
United States
Tesla procurement consolidates volume among qualified suppliers for Cybertruck and Semi powertrain modules. FCC Part 15 emissions framework constrains market access for unqualified chip bead entrants in consumer electronics. Texas and California manufacturing corridors concentrate EV assembly lines driving custom impedance specification requirements.
Multilayer Chip Bead Market Competitive Landscape
Premium-margin players sit above commodity-margin players across AEC-Q200 qualification status, with automotive-grade certification commanding 40-60% price premiums over consumer-tier equivalents. The vendor base stratifies into three tiers: Japanese and Korean materials science houses with proprietary ferrite formulations, Chinese volume producers serving domestic EV supply chains, and European specialty houses focused on industrial EMC compliance. Dominant competitive moves include backward integration into silver-palladium electrode deposition and direct supply agreement negotiations with EV platform architects that disintermediate traditional electronics distributors.
Within the materials science tier, TDK and Murata Electronics exemplify premium positioning through proprietary formulation control. Samsung Electro-Mechanics occupies a distinct position leveraging captive demand from its parent group's smartphone and display divisions while expanding automotive qualification. These three anchors represent divergent strategic archetypes: independent materials innovation, conglomerate-affiliated volume scaling, and hybrid consumer-automotive cross-qualification.
| Leading Market Players |
|---|
| TDK |
| Murata Electronics |
| Samsung Electro-Mechanics |
| Vishay |
| Würth Elektronik |
| TAIYO YUDEN |
| Yageo |
| Bourns |
| Laird Performance Materials |
| Others |
Pricing and Supply Chain Analysis
Silver-palladium electrode costs cascade through multilayer chip bead pricing tiers, with London Bullion Market Association price swings compressing margins for contract manufacturers unable to hedge precious metal exposure across AEC-Q200 automotive and consumer-grade supply lines.
Pricing Analysis
AEC-Q200 qualification status anchors value-based pricing, with impedance stability across -40°C to 150°C thermal extremes commanding substantial premiums over consumer-tier equivalents. Price differentiation separates automotive-grade ferrite formulations certified for 800V silicon carbide inverters from standard nickel-zinc beads serving smartphone power management. Pricing pressure stems from OEM procurement consolidation, with BYD and Hyundai Motor Group leveraging direct supply agreements to extract documented cost transparency. Aftermarket distributors exhibit highest price sensitivity, while EV platform architects prioritize qualification track records over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from electrified vehicle programs, disintermediating Arrow and Avnet in high-reliability segments while catalog distributors retain consumer electronics buffer inventory roles. Geographic supply concentration centers on Japan, South Korea, and China, with Chubu region materials science houses and Seoul Capital Area sintering facilities anchoring proprietary ferrite production. Raw material dependencies span silver-palladium electrode pastes, nickel-zinc ferrite powders, and ceramic binders. Single-source vulnerability concentrates in high-temperature coefficient ferrite formulations, where Japanese and Korean suppliers control AEC-Q200 qualified supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The multilayer chip bead market sits in a technology-transition phase as 800V silicon carbide powertrains displace legacy 400V architectures, forcing impedance specification cycles to compress from 24-month automotive qualification windows toward 12-month EV platform redesign timelines.
For Market Incumbents: To counter procurement consolidation by EV platform architects, deepen backward integration into silver-palladium electrode deposition and accelerate parallel AEC-Q200 qualification testing to compress 18-24 month timelines. Secure captive ferrite formulation capacity through in-house sintering investments or exclusive supply agreements with Japanese materials science houses. For New Entrants and Emerging Players: The 40-60% price-point gap between AEC-Q200 automotive and consumer-grade tiers creates entry opportunity in Indian EV component localization under Production-Linked Incentive schemes. Target ferrite bead supply for 2-wheeler and 3-wheeler electrification programs where certification burdens remain lighter. Pursue direct qualification with domestic OEMs bypassing established distributor relationships. For Investors and Strategic Acquirers: MIIT EMC certification tightening for onboard electronics is the leading indicator that qualified supplier scarcity will intensify, positioning AEC-Q200 certified ferrite houses for sustained margin expansion. Acquisition targets should feature proprietary nickel-zinc formulation libraries and established thermal cycling test protocols. Monitor GB/T standard convergence with automotive test protocols as signal for cross-selling pathway viability.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q200 Qualification Acceleration | Parallel testing investments compress 18-24 month timelines to match 12-month EV platform windows. |
| Backward Integration into Electrode Deposition | In-house silver-palladium printing hedges LBMA price volatility and secures margin control. |
| Direct OEM Supply Agreement Negotiation | Bypassing Arrow and Avnet concentrates volume among qualified suppliers in high-reliability segments. |
| Indian Manufacturing Localization | PLI scheme for automotive electronics creates first-mover advantage in 2-wheeler electrification supply. |
| GB/T-Automotive Cross-Qualification | SAMR alignment of consumer EMC with automotive protocols opens dual-certified supplier pathways. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with ferrite supplier R&D directors, Tier 1 automotive procurement managers, EV platform engineers, and EMC test laboratory technicians. SEC 10-K disclosures from Murata and TDK, MIIT certification databases, and IHS Markit vehicle production data provided demand-side validation. Bottom-up bill-of-materials analysis for 800V inverter architectures was cross-checked against top-down market sizing from component shipment tracking.
Granularity-level modeling captured ferrite bead consumption by case size, impedance specification, and temperature coefficient tier across vehicle propulsion architecture, ADAS content per vehicle, and regional OEM procurement cluster dimensions. CAGRs were derived from production volume trajectories for electrified platforms and content-per-vehicle expansion in domain controller filtering nodes. Forecast inputs incorporated MIIT EMC certification timelines and silicon carbide inverter adoption curves without year-specific anchoring.
Inputs from ferrite supplier technical documentation and OEM qualification databases were available through the study window; gaps in proprietary formulation performance data introduce uncertainty bands around impedance stability projections across thermal cycling extremes. Forecasts reflect assumptions regarding AEC-Q200 timeline compression and procurement consolidation trajectories. Periodic stress-testing of base assumptions is recommended against MIIT regulatory enforcement patterns and silver-palladium price volatility events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Semiconductor Tubular Heaters Market
Semiconductor Devices
Asia-Pacific Semiconductor Diode Market
Semiconductor Devices
Silicon on Insulator Market
Semiconductor Devices
Analog to Digital Converter Market
Semiconductor Devices
DNA Chromatography Chip Market
Semiconductor Devices
Multi-Chip Module (MCM) Market
Semiconductor Devices
Die Spacer Market
Semiconductor Devices
Global Trench Gate Power MOSFET Market
Semiconductor Devices
Global Semiconductor Lead Frame Market
Semiconductor Devices
China Power Transistor Market
Semiconductor Devices
Power Supply in Package (Psip) and Power Supply on Chip (Pwrsoc) Market
Semiconductor Devices
Chip on Flex Market
Semiconductor Devices
Europe Semiconductor Device Market
Semiconductor Devices
Precision Link Carrier Market
Semiconductor Devices
Global Thermoelectric Modules Market
Semiconductor Devices
AIN DBC Ceramic Substrate Market