
 Intel Motherboards Market | 2026-2036
Intel Motherboards Market Size, Share, and Industry Trends Forecast 2026-2036
Intel Motherboards Market Insights
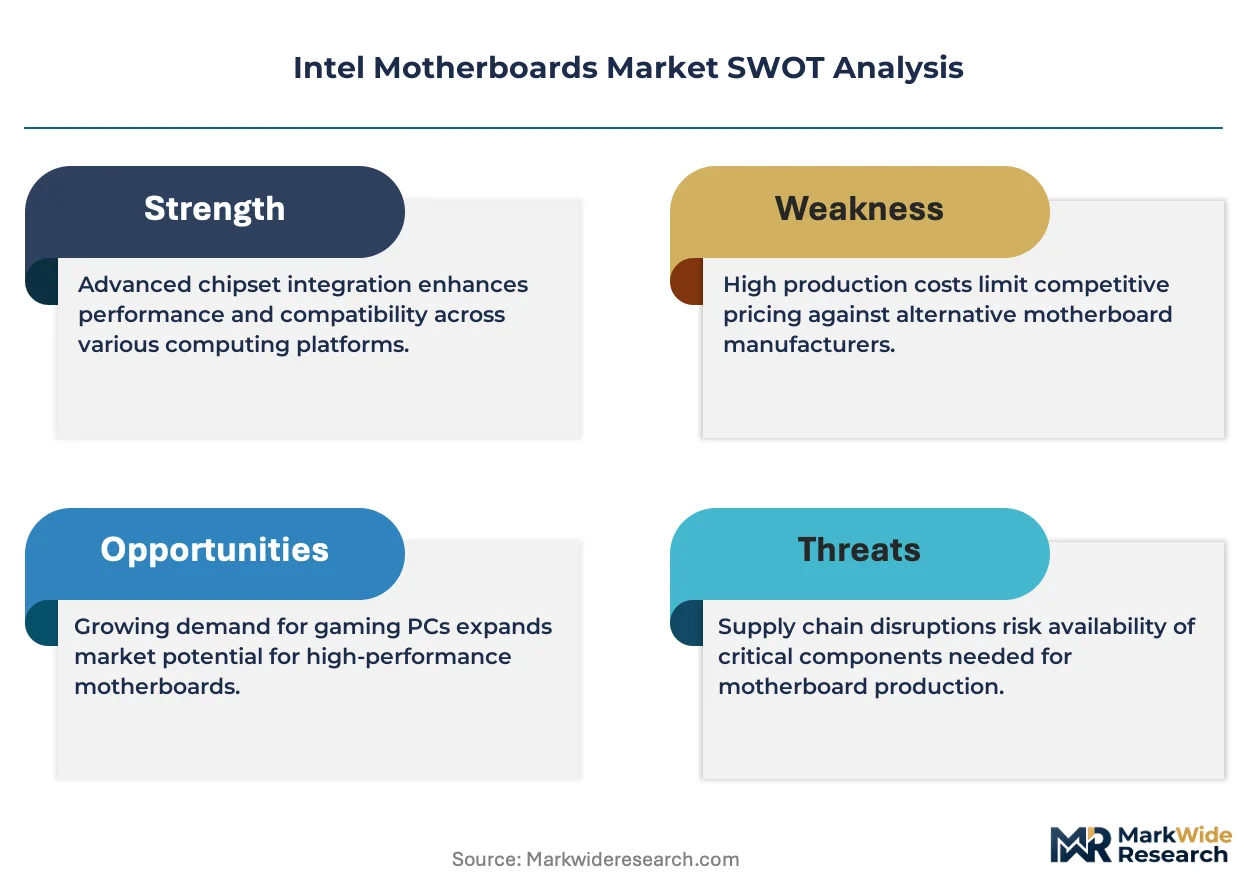
Copper trace layers in high-density PCB designs is pivoting toward modified semi-additive process (mSAP) fabrication to accommodate PCIe 5.0 signal integrity requirements. ASUS leverages in-house BIOS development teams to sustain firmware differentiation across enthusiast segments. Gigabyte Technology anchors its position through AORUS gaming sub-brand specialization with reinforced power delivery designs. Supermicro dominates rack-optimized server board configurations for hyperscale deployments.
Intel motherboards are printed circuit board assemblies designed to interface Intel central processing units with memory, expansion, and peripheral subsystems through standardized socket and chipset architectures, typically incorporating voltage regulator modules supporting 150W to 250W thermal design power envelopes and DDR5 memory channels operating at 4800 MT/s or higher. Their primary commercial purpose is to provide the electrical and mechanical foundation for computing systems ranging from compact embedded nodes to multi-socket enterprise servers. The ATX form factor retains the largest installed base among product types due to backward-compatible chassis ecosystems and balanced expansion slot configurations. Z-series chipsets command premium positioning through unlocked overclocking capabilities and expanded PCIe lane bifurcation. Enterprise OEMs represent the most concentrated margin pool within target customers because of multi-year supply agreements and validated system configurations.
FCC electromagnetic compatibility certifications govern commercial distribution in the United States, while CE marking under the EU RoHS directive restricts hazardous substance thresholds for European market access. China's GB standards and MIIT network access licenses create additional compliance gates for imported board assemblies. NMPA-equivalent quality protocols apply to medical device-integrated computing platforms. Stakeholders must monitor how Intel's socket roadmap transitions affect chipset validation cycles and inventory exposure across distribution channels.
Market Dynamics
The transition from DDR4 to DDR5 memory architectures is compressing motherboard refresh cycles as enterprise data centers and enthusiast segments simultaneously pursue bandwidth expansion. This generational shift intersects with PCIe 5.0 signal integrity demands to reshape PCB fabrication requirements across the supply base.
Growth Catalysts
- Cloud Infrastructure Buildout:Hyperscale operators in the United States, China, and Germany are expanding server-grade board procurement to support AI training clusters and virtualization density requirements.
- EU RoHS Directive:CE marking compliance for hazardous substance thresholds is accelerating board redesigns toward lead-free solder processes and halogen-free laminates.
- Raptor Lake Architecture:Intel's socket LGA 1700 compatibility extensions are extending platform lifecycles and reducing total cost of ownership for mid-tower workstation deployments.
Market Restraints
- Copper and Epoxy Resin Volatility:Raw material input costs for high-layer-count PCBs fluctuate with commodity markets, compressing margin predictability for tier-two fabricators.
- Taiwan Concentration Risk:Advanced substrate and chipset packaging capacity clusters on the island create single-point vulnerability for mSAP and build-up layer supply.
- Signal Integrity Ceilings:PCIe 6.0 electrical specifications demand sub-3% insertion loss tolerances that exceed conventional FR-4 dielectric performance thresholds.
Strategic Opportunities
- Edge Computing Nodes:Industrial automation and smart city deployments in Germany require fanless Mini-ITX boards with extended temperature specifications.
- US CHIPS Act Incentives:Domestic semiconductor manufacturing subsidies are attracting motherboard assembly reshoring investments for defense and aerospace qualification programs.
- DDR5-PMIC Integration:Convergence of power management ICs directly onto memory modules is enabling simplified VRM designs and reduced board layer counts.
Industry Challenges
- Firmware Engineering Scarcity:UEFI/BIOS development expertise concentrates among veteran developers, constraining OEM customization velocity for security-hardened implementations.
- Certification Timeline Compression:FCC Part 15 electromagnetic compatibility testing for 5 GHz Wi-Fi 6E coexistence requires iterative board spins that extend product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intel Motherboards Market |
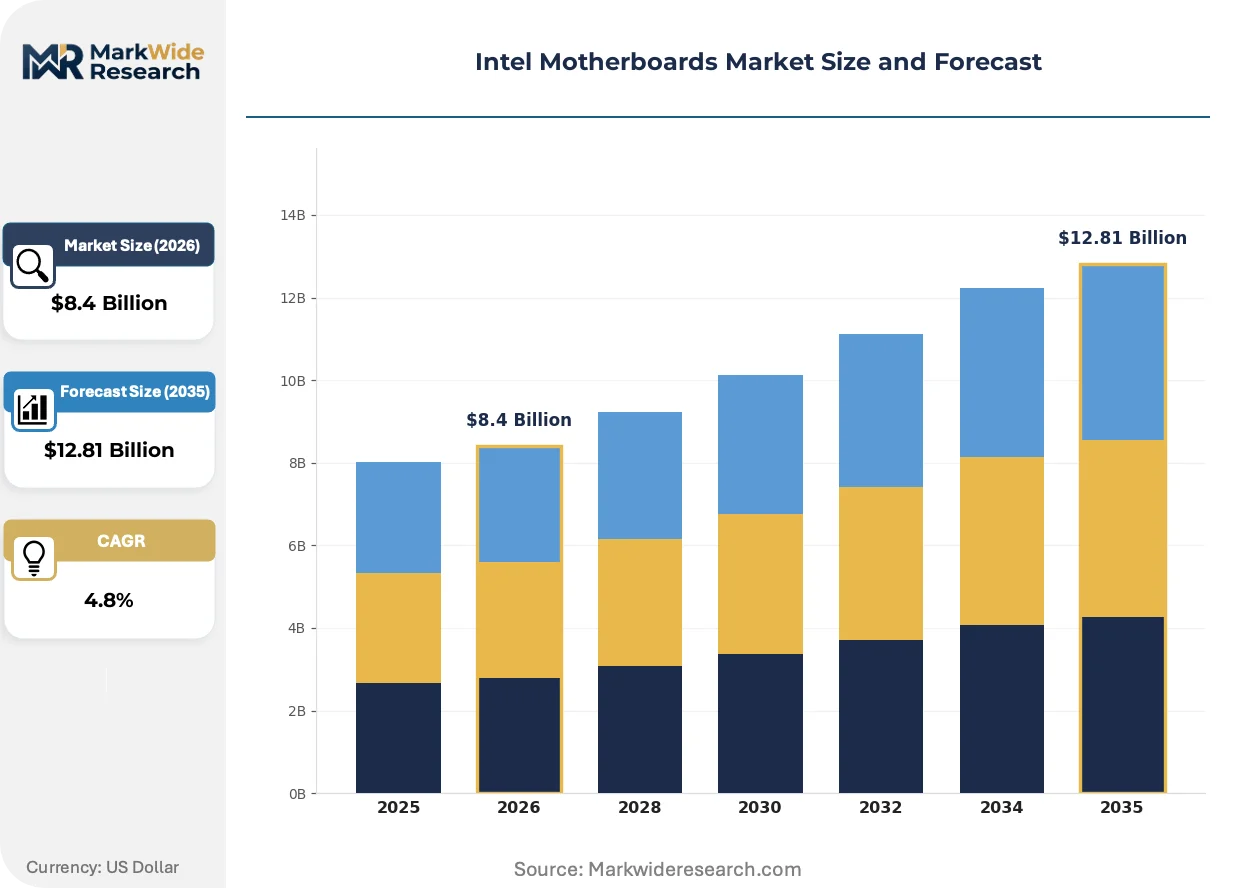
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.81 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ATX, Micro-ATX, Mini-ITX, E-ATX Chipset: Z490, H470, B460, H310 Form Factor: Standard, Low Profile, Extended, Custom Target Customer: OEMs, DIY Builders, Gamers, Enterprises |
| Companies Covered | ASUS, MSI, Gigabyte Technology, ASRock, Intel, Supermicro, EVGA, Biostar, Advantech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intel Motherboards Market Trends and Innovations
Signal routing architectures and power delivery topologies are undergoing simultaneous revision as DDR5 and PCIe 5.0 electrical specifications tighten. Board designers face converging pressures from thermal density, trace density, and firmware complexity.
Modified semi-additive process fabrication is decentralizing high-speed signal layer production away from traditional subtractive etching houses. Hyperscale cloud operators and telecommunications equipment manufacturers are qualifying mSAP-capable suppliers at accelerated rates. This process shift is decentralizing procurement options for 12-layer and above server boards previously concentrated among Japanese and Taiwanese substrate specialists.
China's MIIT network access licensing requirements for Wi-Fi 6E and impending Wi-Fi 7 modules are mandating pre-certification testing at designated domestic laboratories. Board vendors must maintain parallel SKU configurations to satisfy GB standard electromagnetic compatibility thresholds distinct from FCC and CE regimes. Enterprise OEMs targeting Chinese data center deployments face extended validation pipelines as SAR and radiation pattern documentation requirements expand.
Direct-to-manufacturer procurement is displacing traditional distribution for volume server board contracts. Hyperscale operators now negotiate annual pricing frameworks directly with ODMs, bypassing tier-one distributors entirely. This channel compression is most visible in the United States, where Microsoft, Amazon, and Google account for concentrated procurement volumes that reshape supplier prioritization and R&D roadmaps.
Intel Motherboards Market Segmentation
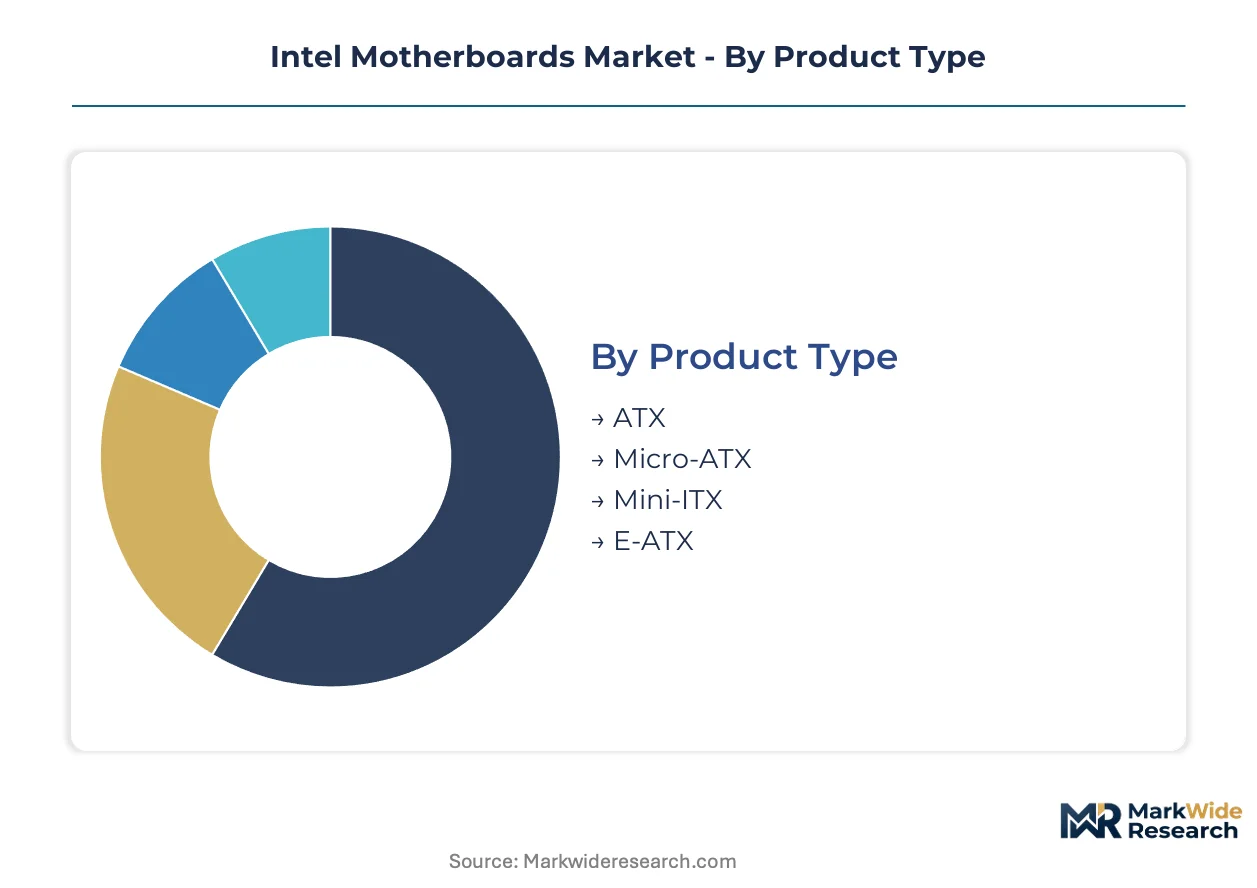
Intel motherboard segmentation reveals divergent optimization targets across thermal envelopes, expansion requirements, and procurement scale. Form factor and chipset selections directly constrain addressable end-use applications and margin profiles.
Product Type:
Volume shipments concentrate in mid-tower compatible formats, while premium positioning attaches to specialized thermal and expansion configurations.
- ATX:The 305mm × 244mm specification accommodates four DIMM slots and multiple PCIe x16 lanes for discrete graphics configurations. Demand clusters among United States DIY builders upgrading to Raptor Lake platforms with DDR5 memory channels, driven by backward-compatible chassis ecosystems that reduce total platform cost.
- Mini-ITX:A compact 170mm × 170mm footprint integrates voltage regulation and chipset functions onto denser PCB real estate. Germany's industrial automation sector sources fanless variants for edge computing nodes, constrained by thermal design power ceilings below 65W and extended temperature specifications.
- Micro-ATX:Mid-range expansion slot configurations serve budget-conscious system integrators with reduced PCIe lane requirements.
- E-ATX:Extended dimensions support dual-socket workstation and server deployments with enhanced power delivery phases.
Mature deployment sits with ATX. Newer deployment is concentrated in Mini-ITX.
Chipset:
Feature unlock tiers separate enthusiast overclocking capabilities from locked corporate fleet configurations.
- Z490:Unlocked multiplier support and expanded PCIe bifurcation options target enthusiast segments with liquid-cooled thermal headroom. United States gaming peripheral retailers report sustained attach rates with K-series processors, though Intel's socket roadmap transitions compress validation cycles for board partners.
- B460:Locked multiplier configurations with reduced PCIe lane allocation serve corporate fleet procurement at lower bill-of-materials cost. China's enterprise OEMs favor this tier for volume workstation contracts, prioritizing stability validation over frequency headroom.
- H470:Mid-tier feature segmentation with limited overclocking support occupies narrowing market position.
- H310:Entry-level chipset with minimal expansion capability serves cost-optimized embedded and education sector deployments.
Corporate standardization favors B460. Enthusiast upgrade cycles drive Z490.
Form Factor:
Physical dimensional constraints determine chassis compatibility and thermal management architecture.
- Standard:Conventional height profiles accommodate tower coolers and full-height expansion cards across ATX and Micro-ATX footprints. Hyperscale cloud operators in Germany specify standard-height server boards for rack-mounted deployment, balancing airflow requirements against density targets.
- Low Profile:Reduced vertical clearance enables 1U and 2U rack configurations with half-height PCIe slots. United States telecommunications equipment manufacturers qualify these variants for network appliance integration, constrained by passive cooling requirements and limited VRM phase counts.
- Extended:Non-standard dimensions support specialized workstation and storage server configurations with additional DIMM or PCIe slot capacity.
- Custom:OEM-specific layouts with proprietary mounting patterns serve defense and aerospace qualification programs under US CHIPS Act incentives.
Volume manufacturing concentrates on Standard. Custom variants are climbing the fastest among defense sector suppliers.
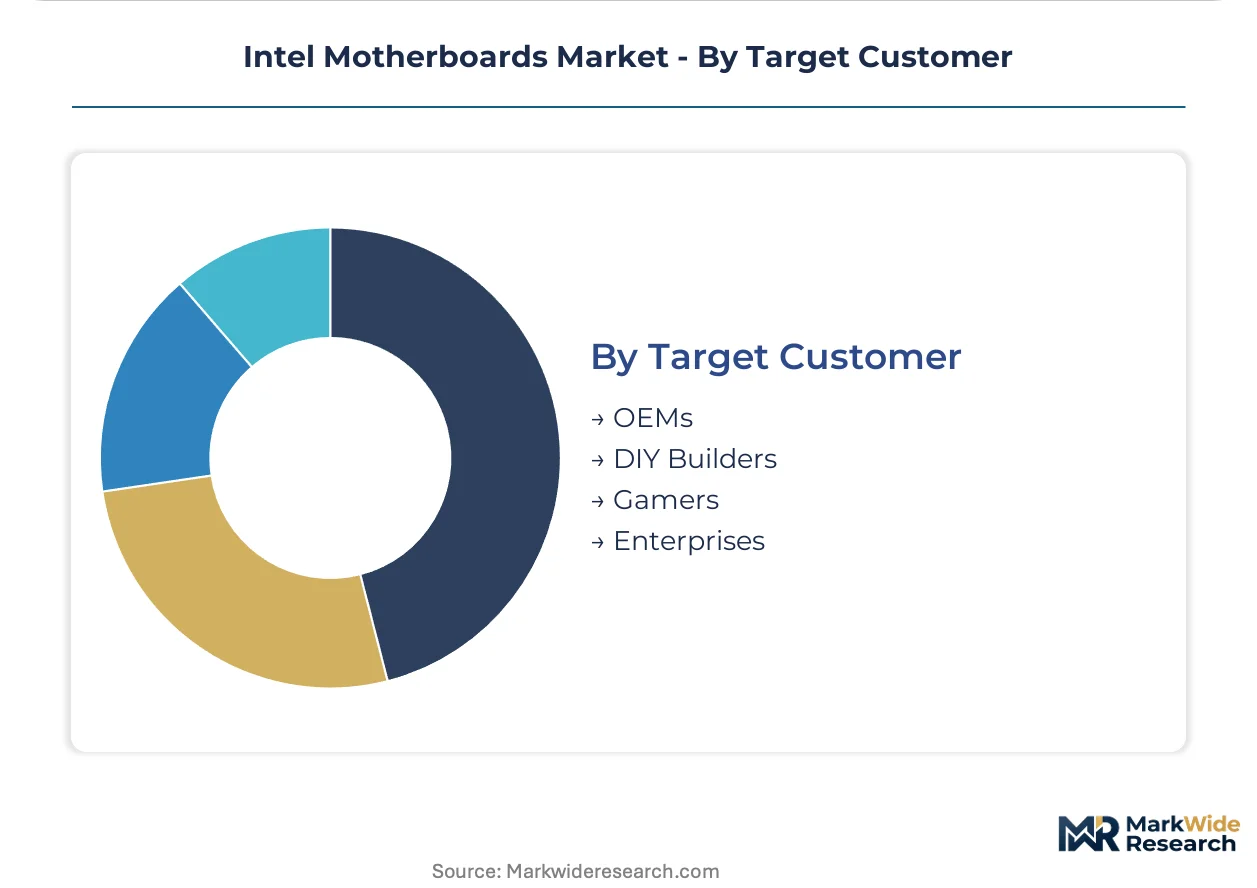
Target Customer:
Procurement scale and technical specification authority separate direct OEM negotiation from retail channel distribution.
- OEMs:Annual volume commitments with validated system configurations command prioritized chipset allocation and customized firmware. China's data center operators negotiate directly with ODMs for server-grade board supply, bypassing traditional distribution channels entirely.
- Enterprises:Multi-year fleet refresh cycles with standardized configurations prioritize remote management capabilities and supply continuity. Germany's automotive manufacturers specify enterprise-grade boards for manufacturing execution system deployments, requiring extended lifecycle guarantees.
- DIY Builders:Retail channel procurement with component-level selection drives enthusiast-focused feature marketing and BIOS differentiation.
- Gamers:AORUS and ROG sub-brand positioning targets RGB integration and overclocking utility software as secondary purchase factors.
Long-term supply agreements anchor OEM procurement. Gamer segment purchases are expanding most quickly through eSports venue buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise data centers and cloud infrastructure operators in the United States, China, and Germany account for the dominant share of server-grade motherboard procurement. Hyperscale buildouts and DDR5 transition cycles are compressing refresh timelines across these demand concentrations.
United States
Hyperscale operators in Northern Virginia and Oregon data center clusters are expanding LGA 1700 server board procurement for AI training infrastructure. FCC Part 15 electromagnetic compatibility certifications govern commercial distribution, with 5 GHz Wi-Fi 6E coexistence testing extending validation pipelines. Microsoft's Redmond campus and Amazon's Seattle engineering centers coordinate directly with ODMs on annual pricing frameworks.
China
MIIT network access licensing requirements for Wi-Fi 6E modules are mandating pre-certification testing at designated domestic laboratories. The country's national telecommunications regulator enforces GB standard electromagnetic compatibility thresholds distinct from Western regimes. Shenzhen and Shanghai host concentrated ODM assembly capacity serving domestic data center operators bypassing traditional distribution channels.
Germany
Automotive manufacturers in Bavaria and Baden-Württemberg specify enterprise-grade boards for manufacturing execution system deployments requiring extended lifecycle guarantees. EU RoHS Directive CE marking compliance accelerates board redesigns toward lead-free solder processes. Frankfurt's financial services sector drives rack-optimized server board demand for low-latency trading infrastructure.
Japan
METI industrial policy supports domestic semiconductor manufacturing equipment suppliers qualifying mSAP-capable substrate specialists. Tokyo and Osaka metropolitan areas concentrate advanced packaging R&D for high-layer-count PCB fabrication. Japanese telecommunications equipment manufacturers are qualifying alternative suppliers for 12-layer and above server boards.
South Korea
Seoul Capital Area cloud operators are negotiating direct procurement agreements with motherboard ODMs for virtualization density expansion. The country's national semiconductor regulator coordinates with MIIT on parallel Wi-Fi 7 certification pathways. Busan-Ulsan industrial corridors host assembly capacity for defense and aerospace qualification programs.
Intel Motherboards Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with enthusiast retail channels favoring feature-differentiated portfolios while hyperscale procurement flows through direct ODM negotiation. The vendor base organizes into three tiers: premium gaming specialists with sub-brand positioning, enterprise-focused rack-optimized suppliers, and volume-optimized system integrator channels. Strategic moves center on firmware engineering team expansion and mSAP fabrication qualification to address PCIe 5.0 signal integrity requirements.
Within the premium gaming tier, ASUS and Gigabyte Technology occupy positions defined by in-house BIOS development capabilities and reinforced power delivery sub-brand specialization. Supermicro anchors the enterprise server board segment through rack-optimized configurations. These three exemplify divergent competitive archetypes: enthusiast feature differentiation, gaming sub-brand premiumization, and hyperscale deployment validation.
| Leading Market Players |
|---|
| ASUS |
| MSI |
| Gigabyte Technology |
| ASRock |
| Intel |
| Supermicro |
| EVGA |
| Biostar |
| Advantech |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud operators in the United States and China negotiate annual pricing frameworks directly with ODMs, compressing margin pools for tier-two fabricators while concentrating volume leverage among direct procurement channels. This buyer concentration forces tiered pricing stratification across premium enthusiast boards, standard corporate fleet configurations, and economy embedded deployments.
Pricing Analysis
Volume shipments of ATX and Micro-ATX boards for system integrators operate on thin margins, while Z-series enthusiast chipsets and E-ATX server configurations retain premium positioning through unlocked overclocking capabilities and validated hyperscale supply agreements. Price differentiation hinges on certification grade—FCC Part 15 and CE marking compliance adds validation overhead—and volume scale, with annual commitments above ten thousand units unlocking prioritized chipset allocation. Pricing pressure stems from copper and epoxy resin commodity volatility, which compresses predictability for high-layer-count PCB fabricators. DIY builders in the United States exhibit highest price sensitivity, whereas enterprise OEMs prioritize supply continuity over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan's concentrated advanced substrate and chipset packaging capacity, where mSAP fabrication for PCIe 5.0 signal integrity requirements clusters among specialized suppliers. Manufacturing draws from Taiwan, China, and South Korea for high-density PCB laminates, voltage regulator modules, and DDR5 memory channel components. Raw material dependencies include copper foil, halogen-free epoxy resins, and low-loss dielectric substrates. Tariff exposure on Chinese-assembled boards creates structural risk for US-bound shipments. Distribution runs through direct ODM negotiation for hyperscale contracts, bypassing traditional tier-one distributors entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Intel motherboards market sits in a technology-transition phase as DDR5 memory architectures displace legacy DDR4 platforms and PCIe 5.0 signal integrity demands reshape PCB fabrication requirements.
For Market Incumbents: Lock in mSAP fabrication partnerships with Taiwanese and Japanese substrate specialists before qualification pipelines saturate, defending against emerging ODMs in Shenzhen and Shanghai. Prioritize firmware engineering team expansion to address UEFI/BIOS development scarcity, which constrains security-hardened customization velocity for enterprise OEMs. For New Entrants and Emerging Players: Capture white-space in Germany's industrial automation sector for fanless Mini-ITX boards with extended temperature specifications below 65W thermal design power. Target US defense and aerospace qualification programs under CHIPS Act incentives, where custom form factors face limited incumbent competition and multi-year contract visibility. For Investors and Strategic Acquirers: The window for entry favors vertically integrated ODMs with captive mSAP capability and validated hyperscale relationships. Board vendors with in-house BIOS development teams command scarcity premiums as firmware engineering talent concentrates among veteran developers. Watch Intel's socket roadmap transitions as the inflection indicator—accelerated LGA platform changes compress inventory cycles and reshape supplier prioritization.| Strategic Initiative | Industry Significance |
|---|---|
| mSAP Fabrication Qualification | Enables PCIe 5.0 server board supply to hyperscale operators in Northern Virginia and Oregon. |
| Firmware Engineering Expansion | Addresses UEFI/BIOS scarcity constraining security-hardened implementations for enterprise OEMs. |
| Direct ODM Procurement Frameworks | Bypasses tier-one distributors to capture annual volume commitments from Amazon and Microsoft. |
| CHIPS Act Defense Qualification | Unlocks custom form factor contracts with US aerospace primes requiring domestic assembly. |
| DDR5-PMIC VRM Simplification | Reduces board layer counts through converged power management IC integration onto memory modules. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with motherboard ODM procurement directors, BIOS firmware engineering leads, hyperscale cloud operator supply chain managers, and tier-two PCB fabricator plant managers. FCC Part 15 electromagnetic compatibility databases, MIIT network access license registries, EU RoHS compliance declarations, and SEC 10-K disclosures from branded motherboard vendors provided validation layers. Bottom-up shipment estimates by form factor and chipset tier reconciled against top-down motherboard attach rates to Intel CPU volume disclosures across the analysis window.
Data-stream reconciliation combined bill-of-materials cost modeling with channel inventory velocity tracking. Segmentation dimensions spanned form factor, chipset tier, target customer archetype, and regional regulatory cluster. CAGRs derived from fitted growth curves against historical refresh cycle patterns and DDR generational transition timelines. Industry-specific inputs included Intel socket roadmap disclosures, hyperscaler capex allocation patterns, and mSAP fabrication capacity expansion announcements from Japanese substrate specialists.
The model holds under stable Intel platform roadmap cadence and continued hyperscale data center expansion; deviation in copper commodity spikes or Taiwan supply disruptions would shift volume and value trajectories. Forecasts reflect documented assumptions regarding DDR5 adoption velocity and PCIe 5.0 signal integrity qualification timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Microcontroller Socket Market
Electronic Components
Ceiling Microphone Market
Electronic Components
Dual Relay Board Market
Electronic Components
Microspeaker Market
Electronic Components
Europe PCB Market
Electronic Components
Bluetooth Adapter Market
Electronic Components
SAW Filters Market
Electronic Components
Audio CODEC Market
Electronic Components
Passive Attenuator Market
Electronic Components
Special Function Data Convertors Market
Electronic Components
Bonding Wires and Ribbons Market
Electronic Components
RAID Controller Card Market
Electronic Components
Gigabit Interface Converter Market
Electronic Components
Timing Relay Market
Electronic Components
Impulse Relays Market
Electronic Components
Encoder Market