
 Microspeaker Market | 2026-2036
Microspeaker Market Size, Share, and Industry Trends Forecast 2026-2036
Microspeaker Market Foresight
Premium-grade acoustic performance is rotating microspeaker procurement toward balanced armature and electrostatic architectures. AAC Technologies leverages captive MEMS fabrication to control transducer consistency across smartphone and hearing aid programs. Goertek sustains massive coil winding and diaphragm stamping capacity for TWS and wearable OEMs in East Asia. Knowles Corporation dominates balanced armature supply for medical audio, anchoring its position through FDA-registered manufacturing lines.
A microspeaker is an electromechanical acoustic transducer, typically 4–15 mm in diameter, that converts electrical audio signals into sound pressure waves through a voice coil, diaphragm, and magnetic motor assembly. Dynamic variants use a moving-coil architecture with neodymium or ferrite magnets, while balanced armature designs employ a pivoted magnetic armature for higher efficiency in confined spaces. The balanced armature segment commands margin pools in hearing aid and high-fidelity in-ear applications where distortion thresholds below one percent justify unit premiums. Dynamic transducers lead volume in smartphone and portable audio systems where cost-per-decibel drives sourcing decisions. Bluetooth-enabled wireless architectures are displacing wired connections in wearable devices, shifting amplifier and DSP integration requirements upstream.
FDA acoustic output limits and EU MDR biocompatibility standards shape hearing aid microspeaker design, material selection, and market access pathways. China's MIIT enforces electromagnetic compatibility and audio quality certification for devices with integrated speakers, filtering import and domestic production. REACH substance restrictions in Europe constrain diaphragm polymer and magnet coating chemistries, raising reformulation costs for suppliers serving medical and consumer tiers. Stakeholders must monitor how FDA, EMA, and MIIT convergence on acoustic safety thresholds reshapes testing protocols and cross-border certification burdens.
Market Dynamics
The microspeaker market pivots on acoustic architecture substitution, as balanced armature and MEMS-based transducers displace dynamic coil designs in premium wearable and medical audio segments. This technological rotation compresses legacy supply chains while elevating precision manufacturing requirements.
Growth Catalysts
- EU MDR acoustic output mandates:Hearing aid manufacturers in Germany and Switzerland are accelerating procurement of balanced armature units to meet stricter biocompatibility and sound pressure limits, expanding the addressable premium component base.
- MEMS foundry clustering:Concentrated fabrication capacity in Guangdong and Jiangsu provinces enables rapid prototyping and scale-up for TWS earbud OEMs, shortening development cycles from months to weeks.
- Bluetooth Low Energy audio:The Auracast broadcast standard is decomposing wired amplifier-speaker pairings, forcing integration of DSP and amplification into microspeaker modules themselves.
Market Restraints
- Neodymium magnet supply concentration:Rare earth processing capacity clusters in China's Inner Mongolia region, exposing non-Chinese assemblers to export quota volatility and price spikes.
- REACH substance restrictions:European diaphragm polymer formulations face reformulation costs as ECHA adds candidate list substances, raising per-unit compliance burdens for medical-grade suppliers.
- Balanced armature technical ceiling:Pivoted armature designs struggle to reproduce sub-100 Hz frequencies without distortion, limiting their penetration in bass-forward consumer audio applications.
Strategic Opportunities
- Underpenetrated Indian hearing aid market:CDSCO streamlined medical device registration pathways create first-mover advantage for suppliers establishing local acoustic testing and assembly presence.
- Over-the-counter hearing aid channel:FDA 2022 deregulation of mild-to-moderate hearing loss devices opens direct-to-consumer distribution, bypassing audiology clinic gatekeepers.
- Electrostatic-MEMS convergence:Hybrid transducer architectures combining thin-film electrostatic actuation with silicon MEMS backplates promise sub-1% distortion at extended bandwidths for high-fidelity in-ear monitors.
Industry Challenges
- Acoustic engineer talent scarcity:Specialized voice coil winding and diaphragm tuning expertise concentrates among aging workforces in Japan and Germany, constraining capacity expansion.
- ISO 10993 biocompatibility certification timelines:Extended cytotoxicity and sensitization testing for skin-contact hearing aid components stretches product launch schedules by 8-14 months.
- Legacy amplifier integration friction:Class-D and Class-G amplifier architectures in existing wearable designs require impedance matching redesigns to accommodate new microspeaker electrical characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microspeaker Market |
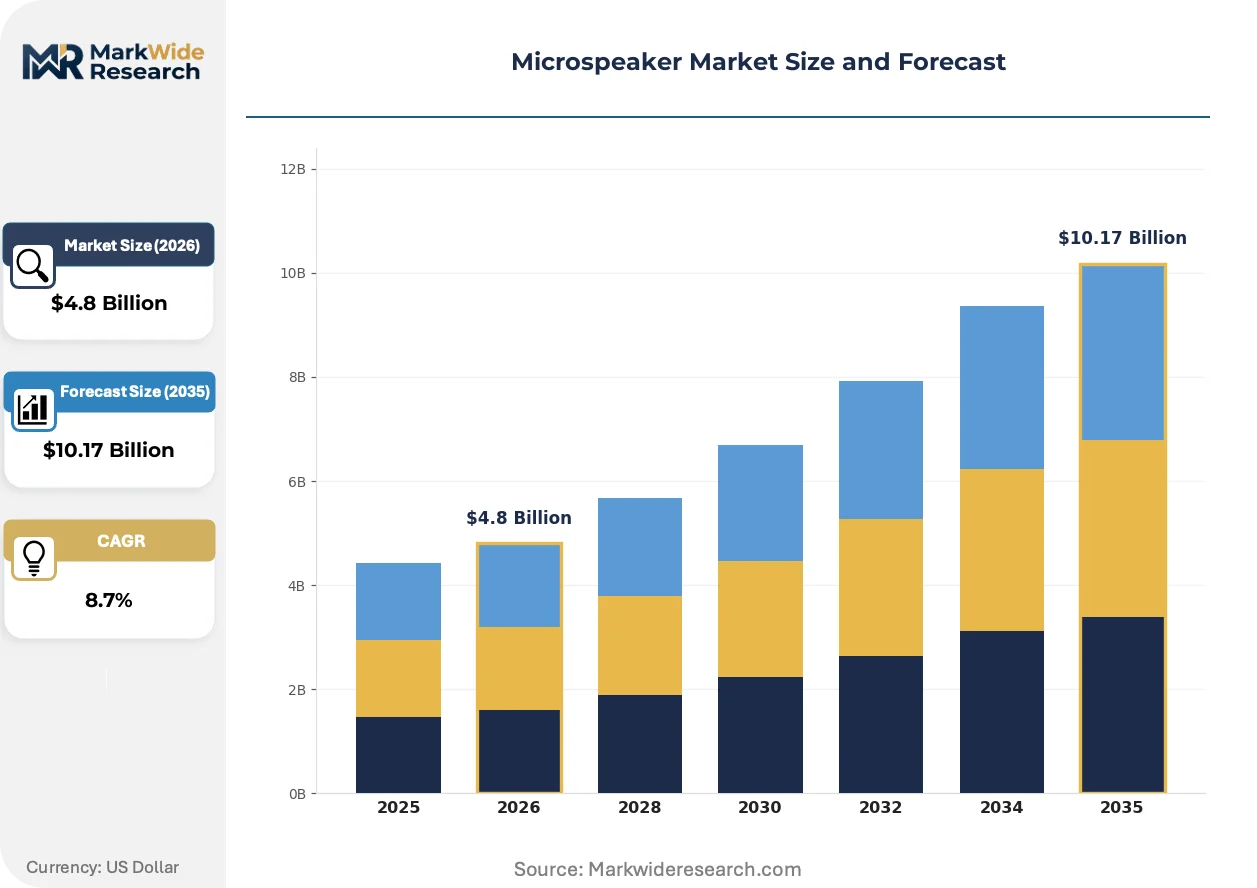
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balanced Armature, Dynamic, Piezoelectric, Electrostatic End User: Consumer Electronics, Automotive, Medical Devices, Industrial Equipment Technology: Bluetooth, Wired, Digital, Analog Application: Smartphones, Hearing Aids, Wearable Devices, Audio Systems |
| Companies Covered | Hosiden Corporation, Merry Electronics, AAC Technologies, Em-tech, TDK Corporation, Goertek, Foster Electric, Bulecom, Knowles Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microspeaker Market Shifts & Advancements
Acoustic transducer miniaturization is intersecting with semiconductor process migration, yielding speaker modules that embed active amplification and digital signal processing within millimeter-scale footprints. This convergence is redrawing competitive boundaries between acoustic component houses and silicon foundries.
Silicon MEMS microspeakers are decomposing the traditional voice coil-magnet-diaphragm stack into monolithic structures fabricated through DRIE and wafer bonding processes. Smartphone and TWS OEMs in South Korea and Taiwan are qualifying these devices for mid-range audio applications. The elimination of manual coil winding and diaphragm lamination is compressing bill-of-materials costs while tightening frequency response consistency.
EU MDR biocompatibility requirements are forcing hearing aid microspeaker suppliers to migrate from brominated flame retardants and certain phthalate plasticizers in housing and diaphragm materials. Manufacturers serving European medical audio markets are establishing dedicated cleanroom assembly lines with full material traceability. The regulatory burden falls heaviest on mid-tier suppliers lacking in-house toxicology and regulatory affairs capabilities.
Audiology clinic procurement is fragmenting as over-the-counter hearing aid channels capture mild-to-moderate loss segments previously gatekept by dispenser networks. Direct-to-consumer brands are sourcing microspeakers through contract manufacturers rather than established hearing aid OEM supply chains. This channel bifurcation is most visible in the United States following FDA deregulation, with similar regulatory reviews underway in Australia and the United Kingdom.
Microspeaker Market Segmentation
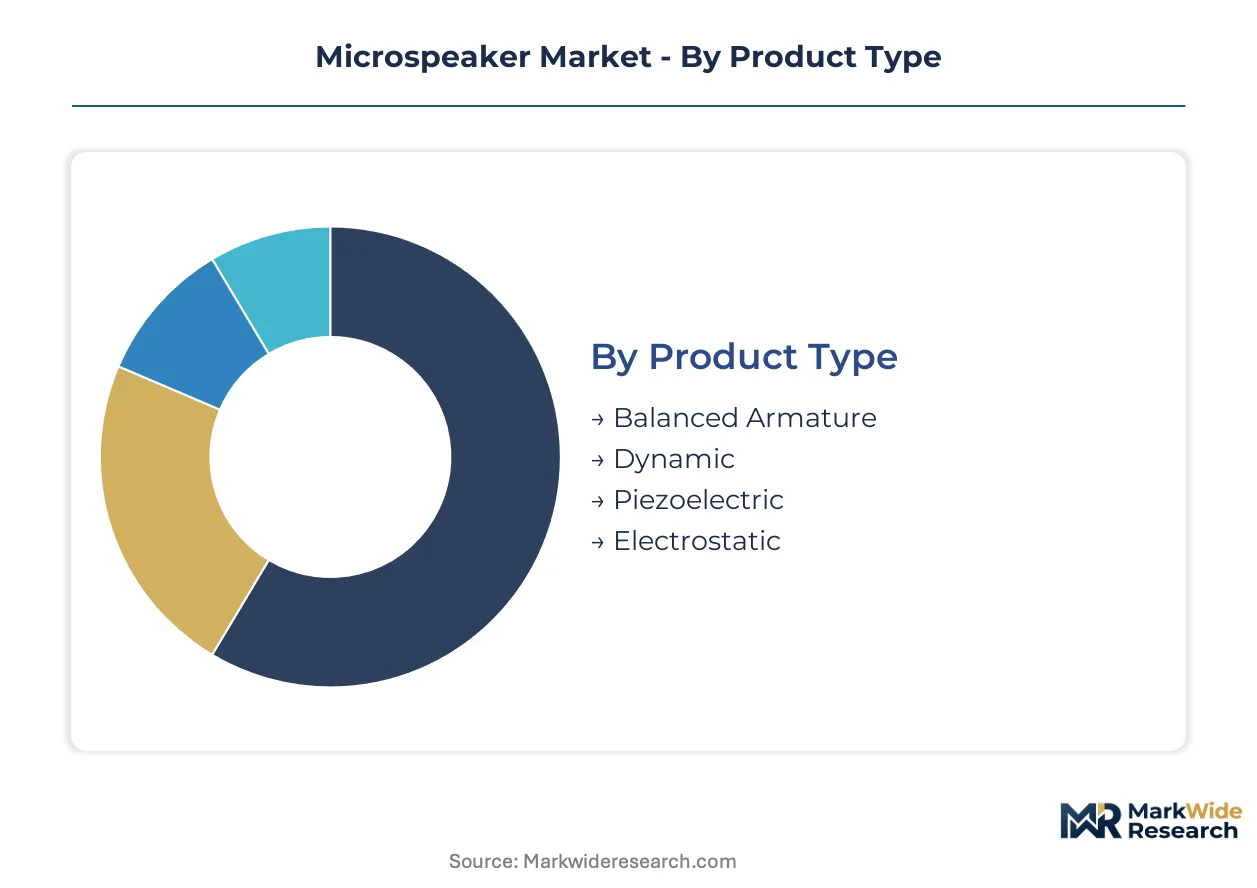
Acoustic transducer architectures diverge sharply across certification tiers, with medical-grade hearing aid components facing EU MDR biocompatibility mandates that consumer smartphone speakers bypass entirely. This regulatory stratification fragments procurement channels, tooling investments, and margin structures within supplier portfolios.
Product Type:
FDA acoustic output limits and EU MDR sound pressure thresholds differentiate material selection, magnet shielding, and diaphragm excursion tolerances across electromechanical architectures.
- Balanced Armature:Pivoted magnetic armature designs achieve sub-1% total harmonic distortion in confined acoustic volumes through precision-wound coils and rare-earth magnet assemblies. Hearing aid manufacturers in Germany and Switzerland source these units under stricter EU MDR biocompatibility requirements, paying premiums for ISO 10993-certified material traceability.
- Dynamic:Moving-coil architectures with neodymium or ferrite motors dominate smartphone and portable audio volumes where cost-per-decibel drives procurement decisions. Guangdong and Jiangsu province assemblers maintain massive coil winding and diaphragm stamping capacity for TWS earbud OEMs serving East Asian consumer electronics brands.
- Piezoelectric:Ceramic actuator elements enable ultra-thin form factors in wearable notification alerts and haptic-audio hybrid modules.
- Electrostatic:Thin-film diaphragm-voltage grid configurations serve high-fidelity in-ear monitor applications demanding extended frequency bandwidth.
Dynamic transducers handle the majority of throughput; balanced armature is gaining share fastest on hearing aid premiumization.
End User:
Customer procurement patterns split between high-volume consumer contracts with 90-day payment cycles and medical device tenders requiring 18-month certification timelines.
- Consumer Electronics:Smartphone and TWS earbud OEMs in South Korea and Taiwan drive massive unit demand with compressed development cycles. MEMS foundry clustering in China's Guangdong province enables rapid prototyping turnaround from months to weeks for Bluetooth-enabled audio modules.
- Medical Devices:Hearing aid manufacturers face FDA acoustic output limits and EU MDR biocompatibility standards that stretch material qualification and assembly validation timelines. Swissmedic-registered production lines in Switzerland anchor premium component supply for European audiology markets.
- Automotive:Cabin notification systems and headrest audio arrays demand extended temperature tolerance and vibration resistance specifications.
- Industrial Equipment:Voice annunciation and alarm systems prioritize SPL output and environmental sealing over frequency response fidelity.
Consumer electronics commands absolute unit volume; medical devices shows the steepest expansion trajectory on aging demographics and OTC channel deregulation.
Technology:
Wireless protocol migration is decomposing traditional amplifier-speaker pairings and redistributing DSP and amplification functions into microspeaker modules themselves.
- Bluetooth:Low Energy Audio and Auracast broadcast standards are displacing wired connections in wearable devices, forcing integration of active amplification into millimeter-scale transducer footprints. Taiwan-based TWS OEMs qualify silicon MEMS microspeakers with embedded Class-D drivers for mid-range audio applications.
- Wired:Legacy 3.5mm and proprietary connector configurations persist in professional audio monitoring and cost-optimized smartphone accessories where BOM compression outweighs wireless convenience premiums.
- Digital:I2S and USB-C audio interfaces enable direct DSP-to-transducer signal paths, eliminating analog amplifier stages in flagship smartphone designs.
- Analog:Resistive impedance matching with Class-AB amplifiers remains prevalent in hearing aid designs prioritizing battery life over feature integration.
Bluetooth absorbs the majority of new design wins; digital interface adoption is climbing fastest on smartphone connector consolidation.
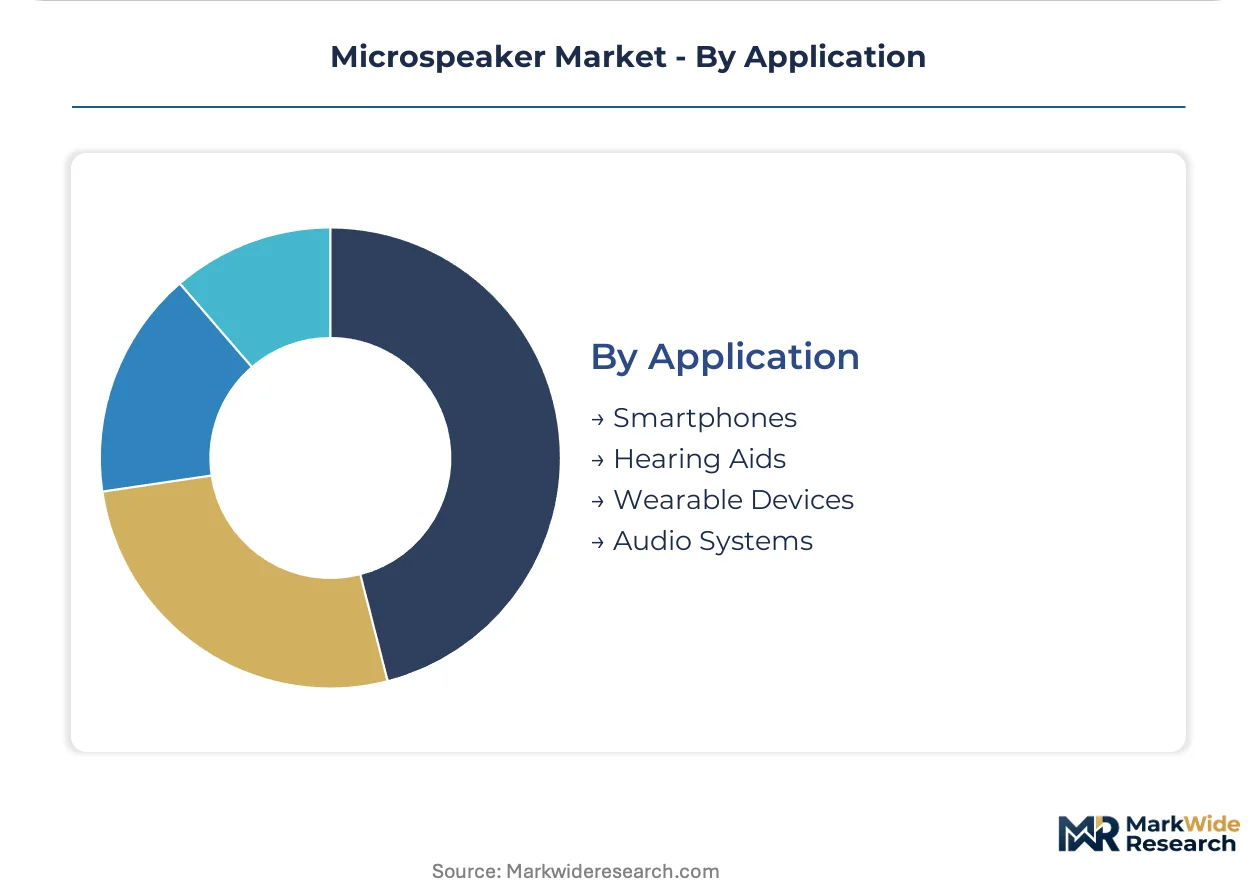
Application:
Form factor constraints and acoustic performance specifications diverge across pocketable consumer devices, medical wearables, and fixed installation audio systems.
- Smartphones:Stereo and multi-array configurations demand sub-4mm height profiles with IP68 environmental sealing, pushing suppliers toward MEMS fabrication and automated assembly. South Korean OEMs qualify electrostatic-MEMS hybrid architectures for flagship tier differentiation.
- Hearing Aids:Behind-the-ear and in-the-canal formats require biocompatible housing materials and distortion thresholds below one percent for speech intelligibility certification. FDA 2022 OTC deregulation is fragmenting procurement channels as direct-to-consumer brands bypass traditional audiology clinic gatekeepers.
- Wearable Devices:TWS earbuds and smartwatch audio outputs prioritize power efficiency and rapid charging compatibility over extended bass response.
- Audio Systems:Smart speaker and soundbar applications leverage larger diaphragm excursions and passive radiator coupling for room-filling output.
Smartphones generates the highest absolute shipment volumes; hearing aids is expanding most quickly on regulatory channel opening and demographic tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China maintains a substantial export surplus in microspeaker assemblies, shipping finished transducers to smartphone OEMs in South Korea and Taiwan while importing rare-earth magnet precursors from Inner Mongolia processors. This trade configuration shapes procurement timelines and inventory strategies across East Asian electronics supply chains.
China
Guangdong and Jiangsu provinces host dense clusters of MEMS foundries and acoustic assembly operations serving TWS earbud and smartphone manufacturers. MIIT enforces electromagnetic compatibility and audio quality certification for devices with integrated speakers, filtering both import and domestic production. Shenzhen and Dongguan factories compress prototyping cycles from months to weeks through vertically integrated coil winding and diaphragm stamping capacity.
Germany
Hearing aid manufacturers in Baden-Württemberg and Bavaria are expanding procurement of balanced armature units to meet EU MDR acoustic output and biocompatibility requirements. ECHA REACH substance restrictions constrain diaphragm polymer and magnet coating chemistries, raising reformulation costs for suppliers serving medical tiers. Stuttgart and Munich anchor precision acoustic engineering talent pools concentrated among aging workforces.
Switzerland
Swissmedic-registered production lines in the Zurich and Basel regions anchor premium component supply for European audiology markets. Hearing aid OEMs source balanced armature transducers under stricter EU MDR sound pressure limits, paying premiums for ISO 10993-certified material traceability. The country's precision manufacturing heritage supports sub-1% distortion threshold requirements for speech intelligibility certification.
South Korea
Seoul-based smartphone OEMs are qualifying silicon MEMS microspeakers with embedded Class-D drivers for mid-range audio applications. MFDS regulates medical device acoustic output for hearing aids distributed domestically, though most Korean manufacturers serve export markets. Suwon and Gyeonggi Province house R&D centers developing electrostatic-MEMS hybrid architectures for flagship tier differentiation.
United States
FDA 2022 deregulation of over-the-counter hearing aids for mild-to-moderate loss has fragmented procurement channels as direct-to-consumer brands bypass traditional audiology clinic gatekeepers. Domestic assembly operations concentrate in Massachusetts and Minnesota near legacy hearing aid engineering centers. The regulatory shift is pulling balanced armature demand toward consumer electronics contract manufacturers rather than established medical device supply chains.
Microspeaker Market Competitive Landscape
Listed leaders compete with private specialists across acoustic architecture specialization, with publicly traded component houses facing off against privately held precision manufacturers. The vendor base stratifies into three tiers: scale-driven dynamic transducer suppliers, premium balanced armature specialists, and emerging MEMS fabrication entrants. Consolidation pressure runs highest in the middle tier, where mid-cap acoustic houses lack the capital intensity for MEMS process migration or the regulatory infrastructure for medical certification. Dominant competitive moves include captive MEMS foundry investments and backward integration into rare-earth magnet supply.
Within the premium balanced armature tier, Knowles Corporation and AAC Technologies occupy positions defined by regulatory infrastructure and fabrication control. Knowles anchors medical audio supply through FDA-registered manufacturing lines, while AAC Technologies leverages captive MEMS fabrication to govern transducer consistency across smartphone and hearing aid programs. Goertek sits within the scale-driven tier, sustaining massive coil winding and diaphragm stamping capacity for TWS and wearable OEMs in East Asia. These three exemplify how competitive positioning derives from either regulatory certification depth, upstream process control, or manufacturing scale rather than product differentiation alone.
| Leading Market Players |
|---|
| Hosiden Corporation |
| Merry Electronics |
| AAC Technologies |
| Em-tech |
| TDK Corporation |
| Goertek |
| Foster Electric |
| Bulecom |
| Knowles Corporation |
| Others |
Supply & Pricing Matrix
EU MDR biocompatibility certification gates both supplier qualification and price differentiation, forcing hearing aid microspeaker vendors to absorb ISO 10993 testing costs that consumer-tier suppliers bypass entirely. This regulatory bifurcation splits procurement channels into premium medical-grade streams with 18-month validation timelines and high-volume consumer contracts with compressed payment cycles.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in this market. Price differentiation stems from certification grade—FDA-registered manufacturing commands premiums over MIIT-compliant consumer tiers—and volume scale, with smartphone OEMs extracting discounts through multi-million unit commitments. Cost compression in standard-tier dynamic transducers is intensifying because Guangdong assemblers compete on coil winding automation. Smartphone and TWS OEMs exhibit highest price sensitivity, while Swiss hearing aid manufacturers accept premiums for distortion thresholds below one percent.
Supply Chain Analysis
Strategic stockpiling of rare-earth magnet precursors dominates inventory strategy as neodymium processing capacity clusters in China's Inner Mongolia region. Supply concentrates in China, South Korea, and Taiwan, with Guangdong and Jiangsu provinces hosting MEMS foundries and acoustic assembly clusters. Raw material dependencies include neodymium-iron-boron magnets, polyimide diaphragm films, and copper voice coil wire. Single-source vulnerability in rare-earth processing exposes non-Chinese assemblers to export quota volatility. Distribution runs through vertically integrated contract manufacturers serving TWS and smartphone OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 2022 OTC deregulation and Auracast broadcast standardization are converging to disrupt legacy audiology procurement channels, opening direct-to-consumer pathways that bypass traditional clinic gatekeepers.
For Market Incumbents: Compound regulatory certification depth to defend against MEMS-based entrants. Invest in captive MEMS fabrication capacity in Guangdong or Jiangsu to match AAC Technologies' upstream control. Secure ISO 10993 biocompatibility pipelines ahead of EU MDR enforcement expansion. Voice coil winding automation in East Asian facilities preserves margin position against price erosion in standard-tier dynamic transducers. For New Entrants and Emerging Players: Differentiate on electrostatic-MEMS hybrid architectures for high-fidelity in-ear monitor applications where distortion thresholds below one percent justify unit premiums. Target India's underpenetrated hearing aid market through CDSCO-streamlined registration pathways and local acoustic testing partnerships. Pursue over-the-counter hearing aid channel relationships with direct-to-consumer brands bypassing traditional audiology networks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across silicon MEMS microspeaker fabrication as DRIE and wafer bonding processes displace manual coil winding. Long-term viability favors suppliers with backward integration into rare-earth magnet supply or captive MEMS foundry control. Acquisition targets include mid-tier acoustic houses lacking regulatory infrastructure for medical certification but holding precision engineering talent pools in Japan or Germany. Watch FDA-EU MDR convergence on acoustic safety thresholds as inflection indicator for testing protocol consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Captive MEMS Foundry Investment | AAC Technologies controls transducer consistency across smartphone and hearing aid programs through in-house fabrication. |
| ISO 10993 Certification Pipeline | Knowles Corporation anchors medical audio supply through biocompatibility-tested manufacturing lines registered with FDA. |
| Rare-Earth Magnet Backward Integration | Goertek secures neodymium supply chains against Inner Mongolia export quota volatility through upstream partnerships. |
| OTC Channel Partnership Development | Direct-to-consumer hearing aid brands fragment procurement away from traditional audiology clinic networks. |
| Electrostatic-MEMS Hybrid R&D | South Korean OEMs qualify sub-1% distortion architectures for flagship smartphone audio differentiation. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hearing aid OEM procurement directors, MEMS foundry engineering leads, TWS contract manufacturing executives, and acoustic component regulatory affairs managers. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, MIIT certification registries, SEC supplier disclosure filings, and customs trade data for rare-earth magnet precursors. Bottom-up unit shipment estimates were triangulated against top-down market value reconstructions.
Across the analysis window, volume and value outputs were modeled through segmentation by acoustic architecture—balanced armature, dynamic, piezoelectric, electrostatic—and by end-use application including smartphones, hearing aids, TWS earbuds, and automotive cabin systems. CAGRs were derived from regression analysis against smartphone shipment trajectories, hearing aid demographic penetration curves, and Bluetooth Low Energy audio adoption rates. Forecast inputs incorporated MEMS process migration timelines and EU MDR biocompatibility compliance cost curves.
The analysis sits within stated boundaries; outcomes outside sustained rare-earth supply stability or accelerated MEMS yield improvement would require recalibration. Forecasts reflect assumptions regarding regulatory enforcement consistency and foundry capacity expansion schedules. Revision becomes warranted when FDA-EU MDR acoustic safety threshold convergence crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Audio Transistors Market
Electronic Components
5G Base Station BAW Filters Market
Electronic Components
Digital Pulse Mixer Market
Electronic Components
Crystal Oscillators Market
Electronic Components
Resonators Market
Electronic Components
Asia-Pacific USB Retimer Market
Electronic Components
Frequency Control and Timing Devices Market
Electronic Components
Handheld Devices Battery Market
Electronic Components
Digital Electronic Detonator Market
Electronic Components
IF Digital Attenuator Market
Electronic Components
Digital Class-D Amplifier Market
Electronic Components
Printed Circuit Board Market
Electronic Components
Stretchable Conductors in Electronics Market
Electronic Components
Electromechanical Timers Market
Electronic Components
Flexible Heater Market
Electronic Components
Global Multilayer Varistors Market