
 Sample Rate Converters Market | 2026-2036
Sample Rate Converters Market Size, Share, and Industry Trends Forecast 2026-2036
Sample Rate Converters Market Analytics
Aftermarket service revenue for legacy broadcast equipment is fragmenting across distributed cloud-based audio processing platforms. Analog Devices Inc. leverages its converter IP portfolio to sustain premium positioning in studio-grade applications. Texas Instruments anchors its strategy through integrated DSP-to-converter bundles that reduce BOM complexity for OEMs. Cirrus Logic competes by specializing in low-latency architectures for automotive infotainment systems.
Sample rate converters are electronic circuits or digital signal processing blocks that transform audio signals between different sampling frequencies, typically operating with 24-bit resolution and supporting rates from 8 kHz to 384 kHz to maintain fidelity across disparate digital audio systems. Their primary purpose is to eliminate clock-domain mismatches in professional audio, telecommunications, and automotive environments where multiple digital sources must synchronize without audible degradation. Integrated converter solutions now dominate volume shipments by embedding clock recovery and jitter reduction within single-chip audio codecs, while FPGA-based implementations capture the fastest-growing niche among broadcast engineers demanding field-reconfigurable processing pipelines. Standalone hardware persists in premium studio recording segments where dedicated clocking infrastructure commands sustained margin pools from mastering engineers and post-production facilities.
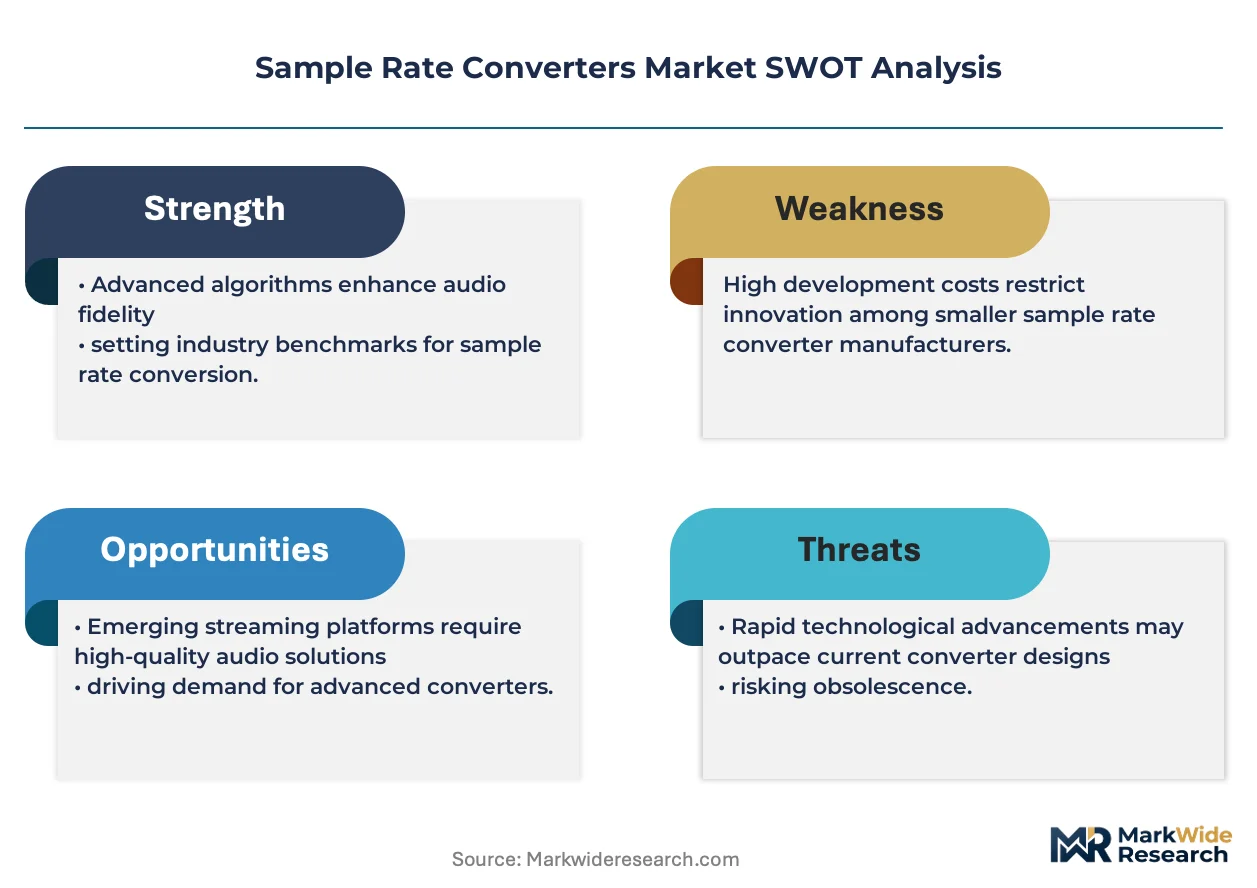
FCC equipment authorization rules shape product access for US-bound broadcast and telecommunications converters, while CE marking under the EU Radio Equipment Directive governs electromagnetic compatibility for European distribution. Japan's METI enforces energy-efficiency benchmarks that directly influence converter power budgets in automotive and portable applications. Stakeholders must monitor how emerging AI-driven audio generation tools will recalibrate latency and fidelity requirements across professional and consumer deployment tiers.
Market Dynamics
Broadcast infrastructure modernization across developed economies is compressing upgrade cycles for audio processing equipment, while automotive OEMs in Germany and Japan embed sample rate conversion directly into centralized compute architectures rather than distributed audio nodes.
Growth Catalysts
- F-Gas Regulation:The European Union's F-Gas Regulation mandates energy-efficient semiconductor designs, pushing converter manufacturers toward lower-power architectures that reduce thermal management costs in broadcast and automotive applications.
- Automotive Infotainment Clustering:Germany's automotive audio ecosystem concentrates R&D investment in zonal audio architectures requiring high-fidelity clock-domain translation between entertainment, navigation, and safety systems.
- Cloud-Based Audio Processing:Distributed cloud platforms for live broadcast production are expanding addressable service revenue beyond hardware shipments, creating recurring revenue streams from remote mastering and post-production workflows.
Market Restraints
- Silicon Supply Concentration:Advanced CMOS foundry capacity for mixed-signal audio ICs concentrates in Taiwan and South Korea, exposing converter suppliers to geopolitical disruption and allocation constraints during demand spikes.
- Legacy Equipment Longevity:Studio-grade standalone converters from the 2010s maintain functional performance for 15-20 year lifecycles, depressing replacement demand in professional audio segments despite feature advancements.
- Integrated Codec Substitution:System-on-chip audio solutions from mobile and consumer electronics suppliers are absorbing mid-tier converter functionality, compressing addressable market for discrete components in cost-sensitive applications.
Strategic Opportunities
- AI-Generated Audio Workflows:Generative audio tools are creating latency-critical production pipelines where real-time sample rate conversion with sub-millisecond delay becomes a technical differentiator for hardware vendors.
- India Broadcast Digitization:India's terrestrial television and radio infrastructure modernization is opening procurement channels for professional audio equipment as content production standards align with international broadcast specifications.
- Automotive Software-Defined Audio:Convergence of Ethernet-based audio transport (AVB/TSN) with AI-powered cabin acoustics is requiring programmable converter architectures that adapt to over-the-air feature updates.
Industry Challenges
- Clock Jitter Engineering Talent:Specialized expertise in ultra-low-jitter PLL design for professional audio applications is scarce, with competition from 5G and data center timing markets draining available engineering pools.
- Multi-Domain Certification Overlap:Converters deployed in automotive infotainment must simultaneously satisfy AEC-Q100 reliability, FCC electromagnetic authorization, and OEM-specific acoustic validation protocols, extending qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sample Rate Converters Market |
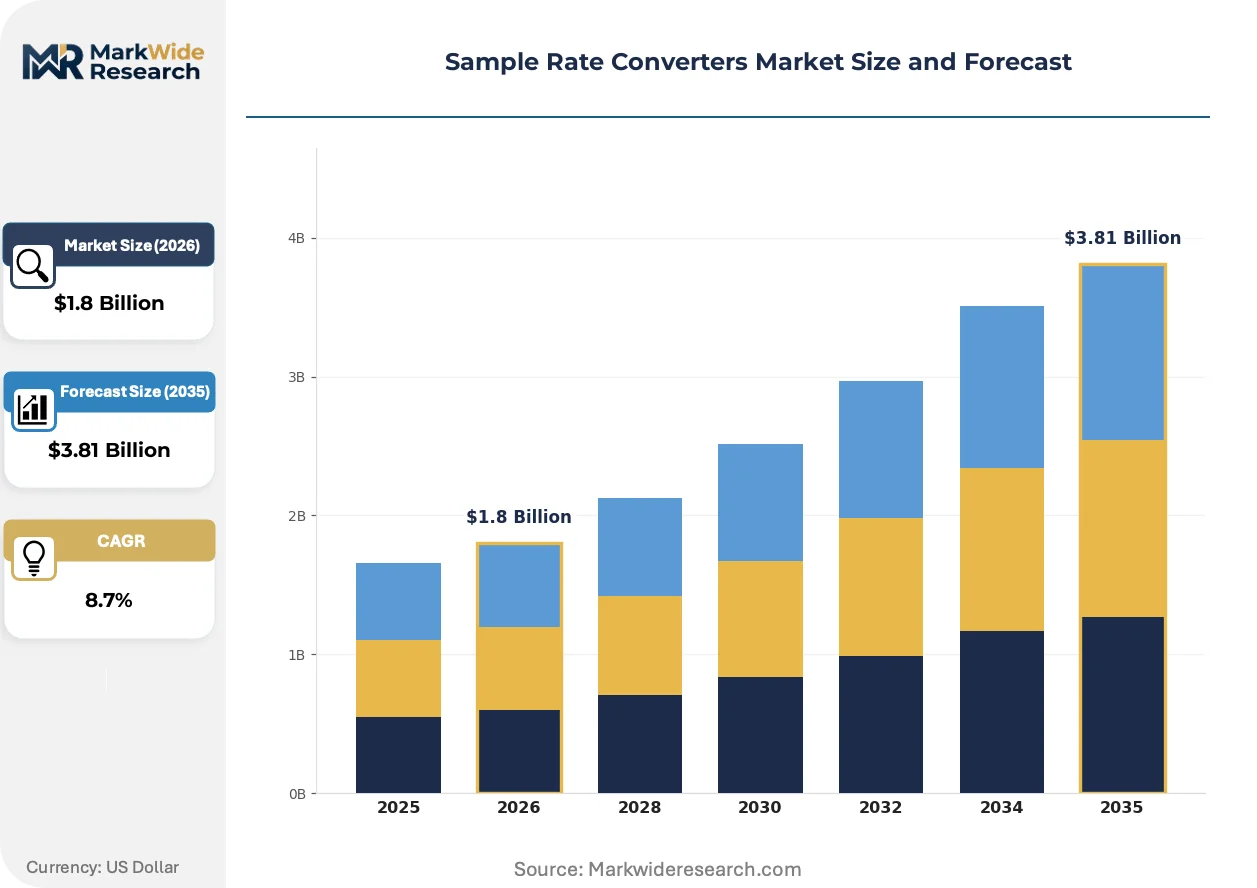
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
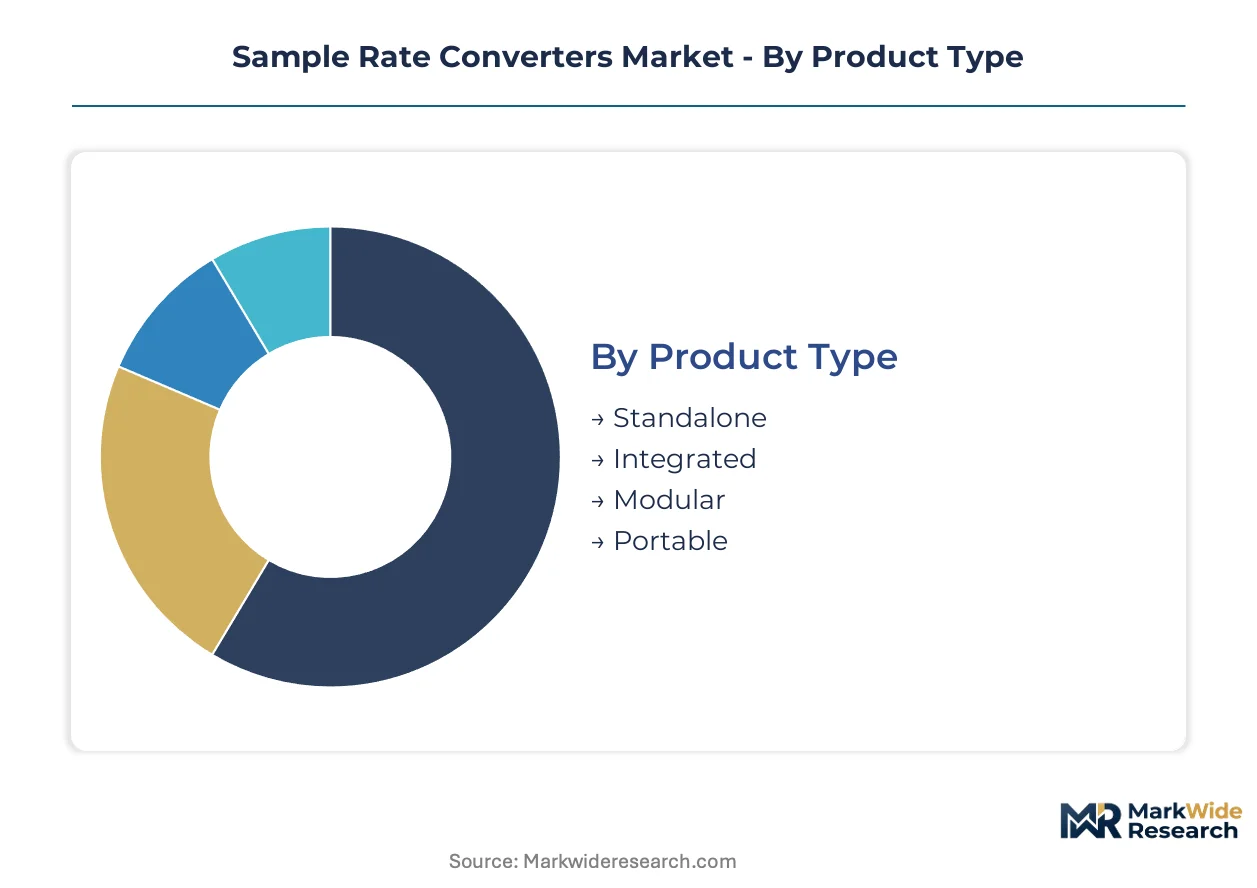
| Segmentation | Product Type: Standalone, Integrated, Modular, Portable Technology: Analog, Digital, Hybrid, FPGA End User: Broadcast, Music Production, Telecommunications, Automotive Application: Live Sound, Studio Recording, Post-Production, Audio Processing |
| Companies Covered | Analog Devices Inc., Texas Instruments, Cirrus Logic, STMicroelectronics, NXP Semiconductors, Microchip Technology, Infineon Technologies, Tempo Semiconductor, Renesas Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sample Rate Converters Market Evolving Landscape
Sample rate converter technology is migrating from hardware-centric implementations toward software-defined architectures, while regulatory pressure on energy consumption and broadcast spectrum efficiency reshapes product roadmaps across supplier tiers.
FPGA-based converter implementations are migrating from niche prototyping tools to mainstream broadcast deployment. Live production engineers in North America and Europe now reconfigure processing pipelines between events rather than swapping dedicated hardware. This flexibility is compressing capital expenditure cycles for regional broadcasters while elevating technical service contracts as recurring revenue anchors.
The European Union's F-Gas Regulation is tightening energy-efficiency benchmarks for electronic equipment sold across member states. Converter manufacturers must now demonstrate reduced standby power and thermal load to maintain CE marking eligibility. Automotive and portable audio segments face the steepest redesign requirements, with engineering teams prioritizing dynamic voltage scaling over static power-optimized architectures.
Aftermarket service models are fragmenting across subscription-based cloud processing platforms. Traditional hardware vendors face disintermediation as broadcast and post-production facilities rent conversion capacity by the hour rather than owning depreciating assets. Japan's precision electronics manufacturers and Germany's automotive suppliers show the strongest resistance to this shift, defending installed-base relationships through integrated hardware-software bundles.
Sample Rate Converters Market Segmentation
Sample rate converter procurement cycles diverge sharply across deployment contexts. Broadcast infrastructure refreshes every 7-10 years while automotive platforms lock designs for entire vehicle generations. Understanding these temporal patterns illuminates where suppliers can capture recurring revenue versus one-time equipment sales.
Product Type:
Replacement velocity separates these segments by a factor of three, with portable and modular solutions turning over fastest against decade-long studio hardware lifecycles.
- Standalone:Rack-mounted hardware units with dedicated clocking infrastructure and balanced I/O connectivity serve mastering engineers in post-production facilities. Demand clusters in Germany's professional audio corridor and Japan's broadcast equipment supply chain, constrained by 15-20 year functional longevity that depresses replacement frequency despite feature advancements.
- Integrated:Single-chip audio codecs embedding sample rate conversion alongside ADC/DAC stages dominate automotive infotainment and mobile device shipments. Germany's automotive OEMs and Japan's precision electronics manufacturers drive specification requirements through centralized compute architectures rather than distributed audio nodes.
- Modular:Card-based systems for broadcast trucks and live event production allow field-swappable configuration. North American rental houses favor these for touring productions.
- Portable:Battery-powered USB and Thunderbolt interfaces target location recording and content creator workflows. India's emerging broadcast digitization programs source these for field journalism applications.
Integrated solutions anchor the volume base while portable units gain share at the steepest rate.
Technology:
Cost stratification runs deepest here, with analog implementations commanding premium positioning against digital volume production and hybrid mid-tier positioning.
- Digital:DSP-based conversion algorithms executing polyphase filter banks with 24-bit precision and 192 kHz capability serve telecommunications infrastructure and consumer electronics. India's TRAI broadcast digitization mandates and Japan's METI efficiency benchmarks shape power-performance tradeoffs in high-volume deployments.
- FPGA:Field-programmable gate arrays enable real-time pipeline reconfiguration for live broadcast engineers demanding format flexibility between events. North American regional broadcasters and European live production houses compress capital expenditure cycles through rental-based access models.
- Analog:Discrete resistor-ladder and switched-capacitor architectures persist in audiophile mastering chains. Limited shipments sustain margin pools.
- Hybrid:Combined analog front-end with digital processing core splits cost-performance optimization. Germany's automotive audio suppliers evaluate these for zonal architectures.
Digital platforms carry the volume weight while FPGA implementations expand most quickly among professional tiers.
End User:
Customer concentration patterns reveal automotive as the most consolidated buyer pool against fragmented music production demand.
- Automotive:OEMs in Germany and Japan embed sample rate conversion within centralized zonal audio processors coordinating entertainment, navigation, and safety system clocks. AEC-Q100 reliability requirements and OEM-specific acoustic validation protocols extend qualification timelines beyond 24 months.
- Broadcast:Terrestrial television and radio operators across North America and Europe modernize infrastructure for high-resolution audio distribution. India's terrestrial digitization programs open procurement channels as content standards align with international specifications.
- Music Production:Independent studios and project facilities purchase discrete converters for tracking and mixing workflows. Highly fragmented demand complicates direct sales coverage.
- Telecommunications:Network equipment manufacturers integrate conversion for voice-over-IP gateway interoperability. Carrier infrastructure refresh cycles drive replacement demand.
Automotive procurement anchors revenue stability while broadcast replacement cycles show the steepest near-term expansion trajectory.
Application:
Margin structure inverts between live sound's rental depreciation model and studio recording's capital equipment ownership.
- Studio Recording:Tracking rooms and control rooms demand sub-nanosecond jitter performance for multi-channel orchestral and ensemble capture. Germany's classical music production ecosystem and Japan's anime scoring facilities sustain premium positioning for dedicated clocking infrastructure.
- Post-Production:Film and television mixing stages require format conversion between production audio, foley, and final mix deliverables. Cloud-based processing platforms fragment traditional hardware revenue in North American and European facilities.
- Live Sound:Touring productions and installed venues prioritize ruggedized reliability over absolute fidelity. Rental house depreciation schedules compress effective selling prices.
- Audio Processing:Broadcast chain signal conditioning and telecommunications transcoding emphasize latency minimization over audiophile performance metrics.
Studio recording defends the margin peak while post-production shows the fastest share gain through cloud displacement of owned hardware.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan consume sample rate converters through automotive zonal architectures, while the United States and India deploy them through broadcast infrastructure and field production workflows respectively.
United States
FCC equipment authorization rules govern electromagnetic compatibility for broadcast and telecommunications converters entering US distribution. Regional broadcasters across the Midwest and Southeast modernize infrastructure for high-resolution audio distribution. Live production rental houses in Nashville and Los Angeles favor modular card-based systems for touring productions.
Germany
Germany's automotive audio cluster concentrates R&D investment in zonal architectures requiring high-fidelity clock-domain translation. The EU F-Gas Regulation mandates energy-efficient semiconductor designs, pushing converter manufacturers toward lower-power architectures. Bavaria's precision electronics corridor anchors specification requirements for centralized compute architectures.
Japan
METI enforces energy-efficiency benchmarks that directly influence converter power budgets in automotive and portable applications. Japan's precision electronics manufacturers defend installed-base relationships through integrated hardware-software bundles. Tokyo and Osaka manufacturing corridors drive specification requirements for mixed-signal audio ICs.
India
TRAI broadcast digitization mandates shape power-performance tradeoffs as terrestrial television and radio infrastructure modernizes. India's terrestrial digitization programs open procurement channels for professional audio equipment. Maharashtra and Karnataka production facilities source portable USB and Thunderbolt interfaces for field journalism applications.
United Kingdom
CE marking under the EU Radio Equipment Directive governs electromagnetic compatibility for European distribution of broadcast equipment. Post-production facilities in London and Manchester fragment traditional hardware revenue through subscription-based cloud processing platforms. British broadcast engineers adopt FPGA-based implementations for live production flexibility.
Sample Rate Converters Market Competitive Landscape
Capability concentration sits with integrated semiconductor specialists; scale advantage sits with diversified mixed-signal suppliers. The vendor base spans three tiers: premium IP licensors commanding studio-grade margins, automotive-focused suppliers bundling DSP-to-converter solutions, and volume producers serving consumer electronics. Consolidation pressure operates through strategic IP acquisitions and foundry partnership restructuring rather than horizontal merger activity.
Within the integrated converter tier, Analog Devices Inc. and Texas Instruments occupy positions exemplifying divergent strategic postures—one defending premium studio-grade positioning through converter IP depth, the other reducing BOM complexity for OEMs through bundled DSP architectures. Cirrus Logic sits within the automotive-specialist vector, anchoring low-latency design expertise for infotainment system integration.
| Leading Market Players |
|---|
| Analog Devices Inc. |
| Texas Instruments |
| Cirrus Logic |
| STMicroelectronics |
| NXP Semiconductors |
| Microchip Technology |
| Infineon Technologies |
| Tempo Semiconductor |
| Renesas Electronics |
| Others |
Value Network & Pricing Analysis
Trans-Pacific container routes from Taiwan and South Korea to Germany and Japan transmit foundry cost fluctuations directly into converter module pricing, while automotive OEM procurement power compresses margins at the integrated tier and broadcast rental houses absorb volatility through subscription models.
Pricing Analysis
Long-term offtake contracts dominate automotive supply relationships, locking volume commitments across vehicle platform generations, while spot purchasing persists in broadcast equipment procurement and project-based licensing anchors professional audio software bundles. Price differentiation rests on AEC-Q100 certification tier and jitter performance grade, with studio-grade standalone units commanding substantial premiums over integrated codec volumes. Cost compression in mid-tier integrated solutions is intensifying because mobile SoC suppliers are absorbing converter functionality. Automotive OEMs exhibit the least price sensitivity due to qualification lock-in, whereas independent music studios show acute responsiveness to per-channel hardware costs.
Supply Chain Analysis
Extended payment terms from German automotive OEMs and supply-chain finance facilities from Japanese precision electronics manufacturers structure working capital flows upstream to Taiwan and South Korea foundries. Advanced CMOS mixed-signal capacity concentrates in Taiwan, South Korea, and Japan, with silicon wafers, specialty analog IP cores, and precision clocking components drawing from concentrated semiconductor ecosystems. Single-source vulnerability around 12-inch mixed-signal foundry capacity presents structural exposure to geopolitical disruption. Distribution runs through Tier 1 automotive electronics suppliers, professional audio equipment distributors, and direct OEM engineering engagement for broadcast infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sample rate converters sit in early-cycle expansion as automotive zonal architectures and AI-generated audio workflows recalibrate latency requirements across professional and consumer deployment tiers.
For Market Incumbents: Insulate premium studio-grade positioning through captive IP development in ultra-low-jitter PLL architectures, countering FPGA-based substitution threats from broadcast engineers demanding field reconfigurability. Backward integration into precision clocking component supply secures margin defense against foundry allocation constraints during demand spikes. Certification investment in AEC-Q100 and METI efficiency benchmarks locks automotive OEM relationships through qualification inertia. For New Entrants and Emerging Players: India's broadcast digitization programs present the most penetrable procurement channel, with TRAI-mandated infrastructure modernization creating first-mover openings for portable USB and Thunderbolt interface suppliers. Field journalism applications in Maharashtra and Karnataka production facilities offer low competitive density against entrenched German and Japanese hardware incumbents. Direct government tender participation, bypassing established distributor networks, accelerates initial reference customer acquisition. For Investors and Strategic Acquirers: Automotive-focused converter specialists with integrated DSP-to-codec bundles represent the priority acquisition archetype, capturing exposure to software-defined vehicle audio architectures with over-the-air update pathways. Long-term viability frames around 5-10 year zonal compute consolidation, with programmable converter architectures displacing static implementations. The signal to monitor is Ethernet AVB/TSN adoption velocity across German and Japanese OEM roadmaps, indicating inflection timing for programmable versus fixed-function converter demand.| Strategic Initiative | Industry Significance |
|---|---|
| FPGA-Based Product Line Expansion | Enables North American broadcast engineers to reconfigure processing pipelines between live events without hardware swaps. |
| Energy-Efficient Architecture Redesign | Satisfies EU F-Gas Regulation standby power requirements for CE marking eligibility across automotive and portable segments. |
| Cloud Processing Platform Launch | Captures recurring subscription revenue from London and Manchester post-production facilities fragmenting traditional hardware ownership. |
| Automotive Zonal Audio Partnership | Locks 24-month qualification timelines with German OEMs through AEC-Q100 reliability and acoustic validation protocol compliance. |
| India Market Direct Entry | Positions portable interface suppliers for TRAI-mandated terrestrial television and radio infrastructure modernization procurement. |
Research Methodology
Operator-level perspectives from broadcast infrastructure engineers, automotive platform architects, professional audio equipment procurement managers, and semiconductor mixed-signal design leads anchored the qualitative base. Primary interview intelligence combined with secondary validation from FCC equipment authorization databases, METI efficiency benchmark filings, EU F-Gas Regulation compliance registries, and SEC 10-K semiconductor segment disclosures. Bottom-up shipment modeling across product type, technology, and end-user segments triangulated against top-down market sizing from foundry capacity allocation and OEM procurement disclosure patterns.
Scenario-bracketing framed demand trajectories across the projection horizon, with base, upside, and downside cases reflecting automotive platform transition timing and broadcast infrastructure refresh cycle acceleration. Segmentation dimensions modeled include product architecture, conversion technology implementation, end-user industry vertical, and regional regulatory cluster. CAGRs derived from logistic curve penetration modeling against replacement cycle dynamics and greenfield adoption curves. Industry-specific forecast inputs incorporated zonal audio architecture deployment roadmaps from German and Japanese OEMs and FPGA rental penetration rates among North American live production houses.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified mixed-signal suppliers or hyperscaler cloud audio platform entrants would shift outcomes. Macroeconomic contraction in automotive production, regulatory relaxation of EU F-Gas efficiency mandates, or breakthrough AI audio generation tools eliminating real-time conversion requirements would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Hearing Aid and True Wireless Earbud Acoustic Performance Test Systems Market
Test and Measurement
Global Nondestructive Testing Equipment Market
Test and Measurement
Onboard Charger and DC Fast-Charging Interoperability Test Equipment Market
Test and Measurement
Electronic Test Instrument Market
Test and Measurement
Radio Frequency Test Equipment Market
Test and Measurement
Compression Testing Machines Market
Test and Measurement
Shape Measuring Devices Market
Test and Measurement
LAN Tester Market
Test and Measurement
Automated Optical Inspection Market
Test and Measurement
Non-Destructive Testing (NDT) Service Market
Test and Measurement
Ground Grid Tester Market
Test and Measurement
Metrology and Inspection Equipment Market
Test and Measurement
Tribometer Market
Test and Measurement
Ethernet Test Equipment Market
Test and Measurement
Structure Tester Market
Test and Measurement
Global NVH Testing Market