
 Switch Diode Market | 2026-2036
Switch Diode Market Size, Share, and Industry Trends Forecast 2026-2036
Switch Diode Market Analytics
Power semiconductor engineering talent is bifurcating between legacy silicon expertise and wide-bandgap material competency, constraining how quickly fabs can retool. ON Semiconductor leverages its integrated manufacturing footprint to capture automotive qualification cycles. Vishay Intertechnology anchors its position through specialized foundry relationships in discrete packaging. ROHM Semiconductor differentiates via deep SiC process know-how that extends into diode companion devices.
A switch diode is a two-terminal semiconductor device engineered for rapid transition between conducting and non-conducting states, typically achieving reverse recovery times below 50 nanoseconds through gold or platinum lifetime killing processes. Its primary commercial purpose is to protect sensitive circuitry from voltage transients and to rectify high-frequency signals in switch-mode power supplies. Schottky diodes command the margin pool in consumer electronics adapters due to their lower forward voltage drop, while fast switching variants are accelerating in server power stages where efficiency standards tighten. Surface mount packaging dominates volume throughput, though custom package formats capture premium pricing in aerospace and defense applications.
FDA oversight of medical power supplies, EPA energy efficiency mandates for external adapters, and FCC electromagnetic interference limits collectively shape diode specification thresholds and test protocol burdens. The EU RoHS and REACH frameworks restrict hazardous substances in semiconductor packaging materials, forcing reformulation of lead frames and mold compounds. Stakeholders must monitor how automotive OEMs integrate diode specifications into platform-level SiC inverter architectures before committing capacity expansion decisions.
Market Dynamics
The transition from silicon to silicon carbide substrates in automotive traction inverters is compressing qualification timelines and forcing diode suppliers to synchronize roadmaps with Tier 1 power module integrators.
Growth Catalysts
- EPA Energy Efficiency Mandates:External power adapter standards in the United States are tightening loss thresholds, pulling fast-switching Schottky variants into consumer electronics supply chains.
- Data Center Server Density:Hyperscale facilities in China are absorbing larger volumes of high-frequency rectifiers as rack power densities climb past 30kW per cabinet.
- EU RoHS Framework:Restrictions on hazardous substances in semiconductor packaging are accelerating reformulation of lead frames and mold compounds toward compliant chemistries.
Market Restraints
- Silicon Carbide Substrate Costs:Premium wafer pricing constrains margin expansion for discrete diode manufacturers serving automotive qualification programs.
- Gold and Platinum Lifetime Killers:Precious metal doping processes for reverse recovery control expose cost structures to commodity volatility on spot markets.
- Wide-Bandgap Talent Scarcity:Engineering competency gaps between legacy silicon expertise and SiC process know-how are slowing fab retooling cycles.
Strategic Opportunities
- India PLI Scheme:Domestic fab capacity incentives for electronic components are creating localized sourcing alternatives to Chinese import dependency.
- Aerospace Custom Packaging:Hermetic and radiation-hardened formats for satellite power systems command premium pricing above standard surface mount volumes.
- GaN-SiC Convergence:Companion diode specifications for gallium nitride gate drivers are opening adjacent design-in opportunities at power module manufacturers.
Industry Challenges
- AEC-Q101 Certification Timelines:Automotive reliability testing protocols extend qualification cycles to 18-24 months, freezing design wins for competing technologies.
- Legacy Silicon Integration:Mixed-signal boards require voltage clamping diodes that bridge incompatible forward drop characteristics between old and new process nodes.
- Supply Chain Reconfiguration:Foundry migration from 6-inch to 8-inch SiC substrates demands synchronized tooling investments across epitaxy and packaging stages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switch Diode Market |
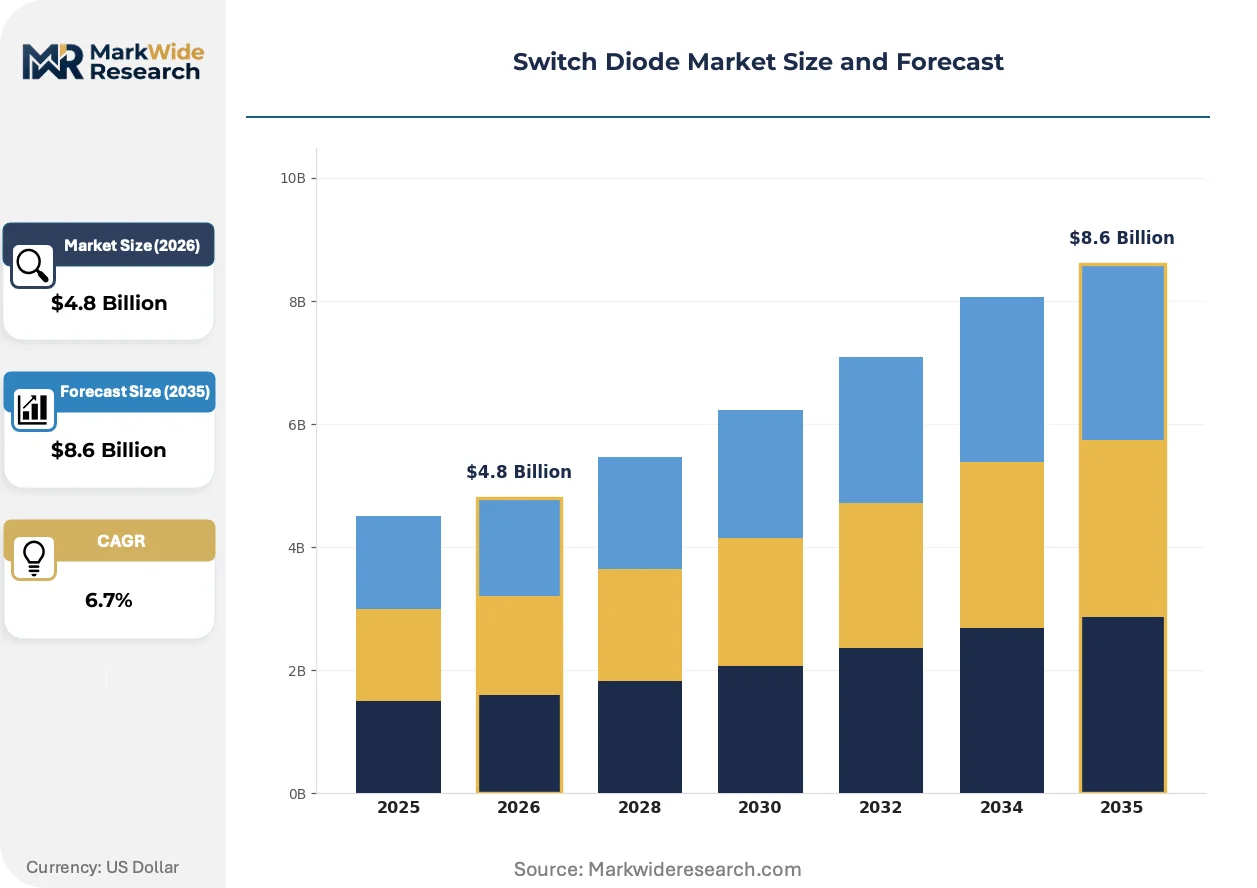
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fast Switching Diodes, Schottky Diodes, Zener Diodes, Avalanche Diodes Application: Consumer Electronics, Automotive Systems, Power Supply, Communication Equipment End User: Manufacturers, OEMs, Service Providers, Distributors Packaging Type: Surface Mount, Through Hole, Standard Package, Custom Package |
| Companies Covered | ON Semiconductor, Vishay Intertechnology, NXP Semiconductors, Diodes Incorporated, ROHM Semiconductor, STMicroelectronics, Infineon Technologies, Toshiba Corporation, Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switch Diode Market Evolving Landscape
Process node compression in power semiconductors is collapsing the boundary between discrete diodes and integrated power stages, forcing packaging specialists to co-develop thermal solutions with module integrators.
Trench-termination silicon carbide Schottky diodes are miniaturizing cell pitch dimensions below 3 microns while maintaining breakdown voltage ratings above 1200V. Automotive inverter designers at German and Japanese OEMs are qualifying these devices for 800V battery architectures ahead of 2026 platform launches. This geometry shrink is miniaturizing die area requirements per ampere of forward current, enabling higher power density in the same package footprints.
REACH substance restrictions on per- and polyfluoroalkyl substances are forcing reformulation of mold compound flame retardants and die attach epoxies used in discrete packaging. Compound suppliers in the European Union are accelerating halogen-free alternatives through JEDEC moisture sensitivity testing. Surface mount diode portfolios targeting industrial automation in Germany and France are experiencing the fastest specification refresh cycles as a result.
Consolidated procurement at hyperscale data center operators is compressing approved vendor lists to three qualified sources per diode category. Server power supply manufacturers are responding with multi-source qualification programs that mirror component specifications across ON Semiconductor, ROHM, and Vishay product lines. This concentration is most visible in China, where domestic cloud providers are vertically integrating power design teams to control component selection directly.
Switch Diode Market Segmentation
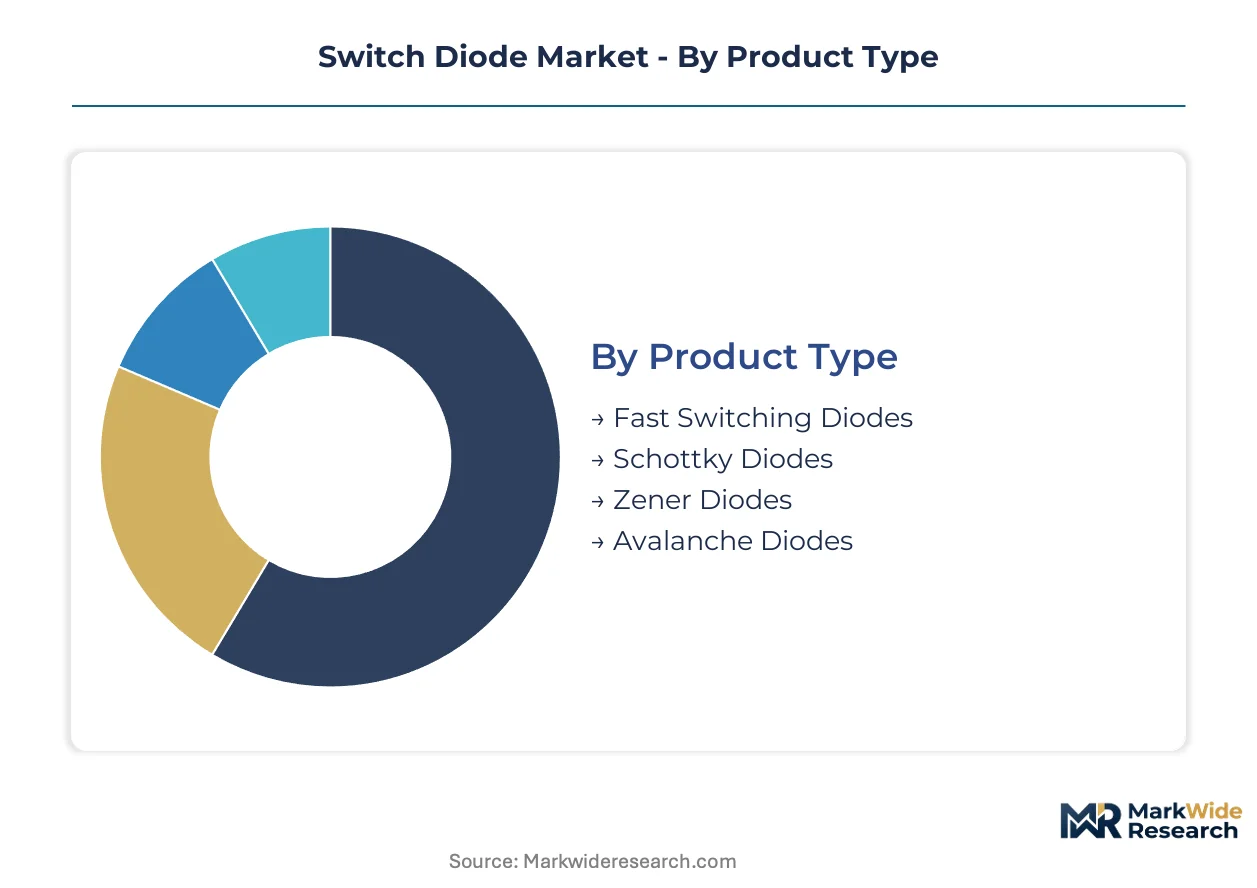
Segmentation in the switch diode market reveals how substrate transitions and packaging evolution reshape procurement priorities across discrete power components. Technical specifications diverge sharply between legacy silicon and wide-bandgap variants, forcing buyers to map qualification timelines against performance thresholds.
Product Type:
Schottky variants face intensifying substitution pressure from silicon carbide alternatives in high-voltage automotive inverters, while fast switching diodes defend position in cost-sensitive consumer adapters.
- Schottky Diodes:Metal-semiconductor junction construction delivers forward voltage drops below 0.4V, minimizing conduction losses in compact power stages. Demand concentrates in smartphone and laptop adapter supply chains serving the EU and US markets, where EPA and EU Green Deal efficiency mandates tighten loss thresholds annually.
- Fast Switching Diodes:Gold and platinum lifetime killing achieves reverse recovery times under 50 nanoseconds for high-frequency rectification. Server power supply manufacturers in China absorb expanding volumes as hyperscale data center rack densities exceed 30kW per cabinet.
- Zener Diodes:Avalanche breakdown characteristics enable precise voltage clamping for sensitive analog circuits in industrial automation controllers.
- Avalanche Diodes:Ruggedized junction designs withstand repetitive reverse energy pulses in automotive load dump protection circuits.
Fast switching diodes retain volume leadership across standard industrial applications; Schottky variants hold the steepest expansion curve as efficiency regulations propagate through consumer electronics supply chains.
Application:
Cost tier stratification separates premium automotive qualification programs from high-volume consumer electronics procurement, with power supply applications occupying the intermediate margin band.
- Power Supply:Switch-mode conversion stages in data center infrastructure demand the highest frequency operation, pulling specialized fast recovery and Schottky specifications into 80 PLUS Titanium-rated designs. Procurement concentrates at consolidated vendor lists of three qualified sources per diode category among Chinese hyperscale operators.
- Automotive Systems:Traction inverter integration requires AEC-Q101 certification across 18-24 month qualification cycles, freezing design wins for SiC companion diodes in 800V battery architectures. German and Japanese OEMs are qualifying trench-termination SiC Schottky devices ahead of platform launches.
- Consumer Electronics:External adapter manufacturers prioritize forward voltage minimization over switching speed in sub-100W applications.
- Communication Equipment:Base station power amplifiers require low-noise rectification for RF signal integrity in 5G infrastructure deployments.
Power supply applications command the broadest specification diversity; automotive systems are climbing fastest as electrification penetrates passenger vehicle platforms.
End User:
Customer type determines whether procurement emphasizes volume scale, technical integration support, or aftermarket availability.
- OEMs:Direct platform-level integration demands synchronized roadmaps with Tier 1 power module manufacturers, particularly for SiC inverter architectures. Automotive OEMs in Germany and Japan are embedding diode specifications into 800V battery platform designs before committing capacity expansion decisions.
- Manufacturers:Contract electronics manufacturers in China manage multi-source qualification programs across ON Semiconductor, ROHM, and Vishay product lines to mitigate supply concentration risk.
- Distributors:Inventory positioning strategies focus on standard surface mount packages with broad cross-reference compatibility.
- Service Providers:Aftermarket repair channels prioritize availability over specification optimization for legacy equipment maintenance.
Manufacturers retain volume leadership through consolidated procurement scale; OEMs are expanding fastest as platform-level integration deepens.
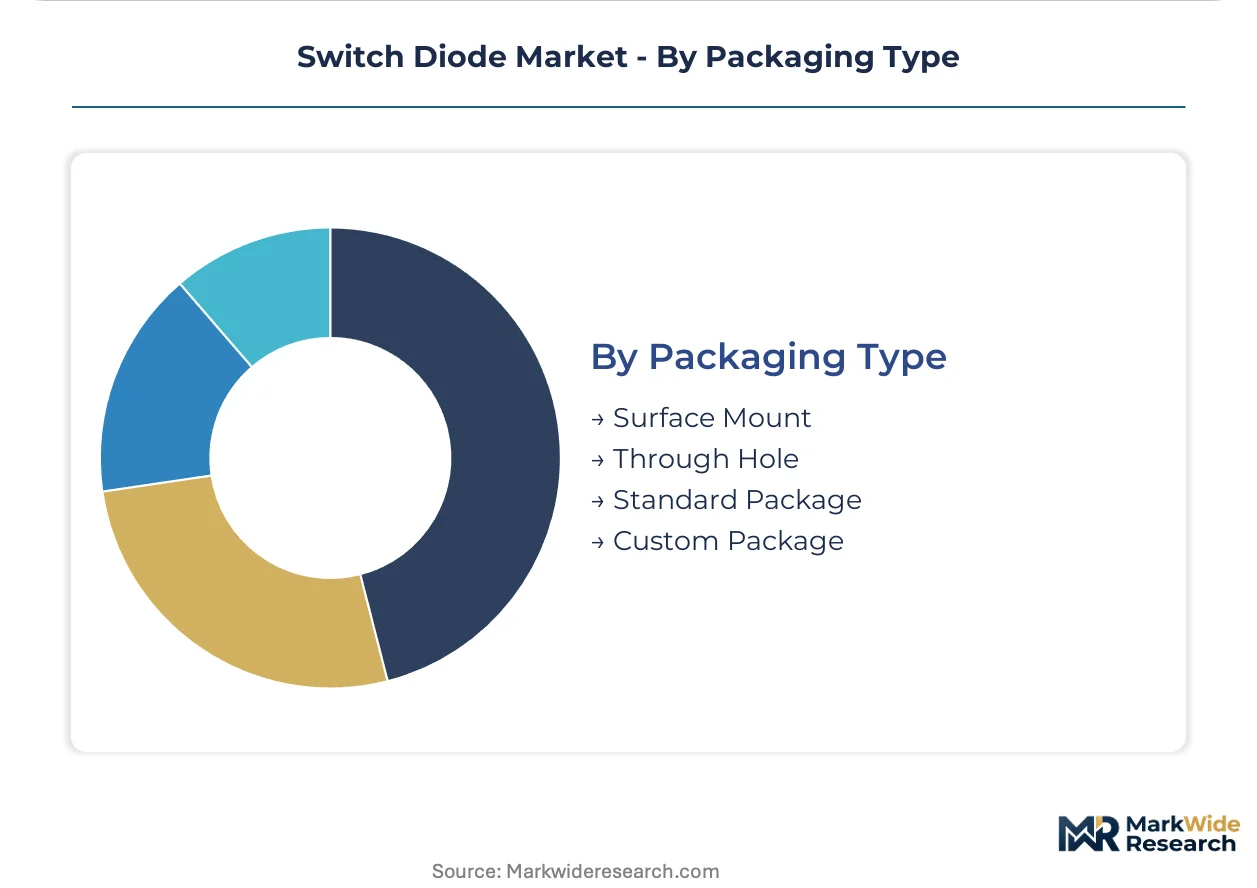
Packaging Type:
Supply concentration in surface mount formats contrasts with fragmented custom packaging for aerospace and defense applications.
- Surface Mount:Tape-and-reel formats dominate throughput in consumer electronics and industrial automation, with JEDEC moisture sensitivity Level 1 qualification enabling high-temperature reflow processing. REACH substance restrictions on PFAS compounds are forcing the fastest specification refresh cycles in Germany and France.
- Custom Package:Hermetic ceramic and metal-can formats command premium pricing for satellite power systems requiring radiation hardness and vacuum compatibility. Aerospace procurement in the US and Europe specifies these formats for 15-20 year operational lifetimes in geostationary orbit.
- Through Hole:Axial and radial leaded formats persist in high-reliability industrial equipment requiring manual rework capability.
- Standard Package:TO-220 and DO-214 variants bridge cost and performance for mid-range power applications.
Surface mount packaging retains volume leadership across commercial applications; custom formats are gaining share fastest as satellite constellation deployments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with automotive traction inverters in Germany and Japan absorbing premium SiC diodes while Chinese hyperscale data centers drive volume throughput for fast-switching variants in server power supplies.
China
Hyperscale data center operators in Beijing and Shenzhen are consolidating procurement to three qualified diode sources per category as rack densities exceed 30kW per cabinet. MIIT's dual carbon goals are accelerating efficiency mandates for server infrastructure. Shanghai-based power supply manufacturers are vertically integrating component selection teams to bypass traditional distributor channels.
Germany
Automotive OEMs in Stuttgart and Munich are embedding SiC diode specifications into 800V battery platform designs ahead of 2026 launches. The KBA coordinates type-approval testing for traction inverter components. Bavarian power module integrators are synchronizing qualification timelines with ROHM and Infineon roadmaps.
United States
EPA energy efficiency mandates for external power adapters are pulling Schottky variants into consumer electronics supply chains serving California and Texas markets. The FCC enforces electromagnetic interference limits that shape diode test protocols. Arizona and Oregon fabrication clusters are retooling for wide-bandgap substrate transitions.
Japan
METI's semiconductor industry revitalization framework is subsidizing SiC process competency development at Nagoya and Osaka fabs. Automotive inverter designers are qualifying trench-termination SiC Schottky devices for next-generation platforms. Kyushu-based foundries are expanding epitaxy capacity to serve domestic power module manufacturers.
India
The PLI scheme for electronic components is attracting diode packaging investments to Gujarat and Karnataka as alternatives to Chinese import dependency. BIS certification requirements are standardizing specifications for industrial automation applications. Tamil Nadu contract manufacturers are launching multi-source qualification programs across global supplier lines.
Switch Diode Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in switch diode supply. The upper tier commands automotive qualification cycles through captive fabrication and packaging assets. Mid-scale specialists anchor position through foundry partnerships and discrete packaging expertise. Competitive moves center on SiC substrate capacity expansion and synchronized roadmap development with Tier 1 power module integrators.
Within the integrated manufacturing tier, ON Semiconductor and Infineon Technologies exemplify players with full-stack control from wafer fabrication to automotive-grade packaging. ROHM Semiconductor occupies a distinct position through deep SiC process heritage that extends into companion device portfolios. Among specialized foundry-dependent suppliers, Vishay Intertechnology anchors market presence through selective packaging relationships rather than captive substrate production.
| Leading Market Players |
|---|
| ON Semiconductor |
| Vishay Intertechnology |
| NXP Semiconductors |
| Diodes Incorporated |
| ROHM Semiconductor |
| STMicroelectronics |
| Infineon Technologies |
| Toshiba Corporation |
| Texas Instruments |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between automotive OEMs and SiC substrate suppliers lock in wafer access and price visibility across 18-24 month qualification cycles, insulating Tier 1 power module integrators from spot market volatility in precious metal doping materials. These contracts concentrate pricing power with integrated manufacturers possessing captive epitaxy capacity while exposing foundry-dependent suppliers to margin compression during gold and platinum price spikes.
Pricing Analysis
Contract-based long-term offtake structures dominate automotive qualification programs, while spot procurement persists in consumer electronics adapter supply chains. Price differentiation rests on AEC-Q101 certification tier and volume scale, with qualified automotive variants commanding substantial premiums over industrial-grade alternatives. Cost compression in standard silicon fast-switching diodes is intensifying because Chinese hyperscale operators are consolidating procurement to three qualified sources per category. Consumer electronics manufacturers exhibit the highest price sensitivity, prioritizing forward voltage drop metrics over switching performance in sub-100W applications.
Supply Chain Analysis
Inventory lead times for SiC substrates extend substantially beyond silicon equivalents, forcing power module manufacturers to position safety stock around epitaxy bottlenecks. Geographic supply concentration centers on Japan, Germany, and China, with Kyushu-based foundries and Bavarian integrators anchoring premium automotive qualification pipelines. Raw material dependencies draw from silicon carbide boule suppliers, gold and platinum lifetime killer sources, and halogen-free mold compound formulators. Single-source vulnerability in 8-inch SiC substrate migration exposes packaging houses to synchronized tooling investment demands. Distribution runs through consolidated direct procurement channels at Chinese hyperscale operators and specialized distributor networks serving industrial automation in Germany and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide MOSFET integration into traction inverters threatens discrete diode attach rates as module designers consolidate power stages, forcing incumbents to defend substitution through companion device bundling and process co-development roadmaps.
For Market Incumbents: Consolidate SiC process competency through backward integration into epitaxy capacity or exclusive wafer supply agreements with substrate specialists. Deepen AEC-Q101 certification pipelines ahead of 800V platform launches at German and Japanese OEMs. Lock in design wins by embedding diode specifications into Tier 1 power module roadmaps before qualification cycles freeze competitor access. For New Entrants and Emerging Players: AEC-Q101 fast-track qualification programs for industrial automation applications in India and Southeast Asia represent the most penetrable entry vector. Target surface mount packaging for 80 PLUS Titanium-rated server power supplies where Chinese hyperscale procurement is diversifying beyond incumbents. Pursue foundry partnerships with established SiC substrate houses rather than greenfield fabrication investments. For Investors and Strategic Acquirers: Specialist packaging houses with halogen-free mold compound expertise and JEDEC moisture sensitivity Level 1 qualification capabilities represent the optimal acquisition target archetype. Monitor automotive OEM platform-level SiC inverter architecture announcements as the critical inflection signal for capacity expansion timing. Long-term viability favors players with synchronized roadmaps to wide-bandgap substrate transitions and captive supply of radiation-hardened formats for satellite power systems.| Strategic Initiative | Industry Significance |
|---|---|
| SiC Epitaxy Capacity Expansion | Captive wafer supply secures automotive qualification timelines against substrate shortages at Japanese foundries. |
| Halogen-Free Packaging Transition | REACH compliance for PFAS-free mold compounds unlocks industrial automation procurement in Germany and France. |
| AEC-Q101 Certification Investment | Automotive reliability testing protocols extend design win protection across 18-24 month competitor exclusion periods. |
| Multi-Source Qualification Programs | Mirror specifications across ON Semiconductor, ROHM, and Vishay lines to mitigate supply concentration risk at Chinese hyperscale operators. |
| Custom Hermetic Package Development | Radiation-hardened formats for satellite power systems command premium pricing above standard surface mount volumes in geostationary orbit applications. |
Research Methodology
Desk research of SEC 10-K filings, customs and trade data, and JEDEC qualification databases preceded structured interviews with power semiconductor engineering directors, Tier 1 automotive supplier procurement leads, and data center infrastructure planners. Primary fieldwork with Chinese hyperscale operator power design teams and German automotive OEM platform engineers validated secondary estimates of SiC adoption timelines. Bottom-up unit demand modeling across Schottky, fast switching, and Zener diode categories was cross-checked against top-down substrate consumption forecasts from epitaxy equipment manufacturers.
Variance decomposition across substrate material, packaging format, and end-use application dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segmented unit demand trajectories multiplied by blended average selling price assumptions across qualification tiers. Modeled inputs included EPA energy efficiency mandate compliance costs for external adapters, MIIT dual carbon goal implementation timelines for Chinese server infrastructure, and AEC-Q101 certification success rates at competing suppliers.
The analysis sits within stated boundaries; outcomes outside sustained SiC substrate cost reduction trajectories or accelerated REACH substance restriction enforcement would require recalibration. Forecasts reflect assumptions regarding automotive electrification penetration and data center rack density evolution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
North America Touch Screen Controllers Market
Electronic Components
Wearable Display Device Materials Market
Electronic Components
Wearable Technology Component Market
Electronic Components
DVB/SAT Remote Controls Market
Electronic Components
Motherboard Battery Market
Electronic Components
Capacitor Aluminum Polymer Market
Electronic Components
5G Base Station BAW Filters Market
Electronic Components
Power Inductors Market
Electronic Components
Electric Capacitor Market
Electronic Components
United States Radiation-Hardened Electronics Market
Electronic Components
North America Miniature Ball Bearing Market
Electronic Components
Digital Electronic Detonator Market
Electronic Components
Audio CODEC Market
Electronic Components
Chip Shield Market
Electronic Components
Capacitor Kits Market
Electronic Components
Digital Class-D Amplifier Market