
 Electric Boat Market | 2026-2036
Electric Boat Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Boat Market Analysis
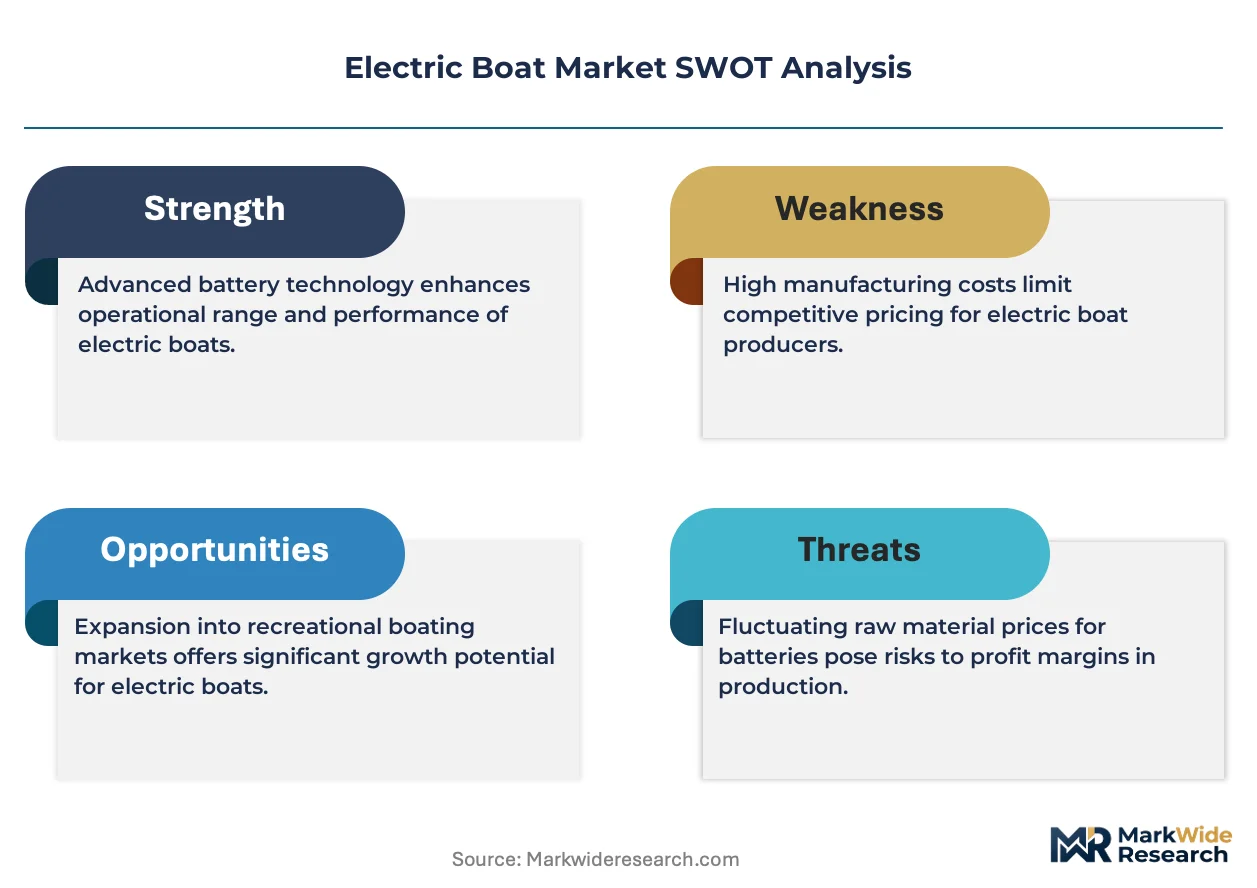
Capital-intensity divergence between integrated drivetrain manufacturers and hull-assemblers is bifurcating competitive tiers in the electric boat sector. Torqeedo GmbH leverages its in-house motor and battery architecture to control supply timelines for European OEMs. Candela Technology AB differentiates through hydrofoil engineering that reduces drag coefficients for premium leisure applications. Vision Marine Technologies anchors North American positioning with outboard systems designed for retrofit compatibility.
An electric boat is a watercraft propelled by electric motors drawing power from battery banks, fuel cells, or solar arrays, typically operating at voltages between 48V and 800V depending on vessel class and range requirements; these craft serve commercial transit, leisure cruising, and specialized missions where emissions restrictions or noise limits apply. Passenger vessels dominate current order books as harbor authorities in Norway, Denmark, and the Netherlands mandate zero-emission ferry replacements. Fully electric technology leads segment investment, though hybrid systems sustain relevance in longer-range coastal routes where charging infrastructure remains sparse.
The European Maritime Safety Agency enforces battery certification standards under the EU Green Deal framework, while the US Coast Guard and EPA coordinate on lithium-ion fire-suppression protocols for commercial passenger applications. These overlapping regimes force manufacturers to design modular battery compartments that satisfy multiple jurisdictional tests, raising engineering overhead but creating barriers for unqualified entrants. Stakeholders must weigh charging infrastructure commitments against vessel deployment schedules as port electrification timelines diverge across regulatory zones.
Market Dynamics
Harbor authorities across Norway, Denmark, and the Netherlands are mandating zero-emission ferry replacements, forcing vessel operators to accelerate electrification timelines and consolidate procurement around certified battery-electric platforms.
Growth Catalysts
- EU Green Deal maritime protocols:The European Maritime Safety Agency enforces battery certification standards that disqualify fossil-fuel vessels from harbor access, redirecting capital toward electric platforms.
- Fjord tourism corridors:Municipal transit authorities in Scandinavian coastal zones overlap with leisure cruising demand, creating dual-revenue route density for electric ferry operators.
- Solid-state battery density gains:Korean suppliers are extending vessel range thresholds, enabling longer coastal routes previously reserved for diesel-hybrid configurations.
Market Restraints
- Lithium supply concentration:Cathode material processing clusters in East Asian supply zones create input cost volatility and geopolitical exposure for European hull-assemblers.
- Charging infrastructure asymmetry:Port electrification timelines diverge across regulatory zones, forcing operators to deploy hybrid systems on longer-range coastal routes where shore power remains unavailable.
- Fire-suppression certification complexity:The US Coast Guard and EPA coordinate on lithium-ion safety protocols that add engineering overhead and extend vessel approval cycles.
Strategic Opportunities
- Retrofit outboard systems:North American marina operators seek drop-in electric propulsion for existing hulls, opening a channel beyond new-build procurement.
- Dual-use municipal-leisure routes:Scandinavian coastal corridors where public transit and tourism overlap offer route density that amortizes vessel capital costs across passenger segments.
- Solar-array integration:Convergence of photovoltaic deck systems with battery-electric architecture enables auxiliary charging for harbor service vessels and day-cruisers.
Industry Challenges
- Marine electrical engineering talent scarcity:Vessel integrators face recruitment gaps for high-voltage system designers capable of meeting multi-jurisdictional certification requirements.
- Modular battery compartment redesign:Manufacturers must engineer flexible architectures that satisfy divergent EU, US, and emerging market safety tests without platform fragmentation.
- Legacy harbor electrical infrastructure:Port authorities require grid upgrade coordination that often lags vessel delivery schedules, creating deployment bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Boat Market |
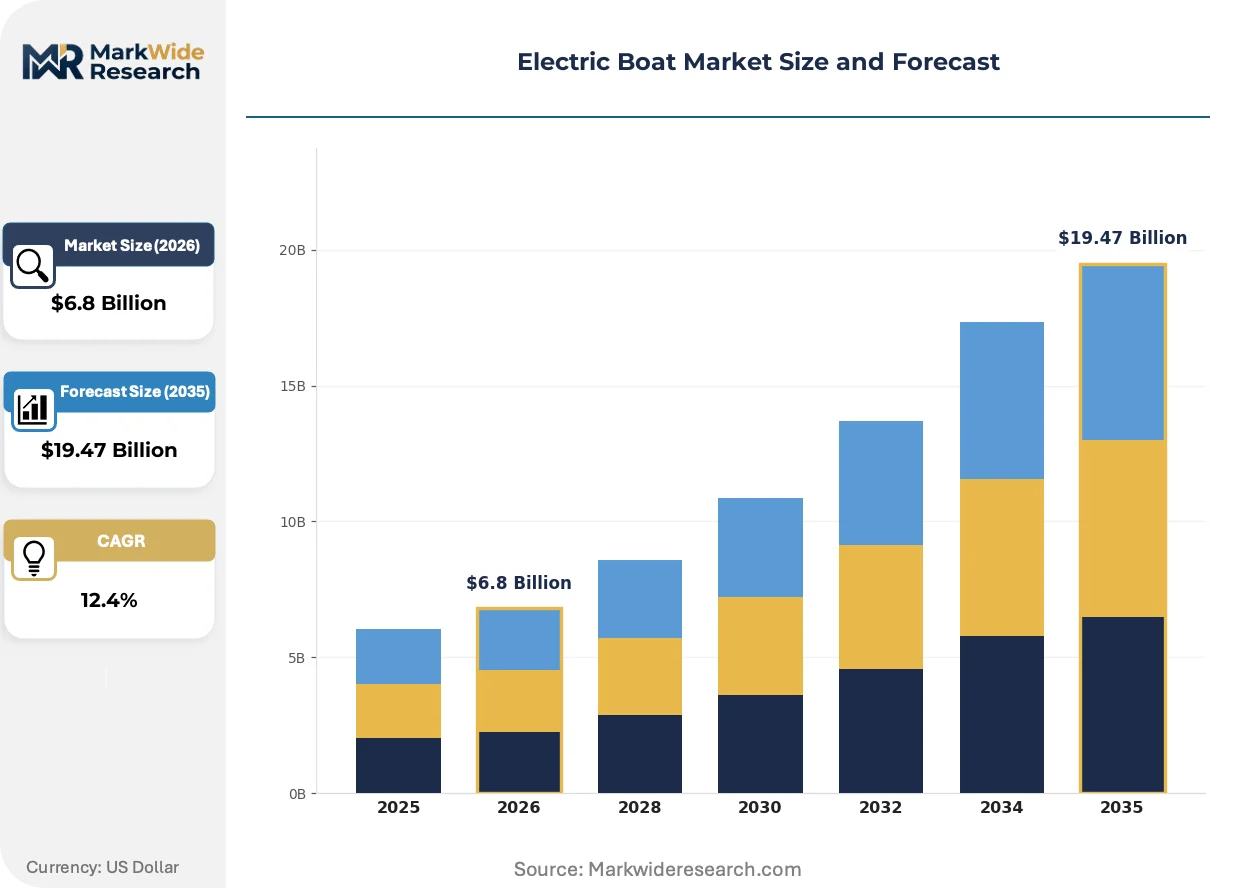
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $19.47 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
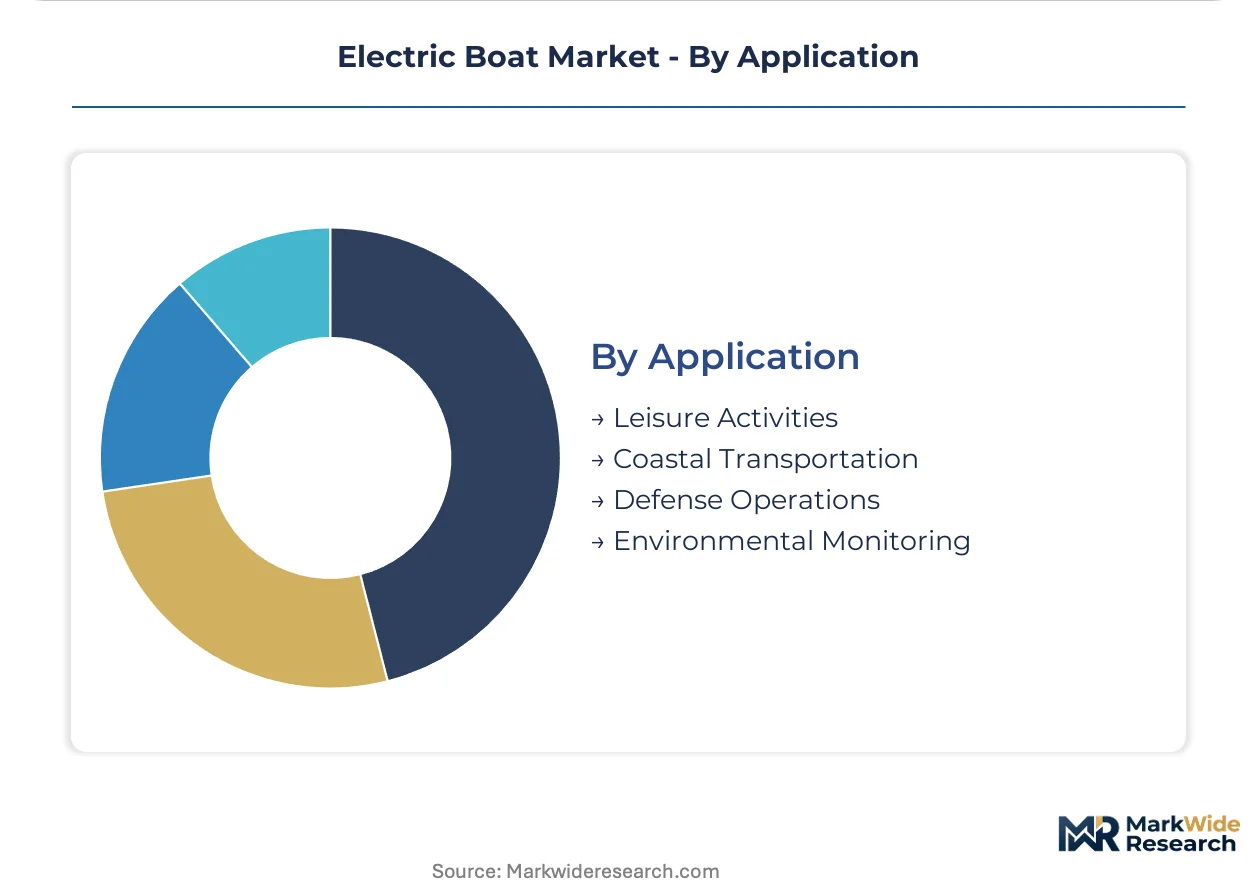
| Segmentation | Product Type: Passenger Vessels, Cargo Vessels, Fishing Boats, Military Crafts Technology: Hybrid Systems, Fully Electric, Fuel Cells, Solar Powered End User: Commercial Operators, Private Owners, Government Agencies, Research Institutions Application: Leisure Activities, Coastal Transportation, Defense Operations, Environmental Monitoring |
| Companies Covered | Torqeedo GmbH, Duffy Electric Boat, Candela Technology AB, Vision Marine Technologies, Ruban Bleu, Elco Motor Yachts, Silent Yachts, Pure Watercraft, Evoy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Boat Market Emerging Trajectories
Propulsion architecture and energy storage systems are diverging between integrated platform providers and component suppliers, reshaping competitive boundaries and procurement patterns across vessel classes.
Hydrofoil engineering is bifurcating the premium leisure segment. Candela Technology AB deploys computer-stabilized foiling hulls that reduce drag coefficients by lifting vessels above waterline at cruising speed. Scandinavian yacht charter operators are adopting these platforms for fjord routes where wake restrictions apply. This technology is bifurcating the market into foil-enabled premium operators and conventional displacement-hull competitors facing margin compression.
REACH chemical restrictions and the EU F-Gas Regulation are accelerating fluorinated coolant phaseouts in battery thermal management systems. Marine integrators must reformulate liquid cooling loops to satisfy substance restrictions while maintaining thermal runaway protection. Passenger ferry builders in the Netherlands and Denmark are most affected, shifting procurement toward dielectric fluid alternatives and passive cooling architectures.
Harbor service contracts are unbundling propulsion from hull procurement. Municipal ferry authorities in Norway now lease battery-electric drivetrains separately from vessel shells, transferring technology obsolescence risk to system suppliers. This model compresses replacement cycles and concentrates vendor relationships around Torqeedo GmbH and specialized lessors. The shift is most visible in Oslofjord and Copenhagen harbor zones where public transit budgets favor operational expenditure structures.
Electric Boat Market Segmentation
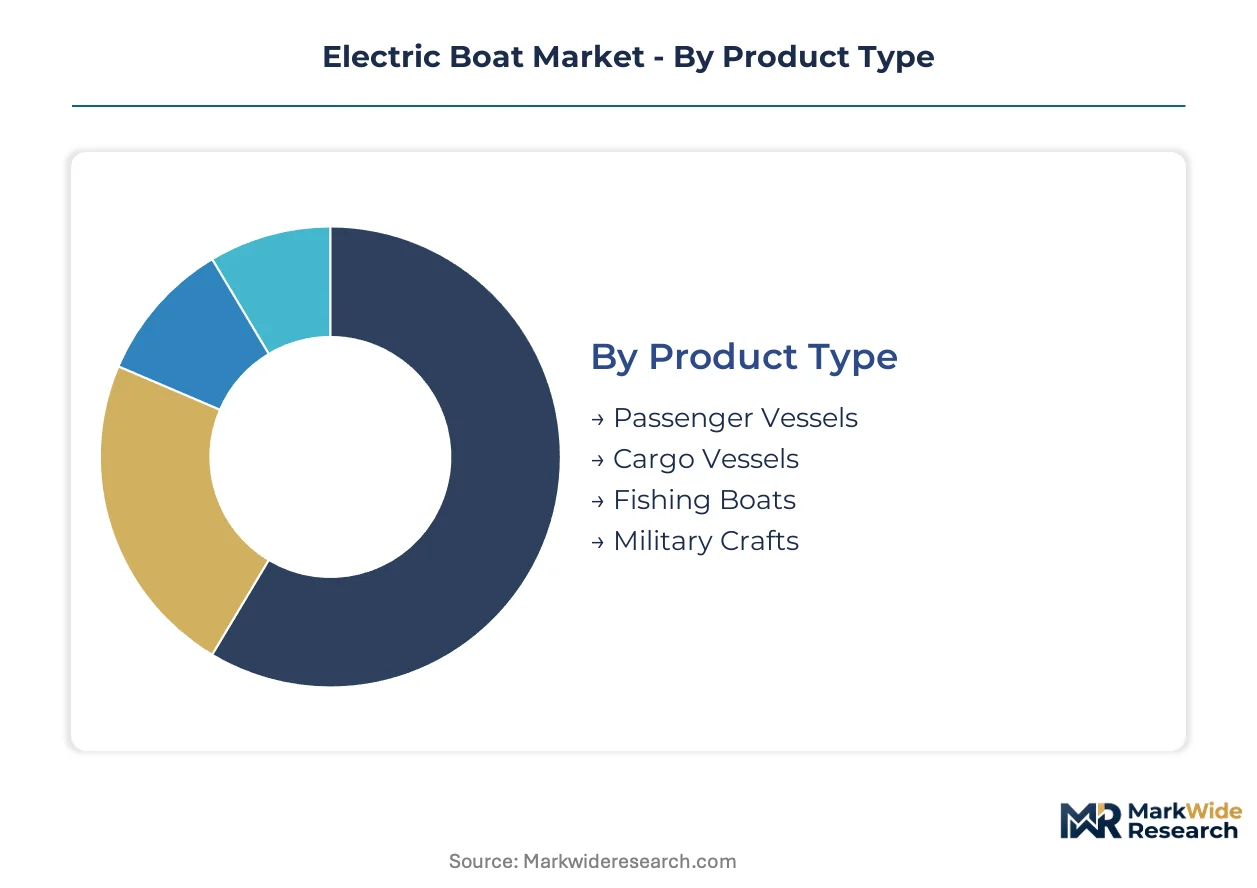
Electric boat procurement channels diverge sharply between municipal ferry authorities seeking certified platforms and private owners prioritizing retrofit compatibility. Channel economics favor integrated drivetrain suppliers for commercial fleets while component vendors capture leisure marina sales.
Product Type:
Passenger vessels flow primarily through municipal procurement channels, while fishing and cargo platforms concentrate in specialized commercial yards.
- Passenger Vessels:These craft carry commuters and tourists across harbor zones, typically operating at 400V-800V architectures for high-capacity routes. Norwegian municipal transit authorities in Oslofjord and Danish harbor operators in Copenhagen dominate current order books as EU Green Deal harbor access rules tighten. Battery-electric ferries here face compressed approval cycles from the European Maritime Safety Agency.
- Cargo Vessels:Short-sea freight carriers serving Baltic and North Sea coastal corridors adopt electric propulsion for last-mile port distribution. Dutch inland waterway operators in Rotterdam harbor zones pilot container barges with swappable battery modules, though charging infrastructure gaps limit route expansion beyond 50-nautical-mile radii.
- Fishing Boats:Small-scale coastal fleets in Mediterranean harbors test electric outboards for day-trip operations. Italian and Greek island fishing cooperatives favor 48V-96V systems for retrofit compatibility with existing hulls.
- Military Crafts:Naval procurement prioritizes silent propulsion for coastal patrol and special operations missions. Scandinavian defense ministries evaluate fuel-cell architectures for extended endurance without exhaust signatures.
Passenger vessels dominate installed base. Cargo vessels are where expansion concentrates.
Technology:
Cost tiers separate premium fully-electric platforms from hybrid systems sustaining relevance in infrastructure-sparse corridors.
- Hybrid Systems:Diesel-electric architectures bridge charging infrastructure gaps on longer coastal routes. Danish inter-island ferry operators deploy these for 100+ nautical-mile legs where shore power remains unavailable, accepting higher capital costs for operational flexibility.
- Fully Electric:Battery-dominant platforms eliminate onboard combustion, requiring dedicated charging infrastructure at termini. Norwegian fjord tourism operators in Geiranger and Nærøyfjord mandate these for UNESCO heritage zone access where emissions restrictions apply.
- Fuel Cells:Hydrogen-electric systems extend range beyond battery limits for military and research applications. Korean suppliers advance maritime fuel-cell stacks for defense procurement channels.
- Solar Powered:Photovoltaic deck arrays supplement battery charging for harbor service vessels and day-cruisers. Dutch canal maintenance fleets integrate solar augmentation for auxiliary power during stationary operations.
Hybrid systems anchor current revenue. Fully electric platforms are climbing the fastest.
End User:
Customer type determines procurement structure, with government agencies favoring operational expenditure models and private owners demanding capital-light retrofit paths.
- Commercial Operators:Ferry companies and water-taxi fleets pursue total-cost-of-ownership optimization through leased drivetrain arrangements. Norwegian harbor authorities now separate hull procurement from propulsion contracts, transferring technology risk to system suppliers.
- Private Owners:Yacht and leisure boat owners prioritize drop-in electric outboard compatibility with existing vessels. North American marina operators represent the primary channel for these retrofit sales.
- Government Agencies:Municipal transit and environmental enforcement fleets mandate zero-emission platforms under procurement rules. Dutch and Danish public harbor authorities consolidate orders for battery-electric ferry replacements.
- Research Institutions:Oceanographic and climate monitoring vessels require silent propulsion for acoustic data collection. Scandinavian marine research stations adopt electric platforms for fjord ecosystem studies.
Commercial operators command volume share. Government agencies are gaining share fastest.
Application:
Margin profiles diverge between price-sensitive leisure cruising and mission-critical defense procurement.
- Leisure Activities:Yacht charter and day-cruise operators seek premium hydrofoil platforms for wake-restricted fjord routes. Swedish and Norwegian coastal tourism corridors overlap with municipal transit, creating dual-revenue density.
- Coastal Transportation:Scheduled ferry and water-bus services prioritize reliability and rapid turnaround charging. Netherlands and Denmark harbor zones lead deployment as EU emissions protocols harden.
- Defense Operations:Naval and coast guard procurement emphasizes acoustic stealth and reduced thermal signatures. Scandinavian defense ministries evaluate electric platforms for archipelago patrol missions.
- Environmental Monitoring:Research and enforcement vessels require minimal disturbance to marine ecosystems. German and Finnish Baltic Sea research stations deploy electric craft for water quality sampling.
Coastal transportation dominates fleet deployment. Leisure activities show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scandinavian buyers accept steep electrification premiums for fjord access rights, while Mediterranean operators resist until retrofit economics align with diesel parity.
Norway
Oslofjord municipal transit and Geiranger UNESCO tourism corridors generate overlapping demand for zero-emission vessels. The Norwegian Maritime Authority enforces harbor access restrictions under national fjord protection statutes. Bergen and Stavanger shipyards concentrate hull assembly for battery-electric ferry platforms serving coastal archipelago routes.
Netherlands
Rotterdam harbor container distribution and Amsterdam canal transit create dual-use procurement volume for short-range electric craft. The EU Green Deal maritime protocols administered by the European Maritime Safety Agency mandate battery certification standards for commercial harbor access. Dutch inland waterway operators in the Randstad cluster pilot swappable battery modules for 50-nautical-mile distribution radii.
Denmark
Copenhagen harbor authorities and Danish inter-island ferry routes drive public transit electrification timelines. National procurement rules favor operational expenditure models that separate hull ownership from drivetrain leasing. Shipyards in the Øresund corridor assemble hybrid platforms for 100-nautical-mile legs where shore power infrastructure remains incomplete.
United States
North American marina operators seek drop-in electric outboard compatibility for existing leisure hulls, prioritizing retrofit capital efficiency over new-build premiums. The US Coast Guard coordinates lithium-ion fire-suppression protocols with the EPA for commercial passenger certification. Pacific Northwest and Great Lakes boating clusters represent concentrated demand for 48V-96V recreational systems.
South Korea
Korean suppliers advance solid-state battery density improvements that extend vessel range thresholds for coastal routes. The Ministry of Trade, Industry and Energy supports maritime fuel-cell stack development for defense procurement channels. Busan-Ulsan industrial corridors concentrate cathode material processing for export to European hull-assemblers.
Electric Boat Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the electric boat sector. Torqeedo GmbH and Candela Technology AB control proprietary architectures that compress supply timelines for European OEMs, while component vendors capture retrofit channels in North American marinas. Three archetypes dominate: integrated drivetrain manufacturers with captive battery-motor systems, hydrofoil engineering specialists targeting premium leisure displacement, and outboard retrofit suppliers optimizing for legacy hull compatibility. Consolidation pressure is accelerating through strategic partnerships between hull-assemblers and battery suppliers, alongside geographic expansion of charging infrastructure networks.
Among European integrated specialists, Torqeedo GmbH and Candela Technology AB exemplify divergent technical strategies—one optimizing supply-chain control through in-house motor and battery architecture, the other reducing drag coefficients via computer-stabilized foiling hulls for wake-restricted corridors. Vision Marine Technologies anchors North American positioning as a retrofit-focused outboard supplier. These three occupy distinct competitive vectors rather than direct confrontation, with specialization depth determining margin capture across municipal transit, premium leisure, and aftermarket channels.
| Leading Market Players |
|---|
| Torqeedo GmbH |
| Duffy Electric Boat |
| Candela Technology AB |
| Vision Marine Technologies |
| Ruban Bleu |
| Elco Motor Yachts |
| Silent Yachts |
| Pure Watercraft |
| Evoy |
| Others |
Supply Flow & Price Mechanics
Ninety-day battery module lead times from Korean cathode suppliers compress procurement windows for European hull-assemblers while amplifying pricing power for integrated drivetrain manufacturers who control captive cell inventories. This inventory tension concentrates margin capture upstream with Torqeedo GmbH and Candela Technology AB, forcing component-dependent assemblers into cost-pass-through arrangements with municipal ferry authorities.
Pricing Analysis
After-sales service contracts and battery replacement programs generate lifetime value multiples exceeding initial vessel sales for integrated suppliers. Three-tier pricing structure across premium hydrofoil, certified municipal ferry, and economy retrofit outboard levels separates Candela's wake-restricted leisure platforms from Torqeedo's transit-grade architectures. Cost compression in standard ferry drivetrains intensifies as Dutch and Danish authorities consolidate procurement volumes. Private marina operators in North America exhibit highest price sensitivity, while Norwegian municipal transit authorities accept electrification premiums for UNESCO fjord access rights.
Supply Chain Analysis
Inventory concentration in South Korean solid-state cell foundries and Chinese lithium hydroxide processing clusters extends replenishment cycles for European battery-electric ferry builders. Cathode material supply draws from Indonesian nickel, Chilean lithium, and Congolese cobalt extraction networks. Single-source vulnerability in Korean maritime fuel-cell stack production threatens defense procurement timelines. Distribution runs through hull-assemblers in Norwegian and Dutch shipyards who integrate drivetrain subsystems from specialized suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric boat adoption sits in early-cycle expansion as EU Green Deal harbor access rules force accelerated diesel fleet replacements across Scandinavian coastal corridors.
For Market Incumbents: Fortify supply-chain control through backward integration into Korean solid-state cell partnerships or captive cathode material offtake agreements. Lock in multi-year drivetrain leasing contracts with Oslofjord and Copenhagen municipal authorities before competing platforms achieve certification. Threat of Vision Marine Technologies' retrofit outboard penetration into North American leisure channels demands preemptive channel consolidation.
For New Entrants and Emerging Players: Lead with swappable battery module architectures for Dutch inland waterway container barges, the most penetrable segment where charging infrastructure gaps still exclude pure-electric competitors. Target Mediterranean fishing cooperatives in Italian and Greek island harbors with 48V retrofit outboard systems priced at diesel parity. Go-to-market through marina operator consortia rather than direct vessel owner sales.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified marine engineering conglomerates seeking to divest non-core electric propulsion divisions amid capital reallocation to core fossil-fuel segments. Long-term viability hinges on sustained regulatory tightening across EU harbor zones rather than technology cost curves alone. Signal to watch: acceleration of US Coast Guard lithium-ion fire-suppression certification timelines for commercial passenger applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures Korean solid-state cell allocation for Norwegian ferry production slots under EU Green Deal timelines. |
| Harbor Infrastructure Partnership | Locks in Rotterdam and Copenhagen shore-power installation schedules ahead of vessel delivery commitments. |
| Hydrofoil Platform Expansion | Extends Candela's wake-restricted technology to Dutch canal transit routes overlapping leisure and municipal demand. |
| Retrofit Outboard Distribution | Captures North American marina operator channel through Vision Marine Technologies' legacy hull compatibility. |
| Fuel-Cell Defense Procurement | Positions Korean suppliers for Scandinavian naval silent-propulsion contracts beyond battery-electric range limits. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with ferry procurement officers at Norwegian and Dutch harbor authorities, drivetrain engineering leads at integrated suppliers, and marina operators across Pacific Northwest boating clusters; and secondary validation through EU Green Deal regulatory filings, European Maritime Safety Agency battery certification records, US Coast Guard lithium-ion safety protocols, and Korean Ministry of Trade maritime fuel-cell development disclosures. Bottom-up vessel deployment tallies triangulated against top-down market sizing from cathode material trade flows and shipyard order book aggregations.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning propulsion architecture, vessel class, end-user procurement structure, and regional regulatory cluster intensity. CAGRs derived from compound growth trajectory analysis of installed base expansion and replacement cycle compression. Forecast inputs incorporated solid-state battery density improvement curves from Korean suppliers and divergent port electrification infrastructure timelines across EU and North American harbor zones.
The analysis sits within stated boundaries; outcomes outside sustained EU emissions protocol enforcement or accelerated US commercial certification pathways would require recalibration. Forecasts reflect documented assumptions regarding cathode material supply continuity and harbor grid upgrade coordination. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Growth Removal Tool Market
Marine
Azimuth Thrusters Market
Marine
Marine Chartplotter Market
Marine
Offshore Autonomous Underwater Vehicle (AUV) Market
Marine
US Fish Finders Market
Marine
Electric Outboard Engines Market
Marine
Marine Asset Integrity Services Market
Marine
Sailboat Market
Marine
Trim Tabs Market
Marine
Integrated All-Electric Propulsion System for Ships Market
Marine
Marine Glass Market
Marine
Marine Trenchers Market
Marine
Boat Control Lever Market
Marine
Marine Turbocharger Market
Marine
Marine Fuel Injector Market
Marine
Marine Pipes Market