
 US Fish Finders Market | 2026-2036
US Fish Finders Market Size, Share, and Industry Trends Forecast 2026-2036
US Fish Finders Market Insights
FCC Part 80 and Part 87 equipment authorization is rotating the competitive landscape for marine electronics manufacturers seeking US market access. Garmin Ltd. leverages vertical integration across GPS and sonar module production to sustain pricing flexibility. Humminbird anchors its position through specialized freshwater imaging algorithms that dominate tournament angler preferences. Lowrance competes aggressively on transducer frequency range and chartplotter integration depth.
US fish finders are electronic marine instruments that emit acoustic pulses through water columns and interpret returning echoes to render underwater topography, fish location, and structure identification on graphical displays, typically operating at frequencies between 50 kHz and 1.2 MHz depending on water depth and target resolution requirements. Their primary commercial purpose is to enhance catch efficiency for recreational and professional operators by reducing search time and improving target species identification. Portable units command the highest volume growth as kayak and ice fishing participation expands, while networked systems capture the strongest margin pools through multi-display helm integration on larger vessels. Sonar technology remains the foundational revenue layer, though 3D imaging segments are attracting R&D investment from manufacturers seeking differentiation in premium tiers.
FCC equipment authorization, NMEA 2000 certification protocols, and Coast Guard safety standards collectively shape product design cycles and aftermarket compatibility requirements for US fish finder manufacturers. The FCC's evolving RF emission rules are forcing hardware redesigns that extend development timelines by several quarters for importers lacking pre-certified modules. Stakeholders must monitor NMEA interface standard revisions and state-level fishing license fee structures to anticipate replacement demand cycles and channel inventory positioning.
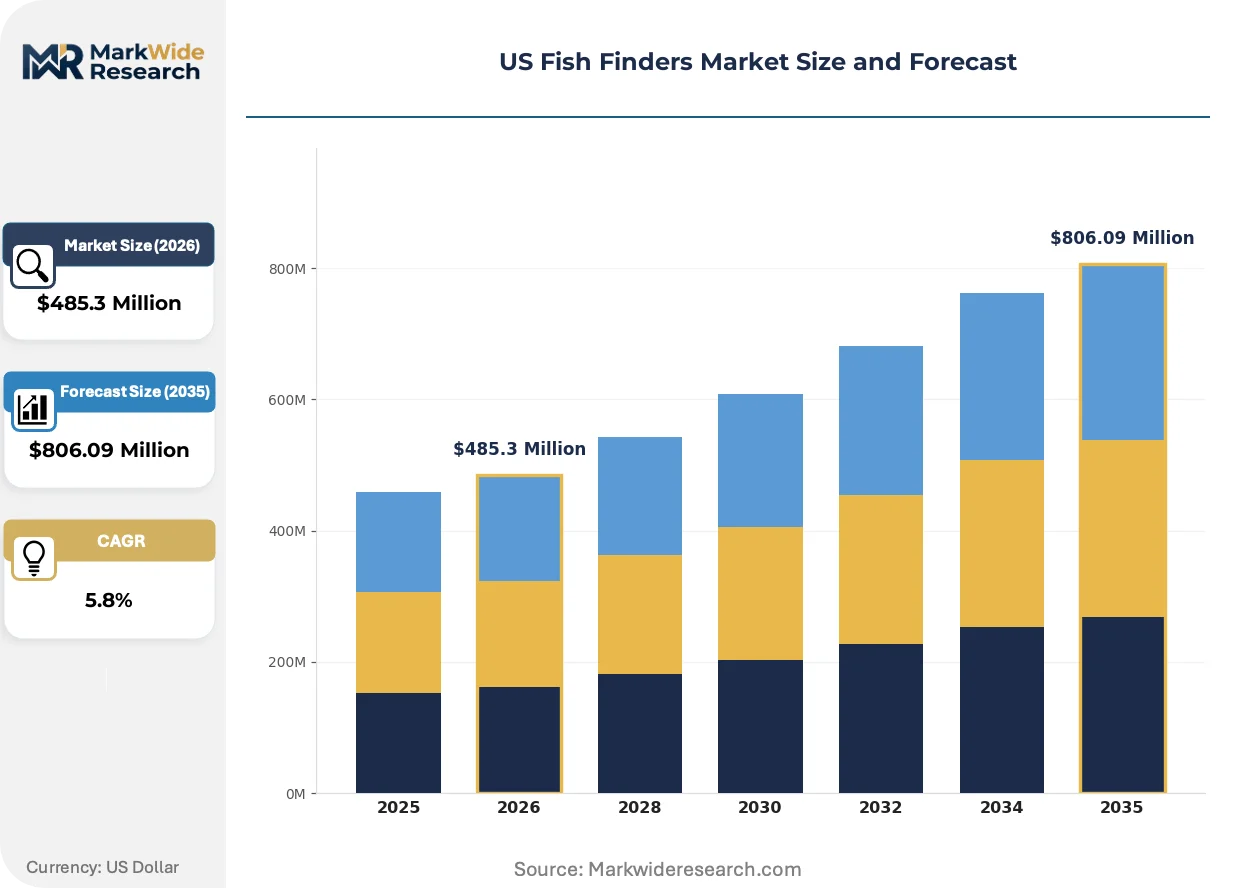
Market Dynamics
FCC Part 80 equipment authorization timelines are compressing product development cycles for marine electronics manufacturers, forcing faster RF module certification and accelerating obsolescence of legacy sonar architectures that cannot meet tightened emission standards.
Growth Catalysts
- Kayak Fishing Expansion:Portable fish finder demand concentrates among paddle-sport anglers seeking lightweight, battery-powered units for shallow-water structure mapping.
- FCC Equipment Authorization Streamlining:Pre-certified RF module availability is shortening time-to-market for mid-tier manufacturers lacking in-house electromagnetic compliance labs.
- Ice Fishing Participation:Flashers and portable sonar units experience seasonal demand spikes across Minnesota, Wisconsin, and Michigan where hard-water angling license sales remain elevated.
Market Restraints
- Semiconductor Supply Concentration:Transducer piezoelectric ceramics and specialized ADC chips depend on concentrated Asian substrate suppliers, creating input cost volatility.
- Freshwater-Saltwater Performance Trade-offs:Single-frequency units face technical limitations in brackish estuary environments where conductivity variations degrade signal clarity.
- NMEA 2000 Certification Friction:Network protocol compliance testing adds quarters to product launches for manufacturers lacking established marine electronics certification relationships.
Strategic Opportunities
- Great Lakes Underpenetration:Tournament-grade networked systems remain underdeployed among charter operators on Lake Erie and Lake Ontario.
- Smartphone Integration Convergence:WiFi-enabled castable transducers paired with iOS and Android applications are opening entry-price-tier adoption among casual anglers.
- Inflation Reduction Act Marine Electrification:Electric outboard subsidies are expanding addressable vessel populations requiring integrated helm electronics including fish finders.
Industry Challenges
- Sonar Algorithm Talent Scarcity:Machine learning engineers with hydroacoustic signal processing expertise command premium compensation, constraining R&D expansion.
- Legacy Transducer Integration Complexity:Retrofit installations on older fiberglass hulls require specialized through-hull mounting expertise that strains dealer technician capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Fish Finders Market |
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $806.09 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Fixed, Networked, Smartphone-Compatible Technology: Sonar, GPS, 3D Imaging, Multi-Beam End User: Recreational Anglers, Commercial Fishers, Research Institutions, Tour Operators Distribution Channel: Online Retailers, Specialty Stores, Wholesalers, Direct Sales |
| Companies Covered | Garmin Ltd., Humminbird, Lowrance, Raymarine, Furuno Electric Co. Ltd., Simrad, Johnson Outdoors Inc., Vexilar, Navico, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Fish Finders Market Trends and Innovations
DownScan and SideScan imaging architectures are compressing the performance gap between mid-tier and premium units, reshaping replacement cycles and margin structures across the US marine electronics channel.
CHIRP (Compressed High-Intensity Radiated Pulse) sonar is displacing traditional single-frequency pulse systems in the tournament angler segment. Bassmaster Elite Series competitors now demand swept-frequency modulation for target separation at depth. This technology is displacing legacy 200 kHz narrowband transducers from professional installations, compressing residual value of non-CHIRP inventory.
FCC Part 80 Subpart T emission rule revisions are mandating reduced spurious RF outputs from marine transmitters. Hardware redesigns for compliance are extending development timelines for importers lacking pre-certified module relationships. Saltwater charter operators in Florida and Louisiana face delayed availability of next-generation units as manufacturers prioritize domestic certification submissions.
Subscription-based cartography and software updates are unbundling from hardware purchases among Great Lakes walleye anglers. Navionics and C-MAP are capturing recurring revenue streams that previously accrued to dealer service departments. This shift concentrates most visibly among Michigan and Ohio tournament competitors who demand quarterly bathymetric updates for competitive structure identification.
US Fish Finders Market Segmentation
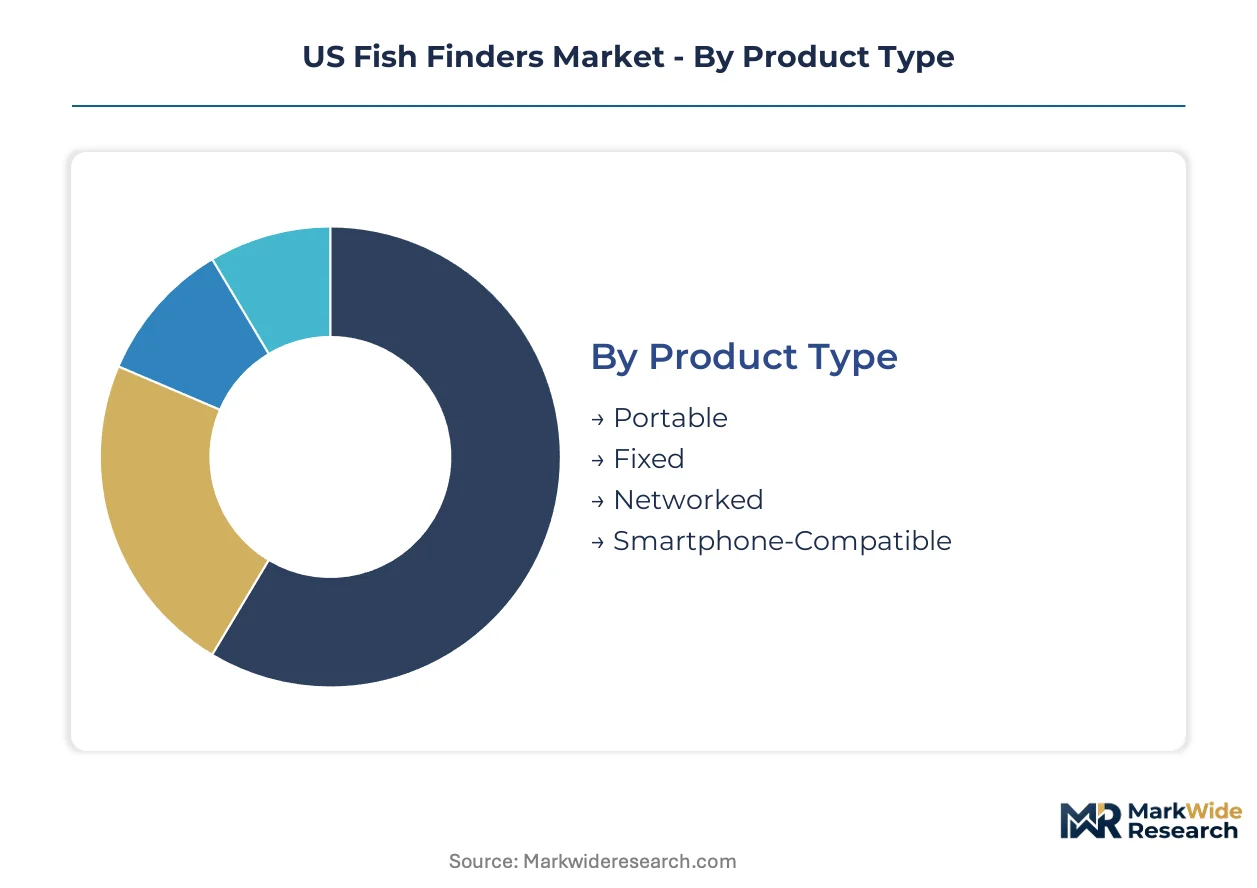
Segmentation in the US fish finders market reveals how substitution pressures from smartphone apps and castable transducers reshape competitive boundaries across hardware categories. Manufacturers must defend discrete product tiers against converging technologies while exploiting installation and performance gaps that mobile alternatives cannot bridge.
Product Type:
Portable units face the most acute substitution threat from smartphone-integrated castable systems, while networked helm installations remain insulated from mobile disruption due to NMEA 2000 integration complexity and multi-display synchronization requirements.
- Portable:Battery-powered units weighing under two pounds dominate kayak and ice fishing applications across Minnesota, Wisconsin, and Michigan. Paddle-sport anglers in the Great Lakes region drive replacement cycles as seasonal participation expands and waterproofing standards tighten.
- Fixed:Through-hull and transom-mount installations on bass boats and center consoles capture the strongest margin pools through transducer frequency customization. Gulf Coast charter operators in Louisiana and Florida prioritize fixed installations for saltwater durability and CHIRP compatibility.
- Networked:Multi-display helm systems integrate with radar, autopilot, and engine monitoring via NMEA 2000 backbone architecture. Tournament anglers on Lake Erie demand synchronized chartplotter-sonar workflows for competitive structure mapping.
- Smartphone-Compatible:WiFi-enabled castable transducers pair with iOS and Android applications for entry-price-tier adoption. Casual anglers in coastal Georgia and the Carolinas favor this segment for shoreline and pier fishing accessibility.
Fixed installations retain volume leadership; smartphone-compatible units hold the steepest expansion curve.
Technology:
Cost tier stratification concentrates R&D investment in swept-frequency architectures that command premium positioning, while legacy single-frequency modules defend economy-tier price points against commoditization.
- Sonar:Traditional pulse-echo systems operating at 50-200 kHz remain foundational for depth sounding and bottom classification. Recreational anglers on the Mississippi River system continue specifying narrowband sonar for cost-sensitive freshwater applications.
- GPS:Integrated position-fixing modules enable waypoint marking, track plotting, and geo-referenced structure mapping. Coastal saltwater operators from Texas to Maine require WAAS-enabled receivers for offshore waypoint accuracy.
- 3D Imaging:Volumetric rendering of underwater terrain and fish schools demands specialized transducer arrays and GPU-intensive processing. Tournament competitors on Lake Ontario deploy 3D systems for suspended walleye identification at thermocline depths.
- Multi-Beam:Simultaneous multiple-angle insonification expands swath coverage for hydrographic survey and commercial trawling efficiency. Research institutions monitoring Chesapeake Bay habitat restoration utilize multi-beam for benthic mapping at survey-grade resolution.
Sonar retains installed-base dominance; 3D imaging captures the steepest margin expansion trajectory.
End User:
Customer-type concentration shapes channel strategy, with recreational volume driving inventory turns while commercial and institutional accounts anchor service contract profitability.
- Recreational Anglers:License-holding freshwater and saltwater hobbyists represent the addressable population base for portable and mid-tier fixed units. Bass fishing participation across Alabama, Tennessee, and Kentucky sustains replacement demand for CHIRP-equipped electronics.
- Commercial Fishers:Professional harvesting operations require Type-Approved equipment meeting Coast Guard carriage requirements for vessels over specific tonnage thresholds. Gulf shrimpers and Pacific Northwest salmon seiners prioritize ruggedized transducers and redundant depth sounding.
- Research Institutions:Universities and government agencies deploy survey-grade systems for fisheries science and habitat monitoring. NOAA-affiliated programs on the Atlantic and Pacific coasts specify calibrated multi-beam for stock assessment protocols.
- Tour Operators:Charter captains and guided fishing services integrate networked systems for client experience differentiation and operational efficiency. Florida Keys flats guides emphasize shallow-water side-imaging for sight-fishing preparation.
Recreational anglers retain volume leadership; tour operators hold the steepest technology upgrade curve.
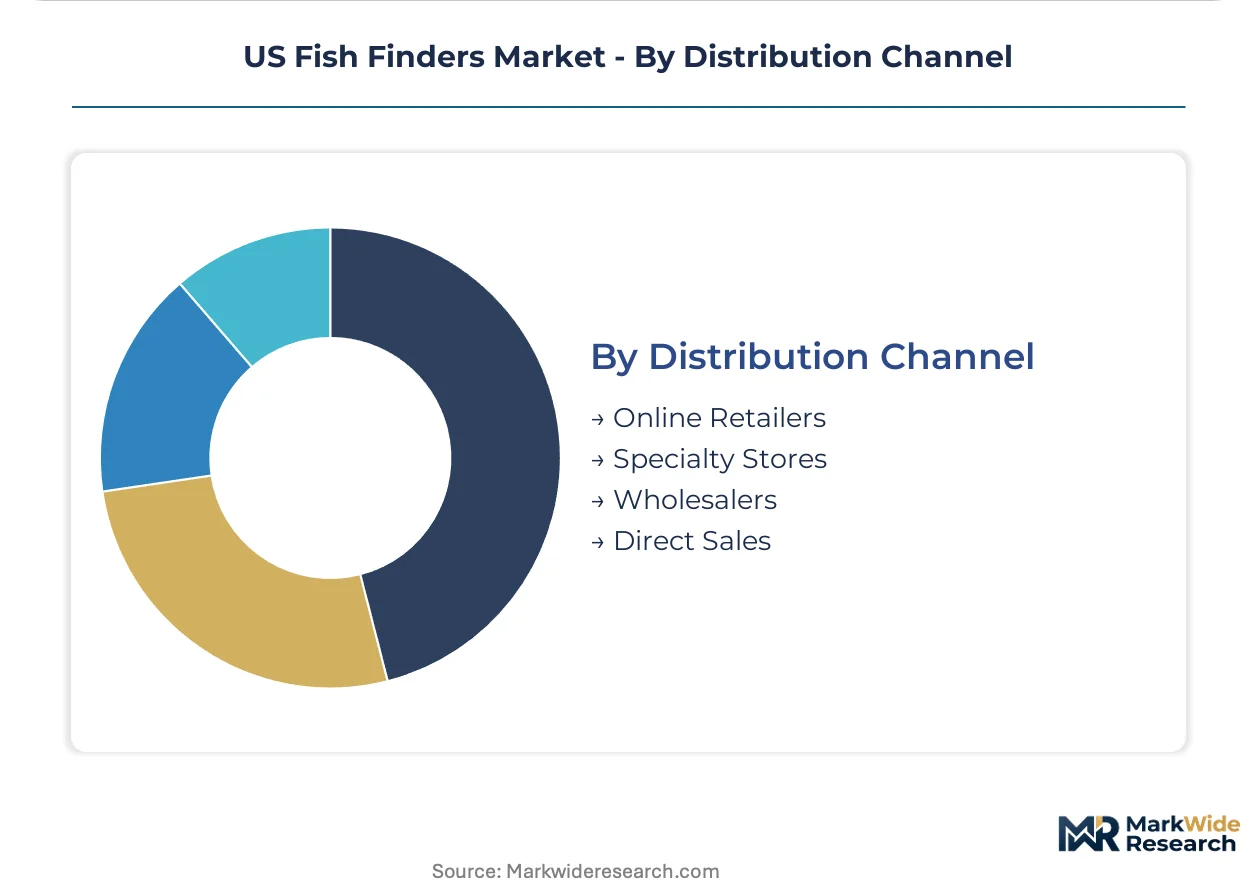
Distribution Channel:
Geography of demand concentration privileges specialty retail in tournament-dense regions while online capture expands where installation complexity remains low.
- Online Retailers:E-commerce platforms dominate portable and smartphone-compatible unit sales through price transparency and review aggregation. Amazon and dedicated marine electronics sites capture share among tech-comfortable anglers in urban and suburban markets.
- Specialty Stores:Independent marine dealers and big-box outdoor retailers provide installation services and technical consultation. Bass Pro Shops and Cabela's locations across the Great Lakes and Southeast anchor tournament-angler purchasing.
- Wholesalers:Distributor networks supply smaller dealers and repair shops with inventory and factory-authorized service capabilities. Regional wholesalers in the Great Lakes corridor maintain relationships with legacy fiberglass hull retrofit specialists.
- Direct Sales:Manufacturer-owned channels serve OEM boat builders and large fleet operators with volume pricing and custom integration support. Ranger and Nitro boat factories specify direct-procured networked systems for new-boat production.
Specialty stores retain volume leadership; online retailers hold the steepest share expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recreational anglers concentrate demand in freshwater basins and coastal corridors where tournament fishing infrastructure and charter operator density create localized equipment upgrade cycles. State-level fishing license structures and federal waterway access programs shape replacement timing across sub-regional markets.
Great Lakes Region
Walleye and salmon tournament circuits in Michigan, Ohio, and Wisconsin drive networked system adoption among competitive anglers. EPA Great Lakes Restoration Initiative funding expands habitat mapping contracts for research-grade multi-beam deployments. Cleveland and Milwaukee anchor freshwater electronics distribution networks serving Lake Erie and Lake Ontario charter fleets.
Gulf Coast States
Louisiana and Florida saltwater charter operators prioritize CHIRP-compatible fixed installations for nearshore and offshore species targeting. Coast Guard safety equipment carriage rules for inspected passenger vessels mandate redundant depth sounding on larger charter boats. Tampa Bay and Venice, Louisiana concentrate marine electronics dealer capacity for retrofit installations on fiberglass hulls.
Southeastern Atlantic Corridor
Georgia and Carolinas kayak fishing participation expands portable unit sales through paddle-sport retail channels. State wildlife agency public access ramp investments reduce shoreline fishing barriers for casual anglers. Charleston and Savannah harbor districts support commercial shrimping electronics maintenance through specialized service technicians.
Pacific Northwest
Washington and Oregon salmon seiners and recreational crabbers specify ruggedized transducers for cold-water durability. NOAA fisheries research contracts in Puget Sound sustain institutional demand for calibrated hydroacoustic systems. Seattle anchors commercial marine electronics procurement relationships with Alaska-bound harvesting operations.
Southwest and Mountain West
Arizona and Colorado reservoir bass fishing sustains mid-tier fixed unit replacement cycles among recreational boat owners. Bureau of Reclamation water level management affects structure mapping relevance for anglers targeting fluctuating shorelines. Phoenix and Denver metropolitan areas concentrate big-box outdoor retail distribution for weekend angler segments.
US Fish Finders Market Competitive Landscape
Player mix skews toward vertically integrated electronics conglomerates with captive sonar module production and specialized marine instrumentation subsidiaries. Market structure concentrates around three to four holding companies controlling multiple brand positions across price tiers. Strategic archetypes include GPS-navigation conglomerates with marine divisions, dedicated fishing electronics specialists, and diversified industrial instrumentation groups. Competitive moves center on RF module pre-certification partnerships and NMEA 2000 protocol licensing arrangements.
Within the navigation-electronics tier, Garmin Ltd. and Raymarine occupy positions exemplifying backward integration into transducer manufacturing and display panel supply chains. Humminbird and Lowrance anchor the freshwater-specialist archetype, representing tournament-angler-focused algorithm development and frequency-range customization capabilities. Furuno Electric Co. Ltd. sits within the commercial-grade instrumentation segment, reflecting industrial-hardened product architectures serving professional harvesting operations.
| Leading Market Players |
|---|
| Garmin Ltd. |
| Humminbird |
| Lowrance |
| Raymarine |
| Furuno Electric Co. Ltd. |
| Simrad |
| Johnson Outdoors Inc. |
| Vexilar |
| Navico |
| Others |
Pricing and Supply Chain Analysis
Long-term RF module offtake agreements with pre-certified component suppliers lock in both FCC compliance timelines and transducer cost visibility for marine electronics manufacturers navigating volatile piezoelectric ceramic markets.
Pricing Analysis
Cost-plus contracts with Asian substrate suppliers indexed to rare earth oxide fluctuations dominate transducer procurement. Three-tier pricing structure across premium CHIRP systems, standard GPS-integrated units, and economy narrowband sonar separates tournament anglers from casual recreational buyers. Pricing pressure stems from semiconductor input volatility as ADC chip lead times extend. Kayak and ice fishing segments exhibit highest price sensitivity while networked helm installations on charter vessels show lowest elasticity.
Supply Chain Analysis
Strategic stockpiling of piezoelectric ceramics and specialized ADC chips buffers Great Lakes distributors against seasonal demand spikes and Asian supplier disruptions. Manufacturing concentrates in China, Taiwan, and South Korea for transducer substrates and RF modules. Raw material dependencies include lead zirconate titanate ceramics, gallium arsenide wafers, and marine-grade aluminum housings. Single-source vulnerability around FCC pre-certified RF modules creates compliance bottlenecks. Distribution runs through regional marine wholesalers serving independent dealers across the Gulf Coast and Great Lakes corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seasonal license sales cycles and tournament fishing calendars create predictable replacement demand windows that manufacturers can exploit for inventory positioning and promotional timing.
For Market Incumbents: Secure NMEA 2000 certification relationships with boat builders to preempt smartphone-integrated castable transducers from penetrating networked helm installations. Deepen backward integration into CHIRP signal processing ASIC design to defend margin pools against mid-tier competitors leveraging pre-certified modules. For New Entrants and Emerging Players: Anchor in Great Lakes walleye tournament circuits where subscription-based cartography unbundling has weakened incumbent dealer relationships. Target smartphone-compatible castable transducers for shoreline anglers in Georgia and Carolinas kayak fishing communities. Pursue WiFi-enabled hardware paired with freemium app models to bypass specialty retail channel costs. For Investors and Strategic Acquirers: Marine electronics specialists with captive sonar algorithm development teams and established FCC equipment authorization track records present durable acquisition targets. Long-term viability hinges on software-defined differentiation as hardware commoditization accelerates. Watch for FCC Part 80 emission rule revision timing as inflection indicator for R&D capital deployment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| FCC Pre-Certification Partnership | Shrinks time-to-market for RF module-dependent product launches by several quarters. |
| NMEA 2000 Protocol Licensing | Locks in multi-display helm integration standards that smartphone alternatives cannot replicate. |
| CHIRP Algorithm Patent Acquisition | Consolidates swept-frequency signal processing expertise that tournament anglers now demand. |
| Subscription Cartography Integration | Captures recurring revenue streams that Navionics and C-MAP currently extract from hardware sales. |
| Ice Fishing Flasher Seasonal Production | Aligns manufacturing capacity with Minnesota and Wisconsin hard-water license sale peaks. |
Research Methodology
Operator-level perspectives from marine electronics dealers, tournament angling captains, charter boat operators, and FCC compliance consultants anchored the qualitative base. Secondary validation drew from Coast Guard safety equipment carriage databases, state fishing license sales records, and NMEA protocol documentation standards. Bottom-up unit demand estimates across portable, fixed, networked, and smartphone-compatible product tiers triangulated against top-down market sizing from marine electronics wholesale shipment data.
Sensitivity analysis tested forecast robustness across semiconductor supply disruption scenarios and FCC equipment authorization timeline compression cases. Modeled segmentation dimensions spanned product type, technology architecture, end-user category, and distribution channel structure. CAGRs derived from fitted growth curves applied to replacement cycle analysis and participation rate projections. Industry-specific inputs included tournament fishing calendar density and electric outboard subsidy uptake rates from Inflation Reduction Act programs.
Material uncertainties — semiconductor supply concentration shifts, FCC emission rule revision timing, and NMEA interface standard updates — sit outside the modeled envelope. Forecasts reflect assumptions around stable fishing license fee structures and continued Great Lakes Restoration Initiative funding levels. Revision becomes warranted when transducer piezoelectric ceramic supply disruptions exceed six-month durations or FCC certification backlogs extend beyond normalized processing windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Navigation System Market
Marine
Global Foldable Inflatable Boats Market
Marine
Marine LED Lights Market
Marine
Asia-Pacific Marine Communication Systems Market
Marine
Digital Nautical Charts Market
Marine
Integrated Bridge System for Ships Market
Marine
Controllable Pitch Marine Propeller Market
Marine
Unmanned Marine Vehicles Market
Marine
Boat Hook Market
Marine
Recreational Vessel Battery Market
Marine
Trim Tabs Market
Marine
Marine AIS Monitoring System Market
Marine
Offshore Autonomous Underwater Vehicle (AUV) Market
Marine
Hydrogen Ships Market
Marine
Marine Filter Market
Marine
Marine Shackle Market