
 Integrated All-Electric Propulsion System for Ships Market | 2026-2036
Integrated All-Electric Propulsion System for Ships Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated All-Electric Propulsion System for Ships Market Insights
Silicon carbide power modules are realigning inverter economics in marine electric drives. ABB leverages its traction motor heritage to dominate high-megawatt ferry installations. Wärtsilä anchors its position through backward integration into energy management software. Kongsberg specializes in podded propulsion configurations for ice-class vessels.
An integrated all-electric propulsion system for ships combines battery systems, fuel cells, electric motors, and power electronics to generate thrust without internal combustion prime movers. These systems typically operate at 690V to 3.3kV DC bus voltages with permanent magnet synchronous motors delivering 1-20 MW per shaft line. Commercial vessels represent the leading application segment where route predictability enables battery sizing optimization. Power electronics constitutes the fastest-growing technology segment as silicon carbide and gallium nitride devices displace silicon IGBTs at higher switching frequencies.
The EU Green Deal and IMO's carbon intensity regulations are tightening compliance windows for vessel operators across European and international fleets. EPA marine engine standards and China's MEE emission rules add parallel compliance layers for ships calling at US and Chinese ports. Shipbuilders and marine operators must monitor fuel cell system maturity against battery energy density improvements to time capital commitments for next-generation fleet designs.
Market Dynamics
Silicon carbide power electronics are compressing inverter footprints while raising switching frequencies, forcing shipyards to redesign engine room layouts around thermal management rather than mechanical drivetrain geometry. This technology transition is restructuring supplier relationships and certification timelines simultaneously.
Growth Catalysts
- EU Green Deal maritime emissions targets:Compliance windows for carbon intensity are tightening vessel operator upgrade schedules across European coastal fleets. Battery system certifications are accelerating as classification societies align with Brussels-mandated decarbonization pathways.
- Norway's fjord cruise corridors:Route predictability in short-sea shipping enables precise battery sizing, reducing capital risk for electrified newbuilds. State ferry procurement mandates now require zero-emission capability for domestic routes.
- Silicon carbide modules:Higher switching frequencies at 690V to 3.3kV DC bus architectures are shrinking power electronics volume by half. Shipyards gain cargo space and machinery arrangement flexibility.
Market Restraints
- Lithium-ion cell supply concentration:Cathode material processing and cell manufacturing cluster in East Asian supply chains, exposing European and North American shipbuilders to geopolitical logistics risk and long lead times for marine-grade battery systems.
- Charging infrastructure capex:Shore power installations at 10-20 MW require harbor authority coordination and grid reinforcement that outpaces vessel electrification timelines in secondary ports.
- Fuel cell system maturity gaps:Proton exchange membrane durability in salt-air environments remains unproven for 20-year vessel lifecycles, forcing hybrid architectures that increase system complexity and maintenance training requirements.
Strategic Opportunities
- Ice-class podded propulsion:Arctic route openings and polar code compliance are creating demand for azimuthing electric thrusters with ice-strengthened gearboxes. Kongsberg's configuration expertise positions Nordic suppliers for polar expedition and research vessel contracts.
- Energy management software integration:Vessel operators seek voyage optimization platforms that coordinate battery state-of-charge, shore power scheduling, and route planning. Wärtsilä's backward integration into control systems captures recurring revenue streams beyond hardware sales.
- China's MEE emission rules:Port state control inspections at Shanghai, Shenzhen, and Ningbo-Zhoushan are accelerating scrubber retrofits and electrification interest among international carriers with Asia-Pacific strings.
Industry Challenges
- Marine electrical engineering talent scarcity:Shipyards lack sufficient high-voltage power electronics specialists to support simultaneous newbuild and retrofit programs. Training pipelines for 690V to 3.3kV DC system commissioning remain underdeveloped.
- Type approval timeline compression:Classification societies face backlog pressures as novel battery chemistries and fuel cell configurations seek certification. Bureaucratic delays extend project financing windows and delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated All-Electric Propulsion System for Ships Market |
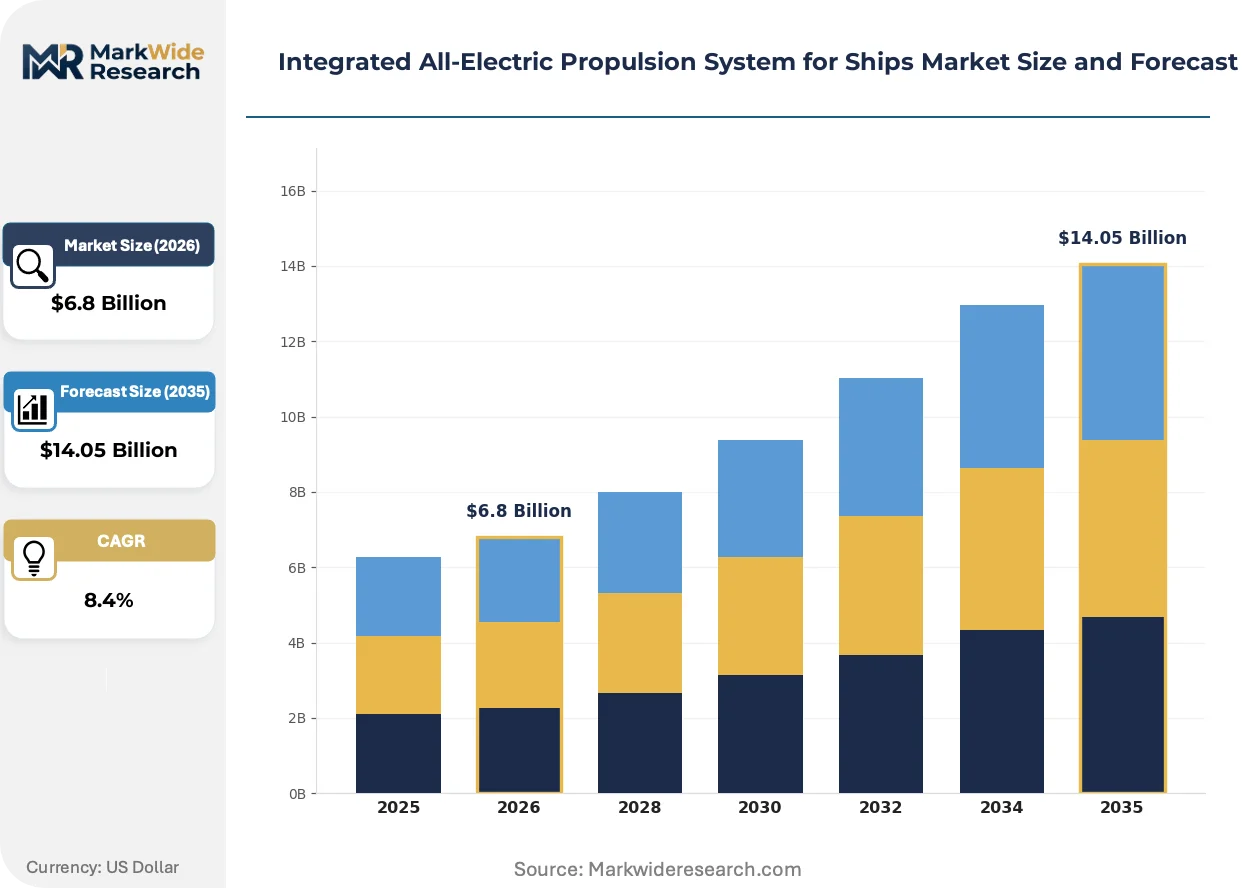
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Propulsion Type: Axial Flow, Radial Flow, Direct Drive, Hybrid Application: Commercial Vessels, Defense Vessels, Offshore Support, Research Vessels Technology: Battery Systems, Fuel Cells, Electric Motors, Power Electronics End User: Shipbuilders, Marine Operators, Government Agencies, Energy Companies |
| Companies Covered | Volvo Penta, Marine Propulsion Solutions, Kongsberg, Nakashima Propeller, Vetus, Wärtsilä, Thrustmaster of Texas, Max Power, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated All-Electric Propulsion System for Ships Market Trends and Innovations
Marine propulsion architecture is converging around solid-state power electronics and modular battery packaging that decouples energy storage from hull form constraints. This convergence is enabling vessel designs previously incompatible with conventional mechanical drivetrains.
Silicon carbide MOSFETs are expanding into marine inverter applications by enabling 50-100 kHz switching frequencies that shrink filter components and cooling systems. Norwegian ferry operators are adopting these modules for 3-8 MW shaftline ratings. The technology is expanding into cruise ship and offshore vessel segments where machinery space premiums command design priority.
EPA marine engine standards are tightening NOx and particulate limits for vessels operating in US coastal waters. Tier 4 compliance costs for medium-speed diesels are pushing harbor craft and short-sea operators toward full electrification where shore power infrastructure exists. California Air Resources Board harbor craft regulations are accelerating battery-electric tug and workboat deployments in Los Angeles and Long Beach.
Charter contracts are incorporating emissions performance clauses that transfer fuel cost volatility and carbon compliance risk from operators to cargo interests. Container lines serving European trades face shipper mandates for documented carbon intensity per TEU-mile. Scandinavian pulp and paper shippers are leading contract renegotiations that penalize fossil fuel consumption and reward shore power utilization.
Integrated All-Electric Propulsion System for Ships Market Segmentation
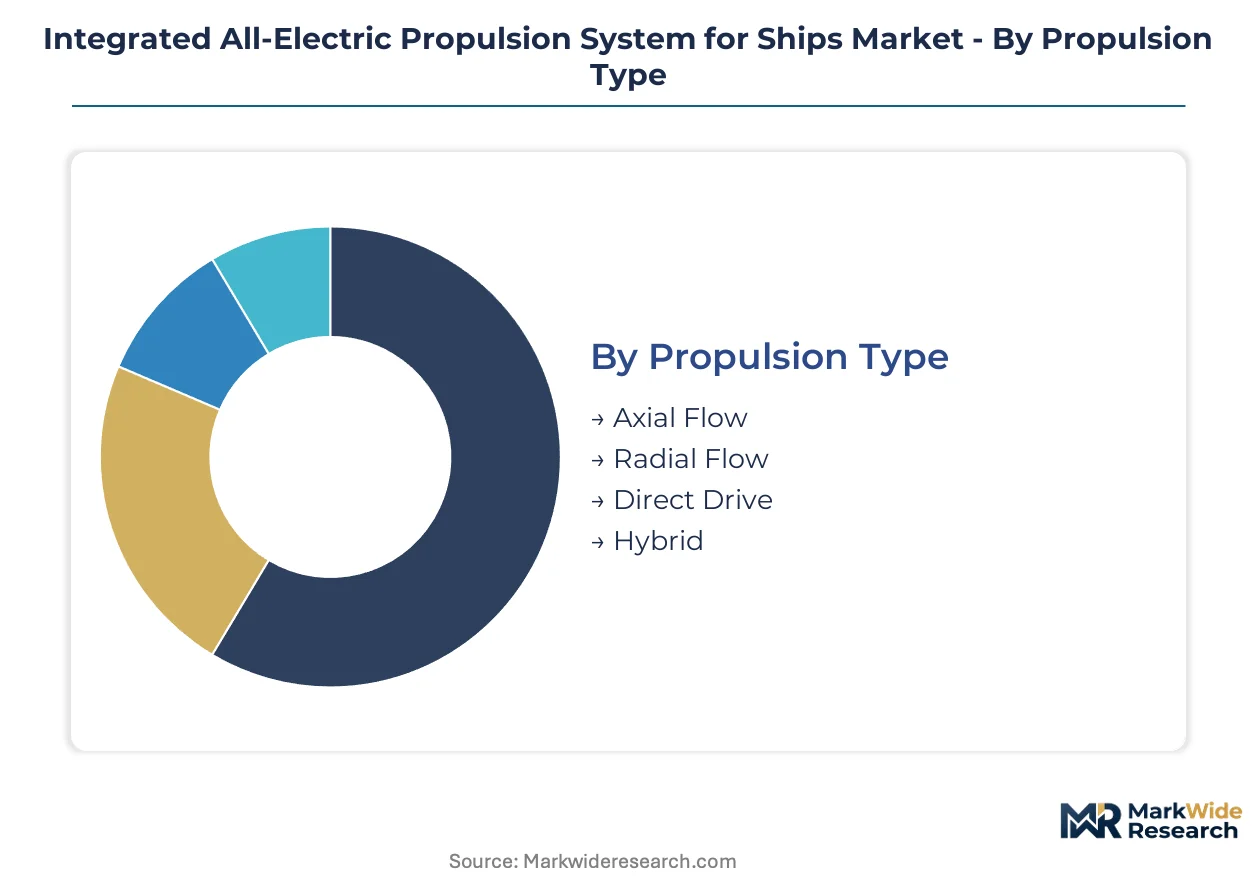
Segmentation in marine electric propulsion reveals how technology maturity, regulatory pressure, and vessel economics intersect. Route predictability and shore power availability determine which configurations achieve commercial scale first.
Propulsion Type:
Volume deployment favors proven mechanical simplicity, while premium positioning targets specialized operational profiles demanding precision maneuverability or ice-class resilience.
- Axial Flow:Configurations utilize streamlined impeller geometry optimized for high-speed ferry and cruise ship applications. Norwegian operators deploy these systems in fjord corridors where route predictability enables precise battery sizing against hydrodynamic efficiency targets.
- Direct Drive:Permanent magnet synchronous motors eliminate gearbox maintenance and reduce acoustic signature for passenger vessels. Arctic expedition operators specify these configurations for ice-class research vessels where mechanical simplicity reduces cold-weather failure modes.
- Radial Flow:Centrifugal designs suit harbor craft and tugboats requiring high thrust at low speeds.
- Hybrid:Combustion-electric architectures bridge infrastructure gaps in secondary ports lacking megawatt shore power.
Mature deployment sits with Direct Drive. Newer deployment is concentrated in Hybrid configurations.
Application:
Customer procurement patterns split between commercial operators seeking total cost of ownership reduction and institutional buyers prioritizing operational sovereignty over fuel supply chains.
- Commercial Vessels:Container feeders, ferries, and cruise ships dominate battery-electric adoption where daily route repetition enables energy storage optimization. Scandinavian ferry operators anchor procurement volumes through state mandates requiring zero-emission capability on domestic routes.
- Research Vessels:Oceanographic and polar expedition platforms demand silent propulsion for acoustic survey work. Ice-class electric podded configurations from Nordic suppliers satisfy Polar Code compliance while enabling precision station-keeping in sensitive marine habitats.
- Defense Vessels:Naval procurement prioritizes signature reduction and fuel logistics independence for littoral operations.
- Offshore Support:Platform supply and wind farm service vessels face charterer emissions clauses driving electrification interest.
Commercial Vessels hold established deployment share. Research Vessels are climbing the fastest as polar access expands.
Technology:
Supply chain concentration in East Asian cell manufacturing shapes technology adoption timelines for European and North American shipbuilders.
- Power Electronics:Silicon carbide MOSFETs enable 50-100 kHz switching frequencies that compress inverter volume by half compared to silicon IGBT legacy designs. Norwegian ferry operators at 3-8 MW ratings drive qualification timelines for these modules.
- Battery Systems:Lithium-ion marine-grade packs operate at 690V to 3.3kV DC bus architectures with thermal management systems sized for 20-year vessel lifecycles. Classification society certification backlogs extend delivery schedules for novel chemistries seeking type approval.
- Fuel Cells:Proton exchange membrane systems remain unproven for full-lifecycle salt-air exposure, forcing hybrid architectures.
- Electric Motors:Permanent magnet synchronous designs deliver 1-20 MW per shaftline with efficiency advantages over induction alternatives.
Battery Systems represent the installed base anchor. Power Electronics is expanding most quickly as silicon carbide displaces legacy semiconductor platforms.
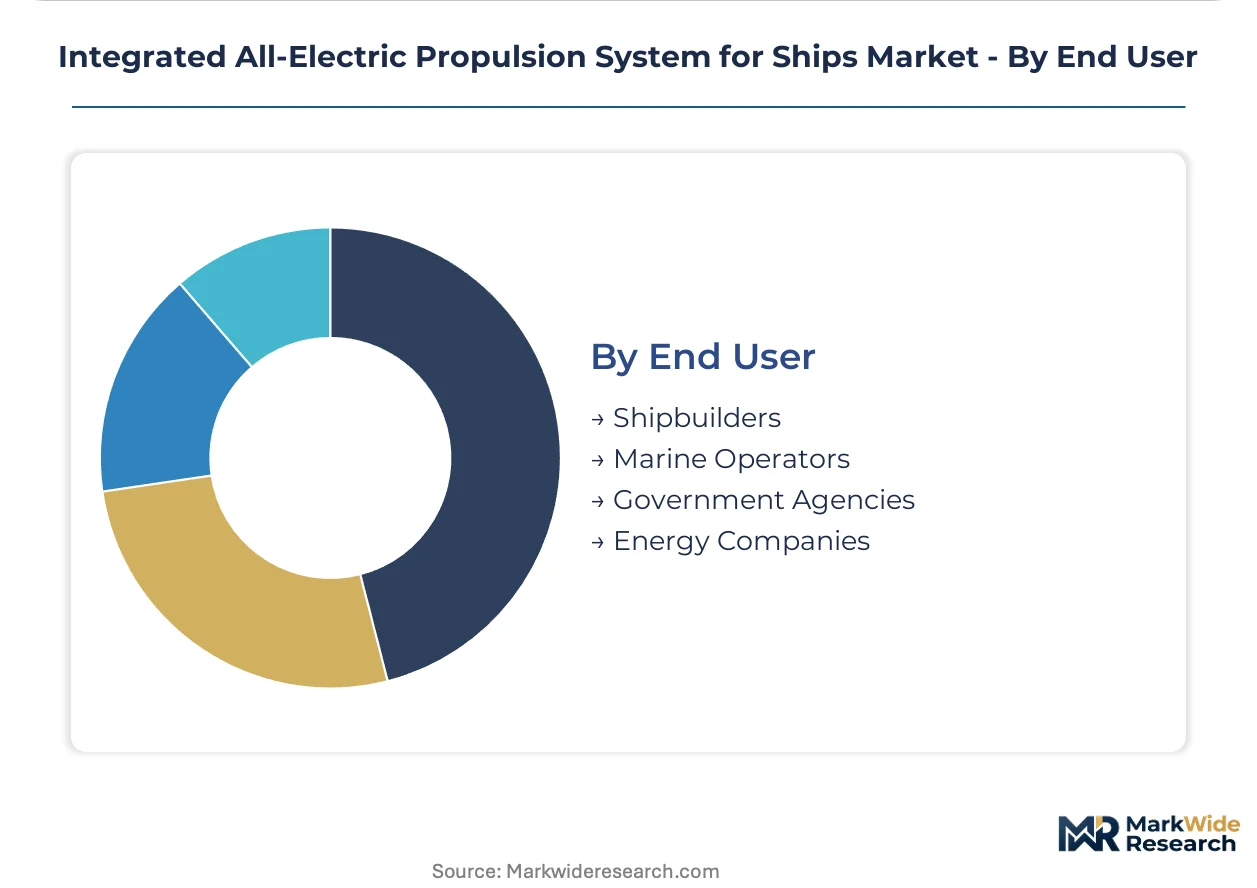
End User:
Capital commitment horizons diverge between asset owners optimizing lifetime operating cost and procurement agencies balancing capability acquisition against budget cycle constraints.
- Marine Operators:Ferry companies and container lines face charter contract emissions clauses transferring carbon compliance risk from cargo interests to vessel operators. Scandinavian pulp and paper shippers penalize fossil fuel consumption while rewarding documented shore power utilization.
- Shipbuilders:Yards in Norway, Finland, and France integrate electric propulsion as standard for coastal newbuilds, redesigning engine room layouts around thermal management rather than mechanical drivetrain geometry.
- Government Agencies:Naval and coast guard procurement prioritizes operational energy independence.
- Energy Companies:Offshore wind developers specify electric service vessels to align supply chain emissions with project certification requirements.
Marine Operators command mature procurement processes. Government Agencies represent the steepest expansion trajectory as defense electrification programs accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway concentrates procurement volumes for integrated all-electric propulsion systems through state ferry mandates and fjord cruise electrification corridors. Route predictability in Scandinavian short-sea shipping enables precise battery sizing that reduces capital risk for vessel operators.
Norway
State ferry procurement mandates now require zero-emission capability for all domestic routes. The Norwegian Maritime Authority accelerates battery system certifications aligned with Brussels-mandated decarbonization pathways. Bergen and Oslo anchor fleet electrification programs where fjord cruise operators deploy 3-8 MW shaftline configurations.
Germany
Container feeder operators face charter contract emissions clauses transferring carbon compliance risk from cargo interests to vessel operators. The KBA enforces EU Green Deal maritime emissions targets across coastal fleets. Hamburg and Bremerhaven concentrate shore power infrastructure investments at 10-20 MW scale.
China
Port state control inspections at Shanghai, Shenzhen, and Ningbo-Zhoushan accelerate scrubber retrofits and electrification interest among international carriers. The MEE emission rules tighten compliance windows for vessels calling at Chinese ports. The Yangtze River Delta clusters battery system manufacturing for marine-grade pack assembly.
United States
EPA marine engine standards tighten NOx and particulate limits for harbor craft operating in coastal waters. The California Air Resources Board mandates battery-electric tug deployments in Los Angeles and Long Beach. The Pacific Northwest and Gulf Coast concentrate offshore wind service vessel electrification programs.
Japan
Research vessel operators demand silent propulsion for acoustic survey work in sensitive marine habitats. METI coordinates fuel cell system demonstration programs for coastal ferry routes. Nagoya and Kobe anchor polar expedition vessel construction where ice-class electric podded configurations satisfy Polar Code compliance.
Integrated All-Electric Propulsion System for Ships Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with system integrators commanding premium positioning in high-megawatt ferry installations while component suppliers capture volume in harbor craft retrofits. Market structure concentrates around Nordic engineering heritage and Swiss-German power electronics capability. Three archetypes dominate: traction motor specialists with maritime adaptation expertise, energy management software providers with backward integration into hardware, and podded propulsion configurators for ice-class applications. Competitive moves center on silicon carbide module qualification partnerships and shore power infrastructure consortia with harbor authorities.
Among Nordic system integrators, Kongsberg and Wärtsilä occupy positions reflecting distinct specialization vectors, while ABB anchors the high-voltage power electronics tier through traction motor heritage adapted for marine duty. These three exemplify how geographic industrial clustering around Norwegian fjord electrification and Finnish shipbuilding shapes competitive positioning. Each represents a strategic archetype: podded propulsion configuration, energy management software integration, and silicon carbide inverter scale-up respectively.
| Leading Market Players |
|---|
| Volvo Penta |
| Marine Propulsion Solutions |
| Kongsberg |
| Nakashima Propeller |
| Vetus |
| Wärtsilä |
| Thrustmaster of Texas |
| Max Power |
| ABB |
| Others |
Pricing and Supply Chain Analysis
High-voltage power electronics specialists clustering in Norway and Germany command wage premiums that compress margins for mid-tier integrators while widening spreads between premium certified systems and economy-grade harbor craft configurations. Labor-cost differentials between Nordic engineering centers and Asian battery assembly hubs translate directly into pricing-tier stratification across ferry newbuilds and retrofit programs.
Pricing Analysis
Volume deployment in harbor craft retrofits trades margin for market share, while premium positioning in ice-class expedition vessels captures value through Polar Code certification and after-sales service bundling. Price differentiation hinges on classification society tier—DNV and Lloyd's Register certified systems command substantial premiums over economy-grade alternatives—and vertical integration depth in energy management software. Pricing pressure stems from silicon carbide module commoditization as Chinese suppliers enter marine qualification pipelines. Charter operators exhibit highest price sensitivity due to emissions-clause risk transfer, while government agencies prioritize capability over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from European shipbuilders mandate qualified cell suppliers from South Korea and Japan alongside dominant Chinese cathode processors, extending procurement timelines for marine-grade battery systems. Raw material dependencies center on lithium carbonate, nickel sulfate, and rare-earth permanent magnet feedstocks. Single-source vulnerability concentrates in East Asian semiconductor foundries producing silicon carbide wafers. Distribution runs through system integrators with classification society relationships, bypassing component spot markets for project-specific contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as silicon carbide qualification costs and certification backlogs force sub-scale competitors toward exit or acquisition, favoring players with captive energy management software revenue streams.
For Market Incumbents: Acquire energy management software platforms to capture recurring revenue beyond hardware sales and defend against pure-play digital entrants. Deepen backward integration into silicon carbide module packaging to secure supply priority during foundry allocation cycles. Prioritize certification pipeline investments to accelerate type approval timelines as classification society backlogs extend competitor delivery schedules. For New Entrants and Emerging Players: Digital-channel routes through vessel voyage optimization platforms offer lower capital barriers than hardware manufacturing entry. Target secondary port electrification infrastructure where harbor authority coordination gaps delay incumbent shore power deployments. Pursue white-label power electronics supply to Nordic shipyards seeking second-source qualification for silicon carbide inverters. For Investors and Strategic Acquirers: Re-rating potential sits with energy management software-anchored system integrators given charter contract emissions-clause proliferation and recurring revenue visibility. Long-term viability favors players with demonstrated Polar Code certification track records and established shore power infrastructure consortia. Monitor battery cell supply agreement renegotiation announcements as inflection indicators for margin compression or supply security premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Module Qualification Partnership | DNV and Lloyd's Register certification accelerates market access for next-generation inverter designs. |
| Shore Power Infrastructure Consortium | Hamburg and Bremerhaven harbor authority coordination secures 10-20 MW charging priority for ferry operators. |
| Energy Management Software Acquisition | Recurring revenue streams from voyage optimization platforms reduce hardware sales cyclicality. |
| Ice-Class Podded Propulsion Development | Polar Code compliance opens Arctic expedition and research vessel procurement pipelines. |
| Dual-Source Battery Cell Agreement | South Korean and Japanese supplier diversification mitigates Chinese cathode processing concentration risk. |
Research Methodology
Independent corroboration across shipyard procurement directors, classification society surveyors, and ferry operator fleet managers underwrites the qualitative findings in this analysis. Primary interviews with power electronics engineering leads and marine battery system integrators combined with secondary validation from DNV maritime reports, Lloyd's Register technical bulletins, and EU Green Deal regulatory filings established demand-side and supply-side triangulation. Bottom-up vessel orderbook analysis and top-down emissions regulation impact modeling converged on segment-level sizing.
Comparable-period anchoring to historical ferry electrification deployment rates and battery system cost curves grounded the projection framework across the analysis window. Segmentation modeling incorporated propulsion type, application category, technology tier, and end-user archetype dimensions with regional regulatory cluster overlays. CAGRs derived from installed base replacement cycles and newbuild orderbook conversion rates, with silicon carbide adoption curves and shore power infrastructure buildout schedules as primary forecast inputs.
The model holds under sustained EU Green Deal enforcement and stable lithium-ion cell supply; deviation in battery chemistry substitution timelines or classification society certification delays would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Lighting Market
Marine
Offshore AUV and ROV Market
Marine
Integrated Bridge System for Ships Market
Marine
Sailboat Market
Marine
Hydrogen Ships Market
Marine
Military Marine Engine Market
Marine
Global Marine Gearbox Market
Marine
Marine Chronometers Market
Marine
Marine Engines Market
Marine
Furnace Boats Market
Marine
Marine AIS Monitoring System Market
Marine
Ballast Water Management Market
Marine
Rigid Inflatable Boats (RIB) Market
Marine
Marine Salvage Services Market
Marine
Steel Ship Plate Market
Marine
Hydrofoil Market