
 Marine Pipes Market | 2026-2036
Marine Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Pipes Market Analytics
A capital-intensity divergence between integrated installation contractors and component suppliers is unwinding traditional competitive boundaries. TechnipFMC leverages its integrated subsea production systems to capture value across engineering, procurement, and installation phases. Saipem anchors its position through proprietary reel-lay vessel technology that reduces offshore welding requirements. McDermott competes by sustaining heavy-lift fabrication yards in strategic coastal corridors.
Marine pipes are pressure-rated tubular systems manufactured from steel alloys, high-density polyethylene, or thermoplastic composites to transport fluids, gases, and slurries across submerged and salt-exposed environments. Wall thickness, corrosion cladding, and fatigue resistance specifications determine service life in dynamic offshore conditions. Steel pipe material dominates offshore structures due to its pressure containment capacity and established welding protocols, while HDPE is gaining share in near-shore marine engineering where flexibility and cathodic protection avoidance matter. Application type insights reveal that shipbuilding remains a mature volume pool with cyclical newbuild orders, whereas offshore structures command premium margins tied to project-specific engineering.
The American Bureau of Shipping and DNV classification societies enforce material certification and welding procedure standards that gate market access for pipe suppliers. The EPA and BSEE impose spill containment and integrity management rules that extend inspection cycles and replacement demand for subsea line pipe. Buyers must monitor classification society rule changes on hydrogen embrittlement testing as offshore operators evaluate pipeline repurposing for carbon capture and hydrogen transport.
Market Dynamics
Subsea electrification and tieback architecture are compressing project timelines while demanding corrosion-resistant metallurgy that withstands dynamic seabed conditions for decades.
Growth Catalysts
- IMO 2020 Sulfur Cap:Fleet-wide retrofit mandates force replacement of legacy piping systems with sulfur-compliant, corrosion-resistant alloys across tanker and bulk carrier segments.
- Deepwater Tieback Projects:Norway's North Sea cluster anchors subsea pipeline expansion as operators access deeper hydrocarbon reserves through extended-reach drilling.
- Carbon Capture Repurposing:Offshore pipeline infrastructure evaluation for hydrogen transport and CO2 injection creates incremental demand for embrittlement-tested line pipe.
Market Restraints
- Alloy Price Volatility:Nickel and molybdenum input costs fluctuate with mining supply disruptions, compressing fabrication margins for seamless pipe producers.
- Fabrication Yard Concentration:Heavy-lift capacity clusters in strategic coastal corridors, creating bottleneck risk during concurrent project waves.
- Welding Protocol Rigidity:DNV and ABS certification requirements for subsea joints limit automation adoption, extending fabrication cycles.
Strategic Opportunities
- HDPE Near-Shore Penetration:High-density polyethylene pipe is capturing marine engineering applications where cathodic protection avoidance and installation flexibility outweigh pressure ratings.
- EU Green Deal Funding:Offshore wind inter-array cable protection systems qualify for sustainable finance taxonomy, redirecting pipe demand toward renewable infrastructure.
- Digital Twin Integration:Sensor-embedded smart pipe converging with predictive maintenance platforms enables condition-based replacement contracts.
Industry Challenges
- Subsea Welding Specialist Shortage:Hyperbaric welding certification programs produce insufficient qualified technicians for deepwater installation demand.
- Multi-Agency Compliance Overlap:EPA spill containment rules and BSEE integrity management mandates create conflicting inspection cycle requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Pipes Market |
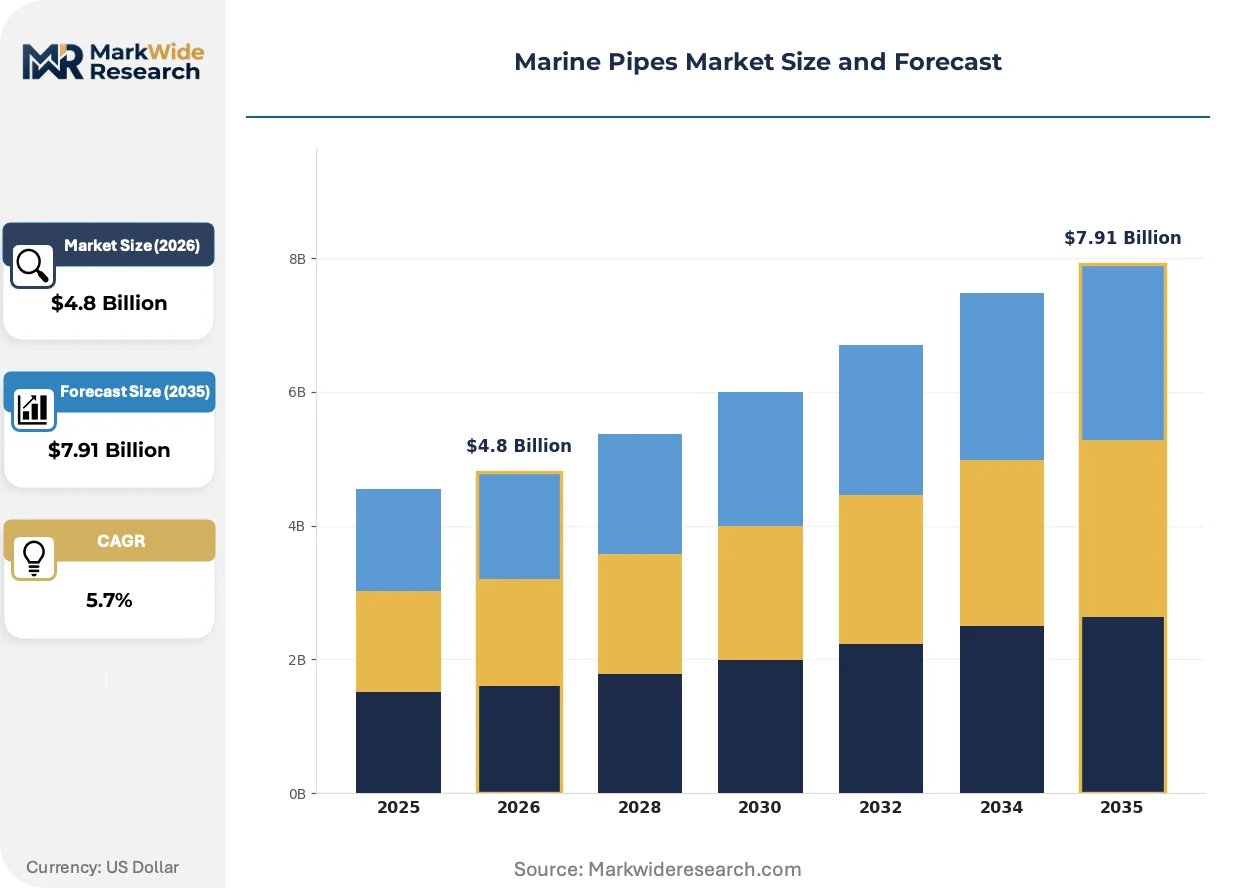
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Pipe Material: Steel, PVC, CPVC, HDPE Application Type: Shipbuilding, Offshore Structures, Marine Engineering, Storage Facilities End User: Shipping Companies, Offshore Oil & Gas, Fishing Industry, Marine Contractors Installation Method: Welding, Threaded, Flanged, Socket Weld |
| Companies Covered | TechnipFMC PLC, Subsea 7, Saipem, National Oilwell Varco, Prysmian Group, Sapura, Penspen, McDermott, Petrofac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Pipes Market Evolving Landscape
Thermoplastic composite pipe is eroding steel's dominance in specific pressure regimes while regulatory pressure on lifecycle emissions reshapes material selection criteria across marine applications.
Reinforced thermoplastic pipe (RTP) is displacing carbon steel in subsea flowlines and water injection systems where moderate pressure containment suffices. Brazilian pre-salt operators and North Sea electrification projects are adopting RTP for its corrosion immunity and reduced installation weight. This displacement is compressing demand for cladded steel line pipe in tieback applications below 150 bar operating pressure.
EU CSRD disclosure mandates now require Scope 3 emissions reporting from marine contractors, forcing pipe suppliers to document embodied carbon in steel and polymer production. Fabricators serving European offshore wind and oil and gas projects must certify lifecycle environmental product declarations to maintain qualification status. This regulatory pressure most acutely affects carbon-intensive seamless pipe producers supplying Norwegian and UK continental shelf developments.
Integrated service contracting is consolidating procurement decisions under engineering-procurement-installation contractors rather than discrete component sourcing. Buyers now bundle pipe supply with installation and subsea hardware through single-source agreements, marginalizing standalone pipe distributors. This consolidation is most visible in Norway's North Sea cluster where Equinor and Aker BP have shifted toward integrated subsea production system awards.
Marine Pipes Market Segmentation
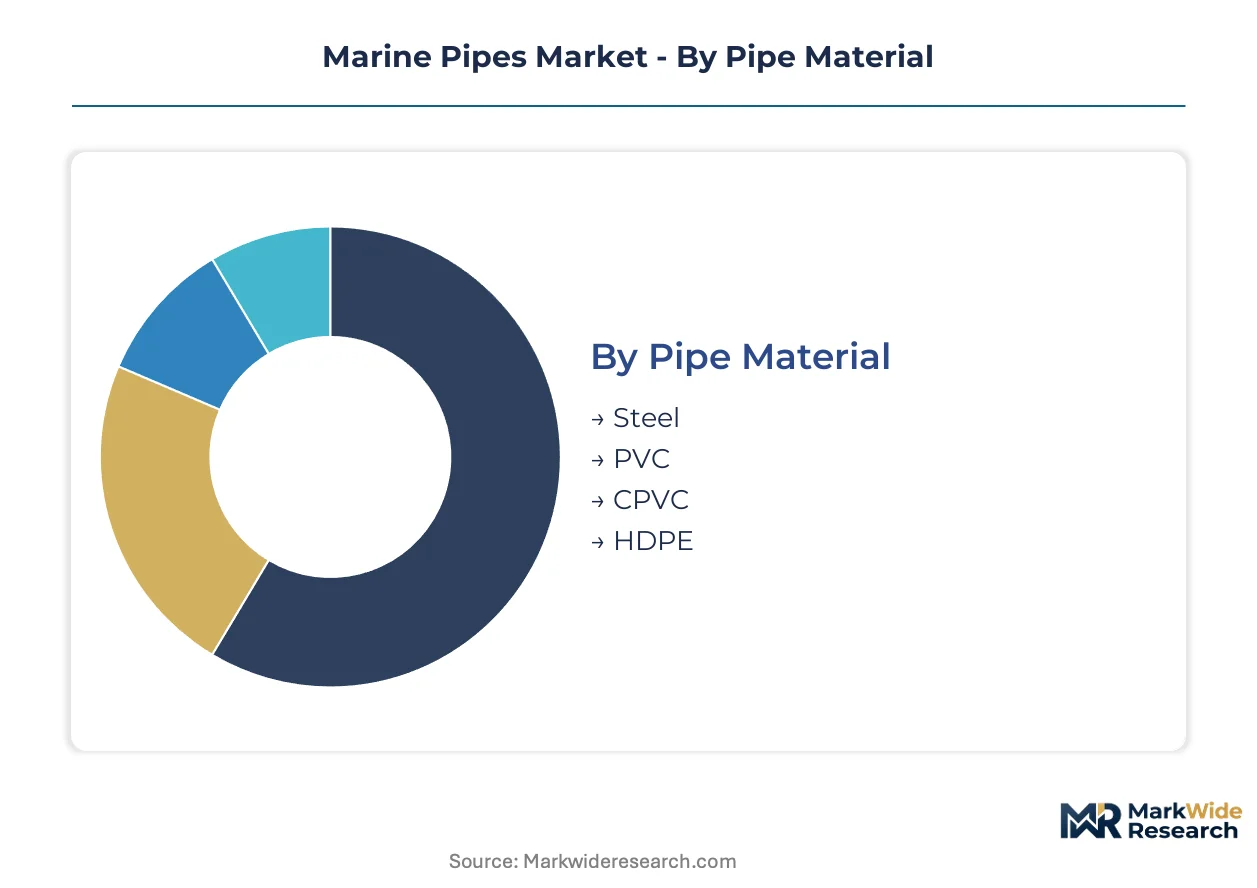
Material selection in marine piping determines corrosion resistance, pressure containment, and installation economics across salt-exposed environments. Segmentation reveals how procurement channels bundle pipe supply with engineering services or discrete component sourcing depending on application criticality.
Pipe Material:
Steel pipe flows through integrated EPCI contractors for offshore projects, while polymer grades reach buyers via specialized distributors serving near-shore marine engineering.
- Steel:Carbon and alloy steel pipe delivers pressure containment above 150 bar through seamless or welded construction with corrosion cladding. Norwegian North Sea tieback projects specify steel for dynamic seabed conditions where fatigue resistance governs service life.
- HDPE:High-density polyethylene pipe eliminates cathodic protection requirements through inherent corrosion immunity and flexural capacity for seabed unevenness. Near-shore installations in EU offshore wind inter-array systems favor HDPE where pressure ratings below 10 bar suffice and installation weight reduction accelerates deployment schedules.
- PVC:Rigid polyvinyl chloride serves low-pressure drainage and ballast systems in coastal vessels and harbor infrastructure.
- CPVC:Chlorinated polyvinyl chloride extends temperature tolerance for hot service lines aboard commercial shipping and offshore accommodation platforms.
By volume, steel leads. By expansion trajectory, HDPE is gaining share fastest in renewable marine infrastructure.
Application Type:
Margin concentration varies sharply: shipbuilding operates on cyclical newbuild economics while offshore structures command project-specific premiums.
- Shipbuilding:Pressure piping for propulsion, ballast, and cargo systems follows classification society welding protocols with ABS and DNV certification gating supplier qualification. Tanker retrofits for IMO 2020 sulfur compliance concentrate replacement demand in South Korean and Chinese yards.
- Offshore Structures:Subsea production systems and platform piping require cladded steel or thermoplastic composites rated for decades of dynamic seabed exposure. Brazil's pre-salt operators and Norway's electrification projects anchor premium procurement through integrated contracting.
- Marine Engineering:Coastal protection, dredging, and port infrastructure deploy flexible polymer solutions where installation speed outweighs pressure specifications.
- Storage Facilities:Tank farm and offshore storage piping emphasize spill containment integrity under EPA and BSEE inspection mandates.
Shipbuilding generates the largest order volumes. Offshore structures deliver the steepest margin premiums per meter installed.
End User:
Procurement sophistication diverges: oil and gas majors bundle pipe with subsea hardware, while fishing fleets source through regional ship chandlers.
- Offshore Oil & Gas:Operators evaluate pipeline repurposing for carbon capture and hydrogen transport, triggering demand for embrittlement-tested metallurgy. Equinor and Aker BP in Norway's North Sea cluster drive integrated subsea production system awards that consolidate pipe procurement under EPCI contractors.
- Shipping Companies:Fleet-wide sulfur cap retrofits force replacement of legacy piping with corrosion-resistant alloys across tanker and bulk carrier segments.
- Marine Contractors:Installation specialists specify pipe compatible with proprietary reel-lay vessel technology that reduces offshore welding requirements.
- Fishing Industry:Processing and refrigeration piping aboard factory trawlers prioritizes sanitary grade materials with regulatory compliance from national maritime authorities.
Offshore oil and gas anchors value per ton. Shipping companies generate the broadest volume base across vessel categories.
Installation Method:
Certification rigidity constrains automation: DNV and ABS welding procedure standards limit robotic adoption despite technician shortages.
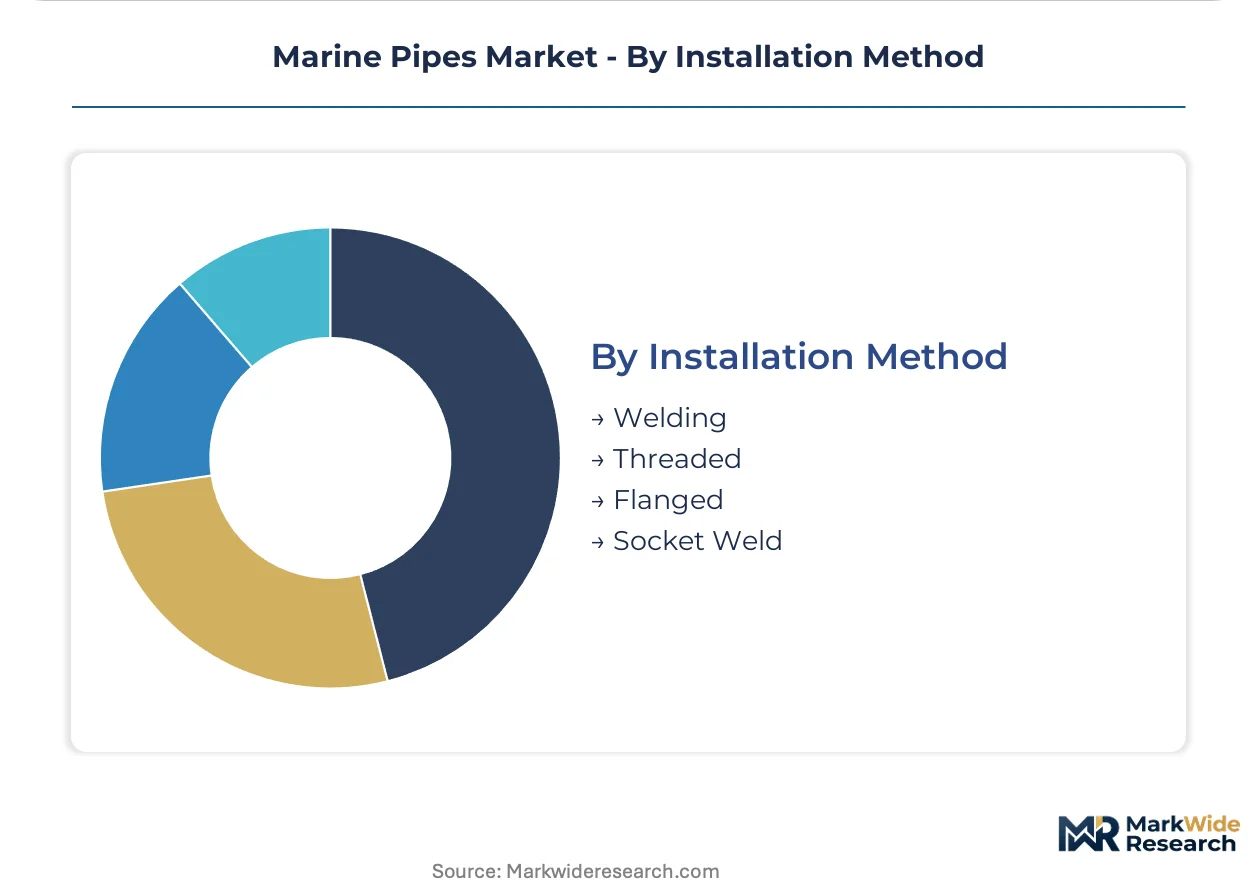
- Welding:Submerged arc and hyperbaric welding protocols dominate offshore line pipe installation, with qualification bottlenecks extending fabrication cycles. Reel-lay vessel technology from specialized marine contractors reduces field welding requirements for deepwater tiebacks.
- Flanged:Bolted connections enable modularity in platform piping and maintenance-accessible systems where future disassembly is anticipated.
- Threaded:Mechanical joining serves lower-pressure auxiliary systems and temporary installations aboard vessels and coastal facilities.
- Socket Weld:Compact welded joints fit confined machinery spaces and high-integrity small-bore piping in critical service applications.
Welding dominates subsea and structural applications. Flanged connections lead in platform topsides and maintenance-intensive systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in marine pipes track fabrication yard capacity against offshore project waves. Countries with heavy-lift coastal infrastructure dominate outbound shipments while import dependence concentrates in regions lacking subsea welding certification ecosystems.
Norway
Equinor and Aker BP electrification projects drive subsea pipeline demand through the North Sea cluster. The Norwegian Petroleum Directorate enforces stringent integrity management standards for tieback installations. Stavanger anchors fabrication activity where reel-lay vessel technology reduces offshore welding requirements.
United States
Gulf of Mexico deepwater tiebacks and carbon capture pipeline repurposing create dual demand channels for embrittlement-tested metallurgy. The EPA and BSEE impose overlapping spill containment and integrity management rules that extend inspection cycles. Houston concentrates EPCI contractor headquarters and heavy-lift fabrication yards serving offshore developments.
Brazil
Pre-salt field operators adopt thermoplastic composite pipe for moderate-pressure flowlines and water injection systems. ANP regulatory frameworks govern subsea production system certification and material traceability. Rio de Janeiro hosts integrated service contractors bundling pipe procurement with installation capabilities.
China
State-owned shipyards process IMO 2020 sulfur cap retrofits for tanker and bulk carrier fleets requiring corrosion-resistant alloy replacements. The Ministry of Industry and Information Technology oversees welding procedure standards through GB certification protocols. Shanghai and Dalian anchor steel pipe fabrication for domestic shipbuilding and export markets.
United Kingdom
North Sea decommissioning and offshore wind inter-array cable protection systems redirect pipe demand toward renewable infrastructure. The Health and Safety Executive enforces pipeline safety regulations aligned with EU CSRD emissions disclosure mandates. Aberdeen maintains subsea engineering expertise clusters serving North Sea continental shelf developments.
Marine Pipes Market Competitive Landscape
Concentration sits with integrated engineering-procurement-installation contractors that bundle pipe supply with subsea hardware and installation services. The vendor base separates into three strategic archetypes: full-system integrators controlling project timelines, specialized fabrication houses with proprietary vessel technology, and regional yards competing on coastal proximity. Dominant competitive moves include backward integration into seamless pipe production and strategic partnerships with classification societies for accelerated certification protocols.
Among the integrated tier, TechnipFMC and Saipem exemplify full-system contractors that consolidate procurement decisions under single-source agreements. McDermott occupies a position among heavy-lift fabrication specialists sustaining strategic coastal yard networks. These three entities represent how competitive positioning increasingly depends on controlling installation logistics rather than discrete component manufacturing.
| Leading Market Players |
|---|
| TechnipFMC PLC |
| Subsea 7 |
| Saipem |
| National Oilwell Varco |
| Prysmian Group |
| Sapura |
| Penspen |
| McDermott |
| Petrofac |
| Others |
Value Network & Pricing Analysis
Six-month order-to-delivery windows for cladded steel line pipe concentrate pricing power with integrated EPCI contractors who control fabrication yard capacity and welding certification pipelines. This lead-time compression amplifies cost pass-through to offshore operators while squeezing standalone pipe distributors unable to bundle installation services.
Pricing Analysis
The customization-premium spread between project-specific cladded steel and standard seamless pipe exceeds threefold, with corrosion-resistant alloys for North Sea tiebacks commanding substantial engineering premiums over commodity grades. Price differentiation rests on DNV certification tier and volume scale, with batch orders above ten thousand meters securing standard-grade discounts unavailable to project-specific procurements. Cost compression in commodity seamless pipe is intensifying because Chinese state-owned mills are expanding export capacity for IMO 2020 retrofit demand. Shipping companies retrofitting tanker fleets exhibit the highest price sensitivity, while Equinor and Aker BP prioritize qualification status over unit economics in integrated subsea production system awards.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Singapore container terminals fluctuate with vessel availability, compressing margins for European and Southeast Asian distributors dependent on Asian mill supply. Fabrication concentrates in China, Norway, and the United States, with seamless pipe production anchored in Chinese state-owned mills and specialized cladding in Norwegian coastal yards. Raw material dependencies center on nickel and molybdenum from mining operations, with high-density polyethylene resin feeding from petrochemical complexes. Single-source vulnerability in hyperbaric welding certification creates bottleneck risk during concurrent North Sea and Gulf of Mexico project waves. Distribution runs through integrated EPCI contractors bundling pipe with installation rather than discrete component sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine pipes function as a service-attach opportunity where condition-based replacement contracts and integrity management subscriptions expand faster than hardware shipments. Digital twin integration enables recurring-revenue layers that decouple supplier economics from project cyclicality.
For Market Incumbents: Fortify market position through backward integration into seamless pipe production and captive control over reel-lay vessel fleets. Thermoplastic composite pipe substitution threatens cladded steel margins in moderate-pressure flowlines below 150 bar, demanding metallurgical R&D investment in embrittlement-tested alloys for hydrogen transport applications. Certification investment with DNV and ABS accelerates qualification protocols that gate competitor entry. For New Entrants and Emerging Players: DNV fast-track certification for hydrogen-ready line pipe creates qualification pathways without incumbent welding protocol legacy. HDPE near-shore penetration in EU offshore wind inter-array systems represents the most penetrable white space, with cable protection systems qualifying for Green Deal sustainable finance taxonomy. Partner with marine contractors seeking cathodic protection avoidance to bypass steel-dominated EPCI channels. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with subsea fabrication assets under strategic review. Long-term viability hinges on exposure to electrification and carbon capture repurposing rather than pure-play hydrocarbon development. Monitor ANP regulatory frameworks in Brazil and Norwegian Petroleum Directorate integrity standards as inflection indicators for thermoplastic composite adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seamless Pipe Production | Captive supply of corrosion-cladded steel reduces fabrication margin leakage to Chinese mills. |
| Digital Twin Platform Development | Sensor-embedded smart pipe enables condition-based replacement contracts with Equinor and Aker BP. |
| HDPE Manufacturing Scale-Up | EU offshore wind inter-array demand qualifies for Green Deal sustainable finance taxonomy funding. |
| Hyperbaric Welding Certification Expansion | DNV and ABS qualification bottlenecks create specialist labor scarcity that commands premium pricing. |
| Hydrogen Transport Metallurgy R&D | Embrittlement-tested alloys position suppliers for carbon capture pipeline repurposing evaluations. |
Research Methodology
Operator-level perspectives from subsea project engineers, EPCI procurement directors, classification society surveyors, and fabrication yard managers anchored the qualitative base for this study. Primary interviews with stakeholders at TechnipFMC, Saipem, and McDermott combined with secondary validation through DNV rule change filings, EPA spill containment enforcement records, and BSEE integrity management directives. Customs data from Norwegian Petroleum Directorate production reports and ANP subsea certification databases provided volume triangulation. Bottom-up project pipeline tracking and top-down macro demand modeling converged on segment-level outputs.
Sensitivity analysis across alloy price volatility scenarios, project sanctioning delays, and regulatory acceleration pathways stress-tested base case assumptions. The analytical framework modeled pipe material grade, application criticality, installation method complexity, and end-user procurement sophistication across the projection horizon. CAGRs derived from weighted average of historical project award patterns and announced tieback timelines. Forecast inputs incorporated IMO 2020 retrofit backlogs, North Sea electrification capex commitments, and EU CSRD disclosure mandates affecting supplier qualification.
The analysis sits within stated boundaries; outcomes outside sustained offshore investment cycles, stable nickel-molybdenum supply, or unchanged DNV welding protocol rigidity would require recalibration. Forecasts reflect documented assumptions regarding project sanctioning rates and regulatory enforcement intensity. Specific risks that could revise projections include ANP regulatory shifts in Brazil, Norwegian Petroleum Directorate integrity standard changes, and EPA-BSEE inspection cycle harmonization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Diesel Engine Market
Marine
Marine Airbags Market
Marine
Ship Searchlight Market
Marine
Singapore Container Transshipment Market
Marine
Boat Console Market
Marine
Marine Growth Removal Tool Market
Marine
Marine Navigation System Market
Marine
Marine Engines Market
Marine
Marine Salvage Services Market
Marine
Buoys and Beacon Market
Marine
LNG Bunkering Vessel Market
Marine
Marine Beacon Market
Marine
Freighter Conversions Market
Marine
Marine Fin Stabilizer Market
Marine
Marine Fasteners Market
Marine
Hydrogen Ships Market