
 Bus Charter Services Market | 2026-2036
Bus Charter Services Market Size, Share, and Industry Trends Forecast 2026-2036
Bus Charter Services Market Outlook
The fleet-size capability gap between national charter networks and regional operators is collapsing as digital booking platforms democratize access to corporate accounts. First Group America leverages its integrated maintenance infrastructure to sustain pricing power across North American corridors. Academy Bus Companies anchors its position through dense terminal networks in the Northeast corridor. Pacific Western Group of Companies differentiates via specialized tourism fleets serving Canadian Rockies routes.
Bus charter services denote contracted passenger transportation using reserved vehicles with defined routes, schedules, and capacity specifications typically ranging from 15 to 56 seats, operating under DOT authority and commercial insurance requirements. The primary purpose involves moving groups efficiently for corporate, educational, or leisure purposes where public transit lacks flexibility or coverage. Corporate transportation commands the largest revenue pool among service types due to recurring contracts and premium pricing for reliability guarantees. Luxury coaches within bus type segmentation carry the highest margin profiles, while school transportation represents the most mature segment with price-sensitive procurement cycles.
Federal Motor Carrier Safety Administration hours-of-service rules and EPA diesel emissions standards shape fleet renewal timelines and capital allocation across operators. DOT accessibility mandates under the ADA compel retrofit investments or new vehicle procurement with lift-equipped configurations. Stakeholders must monitor state-level zero-emission vehicle mandates and their interaction with charter fleet duty cycles to align electrification timelines with contract renewal windows.
Market Dynamics
Digital booking platforms are collapsing the fleet-size capability gap between national charter networks and regional operators, forcing incumbent players to defend accounts through integrated maintenance infrastructure and dense terminal networks rather than scale alone.
Growth Catalysts
- Corporate Shuttle Contracts:Technology campuses in California are expanding recurring transportation agreements with reliability guarantees and premium pricing structures that stabilize operator revenue streams.
- EPA Emissions Standards:Fleet renewal timelines are compressing as diesel emissions rules force capital allocation toward newer, cleaner vehicle configurations.
- Energy Sector Demand:Texas anchors regional operator revenue through energy sector shuttle contracts that sustain high utilization rates across extended duty cycles.
Market Restraints
- Diesel Engine Supply Concentration:Dependence on a limited supplier base for EPA-compliant powertrains creates procurement bottlenecks and extended lead times for fleet expansion.
- ADA Retrofit Costs:DOT accessibility mandates compel lift-equipped vehicle procurement or expensive retrofit investments that strain regional operator balance sheets.
- Rideshare Substitution:On-demand transportation platforms capture smaller group movements that previously defaulted to minimum charter commitments.
Strategic Opportunities
- Zero-Emission Mandates:State-level electrification timelines create contract renewal windows where operators can align fleet conversion with long-term corporate agreements.
- Tourism Fleet Specialization:Scenic corridor operators in the Canadian Rockies demonstrate how dedicated luxury configurations capture premium pricing from leisure segments.
- Maintenance Infrastructure Monetization:Integrated service networks can generate third-party revenue streams by servicing competitor fleets during capacity troughs.
Industry Challenges
- Commercial Driver Shortage:FMCSA hours-of-service compliance requirements intensify recruitment pressure for qualified operators with passenger endorsements.
- Electrification Capex Burden:Battery-electric coach procurement demands capital intensity that outpaces typical contract renewal cycles for mid-size operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bus Charter Services Market |
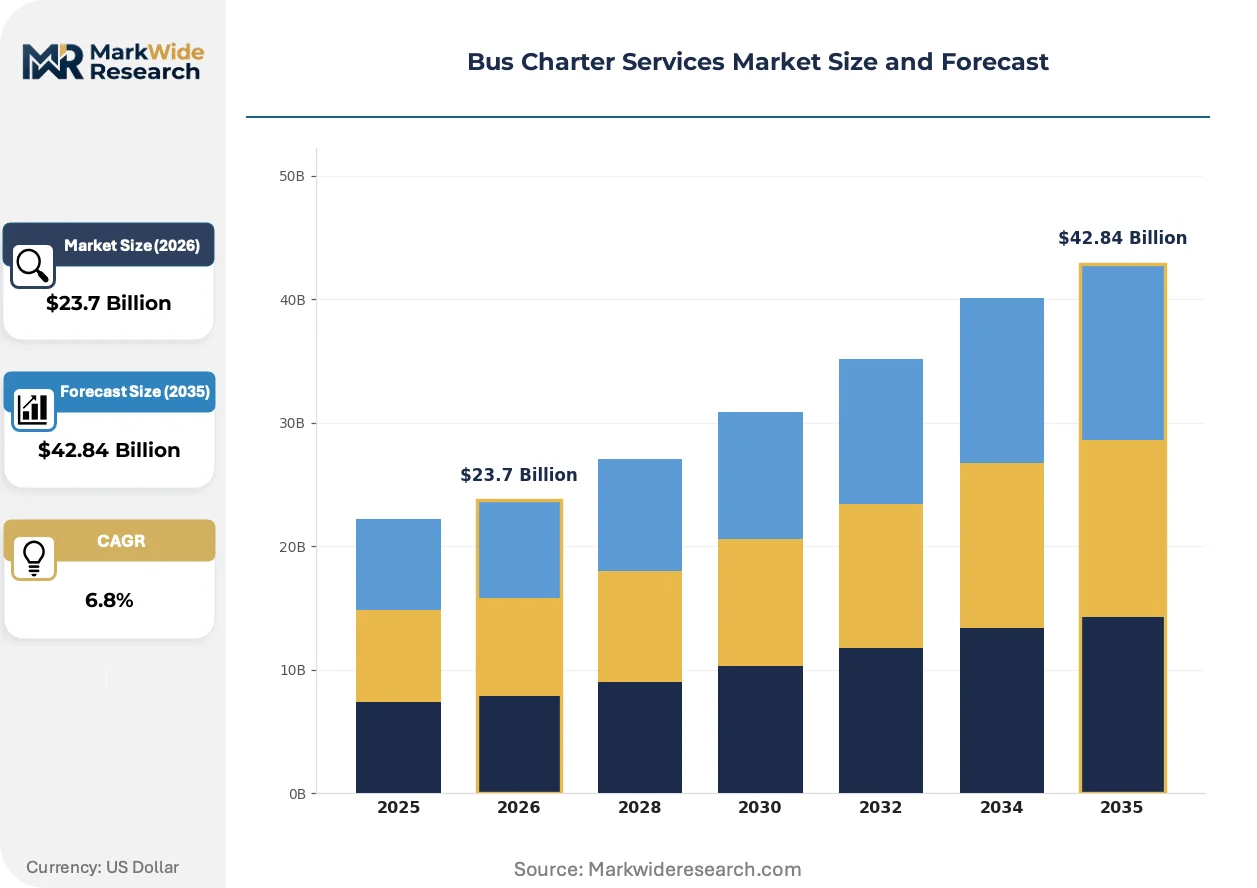
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Corporate Transportation, Event Transportation, School Transportation, Tourism Services Customer Type: Individuals, Corporations, Educational Institutions, Travel Agencies Pricing Model: Hourly Rate, Flat Rate, Seasonal Pricing, Membership Pricing Bus Type: Mini Buses, Standard Coaches, Luxury Coaches, Double Decker Buses |
| Companies Covered | Horizon Coach Lines, All Aboard America Holdings, First Group America, Cyr Bus Lines, Gray Line of Minnesota, Coach USA, Pacific Western Group of Companies, Anchor Transportation, Academy Bus Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bus Charter Services Market Strategic Shifts
Telematics integration and predictive maintenance systems are redefining how fleet operators demonstrate reliability guarantees to corporate accounts, shifting competitive differentiation from vehicle age to uptime metrics.
Telematics platforms are bifurcating the charter market between operators who capture real-time performance data and those dependent on reactive maintenance schedules. Corporate transportation buyers now mandate API-accessible fleet tracking as a contract precondition. This capability compression is squeezing regional operators without integrated technology stacks from premium account contention.
EPA diesel emissions standards are accelerating powertrain diversification across North American fleets as Stage V-equivalent requirements approach. Operators face compressed replacement cycles for pre-2010 chassis that cannot economically achieve compliance. School transportation segments respond with extended procurement timelines while corporate shuttle contracts absorb premium pricing for compliant configurations.
Corporate procurement departments are consolidating vendor relationships through master service agreements that bundle multi-campus transportation under single-operator responsibility. This channel compression displaces fragmented local contracting that previously sustained regional operator margins. California technology campuses demonstrate the most advanced consolidation, demanding unified reporting across distributed shuttle networks.
Bus Charter Services Market Segmentation
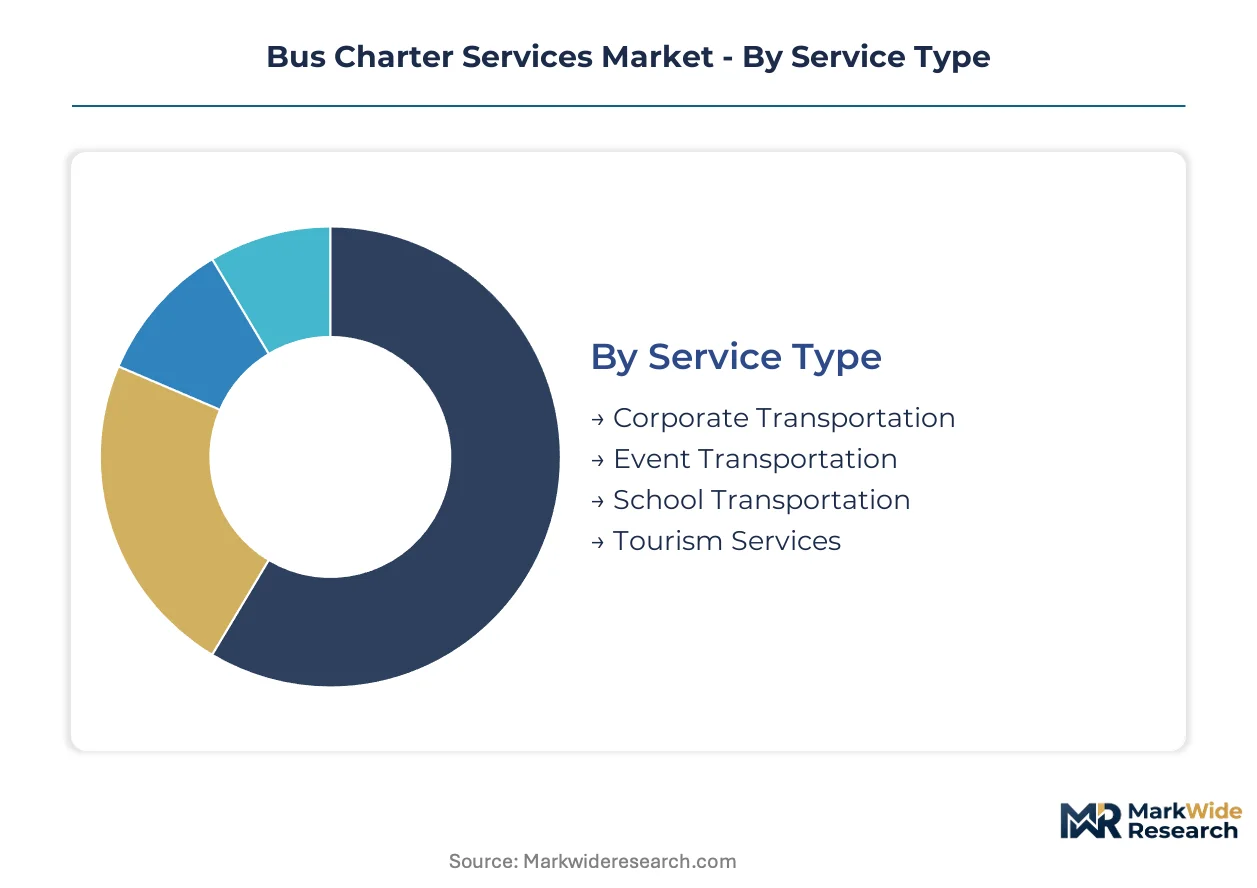
Bus charter segmentation determines capital allocation, fleet configuration, and contract pricing structures. Operators align vehicle specifications and service tiers with distinct regulatory requirements across customer categories.
Service Type:
FMCSA hours-of-service rules and DOT accessibility mandates create divergent compliance costs across service categories, reshaping competitive positioning.
- Corporate Transportation:Recurring shuttle contracts with reliability guarantees and premium pricing structures. California technology campuses anchor demand concentration through multi-campus master service agreements that stabilize operator revenue streams.
- Event Transportation:Episodic demand tied to sports fixtures, conventions, and entertainment venues. Texas energy sector events and Northeast corridor conference circuits generate peak utilization periods requiring surge fleet capacity.
- School Transportation:Price-sensitive procurement cycles with extended bid timelines. EPA diesel emissions compliance drives fleet renewal pressure as pre-2010 chassis face accelerated replacement.
- Tourism Services:Canadian Rockies scenic corridors demonstrate premium pricing capture through dedicated luxury configurations. Seasonal demand patterns require flexible fleet deployment across leisure routes.
Established volume favors Corporate Transportation; emerging adoption favors Tourism Services.
Customer Type:
Procurement authority concentration determines contract scale and margin structure across buyer categories.
- Corporations:Master service agreements consolidate vendor relationships under unified reporting requirements. Technology sector procurement departments in California demand API-accessible fleet tracking as contract preconditions.
- Educational Institutions:State-level procurement frameworks and federal safety mandates shape fleet specifications. ADA lift-equipped configurations are mandatory for institutional contracts.
- Travel Agencies:Commission-based intermediaries aggregate leisure demand across tourism corridors. Canadian Rockies operators leverage agency networks to fill specialized luxury inventory.
- Individuals:Fragmented demand captured through digital booking platforms that democratize access to previously corporate-exclusive fleet capacity.
Contract scale favors Corporations; margin expansion favors Travel Agencies.
Pricing Model:
Duty cycle predictability and utilization risk allocation determine pricing structure adoption across operator portfolios.
- Hourly Rate:Variable cost exposure for episodic demand with driver wages and fuel surcharges passed through. Event transportation and individual bookings default to this structure.
- Flat Rate:Fixed pricing for defined routes and schedules transfers utilization risk to operators. Corporate shuttle contracts absorb premium flat-rate pricing for reliability guarantees.
- Seasonal Pricing:Demand-responsive rate adjustments align with tourism peak periods and school calendar cycles. Canadian Rockies operators deploy this model for leisure corridor revenue optimization.
- Membership Pricing:Subscription-based access models emerging for frequent corporate travelers and educational consortiums seeking committed capacity.
Revenue stability favors Flat Rate; flexibility capture favors Seasonal Pricing.
Bus Type:
Seating capacity and amenity specifications segment capital intensity and margin profiles across fleet configurations.
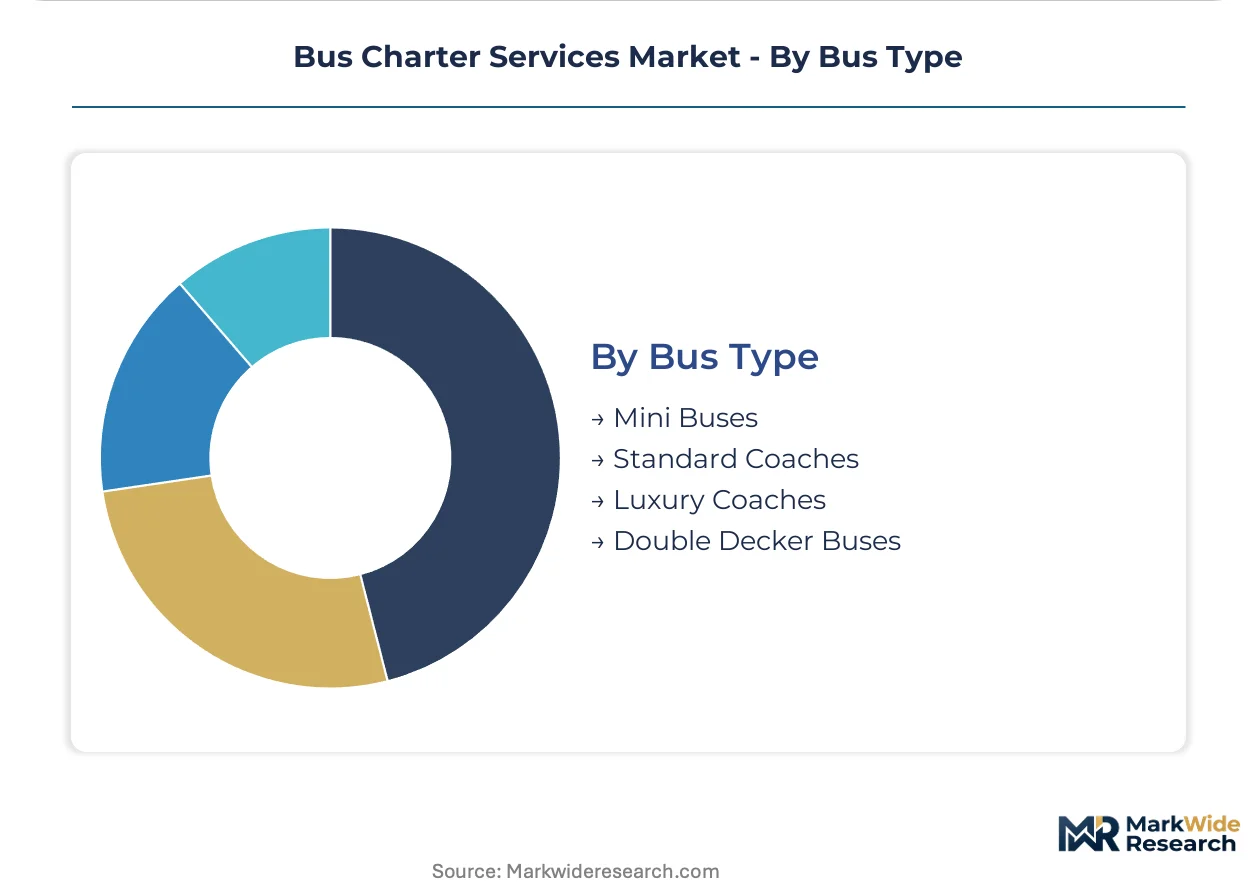
- Luxury Coaches:Premium configurations with reclining seating, onboard entertainment, and climate control systems. Tourism services and executive corporate transportation command highest per-seat pricing for these units.
- Standard Coaches:45-56 seat configurations dominate school transportation and bulk corporate shuttle contracts. EPA emissions compliance costs compress margins in this commoditized segment.
- Mini Buses:15-30 seat capacity serves last-mile corporate shuttles and small-group event transportation. California technology campuses deploy these for distributed campus networks.
- Double Decker Buses:High-capacity sightseeing configurations concentrated in urban tourism markets and scenic corridor operations. Canadian Rockies routes utilize these for panoramic viewing demand.
Margin concentration favors Luxury Coaches; fleet volume favors Standard Coaches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate shuttle buyers in California absorb premium flat-rate pricing with minimal elasticity, while school transportation procurement in Texas and Florida operates under severe price sensitivity with extended competitive bidding cycles.
United States
Technology campuses across California sustain the highest charter service pricing through multi-campus master service agreements with reliability guarantees. EPA diesel emissions standards compress fleet renewal timelines for pre-2010 chassis. The Permian Basin in Texas anchors energy sector shuttle demand with extended duty cycles and utilization rates above industry norms.
Canada
Tourism corridor operators serving the Canadian Rockies capture premium per-seat pricing through dedicated luxury configurations and panoramic viewing demand. The country's national transportation regulator enforces accessibility mandates that compel lift-equipped vehicle procurement. Vancouver and Calgary metropolitan clusters concentrate specialized fleet investment for leisure route optimization.
Germany
Industrial shuttle contracts from manufacturing complexes in Bavaria and Baden-Württemberg sustain recurring revenue with stringent punctuality requirements. The KBA enforces Stage V-equivalent emissions standards that accelerate powertrain diversification. The Munich-Stuttgart corridor demonstrates advanced telematics integration as a contract precondition for corporate accounts.
United Kingdom
London metropolitan corporate transportation consolidates vendor relationships through unified reporting requirements across distributed office networks. The country's national transport regulator mandates commercial insurance thresholds and driver certification standards. The M4 corridor technology cluster drives demand for mini-bus configurations serving last-mile distributed campus networks.
Australia
Mining sector fly-in-fly-out operations in Western Australia sustain high-utilization charter contracts with remote site accessibility requirements. The country's national transport safety regulator enforces heavy vehicle fatigue management standards. The Perth metropolitan area anchors fleet investment for resource sector transportation with extended replacement cycles.
Bus Charter Services Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the bus charter services market. National networks defend position through dense terminal infrastructure and captive maintenance capabilities. Regional operators compete on specialized tourism fleet configurations and energy sector contract expertise. Competitive moves concentrate on master service agreement consolidation and telematics platform integration for corporate account retention.
Within the integrated network tier, First Group America and Academy Bus Companies occupy positions defined by geographic terminal density and maintenance infrastructure scale. Pacific Western Group of Companies exemplifies the specialized tourism operator archetype through Canadian Rockies corridor concentration. These three anchors demonstrate how competitive positioning stratifies between scale-driven consolidation and niche premium capture.
| Leading Market Players |
|---|
| Horizon Coach Lines |
| All Aboard America Holdings |
| First Group America |
| Cyr Bus Lines |
| Gray Line of Minnesota |
| Coach USA |
| Pacific Western Group of Companies |
| Anchor Transportation |
| Academy Bus Companies |
| Others |
Value Chain & Pricing Dynamics
Twelve-to-eighteen-month EPA-compliant chassis lead times concentrate procurement power with national operators who pre-position inventory, while regional players absorb spot-market premiums that compress flat-rate contract margins. This supply bottleneck reinforces pricing stratification between integrated networks with captive maintenance infrastructure and price-competitive regional bids.
Pricing Analysis
After-sales maintenance contracts and parts revenue drive lifetime value capture across fleet operators, with integrated service networks commanding premium hourly labor rates. Three-tier pricing structure across premium, standard, and economy levels segments corporate shuttle, school transportation, and event markets respectively. Cost compression in standard coach procurement intensifies as EPA diesel emissions compliance adds per-unit capital burden. School transportation procurement exhibits highest price sensitivity with extended competitive bidding, while California technology campuses show minimal elasticity for reliability-guaranteed flat-rate structures.
Supply Chain Analysis
Inventory pre-positioning at dense terminal networks buffers against chassis delivery volatility, with Mexico and Canada supplementing US-based final assembly capacity for cross-border fleet deployment. Powertrain sourcing draws from EPA-certified diesel suppliers and emerging electric drivetrain specialists, while seating and climate systems feed from automotive tier-one corridors. Single-source vulnerability concentrates in EPA-compliant engine supply, with tariff exposure on Mexican chassis components threatening margin stability. Distribution runs through direct operator procurement for national networks and dealer-intermediated channels for regional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bus charter market fragmentation creates white-space openings as digital booking platforms democratize access and collapse minimum fleet-scale thresholds for corporate account contention.
For Market Incumbents: Fortify master service agreement retention through API-accessible telematics integration that satisfies California technology campus procurement preconditions. Deepen captive maintenance infrastructure to generate third-party revenue during utilization troughs. Vertical integration into predictive service platforms defends against digital-native entrants capturing corporate accounts through uptime-guarantee pricing.
For New Entrants and Emerging Players: Differentiate on zero-emission fleet specialization aligned with state-level electrification mandates and corporate ESG procurement criteria. Target tourism corridor operators in the Canadian Rockies where luxury configuration premiums sustain above-market returns. Deploy digital-native booking platforms with real-time availability to capture fragmented individual demand and small-group event transportation.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because master service agreement concentration favors scaled operators with dense terminal networks and integrated maintenance capabilities. Target acquisition archetypes include regional operators with energy sector contract expertise and specialized tourism fleet configurations. Watch state-level zero-emission mandate acceleration as inflection signal for electrification capex deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | API-accessible fleet tracking satisfies California technology campus procurement preconditions and contract retention. |
| Zero-Emission Fleet Conversion | State-level electrification mandates create contract renewal windows aligned with long-term corporate agreement cycles. |
| Maintenance Infrastructure Monetization | Integrated service networks generate third-party revenue by servicing competitor fleets during capacity troughs. |
| Master Service Agreement Consolidation | Multi-campus transportation bundling under single-operator responsibility displaces fragmented local contracting. |
| Tourism Fleet Specialization | Dedicated luxury configurations in Canadian Rockies corridors capture premium per-seat pricing from leisure segments. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary fieldwork, with fleet managers at California technology campuses, Texas energy sector procurement leads, Canadian Rockies tourism operators, and maintenance infrastructure directors providing operational validation. Secondary sources incorporated FMCSA regulatory filings, EPA emissions compliance databases, DOT accessibility mandate records, and state-level zero-emission vehicle policy trackers. Bottom-up fleet deployment modeling and top-down contract value aggregation were triangulated against industry association membership data and terminal network density mapping.
Across the analysis window, volume and value outputs reflect segmentation across service type, customer category, pricing model, and bus configuration tiers. CAGRs were derived from contract renewal cycle analysis, fleet replacement timelines, and duty cycle utilization patterns. Forecast inputs incorporated EPA diesel emissions phase-out schedules, state-level electrification mandate trajectories, and corporate shuttle contract pricing elasticity observations.
The analysis sits within stated boundaries; outcomes outside EPA regulatory timeline adherence or accelerated electrification capex deployment would require recalibration. Forecasts reflect documented assumptions regarding fleet renewal compliance costs and driver availability constraints. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
Intercity Bus Travel Market
Buses
North America Bus Market
Buses
Europe Trolley Bus Market
Buses
Bus Chassis Market
Buses
Europe Bus Market
Buses
Intelligent Bus Shelter Market
Buses
Global Bus Market
Buses
Solar Bus Market
Buses
Buses & Coaches Market
Buses
Electric Intercity Bus Market
Buses
City Bus Low-Floor Axle Systems Market
Buses
Luxury Bus Market
Buses
United States School Bus Market
Buses
Hydrogen CNG Bus Market
Buses
Airport Bus Market
Buses
Canada School Bus Market