
 Marine Trenchers Market | 2026-2036
Marine Trenchers Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Trenchers Market Foresight
Software-defined trenching control systems is recalibrating how marine trencher capabilities are packaged and sold. Royal IHC leverages integrated vessel-trencher automation to anchor its position in deep-water deployments. Soil Machine Dynamics Ltd. sustains technology leadership through specialized jet trencher engineering for hostile seabed conditions. Jan De Nul competes via in-house fleet scale and captive installation project pipelines across European offshore zones.
Marine trenchers are seafloor excavation machines engineered to cut burial slots ranging from one to five meters depth for pipelines, cables, and umbilicals, using mechanical cutting chains, high-pressure jetting arrays, or hybrid combinations. Their primary industrial purpose is post-lay burial that protects subsea infrastructure from fishing gear, anchors, and hydrodynamic fatigue. Jet trenchers command the fastest-growing product category as operators favor non-contact seabed disturbance in sensitive marine environments. The energy sector end-user segment occupies the dominant margin pool, though telecommunications cable burial is expanding with offshore wind interconnectivity projects. Deep water deployment represents the structurally premium tier, requiring heavier capital equipment and longer project cycles that filter out smaller fleet operators.
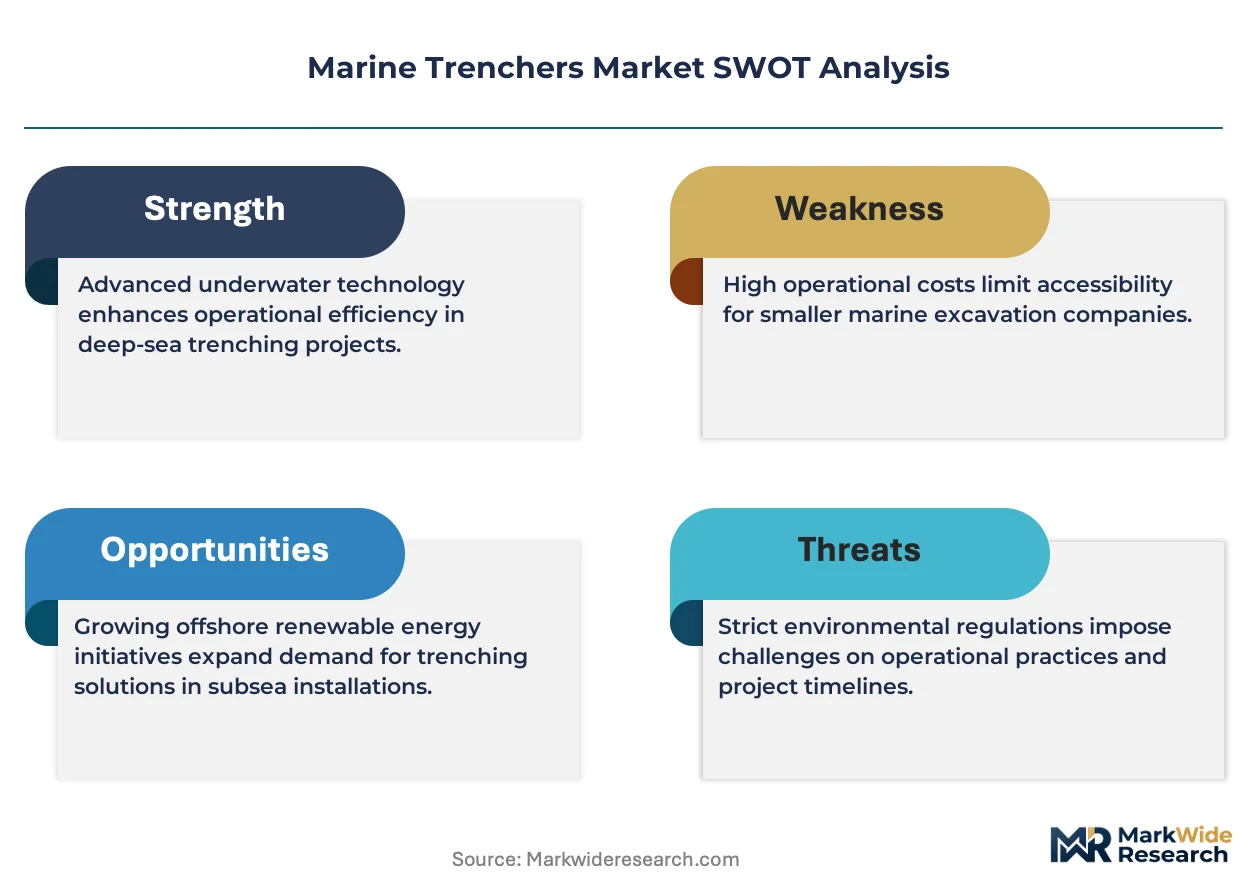
IMO MARPOL Annex VI emissions standards and EU F-Gas Regulation compliance are reshaping trencher propulsion architectures toward hybrid-electric and battery-buffered systems. Classification societies DNV and Lloyd's Register enforce subsea equipment certification that gates market access for non-compliant manufacturers. Stakeholders must monitor how carbon intensity regulations cascade from vessel operations into trencher specification requirements and charter contract terms.
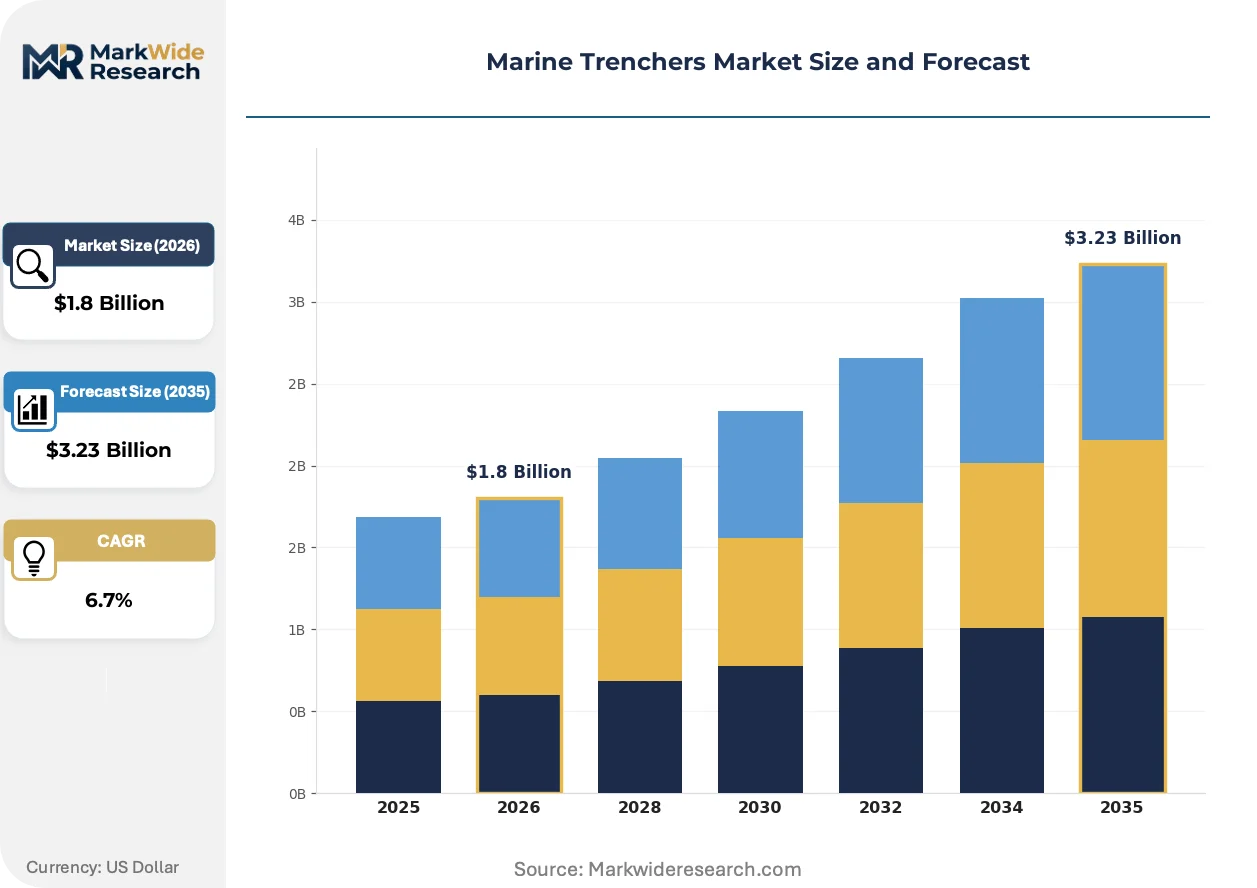
Market Dynamics
Electrification mandates cascading from IMO MARPOL Annex VI and the EU F-Gas Regulation are forcing a wholesale redesign of trencher propulsion systems, compressing development cycles and elevating certification costs for manufacturers serving North Sea and Atlantic offshore corridors.
Growth Catalysts
- Offshore wind interconnectivity:Burial demand for export cables linking wind farms to onshore grids is accelerating jet trencher deployment across European maritime zones.
- EU F-Gas Regulation:Phasedown of fluorinated greenhouse gases is compelling fleet operators to specify lower-emission trenching systems with battery-buffered powertrains.
- Mechanical cutting:Hybrid mechanical-jet trenchers are gaining preference in hostile seabed conditions where pure jetting proves ineffective.
Market Restraints
- Steel and titanium input volatility:Cutting chain fabrication depends on specialized alloys subject to supply concentration from a limited producer base.
- DNV certification timelines:Extended type-approval processes for subsea equipment delay revenue recognition by 18-24 months.
- Remotely operated seabed preparation:ROV-based pre-trenching surveys reduce pure trencher utilization rates on integrated installation contracts.
Strategic Opportunities
- Floating offshore wind in Portugal:Pre-commercial arrays planned for the Atlantic coast require dynamic cable burial at depths exceeding 100 meters.
- CSRD disclosure mandates:Scope 3 emissions reporting is pressuring energy majors to charter lower-carbon trenching fleets.
- Digital twin convergence:Real-time soil condition modeling fused with autonomous trencher control is opening premium service contracting models.
Industry Challenges
- Subsea hydraulics engineering talent:Specialized expertise in high-pressure jetting system design concentrates within a narrow demographic cohort nearing retirement.
- Legacy vessel integration:Retrofitting battery-electric trenchers onto existing offshore support vessels creates power management conflicts with dynamic positioning systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Trenchers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Trenchers, Jet Trenchers, Combination Trenchers, Remote Operated Trenchers Application: Subsea Pipeline Installation, Cable Laying, Marine Excavation, Survey Operations End User: Energy Sector, Telecommunications, Environmental Agencies, Marine Contractors Deployment: Onshore, Offshore, Shallow Water, Deep Water |
| Companies Covered | Royal IHC, Soil Machine Dynamics Ltd., Global Marine, Jan De Nul, Mastenbroek Limited, DeepOcean, Seatools BV, Osbit, Delta Subsea LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Trenchers Market Shifts & Advancements
Software-defined automation is rewriting the competitive logic of trencher specification, shifting buyer preference from hardware durability toward predictive control architectures that compress burial cycle times and reduce seabed disturbance.
Autonomous seabed tracking is overtaking manual operator intervention as the default control paradigm for deep-water deployments. Machine vision systems fused with multibeam sonar enable real-time trench profile adjustment without surface communication latency. North Sea operators are specifying these capabilities as standard on newbuild trenchers. The technology is overtaking conventional joystick-based operation and compressing charter rate differentiation between premium and standard fleet tiers.
The EU F-Gas Regulation's phasedown schedule is accelerating refrigerant transition in trencher climate control and hydraulic cooling systems. Manufacturers must redesign thermal management architectures to accommodate lower-GWP alternatives with reduced cooling efficiency. Jet trencher product lines face the steepest engineering burden given their higher heat rejection requirements.
Charter contracting is fragmenting from multi-year fleet agreements toward project-specific, performance-indexed arrangements. Offshore wind developers are unbundling trenching services from integrated installation packages to optimize capex timing. This pattern is most pronounced in the UK and Danish sectors where auction-based offtake structures dominate project finance.
Marine Trenchers Market Segmentation
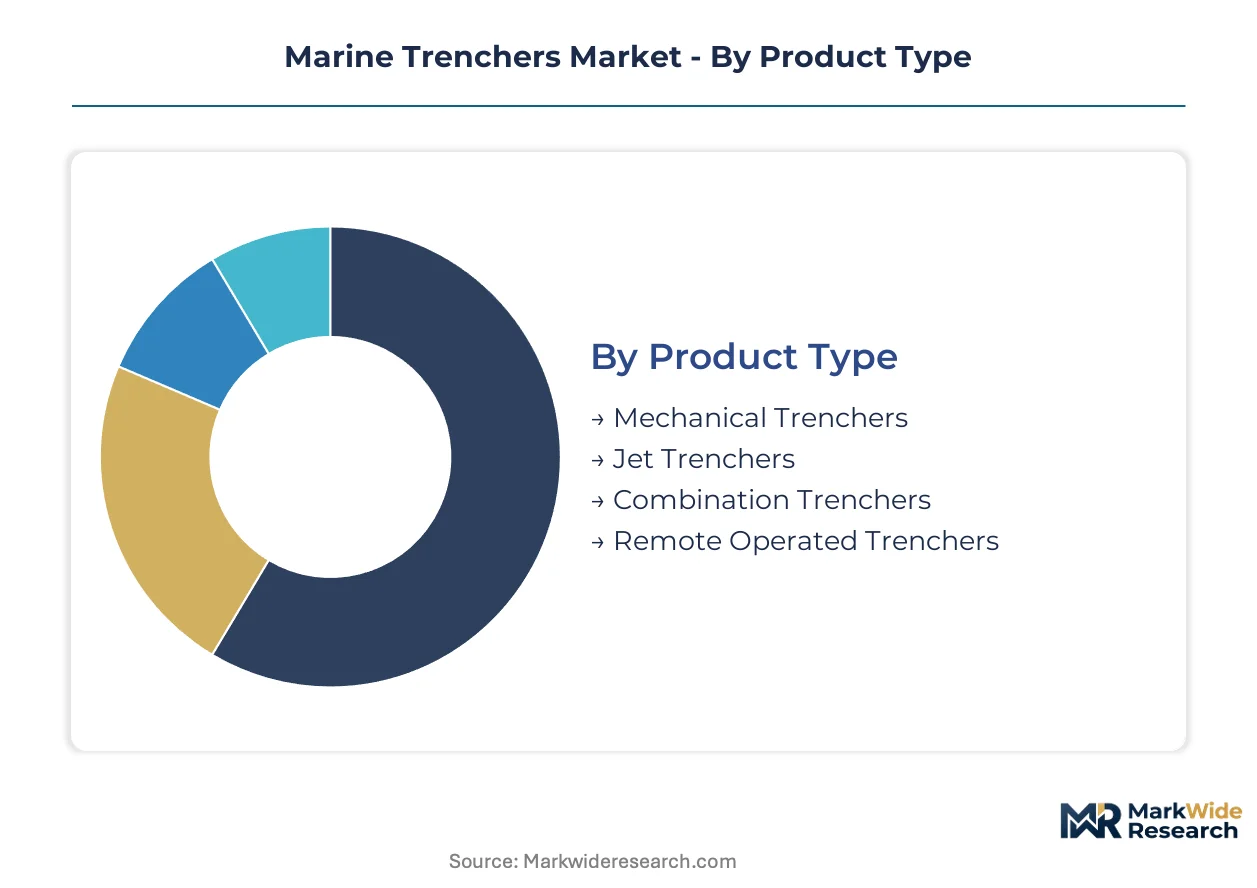
Marine trencher segmentation reveals how capital allocation, regulatory pressure, and seabed complexity fragment demand across equipment categories. Buyers configure trenching fleets differently depending on water depth, substrate hostility, and project bundling with cable-lay or pipeline installation contracts.
Product Type:
Supply concentration in high-pressure jetting system manufacturing favors integrated producers with captive hydraulic engineering capabilities over component assemblers.
- Mechanical Trenchers:These systems deploy articulated cutting chains with hardened steel or titanium teeth to excavate consolidated clay, glacial till, and cemented sediments. Demand clusters around hostile seabed corridors in the Norwegian North Sea where operators encounter boulder fields and overconsolidated soils that jetting cannot penetrate.
- Jet Trenchers:High-pressure water jet arrays fluidize seabed material without mechanical contact, enabling burial in sensitive marine habitats and coral-protected zones. Norwegian and UK offshore wind developers specify these systems for export cable burial to minimize benthic disturbance and secure environmental permits.
- Combination Trenchers:Hybrid mechanical-jet architectures switch modes based on real-time soil classification, reducing equipment swaps on mixed-substrate routes.
- Remote Operated Trenchers:Tethered systems deployed from ROV platforms access congested subsea fields and platform tie-in corridors where surface-deployed trenchers cannot maneuver.
Today's leader: Mechanical trenchers. Tomorrow's challenger: Jet trenchers.
Application:
Cost tier differentiation separates integrated installation contractors who bundle trenching from pure-play service providers competing on equipment utilization rates.
- Subsea Pipeline Installation:Post-lay burial of oil and gas export lines demands trenching depths exceeding three meters to protect against fishing gear and anchor strikes. Norwegian energy majors charter heavy mechanical trenchers for pipeline corridors from the Troll field to continental European landing points.
- Cable Laying:Inter-array and export cables for offshore wind farms require shallower burial depths but higher positional accuracy. UK Round 4 and Danish Energy Island projects are expanding jet trencher deployment for 66kV and 220kV cable circuits.
- Marine Excavation:Decommissioning and site clearance operations remove legacy infrastructure and level seabed footprints.
- Survey Operations:Pre-trench geophysical surveys and as-laid verification employ trencher-mounted sensors for quality assurance.
Pipeline installation commands premium day-rates. Cable laying is climbing the fastest as offshore wind capacity targets escalate.
End User:
Customer type fragmentation splits procurement between capital-intensive fleet owners and project-specific charterers with variable equipment needs.
- Energy Sector:Oil and gas majors and offshore wind developers constitute the dominant revenue pool, specifying trencher capabilities in field development and construction contracts. Norwegian Equinor and UK BP charter dedicated fleets for multi-year pipeline and cable programs.
- Telecommunications:Subsea fiber optic cable consortia demand rapid burial cycles to protect high-value data infrastructure from external aggression.
- Environmental Agencies:Government bodies commission trenching for marine habitat restoration and coastal defense schemes.
- Marine Contractors:Installation specialists bid for trenching work as subcontracted scope on integrated EPCI contracts.
Energy sector procurement dominates contract value. Telecommunications is emerging as a volume challenger with cross-Atlantic cable builds.
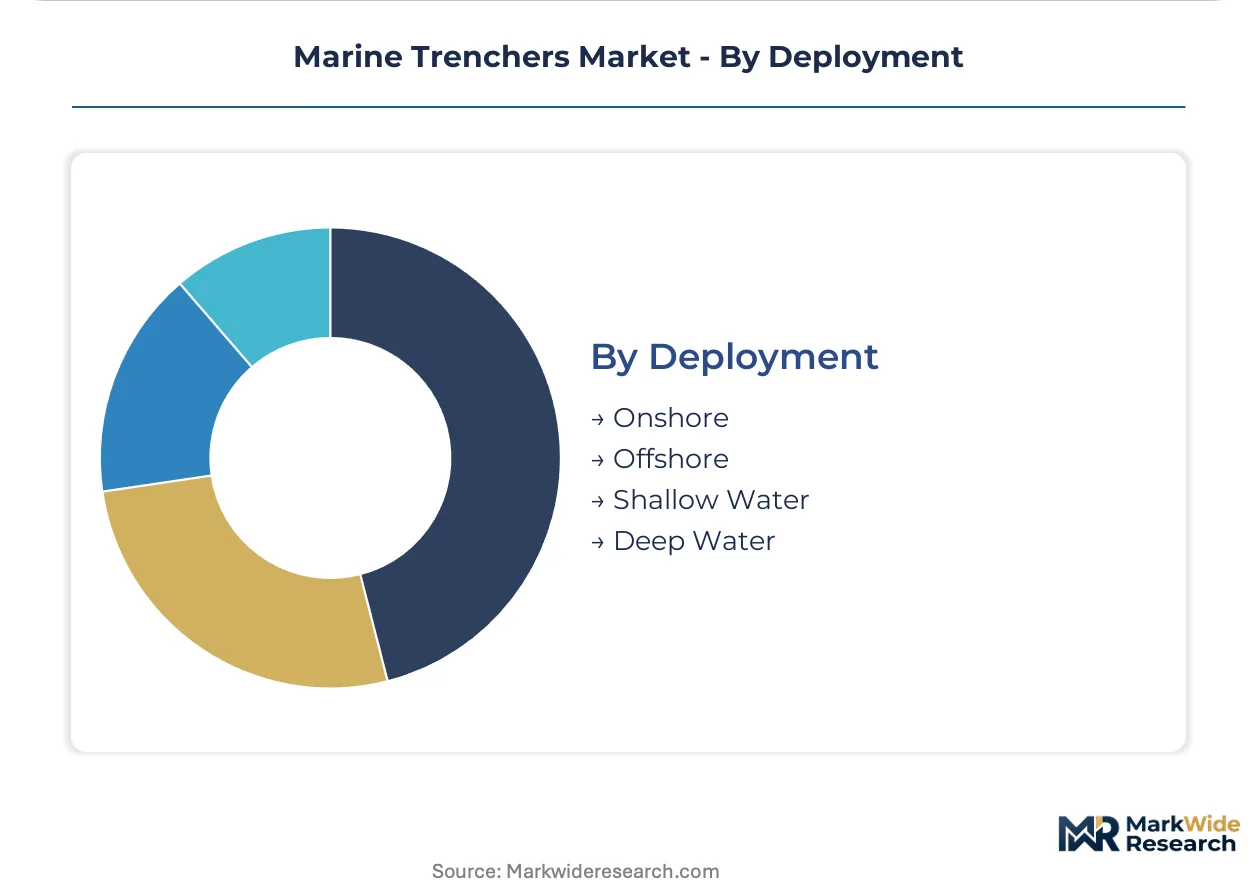
Deployment:
Maturity gradients separate established shallow-water markets from frontier deep-water segments requiring heavier capital commitments and longer certification cycles.
- Deep Water:Deployments beyond 500 meters require pressure-rated hydraulic systems, heavier lift vessels, and dynamic positioning redundancy. Norwegian and UK Atlantic margin projects drive specification of deep-rated mechanical trenchers for pre-salt and ultra-deep developments.
- Offshore:Continental shelf operations between 50 and 200 meters represent the operational sweet spot for most active trenching fleets.
- Shallow Water:Coastal zones and nearshore wind farm sites favor lighter jet trenchers with reduced draft requirements.
- Onshore:Land-based trenching for cable landfall and pipeline shore approaches uses modified marine equipment or purpose-built terrestrial systems.
Offshore deployment anchors current fleet utilization. Deep water is gaining share fastest as pre-salt and floating wind projects advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway commands deeper-water trencher deployment than any European neighbor, while the United Kingdom channels investment toward offshore wind cable corridors. This divergence reflects how geology and policy priorities reshape equipment specifications across North Sea maritime zones.
Norway
Equinor's pre-salt and Arctic margin developments drive demand for pressure-rated mechanical trenchers capable of 500-meter-plus burial operations. The Norwegian Maritime Authority enforces strict IMO MARPOL Annex VI compliance timelines for vessel-trencher integration. Stavanger and Bergen anchor the continent's densest cluster of subsea infrastructure contractors, with trenching fleets concentrated around the Troll and Johan Sverdrup field corridors.
United Kingdom
Round 4 offshore wind auctions and Celtic Sea floating wind pre-commercial arrays expand jet trencher chartering for 66kV and 220kV export cable circuits. The UK's implementation of CSRD disclosure mandates pressures developers to specify lower-carbon trenching equipment in procurement tenders. Aberdeen and Great Yarmouth host competing service bases where installation contractors unbundle trenching from integrated EPCI packages.
Germany
Baltic Sea offshore wind interconnectors and Nord Stream corridor maintenance sustain steady mechanical trencher utilization in shallow-to-mid water depths. Germanischer Lloyd certification requirements extend type-approval timelines for subsea equipment entering North Sea and Baltic operational zones. Rostock and Cuxhaven emerge as strategic logistics hubs for cable-lay vessels with integrated trenching spreads.
Netherlands
Hollandse Kust wind zones and cross-border interconnectors to the UK and Denmark drive specification of jet trenchers with reduced benthic disturbance profiles. The Dutch Emissions Authority enforces EU F-Gas Regulation phasedown schedules that accelerate refrigerant transitions in trencher thermal management systems. Rotterdam and IJmuiden concentrate Europe's largest fleet of heavy-lift offshore vessels with trencher deployment capability.
Denmark
Energy Island projects in the North Sea and Bornholm Basin require hybrid mechanical-jet trenchers for mixed-substrate cable routes spanning glacial till and sand formations. The Danish Maritime Authority coordinates with DNV on subsea equipment certification standards that govern Baltic and North Sea corridor access. Esbjerg functions as the primary marshaling port for trenching spreads serving Danish and German offshore wind construction campaigns.
Marine Trenchers Market Competitive Landscape
Top-tier vendors anchor deep-water and integrated installation contracts, while mid-tier specialists compete on equipment utilization rates and regional charter availability. The vendor base stratifies across three functional tiers: full-system integrators with captive vessel fleets, component specialists licensing trencher technology to third-party operators, and project-specific service providers bundling trenching within broader subsea construction scopes. Strategic moves concentrate on fleet electrification partnerships with vessel owners and software licensing agreements for autonomous seabed tracking systems.
Within the integrated-system tier, Royal IHC, Soil Machine Dynamics Ltd., and Jan De Nul occupy positions defined by divergent capability emphases. Royal IHC exemplifies the full-stack integrator archetype with vessel-trencher automation as a core positioning element. Soil Machine Dynamics Ltd. represents specialized engineering depth in high-pressure jetting architectures. Jan De Nul anchors the captive-fleet scale model, leveraging in-house installation project pipelines across European offshore zones. These three entities collectively illustrate how competitive differentiation fragments across automation depth, hydraulic engineering specialization, and vertical control over project origination.
| Leading Market Players |
|---|
| Royal IHC |
| Soil Machine Dynamics Ltd. |
| Global Marine |
| Jan De Nul |
| Mastenbroek Limited |
| DeepOcean |
| Seatools BV |
| Osbit |
| Delta Subsea LLC |
| Others |
Supply & Pricing Matrix
Titanium and high-grade steel alloy costs cascade from specialty metal foundries in Germany and Japan through cutting chain fabricators to trencher OEMs, compressing margins on mechanical systems while elevating price floors for deep-water rated equipment. Buyers in Norway's North Sea corridor absorb these premiums through multi-year charter structures that bundle certification compliance with vessel-trencher integration.
Pricing Analysis
Capacity additions in the Netherlands and Denmark are reshaping price floors for jet trencher day-rates as fleet operators compete for offshore wind cable burial contracts. Three-tier pricing structure across premium, standard, and economy levels separates DNV-certified deep-water systems from Baltic Sea-rated equipment and uncrewed shallow-water units. Price differentiation hinges on IMO MARPOL Annex VI compliance tier and real-time soil modeling capability. Cost compression in the standard tier is intensifying because charterers unbundle trenching from integrated EPCI packages. Offshore wind developers exhibit highest price sensitivity; oil majors chartering for pre-salt developments show lowest.
Supply Chain Analysis
Heavy-lift vessel repositioning costs from Rotterdam and Singapore dominate logistics expenditure for trencher deployment across Atlantic and North Sea corridors. Hydraulic component manufacturing concentrates in Germany, the Netherlands, and Norway. High-pressure pump assemblies and dynamic positioning sensors draw from specialized subsea engineering clusters. Single-source vulnerability in titanium forging capacity for cutting chains creates procurement risk. Distribution runs through installation contractors with captive fleet ownership rather than pure equipment lessors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine trencher procurement has shifted toward premium specifications as offshore wind developers mandate real-time benthic monitoring and EU F-Gas Regulation compliance as baseline tender requirements.
For Market Incumbents: To counter charter rate erosion from unbundled service procurement, anchor fleet utilization through captive installation project pipelines in Norwegian deep-water corridors. Prioritize backward integration into high-pressure hydraulic component manufacturing to secure supply continuity for jet trencher product lines. DNV certification investment for battery-electric trencher variants creates pricing power against legacy fleet competition. For New Entrants and Emerging Players: Enter via Portugal's floating offshore wind pre-commercial arrays, where dynamic cable burial demand exceeds established fleet capacity. Target remote operated trencher segments serving congested North Sea platform tie-in corridors where surface-deployed systems cannot maneuver. License autonomous seabed tracking software from component specialists rather than developing control architectures in-house. For Investors and Strategic Acquirers: Consolidation pressure builds where project-specific chartering fragments multi-year fleet agreements into discrete auction-based contracts. Five-to-ten year viability favors acquisition targets with captive hydraulic engineering capabilities and EU F-Gas Regulation-compliant thermal management architectures. Monitor CSRD Scope 3 disclosure adoption rates among energy majors as inflection indicator for lower-carbon trenching fleet preference.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Electric Propulsion Retrofit | IMO MARPOL Annex VI compliance secures charter access in Norwegian and UK North Sea corridors. |
| Autonomous Seabed Tracking Licensing | Machine vision integration with multibeam sonar compresses burial cycle times for offshore wind developers. |
| High-Pressure Jetting System Specialization | Captive hydraulic engineering capabilities differentiate jet trencher offerings in sensitive marine habitats. |
| Vertical Fleet Integration with Cable-Lay Vessels | Vessel-trencher automation reduces surface communication latency in deep-water deployments. |
| EU F-Gas Regulation Thermal Redesign | Lower-GWP refrigerant transition maintains certification validity for European offshore zone access. |
Research Methodology
Bottom-up offshore wind and oil field development modeling reconciled against top-down trencher fleet deployment tracking forms the analytical core of this study. Primary interviews with vessel chartering managers, subsea equipment procurement leads, DNV certification engineers, and offshore wind project developers were validated against Lloyd's Register equipment databases, IMO MARPOL Annex VI implementation filings, EU F-Gas Regulation compliance registries, and North Sea offshore construction contract announcements. Secondary triangulation cross-referenced customs data on titanium and high-grade steel alloy imports with fleet positioning signals from heavy-lift vessel operators.
The input-output matrix maps trencher specification requirements across water depth tiers, substrate hostility indices, and regulatory compliance clusters over the projection horizon. Segmentation dimensions modeled include product type, application, end-user category, and deployment depth zone, with additional weighting for electrification technology adoption patterns. CAGRs were derived from equipment procurement pipelines disclosed in offshore wind auction results and oil major field development plans, incorporating EU Green Deal carbon intensity trajectories as scenario variables.
Inputs from EPC contractors and classification society certification records were available through the study window; gaps in pre-commercial floating wind project cost structures introduce uncertainty bands around deep-water deployment forecasts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
North Sea Offshore Support Vessels Market
Marine
Boat Cleat Market
Marine
Marine Stabilizers Market
Marine
Mooring Ropes Market
Marine
Controllable Pitch Marine Propeller Market
Marine
Shipbuilding Market
Marine
Azimuth Thrusters Market
Marine
Unmanned Marine Vehicles Market
Marine
Electric Ferry Market
Marine
Autonomous Ships Market
Marine
Marine Navigation System Market
Marine
Ship Rudders Market
Marine
Global Submarine Market
Marine
India Boat Davits Market
Marine
Boat Ladder Market
Marine
Marine Transport Refrigeration Unit Market