
 Marine Growth Removal Tool Market | 2026-2036
Marine Growth Removal Tool Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Growth Removal Tool Market Foresight
The capital-intensity gap between integrated service providers and standalone equipment manufacturers is collapsing. Jotun A/S leverages its coatings-to-cleaning equipment portfolio to capture recurring vessel maintenance contracts. Oceaneering International anchors its position through subsea robotics integration with growth removal systems. Kongsberg Gruppen ASA differentiates via autonomous underwater vehicle compatibility with cleaning tool payloads.
Marine growth removal tools encompass mechanical, hydraulic, and acoustic devices engineered to dislodge biofouling organisms from submerged surfaces, typically operating at depths exceeding 50 meters with pressure ratings above 10 bar for subsea deployment. Their primary function restores hydrodynamic efficiency on ship hulls and structural integrity on offshore installations. Mechanical brush systems dominate routine maintenance contracts for shipping companies due to proven reliability on flat hull geometries. High-pressure water jet equipment captures expanding share in emergency cleaning applications where chemical discharge restrictions apply. Ultrasonic cleaner adoption accelerates among recreational boaters seeking dockside solutions without haul-out requirements.
The International Maritime Organization's Biofouling Management Guidelines shape product certification requirements for tools deployed in international shipping lanes. The EPA's Vessel General Permit in the United States mandates environmentally acceptable cleaning methods, restricting chemical solution discharge in domestic waters. The EU's Marine Strategy Framework Directive extends similar constraints across European ports. Stakeholders must monitor regulatory divergence between ballast water treatment standards and hull cleaning protocols to align tool development with enforcement trajectories.
Market Dynamics
The collision between tightening biofouling regulations and subsea robotics maturation is restructuring competitive advantage around integrated service capability rather than standalone equipment sales.
Growth Catalysts
- IMO Hull Performance Standards:Mandatory energy efficiency design indices force shipping operators into scheduled cleaning cycles, creating recurring demand for remotely operated vehicle-deployable tools.
- North Sea Infrastructure Density:Norway's subsea asset concentration generates sustained tool deployment requirements as platform operators face mandatory inspection intervals.
- Acoustic Cleaning Maturation:Ultrasonic systems eliminate chemical discharge risks entirely, opening dockside service opportunities for recreational and commercial vessels in restricted harbors.
Market Restraints
- High-Pressure Pump Supply Concentration:German and Japanese pump manufacturers control critical component supply, exposing tool assemblers to input cost volatility and extended lead times.
- Subsea Pressure Rating Requirements:Tools rated beyond 300 meters depth demand specialized sealing technologies and metallurgy that limit viable supplier pools.
- Diver-Dependent Legacy Methods:Manual cleaning using commercial divers persists in shallow-water markets, delaying autonomous tool penetration in cost-sensitive segments.
Strategic Opportunities
- Brazil Pre-Salt Development:Deepwater field expansions off Santos Basin create demand for pressure-rated tools capable of operating at 2,000+ meter depths where diver access is impossible.
- EU Green Deal Alignment:Member state port authorities are integrating hull cleaning infrastructure into green corridor initiatives, subsidizing shore-based robotic cleaning stations.
- ROV-AUV Convergence:Tool payloads compatible with both tethered and autonomous underwater vehicles enable single-platform deployment across inspection and maintenance missions.
Industry Challenges
- Subsea Robotics Technician Scarcity:Tool operation and maintenance require cross-trained personnel fluent in both hydraulic systems and underwater navigation protocols.
- Classification Society Certification Timelines:DNV and Bureau Veritas approval processes for novel cleaning mechanisms extend 18-24 months, delaying product commercialization.
- Legacy Vessel Compatibility:Older hull designs lack standardized attachment points for robotic cleaning systems, forcing costly custom interface engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Growth Removal Tool Market |
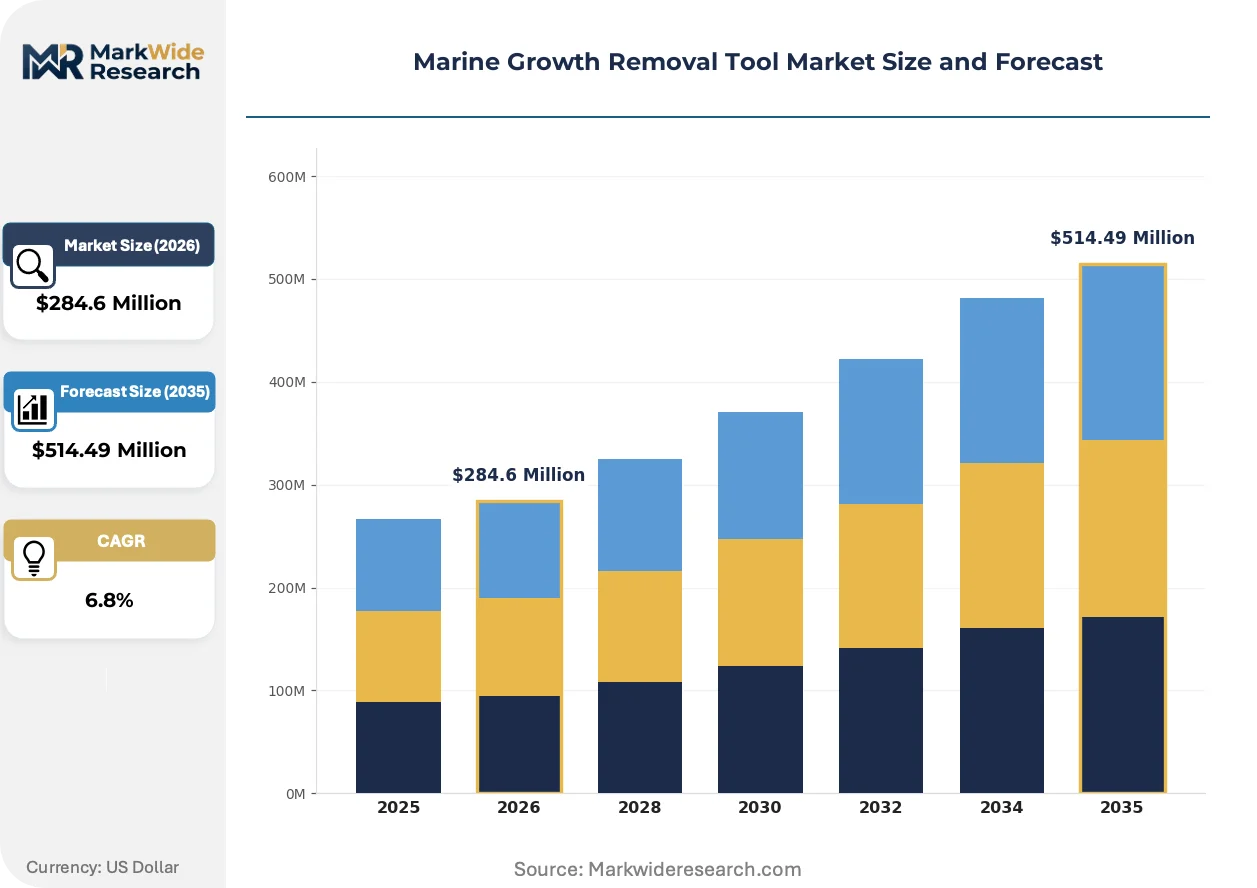
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $514.49 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Brush, High-Pressure Water Jet, Chemical Solution, Ultrasonic Cleaner Application: Ship Hulls, Offshore Platforms, Underwater Structures, Boat Maintenance Service Type: Routine Maintenance, Emergency Cleaning, Inspection Services, Custom Solutions End User: Shipping Companies, Oil & Gas Operators, Marine Contractors, Recreational Boaters |
| Companies Covered | Jotun A/S, VLN Advanced Technologies, Oceaneering International, Inc., FoundOcean, Inc., Ashtead Technology, Hydrex NV, IAS Group, Proserv, Kongsberg Gruppen ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Growth Removal Tool Market Shifts & Advancements
Autonomous deployment architectures and non-chemical cleaning modalities are compressing the traditional service-provider hierarchy by enabling direct vessel-operator tool ownership.
Cavitational water jet technology generates micro-bubbles that implode against biofouling surfaces, stripping organisms without abrasive contact. Offshore platform operators in the North Sea are adopting these systems for subsea structural cleaning where coating damage risks are unacceptable. The technology is displacing mechanical brush systems in inspection-critical applications where surface integrity preservation outweighs cleaning speed.
The EPA's Vessel General Permit mandates environmentally acceptable cleaning methods in US waters, explicitly restricting biocide discharge during in-water maintenance. Ship operators now face enforcement actions for hull cleaning effluent containing copper-based antifouling residues. Container fleets operating between Long Beach and Singapore are retrofitting with closed-loop cleaning capture systems to maintain multi-jurisdiction compliance.
Asset owners are consolidating maintenance procurement under integrated service contracts spanning coatings application, inspection, and growth removal. This bundling compresses standalone equipment rental markets while expanding recurring revenue pools for full-service providers. The shift is most pronounced among European tanker operators managing fleets under EU MRV monitoring requirements.
Marine Growth Removal Tool Market Segmentation
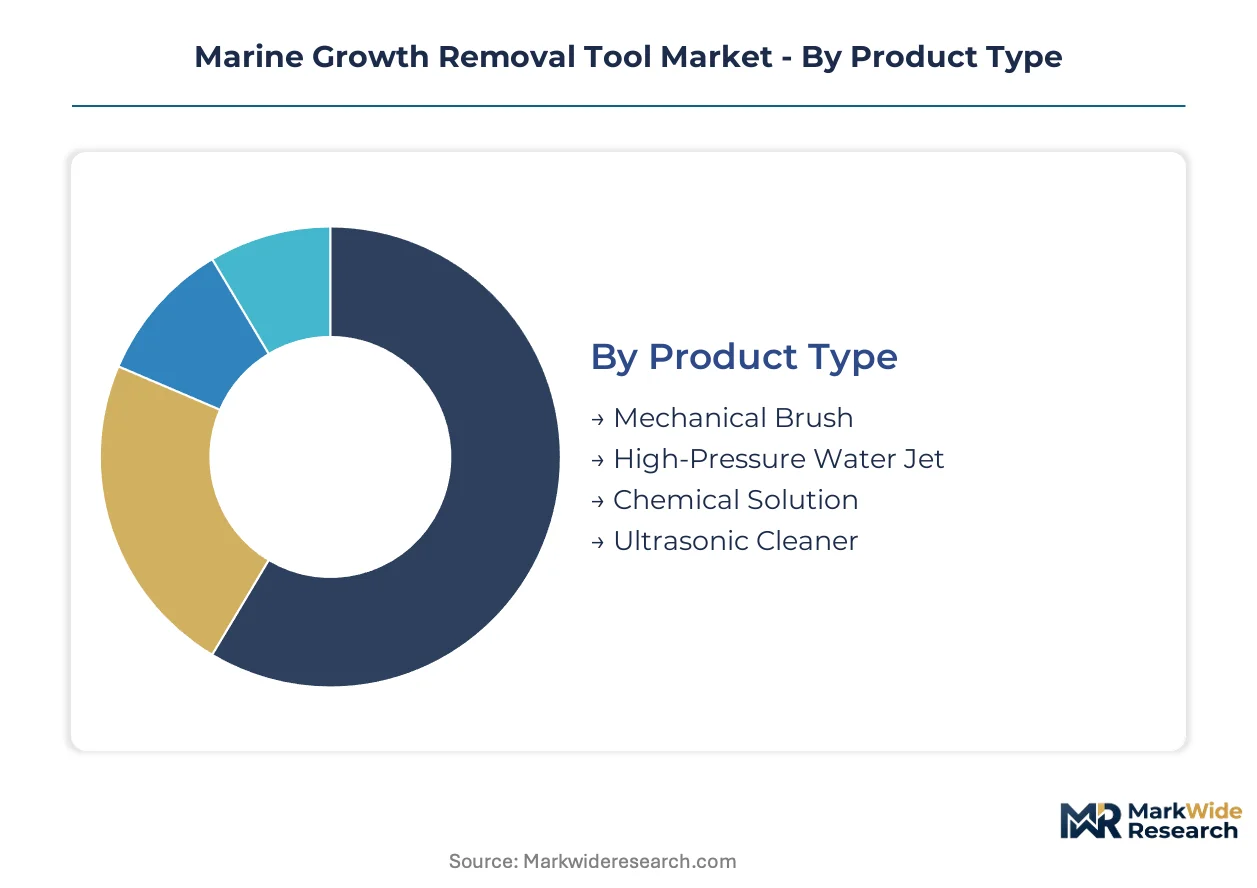
Segmentation reveals how technology choices map to regulatory pressure and operational depth. Tool specifications diverge sharply between dockside recreational use and subsea infrastructure maintenance.
Product Type:
Margin pools concentrate in systems that eliminate chemical discharge liability and reduce vessel downtime.
- Mechanical Brush:Rotating bristle assemblies deliver abrasive contact cleaning for flat hull geometries. Shipping companies in Norway's North Sea cluster deploy these for scheduled maintenance where coating damage tolerance exists. IMO hull performance standards drive replacement cycles as operators seek predictable cleaning intervals.
- High-Pressure Water Jet:Pump-driven systems generate concentrated streams exceeding 500 bar for biofouling dislodgment without chemical additives. Emergency cleaning contracts in US waters favor this modality where EPA Vessel General Permit restrictions apply. Port authorities in California mandate closed-loop effluent capture for these operations.
- Chemical Solution:Biocide-based treatments dissolve marine organisms through controlled chemical reaction. Recreational boaters in Mediterranean harbors use these for dockside application where discharge regulations permit.
- Ultrasonic Cleaner:Acoustic transducers generate cavitation bubbles that implode against fouled surfaces. The technology eliminates consumables entirely, attracting marina operators in EU ports integrating green corridor infrastructure.
Mechanical Brush holds installed capacity. Ultrasonic Cleaner is rotating up the share rankings.
Application:
Volume concentration follows subsea asset density and fleet size rather than unit economics.
- Ship Hulls:Container and tanker fleets require periodic cleaning to maintain energy efficiency design indices. Operators on Asia-Europe routes face the strictest cleaning intervals under IMO monitoring.
- Offshore Platforms:Jacket structures and subsea manifolds accumulate macrofouling that accelerates corrosion. Brazil's pre-salt developments at 2,000+ meter depths demand pressure-rated tools where diver access is impossible.
- Underwater Structures:Pipelines, cables, and renewable energy foundations require inspection-compatible cleaning methods. North Sea offshore wind installations drive adoption of non-contact modalities.
- Boat Maintenance:Recreational and small commercial vessels favor portable systems operable without haul-out. Mediterranean and Caribbean marinas represent the densest service point networks.
Ship Hulls dominates procurement volume. Offshore Platforms is climbing the fastest as deepwater field development accelerates.
Service Type:
Contract structure determines equipment ownership models and recurring revenue stability.
- Routine Maintenance:Scheduled cleaning cycles tied to regulatory compliance calendars. European tanker operators bundle these under integrated service contracts spanning coatings and inspection.
- Emergency Cleaning:Unplanned interventions triggered by performance degradation or inspection failures. High-pressure water jet systems capture this demand where speed outweighs coating preservation.
- Inspection Services:Cleaning as prerequisite for structural assessment and certification. DNV and Bureau Veritas protocols drive standardization of surface preparation methods.
- Custom Solutions:Engineered tool configurations for non-standard geometries or extreme depth ratings. Legacy vessel fleets lacking standardized attachment points require interface customization.
Routine Maintenance anchors long-term contracts. Emergency Cleaning is gaining share fastest as just-in-time logistics compress response windows.
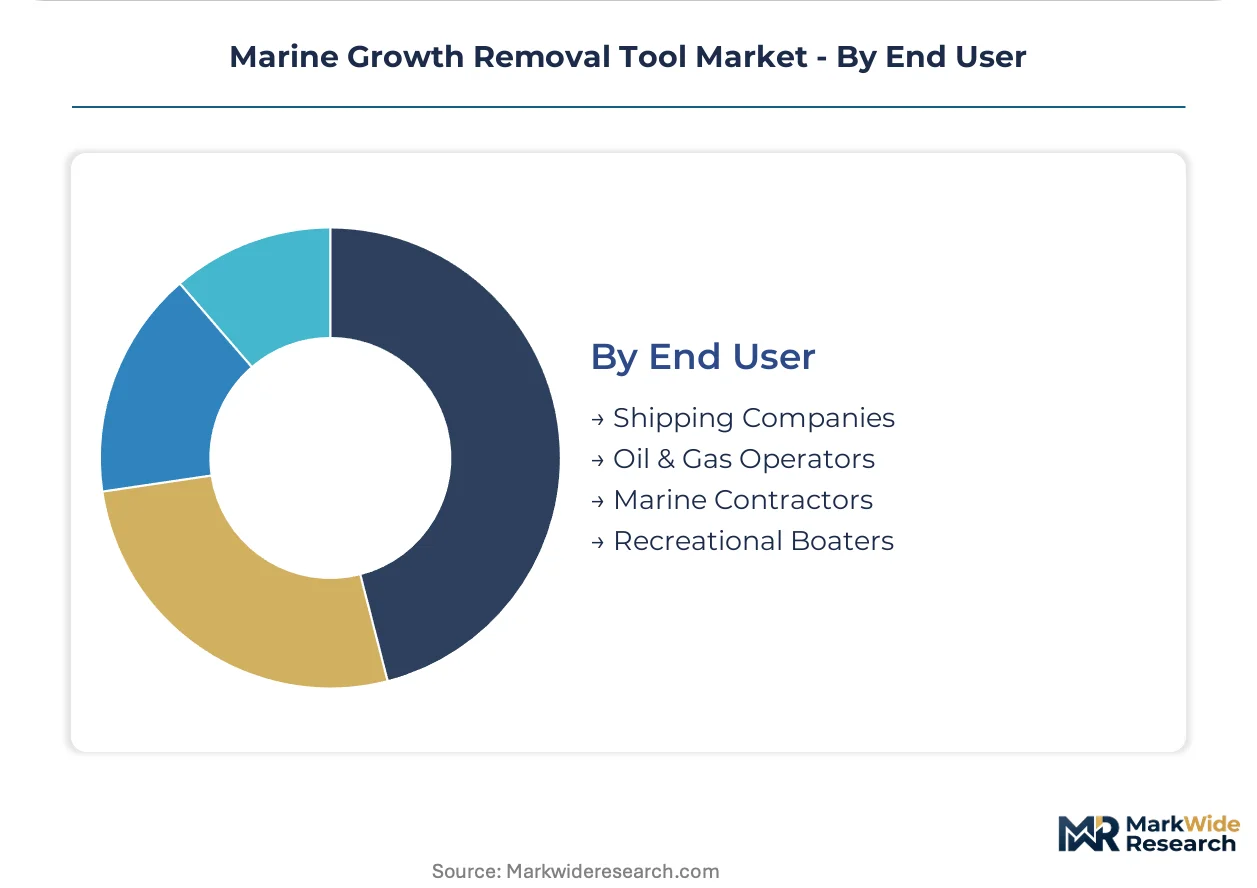
End User:
Procurement sophistication varies from integrated fleet management to individual owner-operator transactions.
- Shipping Companies:Container, bulk, and tanker fleets with centralized technical management. These buyers negotiate multi-vessel service agreements and specify ROV-deployable tools for in-water cleaning.
- Oil & Gas Operators:Offshore platform and subsea infrastructure owners with mandatory inspection regimes. Norway's operator community drives standardization through joint industry projects.
- Marine Contractors:Third-party service providers executing cleaning on behalf of asset owners. These intermediaries seek tool versatility across client specifications.
- Recreational Boaters:Individual vessel owners prioritizing convenience and dockside accessibility. Ultrasonic systems are penetrating this segment through marina retail channels.
Shipping Companies hold committed procurement volume. Oil & Gas Operators is rotating up the share rankings as subsea infrastructure ages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian operators command pricing premiums for deepwater-capable tools while Mediterranean service providers compete on dockside accessibility and turnaround speed. This asymmetry reflects divergent asset bases rather than technology gaps. Regional procurement patterns track subsea infrastructure density and fleet composition rather than manufacturing proximity.
Norway
North Sea platform operators drive demand for pressure-rated tools operating beyond 300 meters. The Norwegian Environment Agency enforces strict biofouling management protocols for offshore installations. Stavanger and Bergen host the densest concentration of subsea service contractors executing mandatory inspection intervals.
United States
Container fleets operating between Long Beach and Singapore require closed-loop cleaning systems for multi-jurisdiction compliance. The EPA's Vessel General Permit restricts biocide discharge during in-water maintenance. Gulf Coast ports in Texas and Louisiana are retrofitting shore-based capture infrastructure for high-pressure water jet operations.
Brazil
Pre-salt field developments at 2,000+ meter depths create demand for diver-replacement technologies. The national petroleum regulator mandates structural integrity assessments at intervals incompatible with human access. The Santos Basin cluster anchors procurement for extreme-depth rated equipment.
United Kingdom
Offshore wind installations in the North Sea require inspection-compatible cleaning methods for turbine foundations. The Maritime and Coastguard Agency aligns with EU Marine Strategy Framework Directive constraints on discharge. Aberdeen maintains its position as a service hub despite production declines in mature oil fields.
Germany
Pump manufacturers in Baden-Württemberg and Bavaria control critical component supply for high-pressure water jet systems. The Federal Maritime and Hydrographic Agency enforces ballast water and hull cleaning protocols for vessels calling Hamburg and Bremerhaven. Component supply concentration exposes tool assemblers to input cost volatility.
Marine Growth Removal Tool Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated service providers capturing recurring contracts while equipment specialists compete on specification breadth. The vendor base stratifies into three tiers: full-service contractors bundling coatings and cleaning, standalone tool manufacturers selling into third-party service fleets, and component suppliers dominating pump and sealing technologies. Strategic moves center on M&A for geographic coverage and partnerships for ROV-AUV payload compatibility.
Among integrated service providers, Jotun A/S and Oceaneering International occupy positions spanning coatings application through growth removal execution. Kongsberg Gruppen ASA exemplifies the autonomy-focused archetype, with tool payloads engineered for both tethered and untethered underwater vehicle deployment. These three anchors represent distinct competitive vectors: chemical-coating integration, subsea robotics heritage, and autonomous system compatibility.
| Leading Market Players |
|---|
| Jotun A/S |
| VLN Advanced Technologies |
| Oceaneering International, Inc. |
| FoundOcean, Inc. |
| Ashtead Technology |
| Hydrex NV |
| IAS Group |
| Proserv |
| Kongsberg Gruppen ASA |
| Others |
Supply & Pricing Matrix
Extended pump component lead times stretching 16-24 weeks compress pricing power for tool assemblers while concentrating margin capture among German and Japanese pump manufacturers who control critical high-pressure system inputs.
Pricing Analysis
The customization-premium spread spans 40-60% above standard catalog configurations for pressure-rated tools exceeding 300-meter depth ratings. Project-based pricing dominates subsea deployments where interface engineering for legacy vessel geometries drives specification variance. Price differentiation rests on DNV certification tier and after-sales service bundling rather than base hardware. Cost compression in standard mechanical brush systems is intensifying because shipping operators are consolidating procurement under multi-vessel integrated service contracts.
Supply Chain Analysis
Inventory cycles for critical sealing technologies and specialized metallurgy components extend 20-30 weeks, forcing tool manufacturers to pre-position finished goods ahead of confirmed contracts. Manufacturing concentrates in Norway, Germany, and the United States where subsea robotics heritage and precision pump engineering anchor supplier ecosystems. Raw material dependencies include high-grade stainless alloys, ceramic coatings for cavitation resistance, and specialized hydraulic fluids rated for deepwater pressure. Single-source vulnerability runs through German pump manufacturers controlling 500+ bar pressure system supply. Distribution feeds from regional service hubs in Stavanger, Aberdeen, and Houston directly to offshore operator procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among European tanker operators bundling coatings, inspection, and cleaning under single-source contracts, compressing standalone equipment rental margins while expanding recurring revenue capture for integrated service providers.
For Market Incumbents: Consolidate control over ROV-AUV payload compatibility to defend against autonomous deployment architectures that enable direct vessel-operator tool ownership. Deepen backward integration into high-pressure pump technologies to reduce exposure to German and Japanese component supply concentration. Prioritize certification investment with DNV and Bureau Veritas to accelerate approval timelines for novel cavitational cleaning mechanisms. For New Entrants and Emerging Players: Lead with dockside ultrasonic systems for recreational boaters in EU green corridor ports where subsidy flows and discharge restrictions create immediate addressable demand. Target Brazil's pre-salt developments with pressure-rated tools engineered for 2,000+ meter depths where diver access is impossible and incumbent tooling lacks rated capacity. Deploy through marina retail channels with portable systems operable without haul-out requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across autonomous underwater vehicle-compatible tool payloads as software-defined control systems displace hydraulic complexity. Long-term viability favors acquirers of subsea robotics integration capabilities over standalone mechanical brush manufacturers facing commoditization pressure. Watch for inflection signals in EU port authority infrastructure subsidy announcements indicating shore-based robotic cleaning station deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| ROV-AUV Payload Standardization | Enables single-platform deployment across inspection and maintenance missions for Norway's North Sea operators. |
| Backward Integration into Pump Manufacturing | Reduces input cost volatility from German and Japanese component supply concentration. |
| Closed-Loop Effluent Capture Systems | Satisfies EPA Vessel General Permit restrictions for container fleets operating US-Asia routes. |
| Cavitational Water Jet Technology Licensing | Opens inspection-critical applications where coating damage risks exclude mechanical brush systems. |
| Marina Infrastructure Partnership | Secures retail channel access for ultrasonic systems targeting EU green corridor subsidy flows. |
Research Methodology
A standing panel of offshore platform maintenance directors, subsea robotics engineers, shipping fleet technical managers, and port authority environmental compliance officers provided ongoing calibration across the study period. Primary interviews combined with secondary validation from IMO regulatory filings, EPA Vessel General Permit enforcement records, DNV classification society protocols, and Norwegian Environment Agency offshore installation directives. Bottom-up equipment deployment estimates triangulated against top-down subsea infrastructure investment forecasts.
Consistency checks validated volume and value outputs against external benchmarks including subsea robotics capex disclosures, offshore wind foundation installation databases, and container fleet energy efficiency monitoring reports. Segmentation dimensions modeled encompass product type, application depth rating, service contract structure, and end-user procurement sophistication across the projection horizon. CAGRs derived from equipment replacement cycle analysis, regulatory compliance calendar alignment, and autonomous deployment adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of biofouling standards or accelerated AUV technology maturation would require recalibration. Forecasts reflect assumptions regarding inspection interval mandates, pump component supply stability, and classification society approval timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Tele-Operated Marine Drone Market
Marine
Jet Boat Market
Marine
Marine Big Data Market
Marine
Marine Chartplotter Market
Marine
Boat Trolling Motor Market
Marine
Marine Beacon Market
Marine
Submarine Propulsion Systems Market
Marine
Marine Winch Motors Market
Marine
Marine Asset Integrity Services Market
Marine
Europe Recreational Boating Market
Marine
Electric Ship Market
Marine
Marine Strip Market
Marine
Marine Glass Market
Marine
Marine Fasteners Market
Marine
Marine Communication Market
Marine
Marine Auxiliary Engine Market