
 Tank Container Shipping Market | 2026-2036
Tank Container Shipping Market Size, Share, and Industry Trends Forecast 2026-2036
Tank Container Shipping Market Outlook
Specialized cryogenic-grade tank specifications is rotating through the chemical logistics sector as shippers replace aging atmospheric fleets. Transtainer dominates European food-grade ISO tank leasing through captive depot networks. Multitank anchors Asia-Pacific chemical transport with purpose-built hazardous cargo fleets. BLT Tank Container specializes in pharmaceutical temperature-controlled units with multi-compartment stainless engineering.
Tank container shipping deploys cylindrical pressure vessels built to ISO 668 frame dimensions with 21,000 to 35,000 liter capacity, designed for multimodal liquid and gas transport across rail, sea, and road without intermediate cargo handling. Cryogenic tank segments lead capital allocation as LNG and liquid industrial gas trade volumes expand, while intermodal transportation modes capture margin pools through reduced transloading costs and cargo integrity guarantees. Specialty tank categories sustain premium positioning for corrosive and high-purity chemical grades where standard ISO construction fails.
IMO Certification and UN Standards govern hazardous material tank construction, testing intervals, and route permissions, forcing fleet operators into scheduled retrofit cycles that sustain replacement demand. ISO 9001 and GMP Certification shape pharmaceutical and food-grade tank access, filtering smaller operators from regulated end-user supply chains. Stakeholders must monitor evolving carbon-border mechanisms and tank-recertification burdens as regulatory stringency tightens across major chemical trade corridors.
Market Dynamics
Specialty chemical producers are consolidating intermodal logistics around ISO-certified tank fleets as the IMO's revised IMDG Code forces systematic replacement of aging atmospheric pressure vessels across maritime trade corridors.
Growth Catalysts
- Asia-Pacific Chemical Manufacturing:Domestic production clusters in China are scaling liquid bulk logistics through dedicated tank container leasing pools. Hazardous cargo volumes from Shanghai and Ningbo chemical parks sustain fleet utilization rates.
- Cryogenic Infrastructure Mandates:Industrial gas trade expansion requires LNG-compatible tank specifications under updated UN portable tank regulations. Energy majors are retrofitting depots for cryogenic handling capabilities.
- REACH Compliance Upgrades:European chemical shippers face mandatory tank recertification cycles for corrosive substance transport. This sustains replacement demand for stainless steel multi-compartment designs.
Market Restraints
- Stainless Steel Input Volatility:Grade 316L plate prices fluctuate with nickel and molybdenum commodity cycles. Tank fabricators pass material cost swings through to lease rates with 6-12 month lags.
- Depot Network Concentration:Food-grade tank cleaning and heating infrastructure clusters in Rotterdam, Houston, and Singapore. Shippers outside these hubs face positioning costs and extended empty mileage.
- Technical Limitations of Standard ISO Frames:Cryogenic tanks require reinforced corner castings and extended frame dimensions. Standard chassis fleets cannot accommodate these units without modification.
Strategic Opportunities
- India Pharmaceutical Cold Chain:CDSCO temperature-validation requirements for biologics transport create demand for pharmaceutical-grade tank containers with active cooling systems. Domestic production of insulin and vaccines drives fleet expansion.
- Rail-Sea Intermodal Integration:New gauge-compatible tank designs allow direct rail transfer from Chinese interior manufacturing zones to coastal ports. This compresses transit times versus road feeder legs.
- EU Green Deal Carbon Border Adjustments:Shippers optimizing cargo consolidation into tank containers versus breakbulk reduce per-tonne emissions. Fleet operators can capture sustainability-linked contract premiums.
Industry Challenges
- Welder Certification Scarcity:ASME Section IX qualified welders for pressure vessel fabrication command premium wages. Training pipelines lag fleet expansion timelines by 18-24 months.
- Multi-Modal Liability Fragmentation:Damage attribution between rail, sea, and road carriers requires blockchain-based custody documentation. Legacy paper bills of lading create dispute resolution friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tank Container Shipping Market |
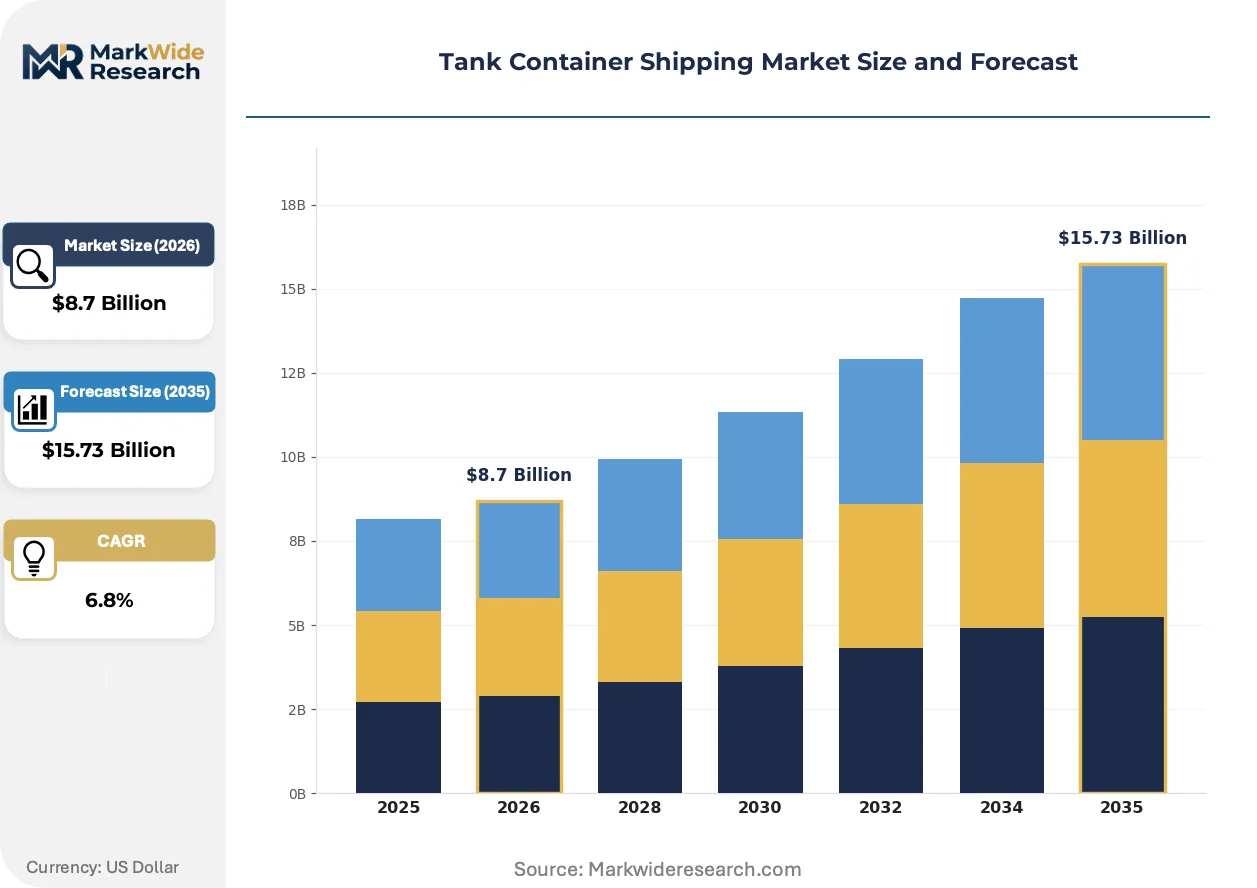
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Container Type: ISO Tank, Cryogenic Tank, Specialty Tank, Atmospheric Tank Transportation Mode: Rail, Sea, Road, Intermodal End User: Chemical Industry, Food & Beverage, Pharmaceuticals, Oil & Gas Regulatory Compliance: IMO Certification, UN Standards, ISO 9001, GMP Certification |
| Companies Covered | Transtainer, Multitank, ISO Tank Joint Venture (ITJV), BLT Tank Container, Exel Tank Container, United Tank Containers (UTC), Denak, Rotank, Tritank, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tank Container Shipping Market Strategic Shifts
Digital cargo monitoring and alternative refrigerant chemistries are restructuring how tank fleet operators guarantee cargo integrity across extended intermodal chains. Asset-light platforms are displacing traditional ownership models.
Multi-sensor telemetry systems embedded in tank containers transmit pressure, temperature, and location data via satellite and cellular networks. Pharmaceutical and food-grade shippers in Germany and the Netherlands mandate real-time visibility as a contract condition. This capability is decomposing the traditional role of freight forwarders as information intermediaries, compressing margins on pure brokerage services.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in mechanically refrigerated tanks. Industrial gas operators are retrofitting fleets with nitrogen-based cooling systems or passive vacuum-insulated designs. Cryogenic tank segments in Belgium and northern France face accelerated replacement cycles as 2024-2030 quota reductions tighten.
Chemical buyers are consolidating procurement around integrated logistics providers offering tank supply, cleaning, and regulatory documentation as bundled services. Small and mid-sized specialty chemical producers in Japan and South Korea are abandoning spot-market tank leasing for multi-year dedicated fleet contracts. This shift concentrates purchasing power with fewer logistics decision-makers and locks out fragmented depot operators lacking certification breadth.
Tank Container Shipping Market Segmentation
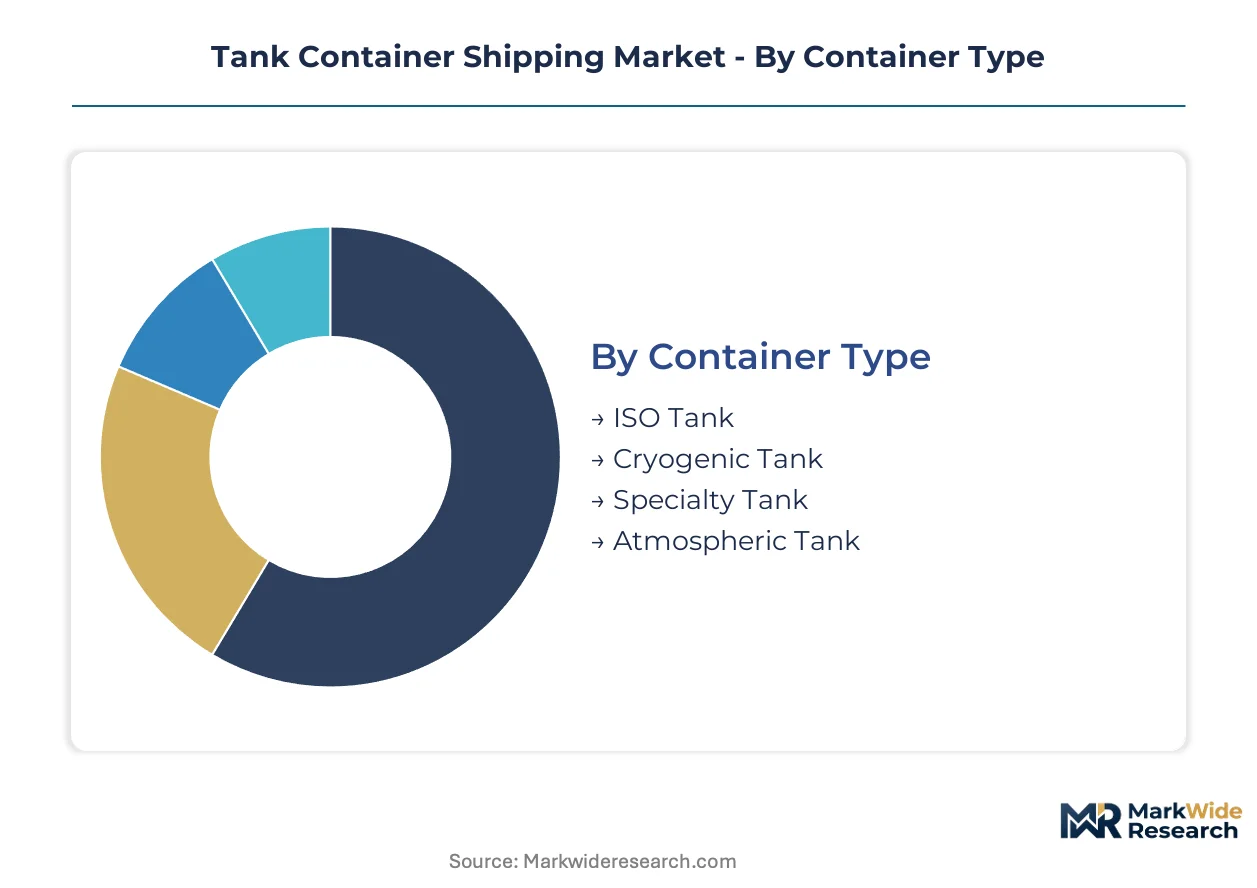
Tank container segmentation determines fleet procurement priorities, depot infrastructure investment, and regulatory compliance pathways. Distinct container specifications, modal capabilities, and end-use certifications fragment operational requirements across chemical, pharmaceutical, and food-grade supply chains.
Container Type:
ISO-standard frames dominate port-to-port movements, while cryogenic and specialty variants capture premium cargo categories through dedicated handling infrastructure.
- ISO Tank:Stainless steel cylindrical vessels built to ISO 668 frame dimensions with 21,000-35,000 liter capacity. Chemical manufacturers in China deploy these units for intermodal liquid bulk between Shanghai port clusters and inland production zones. IMO's revised IMDG Code is forcing systematic replacement of aging atmospheric fleets with pressure-rated ISO constructions.
- Cryogenic Tank:Vacuum-insulated pressure vessels with reinforced corner castings for LNG and liquid industrial gases. Energy majors in Belgium and northern France are retrofitting depots for cryogenic handling as EU F-Gas Regulation phases down conventional refrigerants. These units require modified chassis fleets and extended frame dimensions incompatible with standard road equipment.
- Specialty Tank:Multi-compartment stainless steel designs for corrosive chemicals and high-purity pharmaceutical grades. REACH compliance upgrades in Europe sustain replacement demand for 316L-grade constructions with enhanced surface finishes.
- Atmospheric Tank:Non-pressure vessels for low-hazard liquids and certain food-grade cargoes. These units face accelerated phase-out across maritime routes as safety standards tighten.
By volume, ISO Tank leads. By growth pace, Cryogenic Tank is expanding most quickly.
Transportation Mode:
Modal selection hinges on cargo value density, transit time requirements, and infrastructure availability across origin-destination pairs.
- Sea:Deep-water container shipping carries bulk liquid cargoes across major trade lanes. Port congestion and schedule reliability drive shippers toward dedicated tank container services versus conventional breakbulk.
- Rail:Gauge-compatible tank designs enable direct transfer from Chinese interior manufacturing zones to coastal ports. New rail-sea intermodal specifications compress transit times versus road feeder legs.
- Road:Flexible last-mile delivery and positioning services connect depot networks to final customers. Driver shortages and fuel cost volatility constrain long-haul road economics.
- Intermodal:Seamless rail-sea-road transfers without intermediate cargo handling preserve product integrity and reduce transloading costs. Pharmaceutical and food-grade shippers mandate intermodal capability as a contract condition.
Sea freight handles the greatest cargo volumes. Intermodal solutions are climbing the fastest as chemical buyers consolidate procurement around integrated logistics providers.
End User:
End-use certification requirements fragment fleet deployment, with pharmaceutical and food-grade segments commanding premium positioning through specialized cleaning and temperature-control infrastructure.
- Chemical Industry:Specialty chemical producers in Asia-Pacific are scaling dedicated tank leasing pools for hazardous liquid transport. Corrosive substance classifications under REACH and IMDG Code sustain demand for stainless steel multi-compartment designs.
- Pharmaceuticals:Temperature-controlled units with active cooling systems serve biologics transport under CDSCO validation requirements in India. Insulin and vaccine production drives fleet expansion with GMP-certified cleaning protocols.
- Food & Beverage:Food-grade tank cleaning and heating infrastructure clusters in Rotterdam, Houston, and Singapore. Shippers outside these hubs face positioning costs and extended empty mileage.
- Oil & Gas:LNG-compatible tank specifications support industrial gas trade expansion under updated UN portable tank regulations. Cryogenic depot capabilities anchor this segment's infrastructure requirements.
Chemical Industry absorbs the largest fleet deployment. Pharmaceuticals shows the steepest expansion trajectory as cold-chain validation requirements proliferate.
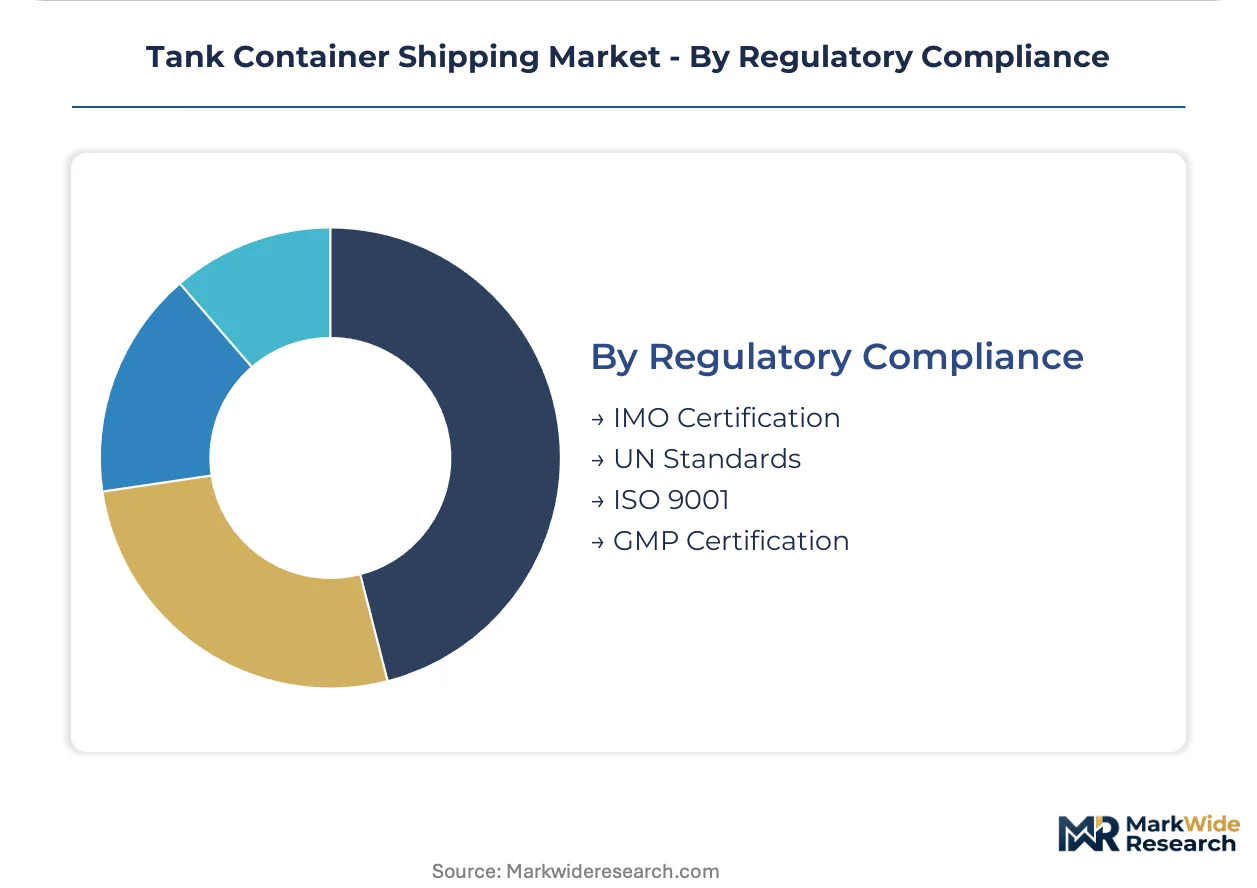
Regulatory Compliance:
Certification tiers filter operator participation, with multi-standard compliance concentrating purchasing power among integrated logistics providers.
- IMO Certification:Governs hazardous material tank construction, testing intervals, and route permissions. Fleet operators face scheduled retrofit cycles that sustain replacement demand across maritime corridors.
- UN Standards:Portable tank regulations specify pressure ratings and structural requirements for cryogenic and high-hazard cargoes. Energy majors align depot investments with UN specification timelines.
- ISO 9001:Quality management certification shapes access to regulated end-user supply chains. Smaller depot operators lacking certification breadth face exclusion from consolidated procurement.
- GMP Certification:Pharmaceutical and food-grade tank access requires documented cleaning validation and temperature-control integrity. Real-time telemetry systems are becoming mandatory for GMP-contracted fleets.
IMO Certification covers the broadest fleet base. GMP Certification is gaining share fastest as pharmaceutical logistics consolidates around integrated providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports specialty chemicals to European and North American buyers through dedicated tank container corridors, with intermodal logistics scaling across Shanghai-Ningbo port clusters and inland manufacturing zones.
China
Domestic chemical manufacturing clusters in Jiangsu and Shandong provinces drive demand for ISO-certified hazardous liquid transport. MIIT's dual carbon goals pressure fleet operators toward energy-efficient intermodal solutions. The Yangtze River Delta anchors tank leasing pools serving pharmaceutical and specialty chemical exporters.
Germany
REACH compliance upgrades sustain replacement demand for 316L-grade stainless multi-compartment tank designs. ECHA enforcement of corrosive substance classifications tightens recertification cycles. The Rhine-Ruhr industrial corridor concentrates food-grade tank cleaning infrastructure serving Benelux chemical shippers.
United States
Shale-derived chemical feedstock expansion drives Gulf Coast tank container utilization for hazardous liquid exports. EPA hazardous waste transport regulations align with UN portable tank specifications for cross-border Mexican trade. Houston hosts the dominant Western Hemisphere depot network for food-grade tank heating and cleaning services.
India
CDSCO temperature-validation requirements for biologics transport create demand for pharmaceutical-grade tank containers with active cooling systems. Domestic insulin and vaccine production clusters in Maharashtra and Telangana drive fleet expansion. The Jawaharlal Nehru Port-Ahmedabad corridor scales dedicated tank leasing for chemical exporters.
Belgium
EU F-Gas Regulation phases down hydrofluorocarbon refrigerants, accelerating cryogenic tank retrofit cycles for industrial gas operators. Antwerp-Rotterdam depot networks anchor LNG-compatible handling infrastructure. Northern France-Belgium border regions concentrate energy major investments in cryogenic fleet capabilities.
Tank Container Shipping Market Competitive Environment
Listed leaders compete with private specialists across certification breadth and depot network density. The vendor base stratifies between integrated logistics providers bundling tank supply with regulatory documentation, and fragmented depot operators lacking multi-standard compliance. Three archetypes dominate: captive network specialists controlling cleaning and heating infrastructure, pharmaceutical-grade certification holders capturing biologics cold chain premiums, and cryogenic equipment fabricators serving LNG trade expansion. Capacity expansion and strategic partnerships represent the dominant competitive moves, with operators retrofitting depots for cryogenic handling or forming rail-sea intermodal alliances.
Among European-based specialists, Transtainer exemplifies the captive network archetype through food-grade ISO tank leasing with controlled depot infrastructure. Multitank occupies a position within Asia-Pacific chemical transport, representing purpose-built hazardous cargo fleet deployment. BLT Tank Container anchors the pharmaceutical-grade tier, exemplifying temperature-controlled unit specialization with multi-compartment stainless engineering requirements.
| Leading Market Players |
|---|
| Transtainer |
| Multitank |
| ISO Tank Joint Venture (ITJV) |
| BLT Tank Container |
| Exel Tank Container |
| United Tank Containers (UTC) |
| Denak |
| Rotank |
| Tritank |
| Others |
Value Chain & Pricing Dynamics
Long-term dedicated fleet contracts lock in both supply access and price visibility for specialty chemical producers across Asia-Pacific manufacturing corridors. These multi-year agreements with integrated logistics providers shield shippers from stainless steel input volatility while securing depot network priority.
Pricing Analysis
Next-generation cryogenic-grade tank specifications command substantial premiums over standard ISO frames and aging atmospheric vessels. Three-tier pricing structure across GMP-certified pharmaceutical, food-grade, and standard chemical tiers reflects certification investment and cleaning protocol complexity. Cost compression in standard chemical transport is intensifying because Chinese domestic manufacturers are scaling captive leasing pools. Small and mid-sized specialty chemical producers in Japan and South Korea exhibit the highest price sensitivity, while pharmaceutical shippers under CDSCO and EMA validation requirements show minimal elasticity.
Supply Chain Analysis
Strategic stockpiling of Grade 316L stainless steel plate dominates fabricator procurement as nickel and molybdenum commodity cycles drive input cost volatility. Manufacturing concentration centers on China, Germany, and South Korea for pressure vessel fabrication. Raw material dependencies draw from Indonesian nickel ore, Chilean molybdenum concentrates, and European specialty steel finishing. Single-source vulnerability around ASME Section IX qualified welders constrains fleet expansion timelines. Distribution runs through Rotterdam, Houston, and Singapore depot clusters for food-grade and pharmaceutical cleaning infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. Certification breadth and multi-standard compliance create switching costs that fragment smaller operators and concentrate purchasing power.
For Market Incumbents: Compound network density through cryogenic depot retrofit investments in Belgium and northern France ahead of EU F-Gas Regulation quota reductions. Extend certification moats by integrating GMP-validated cleaning protocols with real-time telemetry systems. The threat of asset-light digital platforms displacing traditional ownership models demands preemptive bundling of tank supply with regulatory documentation services. For New Entrants and Emerging Players: Anchor in India's pharmaceutical cold chain where CDSCO temperature-validation requirements for biologics transport outpace domestic fleet capacity. Target Maharashtra and Telangana insulin and vaccine production clusters with active cooling system tank containers. The most penetrable entry angle pairs pharmaceutical-grade certification investment with multi-compartment stainless engineering capabilities. For Investors and Strategic Acquirers: Captive depot network specialists controlling Rotterdam and Houston food-grade cleaning infrastructure represent the priority acquisition archetype. Long-term viability hinges on regulatory compliance breadth rather than fleet scale alone. Watch for MIIT dual carbon goal acceleration in China as an inflection indicator for intermodal logistics consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Depot Retrofit | Antwerp-Rotterdam networks capture EU F-Gas Regulation-driven replacement cycles. |
| GMP Certification Investment | Pharmaceutical shippers in Germany and the Netherlands mandate real-time telemetry. |
| Rail-Sea Intermodal Alliance | Gauge-compatible designs compress transit from Chinese interior to coastal ports. |
| Backward Integration into Steel Sourcing | Fabricators hedge Grade 316L plate volatility through captive nickel supply arrangements. |
| Blockchain Custody Documentation | Multi-modal liability fragmentation demands digitized bills of lading across rail-sea-road chains. |
Study Parameters
Desk research of customs trade data, IMO regulatory filings, and stainless steel commodity reports preceded structured interviews with tank fleet operations managers, chemical procurement leads at Asia-Pacific manufacturing clusters, depot network operators, and ASME-certified fabrication engineers. Primary fieldwork validated secondary indicators around certification timeline pressures and depot capacity utilization. Bottom-up fleet deployment estimates triangulated against top-down chemical trade volume projections.
Variance decomposition across container type, transportation mode, end-use certification, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segmented fleet expansion rates and replacement cycle frequencies. Industry-specific inputs incorporated UN portable tank regulation amendment timelines and REACH recertification burden trajectories.
Material uncertainties — nickel price volatility, welder certification pipeline delays, carbon-border mechanism implementations — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory enforcement continuity and intermodal infrastructure investment pacing. Revision becomes warranted when stainless steel input cost swings exceed historical lag-adjusted lease rate pass-through thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Nordics Freight and Logistics Market
Logistics and Shipping
United Kingdom Contract Logistics Market
Logistics and Shipping
Ocean Freight Software Market
Logistics and Shipping
South Africa Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Texas Freight and Logistics Market
Logistics and Shipping
Global Logistics Market
Logistics and Shipping
Digital Freight Forwarder Market
Logistics and Shipping
Poland Cold Chain Logistics Market
Logistics and Shipping
Freight Forwarding Market
Logistics and Shipping
Peru Freight and Logistics Market
Logistics and Shipping
United States Chartered Air Freight Transport Market
Logistics and Shipping
Logistics Automation Market
Logistics and Shipping
Global Drone Logistics and Transportation Market
Logistics and Shipping
GCC Trailer Market
Logistics and Shipping
Asia-Pacific FMCG Logistics Market
Logistics and Shipping
Hong Kong Freight and Logistics Market