
 Boat Control Lever Market | 2026-2036
Boat Control Lever Market Size, Share, and Industry Trends Forecast 2026-2036
Boat Control Lever Market Outlook
The capital-intensity divergence between integrated marine propulsion suppliers and standalone control component vendors is rotating competitive investment toward electronic joystick architectures. Mercury Marine leverages its captive outboard ecosystem to sustain pricing power across console-mount installations. ZF Friedrichshafen AG anchors its position through backward integration into hydraulic actuation systems. Uflex competes aggressively on cost in the plastic-composite mechanical lever tier.
A boat control lever translates operator input into throttle, shift, or steering commands through mechanical linkage, electronic signal transmission, or hydraulic pressure modulation, typically rated for saltwater corrosion resistance and vibration tolerance per marine industry standards. The device serves as the primary human-machine interface governing vessel propulsion and directional control. Electronic levers and joystick controls command expanding margin pools as recreational boaters and commercial operators replace cable-actuated systems. Aluminum and stainless steel materials retain dominance in saltwater commercial use cases where fatigue resistance outweighs cost sensitivity.
The US Coast Guard, EPA, and ISO 25197 standards collectively shape product certification requirements, mandating electromagnetic compatibility and emergency-stop functionality for electronic controls in US-navigable waters. The EU Marine Equipment Directive and REACH substance restrictions impose parallel compliance burdens on European-sourced components. Stakeholders must monitor the pace of electronic lever standardization against persistent mechanical lever replacement demand in emerging boatbuilding clusters.
Market Dynamics
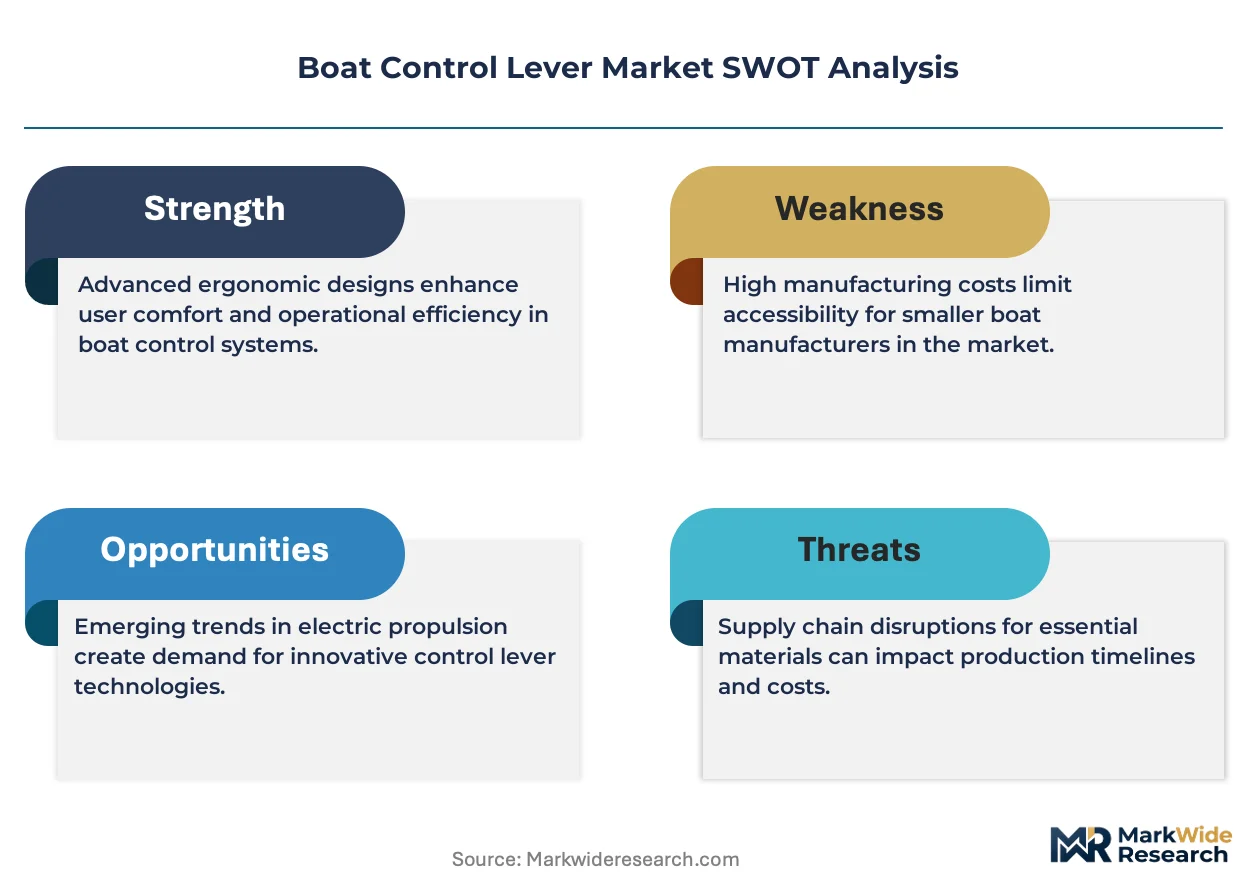
Electronic joystick architectures are compressing mechanical lever replacement cycles as recreational boaters demand integrated propulsion control. Mercury Marine's captive outboard ecosystem and ZF Friedrichshafen's hydraulic actuation integration illustrate how suppliers are capturing margin pools through system-level bundling.
Growth Catalysts
- EPA Marine Emission Standards:Tightened control system requirements under US environmental rules mandate precision throttle management, accelerating electronic lever penetration in outboard-powered vessels.
- Saltwater Corrosion Resistance Standards:ISO 25197 certification requirements for vibration tolerance and electromagnetic compatibility create replacement demand in commercial fishing fleets operating in Florida and California coastal waters.
- Composite Material Advances:Glass-reinforced polymer formulations are reducing mechanical lever weight while maintaining fatigue resistance, opening retrofit opportunities in aging fiberglass hull installations.
Market Restraints
- Hydraulic Actuator Supply Concentration:Precision servo valve production clusters in German and Japanese industrial centers, exposing OEMs to extended lead times during capacity constraints.
- Aluminum Alloy Price Volatility:Marine-grade 6061-T6 billet costs fluctuate with energy-intensive smelting economics, compressing margins for stainless-steel-dominated saltwater product lines.
- Mechanical Linkage Substitution Threat:Cable-actuated controls retain cost advantage in freshwater bass boat segments where electronic redundancy offers limited operational benefit.
Strategic Opportunities
- EU Marine Equipment Directive Alignment:REACH substance restrictions and electromagnetic compatibility mandates create certified supplier scarcity for European boatbuilders sourcing control systems.
- Joystick-Docking Convergence:Integration of dynamic positioning algorithms with lever hardware enables premium pricing in yacht charter operations requiring single-handed maneuverability.
- Direct-to-Builder Distribution:Bypassing traditional marine aftermarket channels through OEM pre-installation contracts captures specification influence earlier in hull construction workflows.
Industry Challenges
- Embedded Software Certification Timelines:US Coast Guard type-approval processes for electronic control firmware extend product launch schedules by 8-14 months versus mechanical equivalents.
- Legacy System Integration Complexity:Retrofitting electronic levers onto cable-actuated steering infrastructure requires custom mounting bracket engineering, fragmenting aftermarket service standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boat Control Lever Market |
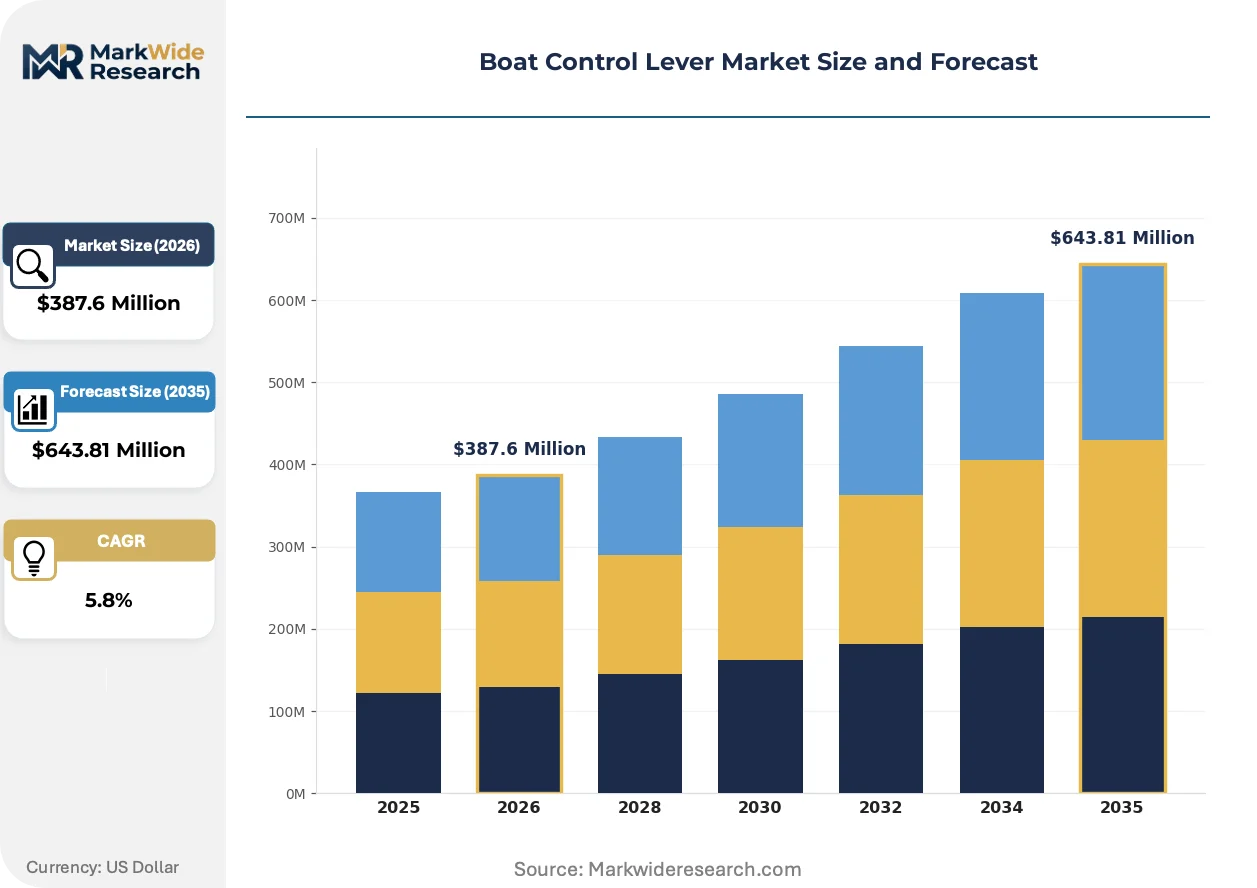
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Levers, Electronic Levers, Joystick Controls, Hydraulic Controls Material: Aluminum, Stainless Steel, Plastic, Composite Installation: Console Mount, Pedestal Mount, Flush Mount, Remote Mount Use Case: Recreational Boats, Commercial Vessels, Fishing Boats, Sailboats |
| Companies Covered | Rolls-Royce Marine, Vetus, Kongsberg Gruppen, Mercury Marine, ZF Friedrichshafen AG, Volvo Penta, Uflex, Kobelt Manufacturing, Teleflex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boat Control Lever Market Strategic Shifts
Control interface digitization is redefining operator ergonomics and propulsion system architecture. Three developments are compressing traditional hardware replacement cycles and reshaping supplier competitive positioning.
Fly-by-wire throttle modulation is displacing mechanical cable transmission in recreational outboard installations. Saltwater sportfishing operators in Florida and California are specifying integrated lever-and-display consoles. Mercury Marine's proprietary SmartCraft networking protocol is locking aftermarket service revenue through diagnostic software tethering.
ISO 25197 electromagnetic compatibility mandates are forcing firmware architecture redesigns for US-navigable waters. EPA marine emission enforcement is tightening throttle-position sensor calibration tolerances. Electronic control suppliers are pre-certifying platforms to accelerate Coast Guard type-approval timelines.
Builder-preferred specification contracts are consolidating procurement influence among top-20 recreational hull manufacturers. Traditional marine distributor networks are losing volume to direct OEM supply agreements. California and Florida production facilities are piloting vendor-managed inventory programs for high-volume lever SKUs.
Boat Control Lever Market Segmentation
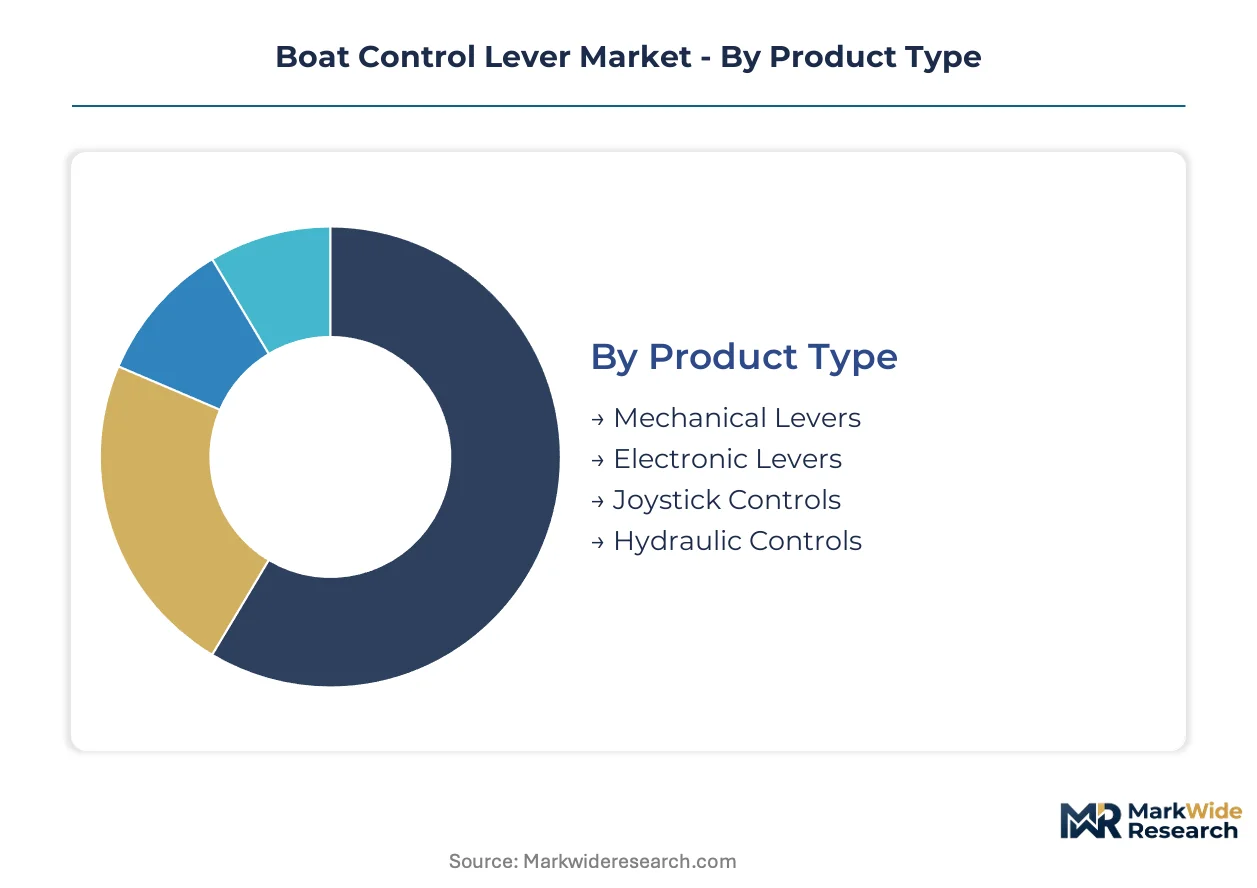
Boat control lever procurement channels diverge sharply by product complexity and end-use durability requirements. Electronic and joystick systems flow through OEM pre-installation contracts, while mechanical replacements dominate aftermarket marine distributors.
Product Type:
Channel mix splits between OEM specification capture for electronic architectures and distributor fulfillment for mechanical retrofits, with joystick controls consolidating through integrated propulsion bundling.
- Mechanical Levers:Cable-actuated linkages constructed from glass-reinforced polymer or aluminum billet transmit throttle and shift commands through physical displacement. Demand concentrates in freshwater bass boat segments across Florida inland waterways, where electronic redundancy offers limited operational benefit and cost sensitivity dominates procurement decisions.
- Electronic Levers:Fly-by-wire signal transmission architectures integrate throttle-position sensors with CAN bus networking protocols for precision modulation. Saltwater sportfishing operators in California coastal waters specify these for EPA marine emission compliance, as tightened control system requirements mandate exact throttle management in outboard-powered vessels.
- Joystick Controls:Multi-axis electronic interfaces enabling single-handed vessel maneuverability through dynamic positioning algorithms.
- Hydraulic Controls:Pressure-modulated actuation systems for commercial fishing fleet applications requiring high-force transmission.
Mechanical levers dominate installed base. Electronic levers are where expansion concentrates.
Material:
Cost tier stratification separates premium corrosion-resistant grades from economy polymer alternatives, with specification-grade alloys commanding OEM pre-installation placement.
- Aluminum:Marine-grade 6061-T6 billet delivers fatigue resistance and machinability for console-mount installations. California production facilities specify aluminum for high-volume recreational hull programs where weight reduction offsets material cost volatility from energy-intensive smelting economics.
- Stainless Steel:316L austenitic grades provide saltwater corrosion resistance for commercial fishing fleets operating in Florida coastal waters. ISO 25197 certification requirements for vibration tolerance drive replacement demand where fatigue resistance outweighs cost sensitivity.
- Plastic:Injection-molded ABS and polypropylene formulations for freshwater recreational price-sensitive segments.
- Composite:Glass-reinforced polymer matrices reducing mechanical lever weight while maintaining structural integrity.
Stainless steel dominates commercial saltwater specification. Composite formulations are climbing the fastest as retrofit demand accelerates.
Installation:
Application-specific mounting geometries determine aftermarket accessibility versus factory-integrated supply chains, with flush architectures requiring hull-design coordination.
- Console Mount:Surface-mounted assemblies attaching to helm station dashboards through standardized cutout patterns. Mercury Marine leverages its captive outboard ecosystem to sustain pricing power across console-mount installations, locking aftermarket service revenue through diagnostic software tethering.
- Pedestal Mount:Standalone vertical columns for center-console fishing vessels requiring elevated operator positioning.
- Flush Mount:Recessed integration with dashboard surfaces for yacht charter operations demanding clean aesthetic lines.
- Remote Mount:Detached control heads connected via cable extensions for multi-station vessel configurations.
Console mount dominates new-build specification. Flush mount is where premium pricing expansion concentrates.
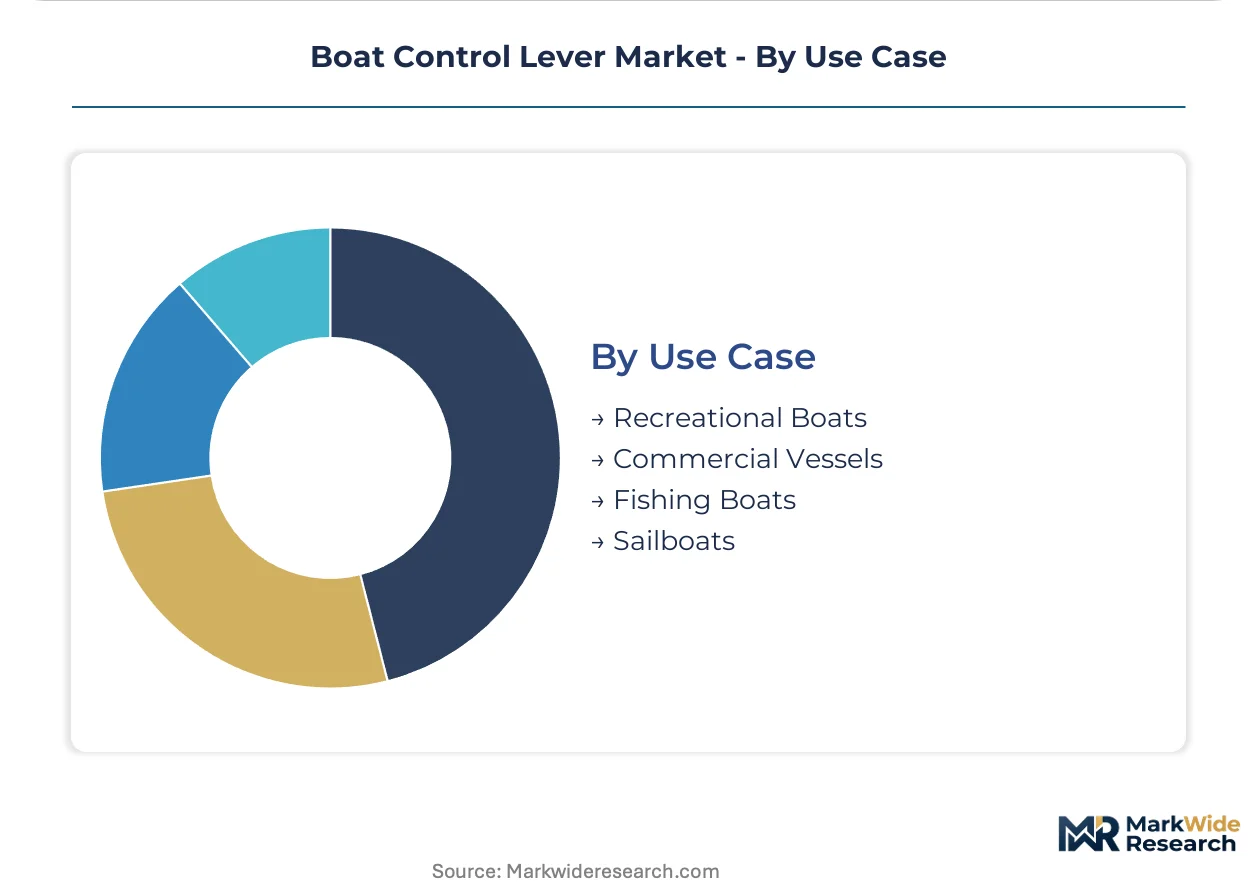
Use Case:
Customer type segmentation separates recreational price sensitivity from commercial durability mandates, with fishing applications bridging both procurement modes.
- Recreational Boats:Pleasure craft operators prioritizing ergonomic interface design and integrated display compatibility. Demand concentrates in Florida and California coastal states where electronic joystick architectures compress replacement cycles as boaters seek integrated propulsion control.
- Commercial Vessels:Workboat operators requiring redundant control paths and extended service intervals. US Coast Guard type-approval processes for electronic control firmware extend product launch schedules, favoring pre-certified mechanical alternatives in fleet procurement.
- Fishing Boats:Dual-purpose recreational-commercial segments spanning bass boats to offshore sportfishing platforms.
- Sailboats:Auxiliary power control for displacement hulls with intermittent engine operation requirements.
Recreational boats dominate unit volume. Commercial vessels are where specification-grade margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Buyers in mature recreational boating markets absorb premium electronic lever pricing, while emerging boatbuilding clusters prioritize mechanical alternatives for cost containment.
United States
Recreational outboard installations drive electronic lever specification in Florida and California coastal waters. EPA marine emission standards mandate precision throttle management, tightening control system requirements for saltwater sportfishing operators. Tampa Bay and San Diego production facilities pilot vendor-managed inventory programs for high-volume console-mount SKUs.
Germany
Precision servo valve production clusters anchor hydraulic actuator supply for commercial fishing fleets. REACH substance restrictions and EU Marine Equipment Directive compliance burdens shape component certification workflows. Hamburg and Bremen industrial centers concentrate backward integration into hydraulic actuation systems for North Sea workboat applications.
China
Boatbuilding capacity expansion in fiberglass hull manufacturing creates retrofit demand for glass-reinforced polymer mechanical levers. GB standards and MIIT marine equipment regulations impose parallel electromagnetic compatibility mandates for electronic control exports. Yangtze River Delta production facilities scale injection-molded ABS lever output for price-sensitive freshwater segments.
Japan
Commercial fishing fleet durability requirements sustain stainless steel specification for saltwater corrosion resistance. METI industrial standards and JIS certification protocols govern vibration tolerance testing for console-mount installations. Nagoya and Osaka industrial corridors concentrate high-force hydraulic control production for Pacific Rim workboat operators.
Italy
Yacht charter operations in Mediterranean ports demand flush-mount joystick integration for single-handed maneuverability. EU Green Deal marine decarbonization targets accelerate electronic lever penetration in auxiliary sailboat power systems. Lombardy and Liguria manufacturing clusters specialize in premium aesthetic console designs for superyacht specification.
Boat Control Lever Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics. Integrated marine propulsion suppliers command specification influence through system-level bundling, while standalone control component vendors compete on retrofit accessibility and aftermarket service reach. Three archetypes dominate: captive ecosystem players with proprietary networking protocols, hydraulic integration specialists with backward control over actuator supply, and cost-optimized fabricators in polymer mechanical tiers. Competitive moves concentrate on direct-to-builder distribution contracts and pre-certification investments to compress regulatory approval timelines.
Among integrated propulsion suppliers, Mercury Marine and ZF Friedrichshafen AG exemplify contrasting ecosystem strategies. Mercury Marine leverages its captive outboard ecosystem to sustain pricing power across console-mount installations, locking aftermarket service revenue through diagnostic software tethering. ZF Friedrichshafen AG anchors its position through backward integration into hydraulic actuation systems, capturing margin pools in commercial fleet specification. Uflex occupies a position within the cost-optimized tier, competing aggressively on price in plastic-composite mechanical lever segments where specification-grade certification offers limited differentiation.
| Leading Market Players |
|---|
| Rolls-Royce Marine |
| Vetus |
| Kongsberg Gruppen |
| Mercury Marine |
| ZF Friedrichshafen AG |
| Volvo Penta |
| Uflex |
| Kobelt Manufacturing |
| Teleflex |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty-day lead times for precision servo valves from German and Japanese production clusters concentrate pricing power among hydraulic integration specialists, while electronic lever assemblers absorb margin compression through vendor-managed inventory programs in Florida and California coastal facilities.
Pricing Analysis
Aftermarket diagnostic software subscriptions and extended service contracts drive lifetime value capture for integrated propulsion suppliers. Three-tier pricing structure across premium electronic joystick, standard fly-by-wire, and economy mechanical cable-actuated tiers separates specification-grade certification from volume scale. Pricing pressure stems from aluminum alloy 6061-T6 billet volatility tied to energy-intensive smelting economics. Freshwater bass boat operators exhibit highest price sensitivity, while saltwater commercial fleets prioritize fatigue resistance over cost.
Supply Chain Analysis
Inventory buffers for marine-grade stainless steel 316L and glass-reinforced polymer formulations stretch to ninety days in California and Florida production facilities. Precision servo valve manufacturing concentrates in Germany and Japan, while injection-molded polymer lever fabrication scales in China and Italy. Raw material dependencies center on aluminum billet, stainless steel austenitic grades, and engineered polymer resins. Single-source vulnerability in hydraulic actuator servo valve supply exposes OEMs to allocation risk during capacity constraints. Distribution runs through direct-to-builder contracts for electronic architectures and marine aftermarket distributors for mechanical retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic joystick penetration in recreational outboard installations signals early-cycle expansion, with EPA marine emission enforcement tightening throttle-position sensor calibration tolerances and accelerating fly-by-wire replacement of cable-actuated systems.
For Market Incumbents: Secure pre-installation specification contracts with top-20 recreational hull manufacturers before hull-design workflows finalize control interface geometry. Defend margin pools through backward integration into hydraulic actuation systems and captive diagnostic software tethering that locks aftermarket service revenue against standalone control component vendors. For New Entrants and Emerging Players: Aftermarket retrofit engineering for aging fiberglass hull installations with cable-actuated steering infrastructure represents the most penetrable white-space target. Target Florida and California coastal states where ISO 25197 certification requirements drive replacement demand in commercial fishing fleets. Pursue direct-to-builder distribution bypassing traditional marine distributor networks to capture specification influence earlier in procurement workflows. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electronic joystick architectures as firmware pre-certification investments and Coast Guard type-approval timelines extend product launch schedules. Five-to-ten year viability favors integrated propulsion suppliers with captive outboard ecosystems and proprietary CAN bus networking protocols. Monitor the pace of electronic lever standardization against persistent mechanical lever replacement demand in emerging boatbuilding clusters as the inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Pre-Certification Investment | Compresses US Coast Guard type-approval timelines by 8-14 months versus mechanical equivalents. |
| Backward Integration into Hydraulic Actuation | Captures margin pools in commercial fleet specification through captive servo valve supply. |
| Direct-to-Builder Distribution Contracts | Bypasses marine aftermarket channels to lock specification influence during hull-design workflows. |
| Vendor-Managed Inventory Programs | Reduces lead-time exposure for high-volume console-mount SKUs in Florida and California facilities. |
| Diagnostic Software Tethering | Locks aftermarket service revenue through proprietary SmartCraft networking protocol integration. |
Study Parameters
Initial hypotheses were tested against primary input from marine propulsion engineers, recreational boatbuilder procurement directors, commercial fishing fleet maintenance managers, and hydraulic actuator manufacturing specialists and refined through secondary validation against US Coast Guard type-approval databases, EPA marine emission enforcement records, ISO 25197 certification registries, and customs trade data for aluminum billet and stainless steel imports. Bottom-up triangulation of unit shipment estimates by product type and installation geometry was cross-checked against top-down market value reconstruction.
Variance decomposition across the projection horizon isolates volume, price, and mix effects within electronic lever, mechanical lever, joystick control, and hydraulic control segments, with additional stratification by material grade and use case intensity. CAGRs were derived from modeled replacement cycles and new-build penetration curves. Forecast inputs include recreational outboard installation rates in Florida and California, commercial fishing fleet durability requirements in saltwater corrosion environments, and EPA marine emission standard enforcement trajectories.
Underlying assumptions cover regulatory compliance timelines, raw material price stability, and electronic control firmware certification pacing, with deviation risk concentrated in aluminum alloy smelting economics and hydraulic actuator supply concentration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Engine Cooling Systems Market
Marine
Marine Interiors Market
Marine
Marine Base Steering Gear Market
Marine
North America Naval Vessels Market
Marine
Rescue Boats Market
Marine
Marine Diesel Engine Market
Marine
Marine VFD Market
Marine
Marine Gas Oil Market
Marine
GCC ROV Market
Marine
Marine Chartplotter Market
Marine
Japan Marine Composites Market
Marine
Sailboat Propellers Market
Marine
Swamp Boat Market
Marine
Jet Boat Market
Marine
Commercial Hovercraft Market
Marine
Marine Strip Market