
 Perishable Goods Transportation Market | 2026-2036
Perishable Goods Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
Perishable Goods Transportation Market Outlook
Refrigerated truck driver shortages across North America and Europe is bifurcating the market between asset-heavy operators and digital freight brokers. Kuehne + Nagel leverages its global warehouse footprint to sustain integrated sea-air-road perishable corridors. Lineage Logistics anchors North American cold storage density through automated high-bay facilities. DHL Supply Chain competes on pharmaceutical cold chain certification against food sector rivals.
Perishable goods transportation encompasses the temperature-controlled movement of products with finite shelf lives, requiring continuous maintenance between 0°C and 4°C for chilled goods and below -18°C for frozen categories through mechanical vapor-compression or cryogenic systems. The primary commercial purpose is preserving biochemical stability from harvest or production through final consumption, eliminating microbial proliferation and enzymatic degradation. Refrigerated trucks occupy the highest volume share in last-mile food distribution but face margin compression from fuel volatility and driver recruitment costs. IoT Sensors represent the fastest-expanding technology segment as real-time temperature logging becomes mandatory for pharmaceutical and premium produce clients. Air Freight retains premium pricing power in time-critical seafood and flower exports despite capacity constraints.
The US FDA Food Safety Modernization Act mandates preventive controls during transport, while the EU F-Gas Regulation accelerates adoption of CO2 and ammonia-based refrigeration units. India's FSSAI cold chain directives for dairy and meat are tightening licensing requirements for inter-state carriers. Stakeholders must monitor refrigerant transition timelines and digital traceability mandates as compliance costs reshape fleet investment decisions.
Market Dynamics
The EU F-Gas Regulation is forcing a wholesale refrigerant transition across European fleets, compressing margins for operators while accelerating adoption of CO2 and ammonia-based systems in temperature-controlled logistics.
Growth Catalysts
- Pharmaceutical Cold Chain Mandates:Temperature-sensitive biologics shipments are expanding as regulators tighten stability requirements for mRNA therapies and cell-based treatments across North America and Europe.
- India's FSSAI Directives:Inter-state dairy and meat licensing requirements are formalizing cold chain infrastructure investments by food service providers building captive networks to reduce post-harvest losses.
- IoT Sensor Proliferation:Real-time temperature logging devices are becoming mandatory for premium produce and pharmaceutical clients, creating compliance-driven hardware refresh cycles.
Market Restraints
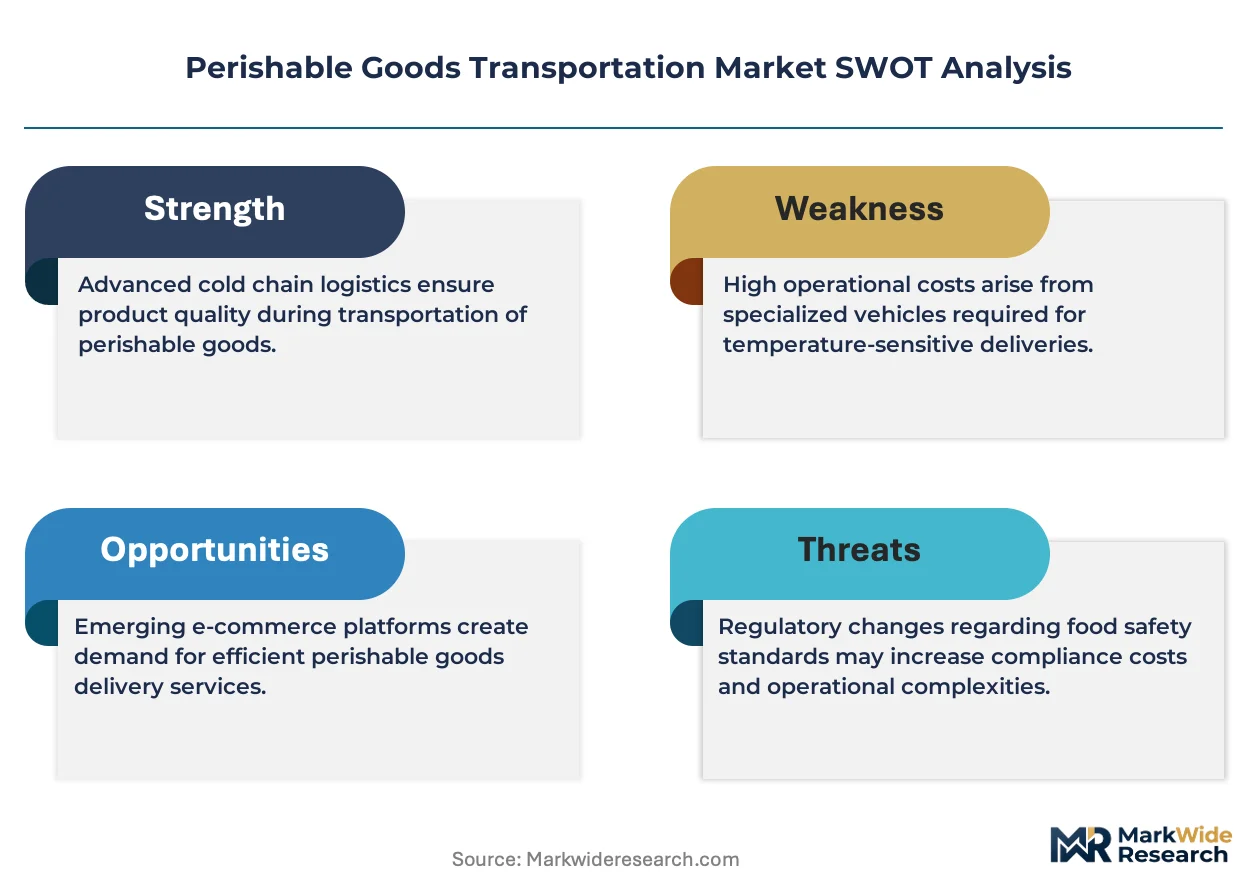
- Hydrofluorocarbon Phase-Down Costs:Fleet retrofit expenditures for EU operators are absorbing capital that would otherwise expand refrigerated vehicle capacity.
- Driver Recruitment Compression:Refrigerated truck operator shortages across Germany, France, and the United States are constraining asset utilization rates for chilled last-mile networks.
- Fuel Price Volatility:Diesel cost swings are eroding margins for refrigerated transport operators who cannot pass through energy costs in contracted pharmaceutical lanes.
Strategic Opportunities
- Automated High-Bay Cold Storage:Robotics-enabled warehouse density is opening capacity for perishable consolidation hubs serving e-commerce grocery fulfillment in suburban United States markets.
- Sea-Air-Road Corridors:Integrated multimodal temperature-controlled routing is capturing premium seafood and flower exports from Latin America to European retail chains.
- Biologics Distribution Expansion:Cell and gene therapy logistics requirements are creating certified cold chain service tiers that command pricing premiums over standard pharmaceutical transport.
Industry Challenges
- Refrigerant Technician Scarcity:CO2 and ammonia system maintenance expertise is concentrated among specialized contractors, creating service bottlenecks during fleet conversion timelines.
- Legacy Fleet Integration:Retrofitting existing refrigerated vehicles with compliant cooling units while maintaining temperature integrity during conversion downtime is straining operator technical teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Perishable Goods Transportation Market |
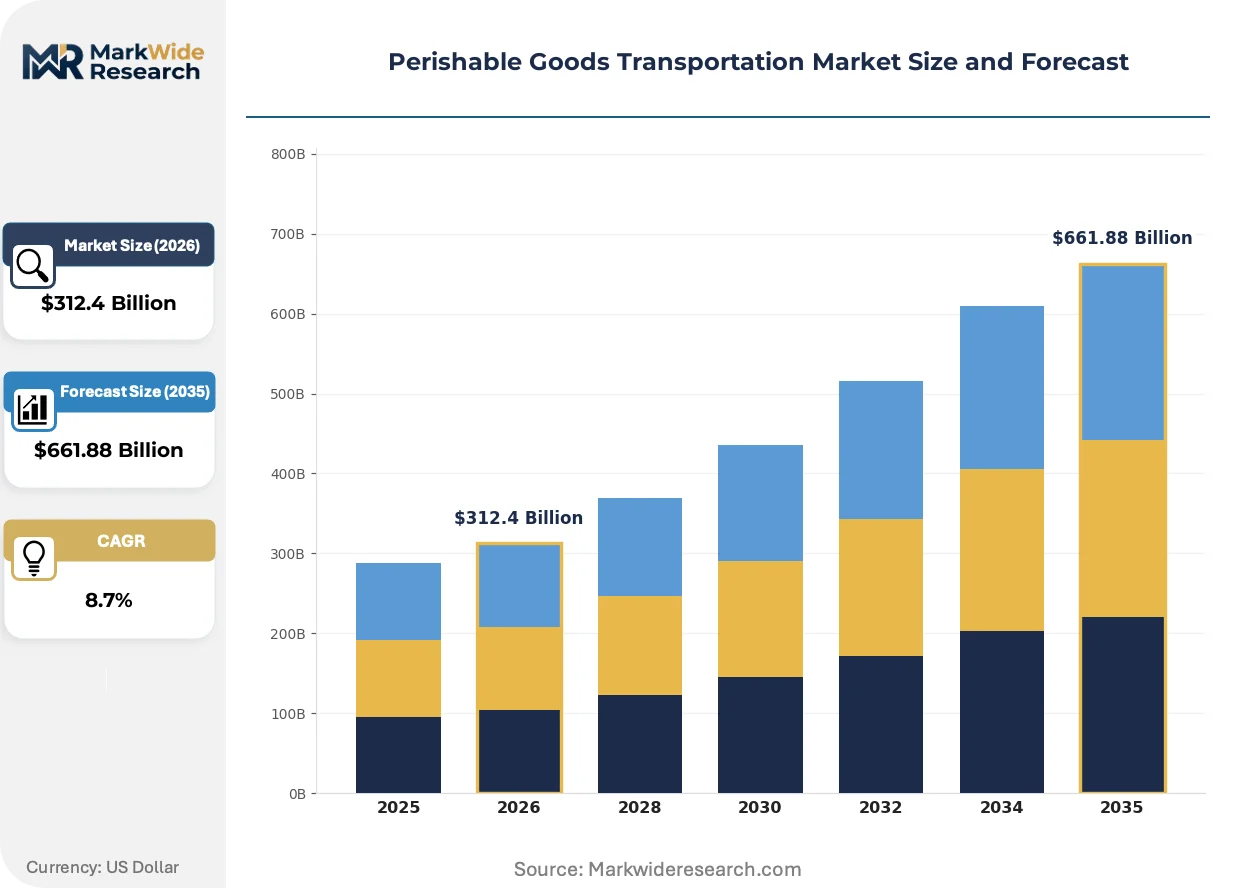
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $661.88 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transportation Method: Refrigerated Trucks, Air Freight, Shipping Containers, Rail Transport Product Type: Fruits, Vegetables, Dairy Products, Meat End User: Retailers, Wholesalers, Food Service Providers, Manufacturers Technology: GPS Tracking, IoT Sensors, Cold Chain Management, Automated Temperature Control |
| Companies Covered | Kuehne + Nagel, Lineage Logistics, DHL Supply Chain, J.B. Hunt Transport Services, Sysco Corporation, C.H. Robinson, Americold Logistics, FedEx, XPO Logistics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Perishable Goods Transportation Market Strategic Shifts
Digital freight platforms are fragmenting traditional asset-heavy operator dominance while real-time visibility technologies reconfigure buyer expectations for temperature documentation.
Electrified refrigeration units are bifurcating fleet procurement strategies across European and North American operators. Battery-electric and hydrogen fuel cell auxiliary power units are replacing diesel-powered transport refrigeration for urban delivery routes. Pharmaceutical distributors and premium produce wholesalers are adopting these systems fastest to meet municipal emissions restrictions. The technology is bifurcating the market between capital-intensive green fleet operators and digital freight brokers aggregating capacity from legacy diesel assets.
The EU F-Gas Regulation is accelerating refrigerant transition timelines with binding phase-down quotas for hydrofluorocarbon gases. Fleet operators must retrofit or replace cooling systems before mandated deadlines or face operating restrictions in member states. Cold storage and transport providers in Germany, France, and the Netherlands are consolidating retrofit purchasing to secure scarce CO2 compressor capacity.
Direct sourcing contracts between food service providers and cold chain operators are displacing traditional wholesale distribution layers in India. Quick-service restaurant chains and organized retail are building captive logistics networks with dedicated temperature-controlled vehicle pools. This pattern is most visible in Maharashtra and Karnataka where dairy and meat processing clusters support dedicated fleet economics.
Perishable Goods Transportation Market Segmentation
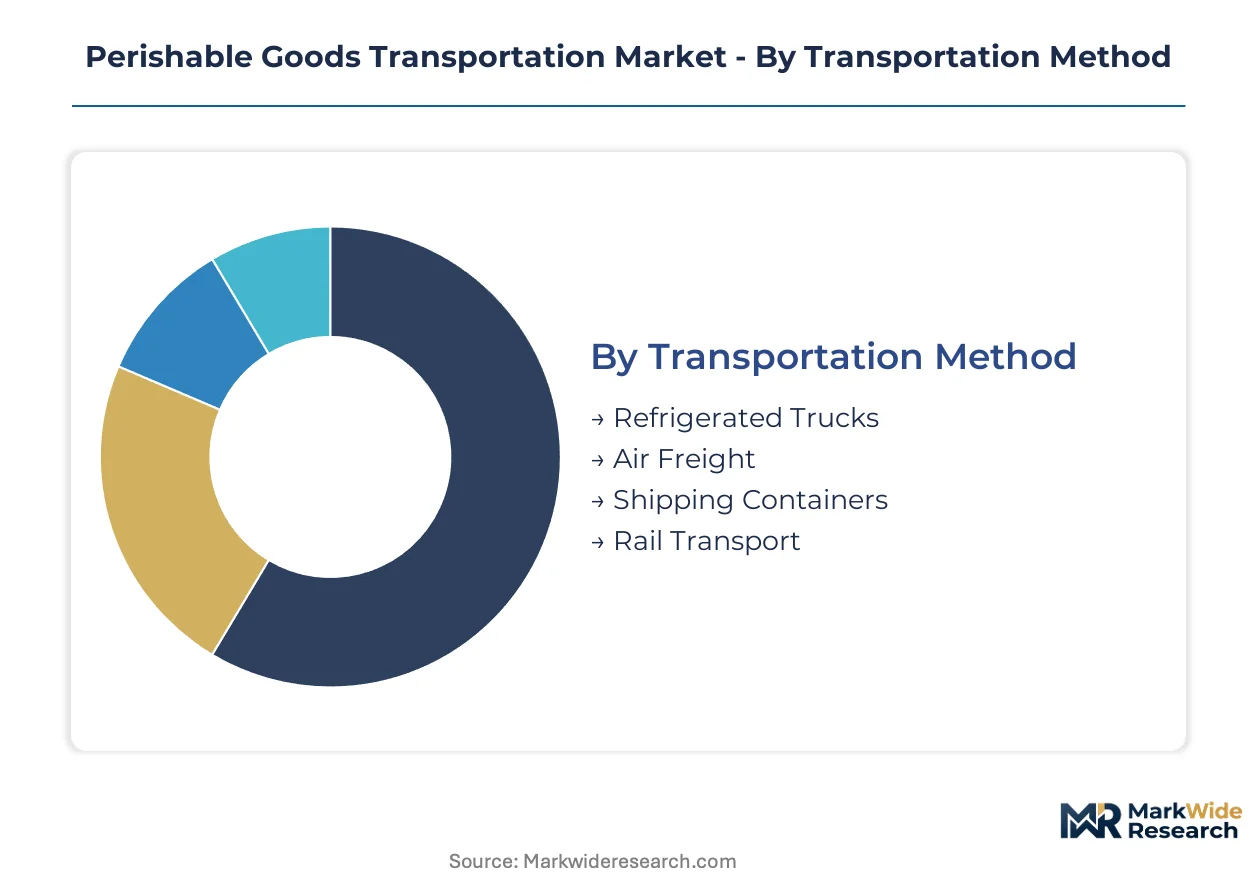
Segmentation in perishable goods transportation determines which infrastructure investments capture margin and which channels dominate volume flow. Channel-mix decisions hinge on product decay rates, regulatory documentation requirements, and last-mile density economics.
Transportation Method:
Refrigerated trucks dominate food retail distribution while air freight commands pharmaceutical corridors; shipping containers and rail serve bulk commodity flows with different cost-velocity tradeoffs.
- Refrigerated Trucks:Mechanical vapor-compression or cryogenic units maintain 0°C to 4°C for chilled loads and below -18°C for frozen categories across final-mile networks. Demand concentrates in suburban United States grocery fulfillment where e-commerce penetration is forcing smaller, more frequent drops. Driver recruitment shortages across Germany, France, and the United States constrain asset utilization rates.
- Air Freight:Temperature-controlled cargo holds and active container systems preserve biochemical stability for time-critical seafood, flower exports, and cell-based therapies. Demand concentrates in Latin America-to-European retail corridors for premium perishables where shelf-life compression justifies unit cost premiums. Capacity constraints at major cargo hubs limit volume expansion.
- Shipping Containers:Reefer units with integrated power systems handle intermodal bulk movements of frozen meat and processed dairy across ocean lanes.
- Rail Transport:Refrigerated boxcars and intermodal spine cars serve inland distribution of grain-fed proteins and temperature-stable produce from processing clusters.
By volume, refrigerated trucks lead. By growth pace, air freight is ahead.
Product Type:
Product decay chemistry dictates equipment specifications and channel selection, with high-respiration produce requiring different protocols than frozen proteins.
- Fruits:Ethylene-sensitive varieties demand precise temperature-humidity control and rapid transit to arrest ripening cascades. Mango and avocado exports from Maharashtra and Karnataka drive dedicated fleet investments by Indian food service providers building captive cold storage networks.
- Vegetables:Leafy greens and brassicas require continuous cold chain maintenance to prevent enzymatic degradation and moisture loss. Demand concentrates in quick-service restaurant supply chains where FDA Food Safety Modernization Act documentation requirements favor certified carriers.
- Dairy Products:Pasteurized fluid milk and cheese categories move through temperature-controlled distribution with FSSAI licensing mandates tightening inter-state carrier qualifications in India.
- Meat:Fresh and frozen protein categories face the most stringent pathogen control protocols across USDA-inspected facilities and EU hygiene regulations.
Meat commands the highest equipment investment per ton. Fruits are expanding most quickly in emerging market corridors.
End User:
Customer procurement patterns split between scale-driven consolidation and fragmentation, reshaping carrier contract structures and technology adoption timelines.
- Retailers:Organized grocery and big-box chains demand real-time visibility and temperature documentation through integrated cold chain management platforms. Walmart and Carrefour procurement specifications are accelerating IoT sensor mandates across their supplier bases.
- Wholesalers:Traditional distribution intermediaries face margin compression as direct sourcing contracts displace layered supply structures in India and Southeast Asia.
- Food Service Providers:Quick-service restaurant chains and institutional caterers build captive logistics networks with dedicated vehicle pools to secure supply continuity.
- Manufacturers:Dairy processors and meatpackers integrate backward into temperature-controlled distribution to protect brand integrity and reduce third-party handling.
Retailers drive technology standardization. Food service providers are gaining share fastest through vertical integration.
Technology:
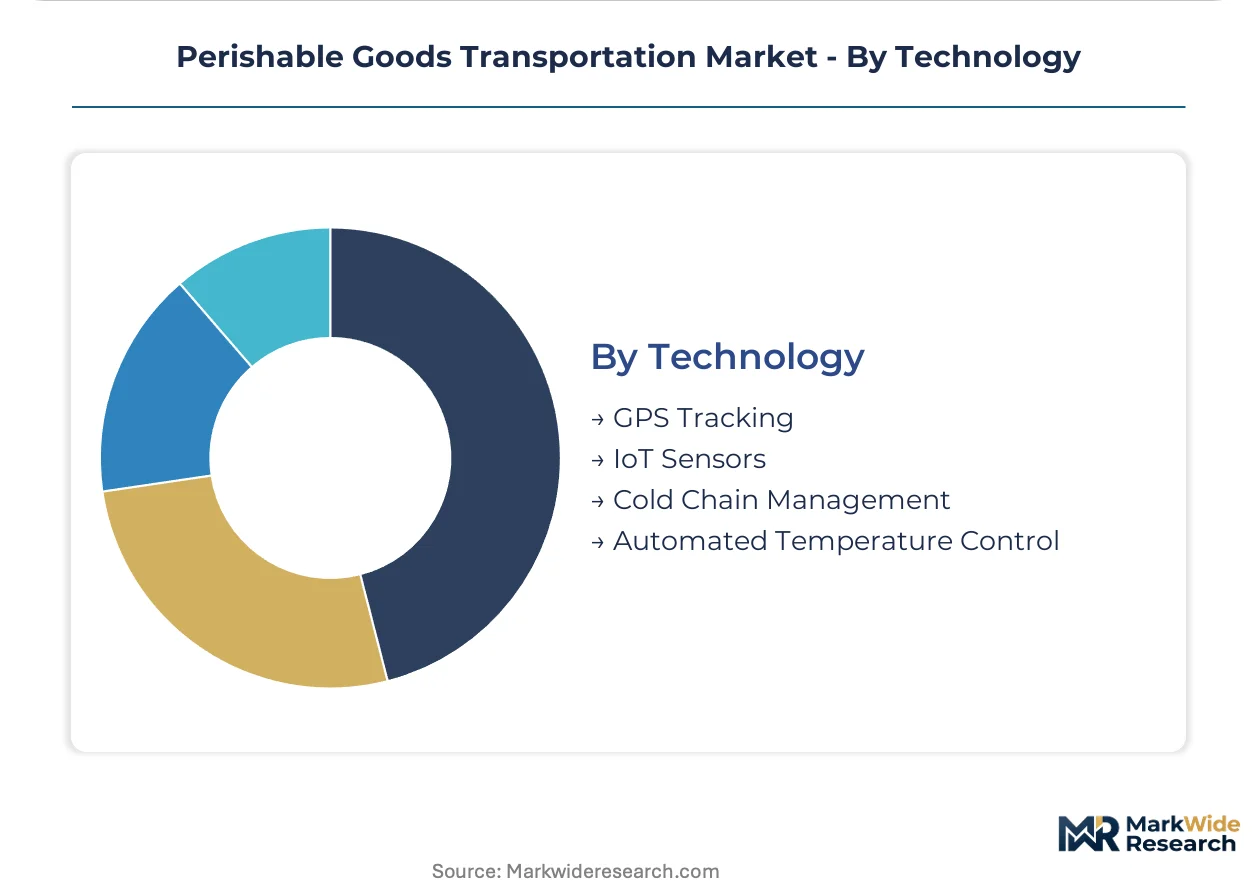
Technology deployment separates premium service tiers from commodity transport, with compliance mandates forcing hardware refresh cycles regardless of carrier size.
- GPS Tracking:Location-based fleet management systems enable route optimization and delivery confirmation for contracted pharmaceutical lanes. Carriers serving EU F-Gas Regulation retrofit timelines use GPS data to minimize vehicle downtime during depot conversions.
- IoT Sensors:Real-time temperature and humidity logging devices are becoming mandatory for premium produce and pharmaceutical clients. Battery-powered wireless transmitters eliminate wiring complexity in retrofitted refrigerated vehicles.
- Cold Chain Management:Integrated software platforms consolidate sensor data, documentation workflows, and regulatory reporting across multimodal shipments.
- Automated Temperature Control:Microprocessor-driven refrigeration units with predictive maintenance algorithms reduce spoilage incidents and service intervention frequency.
IoT sensors are climbing the fastest as compliance documentation requirements harden across North American and European pharmaceutical distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Food Safety Modernization Act mandates anchor North American compliance frameworks, while EU F-Gas Regulation retrofit timelines compress European fleet economics. India's FSSAI directives and China's cold chain infrastructure programs reshape capacity deployment across Asia-Pacific corridors.
United States
Pharmaceutical distributors shipping mRNA therapies drive temperature-controlled lane expansion. FDA preventive controls during transport mandate documentation systems that favor certified carriers. Chicago and Dallas-Fort Worth anchor automated high-bay cold storage density serving e-commerce grocery fulfillment networks.
Germany
EU F-Gas Regulation phase-down quotas force CO2 compressor adoption across refrigerated vehicle fleets. KBA vehicle certification requirements tighten for hydrofluorocarbon-dependent cooling systems. The Rhine-Ruhr corridor concentrates retrofit purchasing consortia among temperature-controlled logistics operators.
India
FSSAI inter-state dairy and meat licensing formalizes captive cold storage investments by food service providers. Post-harvest loss reduction targets accelerate dedicated fleet deployment. Maharashtra and Karnataka processing clusters support mango and avocado export corridors with integrated temperature-controlled vehicle pools.
China
NMPA biologics distribution standards tighten stability requirements for cell-based therapies. Dual carbon goals accelerate battery-electric refrigeration unit procurement for urban delivery routes. Yangtze River Delta pharmaceutical manufacturing clusters demand certified cold chain service tiers.
Netherlands
Rotterdam's intermodal hub position captures sea-air-road perishable routing for Latin American seafood and flower exports. EU F-Gas Regulation compliance deadlines consolidate retrofit purchasing among Dutch cold storage operators. Amsterdam-Schiphol cargo capacity constraints limit pharmaceutical air freight volume expansion.
Perishable Goods Transportation Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in perishable goods transportation. Asset-heavy operators with captive warehouse networks compete against digital freight brokers aggregating fragmented refrigerated truck capacity. Three archetypes dominate: global 3PLs with pharmaceutical certification, regional cold storage specialists with automated facilities, and technology-enabled freight platforms. M&A activity concentrates warehouse automation assets, while strategic partnerships secure scarce CO2 compressor capacity for fleet retrofits.
Within the integrated logistics tier, Kuehne + Nagel and DHL Supply Chain exemplify global operators leveraging multimodal temperature-controlled corridors. Lineage Logistics occupies a position among automated cold storage specialists anchoring North American density. These three represent distinct strategic postures: sea-air-road integration, pharmaceutical certification depth, and robotics-enabled warehouse scale.
| Leading Market Players |
|---|
| Kuehne + Nagel |
| Lineage Logistics |
| DHL Supply Chain |
| J.B. Hunt Transport Services |
| Sysco Corporation |
| C.H. Robinson |
| Americold Logistics |
| FedEx |
| XPO Logistics |
| Others |
Value Chain & Pricing Dynamics
CO2 compressor adoption replacing hydrofluorocarbon systems across EU fleets is redrawing supplier geography toward German and Dutch equipment manufacturers while compressing operator margins through accelerated retrofit timelines. This substitution dynamic concentrates purchasing power among consolidated retrofit consortia in the Rhine-Ruhr corridor and Rotterdam hub, amplifying price volatility for carriers locked into legacy diesel refrigeration assets.
Pricing Analysis
Long-term offtake contracts dominate pharmaceutical cold chain lanes where FDA preventive controls mandate certified carrier relationships, while spot-market pricing prevails in fragmented produce brokerage. Three-tier pricing structure across certified biologics, standard food-grade, and economy bulk frozen tiers separates premium service margins from commodity transport rates. Cost compression in economy frozen segments is intensifying because diesel fuel volatility erodes per-mile returns. Quick-service restaurant chains exhibit highest price sensitivity through captive fleet buildouts, while cell therapy distributors accept premium pricing for validated cold chain documentation.
Supply Chain Analysis
Inventory lead times for CO2 and ammonia compressor units have extended to 18-24 months as EU F-Gas Regulation deadlines concentrate demand among fleet operators. Supply concentrates in Germany, the Netherlands, and Denmark where refrigeration equipment manufacturers anchor production. Component dependencies include specialized aluminum heat exchangers, high-pressure piping systems, and microprocessor-driven control units. Single-source vulnerability runs through German compressor OEMs serving retrofit consortia. Distribution runs through integrated logistics operators with captive warehouse networks rather than fragmented owner-operator pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Perishable goods transportation represents a high-growth disruption as electrified refrigeration units and IoT sensor mandates reconfigure fleet economics and compliance requirements across North American and European corridors.
For Market Incumbents: Secure scarce CO2 compressor capacity through forward purchasing agreements with German and Dutch equipment suppliers before EU F-Gas Regulation deadlines tighten further. Anchor pharmaceutical certification depth against digital freight broker encroachment by investing in automated temperature control systems with predictive maintenance algorithms. Defensive consolidation around automated high-bay cold storage assets in suburban United States markets protects margin position from e-commerce grocery fulfillment demands. For New Entrants and Emerging Players: Anchor in India's Maharashtra and Karnataka processing corridors where FSSAI licensing formalization creates captive fleet opportunities for quick-service restaurant supply chains. Target underpenetrated biologics distribution tiers serving cell and gene therapy manufacturers demanding validated cold chain documentation. Deploy battery-electric auxiliary power units for urban last-mile routes as municipal emissions restrictions harden across European city centers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automated cold storage specialists consolidating North American warehouse density through robotics-enabled high-bay facilities. Five-to-ten-year viability hinges on refrigerant transition execution and pharmaceutical certification breadth rather than commodity transport scale. Monitor EU F-Gas Regulation retrofit completion rates as inflection indicator for equipment supplier pricing power and carrier margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Fleet Retrofit | EU F-Gas Regulation compliance deadlines force CO2 compressor adoption across German and Dutch operator consortia. |
| Pharmaceutical Certification Investment | FDA preventive controls documentation requirements favor carriers with validated cold chain management platforms. |
| Automated High-Bay Cold Storage Expansion | Robotics-enabled warehouse density captures e-commerce grocery fulfillment volume in suburban United States markets. |
| Electrified Refrigeration Procurement | Battery-electric auxiliary power units meet municipal emissions restrictions for urban pharmaceutical delivery routes. |
| Captive Fleet Buildout | Direct sourcing contracts displace wholesale layers as Indian food service providers integrate temperature-controlled vehicle pools. |
Study Parameters
Cross-validation between refrigerated fleet operator interviews and customs trade data anchors the qualitative findings on equipment procurement patterns. Primary discussions with cold chain logistics directors, pharmaceutical distribution managers, FSSAI licensing officers, and refrigerated vehicle procurement leads combined with secondary validation from EU refrigerant phase-down filings, FDA transport guidance documents, and automated warehouse capacity databases. Bottom-up carrier fleet surveys and top-down cold storage square footage estimates triangulate market sizing.
Sensitivity analysis around diesel price trajectories and CO2 compressor availability constraints frames the forecast uncertainty. Segmentation dimensions modeled include transportation method, product decay chemistry, end-user procurement scale, and refrigerant technology type across the projection horizon. CAGRs derive from equipment replacement cycles, regulatory deadline impacts, and pharmaceutical shipment growth curves. Forecast inputs incorporate EU F-Gas Regulation phase-down quotas and India's post-harvest loss reduction targets.
Decision-makers should treat outputs as directional under stable refrigerant transition timelines and pharmaceutical cold chain mandate continuity; material deviation in fleet retrofit completion rates or biologics distribution growth would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
North America Long-Haul Transport Market
Transportation & Logistics
Romania Road Freight Transport Market
Transportation & Logistics
Egypt Cold Chain Logistics Market
Transportation & Logistics
Rental and Subscription Product Logistics Orchestration Platforms Market
Transportation & Logistics
United States Retail 3PL Market
Transportation & Logistics
Refrigerated Road Transportation Market
Transportation & Logistics
United States Refrigerated Transport Market
Transportation & Logistics
Weigh in Motion Market
Transportation & Logistics
Argentina Road Freight Transport Market
Transportation & Logistics
Europe Road Feeder Services Market
Transportation & Logistics
Asia Pacific Road Freight Transport Market
Transportation & Logistics
North America Road Freight Transport Market
Transportation & Logistics
Global Fourth Party Logistics Market
Transportation & Logistics
Spain Cold Chain Logistics Market
Transportation & Logistics
Europe Road Freight Transport Market
Transportation & Logistics
Europe Refrigerated Transport Market