
 Global Boat Market | 2026-2036
Global Boat Market Size, Share, and Industry Trends Forecast 2026-2036
Global Boat Market Analysis
Project finance and lease-to-own structures are reshaping competitive entry in the Global Boat Market, lowering capital barriers for mid-tier operators and fleet managers. Brunswick Corporation leverages its vertical integration across engines and hull manufacturing to sustain margin control across price tiers. Groupe Beneteau anchors European production scale with diversified sailboat and motorboat portfolios. Yamaha Motor Co., Ltd. competes through outboard engine technology leadership and Asian distribution density.
A boat is a watercraft designed for navigation on oceans, lakes, or rivers, typically constructed from fiberglass-reinforced polymer, marine-grade aluminum, or laminated wood composites, with displacement, length, and draft specifications matched to intended operating conditions. The primary purpose spans commercial fishing, passenger transport, defense patrol, and leisure cruising across regulated waterways. Motorboats lead volume shipments globally due to versatility across recreational and commercial end users, while yachts command concentrated margin pools in the superyacht segment above 24 meters. Fiberglass dominates material selection for hull construction in recreational categories, though aluminum gains share in commercial and military applications where impact resistance and repairability matter.
The EPA enforces marine engine emissions standards under the Clean Air Act, compelling manufacturers to invest in catalytic aftertreatment and alternative fuels. The EU Green Deal and F-Gas Regulation constrain refrigerant and coating chemistries used in vessel construction and outfitting. The IMO coordinates international safety and pollution protocols that govern cross-border vessel certification and operating permits. Stakeholders must monitor regulatory divergence between North American and European compliance frameworks when configuring product platforms for multiple jurisdictions.
Market Dynamics
Hybrid-electric propulsion systems are forcing a fundamental reconfiguration of vessel powertrain architectures as EU Green Deal emissions targets and EPA Tier 4 standards compress the viable lifespan of conventional diesel marine engines.
Growth Catalysts
- EU Green Deal marine emissions mandates:Brussels' binding decarbonization timeline for recreational and commercial fleets is compelling shipyards to retool production lines for electrified drivetrains and alternative fuel compatibility.
- High-net-worth leisure demand:Charter operators and private owners across the Mediterranean and Caribbean are expanding superyacht order books, concentrating margin capture in the 24-meter-plus segment.
- Fiberglass hull manufacturing scale:Automated resin infusion and vacuum-assisted processes are reducing unit production costs for recreational motorboats, widening addressable demand among mid-tier consumers.
Market Restraints
- Marine-grade aluminum supply concentration:Primary smelting capacity for aerospace-specification alloys clusters in specific industrial corridors, exposing commercial and military hull fabricators to input volatility and extended lead times.
- Battery energy density limitations:Lithium-ion cell chemistry constraints restrict range and payload for pure-electric propulsion in commercial fishing and offshore patrol applications where operational endurance is non-negotiable.
- REACH coating compliance costs:ECHA restrictions on anti-fouling biocides and solvent-based marine paints are elevating material costs and application complexity for European shipyards.
Strategic Opportunities
- India's inland waterway modernization:The country's National Waterway network expansion is generating tender volume for shallow-draft passenger and cargo vessels with localized manufacturing requirements.
- Lease-to-own fleet structures:Asset-light financing models are emerging as a channel innovation, lowering capital barriers for commercial operators and marina-based rental fleets.
- Hydrogen fuel cell convergence:Integration of PEM fuel cell stacks with battery-electric architectures offers a pathway to zero-emission propulsion for larger displacement categories beyond battery-electric viability.
Industry Challenges
- Marine electrical systems certification:IEC 60092 and ABYC standards compliance for high-voltage installations requires specialized technician training that outpaces current vocational pipeline output.
- Legacy hull-to-powertrain integration:Retrofitting existing fiberglass and aluminum hull designs with hybrid-electric systems demands structural reinforcement and weight redistribution engineering that extends development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Boat Market |
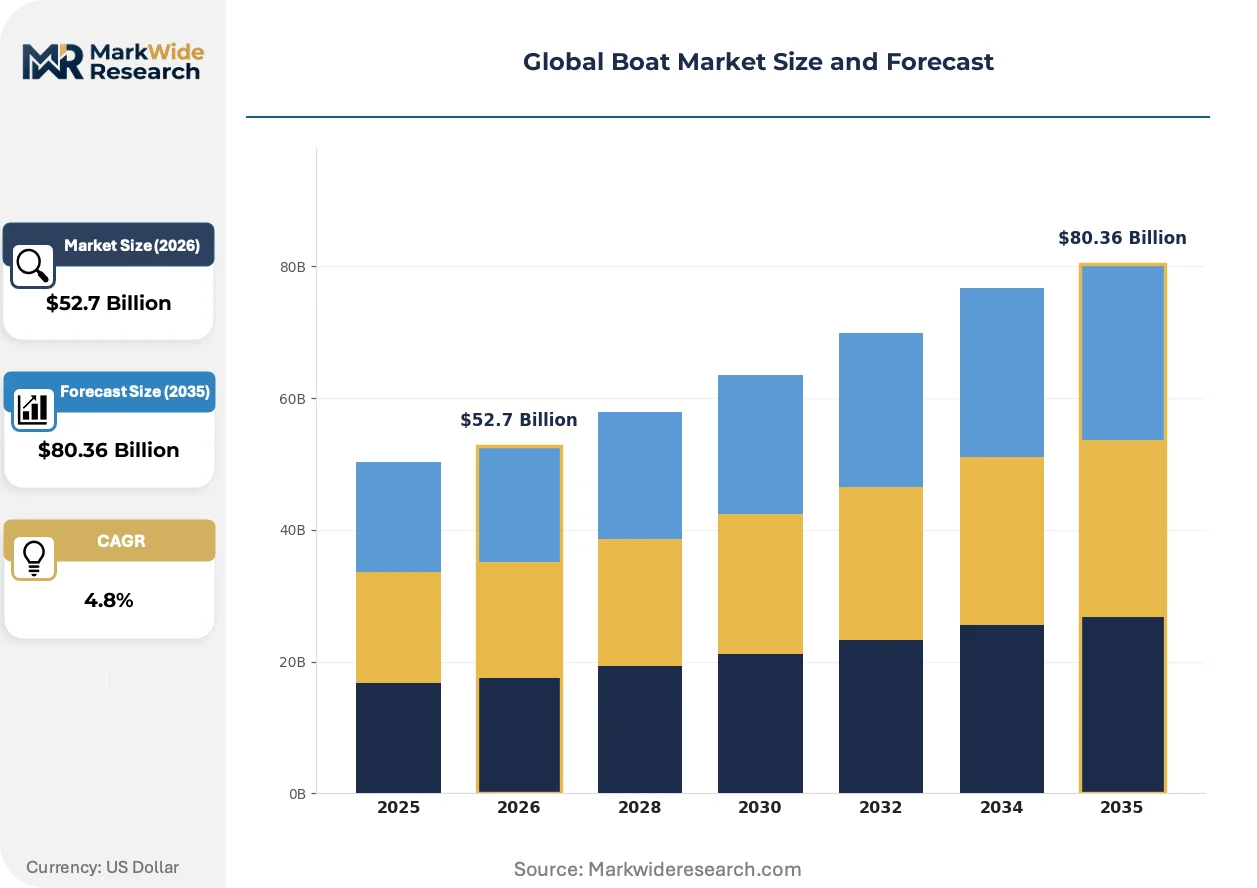
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $80.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sailboats, Yachts, Canoes, Motorboats End User: Recreational, Commercial, Government, Military Material: Fiberglass, Aluminum, Wood, Steel Distribution Channel: Online Sales, Retail Stores, Direct Sales, Brokers |
| Companies Covered | Brunswick Corporation, Groupe Beneteau, Yamaha Motor Co., Ltd., Azimut Benetti Group, Ferretti Group, Malibu Boats, Fincantieri, Sunseeker International, Polaris Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Boat Market Emerging Trajectories
Propulsion electrification, regulatory chemistry constraints, and asset-light ownership models are simultaneously reshaping vessel design priorities, material selection criteria, and customer financing structures across recreational and commercial segments.
Solid-state battery architectures with silicon-anode chemistries are rendering obsolete the range anxiety and thermal management compromises that have constrained lithium-ion adoption in planing hull applications. Superyacht builders in northern Italy are integrating these systems for silent hotel loads and short-range electric-only navigation. The technology is compressing the performance gap between conventional diesel and zero-emission alternatives in the 40-60 foot recreational category.
EPA Tier 4 and EU Stage V emissions standards for marine compression-ignition engines are compelling exhaust aftertreatment investments that add weight, cost, and maintenance complexity to conventional powertrains. Commercial fishing operators in the US Northeast are facing vessel replacement economics where retrofit compliance costs approach newbuild alternatives. The regulation is accelerating interest in hybrid architectures that downsize prime movers and optimize load profiles.
Fractional ownership platforms and peer-to-peer charter marketplaces are disrupting traditional dealer-network sales cycles for recreational motorboats. Mediterranean and Caribbean demand clusters are seeing vessel utilization rates become a primary purchase criterion rather than outright possession. The shift is most visible among urban high-net-worth buyers in Barcelona, Miami, and Singapore who prioritize access over asset ownership.
Global Boat Market Segmentation
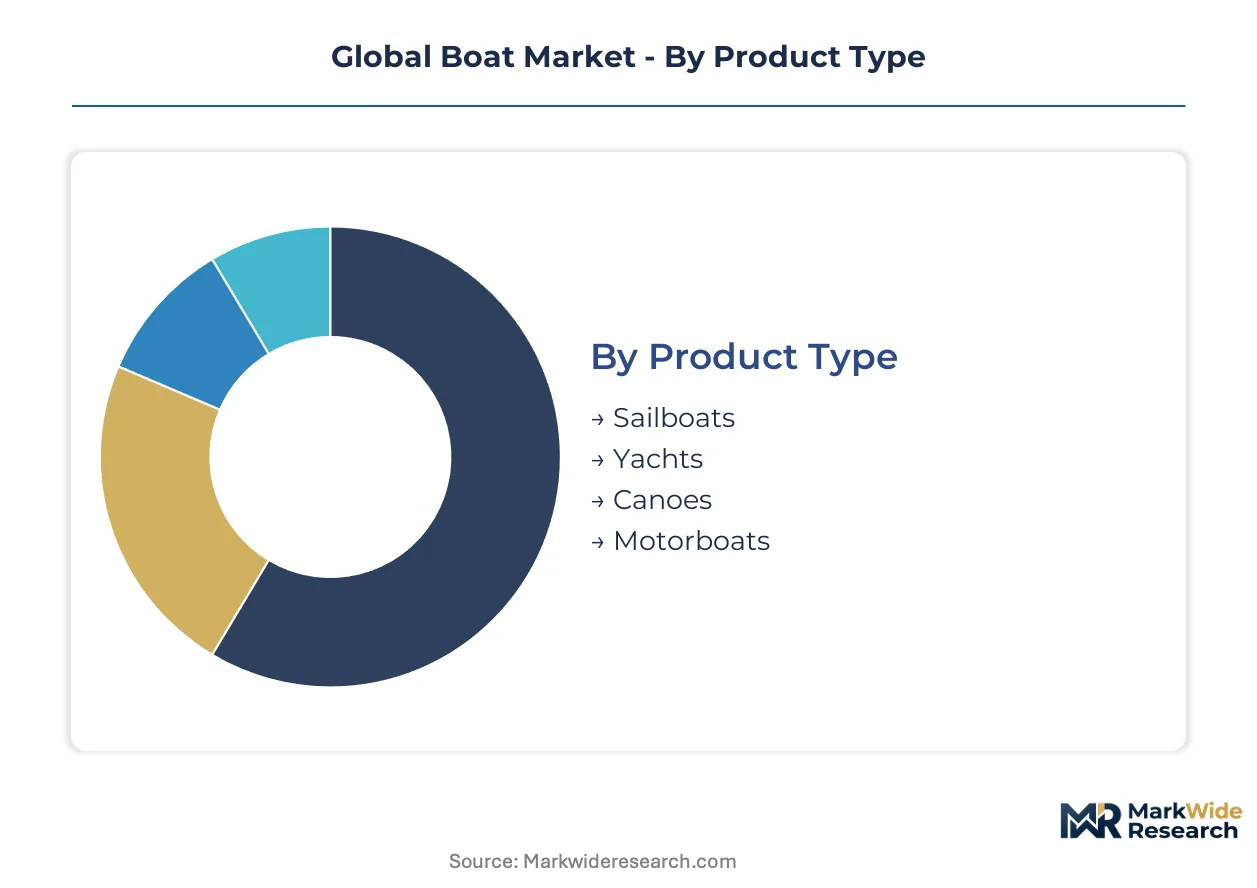
Segmentation in the Global Boat Market reveals distinct service intensity profiles across product categories. Hull material selection and propulsion system complexity determine aftermarket revenue potential and customer lifetime value for manufacturers and dealers.
Product Type:
After-sales service intensity varies dramatically across hull configurations, with motorboats demanding continuous engine maintenance and yachts requiring specialized crew training and refit cycles.
- Motorboats:These vessels incorporate inboard or outboard combustion engines, sterndrives, or emerging electric propulsion systems with displacement hulls or planing geometries. Demand concentrates among recreational families in the United States and charter operators in the Mediterranean, driven by versatility across fishing, watersports, and coastal cruising applications where operational flexibility outweighs fuel efficiency considerations.
- Yachts:Yachts span displacement motor yachts and sailing superyachts above 24 meters with complex integrated systems including stabilizers, desalination, and navigation suites. Orders cluster with high-net-worth individuals in Monaco, Fort Lauderdale, and Singapore, compelled by EU Green Deal emissions mandates that accelerate hybrid-electric refit demand in the 40-80 meter segment.
- Sailboats:Wind-powered vessels with mast, rigging, and keel configurations ranging from day sailors to ocean-going cruisers.
- Canoes:Paddle-driven small craft constructed from polyethylene, composite laminates, or inflatable materials for flatwater recreation.
Motorboats hold the largest share; momentum sits with yachts.
End User:
Procurement patterns diverge sharply between discretionary consumer spending and mission-critical fleet replacement cycles.
- Recreational:Private owners and fractional membership participants purchasing vessels for leisure cruising, fishing, and watersports across inland lakes and coastal waterways. Mediterranean and Caribbean marina infrastructure expansion supports this segment.
- Commercial:Fishing enterprises, passenger ferry operators, and offshore service providers requiring certified workboats with documented maintenance histories for regulatory compliance and insurance coverage.
- Government:National and provincial agencies procuring patrol craft, research vessels, and survey boats through tender processes with domestic content requirements.
- Military:Naval forces and coast guards acquiring rigid-hull inflatable boats, landing craft, and specialized interceptors with classified communications and weapons integration specifications.
Recreational users dominate volume; commercial operators are expanding most quickly.
Material:
Supply concentration for marine-grade inputs shapes regional manufacturing footprints and repair network density.
- Fiberglass:Glass-reinforced polymer composites dominate recreational hull production through resin infusion and hand-layup methods, favored for design flexibility and corrosion resistance in saltwater environments.
- Aluminum:Marine-grade 5083 and 5086 alloys deliver impact resistance and weldability for commercial fishing vessels, military craft, and ice-class expedition yachts where hull repairability in remote locations matters.
- Wood:Traditional cold-molded or strip-planked construction persists in custom sailing yacht and classic runabout restoration niches.
- Steel:Heavy-displacement hulls for icebreakers, commercial barges, and expedition vessels requiring structural integrity under extreme load conditions.
Fiberglass commands the greatest volume; aluminum is gaining share fastest.
Distribution Channel:
Customer acquisition economics shift as digital platforms displace legacy dealer relationships in certain price tiers.
- Retail Stores:Branded dealership networks with physical showrooms, sea trial facilities, and attached service departments anchor motorboat sales below 30 feet.
- Brokers:Commission-based intermediaries specializing in pre-owned yacht transactions, documentation, and survey coordination for vessels above 15 meters.
- Direct Sales:Manufacturer-owned channels for custom superyacht builds and military procurement with classified specification negotiations.
- Online Sales:Digital configurators and deposit-based reservation systems emerging for small craft and electric outboard packages.
Retail stores maintain the largest share; online sales show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal emissions mandates and national subsidy programs are redirecting fleet investment toward electrified propulsion systems across major boating economies. Italy, the United States, China, Germany, and Australia concentrate manufacturing capacity and premium demand clusters.
United States
Charter operators in Florida and private owners across the Great Lakes are expanding motorboat replacement cycles. The EPA enforces Tier 4 marine compression-ignition standards that accelerate hybrid-electric retrofits in commercial fishing fleets. Brunswick Corporation anchors production in Wisconsin and Tennessee with integrated engine-hull manufacturing.
Italy
Superyacht orders from Monaco-based buyers and Mediterranean charter fleets are concentrating margin capture in the 24-meter-plus segment. The EU Green Deal binding decarbonization timeline compels shipyards in Viareggio and La Spezia to retool for electrified drivetrains. Azimut Benetti Group and Ferretti Group exemplify the vertically integrated builder archetype dominating custom yacht fabrication.
China
Coastal tourism development in Hainan and municipal waterway transit expansion in the Yangtze Delta are generating tender volume for passenger vessels. MIIT domestic content requirements favor localized hull fabrication and electric propulsion system assembly. Shanghai and Zhoushan industrial corridors concentrate fiberglass resin infusion capacity for export-oriented motorboat production.
Germany
Inland waterway freight operators on the Rhine and Danube are modernizing fleets under EU Stage V emissions compliance deadlines. ECHA REACH restrictions on anti-fouling biocides elevate material costs for Baltic Sea yacht refit yards. Bavaria Yachtbau and HanseYachts anchor sailboat and motor yacht production in Giebelstadt and Greifswald with automated lamination processes.
Australia
Great Barrier Reef tourism operators and Western Australian offshore service providers are renewing commercial workboat fleets. The Australian Maritime Safety Authority enforces strict ballast water and biofouling protocols that favor aluminum hull repairability in remote locations. Queensland shipyards in Brisbane and the Gold Coast specialize in custom fishing vessel fabrication for Pacific export markets.
Global Boat Market Vendor Landscape
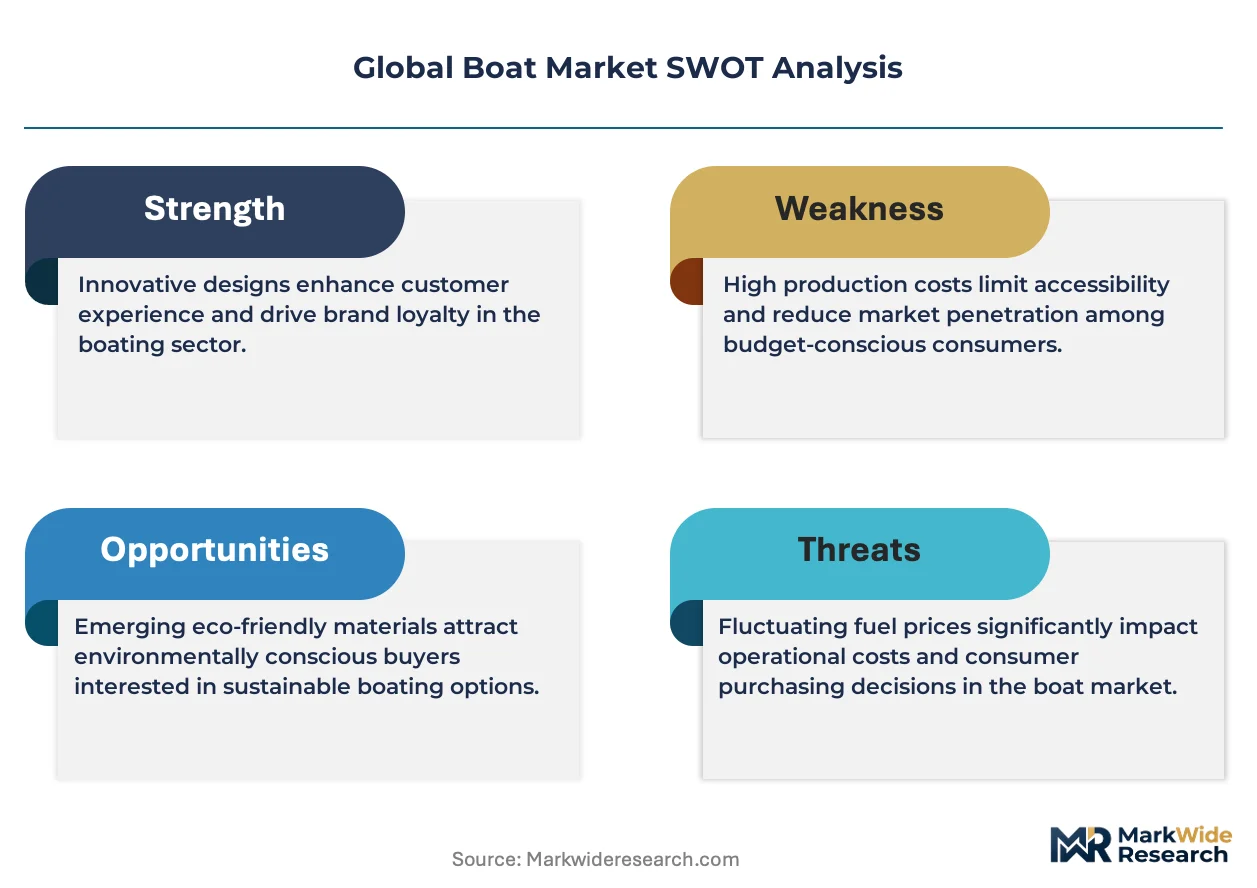
Channel-controlling players compete with product-specialist players across fragmented price tiers. The vendor base clusters around three strategic archetypes: vertically integrated engine-hull manufacturers, diversified sailboat-motorboat portfolio builders, and outboard engine technology specialists. Consolidation pressure concentrates in the superyacht segment above 24 meters while mid-tier motorboat production remains dispersed. Dominant competitive moves include backward integration into marine-grade aluminum supply and geographic expansion through lease-to-own fleet financing partnerships.
Within the vertically integrated tier, Brunswick Corporation and Groupe Beneteau exemplify channel-control strategies spanning engines, hull fabrication, and dealership networks. Yamaha Motor Co., Ltd. occupies a distinct position as an outboard engine technology anchor with Asian distribution density. These three companies represent the dominant competitive archetypes: captive supply chain control, diversified portfolio scale, and propulsion system specialization.
| Leading Market Players |
|---|
| Brunswick Corporation |
| Groupe Beneteau |
| Yamaha Motor Co., Ltd. |
| Azimut Benetti Group |
| Ferretti Group |
| Malibu Boats |
| Fincantieri |
| Sunseeker International |
| Polaris Inc. |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Antwerp barge freight corridors transmit resin and gelcoat cost volatility directly to Mediterranean yacht yards, compressing margins at the premium tier while fiberglass motorboat producers in the United States exploit inland waterway logistics to sustain three-tier pricing separation across certification grades.
Pricing Analysis
Certification level under EU Stage V and EPA Tier 4 standards creates the primary spread between premium superyacht builds and economy outboard packages. Pricing stratifies across CE-marked expedition yachts, standard recreational motorboats, and basic utility hulls without integrated navigation suites. Cost compression in the mid-tier fiberglass segment intensifies because automated resin infusion is flattening unit production differentials. Charter operators in the Caribbean exhibit the least price sensitivity, while inland lake recreational buyers in the United States drive hard volume negotiations on entry-level runabouts.
Supply Chain Analysis
Marine-grade aluminum feedstock draws from primary smelting corridors in Norway, Iceland, and the Persian Gulf, with 5083 and 5086 alloys feeding commercial hull fabricators in Italy and Australia. Fiberglass resin systems source from petrochemical complexes in Germany, China, and the United States, tethered to styrene and epoxy precursor markets. Single-source vulnerability concentrates in lithium-ion cell supply for electric propulsion retrofits, where Korean and Japanese producers dominate marine-certified formats. Distribution runs through branded dealership networks below 30 feet, while superyacht transactions rely on broker-mediated direct negotiations with Viareggio and Fort Lauderdale build yards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from hybrid-electric drivetrain maintenance and battery management systems is expanding faster than hull hardware sales, creating recurring income pools that offset cyclical newbuild demand.
For Market Incumbents: Harden captive supply positions in marine-grade aluminum and solid-state battery distribution before Korean and Chinese cell producers establish direct European service networks. Defend margin pools in the 24-meter-plus yacht segment through backward integration into custom stabilizer and desalination system fabrication, countering the threat of modular subsystem suppliers disintermediating traditional shipyard value chains. For New Entrants and Emerging Players: Pursue India's National Waterway tender volume for shallow-draft electric passenger vessels, where localized assembly requirements and MIIT content rules have kept established European builders at arm's length. Target lease-to-own fleet financing partnerships with Mediterranean charter operators as the most penetrable channel, leveraging asset-light structures to bypass capital-intensive dealership network buildouts. For Investors and Strategic Acquirers: EU Green Deal binding decarbonization deadlines for recreational and commercial fleets reshape the acquisition landscape toward shipyards with proven hybrid-electric integration capabilities and ABYC-certified high-voltage installation expertise. Long-term viability over the next decade hinges on exposure to refit and retrofit cycles rather than pure newbuild order books. Watch battery energy density breakthrough announcements from solid-state silicon-anode developers as the critical inflection signal for electric range viability in planing hull applications.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Drivetrain Integration | EU Stage V compliance in Viareggio yards depends on certified high-voltage marine electrical installations. |
| Marine-Grade Aluminum Backward Integration | Norwegian smelter partnerships secure 5083 alloy supply for Australian ice-class expedition yacht builders. |
| Lease-to-Own Fleet Financing Platform | Mediterranean charter operators in Monaco reduce capital barriers through asset-light vessel access structures. |
| Solid-State Battery Supply Agreement | Italian superyacht builders source silicon-anode cells for silent hotel load and short-range electric navigation. |
| India Waterway Manufacturing Joint Venture | Shallow-draft passenger vessel assembly in Kolkata meets MIIT domestic content requirements for tender eligibility. |
Methodological Framework
Desk research of customs trade databases, EPA and ECHA regulatory filings, and shipyard production disclosures preceded structured interviews with superyacht build yard operations directors, commercial fishing fleet procurement managers, marina charter operators, and marine electrical systems certification engineers. Primary fieldwork across Mediterranean and Caribbean demand clusters was cross-validated against secondary sources including IMO safety protocol amendments, EU Green Deal implementation timelines, and fiberglass resin import statistics. Bottom-up vessel shipment tallies by hull material and propulsion type were reconciled with top-down market value estimates derived from disclosed order book values at listed shipyard groups.
Assumptions held fixed across the modeling period include current EU and EPA emissions compliance deadlines, existing lithium-ion cell energy density ceilings, and prevailing marine-grade aluminum alloy pricing structures. Variables tested included hydrogen fuel cell cost convergence timelines, fractional ownership platform penetration rates, and India's inland waterway infrastructure deployment pace. Segmentation dimensions modeled encompassed hull material category, propulsion architecture, length displacement tier, end-use application, and regional regulatory cluster. CAGRs were derived from slope analysis of historical shipment volumes projected against tender pipeline visibility and disclosed superyacht order backlogs.
Macroeconomic conditions sit as an overlay; deviation in marine leisure discretionary spending, aluminum LME pricing, or battery raw material supply would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology cost curves. Cross-checking against Lloyd's Register vessel construction statistics and national maritime authority registration databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Global Luxury Boat Market
Marine Vehicles
Asean Boat Davits Market
Marine Vehicles
Small Boats Market
Marine Vehicles
Trawler Boat Market
Marine Vehicles
Fishing Boat Market
Marine Vehicles
Marine Outboard Engine Market
Marine Vehicles
Hydrogen-Powered Yacht Market
Marine Vehicles
Marine Steering Systems Market
Marine Vehicles
Marine Passenger Seat Market
Marine Vehicles
Boat Davits Market
Marine Vehicles
Tugboat Market
Marine Vehicles
Marine Methanol Engine Market
Marine Vehicles
Global Outboard Motors Market
Marine Vehicles
Marine Hybrid Propulsion Market
Marine Vehicles
Marine Trailers Market
Marine Vehicles
Marine Reciprocating Engine Market