
 Autonomous Ships Market | 2026-2036
Autonomous Ships Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Ships Market Analysis
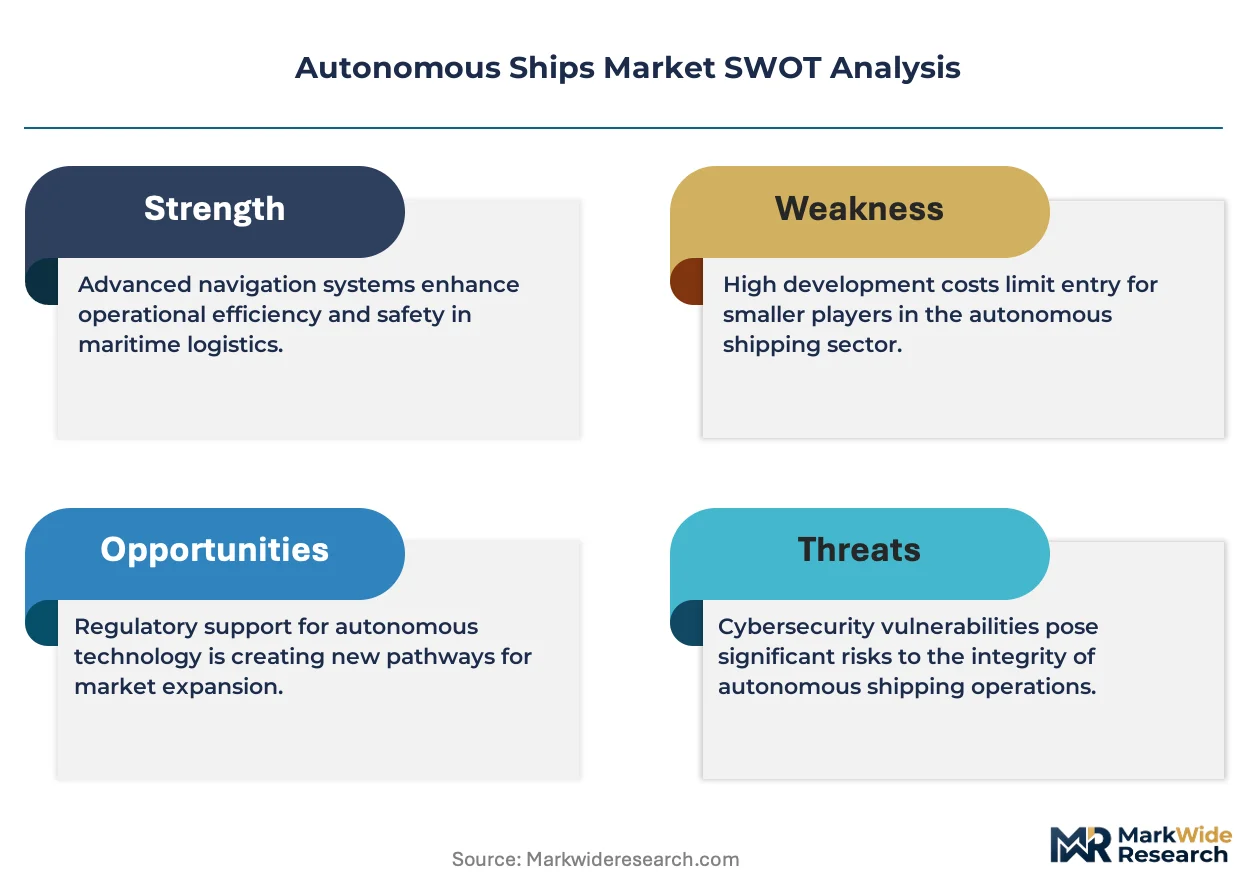
IMO-compliant safety certification is unwinding legacy vessel design standards across maritime automation. Kongsberg Maritime leverages its integrated bridge-to-propulsion ecosystem to dominate Norwegian fjord logistics corridors. Wärtsilä anchors Finnish-German port automation partnerships through its Smart Marine portfolio. ABB competes on electric propulsion integration with autonomous navigation stacks for coastal freighters.
Autonomous ships are self-navigating maritime vessels employing sensor fusion arrays, machine-vision cameras, and redundant communication links to execute voyages with minimal or zero crew intervention, primarily reducing operational expenditure and eliminating human-error casualties in commercial shipping. Sensor systems and navigation software capture the dominant share of technology spending as lidar-radar fusion architectures mature for all-weather berth-to-berth transit. Cargo transport leads use-case deployment where route predictability justifies capital-intensive autonomy retrofits on bulk carriers and container feeders.
The International Maritime Organization's Maritime Safety Committee, Lloyd's Register's Remote-Controlled Ship Code, and the EU's MRV Regulation collectively shape vessel certification pathways and emissions accountability for unmanned operations. Flag-state regulators in Norway, Singapore, and Japan issue limited trial permits that constrain fleet-scale rollout until liability frameworks solidify. Stakeholders must track which port authorities pioneer dedicated autonomous vessel traffic lanes before committing yard capacity to unmanned newbuilds.
Market Dynamics
The International Maritime Organization's Maritime Safety Committee is compressing certification timelines for remote-controlled navigation systems, forcing shipyards to redesign bridge architectures before liability frameworks mature.
Growth Catalysts
- EU MRV Regulation:Emissions accountability mandates for unmanned operations accelerate retrofit demand on coastal bulk carriers operating in the Baltic and North Sea corridors.
- Sensor fusion architectures:Lidar-radar integration for all-weather berth-to-berth transit is reducing crew complements on Norwegian fjord logistics routes.
- Japan's coastal shipping lanes:Crew-reduced cargo transport trials concentrate early deployment demand for autonomous container feeders.
Market Restraints
- Flag-state permit fragmentation:Norway, Singapore, and Japan issue limited trial licenses that constrain fleet-scale rollout until unified liability standards emerge.
- Retrofit capex concentration:Bulk carrier automation packages require yard capacity commitments that few operators can finance without charterer guarantees.
- Redundant communication link costs:Satellite and shore-based control infrastructure doubles connectivity expenditure versus conventional vessel operations.
Strategic Opportunities
- Finnish-German port automation partnerships:Smart Marine ecosystem integration creates white space for electric propulsion-autonomy bundled offerings in Hamburg and Rotterdam terminals.
- Berth-to-berth software stacks:Machine-vision camera arrays and AI collision-avoidance algorithms converge to enable fully unmanned feeder services on fixed routes.
- IMO remote-controlled ship code finalization:Anticipated certification clarity will unlock institutional capital for autonomous newbuilds currently stalled in pre-contract negotiations.
Industry Challenges
- Marine autonomy engineer scarcity:Bridge system integrators and shore-based vessel operators compete for talent pools that maritime academies have not yet trained.
- Legacy vessel integration complexity:Retrofitting 1990s-era bulk carriers with redundant sensor arrays and satellite command links extends yard stays by 40-60 days.
- Classification society certification timelines:Lloyd's Register and DNV review queues for remote-controlled ship notation currently exceed 18 months for novel designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Ships Market |
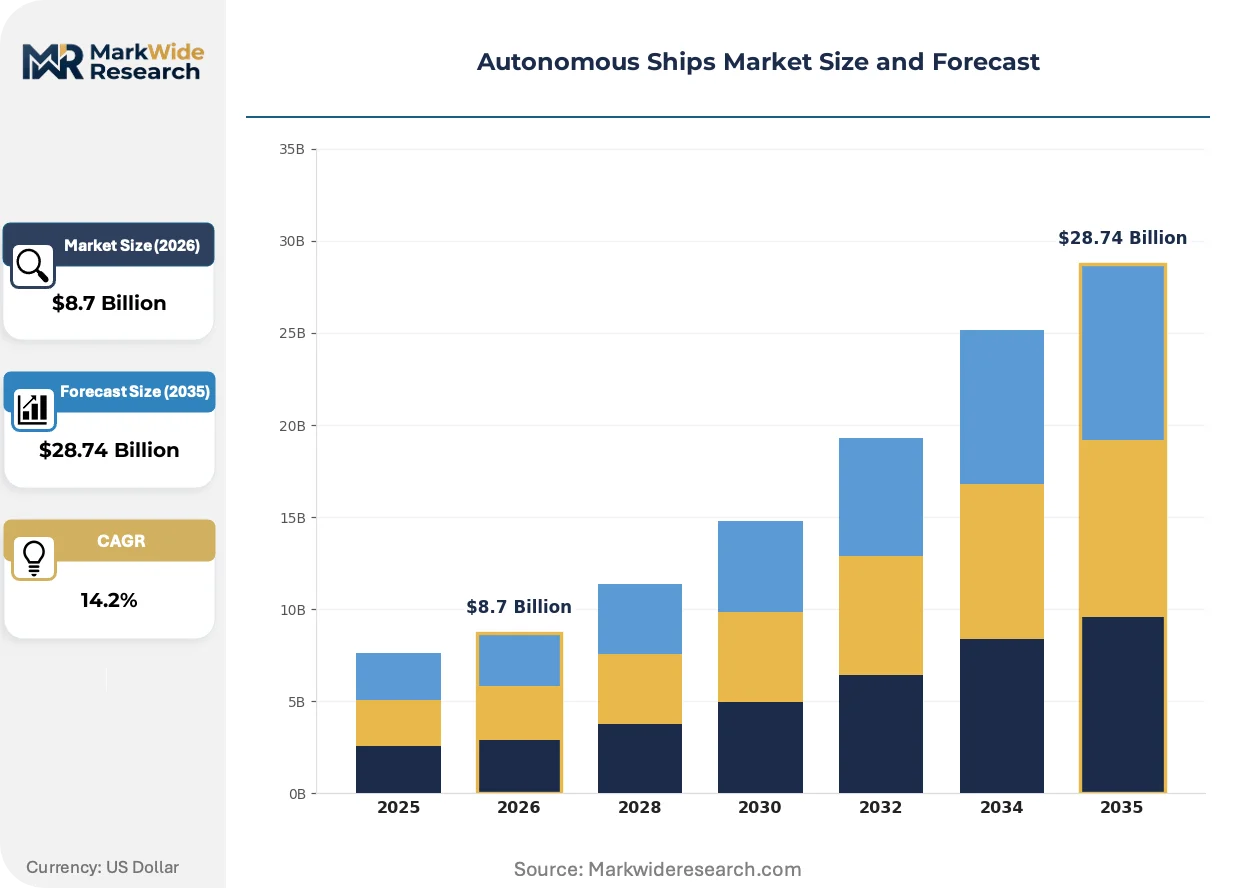
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: AI, Sensor Systems, Navigation Software, Communication Systems Use Case: Cargo Transport, Passenger Transport, Oil & Gas Shipping, Research Vessels Service Type: Maintenance, Monitoring, Fleet Management, Navigation Assistance Component: Control Systems, Propulsion Units, Hull Structures, Energy Management Systems |
| Companies Covered | ABB, Kongsberg Maritime, Rolls-Royce plc, BAE Systems, Honeywell International Inc., L3Harris Technologies, Wärtsilä, HD Hyundai Heavy Industries, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Ships Market Emerging Trajectories
Autonomous navigation technology is compressing traditional crew hierarchies while regulatory fragmentation across flag states creates uneven deployment terrain for first-movers.
Lidar-radar fusion architectures for maritime navigation is fragmenting legacy single-sensor bridge systems into modular, multi-redundant arrays. Norwegian coastal freight operators are adopting these configurations fastest, driven by fjord route predictability and narrow-channel precision requirements. The technology is fragmenting competitive advantage away from engine manufacturers toward sensor-software integrators who control berth-to-berth decision stacks.
The EU's proposed AI Act liability provisions for autonomous transport systems are forcing shipyards to document algorithmic decision trails for collision-avoidance scenarios. Classification societies must now verify machine-learning model training datasets alongside traditional hull and machinery inspections. Container feeder operators in Northern Europe are front-loading compliance costs to secure early-mover certification advantages before the regulation hardens.
Charterers are unbundling crew cost risk from freight rate negotiations, demanding autonomous-ready vessel specifications in five-year fixture contracts. Traditional shipowners who cannot demonstrate remote-control capability face exclusion from premium cargo pools. Japanese trading houses and Northern European pulp-and-paper shippers are driving this specification shift hardest, rewriting standard charterparty clauses to penalize manned-vessel operational premiums.
Autonomous Ships Market Segmentation
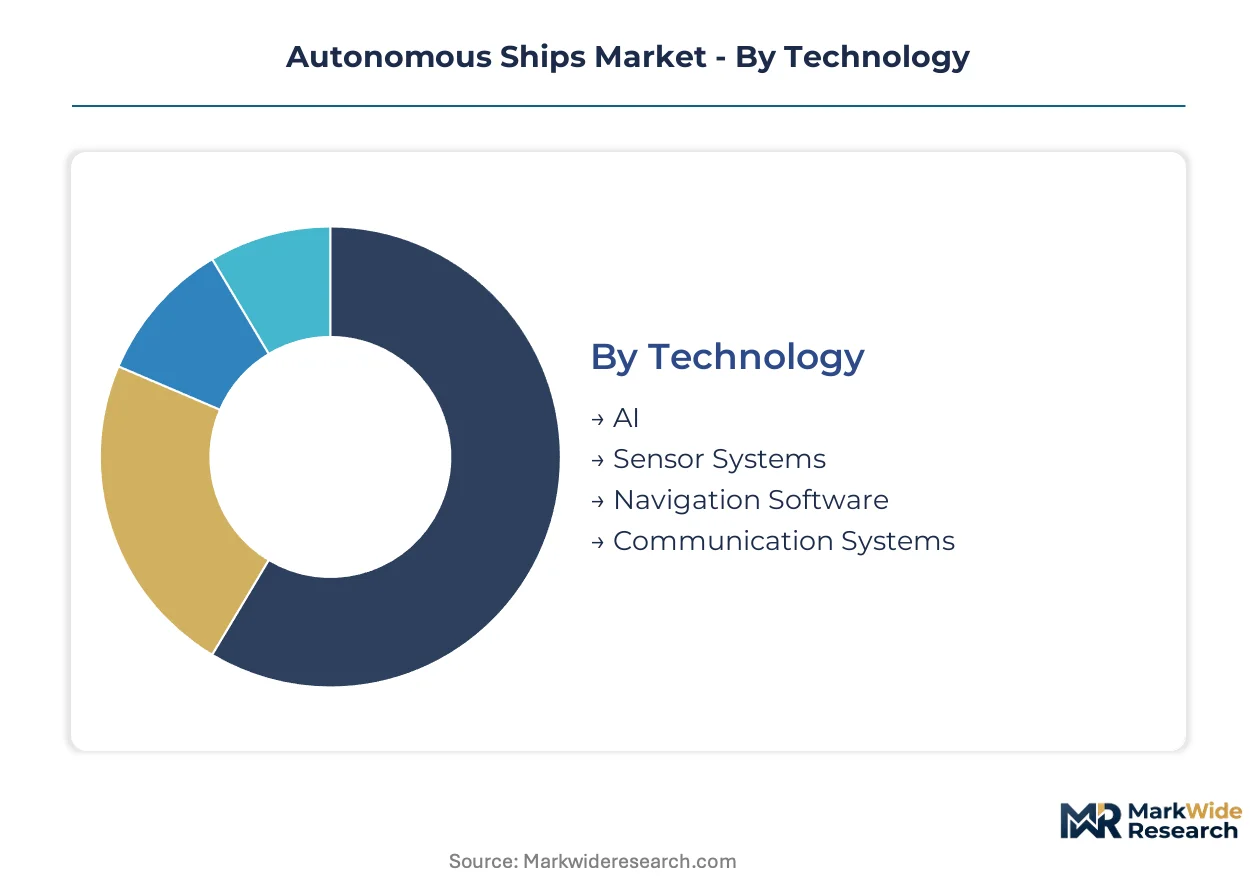
Segmentation in autonomous shipping reveals how technology investment flows through distinct procurement channels. Shipowners, naval architects, and port authorities each prioritize different capability bundles when evaluating automation packages.
Technology:
Technology procurement channels split between integrated bridge system vendors and specialized component suppliers, with shipyards acting as the primary bundling intermediary for newbuild contracts.
- AI:Machine-learning inference engines process collision-avoidance scenarios and route optimization in real-time. Norwegian fjord operators deploy these systems most aggressively where narrow-channel precision reduces crew complements.
- Sensor Systems:Lidar-radar fusion architectures combine redundant detection layers for all-weather berth-to-berth transit. Baltic bulk carriers concentrate retrofit demand here as the EU MRV Regulation tightens emissions accountability for coastal routes.
- Navigation Software:Digital twin platforms simulate vessel dynamics before physical commissioning.
- Communication Systems:Satellite and shore-based control links enable remote vessel operation from land-based centers.
Sensor Systems dominate installed base. AI is where expansion concentrates.
Use Case:
Use case segmentation tracks where operational predictability justifies capital-intensive autonomy investments, with route regularity serving as the primary screening criterion for shipowner business cases.
- Cargo Transport:Container feeders and bulk carriers on fixed coastal routes achieve fastest payback periods through crew reduction. Japanese coastal shipping lanes concentrate early deployment demand for crew-reduced cargo transport.
- Passenger Transport:Autonomous ferries operate in controlled waterways with dedicated traffic separation schemes. Finnish archipelago routes and Norwegian fjord crossings lead operational trials where regulatory sandboxes permit reduced manning.
- Oil & Gas Shipping:Tanker automation faces stricter flag-state scrutiny due to cargo hazard classification.
- Research Vessels:Scientific mission profiles favor autonomous platforms for extended oceanographic data collection.
Cargo Transport commands the largest committed fleet. Passenger Transport is climbing the fastest as ferry operators seek operational cost parity with road and rail alternatives.
Service Type:
Service type segmentation reflects the shift from transactional spare parts procurement to subscription-based operational support, with fleet operators increasingly outsourcing vessel intelligence layers.
- Maintenance:Predictive analytics platforms monitor propulsion health and sensor calibration drift. German port automation partnerships bundle maintenance subscriptions with Smart Marine ecosystem integration.
- Monitoring:Shore-based operations centers track vessel position, machinery status, and environmental conditions continuously. Singapore flag-state trial permits require 24/7 remote monitoring as a condition of reduced-crew certification.
- Fleet Management:Multi-vessel optimization platforms coordinate scheduling and fuel consumption across owned and chartered assets.
- Navigation Assistance:Remote pilotage services supplement or replace onboard deck officers in constrained waters.
Maintenance dominates recurring revenue streams. Monitoring is gaining share fastest as liability frameworks push accountability toward shore-based operators.
Component:
Component procurement splits between yard-integrated systems installed during construction and retrofit packages requiring extended drydock periods, with energy architecture choices increasingly constraining automation compatibility.
- Control Systems:Integrated bridge-to-propulsion command architectures enable single-point decision authority. Kongsberg Maritime dominates Norwegian installations through its ecosystem lock-in across fjord logistics corridors.
- Propulsion Units:Electric and hybrid configurations simplify autonomous integration by reducing mechanical complexity. ABB competes on electric propulsion bundled with navigation stacks for coastal freighters.
- Hull Structures:Dedicated autonomous vessel designs eliminate accommodation blocks and lifeboat requirements.
- Energy Management Systems:Battery and fuel cell monitoring platforms optimize power distribution for sensor and computing loads.
Control Systems anchor retrofit economics. Energy Management Systems represent the steepest expansion trajectory as zero-emission mandates reshape propulsion architecture decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese operators exhibit the lowest price elasticity as labor shortages intensify crew cost pressures, while European bulk carriers face acute retrofit financing constraints that amplify budget sensitivity.
Norway
Norwegian fjord logistics operators drive concentrated demand for crew-reduced coastal feeders where narrow-channel precision justifies premium automation packages. The Norwegian Maritime Authority issues limited trial permits under remote-controlled vessel frameworks that constrain fleet-scale deployment. Kongsberg Maritime anchors technology supply from its Kongsberg headquarters, dominating integrated bridge-to-propulsion installations across Scandinavian coastal corridors.
Japan
Japanese coastal shipping lanes concentrate early deployment demand as aging demographics shrink available maritime labor pools. METI coordinates cross-ministry trials for autonomous container feeders through designated technology demonstration zones. Tokyo Bay and Osaka Bay port clusters host operational pilots where shore-based control centers supplement reduced onboard manning.
Germany
German port authorities in Hamburg and Bremen pioneer dedicated autonomous vessel traffic lanes that reduce collision-risk premiums for first-mover operators. The EU MRV Regulation tightens emissions accountability for Baltic and North Sea coastal routes, accelerating retrofit demand on German-flagged bulk carriers. Wärtsilä anchors Smart Marine ecosystem partnerships with German terminal operators, bundling electric propulsion with automation stacks.
Singapore
Singapore's Maritime and Port Authority issues conditional reduced-crew certifications contingent on 24/7 shore-based monitoring infrastructure. The port city-state positions itself as a regulatory sandbox for Asian autonomous shipping trials, attracting technology vendors seeking tropical-climate operational data. Tuas Mega Port development incorporates dedicated berthing configurations for unmanned feeder vessels on intra-Asia routes.
United Kingdom
UK maritime regulators align with Lloyd's Register Remote-Controlled Ship Code development, influencing certification pathways for North Sea oil and gas support vessels. The Maritime and Coastguard Agency collaborates on liability framework pilots that address collision accountability in mixed-traffic waters. Scottish coastal freight operators trial autonomous feeders on Orkney and Shetland routes where weather resilience demands redundant sensor architectures.
Autonomous Ships Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated bridge system vendors commanding premium positioning while component specialists compete on retrofit economics. The vendor base concentrates around Nordic maritime technology clusters and diversified industrial conglomerates with marine automation divisions. Two strategic archetypes dominate: full-stack ecosystem providers bundling navigation-propulsion-control architectures, and modular component suppliers targeting yard retrofit channels. Competitive moves center on port authority partnership lock-ins and classification society pre-certification investments that accelerate customer approval timelines.
Within the full-stack ecosystem tier, Kongsberg Maritime and Wärtsilä exemplify Nordic integrated-systems positioning, while ABB anchors the electric propulsion-automation convergence archetype. Kongsberg Maritime occupies a position representing Norwegian fjord logistics corridor dominance through bridge-to-propulsion ecosystem lock-in. Wärtsilä sits within the Smart Marine portfolio tier, anchoring Finnish-German port automation partnerships. ABB represents the industrial-electrification pathway, competing on bundled electric propulsion with navigation stacks for coastal freighter retrofits.
| Leading Market Players |
|---|
| ABB |
| Kongsberg Maritime |
| Rolls-Royce plc |
| BAE Systems |
| Honeywell International Inc. |
| L3Harris Technologies |
| Wärtsilä |
| HD Hyundai Heavy Industries |
| Siemens |
| Others |
Supply Flow & Price Mechanics
Take-or-pay contracts for autonomous navigation software bundles lock in yard capacity and price visibility for Norwegian and Japanese operators navigating fragmented flag-state certification timelines. These multi-year agreements tie sensor-software integrators to shipowner retrofit schedules while insulating against component cost volatility in lidar-radar fusion architectures.
Pricing Analysis
The EU's MRV Regulation dictates the pricing tier structure across emissions-accountable coastal routes, separating IMO-compliant certification grades from provisional trial permits. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and shore-based monitoring integration depth. Cost compression in standard-tier retrofit packages intensifies as German and Finnish port automation partnerships consolidate procurement volumes. Japanese coastal operators exhibit lowest price sensitivity due to acute maritime labor shortages, while European bulk carriers face acute budget constraints amplifying financing risk.
Supply Chain Analysis
Norway, Japan, and Germany anchor integrated bridge system production and sensor-software development for maritime autonomy applications. Component sourcing draws from Finnish-German electric propulsion specialists and Nordic lidar manufacturers tethered to narrow-channel precision requirements. Single-source vulnerability concentrates in satellite communication link providers serving shore-based control infrastructure. Distribution runs through shipyard bundling intermediaries for newbuild contracts and specialized retrofit channels for legacy bulk carrier automation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Charterer consolidation in Northern European pulp-and-paper and Japanese trading house segments is shifting specification power toward autonomous-ready vessel requirements, squeezing traditional shipowners without remote-control capability.
For Market Incumbents: Compound ecosystem lock-in across bridge-to-propulsion architectures by deepening software subscription attach rates and pre-certifying designs with Lloyd's Register and DNV. Shore-based operations center partnerships with Singapore and Hamburg port authorities defend against modular component suppliers eroding retrofit margins. Flag-state permit fragmentation threatens fleet-scale rollout timelines; early MPA and Norwegian Maritime Authority relationship investment secures trial permit priority access. For New Entrants and Emerging Players: Differentiate on tropical-climate operational data capture by positioning in Singapore's Tuas Mega Port regulatory sandbox where Asian autonomous shipping trials concentrate unmet demand. White space sits in AI collision-avoidance algorithm development for mixed-traffic waters where EU AI Act liability documentation requirements outpace incumbent compliance investment. Target research vessel and scientific mission profiles where extended oceanographic data collection favors autonomous platform procurement outside established cargo transport channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sensor-software integrators controlling berth-to-berth decision stacks rather than hardware component suppliers. Long-term viability over the analysis window favors acquisition targets with Lloyd's Register Remote-Controlled Ship Code pre-certification and established Finnish-German or Norwegian port authority partnerships. Monitor IMO Maritime Safety Committee certification timeline compression as the inflection signal unlocking institutional capital for autonomous newbuilds currently stalled in pre-contract negotiation phases.| Strategic Initiative | Industry Significance |
|---|---|
| IMO Certification Pre-Investment | Lloyd's Register and DNV queue priority accelerates customer approval timelines for Norwegian coastal operators. |
| Shore-Based Operations Center Partnership | Singapore MPA conditional certification requirements create captive demand for 24/7 remote monitoring infrastructure. |
| Electric Propulsion-Autonomy Bundling | Finnish-German port automation partnerships in Hamburg and Rotterdam terminals capture zero-emission mandate alignment. |
| Sensor-Software Vertical Integration | In-house lidar-radar fusion development reduces dependency on single-source maritime sensor suppliers. |
| Flag-State Regulatory Sandbox Entry | Japan METI technology demonstration zones in Tokyo Bay and Osaka Bay concentrate early deployment demand access. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of Lloyd's Register filings, IMO Maritime Safety Committee protocols, EU MRV Regulation implementation reports, and flag-state permit databases across Norway, Singapore, and Japan. Interviews with shipowner fleet managers, naval architect automation specialists, port authority operations directors, and classification society surveyors informed technology procurement channel segmentation. Customs and trade data on sensor system imports, SEC filings from marine technology conglomerates, and autonomous vessel trial permit registers provided secondary validation. Bottom-up installed base estimates triangulate against top-down market size reconciliation.
Segmentation dimensions modeled span technology procurement channel, use case deployment scenario, service type subscription structure, and component integration timing across the projection horizon. Technology splits capture AI inference engine, sensor system, navigation software, and communication system investment flows. Use case segmentation tracks cargo transport, passenger ferry, and research vessel deployment patterns. CAGRs derive from yard capacity constraints, flag-state permit issuance rates, and charterer specification shift velocity. Forecast inputs incorporate EU AI Act liability provision implementation timing and IMO remote-controlled ship code finalization trajectory.
Material uncertainties — regulatory timeline slippage, liability framework fragmentation, marine autonomy engineer scarcity — sit outside the modeled envelope. Forecasts reflect assumptions on certification queue clearance rates and shore-based infrastructure deployment pace. Recalibration cycles align with material shifts in IMO committee proceedings and flag-state permit policy harmonization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Exhaust Systems Market
Marine
Marine Engine Cooling Systems Market
Marine
Mooring Ropes Market
Marine
Integrated All-Electric Propulsion System for Ships Market
Marine
Electric Ferry Market
Marine
Marine LED Lights Market
Marine
Autonomous Underwater Vehicle (AUV) Market
Marine
Japan Marine Composites Market
Marine
Deep-V Boat Market
Marine
Marine Bearings Market
Marine
Trim Tabs Market
Marine
Marine Asset Integrity Services Market
Marine
Global Marine Gearbox Market
Marine
Marine Trenchers Market
Marine
Marine Fuel Injector Market
Marine
Marine Fender Market