
 Freighter Conversions Market | 2026-2036
Freighter Conversions Market Size, Share, and Industry Trends Forecast 2026-2036
Freighter Conversions Market Insights
Aftermarket service revenue from MRO and component overhaul is narrowing the margin gap with original conversion programs across the freighter value chain. ST Engineering sustains a dominant position in Asia-Pacific through its Singapore and Guangzhou facilities. IAI Bedek leverages decades of Boeing 737 and 747 conversion experience to anchor Israeli technical leadership. Boeing competes through factory-authorized conversion partnerships that extend OEM control over certified modification pathways.
Freighter conversion denotes the structural modification of retired passenger aircraft into dedicated cargo platforms, involving reinforced flooring, cargo door installation, and fuselage strengthening to achieve 9g forward restraint compliance and main deck loading capability. The permanent mount technology segment leads volume due to its structural permanence and lower long-term maintenance burden, while quick-change systems represent the fastest-growing technology category as operators seek dual-use flexibility for seasonal demand peaks. Narrow-body conversions occupy the largest share of active programs given the abundant feedstock of aging A320 and 737-800 airframes reaching retirement.
FAA supplemental type certificate standards, EASA CS-25 certification requirements, and China's CAAC airworthiness directives collectively govern conversion eligibility, inspection protocols, and operational clearance across major aviation jurisdictions. These frameworks directly determine which airframe vintages qualify for modification, how fire suppression and ventilation systems must be reconfigured, and where converted aircraft may be registered and operated. Stakeholders must monitor emerging sustainability mandates from regulators and cargo operators regarding lifecycle emissions accounting for converted versus new-build freighters.
Market Dynamics
Retirement waves of mid-life passenger aircraft are compressing feedstock availability and reshaping conversion slot economics across conversion centers. The structural tension between OEM factory freighter programs and independent conversion shops intensifies as Boeing and Airbus tighten parts access for competing modification pathways.
Growth Catalysts
- E-commerce parcel density:Express carriers in the United States, Germany, and China are expanding narrow-body freighter fleets to handle last-mile and regional hub distribution. This operational shift sustains conversion demand for 737-800 and A321 platforms.
- FAA supplemental type certificate streamlining:Recent procedural adjustments to STC validation timelines are reducing certification bottlenecks for established conversion programs. Eligible airframes now reach revenue service faster.
- Feedstock concentration in secondary markets:Aircraft lessors in Ireland and Singapore are accelerating lease returns of 15-20 year old narrow-bodies. These airframes provide conversion-ready hulls at depreciated book values.
Market Restraints
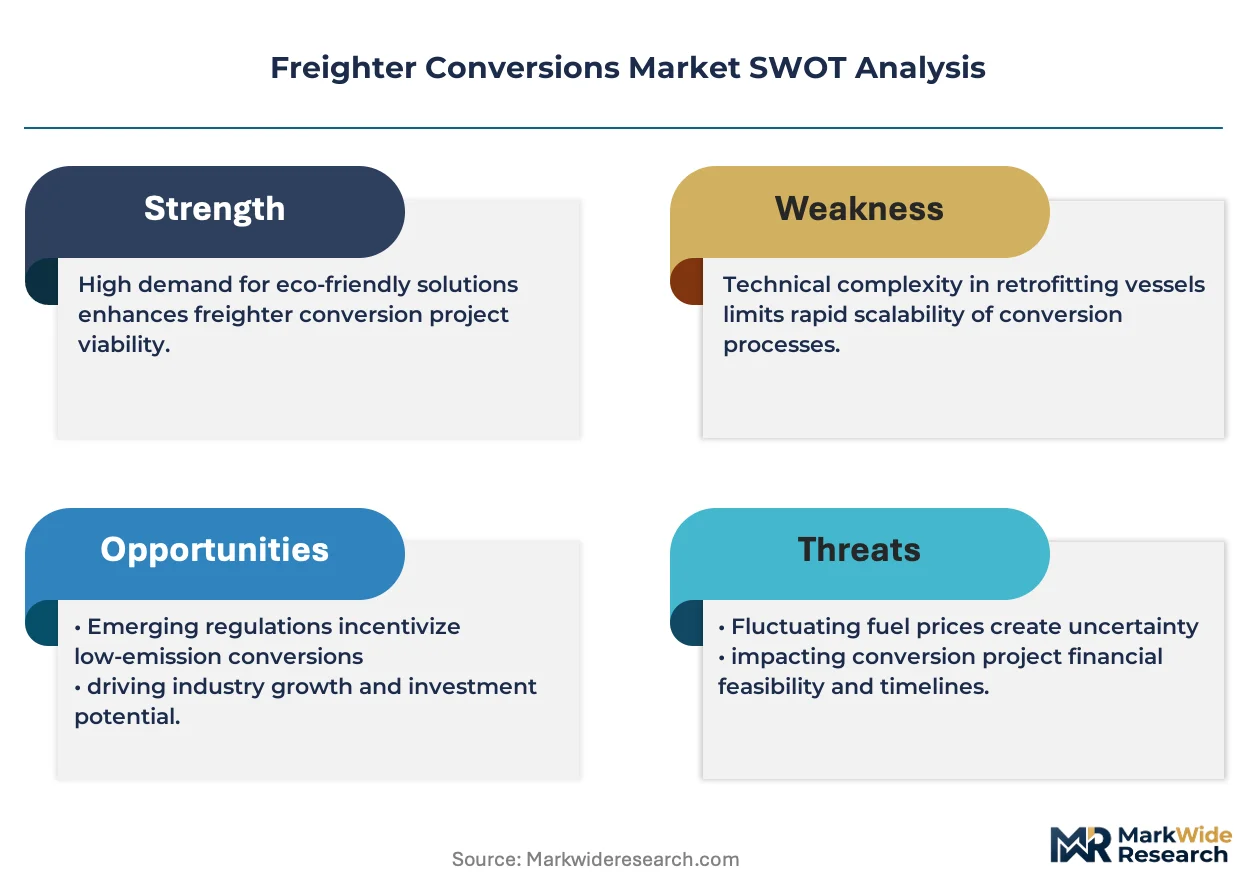
- Airframe availability cliffs:The 737 MAX grounding and subsequent production slowdown reduced 737-800 retirements during 2019-2023. This supply gap limits conversion pipeline depth through 2027.
- OEM parts access restrictions:Boeing's controlled distribution of structural modification kits and engineering data constrains independent conversion shop capabilities. Technical dependency concentrates among factory-authorized partners.
- Aluminum-lithium fuselage incompatibility:Newer A350 and 787 composite structures resist cost-effective cargo door integration. These airframes remain excluded from conversion economics.
Strategic Opportunities
- India domestic cargo liberalization:The country's revised aircraft acquisition rules for non-scheduled operators permit converted freighter imports without legacy bilateral constraints. Regional integrators are evaluating A320 conversions for subcontinent networks.
- Quick-change system adoption:Dual-use platforms combining passenger and cargo configurations address seasonal demand volatility. European charter operators are piloting these systems for summer passenger peaks and winter freight surges.
- Sustainability-linked financing:Conversion programs qualify for green aviation credit facilities in the European Union and Singapore. Lifecycle emissions advantages over new-build freighters attract ESG-mandated capital.
Industry Challenges
- Certification engineer scarcity:FAA DER and EASA DOA qualified structural engineers command premium compensation. Conversion shops in Israel, Singapore, and the United States compete for limited talent pools.
- Fire suppression system reconfiguration:Main deck cargo compartment smoke detection and extinguisher installation requires extensive rewiring. Technical delays in this subsystem extend hangar occupancy by 15-25%.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freighter Conversions Market |
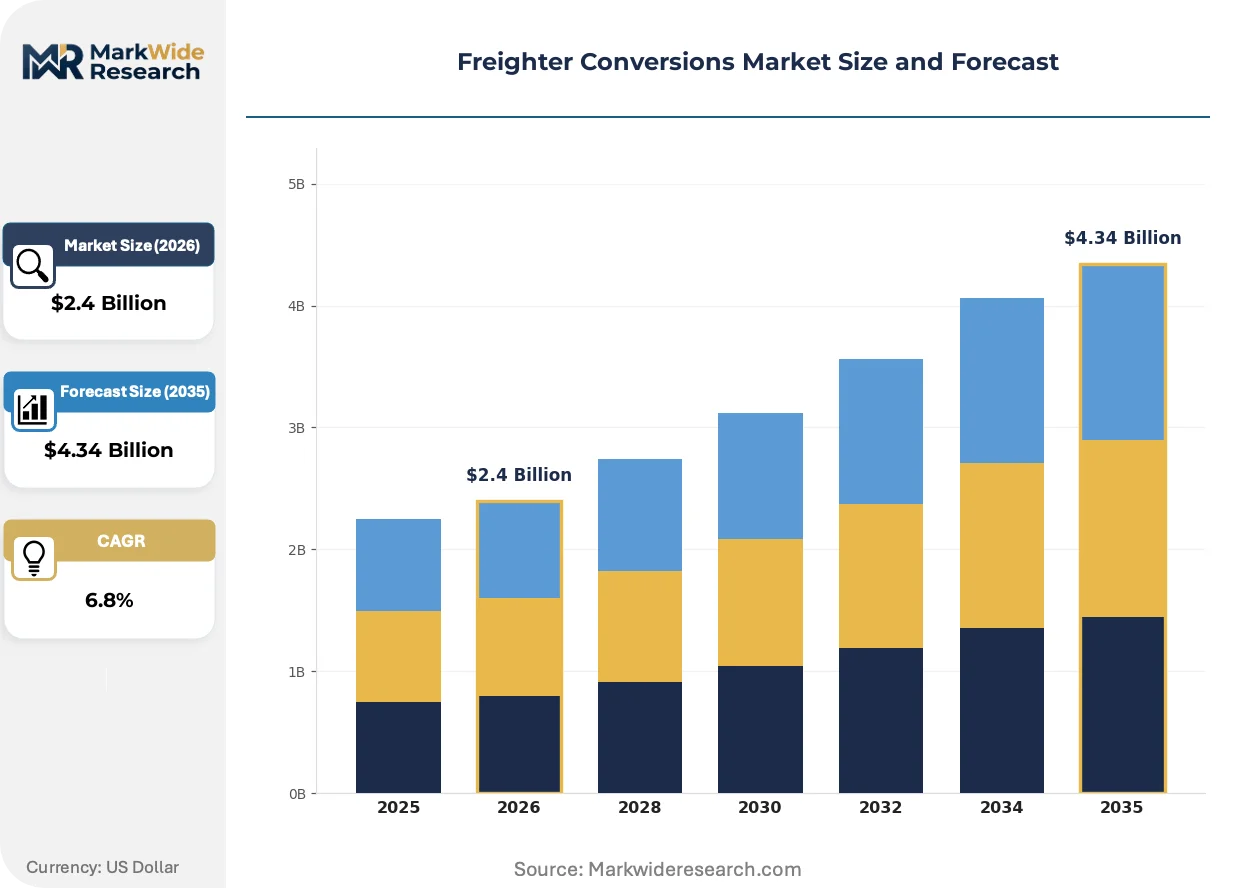
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Conversion Type: Passenger to Freighter, Combi, Full Freighter, Partial Freighter Aircraft Type: Narrow-body, Wide-body, Regional, Cargo-only, Light Freighters End User: Express Carriers, Postal Services, Third-Party Logistics, Dedicated Cargo Operators Technology: Permanent Mount, Quick Change, Palletized Systems, Roll-on/Roll-off, Locking Mechanisms |
| Companies Covered | Aeronautical Engineers, ST Engineering, HAECO, Precision Aircraft Solutions, IAI Bedek, Pemco Conversions, EFW, Elbe Flugzeugwerke, Boeing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freighter Conversions Market Trends and Innovations
Digital thread technologies are penetrating conversion engineering workflows, compressing design-to-certification timelines and enabling remote inspection protocols. These capabilities are redistributing competitive advantage toward technology-enabled conversion centers.
Structural health monitoring systems embedded during conversion are digitizing maintenance planning for cargo operators. FedEx and DHL are retrofitting converted fleets with real-time fuselage stress sensors. This capability is digitizing scheduled inspection intervals and reducing unplanned downtime.
REACH restrictions on hexavalent chromium surface treatments are forcing conversion shops to adopt alternative corrosion protection chemistries. German and French MRO facilities are qualifying trivalent chromium and plasma electrolytic oxidation processes. Narrow-body programs serving European-registered operators face accelerated compliance deadlines.
Airframe procurement through leasing companies rather than direct airline acquisition is fragmenting feedstock ownership. Lessors in Dublin and Singapore now control 60% of conversion-eligible narrow-body supply. This concentration is lengthening price negotiation cycles and introducing residual value guarantee complexity.
Freighter Conversions Market Segmentation
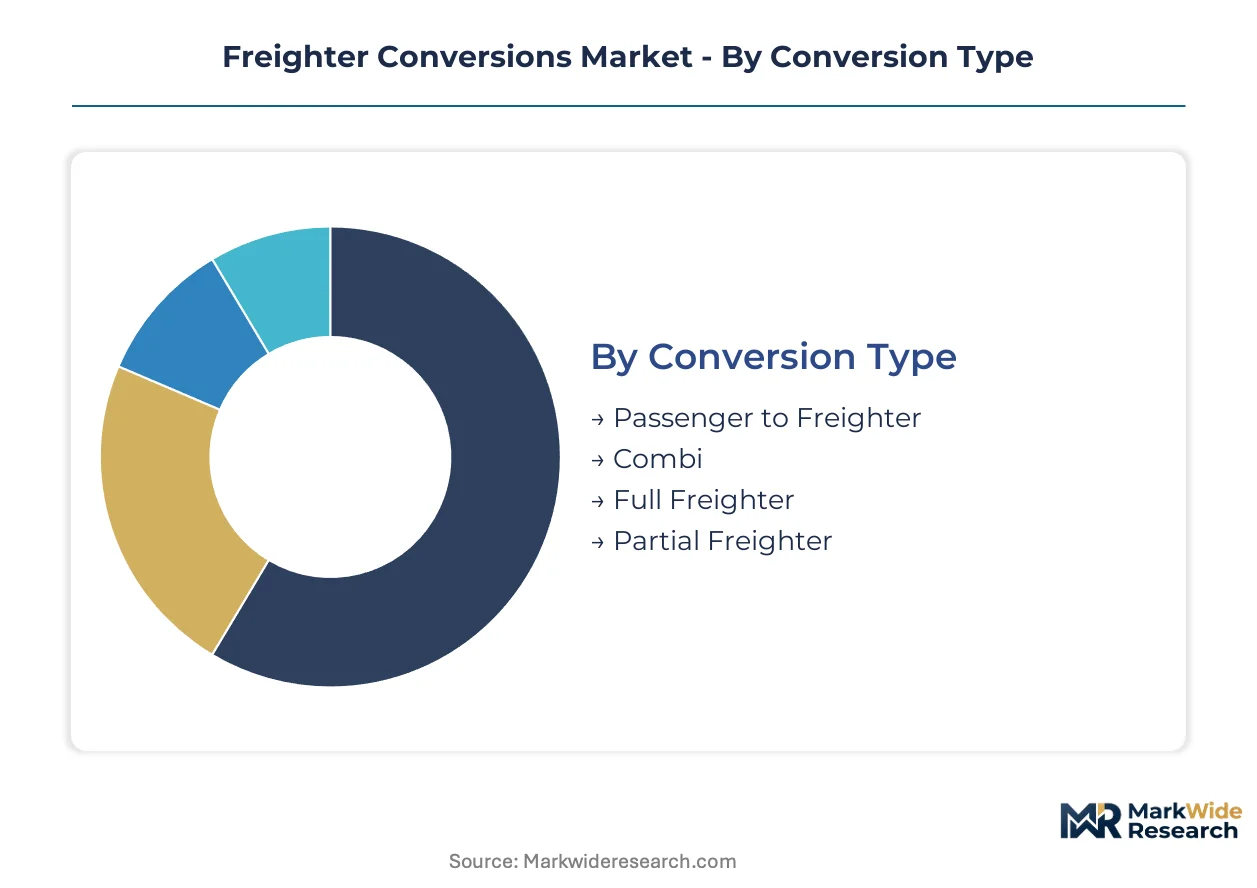
Freighter conversion programs align engineering specifications with operator business models across four critical dimensions. Conversion type determines structural scope and certification pathway. Aircraft type dictates feedstock economics and payload capability. End user profiles shape route network requirements and fleet composition. Technology selection balances operational flexibility against lifetime maintenance burden.
Conversion Type:
Mature full freighter programs dominate revenue conversion hours, while emerging partial freighter modifications address niche cargo-plus-passenger demand.
- Passenger to Freighter:Complete structural transformation including main deck cargo door installation, reinforced flooring, and 9g forward restraint systems. Express carriers in the United States concentrate demand here for 737-800 and A321 platforms serving regional hub networks.
- Combi:Dual-configuration aircraft retaining partial passenger cabin forward of the cargo compartment. Operators in Alaska and remote Canadian territories deploy these for mixed passenger-freight routes where infrastructure constraints prevent dedicated freighter economics.
- Full Freighter:Dedicated all-cargo configuration maximizing volumetric capacity through continuous main deck loading. Postal services in Germany and Japan standardize on this format for high-frequency trunk routes.
- Partial Freighter:Limited modification preserving passenger emergency exits and windows for regulatory simplicity. Charter operators in Southeast Asia favor this lower-cost pathway for seasonal cargo peaks.
Passenger-to-freighter handles the majority of throughput; partial freighter is the fastest mover on share.
Aircraft Type:
Volume concentration tracks feedstock availability, with narrow-body retirements supplying the densest conversion pipeline.
- Narrow-body:A320 and 737-800 platforms dominate active programs due to abundant 15-20 year old feedstock from lessor portfolios. Last-mile integrators in China and the United States absorb converted narrow-body capacity for domestic distribution networks.
- Wide-body:767-300ER and A330 conversions serve transcontinental trunk routes requiring main deck container capability. Dedicated cargo operators in Luxembourg and Hong Kong anchor demand for extended-range wide-body freighters.
- Regional:ATR 72 and CRJ700 modifications address thin cargo routes where jet economics fail. Sub-Saharan African operators deploy these for humanitarian and perishable commodity transport.
- Cargo-only:Factory-built freighters without passenger heritage, occasionally retrofitted for specialized missions. Military contractors in the United States modify these for aerial refueling and surveillance platforms.
- Light Freighters:Cessna Caravan and Pilatus PC-12 conversions for feeder and remote airstrip operations. Mining and energy companies in Australia and Canada operate these for camp resupply.
Narrow-body conversions absorb the greatest modification hours; wide-body programs command the steepest expansion trajectory as feedstock availability improves.
End User:
Customer procurement patterns diverge sharply between asset-light logistics integrators and capital-intensive dedicated operators.
- Express Carriers:Fleet standardization around 737-800 and 767-300ER conversions with integrated ground handling systems. Memphis and Louisville hub operators in the United States drive narrow-body conversion slot demand through 2027.
- Postal Services:National mail operators prioritize reliability over speed, favoring mature conversion programs with established maintenance protocols. Japan Post and Deutsche Post anchor wide-body orders for intercontinental mail flows.
- Third-Party Logistics:Asset-light forwarders lease converted capacity from dedicated operators rather than owning freighters directly. DHL Supply Chain and Kuehne+Nagel influence lessor specification requirements for conversion-eligible feedstock.
- Dedicated Cargo Operators:Full-freighter airlines with owned fleets optimizing for block hour economics. Cargolux and Atlas Air specification requirements shape 747-400 conversion engineering standards.
Express carriers dominate conversion order books; third-party logistics represents the segment gaining share fastest as e-commerce parcel volumes fragment ownership models.
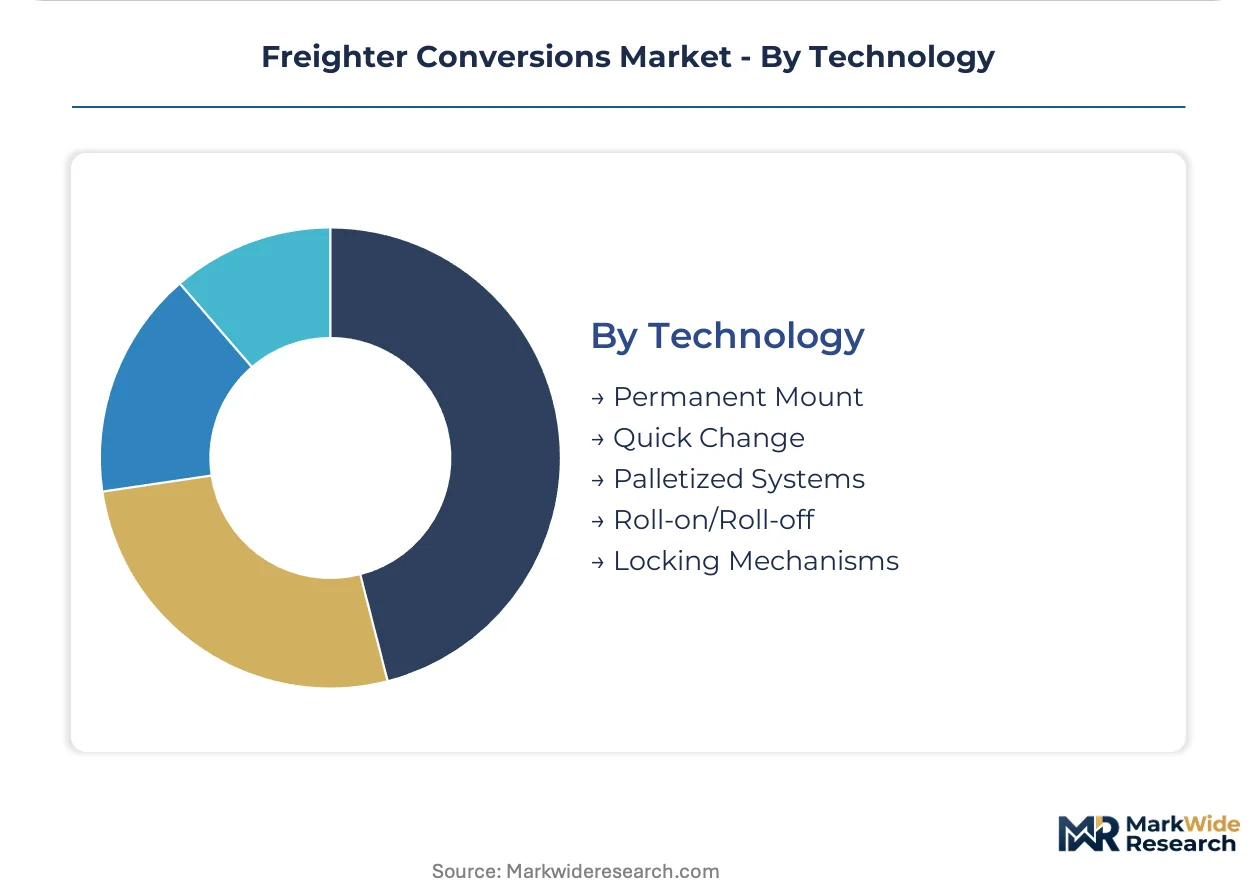
Technology:
Cost tier differentiation separates permanent structural modifications from flexible quick-change systems.
- Permanent Mount:Fixed cargo handling infrastructure welded to airframe structure with lowest lifetime maintenance burden. FedEx and UPS standardize on this technology for high-utilization domestic networks.
- Quick Change:Modular systems enabling overnight conversion between passenger and cargo configurations. European charter operators in Scandinavia pilot these for summer passenger peaks and winter freight surges.
- Palletized Systems:Standardized ULD compatibility for interline cargo transfer. Ground handlers at Frankfurt and Singapore hubs drive specification requirements for main deck roller systems.
- Roll-on/Roll-off:Drive-through loading for wheeled cargo and live animals. Australian livestock exporters and Middle Eastern automotive logistics providers specify these configurations.
- Locking Mechanisms:Cargo restraint systems achieving 9g forward load compliance. IAI Bedek and ST Engineering compete on proprietary locking rail designs for narrow-body programs.
Permanent mount technology secures the largest installed base; quick change systems are expanding most quickly as operators seek asset utilization flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across conversion demand centers, with United States express carriers absorbing premium slots while Indian regional operators negotiate aggressively on narrow-body feedstock. Mature aviation jurisdictions pay certification premiums; emerging cargo markets prioritize depreciated asset economics.
United States
FedEx and UPS anchor narrow-body conversion demand through Memphis and Louisville hub expansions. FAA supplemental type certificate processes govern all modification approvals, with recent procedural streamlining reducing validation timelines. ST Engineering operates conversion partnerships in San Antonio, Texas, serving domestic express carrier specifications.
China
E-commerce parcel volumes from Alibaba and JD Logistics sustain A321 conversion interest for domestic trunk routes. CAAC airworthiness directives determine eligibility standards for imported feedstock and local registration. Guangzhou hosts ST Engineering's primary Asian conversion facility, processing narrow-body programs for regional integrators.
Germany
Deutsche Post DHL specifications shape wide-body conversion standards for European mail and parcel networks. EASA CS-25 certification requirements mandate fire suppression and ventilation reconfigurations exceeding FAA baselines. Dresden conversion specialists serve EFW programs with factory-authorized engineering pathways.
Singapore
Lessors based in Singapore control substantial A320 and 737-800 lease return pipelines, fragmenting feedstock ownership across conversion-eligible fleets. The country's aviation regulator enforces alignment with EASA and FAA standards for dual-registered operations. Seletar Aerospace Park concentrates MRO and modification capabilities serving Asia-Pacific cargo operators.
Israel
IAI Bedek's decades of Boeing platform conversion experience anchor national technical leadership in structural modification engineering. Israeli civil aviation authority certification reciprocity with FAA and EASA enables multi-jurisdictional operational clearances. Tel Aviv-area engineering clusters supply DER-qualified structural engineers to conversion programs globally.
Freighter Conversions Market Competitive Landscape
Capability concentration sits with engineering-intensive conversion specialists; scale advantage sits with factory-authorized OEM partnerships. The market structures around three tiers: independent modification shops with proprietary STC portfolios, aerospace conglomerates operating multi-facility conversion networks, and OEM-captive programs controlling parts access and certification pathways. Dominant competitive moves include strategic slot reservation agreements with lessors and technology licensing for quick-change system deployment.
Among Asia-Pacific-based engineering groups, ST Engineering exemplifies multi-facility scale with Singapore and Guangzhou operations. IAI Bedek represents the independent specialist archetype with deep Boeing platform heritage. Boeing itself anchors the OEM-captive tier through factory-authorized conversion partnerships that constrain independent access to structural modification kits.
| Leading Market Players |
|---|
| Aeronautical Engineers |
| ST Engineering |
| HAECO |
| Precision Aircraft Solutions |
| IAI Bedek |
| Pemco Conversions |
| EFW |
| Elbe Flugzeugwerke |
| Boeing |
| Others |
Pricing and Supply Chain Analysis
Hangar slot undercapacity at Singapore and Guangzhou conversion centers is compressing lead times and amplifying pricing power for engineering-intensive modification programs. This utilization squeeze simultaneously elevates premium slot rates and forces feedstock buyers toward secondary conversion facilities with softer pricing.
Pricing Analysis
Aftermarket service revenue from MRO contracts and component overhaul drives lifetime value capture beyond initial conversion fees. Three-tier pricing structure across premium, standard, and economy levels separates factory-authorized programs from independent STC pathways and partial-freighter shortcuts. Cost compression in narrow-body slots is intensifying because lessor portfolio concentration fragments feedstock negotiation leverage. Regional integrators in India exhibit acute price sensitivity, while express carriers in the United States absorb premium rates for FAA-validated programs.
Supply Chain Analysis
Tariff exposure between the United States and China dominates conversion kit sourcing vulnerabilities for structural modification hardware. Engineering talent concentrates in Israel, Singapore, and the United States, while aluminum sheet and composite panel supply feeds from Germany, Japan, and domestic Chinese mills. Fire suppression system rewiring and 9g restraint rail fabrication represent critical single-source dependencies. Distribution runs through lessor-controlled feedstock auctions in Dublin and Singapore rather than direct airline procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified structural engineers with FAA DER and EASA DOA qualifications represent the binding constraint across conversion programs, with talent scarcity shaping competitive outcomes more than capital access or facility scale.
For Market Incumbents: Insulate engineering talent pipelines through captive training partnerships with Tel Aviv-area technical universities and Singapore polytechnics. Deepen backward integration into proprietary locking rail manufacturing to reduce dependency on Boeing-controlled structural modification kits. OEM parts access restrictions threaten independent conversion shop viability; vertical control over certification-critical subsystems defends margin position. For New Entrants and Emerging Players: India's domestic cargo liberalization offers the most penetrable regulatory opening for A320 conversion programs serving subcontinent integrators. Quick-change system adoption in European charter markets presents a second white-space target with lower certification barriers than full freighter programs. A go-to-market angle anchored in seasonal flexibility—passenger summer peaks, freight winter surges—differentiates against permanent-mount incumbents. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among multi-facility engineering groups with captive MRO networks and lessor slot reservation agreements. Long-term viability over the next decade favors acquisition targets with proprietary STC portfolios and established regulatory reciprocity across FAA, EASA, and CAAC jurisdictions. The signal to watch is feedstock auction pricing at Dublin lessor portfolios—sustained elevation indicates conversion demand outrunning engineering capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Engineering Talent Captive Development | DER-qualified structural engineers from Tel Aviv universities secure certification capacity. |
| Proprietary STC Portfolio Expansion | IAI Bedek's Boeing platform heritage demonstrates defensible intellectual property moats. |
| Quick-Change System Licensing | European charter operators in Scandinavia pilot dual-use flexibility for seasonal demand. |
| Lessor Slot Reservation Agreements | Singapore-based lessor partnerships fragment feedstock ownership toward conversion-ready pipelines. |
| Fire Suppression Subsystem Verticalization | German and French REACH compliance deadlines accelerate alternative chemistry qualification needs. |
Research Methodology
A standing panel of conversion program directors, FAA DER structural engineers, aircraft lessor portfolio managers, and express carrier fleet planners provided ongoing calibration against operating reality. Primary interviews with these stakeholders combined with secondary validation from FAA supplemental type certificate filings, EASA CS-25 certification databases, CAAC airworthiness directive records, and customs trade data for conversion kit imports. Bottom-up facility capacity utilization estimates triangulated against top-down feedstock retirement projections.
Scenario-bracketing around feedstock availability cliffs and certification timeline compression shaped the analytical framework across the analysis window. Segmentation dimensions modeled include conversion type, aircraft platform, end-user archetype, and technology selection. CAGRs derived from facility throughput capacity expansion trajectories and lessor portfolio aging curves. Industry-specific forecast inputs incorporated e-commerce parcel density growth and regulatory streamlining effects on STC validation timelines.
Practitioners should monitor feedstock auction pricing at Dublin and Singapore lessor portfolios for early signals of demand-supply imbalance. Forecasts reflect assumptions regarding 737-800 retirement wave timing and FAA procedural streamlining sustainability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Furnace Boats Market
Marine
Jet Boat Market
Marine
Marine Communication Market
Marine
Sailboat Market
Marine
Digital Nautical Charts Market
Marine
Marine Shackle Market
Marine
Electric Boat and Ship Market
Marine
Yacht Shell Doors Market
Marine
Global Foldable Inflatable Boats Market
Marine
Marine and Marine Management Software Market
Marine
Asia-Pacific Leisure Boat Marine Coating Market
Marine
US Fish Finders Market
Marine
North Sea Offshore Support Vessels Market
Marine
Trim Tabs Market
Marine
Rescue Boats Market
Marine
Europe Recreational Boating Market