
 Global Outboard Motors Market | 2026-2036
Global Outboard Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Outboard Motors Market Outlook
China is reconfiguring its marine manufacturing footprint through expanded outboard motor production clusters in Zhejiang and Jiangsu provinces. Brunswick Corporation sustains dominant position in North American distribution networks through Mercury Marine brand infrastructure. Yamaha Motor Co. Ltd leverages integrated engine casting and precision machining capabilities to control premium four-stroke supply chains. Suzuki Motor Corporation specializes in lightweight high-torque designs that anchor its competitiveness across Asian recreational markets.
Outboard motors are self-contained marine propulsion units mounted on a boat transom, comprising powerhead, driveshaft, and gearcase assemblies that convert fuel or electrical energy into thrust through submerged propeller rotation. Four-stroke gasoline configurations now dominate volume production due to superior fuel efficiency and emissions compliance versus two-stroke alternatives, though electric outboards are displacing small-combustion units in lake-restricted and environmentally regulated waterways. Application segmentation shows recreational boating commanding the largest installed base while commercial fishing generates the highest replacement frequency and aftermarket parts demand. Output power stratification reveals above 100 HP segments carrying disproportionate margin contribution despite lower unit volumes.
EPA marine engine standards and EU F-Gas Regulation are forcing combustion redesigns and catalyzing electric platform investment across major manufacturing jurisdictions. Japan's METI efficiency benchmarks and China's MEE emissions protocols add compliance layers for products entering Asian markets. ISO marine propulsion standards provide interoperability frameworks that reduce certification friction for cross-border sales. Stakeholders must monitor regulatory divergence between combustion-phaseout timelines and charging infrastructure deployment rates to calibrate product portfolio transitions.
Market Dynamics
Electric propulsion architectures are forcing combustion-focused manufacturers to reconfigure R&D allocation and factory tooling commitments across three continents simultaneously.
Growth Catalysts
- EPA Marine Tier 3 Standards:Stringent emissions thresholds for gasoline outboards are accelerating four-stroke engine upgrades and catalytic converter integration across US recreational fleets.
- Freshwater Lake Bans:Municipal restrictions on combustion motors in Germany, Switzerland, and Austria are redirecting demand toward electric alternatives in sub-25 HP segments.
- Lithium-Ion Pack Cost Curves:Falling battery cell prices are compressing the total-cost-of-ownership gap between electric and gasoline propulsion for commercial fishing operators.
Market Restraints
- Aluminum Alloy Supply Concentration:Gearcase and powerhead casting operations depend heavily on Chinese primary aluminum smelters, exposing margins to energy-price volatility and export quota shifts.
- Charging Infrastructure Gaps:Marina electrical upgrades lag electric motor adoption in Japan, Australia, and Nordic coastal regions, constraining range confidence among cruising boaters.
- Two-Stroke Legacy Inventory:Pre-ban stockpiles of carbureted engines in Southeast Asian markets create price-floor pressure that delays premium four-stroke conversion timelines.
Strategic Opportunities
- Brazilian Coastal Municipalities:Underpenetrated recreational boating infrastructure along Rio de Janeiro and São Paulo state coastlines offers first-mover positioning for rental fleet electrification.
- EU Green Deal Maritime Funding:Dedicated innovation grants for zero-emission propulsion are subsidizing pilot deployments of hydrogen fuel-cell range extenders in commercial ferry applications.
- Direct-to-Consumer Marine Retail:Bypassing traditional dealer networks through manufacturer-owned digital platforms is capturing younger demographic segments in US and Australian markets.
Industry Challenges
- Marine Electrician Certification Bottlenecks:Shortages of technicians qualified for high-voltage propulsion system diagnostics are extending service wait times and eroding customer satisfaction scores.
- Dual Homologation Burden:Parallel EPA and EU F-Gas compliance testing protocols are stretching product development cycles and inflating certification budgets for multi-market launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Outboard Motors Market |
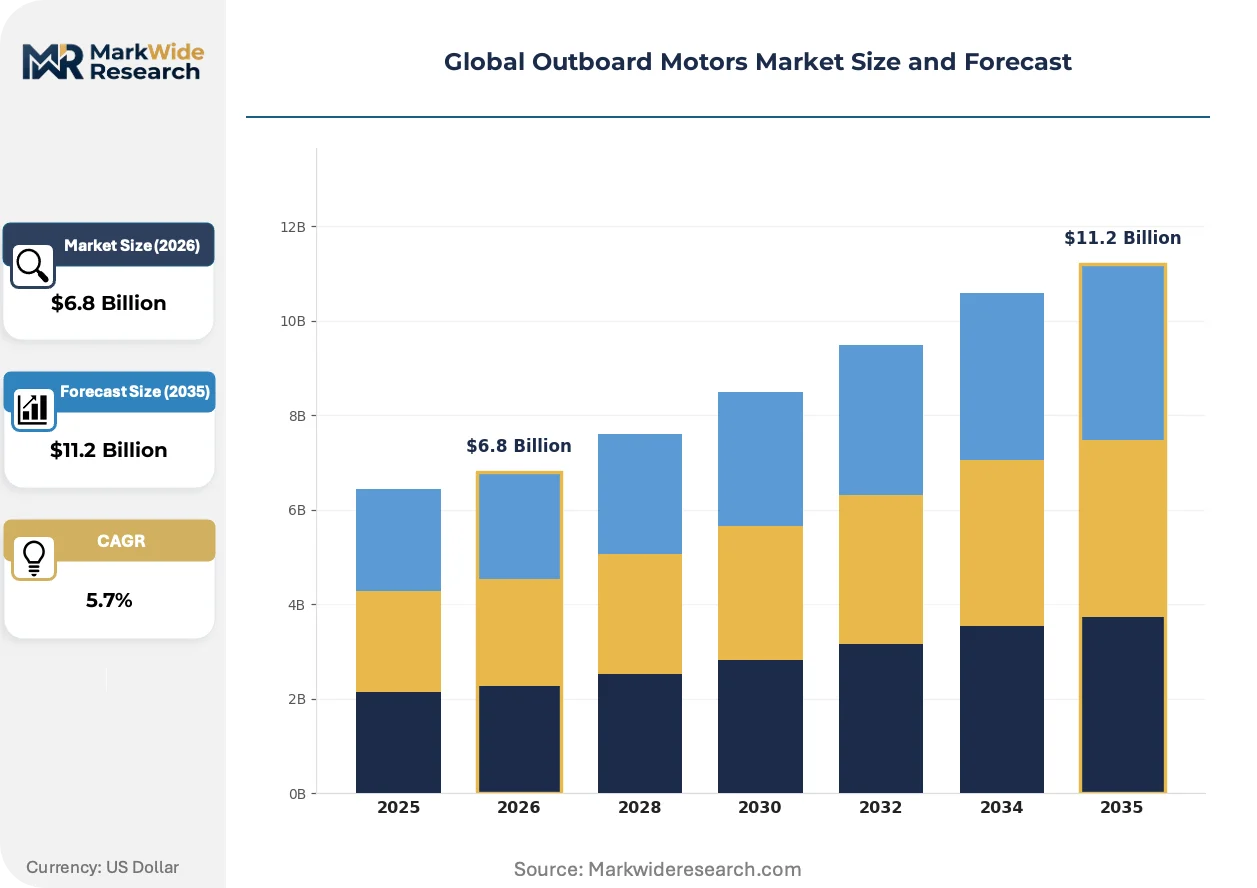
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Two-Stroke, Four-Stroke, Electric, Diesel Application: Recreational Boating, Commercial Fishing, Water Sports, Industrial Use Output Power: Less than 10 HP, 10-50 HP, 51-100 HP, Above 100 HP End User: Individual Consumers, Boat Manufacturers, Rental Services, Government Agencies |
| Companies Covered | Yamaha Motor Co. Ltd, Brunswick Corporation, Suzuki Motor Corporation, Honda Motor Co. Ltd, Tohatsu Corporation, Bombardier Recreational Products Inc, Mercury Marine, Suzhou Parsun Power Machine Co. Ltd, Hidea Power Machinery Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Outboard Motors Market Strategic Shifts
Propulsion technology is bifurcating between refined combustion architectures and battery-electric platforms, with hybrid configurations emerging as the contested middle ground for range-sensitive applications.
Integrated motor-controller-battery systems are hybridizing the traditional outboard supply chain. Tier-1 suppliers previously focused on mechanical gearcase assemblies now source power electronics from automotive-tier semiconductor fabricators. Charter operators in the Mediterranean and Caribbean are piloting these unified platforms to reduce maintenance intervals. The technology is hybridizing competitive boundaries between marine specialists and cross-industrial mobility component suppliers.
EU F-Gas Regulation phase-down schedules for fluorinated greenhouse gases are restricting refrigerant options for closed-circuit cooling systems in high-output outboards. Engine manufacturers must redesign thermal management architectures using CO2 or hydrocarbon alternatives. Commercial fishing fleets operating in EU waters face accelerated replacement timelines for existing refrigerated hold systems tied to propulsion packages.
Boat builders are consolidating vendor relationships to reduce configuration complexity. Multi-brand dealerships are losing access to exclusive territory arrangements as manufacturers pursue flagship store formats in high-density boating regions. This consolidation is most visible in Florida, Queensland, and the French Riviera where direct manufacturer presence now dominates premium segment transactions.
Global Outboard Motors Market Segmentation
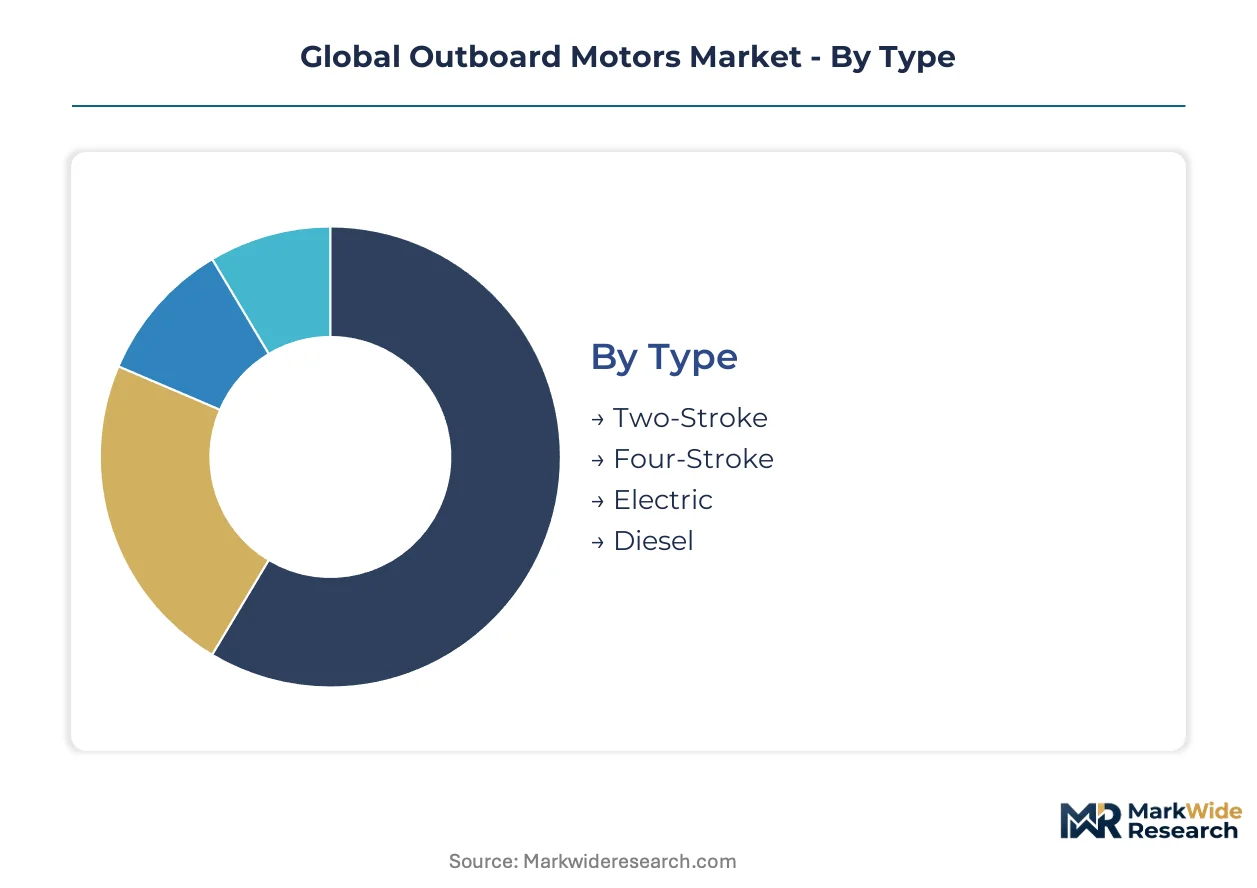
Segmentation in the outboard motors market reveals how propulsion technology, application intensity, and procurement channels create divergent margin profiles and replacement cycles. Manufacturers calibrate R&D investment and distribution partnerships against these fault lines to defend positioning across fragmented demand pools.
Type:
Propulsion technology defines the core competitive battleground, with fuel chemistry and powertrain architecture determining regulatory compliance pathways and aftermarket revenue durability.
- Four-Stroke:These gasoline engines employ dedicated intake and exhaust strokes separate from combustion cycles, delivering superior fuel efficiency and emissions compliance versus legacy alternatives. Demand concentrates in United States recreational boating as EPA Tier 3 standards force fleet turnover, with Mercury Marine and Yamaha Motor controlling casting and machining capacity for powerhead assemblies.
- Electric:Battery-powered outboards integrate lithium-ion packs with brushless DC motors and regenerative controllers, eliminating onboard fuel storage. Municipal combustion bans across German, Swiss, and Austrian lakes are redirecting sub-25 HP demand toward these zero-emission platforms, though marina charging infrastructure gaps in Japan and Australia constrain cruising adoption.
- Two-Stroke:Carbureted and direct-injection gasoline designs retain cost advantages in price-sensitive Southeast Asian markets where pre-ban inventory stockpiles create price-floor pressure.
- Diesel:Compression-ignition outboards deliver torque density for commercial fishing vessels operating extended offshore ranges, with Yanmar and Mercury Marine dominating heavy-duty gearcase engineering.
Four-Stroke holds installed capacity. Electric is rotating up the share rankings.
Application:
End-use intensity shapes product durability specifications, maintenance contract structures, and replacement frequency across the installed base.
- Recreational Boating:Leisure craft operators prioritize noise reduction, fuel efficiency, and aesthetic integration with hull designs. United States coastal municipalities and Japanese freshwater lakes generate the highest unit volumes, though seasonal usage patterns extend replacement intervals versus commercial applications.
- Commercial Fishing:Professional operators demand maximum reliability under continuous load conditions, with trawler and longline fleets in Indonesia, Vietnam, and Norway driving the highest aftermarket parts consumption. Suzuki Motor's lightweight high-torque architectures anchor competitiveness across Asian markets where fuel costs dominate operating economics.
- Water Sports:Wakeboarding and waterskiing applications require precise throttle response and rapid planing capability, with tournament boat builders specifying premium four-stroke configurations.
- Industrial Use:Workboat operators in dredging, survey, and offshore support prioritize redundancy and field-serviceability over performance metrics.
Recreational Boating commands unit volume leadership. Commercial Fishing generates the steepest expansion trajectory in aftermarket revenue intensity.
Output Power:
Power band stratification separates commodity volume segments from premium-margin territories where technical differentiation justifies pricing authority.
- Above 100 HP:High-displacement powerheads with multi-cylinder architectures and closed-circuit cooling systems serve offshore cruisers and commercial vessels. These configurations carry disproportionate margin contribution despite lower unit volumes, with Brunswick Corporation's Mercury Marine brand sustaining dominant North American distribution control.
- 10-50 HP:Mid-range four-stroke and electric platforms balance portability with sufficient thrust for aluminum fishing boats and small fiberglass runabouts. China's Zhejiang and Jiangsu production clusters are expanding casting and assembly capacity to serve domestic lake recreation and export markets simultaneously.
- Less than 10 HP:Portable outboards for inflatable tenders and small dinghies face maximum displacement pressure from electric alternatives in regulated waterways.
- 51-100 HP:Crossover segment serving dual-console fishing boats and pontoon platforms where load capacity demands exceed mid-range thresholds.
Above 100 HP anchors profit pool concentration. 10-50 HP is climbing the fastest in production volume.
End User:
Procurement channel structure determines pricing transparency, brand loyalty mechanics, and service attachment rates across the value chain.
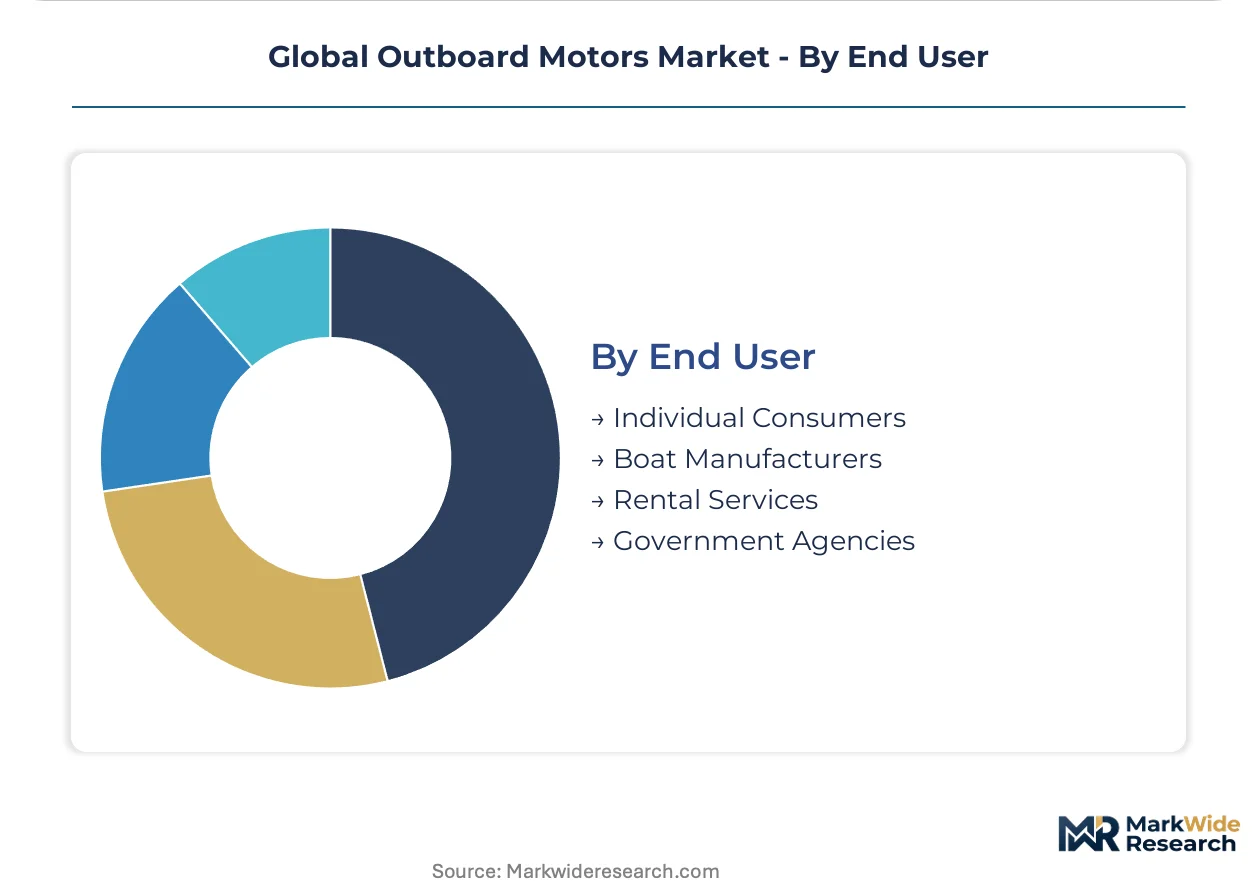
- Boat Manufacturers:OEM bundling agreements with Brunswick, Yamaha, and Suzuki lock in multi-year supply commitments for new vessel production. These relationships prioritize technical integration support and volume pricing schedules over spot-market flexibility.
- Rental Services:Fleet operators in Mediterranean and Caribbean charter markets pilot integrated motor-controller-battery systems to compress maintenance intervals and maximize vessel utilization rates.
- Individual Consumers:Direct-to-consumer digital platforms are capturing younger demographic segments in United States and Australian markets, bypassing traditional dealer networks.
- Government Agencies:Coast guard, fisheries enforcement, and park services specify hardened configurations with extended service intervals and domestic content requirements.
Boat Manufacturers dominate procurement scale. Rental Services is gaining share fastest in electric platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recreational boating intensity varies sharply by geography. United States operators favor high-horsepower offshore cruisers, while European lake municipalities enforce combustion restrictions that redirect demand toward electric alternatives. Asian commercial fishing fleets prioritize fuel efficiency over performance metrics.
United States
Coastal municipalities from Florida to the Pacific Northwest are expanding marina infrastructure to accommodate larger recreational fleets. EPA Marine Tier 3 emissions standards are forcing four-stroke upgrades across saltwater and freshwater segments. Mercury Marine maintains dominant distribution control through dealer networks concentrated in the Southeast and Great Lakes regions.
China
Domestic lake recreation and export manufacturing are driving parallel demand streams for mid-range outboards. MEE emissions protocols add compliance layers for products entering regulated waterways. Zhejiang and Jiangsu provinces are expanding casting and assembly clusters to serve both domestic consumption and international OEM contracts.
Japan
Freshwater boating participation rates anchor steady replacement demand for precision-engineered four-stroke units. METI efficiency benchmarks shape product development cycles for manufacturers targeting domestic and export markets. Coastal regions around Tokyo Bay and Osaka maintain concentrated dealership networks for premium segment distribution.
Germany
Municipal combustion bans across Bavarian and northern lakes are redirecting sub-25 HP demand toward electric platforms. EU F-Gas Regulation restricts refrigerant options for closed-circuit cooling systems in high-output configurations. Industrial fabrication capabilities in Baden-Württemberg support gearcase machining for European OEM supply chains.
Australia
Coastal cruising and commercial fishing generate divergent demand profiles across Queensland and Western Australia. Marina electrical upgrades lag electric motor adoption, constraining range confidence among extended-range operators. Sydney and Melbourne metropolitan areas are piloting direct-to-consumer digital platforms that bypass traditional dealer networks.
Global Outboard Motors Market Competitive Environment
Capability concentration sits with integrated engine specialists; scale advantage sits with diversified mobility conglomerates. The market structures around three tiers: premium four-stroke manufacturers with captive casting capacity, electric platform specialists with automotive-tier semiconductor sourcing, and price-competitive two-stroke suppliers serving residual demand in Southeast Asia. Strategic moves center on factory tooling reconfiguration for dual propulsion architectures and exclusive territory consolidation in high-density boating regions.
Within the integrated powertrain tier, Yamaha Motor Co. Ltd and Suzuki Motor Corporation exemplify manufacturers with precision machining capabilities that control premium four-stroke supply chains. Brunswick Corporation, operating through Mercury Marine, anchors North American distribution infrastructure. Suzhou Parsun Power Machine Co. Ltd represents Chinese fabrication scale serving mid-range export markets.
| Leading Market Players |
|---|
| Yamaha Motor Co. Ltd |
| Brunswick Corporation |
| Suzuki Motor Corporation |
| Honda Motor Co. Ltd |
| Tohatsu Corporation |
| Bombardier Recreational Products Inc |
| Mercury Marine |
| Suzhou Parsun Power Machine Co. Ltd |
| Hidea Power Machinery Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
Zhejiang and Jiangsu production clusters in China anchor casting capacity for powerhead and gearcase assemblies, translating upstream metalworking scale into downstream pricing leverage for mid-range four-stroke and electric platforms. Brunswick Corporation's Mercury Marine brand and Yamaha Motor Co. Ltd command premium positioning through captive machining capabilities, while price-sensitive Southeast Asian markets absorb residual two-stroke inventory that compresses entry-level pricing floors.
Pricing Analysis
Geographic price spreads between North American premium four-stroke configurations and Southeast Asian two-stroke alternatives exceed factor-of-two differentials, with EPA Tier 3 certification requirements and EU F-Gas Regulation compliance costs driving stratification across premium, standard, and economy tiers. Brand premiums attached to Mercury Marine and Yamaha Motor distribution networks sustain pricing authority in above 100 HP segments, while lithium-ion pack cost curves compress electric platform premiums for commercial fishing operators. Price erosion runs through sub-25 HP combustion segments as municipal lake bans in Germany, Switzerland, and Austria redirect demand toward zero-emission alternatives. Rental fleet operators in Mediterranean and Caribbean charter markets exhibit lowest price sensitivity due to utilization-rate optimization priorities, whereas individual consumers in price-sensitive Asian markets resist four-stroke conversion timelines.
Supply Chain Analysis
Contract manufacturing concentration for power electronics and battery pack assembly rests on automotive-tier semiconductor fabricators in South Korea and Japan, with gearcase and powerhead casting operations drawing from Chinese primary aluminum smelters in Henan and Shandong provinces. Critical input dependencies span lithium carbonate from Chile and Australia, rare earth magnets for brushless DC motors from China, and high-strength aluminum alloys for marine-grade corrosion resistance. Single-source vulnerability concentrates in Chinese aluminum smelter energy-price exposure and export quota volatility. Distribution runs through traditional dealer networks in United States Southeast and Great Lakes regions, direct-to-consumer digital platforms in Australian metropolitan areas, and flagship store formats consolidating in Florida, Queensland, and the French Riviera.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through boat manufacturer OEM bundling agreements and rental fleet operator consolidation, fragmenting pricing leverage across individual consumers and small commercial operators.
For Market Incumbents: Pre-empt electric platform displacement by locking marina charging infrastructure partnerships in Japan and Australia before range-confidence gaps harden competitive barriers. Secure captive aluminum alloy supply through backward integration into Zhejiang casting clusters or long-term offtake agreements with Chinese smelters, insulating margins from energy-price volatility. Defend against automotive-tier semiconductor fabricators encroaching on marine power electronics by deepening technical integration support with OEM boat builders. For New Entrants and Emerging Players: Build out white-space positioning in Brazilian coastal municipalities along Rio de Janeiro and São Paulo state coastlines, where underpenetrated recreational boating infrastructure offers first-mover rental fleet electrification opportunities. Target sub-25 HP electric platforms for German, Swiss, and Austrian lake municipalities enforcing combustion bans, leveraging EU Green Deal Maritime funding for pilot deployment subsidies. Pursue direct-to-consumer digital platforms capturing younger demographic segments in United States and Australian markets, bypassing traditional dealer network establishment costs. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-transition play because EPA marine emissions standards and EU F-Gas Regulation phase-down schedules guarantee replacement demand cycles regardless of macroeconomic volatility. Acquisition targets should emphasize electric platform specialists with automotive-tier semiconductor sourcing relationships and integrated motor-controller-battery system capabilities. Monitor lithium-ion pack cost curve trajectories and marina electrical upgrade deployment rates as dual inflection indicators for electric adoption acceleration versus combustion resilience.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Zhejiang and Jiangsu | Domestic Chinese lake recreation and export OEM contracts simultaneously served through casting cluster scale. |
| Backward Integration into Aluminum Supply | Henan and Shandong smelter relationships reduce exposure to energy-price volatility and export quota shifts. |
| Marina Charging Infrastructure Partnership | Tokyo Bay and Osaka coastal electrical upgrades address range-confidence gaps constraining electric adoption. |
| Direct-to-Consumer Platform Launch | Sydney and Melbourne metropolitan digital sales bypass traditional dealer networks capturing younger demographics. |
| EU Green Deal Maritime Funding Access | Commercial ferry hydrogen fuel-cell range extender pilots subsidized through dedicated innovation grants. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with marine propulsion engineering directors, OEM boat manufacturer procurement leads, rental fleet operations managers, aftermarket parts distributors, and marina infrastructure developers. Secondary validation drew from EPA marine engine certification databases, EU F-Gas Regulation implementation reports, Japan METI efficiency benchmark filings, China MEE emissions protocol documentation, and ISO marine propulsion standard technical specifications. Bottom-up vessel registration data and top-down manufacturing capacity assessments were triangulated to reconcile demand and supply-side perspectives.
Calibration across the projection horizon employed multi-dimensional segmentation modeling spanning propulsion technology type, application intensity, output power band, and procurement channel structure. CAGRs were derived from replacement cycle analysis, fleet turnover rates under tightening emissions standards, and electric platform cost-parity trajectory modeling. Industry-specific forecast inputs incorporated lithium-ion pack cost curve projections, marina electrical infrastructure deployment schedules, and aluminum alloy price volatility scenarios.
Stress conditions across battery cell supply disruptions, Chinese aluminum export quota restrictions, and accelerated EPA combustion phaseout timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and charging infrastructure investment continuity. Quarterly review of marina electrical upgrade permitting data and lithium carbonate spot price movements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Tugboat Market
Marine Vehicles
Marine Electric Vehicle Market
Marine Vehicles
Global Luxury Boat Market
Marine Vehicles
Outboard Boats Market
Marine Vehicles
Marine Boat Passenger Seat Market
Marine Vehicles
Airboats Market
Marine Vehicles
Marine Propulsion Engine Market
Marine Vehicles
Outboard Engines Market
Marine Vehicles
Air-Cushion Vehicle Market
Marine Vehicles
Small Boats Market
Marine Vehicles
LNG Marine Engine Market
Marine Vehicles
Cargo Vessel Market
Marine Vehicles
Global Catamaran Market
Marine Vehicles
Europe Inland Waterways Vessel Market
Marine Vehicles
Asean Boat Davits Market
Marine Vehicles
Yacht Market