
 AI in-Vehicle Surveillance Market | 2026-2036
AI in-Vehicle Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
AI in-Vehicle Surveillance Market Insights
Subscription-based fleet surveillance leasing is reshaping competitive access for mid-tier logistics providers. Robert Bosch GmbH leverages its tier-1 automotive supply relationships to anchor embedded camera module production. Dahua Technology competes through aftermarket channel density across commercial vehicle segments. Qualcomm Incorporated differentiates by supplying edge-AI silicon that sustains real-time inference without cloud dependency.
AI in-vehicle surveillance encompasses camera arrays, biometric sensors, and edge computing units that process occupant behavior, vehicle perimeter activity, and cabin security events within milliseconds. The systems fuse infrared imaging with millimeter-wave radar to maintain detection accuracy through darkness, glare, and partial occlusion for commercial fleet safety and law enforcement evidence capture. Computer vision dominates current deployment volumes as established algorithms satisfy regulatory minimums for drowsiness detection, while deep learning segments attract development investment for predictive anomaly recognition. Fleet management applications generate the most concentrated demand volume, though driver monitoring commands premium pricing due to OEM integration complexity and type-approval requirements.
The EU AI Act imposes conformity assessment obligations on biometric identification systems deployed in vehicles, while NHTSA guidelines in the United States shape voluntary performance benchmarks for driver distraction alerts. ECE R79 and ISO 26262 functional safety standards further constrain how machine learning models validate deterministic behavior for steering-critical interventions. Stakeholders must track divergence between European mandatory compliance and American guideline-based adoption when allocating R&D across regulatory jurisdictions.
Market Dynamics
The EU AI Act's risk classification framework for biometric identification in vehicles is forcing OEMs to restructure conformity assessment workflows before embedded camera modules reach production lines. Fleet operators simultaneously demand real-time edge inference to reduce liability exposure from driver distraction incidents.
Growth Catalysts
- EU AI Act biometric mandates:The regulation's high-risk system classification for driver monitoring creates mandatory compliance pull-through for embedded camera modules and edge-AI silicon in passenger vehicles.
- Commercial fleet liability reduction:Logistics operators deploy cabin-facing camera arrays to generate timestamped evidence for insurance claims and driver coaching protocols.
- Edge computing latency requirements:Sub-100 millisecond inference demands for steering-critical interventions push processing from cloud to vehicle-mounted units.
Market Restraints
- Automotive-grade sensor cost premiums:Infrared imaging modules with ISO 26262 ASIL-B certification carry 3-4x cost multiples versus consumer-grade alternatives.
- Foundry capacity concentration:Advanced node semiconductor fabrication for neural processing units concentrates in Taiwan, creating supply vulnerability for edge-AI chipsets.
- Millimeter-wave radar interference:Cabin-mounted radar sensors face signal degradation from metallic vehicle structures and competing automotive radar systems.
Strategic Opportunities
- India commercial vehicle retrofit channel:Aftermarket installation of driver monitoring systems in existing truck fleets bypasses OEM integration timelines and type-approval bottlenecks.
- Occupant health vital sign monitoring:Fusion of infrared thermography with radar micro-Doppler signatures enables cardiac and respiratory tracking for autonomous vehicle handover readiness.
- Subscription-based fleet leasing:Hardware-as-a-service models reduce upfront capital barriers for mid-tier logistics providers accessing enterprise-grade surveillance capabilities.
Industry Challenges
- Functional safety validation timelines:ISO 26262 ASIL-D certification for steering-intervention systems extends development cycles by 18-24 months.
- Computer vision engineering scarcity:Specialized talent for automotive embedded vision pipelines concentrates in Germany and China, constraining R&D scaling elsewhere.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in-Vehicle Surveillance Market |
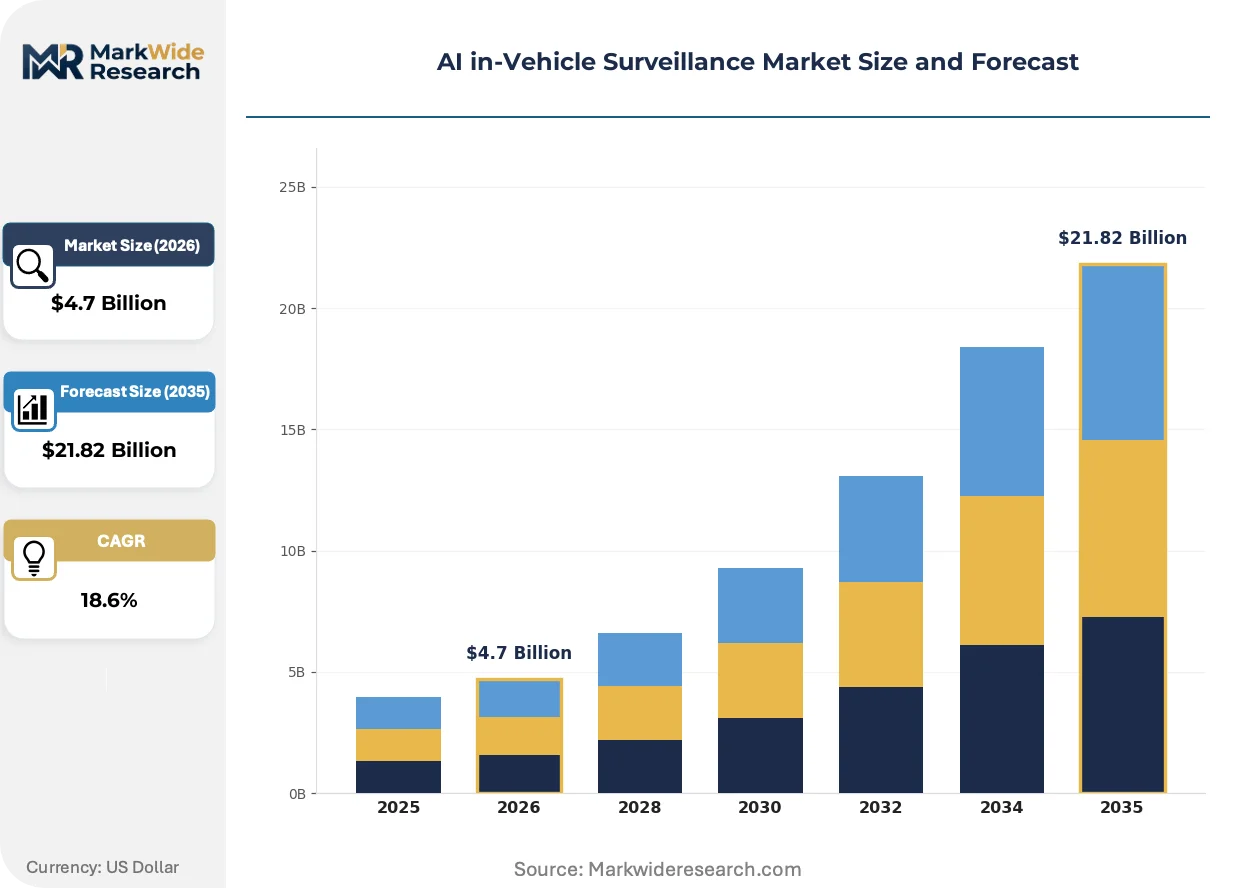
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Computer Vision, Sensor Fusion, Machine Learning, Deep Learning Application: Driver Monitoring, Fleet Management, Security Systems, Accident Detection End User: OEMs, Insurance Companies, Fleet Operators, Law Enforcement Feature: Real-time Analytics, Alerts, Data Recording, Remote Monitoring |
| Companies Covered | Robert Bosch GmbH, Dahua Technology, Qualcomm Incorporated, Eyeris Technologies Inc., Seeing Machines, Advantech Co. Ltd, Continental AG, Valeo, ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in-Vehicle Surveillance Market Trends and Innovations
Edge-AI silicon architectures are compressing the latency-performance tradeoff that previously forced fleet operators toward cloud-dependent surveillance systems. Three developments are restructuring competitive positioning across hardware and software layers.
Neural processing units with dedicated tensor cores are rendering obsolete the general-purpose GPU architectures that dominated early autonomous vehicle prototyping. Tier-1 suppliers now specify NPU-integrated system-on-chips for production vehicle platforms. The shift compresses bill-of-materials costs while sustaining real-time multi-object detection.
The EU AI Act's conformity assessment obligations for biometric identification systems are restructuring OEM validation workflows. Manufacturers must document algorithmic transparency and bias mitigation before type approval. German automotive suppliers have established dedicated AI governance offices to manage regulatory submission timelines.
Leasing-based procurement for fleet surveillance hardware is displacing capital purchase models among mid-tier logistics operators. Monthly per-vehicle fees bundle hardware, software licenses, and over-the-air updates. The pattern concentrates in North American long-haul trucking where asset turnover cycles compress technology refresh decisions.
AI in-Vehicle Surveillance Market Segmentation
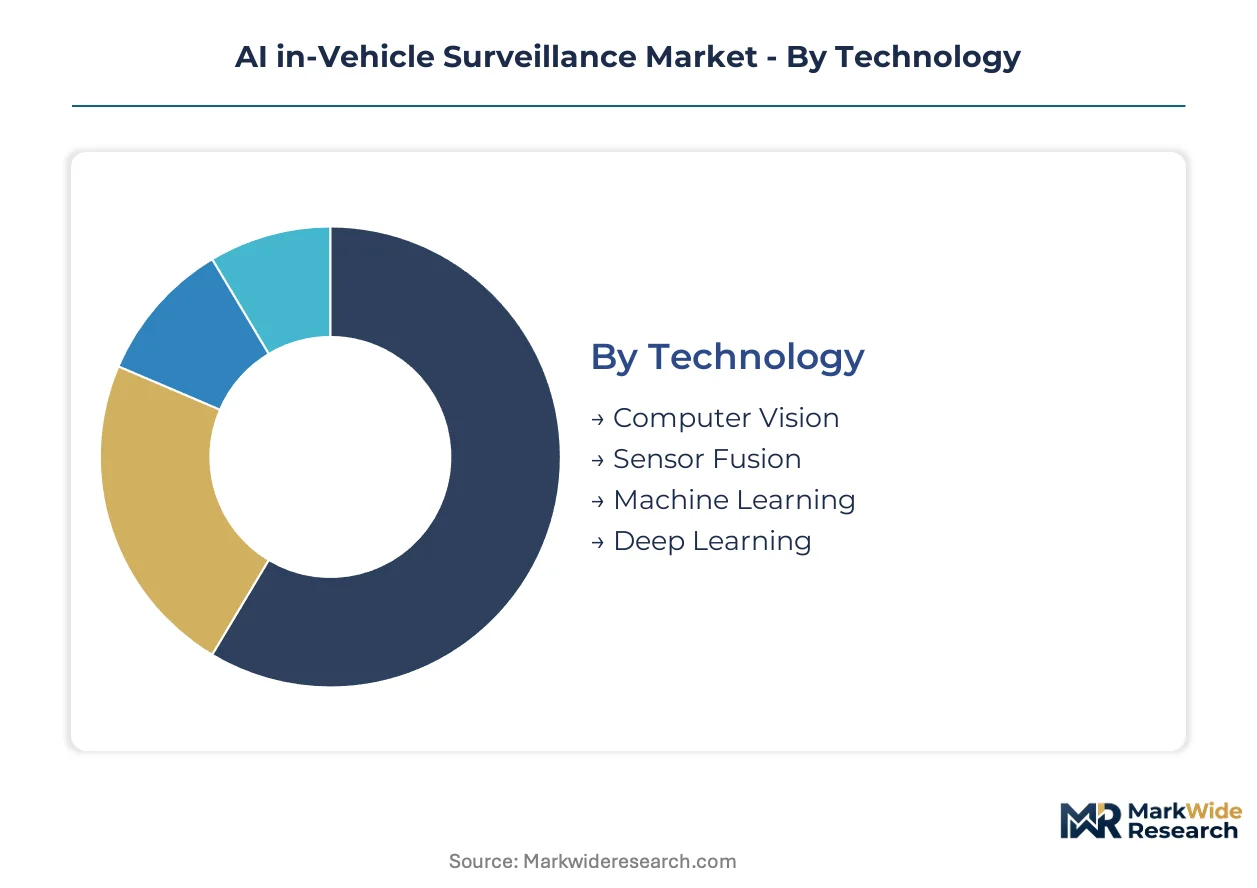
Technology choice dictates refresh cycles across the AI in-vehicle surveillance value chain. Edge-AI silicon obsolescence accelerates faster than mechanical sensor platforms, fragmenting procurement timing between hardware tiers.
Technology:
Cycle times diverge sharply: deep learning models retrain quarterly, while sensor fusion hardware endures multi-year automotive qualification timelines.
- Computer Vision:Established algorithms process optical camera feeds for drowsiness detection and lane departure warnings. Germany anchors deployment volume as KBA type-approval requirements favor proven image recognition pipelines over experimental architectures.
- Deep Learning:Neural networks enable predictive anomaly recognition beyond rule-based detection thresholds. Edge-AI chipsets from Qualcomm and Ambarella sustain real-time inference for cabin behavior classification without cloud dependency.
- Sensor Fusion:Millimeter-wave radar combined with infrared imaging maintains detection accuracy through darkness and partial occlusion.
- Machine Learning:Statistical pattern recognition supports occupancy counting and gesture classification with lower computational overhead than deep neural approaches.
Computer Vision dominates installed base. Deep Learning is where expansion concentrates.
Application:
Cost tier separation runs from premium OEM-integrated driver monitoring to aftermarket fleet retrofit packages.
- Driver Monitoring:Cabin-facing camera arrays with biometric analysis command premium pricing due to ISO 26262 functional safety certification and steering-critical intervention requirements. EU AI Act high-risk system classification tightens conformity assessment workflows for passenger vehicle deployments.
- Fleet Management:Commercial vehicle operators generate concentrated demand volume through subscription-based hardware leasing that bundles real-time coaching and timestamped incident evidence.
- Security Systems:Perimeter surveillance and cabin intrusion detection serve law enforcement evidence capture and high-value cargo protection.
- Accident Detection:Automated collision classification and emergency response triggering integrate with vehicle telematics platforms.
Driver Monitoring captures margin concentration. Fleet Management is climbing the fastest.
End User:
Customer type determines procurement authority and integration complexity across the value chain.
- OEMs:Vehicle manufacturers specify embedded camera modules and edge-AI silicon during platform development, locking suppliers into 5-7 year production cycles.
- Fleet Operators:Logistics providers bypass OEM integration timelines through aftermarket installation, accelerating technology refresh decisions.
- Insurance Companies:Underwriters deploy surveillance hardware to reduce claim dispute costs and enable usage-based premium pricing.
- Law Enforcement:Police agencies require tamper-evident data recording and chain-of-custody protocols for evidentiary admissibility.
OEMs anchor long-term supply agreements. Fleet Operators are gaining share fastest.
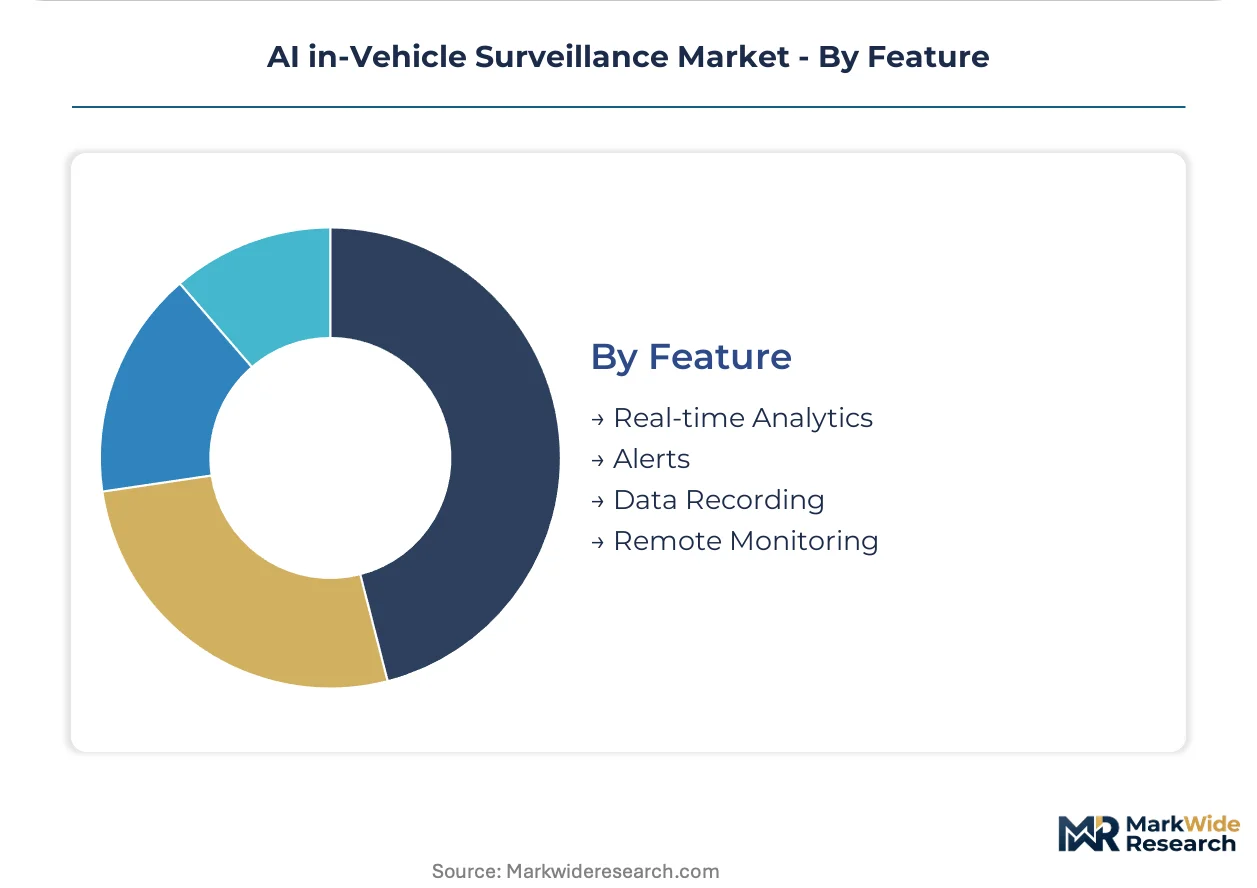
Feature:
Functional maturity separates proven capabilities from emerging value-added services.
- Real-time Analytics:Sub-100 millisecond edge processing enables steering-critical interventions without cloud latency exposure.
- Data Recording:Tamper-evident storage with cryptographic integrity verification supports insurance claims and legal proceedings.
- Alerts:Audio-visual driver warnings and fleet dispatcher notifications trigger coaching protocols and incident response.
- Remote Monitoring:Cellular-connected live video streaming extends surveillance reach beyond vehicle-local processing constraints.
Data Recording dominates regulatory compliance specifications. Real-time Analytics is where capability investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive suppliers extract premium pricing for ISO 26262-certified camera modules, while Indian retrofit installers compete on hardware cost minimization for commercial truck fleets. This pricing-power asymmetry shapes regional deployment patterns across the value chain.
Germany
KBA type-approval requirements and EU AI Act conformity assessments drive embedded system demand from Stuttgart and Munich automotive clusters. The EU AI Act's high-risk biometric classification mandates algorithmic transparency documentation before production deployment. Continental AG and Robert Bosch GmbH anchor development in Baden-Württemberg and Bavaria, integrating edge-AI silicon into production vehicle platforms.
United States
NHTSA voluntary distraction-alert guidelines shape fleet operator procurement for long-haul trucking corridors across Texas and California. The Federal Motor Carrier Safety Administration hours-of-service rules incentivize timestamped driver evidence systems. Detroit's tier-1 supplier ecosystem and Silicon Valley edge-AI semiconductor development create a bifurcated regional value chain.
China
Domestic commercial vehicle production volume and MIIT intelligent vehicle standards accelerate cabin-facing camera adoption in heavy truck manufacturing. GB standards for driver monitoring systems establish baseline technical requirements for domestic OEMs. Yangtze River Delta electronics manufacturing clusters supply infrared imaging modules to both domestic brands and export markets.
India
Commercial fleet retrofit demand bypasses OEM integration timelines for existing truck populations along Mumbai-Delhi freight corridors. The Automotive Research Association of India facilitates component homologation for aftermarket driver monitoring installations. Tamil Nadu and Maharashtra manufacturing zones produce cost-optimized camera arrays for domestic logistics operators and African export markets.
Japan
METI autonomous vehicle roadmaps integrate occupant health monitoring for handover readiness in aging-driver populations. JIS standards for automotive cameras constrain supplier qualification to established domestic electronics manufacturers. Nagoya's automotive supplier concentration and Tokyo's imaging sensor development sustain integrated domestic supply chains.
AI in-Vehicle Surveillance Market Competitive Landscape
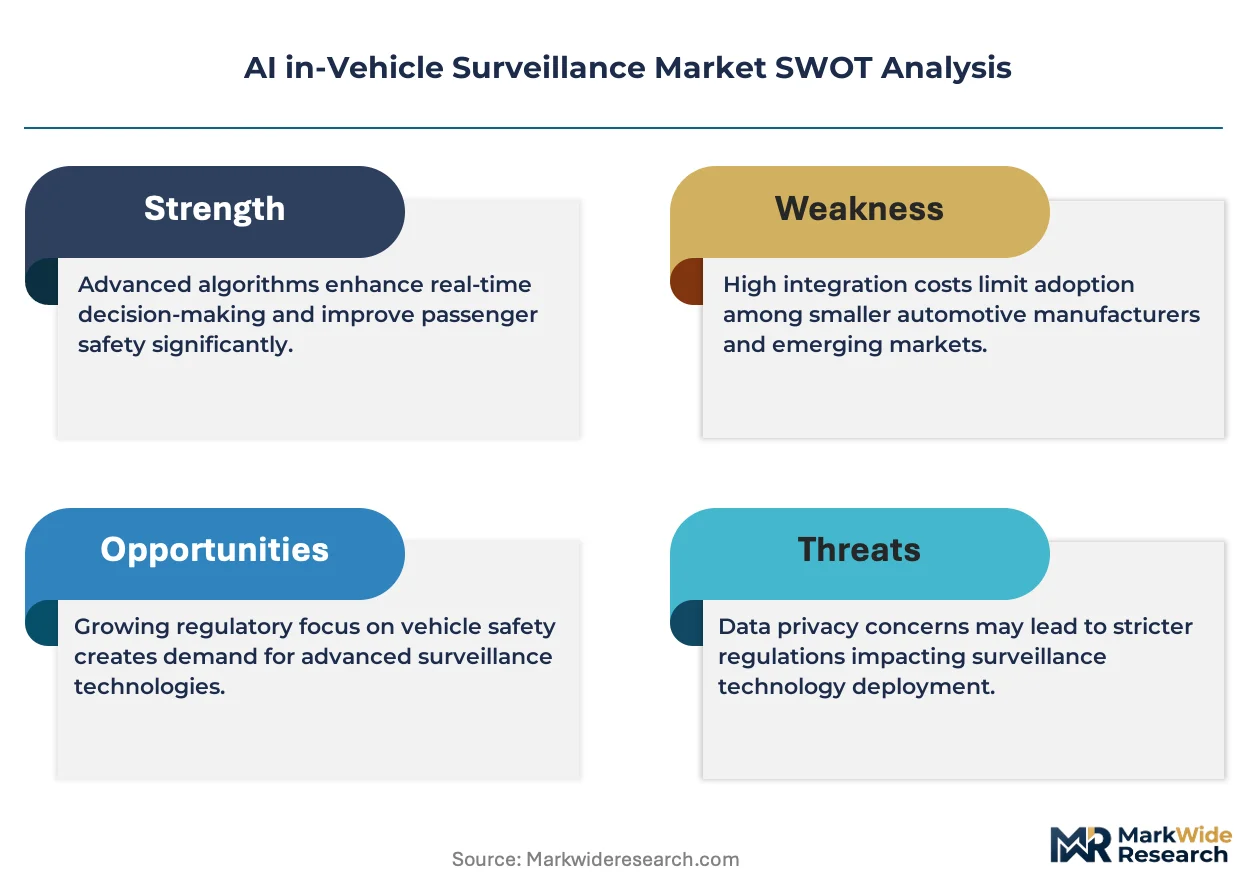
Platform integrators command the system tier; component specialists sit upstream supplying camera modules and edge-AI silicon. The market exhibits tiered consolidation with tier-1 automotive suppliers locking OEM production cycles against aftermarket retrofit specialists serving fleet operators. Two strategic archetypes dominate: embedded system integrators with ISO 26262 certification capabilities, and edge-AI semiconductor suppliers with neural processing unit architectures. Competitive moves concentrate on strategic partnerships between tier-1 suppliers and semiconductor vendors, plus capacity expansion in automotive-grade sensor fabrication.
Within the embedded system integrator tier, Robert Bosch GmbH and Continental AG exemplify tier-1 suppliers leveraging automotive supply relationships for production platform integration. Qualcomm Incorporated occupies a position at the semiconductor tier supplying neural processing units for real-time edge inference. Seeing Machines represents the specialized driver monitoring archetype with biometric algorithm development focus. These three anchors illustrate how competitive positioning fragments across hardware tiers rather than consolidating around full-stack solutions.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Dahua Technology |
| Qualcomm Incorporated |
| Eyeris Technologies Inc. |
| Seeing Machines |
| Advantech Co. Ltd |
| Continental AG |
| Valeo |
| ZF Friedrichshafen AG |
| Others |
Pricing and Supply Chain Analysis
Foundry undercapacity in Taiwan is compressing edge-AI silicon availability and amplifying pricing power for automotive-grade neural processing units, while simultaneously forcing tier-1 suppliers toward longer-term contract structures to secure wafer allocation.
Pricing Analysis
The customization-premium spread between configured-to-order embedded systems and standard aftermarket modules exceeds threefold in the AI in-vehicle surveillance market. Subscription-based hardware-as-a-service models dominate fleet management procurement, while OEM-integrated driver monitoring commands premium pricing due to ISO 26262 ASIL-B certification requirements and algorithmic transparency documentation mandated by the EU AI Act. Cost compression in consumer-grade camera arrays is intensifying because Chinese electronics manufacturers are scaling infrared imaging module production for domestic commercial vehicle retrofit channels. Mid-tier logistics operators exhibit the highest price sensitivity, whereas premium passenger vehicle OEMs prioritize functional safety validation over unit economics.
Supply Chain Analysis
Contract manufacturing concentration rests with Taiwan Semiconductor Manufacturing Company and Samsung Foundry for advanced node neural processing units, while Yangtze River Delta electronics clusters handle infrared imaging module assembly. The supply chain draws from germanium substrates for thermal optics, automotive-grade CMOS sensors from Japan, and specialized ASIC design services concentrated in Germany and the United States. Single-source vulnerability in Taiwan-based foundry capacity creates exposure for edge-AI chipset procurement timelines. Distribution runs through tier-1 automotive supplier networks for OEM-integrated systems and direct aftermarket channels for fleet retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AI in-vehicle surveillance market represents a service-attach opportunity where over-the-air software update revenues and predictive maintenance subscriptions are expanding faster than hardware bill-of-materials, rewarding suppliers who bundle recurring capabilities with initial sensor deployments.
For Market Incumbents: Insulate embedded system margins by deepening backward integration into automotive-grade infrared sensor fabrication and securing exclusive edge-AI silicon allocation agreements with Taiwan-based foundries. The threat of Chinese aftermarket retrofit specialists commoditizing camera module hardware necessitates ISO 26262 certification investment as a differentiation lever. Channel control through tier-1 supplier relationships locks OEM production cycles against price erosion. For New Entrants and Emerging Players: Build out white-space presence in India's commercial vehicle retrofit channel, where aftermarket driver monitoring installations bypass OEM integration timelines and type-approval bottlenecks. The most penetrable segment is mid-tier logistics operators seeking subscription-based hardware leasing without upfront capital commitment. A software-first go-to-market angle emphasizing edge-AI inference customization for regional fleet coaching protocols accelerates customer acquisition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across edge-AI semiconductor design houses as automotive qualification timelines extend development cycles. Long-term viability over the next decade hinges on securing foundry capacity allocation and navigating EU AI Act conformity assessment workflows. Acquisition targets should exhibit neural processing unit architecture differentiation and established automotive OEM validation relationships. The signal to watch is KBA type-approval submission volumes from German tier-1 suppliers as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Silicon Partnership | Qualcomm's NPU supply to Robert Bosch GmbH accelerates real-time inference without cloud dependency. |
| Subscription Model Expansion | Hardware-as-a-service bundling reduces capital barriers for North American long-haul trucking operators. |
| EU AI Act Compliance Investment | Continental AG's dedicated AI governance office manages algorithmic transparency documentation timelines. |
| Retrofit Channel Penetration | Dahua Technology's aftermarket density across commercial segments bypasses OEM integration constraints. |
| Functional Safety Certification | ISO 26262 ASIL-D validation for steering-critical interventions extends supplier lock-in with OEMs. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with tier-1 supplier procurement directors, OEM platform engineers, aftermarket fleet distributors, and edge-AI semiconductor product managers; and secondary validation against SEC 10-K filings, vehicle production databases from IHS Markit, KBA type-approval registries, and EU AI Act implementation guidance documents. Bottom-up triangulation across sensor shipment volumes and top-down reconciliation against automotive electronics content per vehicle estimates anchored market sizing.
Forecast inputs considered technology adoption curves across computer vision, deep learning, and sensor fusion segments; application penetration rates for driver monitoring versus fleet management; and end-user procurement authority shifts between OEMs and aftermarket operators over the projection horizon. CAGRs were derived from regression analysis of historical automotive electronics adoption patterns and regulatory mandate implementation timelines. Edge-AI silicon price erosion trajectories and infrared imaging module cost curves informed hardware tier projections.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese aftermarket specialists or accelerated EU AI Act enforcement timelines would shift outcomes. Quarterly review of KBA type-approval submission volumes, Taiwan foundry utilization rates, and commercial vehicle retrofit installation data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Acoustic Vehicle Alerting System Market
Automotive Safety and Security Systems
Global Automotive Knee Airbags Market
Automotive Safety and Security Systems
Automotive Airbag Gas Generators Market
Automotive Safety and Security Systems
China Airbag Systems Market
Automotive Safety and Security Systems
Automotive Battery Pack Fire Barrier Pad Market
Automotive Safety and Security Systems
Car Camera Cleaning Systems Market
Automotive Safety and Security Systems
Driving Armor Market
Automotive Safety and Security Systems
Automotive Biometric Access System Market
Automotive Safety and Security Systems
Driver Alert System Market
Automotive Safety and Security Systems
Automotive TPMS Market
Automotive Safety and Security Systems
Whiplash Protection System Market
Automotive Safety and Security Systems
Occupant Classification System Market
Automotive Safety and Security Systems
Global Automotive Terrain Response System Market
Automotive Safety and Security Systems
North America Airbag Systems Market
Automotive Safety and Security Systems
Global Emergency Locking Retractor Seatbelt Market
Automotive Safety and Security Systems
Automotive Airbag Inflator Market