
 Offshore AUV and ROV Market | 2026-2036
Offshore AUV and ROV Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore AUV and ROV Market Intelligence
REACH compliance is rebalancing the cost-of-entry calculus for European offshore contractors by mandating stricter material traceability and environmental liability across subsea operations. Kongsberg Gruppen leverages its integrated sonar and navigation portfolio to dominate Nordic deepwater contracts. Oceaneering International sustains a formidable position in Gulf of Mexico intervention services through its specialized riserless light well intervention systems. Saab AB competes in defense-adjacent seabed warfare applications where dual-use technology credentials create asymmetric access.
Offshore AUV and ROV systems encompass untethered and tethered underwater robotic platforms typically rated for depths from 300 to 6,000 meters, propelled by electric thrusters and guided by inertial navigation fused with acoustic positioning for seafloor mapping, pipeline inspection, and subsea construction support in hydrocarbon and renewable energy sectors. Remotely Operated Vehicles retain the largest installed base due to mature hydraulic manipulator ecosystems and real-time operator control requirements in high-risk intervention tasks. Autonomous Underwater Vehicles represent the fastest-expanding product category as battery energy density improvements and AI-driven path planning reduce surface vessel dependency for repetitive survey missions.
The US Bureau of Safety and Environmental Enforcement and the UK Health and Safety Executive impose prescriptive integrity management rules that compel operators to deploy certified inspection-class vehicles on annual pipeline schedules. Norway's Petroleum Safety Authority and the EU F-Gas Regulation jointly pressure manufacturers toward electric propulsion architectures and refrigerant-free pressure vessel designs. Stakeholders must monitor how emerging seabed mining licensing frameworks in international waters reshape vehicle depth rating and autonomy specifications before committing to next-generation platform investments.
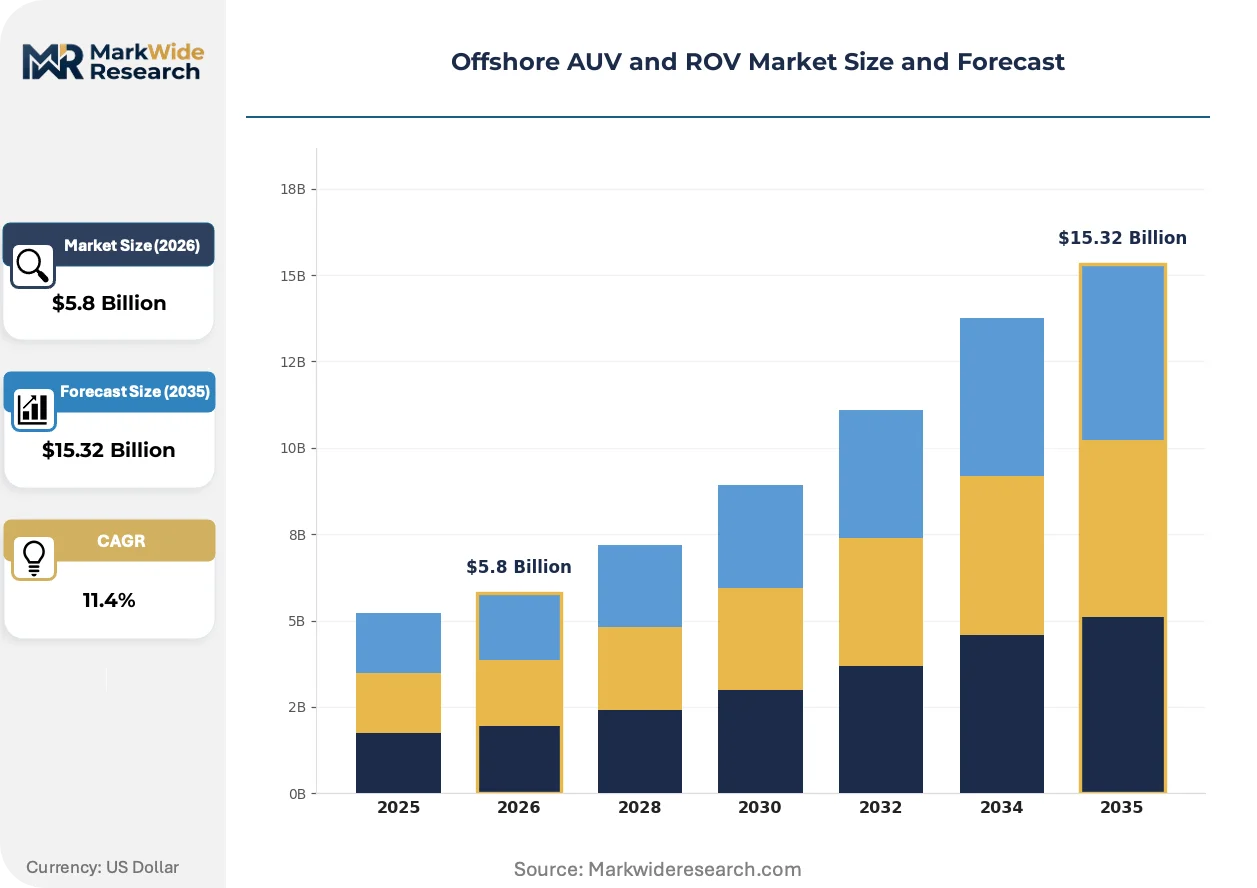
Market Dynamics
Electric propulsion architectures are displacing hydraulic systems across inspection-class vehicle fleets as Norway's Petroleum Safety Authority and the EU F-Gas Regulation jointly mandate refrigerant-free pressure vessel designs and emissions reductions in subsea operations.
Growth Catalysts
- EU decommissioning obligations:Tightening environmental directives under EU frameworks compel North Sea offshore wind developers to deploy inspection-class vehicles for seabed clearance and infrastructure removal, accelerating replacement cycles for aging ROV fleets.
- Battery energy density gains:Lithium-sulfur and solid-state cell chemistries extend AUV endurance beyond 72 hours, reducing surface vessel dependency for repetitive pipeline survey missions in deepwater hydrocarbon fields.
- Subsea construction support:Oil and gas operators in the Gulf of Mexico and North Sea require heavy-workclass ROVs for riser installation and wellhead intervention, sustaining demand for hydraulic manipulator ecosystems rated to 3,000 meters.
Market Restraints
- High-grade titanium alloy supply:Pressure hull fabrication depends on Ti-6Al-4V ELI sourced from a concentrated supplier base in Russia and China, exposing manufacturers to export control volatility and price spikes.
- Acoustic positioning infrastructure gaps:Ultra-short baseline systems require seabed transponder networks that remain sparse in frontier basins offshore West Africa and Southeast Asia, limiting AUV deployment economics.
- REACH compliance burden:ECHA-mandated material traceability for subsea umbilicals and tether compounds forces European contractors to requalify entire supply chains, extending procurement timelines by 8-14 months.
Strategic Opportunities
- Seabed mining licensing frameworks:International Seabed Authority draft regulations for polymetallic nodule extraction in the Clarion-Clipperton Zone will specify autonomous vehicle depth ratings exceeding 6,000 meters, creating first-mover specification advantages.
- Offshore wind installation growth:Germany, the United Kingdom, and Denmark require cable burial and scour protection services that favor hovering-capable ROVs with precision dredging tools over traditional plough systems.
- AI-driven path planning convergence:Machine learning-based obstacle avoidance fused with synthetic aperture sonar enables single-pass seabed mapping at resolutions previously requiring multiple survey lines, compressing charter durations.
Industry Challenges
- Subsea robotics technician scarcity:Deepwater hydraulic systems and inertial navigation calibration require specialized skills concentrated in Aberdeen, Stavanger, and Houston, constraining fleet expansion rates.
- Classification society certification timelines:DNV-ST-E273 and API RP 2D compliance for new vehicle platforms demands 18-24 months of sea trials, delaying revenue recognition for next-generation AUV programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore AUV and ROV Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $15.32 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Underwater Vehicles, Remotely Operated Vehicles, Hybrid ROVs, Inspection-Class Vehicles Technology: Sonar Imaging, Acoustic Positioning, Navigation Systems, Manipulator Arms, Sensor Integration Application: Seafloor Mapping, Pipeline Inspection, Subsea Construction Support, Environmental Monitoring, Search & Recovery End User: Oil & Gas Operators, Offshore Wind Developers, Subsea Engineering Firms, Marine Research Institutes |
| Companies Covered | Teledyne Technologies, BAE Systems, Kongsberg Gruppen, L3Harris Technologies, ECA Group, Oceaneering International, Fugro, TechnipFMC, Saab AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore AUV and ROV Market Strategic Shifts & Innovations
Autonomy algorithms and electric drivetrains are compressing the operational gap between tethered and untethered platforms, forcing incumbents to reposition service offerings around data deliverables rather than equipment deployment.
Synthetic aperture sonar payloads are expanding into commercial survey operations from their defense origins, enabling pipeline inspection contractors to detect millimeter-scale metal loss features at standoff distances exceeding 50 meters. Offshore wind developers in the North Sea are specifying these sensors for inter-array cable route surveys, reducing seabed disturbance permits. The technology is expanding into shallow-water applications previously dominated by multibeam echosounders, compressing equipment rental rates for conventional systems.
The EU F-Gas Regulation and Norway's Petroleum Safety Authority jointly prohibit hydrofluorocarbon refrigerants in pressure vessel cooling loops, compelling manufacturers to adopt thermoelectric or liquid-cooled architectures. This regulatory convergence accelerates electric thruster development programs previously stalled by thermal management constraints. Subsea intervention contractors operating in Norwegian and UK waters face accelerated obsolescence schedules for hydraulic work-class vehicles using legacy cooling circuits.
Charter contracting is consolidating around integrated survey packages that bundle AUV deployment, data processing, and regulatory submission deliverables into fixed-price agreements. Oil and gas majors in the Gulf of Mexico are displacing day-rate vessel charters with outcome-based contracts that transfer weather downtime risk to service providers. This model concentrates procurement authority with inspection-class vehicle operators capable of autonomous mission execution, marginalizing traditional ROV rental houses dependent on offshore personnel.
Offshore AUV and ROV Market Segmentation
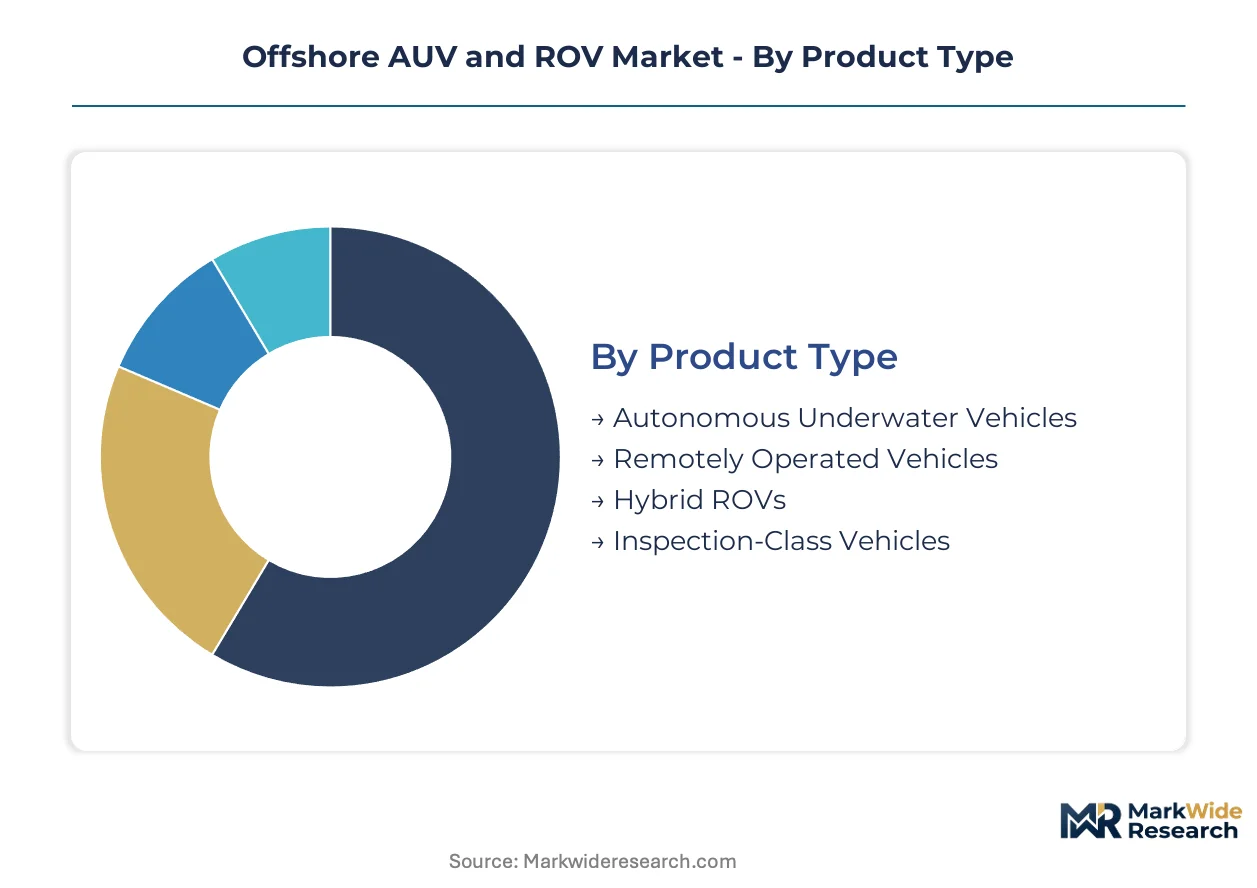
Segmentation in the Offshore AUV and ROV Market reveals how vessel architecture, sensor payload, and end-use mission profiles determine procurement priorities. Contractors select platforms based on depth rating, autonomy level, and regulatory certification requirements specific to hydrocarbon or renewable energy operations.
Product Type:
Volume concentrates in tethered work-class fleets, while premium margins flow toward untethered autonomous systems with extended endurance specifications.
- Autonomous Underwater Vehicles:Battery-powered untethered platforms rated to 6,000 meters, executing pre-programmed survey missions without surface vessel umbilical support. Offshore wind developers in the North Sea deploy AUVs for inter-array cable route surveys to minimize seabed disturbance permits and reduce charter durations.
- Remotely Operated Vehicles:Tethered hydraulic or electric platforms with real-time operator control, dominating subsea intervention tasks requiring manipulator precision. Gulf of Mexico oil and gas operators sustain demand for heavy-workclass ROVs in riser installation and wellhead intervention at depths to 3,000 meters.
- Hybrid ROVs:Dual-mode platforms switching between tethered intervention and limited autonomous operation for transit phases.
- Inspection-Class Vehicles:Compact electric systems optimized for pipeline integrity management under US Bureau of Safety and Environmental Enforcement annual schedules.
Today's leader: Remotely Operated Vehicles. Tomorrow's challenger: Autonomous Underwater Vehicles.
Technology:
Mission-critical performance hinges on acoustic and optical payload integration rather than propulsion hardware alone.
- Sonar Imaging:Synthetic aperture and multibeam systems enabling centimeter-scale seabed resolution at standoff distances exceeding 50 meters. Pipeline inspection contractors detect millimeter-scale metal loss features without seabed contact, compressing survey timelines.
- Acoustic Positioning:Ultra-short baseline and long-baseline transponder networks providing sub-meter navigation accuracy in GPS-denied environments. Sparse seabed infrastructure in frontier basins offshore West Africa constrains AUV deployment economics and limits addressable market scope.
- Navigation Systems:Inertial measurement units fused with Doppler velocity logs for dead-reckoning position updates.
- Manipulator Arms:Hydraulic and electric seven-function manipulators rated to 300-bar ambient pressure for subsea construction tasks.
- Sensor Integration:Multi-sensor fusion architectures combining bathymetry, sub-bottom profiler, and camera payloads.
Current procurement prioritizes Sonar Imaging. Acoustic Positioning infrastructure gaps present the binding constraint on autonomous mission expansion.
Application:
Recurring regulatory mandates drive inspection volumes, while episodic construction projects concentrate fleet utilization in specific basins.
- Seafloor Mapping:High-resolution bathymetric survey for route planning and hazard identification across hydrocarbon and wind farm developments. Norway's Petroleum Safety Authority mandates pre-installation seabed surveys for all subsea infrastructure placements.
- Pipeline Inspection:Annual integrity assessments compelled by US Bureau of Safety and Environmental Enforcement and UK Health and Safety Executive prescriptive rules. Operators deploy certified inspection-class vehicles on fixed schedules, creating predictable demand cycles for service contractors.
- Subsea Construction Support:Heavy intervention tasks including riser installation, wellhead tie-in, and decommissioning operations.
- Environmental Monitoring:Baseline and post-construction seabed surveys for regulatory compliance and impact assessment.
- Search & Recovery:Emergency response missions for equipment retrieval or wreckage location.
Pipeline Inspection generates the steadiest revenue stream. Subsea Construction Support delivers the highest day-rate premiums during project execution windows.
End User:
Oil and gas majors anchor fleet utilization, while offshore wind developers represent the fastest-expanding customer category with distinct technical specifications.
- Oil & Gas Operators:Integrated majors and independents requiring continuous ROV availability for production facility maintenance and drilling support. Gulf of Mexico and North Sea operators contract integrated survey packages bundling deployment, processing, and regulatory submission deliverables.
- Offshore Wind Developers:European utilities and project sponsors in Germany, the United Kingdom, and Denmark specifying hovering-capable ROVs with precision dredging tools for cable burial and scour protection services.
- Subsea Engineering Firms:EPCI contractors and installation specialists leasing vehicles on project-specific charters.
- Marine Research Institutes:Academic and government oceanographic programs utilizing AUVs for deep-sea exploration and climate monitoring.
Oil & Gas Operators command current fleet capacity. Offshore Wind Developers are gaining share fastest as North Sea installation pipelines accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Subsea robotics technicians cluster in Aberdeen, Stavanger, and Houston, anchoring the industry's geographic footprint around deepwater hydrocarbon basins and North Sea wind development corridors.
Norway
Deepwater field developments in the Norwegian Continental Shelf sustain demand for heavy-workclass ROVs in riser installation and subsea tie-in operations. The Petroleum Safety Authority mandates refrigerant-free pressure vessel designs and electric propulsion architectures under joint pressure with the EU F-Gas Regulation. Kongsberg Gruppen dominates Nordic deepwater contracts from its Kongsberg base, leveraging integrated sonar and navigation portfolios.
United Kingdom
North Sea decommissioning obligations under EU environmental directives accelerate replacement cycles for aging ROV fleets among offshore wind developers. The UK Health and Safety Enforcement imposes prescriptive integrity management rules compelling annual pipeline inspection schedules. Aberdeen concentrates technician expertise and service contractor headquarters for inspection-class vehicle operations.
United States
Gulf of Mexico oil and gas operators sustain demand for riserless light well intervention systems and heavy-workclass ROVs at depths to 3,000 meters. The US Bureau of Safety and Environmental Enforcement mandates certified inspection-class vehicles on fixed annual pipeline schedules. Houston anchors the industry's Western Hemisphere service hub, with contractors displacing day-rate vessel charters in favor of outcome-based agreements.
Germany
Offshore wind installation pipelines in the North Sea and Baltic Sea require cable burial and scour protection services favoring hovering-capable ROVs with precision dredging tools. REACH compliance mandates stricter material traceability for subsea umbilicals, forcing contractors to requalify entire supply chains. Northern port cities concentrate demand for inter-array cable route surveys using synthetic aperture sonar payloads.
China
Deep-sea exploration programs and seabed mining research initiatives drive AUV development for depths exceeding 6,000 meters. The country's national maritime regulator pressures manufacturers toward domestic pressure hull fabrication capabilities amid concentrated titanium alloy supply from external sources. Qingdao and Shanghai host research institutes and emerging vehicle assembly operations targeting international seabed mining licensing frameworks.
Offshore AUV and ROV Market Key Industry Players
The competitive structure tilts toward integrated technology conglomerates with defense-adjacent seabed warfare credentials. Market concentration reflects high barriers in acoustic positioning, inertial navigation, and pressure-rated fabrication. Three archetypes dominate: Nordic integrated sonar-navigation houses, US-Gulf intervention specialists with riserless systems, and European survey contractors bundling data deliverables. Consolidation pressures favor M&A around autonomy software stacks and strategic partnerships for frontier basin acoustic infrastructure.
Among Nordic integrated technology providers, Kongsberg Gruppen occupies a position exemplifying the sonar-navigation bundling archetype, while Saab AB sits within the defense-adjacent seabed warfare tier where dual-use credentials create asymmetric market access. Oceaneering International represents the Gulf of Mexico intervention specialist model, anchoring the heavy-workclass service segment through established riserless light well intervention positioning. These three companies illustrate how geographic origin and corporate structure shape competitive differentiation in a field where classification society certification timelines and technician scarcity constrain fleet expansion rates.
| Leading Market Players |
|---|
| Teledyne Technologies |
| BAE Systems |
| Kongsberg Gruppen |
| L3Harris Technologies |
| ECA Group |
| Oceaneering International |
| Fugro |
| TechnipFMC |
| Saab AB |
| Others |
Cost & Logistics Intelligence
EU F-Gas Regulation mandates for refrigerant-free pressure vessel designs are forcing contractors to absorb requalification costs across subsea umbilical supply chains, compressing margins on legacy hydraulic work-class vehicles while elevating premiums for certified electric architectures. This specification shift concentrates pricing power with integrated manufacturers capable of in-house thermal management system redesign.
Pricing Analysis
Bundled integrated survey packages displace day-rate vessel charters across Gulf of Mexico and North Sea operations, transferring weather downtime risk to service providers. Three-tier pricing structure across premium, standard, and economy levels stratifies by autonomy level and sensor payload sophistication, with AI-driven path planning capabilities commanding substantial premiums. Pricing pressure stems from charter contracting consolidation around outcome-based agreements, compressing equipment rental rates for conventional multibeam echosounder systems. Offshore wind developers exhibit highest price sensitivity due to project finance constraints, while oil and gas majors prioritize mission assurance over unit cost minimization.
Supply Chain Analysis
Refurbishment flows for pressure hull components and inertial navigation units create secondary supply channels that extend platform service life and moderate new-build demand cyclicality. Ti-6Al-4V ELI titanium alloy sourcing draws from concentrated supplier bases in Russia and China, exposing manufacturers to export control volatility and price spikes. Acoustic positioning transponder networks, lithium-sulfur battery cells, and synthetic aperture sonar arrays constitute critical component dependencies. Single-source vulnerability in high-grade titanium supply presents the dominant structural risk. Distribution runs through Aberdeen, Stavanger, and Houston service hubs that cluster technician expertise and spare parts inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by offshore wind developers specifying hovering-capable ROVs with precision dredging tools over traditional plough systems, elevating technical certification requirements across procurement criteria.
For Market Incumbents: Extend electric propulsion development programs to preempt obsolescence of hydraulic work-class vehicles under Norway Petroleum Safety Authority and EU F-Gas Regulation convergence. Acquire autonomy software stacks to defend against AI-driven path planning specialists threatening integrated survey package margins. Deepen backward integration into pressure hull fabrication to mitigate Ti-6Al-4V ELI supply concentration risk. For New Entrants and Emerging Players: Solid-state battery chemistry expertise offers a technology-first wedge into AUV endurance extension segments where lithium-sulfur cell development lags specification requirements. Target frontier basin acoustic positioning infrastructure gaps offshore West Africa and Southeast Asia where sparse seabed transponder networks limit incumbent deployment economics. Pursue joint venture structures with established classification societies to compress DNV-ST-E273 certification timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with autonomy algorithm developers possessing seabed mining depth rating specifications exceeding 6,000 meters ahead of International Seabed Authority licensing frameworks. Five-to-ten year viability hinges on electric architecture transition completion and technician training pipeline adequacy. Acquisition candidates include electric thruster specialists and synthetic aperture sonar payload integrators. Monitor International Seabed Authority draft regulation publication timing for autonomous vehicle specification inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Architecture Transition | Preempts regulatory obsolescence under EU F-Gas and Norway PSA mandates. |
| Autonomy Software Acquisition | Compresses charter durations through AI-driven path planning integration. |
| Seabed Mining Specification Development | Creates first-mover advantage in Clarion-Clipperton Zone licensing frameworks. |
| Acoustic Infrastructure Partnership | Addresses positioning gaps constraining AUV economics in frontier basins. |
| Technician Training Pipeline Investment | Alleviates scarcity constraints concentrated in Aberdeen, Stavanger, Houston clusters. |
Research Approach
Bottom-up offshore operator deployment modeling reconciled against top-down vessel manufacturer order book tracking forms the analytical core of this study. Primary interviews with ROV operations managers, subsea engineering directors, offshore wind project developers, and classification society surveyors combine with secondary validation through US Bureau of Safety and Environmental Enforcement incident databases, UK Health and Safety Executive inspection records, Norway Petroleum Safety Authority audit disclosures, and EU F-Gas Regulation implementation guidance. Triangulation across these sources ensures segmentation integrity across product type, technology, application, and end-user dimensions.
Historical trendline analysis of charter contracting patterns, vessel day-rate movements, and platform replacement cycles informs projection modeling across the analysis window. Segmentation dimensions include propulsion architecture, autonomy level, depth rating tier, sensor payload category, and regional regulatory cluster. CAGRs derive from weighted average of bottom-up deployment forecasts and top-down capital expenditure tracking. Industry-specific inputs encompass battery energy density improvement curves, acoustic positioning infrastructure deployment schedules, and seabed mining licensing framework progression status.
The model holds under stable regulatory enforcement intensity and continued offshore wind installation pipeline execution; deviation in International Seabed Authority licensing timeline acceleration or titanium alloy export control expansion would shift autonomous vehicle specification investment timing. Forecasts embed assumptions regarding electric propulsion cost convergence and technician training pipeline adequacy. Practitioners should monitor F-Gas Regulation implementation stringency and seabed mining draft regulation publication for early signals of specification inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Sailboat Market
Marine
Marine Auxiliary Engine Market
Marine
Steel Ship Plate Market
Marine
Ship Searchlight Market
Marine
Autonomous Underwater Vehicle (AUV) Market
Marine
Electric Ferry Market
Marine
Marine Big Data Market
Marine
Marine Chartplotter Market
Marine
Marine Winch Motors Market
Marine
Deep-V Boat Market
Marine
Commercial Hovercraft Market
Marine
Asia-Pacific Electric Boat Market
Marine
Asia-Pacific Leisure Boat Marine Coating Market
Marine
Sliding Fender Market
Marine
Marine Elevators Market
Marine
Marine LED Lights Market