
 Marine Auxiliary Engine Market | 2026-2036
Marine Auxiliary Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Auxiliary Engine Market Analytics
IMO 2023 carbon intensity regulations is shifting procurement criteria toward fuel-flexible auxiliary power systems. MAN Energy Solutions leverages its two-stroke technology heritage to anchor large-vessel contracts. Wärtsilä competes through integrated hybrid power packages that combine conventional engines with battery storage. Cummins specializes in compact high-speed diesels for commercial workboats and coastal ferries.
Marine auxiliary engines are internal combustion or electric power units rated below main propulsion output, typically ranging from 50 kW to 5 MW, that generate electricity for onboard hotel loads, cargo handling, and emergency systems. Diesel configurations retain the largest installed base across tankers and commercial vessels due to fuel availability and technician familiarity. Dual fuel variants represent the fastest-expanding technology category as shipbuilders face charterer mandates for methanol and LNG compatibility. Turbocharged low-speed designs concentrate margin pools in deep-sea tanker and container ship segments where fuel efficiency premiums command pricing power.
The International Maritime Organization enforces Energy Efficiency Existing Ship Index and Carbon Intensity Indicator standards that directly determine auxiliary engine upgrade schedules for fleet operators. Classification societies including Lloyd's Register and DNV apply tiered NOx emission notations that gate market access for new engine designs. Stakeholders must monitor fuel infrastructure buildout at bunkering hubs to validate dual fuel investment timelines and avoid stranded technology commitments.
Market Dynamics
The IMO 2023 Carbon Intensity Indicator enforcement is compressing auxiliary engine replacement cycles across deep-sea fleets, forcing operators to retire non-compliant gensets ahead of technical obsolescence. Shipyards in China, South Korea, and Japan now specify fuel-flexible auxiliary packages as default configurations.
Growth Catalysts
- IMO CII Compliance Deadlines:Fleet operators must retrofit or replace auxiliary engines to meet annual efficiency thresholds, accelerating hardware turnover in the installed base.
- Methanol Bunkering Infrastructure:Port authorities in Rotterdam, Singapore, and Shanghai are installing methanol storage and transfer systems, validating dual-fuel auxiliary engine investments.
- Container Fleet Renewal:Major shipping lines are expanding newbuild programs with integrated auxiliary power systems sized for shore-power compatibility and cold-ironing operations.
Market Restraints
- Stainless Steel Price Volatility:Turbocharger housings and exhaust manifolds rely on nickel-alloy grades subject to London Metal Exchange fluctuations, squeezing fabricator margins.
- CRANZ Supplier Concentration:High-pressure fuel injection components for dual-fuel variants source from a narrow base of German and Swiss precision manufacturers, creating single-source vulnerability.
- NOx Aftertreatment Footprint:Selective catalytic reduction systems add tonnage and maintenance complexity that smaller coastal vessels cannot accommodate within stability limits.
Strategic Opportunities
- Vietnam Shipbuilding Expansion:Vietnamese yards are upgrading from fishing vessel construction to commercial tonnage, opening auxiliary engine supply relationships with non-incumbent vendors.
- Battery-Hybrid Retrofit Kits:Modular lithium-ion storage systems paired with downsized auxiliary gensets enable peak shaving for offshore support vessels without hull modifications.
- EU Green Deal Maritime Funding:The European Investment Bank's sustainable shipping facility offers concessional financing for auxiliary engine upgrades on EU-flagged vessels.
Industry Challenges
- Marine Engineer Certification Gaps:Dual-fuel auxiliary engines require technicians trained in high-pressure gas handling and cryogenic systems, qualifications scarce outside major port cities.
- Classification Society Backlogs:Lloyd's Register and DNV approval queues for novel auxiliary engine designs extend 14-18 months, delaying commercial deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Auxiliary Engine Market |
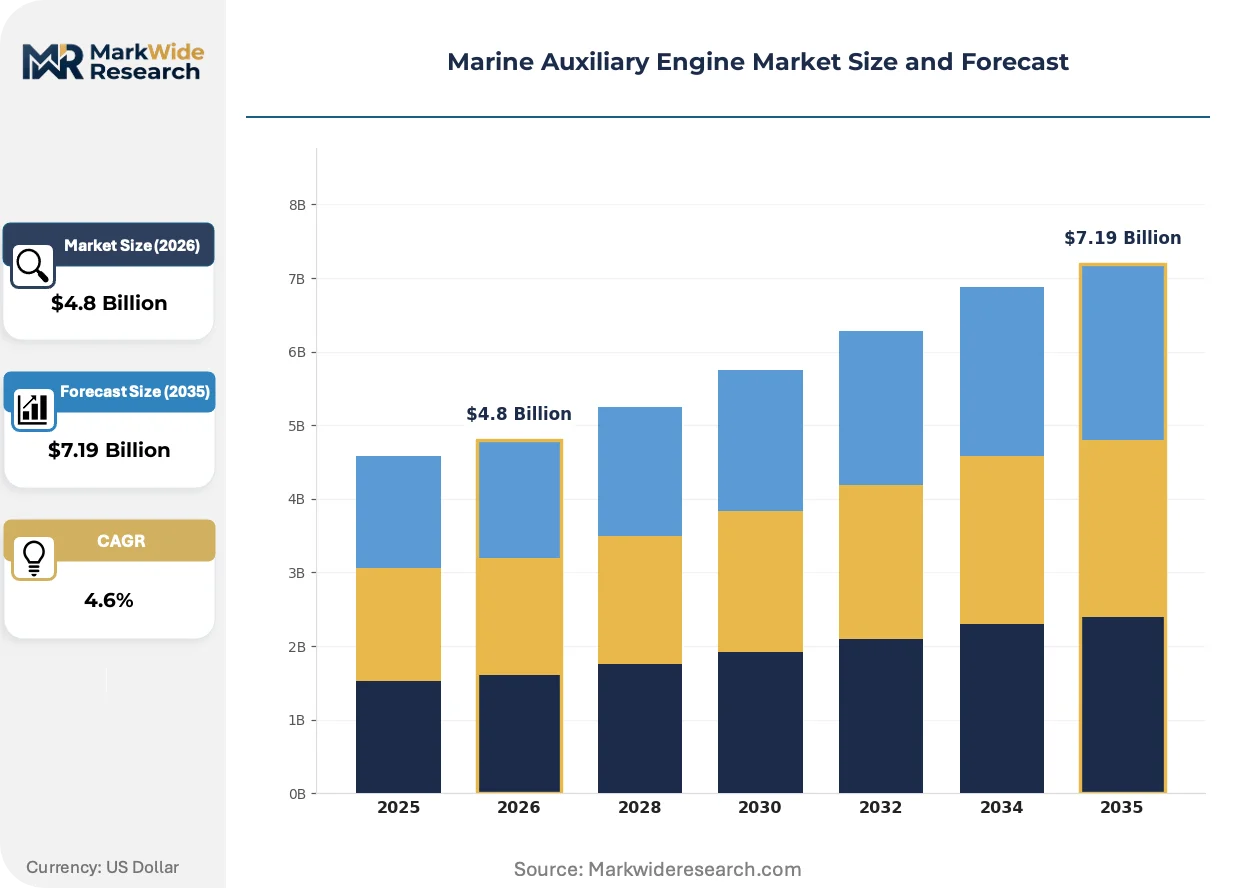
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Diesel, Gasoline, Dual Fuel, Electric Application: Commercial Vessels, Fishing Boats, Research Vessels, Tankers Technology: Conventional, Hybrid, Turbocharged, Low-Speed End User: Shipbuilders, Fleet Operators, Marine Research Institutes, Coastal Services |
| Companies Covered | MAN Energy Solutions, Mitsubishi Heavy Industries, Caterpillar, Yanmar, Rolls-Royce, Cummins, Hyundai Heavy Industries, Volvo Penta, Wärtsilä, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Auxiliary Engine Market Evolving Landscape
Digitalization of engine monitoring and predictive maintenance is converging with alternative fuel readiness, reshaping how ship operators specify and contract auxiliary power systems. Vendors now compete on data integration capabilities alongside mechanical performance.
Variable-speed generator technology is integrating permanent-magnet alternators with intelligent frequency converters to maintain stable electrical output across engine load variations. Offshore supply vessel operators are adopting these systems to reduce fuel consumption during dynamic positioning operations. The technology is integrating fuel savings of 8-12 percent into charter rate negotiations, compressing payback periods for premium auxiliary packages.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in auxiliary engine cooling systems, forcing manufacturers to certify CO2 or ammonia-based alternatives. Marine engine builders must redesign compact heat exchangers to accommodate higher-pressure refrigerant circuits. Deep-sea container ships operating EU routes are most affected, with yards in South Korea accelerating R-744 system validation.
Charterers now unbundle auxiliary engine maintenance from vessel operating leases, contracting directly with OEM service networks for guaranteed availability. This disintermediation strips shipowners of aftermarket revenue and shifts spare parts procurement to centralized fleet purchasing desks. The pattern is most visible in Singapore and Hamburg, where major container lines have established captive technical management subsidiaries.
Marine Auxiliary Engine Market Segmentation
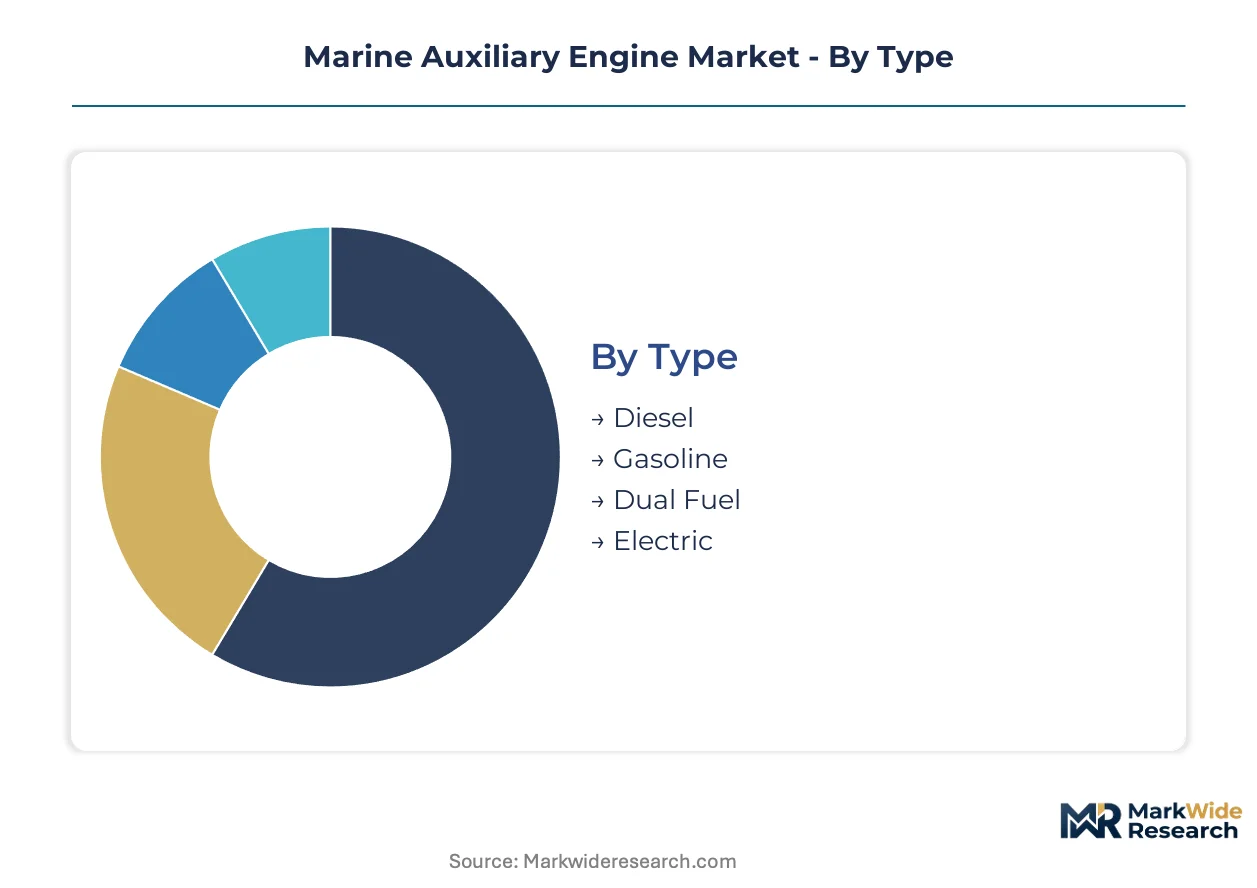
Segmentation in marine auxiliary engines reveals how regulatory pressure and fuel infrastructure shape procurement patterns across vessel categories. Shipyards and fleet operators prioritize different performance attributes depending on route profiles, charterer mandates, and bunkering availability.
Type:
Standardization dominates diesel configurations, while dual-fuel and electric variants require extensive customization to match vessel-specific fuel handling and power management architectures.
- Diesel:Compression-ignition engines burning marine gas oil or heavy fuel oil remain the default for tankers and bulk carriers operating established routes. Demand concentrates in Chinese and South Korean shipyards building vessels for Greek and Singaporean owners where technician familiarity and global spare parts networks outweigh fuel flexibility premiums.
- Dual Fuel:Engines capable of switching between diesel and LNG or methanol combustion address IMO CII compliance mandates for container lines. Retrofit demand clusters at Rotterdam and Singapore where bunkering infrastructure validates capital commitments, though high-pressure fuel injection component sourcing from German and Swiss suppliers creates procurement bottlenecks.
- Gasoline:Spark-ignition units serve small commercial workboats and harbor craft requiring rapid cold-start capability. Japanese coastal ferry operators specify these for short-haul routes with frequent stop-start cycles.
- Electric:Battery-dominant auxiliary systems paired with shore-power compatibility enable zero-emission hotel loads during port stays. Norwegian fjord cruise operators and California harbor craft mandates are accelerating specification rates.
Leading the category by volume: Diesel. Growing fastest: Dual Fuel.
Application:
Cost tier separation between deep-sea tonnage and coastal operations determines engine specification complexity and aftermarket service bundling.
- Commercial Vessels:Container ships, general cargo carriers, and roll-on/roll-off vessels require auxiliary gensets sized for refrigerated container power and cargo crane operations. South Korean yards specify integrated packages with permanent-magnet alternators and intelligent frequency converters for fuel savings during dynamic positioning.
- Tankers:Crude oil and product tankers demand explosion-proof auxiliary configurations with segregated ventilation for pump room power. Greek and Middle Eastern fleet operators prioritize reliability metrics over efficiency premiums given voyage predictability.
- Fishing Boats:Trawlers and longliners use compact high-speed diesels with simplified maintenance protocols. Vietnamese yards upgrading from wooden vessel construction specify these for cost-sensitive domestic owners.
- Research Vessels:Scientific platforms require low-vibration auxiliary systems with redundant power paths for sensitive instrumentation. German and Norwegian institutes specify these with classification society notations for acoustic signature compliance.
Highest specification complexity: Research Vessels. Steepest expansion trajectory: Commercial Vessels.
Technology:
Maturity gradients separate proven conventional architectures from emerging hybrid integrations requiring new certification pathways.
- Conventional:Fixed-speed diesel generators with mechanical governing dominate legacy fleet replacements. Demand concentrates among second-hand vessel buyers in India and Bangladesh where capital constraints override efficiency gains.
- Turbocharged:Exhaust gas-driven compressors boost power density for compact installations in engine-room-constrained vessels. Offshore supply vessel operators in the North Sea and Gulf of Mexico specify these for space-critical platform supply duties.
- Hybrid:Battery storage paired with downsized gensets enables peak shaving and spinning reserve optimization. Modular retrofit kits are gaining traction among offshore support vessel owners seeking charter rate premiums without hull modifications.
- Low-Speed:Direct-coupled auxiliary engines running at propulsion shaft speeds eliminate gearbox losses. Deep-sea tanker newbuilds in Chinese yards specify these for marginal fuel efficiency gains on long-haul routes.
Widest installed base: Conventional. Gaining share fastest: Hybrid.
End User:
Customer type determines procurement authority distribution between vessel construction contracts and operating fleet retrofit decisions.
- Shipbuilders:Yard procurement teams specify auxiliary packages during newbuild construction, often under owner-furnished-equipment arrangements. Chinese, South Korean, and Japanese yards dominate volume through integrated power system sourcing.
- Fleet Operators:Container lines and tanker owners directly procure auxiliary engines for retrofit programs and owned-vessel newbuilds. Major Singapore and Hamburg-based technical management subsidiaries now centralize spare parts purchasing across fleets.
- Marine Research Institutes:Government-funded scientific agencies specify custom auxiliary configurations with redundant power paths and low acoustic signatures. German federal and Norwegian state research fleets drive demand for specialized certifications.
- Coastal Services:Harbor authorities and short-sea ferry operators procure standardized auxiliary packages for fleet renewal. Vietnamese and Indonesian domestic operators prioritize first-cost minimization over lifecycle efficiency.
Largest procurement volume: Shipbuilders. Expanding most quickly: Fleet Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors newbuild demand through integrated shipyard clusters serving container line fleet renewal programs. IMO 2023 carbon intensity regulations compress auxiliary engine replacement cycles across deep-sea fleets. Procurement patterns concentrate in East Asian manufacturing corridors and European retrofit hubs.
China
State-owned shipyards in Dalian and Guangzhou specify fuel-flexible auxiliary packages as default configurations for export tonnage. The Ministry of Ecology and Environment enforces dual carbon goals that tighten engine efficiency benchmarks for domestic fleet operators. Yangtze River Delta fabricators scale turbocharger production for deep-sea tanker segments.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries integrate permanent-magnet alternator systems into newbuild power architectures. The Korean Register of Shipping applies tiered NOx emission notations that gate market access for novel auxiliary designs. Ulsan shipyard complexes validate R-744 cooling systems for EU-route container vessels.
Japan
Coastal ferry operators in Nagoya and Osaka specify gasoline auxiliary units for short-haul routes with frequent stop-start cycles. METI subsidizes methanol bunkering infrastructure development at Yokohama and Chiba ports. Kobe marine equipment suppliers concentrate precision fuel injection component sourcing.
Germany
Hamburg technical management subsidiaries centralize spare parts procurement across container line fleets. The EU Green Deal Maritime Funding facility offers concessional financing for auxiliary engine upgrades on EU-flagged vessels. Lloyd's Register approval queues for novel designs extend 14-18 months at classification society headquarters.
Singapore
Bunkering infrastructure investments at Jurong Port validate dual-fuel auxiliary engine commitments for Asia-Pacific container operators. The Maritime and Port Authority coordinates methanol storage and transfer system installations. Captive technical management subsidiaries disintermediate shipowners from aftermarket revenue streams.
Marine Auxiliary Engine Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth and certification complexity. The vendor base stratifies between integrated power system architects, precision component specialists, and high-volume fabricators serving cost-sensitive coastal segments. Two strategic archetypes dominate: heritage two-stroke technology houses leveraging large-vessel contracts, and hybrid power integrators competing on battery-storage bundling. Competitive moves concentrate on strategic partnerships for fuel infrastructure alignment and geographic expansion into Vietnamese and Indonesian yard supply relationships.
Within the integrated power system tier, MAN Energy Solutions and Wärtsilä represent contrasting heritage-to-hybrid positioning archetypes. MAN Energy Solutions anchors large-vessel contracts through two-stroke technology lineage. Wärtsilä occupies a position emphasizing battery storage integration alongside conventional engine architectures. Cummins exemplifies the compact high-speed diesel specialization for commercial workboats and coastal ferries.
| Leading Market Players |
|---|
| MAN Energy Solutions |
| Mitsubishi Heavy Industries |
| Caterpillar |
| Yanmar |
| Rolls-Royce |
| Cummins |
| Hyundai Heavy Industries |
| Volvo Penta |
| Wärtsilä |
| Others |
Value Network & Pricing Analysis
Marine engineer certification concentrations in Hamburg and Singapore compress labor-cost differentials into three-tier pricing spreads across premium OEM service networks, standard yard-procured packages, and economy coastal-fabricator tiers.
Pricing Analysis
Guaranteed-availability contracts anchor value-based pricing for auxiliary engine maintenance, with charterers paying premiums for uptime commitments rather than hardware alone. Three-tier pricing structure across premium, standard, and economy levels separates IMO-certified dual-fuel systems from conventional diesel configurations and refurbished coastal-fleet units. Price differentiation rests on classification society notation tier and after-sales service bundling. Margins are tightening in the standard tier due to Chinese yard procurement centralization, while premium segments show pricing resilience among container lines prioritizing CII compliance.
Supply Chain Analysis
Domestic-content mandates in China's Yangtze River Delta and South Korea's Ulsan corridor reshape sourcing toward local turbocharger and heat-exchanger fabricators. High-pressure fuel injection components draw from German and Swiss precision manufacturers, while nickel-alloy grades for exhaust manifolds feed from London Metal Exchange suppliers. Single-source vulnerability in CRANZ fuel systems creates structural risk. Distribution runs through shipbuilder-integrated procurement desks and fleet-operator technical management subsidiaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine auxiliary engines constitute a cost-of-compliance market where IMO 2023 Carbon Intensity Indicator enforcement erects regulatory moats favoring players with pre-certified dual-fuel portfolios and established classification society relationships.
For Market Incumbents: Lock in yard-procurement relationships at Hyundai Heavy Industries and Dalian Shipbuilding through integrated power system bundling that embeds battery-hybrid options as default configurations. Deepen backward integration into precision fuel injection component sourcing to offset CRANZ supplier concentration risk. Prioritize Lloyd's Register and DNV certification pipeline investments to compress 14-18 month approval queues for novel designs. For New Entrants and Emerging Players: Vietnamese shipyard technical upgrade programs offer the most penetrable entry channel for non-incumbent auxiliary engine vendors transitioning from fishing vessel to commercial tonnage supply. Target modular battery-hybrid retrofit kits for offshore support vessel operators seeking charter rate premiums without hull modifications. Pursue EU Green Deal Maritime Funding eligibility as a go-to-market credential for EU-flagged fleet operator access. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid power integrators given battery-storage bundling catalysts accelerating specification rates among Norwegian fjord cruise and California harbor craft operators. Long-term viability favors vendors with methanol and LNG dual-fuel certification depth over pure-play diesel fabricators. Watch methanol bunkering infrastructure buildout at Rotterdam, Singapore, and Shanghai as the inflection signal for dual-fuel investment validation.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Certification Investment | DNV and Lloyd's Register tiered NOx notations gate market access for IMO CII-compliant designs. |
| Battery-Hybrid Retrofit Kit Development | Modular lithium-ion systems paired with downsized gensets enable peak shaving without hull modifications for offshore vessels. |
| Precision Component Backward Integration | In-house production of high-pressure fuel injection systems mitigates CRANZ supplier concentration vulnerability. |
| Methanol Bunkering Partnership | Alignment with Rotterdam, Singapore, and Shanghai port infrastructure validates dual-fuel capital commitments. |
| Vietnamese Yard Supply Relationship | Non-incumbent vendors capture commercial tonnage procurement as Vietnamese shipbuilding upgrades from fishing vessels. |
Research Methodology
Multi-period observation of IMO regulatory enforcement timelines, shipyard orderbook compositions, and bunkering infrastructure deployments anchored the trend analysis, supplemented by interviews with marine engineering directors, fleet technical managers, shipyard procurement leads, and classification society surveyors. Secondary validation drew from Lloyd's Register and DNV classification databases, UNCTAD maritime trade statistics, and port authority bunkering infrastructure disclosures. Bottom-up vessel-by-vessel auxiliary engine specification tracking triangulated against top-down shipyard output aggregation.
Input-output matrices mapped fuel-flexible technology adoption curves across vessel categories, with segmentation dimensions spanning engine type, application, technology tier, and end-user procurement authority. CAGRs were derived from installed base turnover modeling incorporating regulatory compliance deadlines and fleet renewal program announcements. Forecast inputs included methanol bunkering infrastructure buildout schedules and EU Green Deal Maritime Funding disbursement patterns.
Caveats apply where stainless steel price volatility, CRANZ supplier bottlenecks, or classification society approval delays could materially shift the outlook for dual-fuel auxiliary engine deployment timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Ship/Boat Keel Market
Marine
Swamp Boat Market
Marine
Sea Scooter Market
Marine
Asia-Pacific Electric Boat Market
Marine
Marine Propeller Market
Marine
Integrated Bridge System for Ships Market
Marine
Global Submarine Market
Marine
Furnace Boats Market
Marine
Marine Bearings Market
Marine
Marine Chartplotter Market
Marine
Marine Pipes Market
Marine
North America Naval Vessels Market
Marine
Marine Interiors Market
Marine
Marine Fasteners Market
Marine
Marine Exhaust Systems Market
Marine
Yacht Shell Doors Market