
 Organ Preservation Market | 2026-2036
Organ Preservation Market Size, Share, and Industry Trends Forecast 2026-2036
Organ Preservation Market Intelligence
Hypothermic machine perfusion is reorganizing procurement economics for transplant programs. TransMedics sustains technology leadership in portable normothermic systems for heart and lung grafts. Paragonix Technologies specializes in advanced transport containers with integrated temperature monitoring. XVIVO Perfusion anchors European market presence through clinical evidence generation and perfusion service partnerships.
Organ preservation encompasses the controlled maintenance of donor organ viability through temperature regulation, metabolic suppression, and perfusion with specialized solutions containing electrolytes, colloids, and pharmacological agents to prevent ischemia-reperfusion injury prior to transplantation. Static cold storage dominates kidney transplantation due to cost efficiency and established workflows, while hypothermic machine perfusion commands margin pools in liver grafting through extended preservation windows and viability assessment capabilities. Normothermic perfusion represents the fastest-growing technology segment as transplant centers adopt organ assessment platforms that permit functional recovery and metabolic resuscitation of marginal donor organs.
FDA premarket authorization pathways and EMA medical device regulations shape product development timelines and clinical evidence requirements for perfusion device manufacturers. ISO 14155 clinical investigation standards and ASTS/ASTP procurement guidelines influence adoption thresholds at organ procurement organizations and transplant centers. Stakeholders must monitor evolving reimbursement decisions for machine perfusion procedures and the integration of real-time organ assessment biomarkers into clinical protocols.
Market Dynamics
Normothermic machine perfusion is decomposing the static cold storage paradigm that has dominated organ transplantation for four decades. Transplant centers in the United States, Germany, and Japan are reallocating capital toward perfusion platforms that enable metabolic resuscitation of marginal donor organs.
Growth Catalysts
- FDA premarket authorization pathways:Streamlined device review processes accelerate clinical validation timelines for perfusion manufacturers targeting the US market.
- Extended criteria donor expansion:Transplant programs are widening donor acceptance windows as perfusion technology permits viability assessment of steatotic livers and donation-after-circulatory-death hearts.
- Japan's revised transplant legislation:Policy reforms expanding brain-dead donor criteria create procurement volume growth for advanced preservation systems.
Market Restraints
- Capital intensity of perfusion platforms:Single-use organ cassettes and proprietary consumables impose recurring cost burdens on organ procurement organizations with fixed reimbursement rates.
- Supply concentration in pump manufacturing:Precision perfusion pump components rely on concentrated German and Swiss precision engineering suppliers.
- Technical limitation in multi-organ perfusion:Current systems lack standardized protocols for simultaneous heart-lung or liver-kidney perfusion, constraining operational efficiency.
Strategic Opportunities
- Underpenetrated Indian transplant infrastructure:The country's emerging organ allocation network presents first-mover positioning for portable hypothermic perfusion systems.
- Biomarker integration convergence:Real-time lactate clearance and hepatic bile production monitoring are converging with machine perfusion to create predictive viability scoring.
- EU Medical Device Regulation tailwind:MDR compliance requirements favor established perfusion device manufacturers with robust clinical evidence packages over new entrants.
Industry Challenges
- Perfusionist workforce scarcity:Specialized training requirements for normothermic system operation outpace educational program expansion at US and European transplant centers.
- Legacy cold storage workflow integration:Procurement organizations face operational friction retrofitting organ transport logistics for machine perfusion protocols.
- ISO 14155 clinical investigation timelines:Extended device validation studies delay market entry for novel perfusion solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organ Preservation Market |
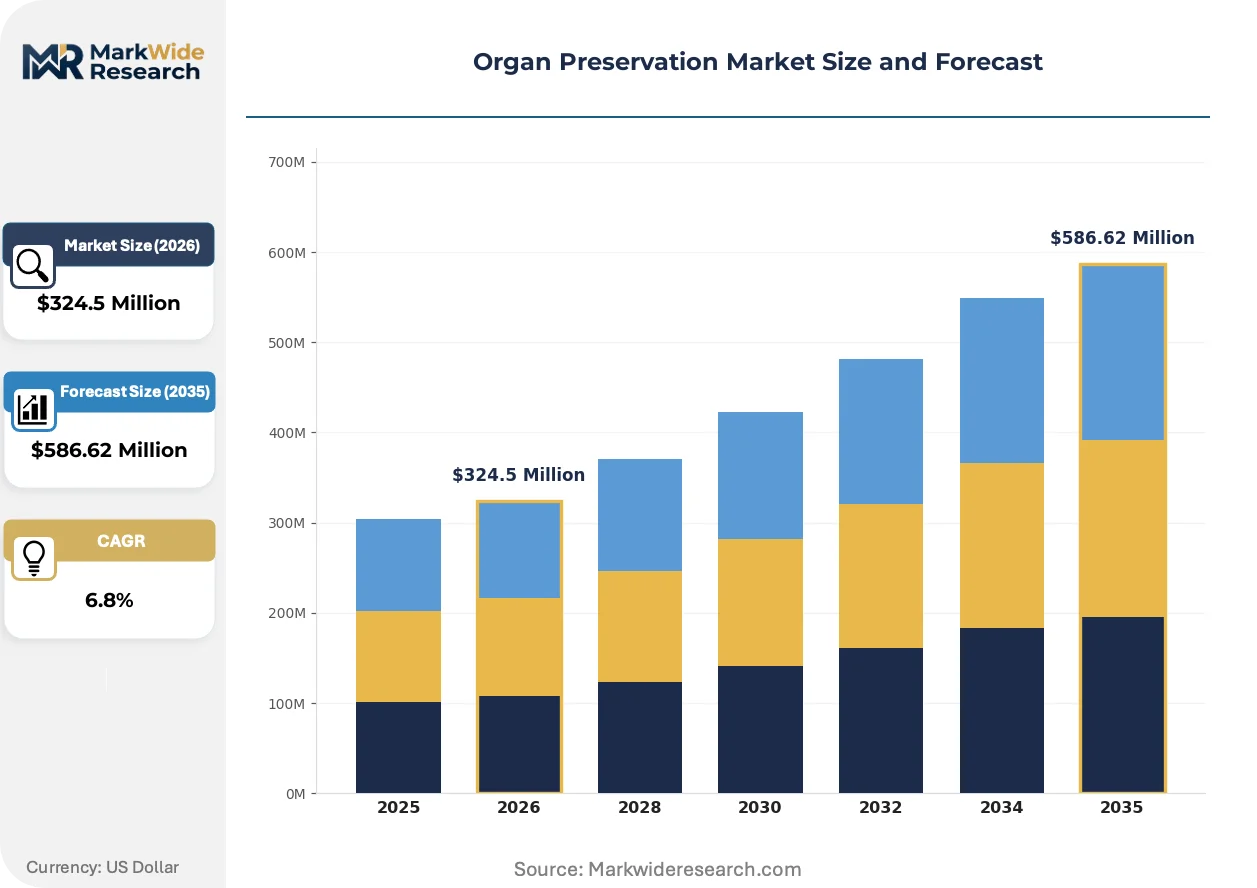
| Market Size in 2026 | $324.5 Million |
| Market Size in 2035 | $586.62 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Storage Solutions, Preservation Solutions, Transport Containers, Perfusion Devices, Preservation Films Technology: Hypothermic Machine Perfusion, Static Cold Storage, Normothermic Perfusion, Subnormothermic Preservation, Cryopreservation Application: Kidney Transplantation, Liver Grafting, Heart Replacement, Lung Transplant, Pancreas Transplantation End User: Organ Procurement Organizations, Transplant Centers, Research Institutes, Biobanking Facilities |
| Companies Covered | XVIVO Perfusion AB, TransMedics, Inc., Paragonix Technologies, Inc., Organ Recovery Systems, Bridge to Life Ltd., Preservation Solutions, Inc., OrganOx Limited, Getinge AB, Waters Medical Systems LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organ Preservation Market Strategic Shifts & Innovations
Perfusion technology architectures are fragmenting into specialized organ-specific platforms rather than converging toward universal systems. This specialization is accelerating competitive differentiation around biomarker integration and remote monitoring capabilities.
Normothermic regional perfusion is decomposing traditional static preservation workflows for abdominal organs. US liver transplant centers are adopting the technology at accelerating rates as viability assessment protocols mature. The shift is compressing discard rates for marginal grafts and redistributing procurement economics toward technology-enabled organ procurement organizations.
EMA Medical Device Regulation enforcement is tightening clinical evidence requirements for CE marking of perfusion devices. Manufacturers must now submit extended follow-up data on graft survival outcomes. European transplant centers are prioritizing suppliers with established MDR technical documentation over emerging competitors.
Hospital procurement committees are consolidating vendor relationships around full-service perfusion partnerships rather than discrete device acquisitions. Organ procurement organizations in Germany and Japan are negotiating multi-year service agreements that bundle equipment, consumables, and clinical support. This bundling is displacing transactional equipment purchasing models and concentrating purchasing power among integrated platform providers.
Organ Preservation Market Segmentation
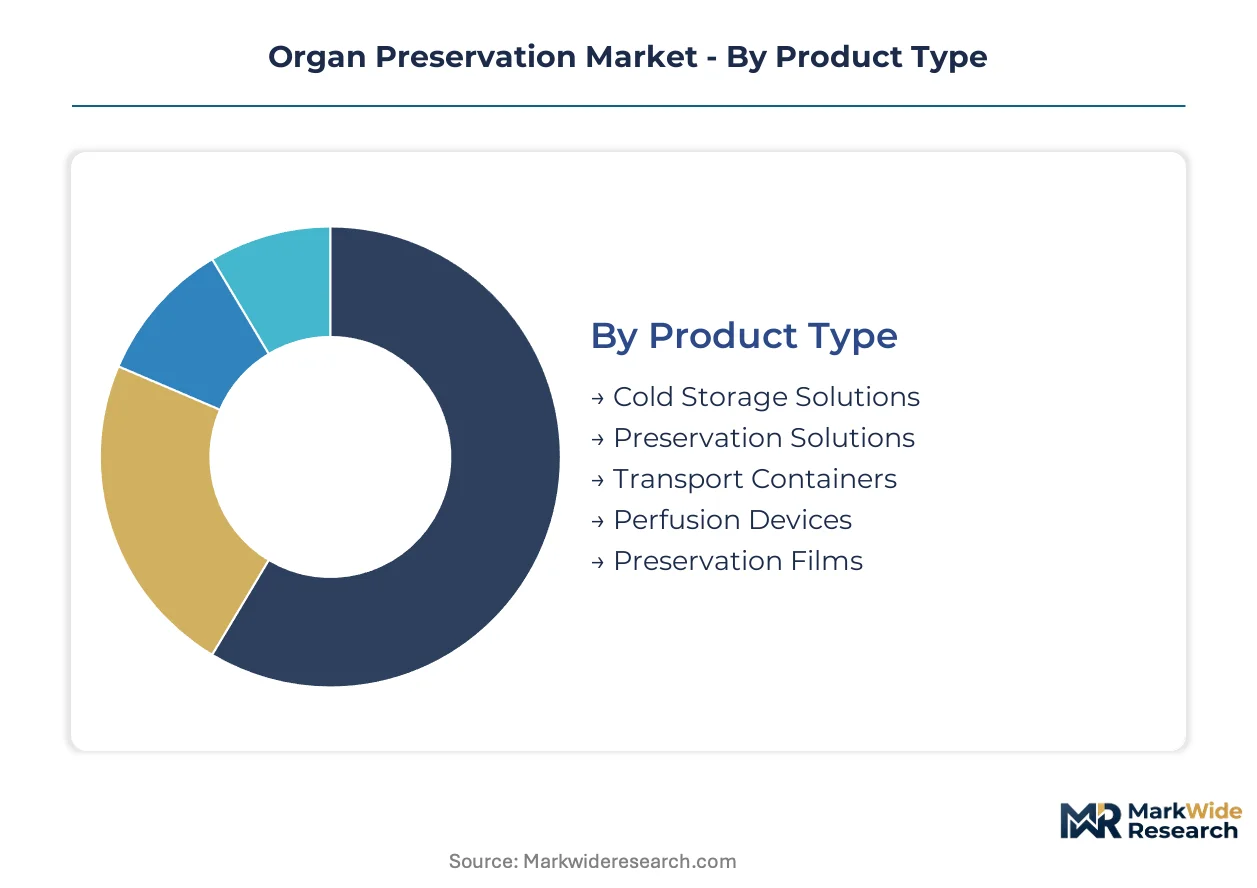
Segmentation in organ preservation technology directly shapes procurement economics and reimbursement pathways. Product architecture, perfusion modality, and end-user infrastructure each impose distinct technical requirements and capital deployment patterns across transplant networks.
Product Type:
Substitution pressure from integrated perfusion platforms is eroding standalone consumable margins as transplant centers consolidate vendor relationships.
- Perfusion Devices:Portable and stationary systems enable normothermic or hypothermic mechanical circulation of preservation solutions through donor organs. United States transplant centers concentrate procurement of these platforms as FDA premarket authorizations validate extended preservation windows for marginal grafts.
- Preservation Solutions:Electrolyte-balanced fluids containing colloids, buffers, and pharmacological agents suppress metabolic activity and prevent ischemia-reperfusion injury. German and Japanese procurement organizations standardize on University of Wisconsin and histidine-tryptophan-ketoglutarate formulations for liver and kidney grafting protocols.
- Cold Storage Solutions:Iced saline and specialized cooling media maintain hypothermic temperatures during organ transport.
- Transport Containers:Insulated vessels with integrated temperature monitoring protect grafts during procurement logistics.
- Preservation Films:Oxygen-impermeable barrier materials reduce desiccation risk for surface-exposed organs.
Preservation Solutions anchors the volume base while Perfusion Devices gains share at the steepest rate.
Technology:
Cost tier stratification separates capital-intensive normothermic platforms from established low-cost hypothermic methods.
- Normothermic Perfusion:Systems maintain donor organs at physiological temperature with oxygenated blood or specialized perfusate, permitting metabolic resuscitation and real-time viability assessment. United States liver and heart transplant programs concentrate adoption as procurement economics shift toward technology-enabled organ assessment.
- Static Cold Storage:Ice-based temperature reduction to 4°C remains the dominant protocol for kidney transplantation due to established workflows and minimal equipment requirements. Japanese transplant centers retain this method for standard-criteria donor kidneys where ischemic time constraints are manageable.
- Hypothermic Machine Perfusion:Mechanical circulation of cold preservation solution extends viable preservation windows and enables viability biomarker measurement.
- Subnormothermic Preservation:Intermediate temperature ranges balance metabolic suppression with reduced reperfusion injury.
- Cryopreservation:Ultra-low temperature protocols using cryoprotectants enable long-term biobanking of vascularized tissues.
Static Cold Storage dominates procurement volume while Normothermic Perfusion climbs the fastest among transplant centers with capital expansion capacity.
Application:
Organ-specific perfusion requirements fragment technology adoption across abdominal and thoracic transplant programs.
- Liver Grafting:Steatotic and donation-after-circulatory-death livers demand extended preservation windows and metabolic assessment capabilities that normothermic perfusion provides. German transplant centers lead European adoption of machine perfusion for marginal hepatic grafts.
- Kidney Transplantation:High procedural volume and established cold storage workflows sustain cost-efficient preservation economics. United States organ procurement organizations prioritize hypothermic machine perfusion only for extended criteria donor kidneys with prolonged ischemic risk.
- Heart Replacement:Ex-situ normothermic perfusion enables assessment of donation-after-circulatory-death cardiac grafts previously excluded from transplantation.
- Lung Transplant:Specialized perfusion protocols address alveolar gas exchange preservation during transport.
- Pancreas Transplantation:Low procedural volume limits dedicated perfusion technology investment relative to solid organ standards.
Kidney Transplantation anchors the volume base while Liver Grafting gains share at the steepest rate.
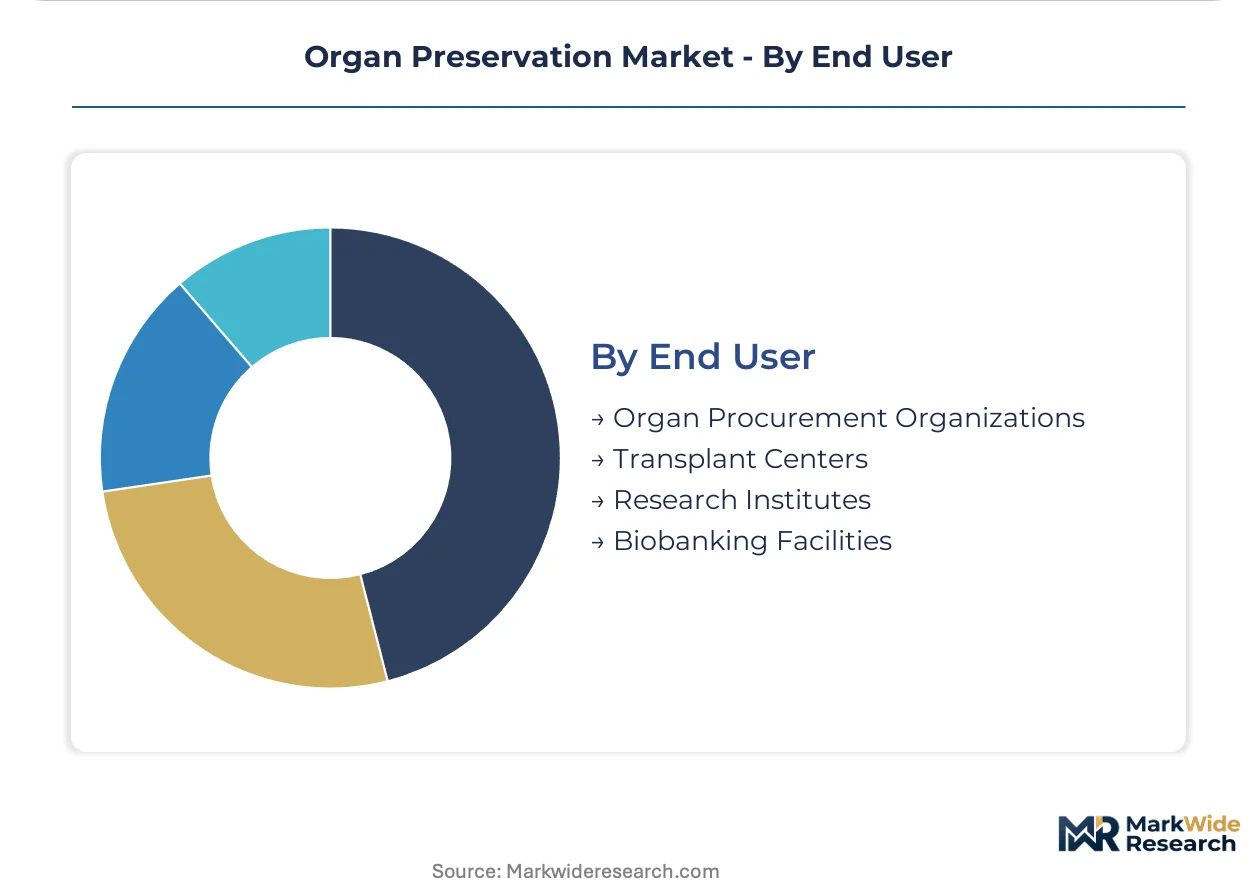
End User:
Customer type determines capital intensity tolerance and service bundling requirements across procurement infrastructure.
- Transplant Centers:Hospital-based surgical programs perform graft implantation and increasingly operate on-site perfusion capabilities for viability assessment. Japanese academic medical centers concentrate investment in normothermic platforms as national transplant legislation expands donor criteria.
- Organ Procurement Organizations:Nonprofit entities coordinate donor identification, organ recovery, and transport logistics with fixed reimbursement constraints. United States OPOs face capital allocation pressure between legacy cold storage workflows and emerging perfusion technology mandates.
- Research Institutes:Academic and commercial laboratories develop preservation protocol innovations and biomarker validation studies.
- Biobanking Facilities:Tissue repositories require cryopreservation and subnormothermic systems for extended specimen storage.
Organ Procurement Organizations anchors the volume base while Transplant Centers gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision perfusion pump components concentrate manufacturing in German and Swiss engineering clusters, while transplant volume growth drives platform deployment across high-income healthcare systems. Regulatory frameworks and reimbursement policies shape adoption velocity in each national market.
United States
FDA premarket authorization pathways accelerate clinical validation timelines for perfusion manufacturers targeting domestic transplant centers. The Medicare reimbursement structure for machine perfusion procedures influences capital allocation at organ procurement organizations. Transplant hubs in Houston, Pittsburgh, and Los Angeles concentrate normothermic platform adoption for liver and heart graft assessment.
Germany
EMA Medical Device Regulation enforcement tightens clinical evidence requirements for CE marking of perfusion devices entering European markets. The country's statutory health insurance system maintains favorable reimbursement for extended criteria donor protocols. Medical technology clusters in Baden-Württemberg and Bavaria host precision pump component suppliers serving global device manufacturers.
Japan
Revised transplant legislation expanding brain-dead donor criteria creates procurement volume growth for advanced preservation systems. PMDA medical device review processes shape product registration timelines for foreign manufacturers. Academic medical centers in Tokyo and Osaka concentrate investment in normothermic platforms as national donor pools expand.
United Kingdom
NHS England procurement frameworks standardize perfusion technology assessment criteria across transplant networks. The Medicines and Healthcare products Regulatory Agency oversees post-market surveillance of CE-marked devices. Liver transplant centers in Birmingham and Edinburgh lead European adoption of machine perfusion for marginal hepatic grafts.
India
Emerging organ allocation network infrastructure presents positioning opportunities for portable hypothermic perfusion systems. CDSCO medical device regulations govern import and registration of preservation platforms. Transplant programs in Maharashtra and Karnataka drive initial technology adoption as procurement capabilities mature.
Organ Preservation Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the organ preservation market. The vendor base stratifies into integrated platform providers, specialized perfusion device manufacturers, and consumables-focused suppliers. Three archetypes dominate: full-service perfusion partnerships, portable normothermic system specialists, and established cold storage solution providers. Competitive moves concentrate on multi-year service agreement bundling and M&A targeting biomarker integration capabilities.
Within the integrated platform tier, TransMedics and XVIVO Perfusion occupy positions exemplifying divergent geographic strategies. TransMedics anchors North American technology leadership through portable normothermic systems, while XVIVO Perfusion represents European market presence through clinical evidence generation and perfusion service partnerships. Paragonix Technologies sits within the specialized transport container segment, illustrating how temperature monitoring integration creates differentiation in logistics-dependent procurement workflows.
| Leading Market Players |
|---|
| XVIVO Perfusion AB |
| TransMedics, Inc. |
| Paragonix Technologies, Inc. |
| Organ Recovery Systems |
| Bridge to Life Ltd. |
| Preservation Solutions, Inc. |
| OrganOx Limited |
| Getinge AB |
| Waters Medical Systems LLC |
| Others |
Cost & Logistics Intelligence
Normothermic perfusion technology substitution for static cold storage is simultaneously concentrating supply geography in German and Swiss precision engineering clusters and fragmenting pricing economics across tiered service-attach models. Transplant centers now negotiate bundled agreements where consumable cassettes and clinical support layers command recurring revenue streams distinct from capital equipment acquisition.
Pricing Analysis
FDA premarket authorization pathways and EMA MDR compliance requirements dictate the pricing tier structure across the organ preservation market. Three-tier pricing structure across premium, standard, and economy levels separates normothermic platforms with real-time biomarker integration from hypothermic systems with basic viability assessment, with static cold storage occupying the economy tier. Price differentiation rests on FDA breakthrough device designation and ISO 14155 clinical evidence depth. Margins are tightening in the hypothermic tier due to consumable commoditization. Organ procurement organizations exhibit highest price sensitivity given fixed reimbursement constraints, while academic transplant centers in Japan and Germany demonstrate lowest sensitivity where research budgets subsidize technology evaluation.
Supply Chain Analysis
Germany and Switzerland anchor precision perfusion pump manufacturing, with Taiwan and Japan contributing sensor electronics and disposable biocompatibility materials. Supply chains draw from specialized electrolyte formulation facilities in the United States and Netherlands for preservation solutions, plus oxygenator membrane suppliers concentrated in Scandinavian polymer clusters. Single-source vulnerability in precision pump motor assemblies presents structural risk given limited qualified suppliers. Distribution runs through hospital procurement committees and organ procurement organization centralized purchasing, with multi-year service agreements displacing transactional equipment sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue models in organ preservation are expanding faster than hardware sales as transplant centers prioritize perfusion partnerships bundling equipment, consumables, and clinical specialist deployment. This recurring-revenue layer now represents the primary value capture mechanism for platform providers.
For Market Incumbents: Secure multi-year service agreement extensions with organ procurement organizations before competitive displacement accelerates. Threats from emerging portable hypothermic system specialists targeting underpenetrated Indian infrastructure require defensive certification investment in CDSCO registration pathways. Backward integration into precision pump component manufacturing in Baden-Württemberg engineering clusters reduces supply vulnerability. For New Entrants and Emerging Players: Differentiate on biomarker integration capabilities for real-time lactate clearance and hepatic bile production monitoring. White-space concentration exists in portable hypothermic perfusion systems for India's emerging organ allocation network, with Maharashtra and Karnataka transplant programs as initial beachheads. Go-to-market through perfusionist training program partnerships addresses workforce scarcity barriers. For Investors and Strategic Acquirers: EMA MDR enforcement reshapes the acquisition landscape toward targets with established technical documentation and extended graft survival outcome databases. Long-term viability centers on platforms capable of multi-organ protocol expansion. Acquisition target archetype: European perfusion service providers with hospital system embeddedness. Signal to watch: Medicare reimbursement decisions for machine perfusion procedures as volume inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerated review timelines compress competitive entry windows for normothermic platforms. |
| Perfusionist Training Program Expansion | Workforce development partnerships with ASTS/ASTP address operational adoption barriers. |
| Biomarker Integration Development | Real-time viability scoring capabilities differentiate premium platform tiers. |
| Multi-Year Service Agreement Bundling | Recurring revenue concentration displaces transactional equipment purchasing models. |
| CDSCO Registration Investment | Early positioning in India's emerging transplant infrastructure captures first-mover advantage. |
Research Approach
A standing panel of transplant surgeons, organ procurement organization executives, perfusionist training program directors, and biomedical engineering procurement managers provided ongoing calibration against secondary validation. Primary interviews with FDA regulatory consultants and EMA notified body representatives informed compliance pathway analysis. Secondary sources encompassed FDA 510(k) and PMA filings, EMA MDR technical documentation databases, hospital GPO contract repositories, and ASTS/ASTP procurement guidelines. Bottom-up modeling of transplant center capital expenditure patterns triangulated against top-down reimbursement framework analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including perfusion modality, organ-specific application, end-user infrastructure type, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to technology substitution rates and procurement budget elasticity estimates. Industry-specific inputs included transplant volume projections by donor criteria expansion, machine perfusion reimbursement decision timelines, and precision component supply lead time variations.
The analysis sits within stated boundaries; outcomes outside FDA authorization acceleration, EMA MDR enforcement intensity, or Japanese donor legislation expansion would require recalibration. Forecasts reflect assumptions regarding biomarker validation timelines and perfusionist workforce growth trajectories. Recalibration cycles align with material shifts in Medicare reimbursement policy and MDR technical documentation precedent.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Transabdominal Retrieval Kits Market
Medical Devices
Eye Massage Device Market
Medical Devices
Wearable Atrial Fibrillation Detection Devices Market
Medical Devices
Cheek Implants Market
Medical Devices
South Korea Ultrasound Devices Market
Medical Devices
Asia-Pacific Digital Dentistry Market
Medical Devices
Medical Electrodes Market
Medical Devices
Struts Implants Market
Medical Devices
Spain Artificial Organs and Bionic Implants Market
Medical Devices
Central Venous Catheter Market
Medical Devices
Non-Invasive Pulse Oximeter Market
Medical Devices
Breast Pump Flange Market
Medical Devices
Sphincterotomes Market
Medical Devices
Clear Aligners Market
Medical Devices
South Korea Ophthalmic Devices Market
Medical Devices
Neurovascular Stent Market