
 Specialty Pharma Home Delivery and Patient Support Logistics Market | 2026-2036
Specialty Pharma Home Delivery and Patient Support Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Pharma Home Delivery and Patient Support Logistics Market Insights
Temperature-sensitive biologics is repositioning cold chain economics toward reusable thermal packaging and phase-change materials. Cencora leverages its specialty pharmacy network to control last-mile distribution for complex therapies. McKesson anchors wholesale infrastructure that sustains same-day delivery commitments to infusion centers. FedEx competes through dedicated healthcare divisions with validated cold chain corridors across North America and Europe.
Specialty pharma home delivery and patient support logistics encompasses the end-to-end coordination of temperature-controlled distribution, patient onboarding, adherence monitoring, and clinical support services for high-cost biologic and orphan drugs, typically requiring maintenance between two and eight degrees Celsius with real-time deviation alerts. Cold chain logistics dominates service type revenue due to infrastructure intensity and regulatory validation costs, while remote monitoring grows fastest as connected devices integrate with telehealth platforms. Direct-to-patient channels capture premium margin pools by eliminating intermediary markups, though specialty pharmacies retain structural importance for payer-contracted therapies requiring prior authorization management.
FDA's Drug Supply Chain Security Act mandates unit-level traceability, while the EU Good Distribution Practice framework enforces temperature mapping and qualification protocols for cross-border shipments. HIPAA in the United States and GDPR in Europe constrain how patient data flows through telehealth platforms and adherence apps, directly shaping technology integration roadmaps. Stakeholders must weigh capital deployment between owned cold chain infrastructure and third-party logistics partnerships as regulatory stringency diverges across jurisdictions.
Market Dynamics
Cold chain infrastructure investment is concentrating around phase-change materials and reusable thermal packaging as biologics displace small-molecule drugs in oncology and autoimmune therapy portfolios.
Growth Catalysts
- FDA's Drug Supply Chain Security Act:Unit-level traceability mandates force wholesale distributors to upgrade serialization infrastructure, expanding demand for integrated logistics platforms with real-time tracking capabilities.
- Oncology patient populations:Oral oncolytic prescriptions are accelerating direct-to-patient delivery models as infusion centers face capacity constraints and patients seek home-based administration options.
- Connected temperature sensors:IoT-enabled cold chain monitoring is converging with telehealth platforms to create closed-loop adherence systems that trigger automated interventions when deviations occur.
Market Restraints
- Qualified packaging scarcity:Validated thermal shippers for two-to-eight-degree Celsius maintenance require extensive stability testing, creating bottlenecks as biologics volumes expand faster than packaging qualification timelines.
- EU Good Distribution Practice:Cross-border temperature mapping requirements impose redundant qualification protocols that fragment distribution networks and elevate compliance costs for pan-European operations.
- Dry ice supply concentration:Carbon dioxide capture infrastructure for pharmaceutical-grade dry ice clusters in the United States Gulf Coast and German industrial corridors, exposing networks to feedstock volatility.
Strategic Opportunities
- Japan's aging demographics:Home nursing support reimbursement under the country's long-term care insurance system creates structural pull for integrated patient support services alongside drug delivery.
- Real-world evidence platforms:Adherence data captured through connected devices is converging with outcomes research to demonstrate therapy value, opening new revenue streams beyond logistics fees.
- Cell and gene therapy pipelines:Cryogenic logistics requirements for negative one hundred fifty degrees Celsius distribution are forcing development of specialized courier networks with chain-of-identity protocols.
Industry Challenges
- Cold chain engineering talent:Thermal packaging design and validation protocol development require scarce expertise in heat transfer modeling and regulatory documentation.
- HIPAA-GDPR data fragmentation:Patient adherence data flows through logistics platforms must reconcile divergent privacy frameworks when therapies cross United States-European borders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Pharma Home Delivery and Patient Support Logistics Market |
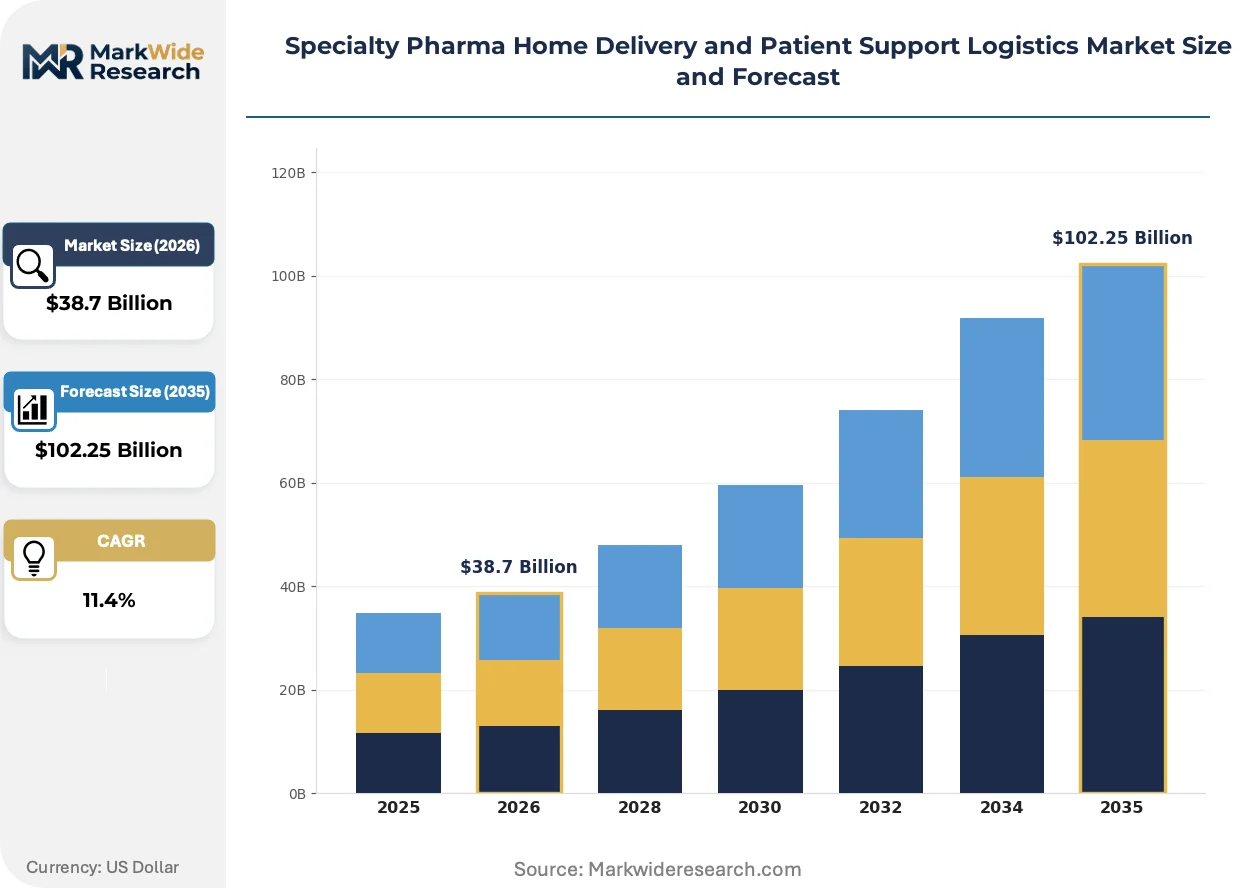
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cold Chain Logistics, White Glove Delivery, Subscription Services, Remote Monitoring, Inventory Management Patient Support Program: Adherence Assistance, Education & Training, 24/7 Nurse Helpline, Financial Assistance, Therapy Management Distribution Channel: Direct-to-Patient, Specialty Pharmacies, Third-Party Logistics, Hospital Pharmacies, Mail Order Pharmacies Technology Integration: Mobile Apps, Telehealth Platforms, Real-Time Tracking, Data Analytics, Automated Scheduling |
| Companies Covered | Cencora, McKesson, CVS Health, UnitedHealth Group, The Cigna Group, Cardinal Health, Option Care Health, DHL Group, FedEx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Pharma Home Delivery and Patient Support Logistics Market Trends and Innovations
Digital integration across temperature monitoring, patient onboarding, and clinical support is compressing service boundaries between logistics providers and specialty pharmacies.
Reusable thermal packaging systems are converging with blockchain-enabled chain-of-custody records. Third-party logistics providers in Germany and the Netherlands are piloting closed-loop container networks that reduce per-shipment packaging costs by seventy percent after five rotation cycles. This convergence is compressing capital requirements for cold chain entry and shifting competitive advantage toward asset-light platform operators with strong reverse logistics capabilities.
EMA's strengthened GDP Annex guidelines now mandate risk-based temperature monitoring with continuous data loggers for all Category B and C products. Wholesale distributors must demonstrate mapping studies for every lane and seasonal variant, forcing consolidation among smaller operators lacking validation infrastructure. Italian and Spanish distributors are responding by pooling qualification resources through shared service centers.
Oncology patients are demanding same-day delivery windows that match retail e-commerce expectations. Specialty pharmacies in the United States are unbundling clinical support from dispensing, allowing pure-play logistics providers to capture direct-to-patient volumes for stable chronic therapies. This behavioral shift is most visible in Florida and Texas, where Medicare Advantage penetration concentrates risk-bearing entities with incentive to minimize infusion center utilization.
Specialty Pharma Home Delivery and Patient Support Logistics Market Segmentation
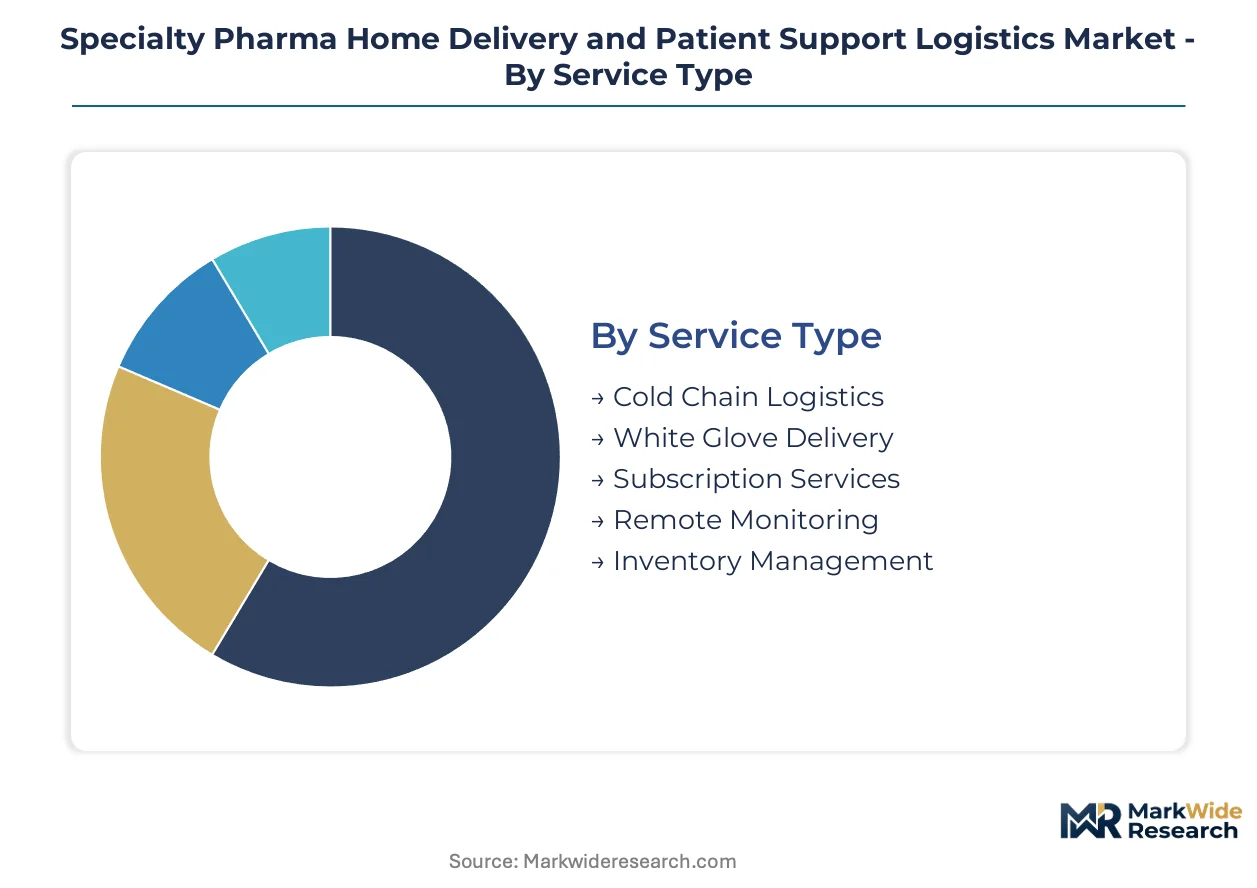
Segmentation in specialty pharma logistics reflects divergent regulatory validation burdens and capital intensity requirements. Service types separate by infrastructure ownership versus platform licensing models. Patient support programs stratify by clinical labor ratios and reimbursement eligibility.
Service Type:
Cold chain logistics demands GDP qualification and FDA 21 CFR Part 11 validation for electronic records. White glove delivery requires HIPAA-compliant handler certification. Subscription services face state-level pharmacy licensure. Remote monitoring triggers FDA device classification reviews. Inventory management systems need DSCSA serialization integration.
- Cold Chain Logistics:Temperature-controlled distribution infrastructure maintaining two-to-eight degrees Celsius for biologics, validated through ISTA 7E thermal testing protocols. Demand concentrates in oncology and autoimmune therapy corridors across the United States, Germany, and Japan, where infusion center capacity constraints accelerate direct-to-patient shifts.
- White Glove Delivery:Hand-carried courier services with chain-of-custody documentation for high-value orphan drugs requiring signature capture and patient identity verification. United States metropolitan hubs drive volume as Medicare Advantage plans seek to reduce emergency department utilization through proactive home delivery.
- Subscription Services:Recurring shipment models with automated refill triggers and prior authorization management.
- Remote Monitoring:Connected device integration for adherence tracking and temperature excursion alerts.
- Inventory Management:Hub-and-spoke warehousing with lot-level traceability and expiration date optimization.
Leading the category by volume: Cold Chain Logistics. Growing fastest: Remote Monitoring.
Patient Support Program:
Program design reflects labor cost tiers and clinical outcome accountability. Nurse helplines carry premium reimbursement rates under risk-bearing contracts. Financial assistance programs require charity care compliance documentation.
- Adherence Assistance:Intervention protocols triggered by missed doses or refill delays, combining automated outreach with pharmacist callback escalation. United States specialty pharmacies deploy these programs most intensively where value-based contracts tie reimbursement to persistence metrics.
- 24/7 Nurse Helpline:Clinical call centers staffed by licensed RNs handling adverse event reporting and dosing questions under FDA-mandated pharmacovigilance timelines. Japan's long-term care insurance system reimburses home nursing support, creating structural demand for integrated helpline services alongside drug delivery.
- Education & Training:Injection technique certification and self-administration coaching for subcutaneous biologics.
- Financial Assistance:Copay card administration and manufacturer patient assistance program enrollment.
- Therapy Management:Comprehensive care coordination spanning prior authorization, benefits investigation, and site-of-care optimization.
Dominant by enrollment: Adherence Assistance. Expanding most quickly: 24/7 Nurse Helpline.
Distribution Channel:
Channel selection determines margin capture and data control positions. Direct-to-patient models bypass specialty pharmacy dispensing fees but require in-house clinical support infrastructure.
- Direct-to-Patient:Manufacturer-controlled last-mile delivery eliminating intermediary markups, feasible only for therapies without prior authorization complexity or payer-mandated specialty pharmacy networks. Florida and Texas Medicare Advantage penetration concentrates risk-bearing entities with incentive to minimize infusion center utilization.
- Specialty Pharmacies:Payer-contracted dispensing with integrated prior authorization management and clinical outcomes reporting. United States hub pharmacies in Pennsylvania and Arizona anchor national distribution networks through central fill operations.
- Third-Party Logistics:Outsourced cold chain execution by validated courier networks.
- Hospital Pharmacies:Inpatient-to-outpatient transition programs for discharge medication continuity.
- Mail Order Pharmacies:High-volume automated dispensing for stable chronic therapies with 90-day supply authorization.
Highest margin capture: Direct-to-Patient. Fastest volume shift: Specialty Pharmacies.
Technology Integration:
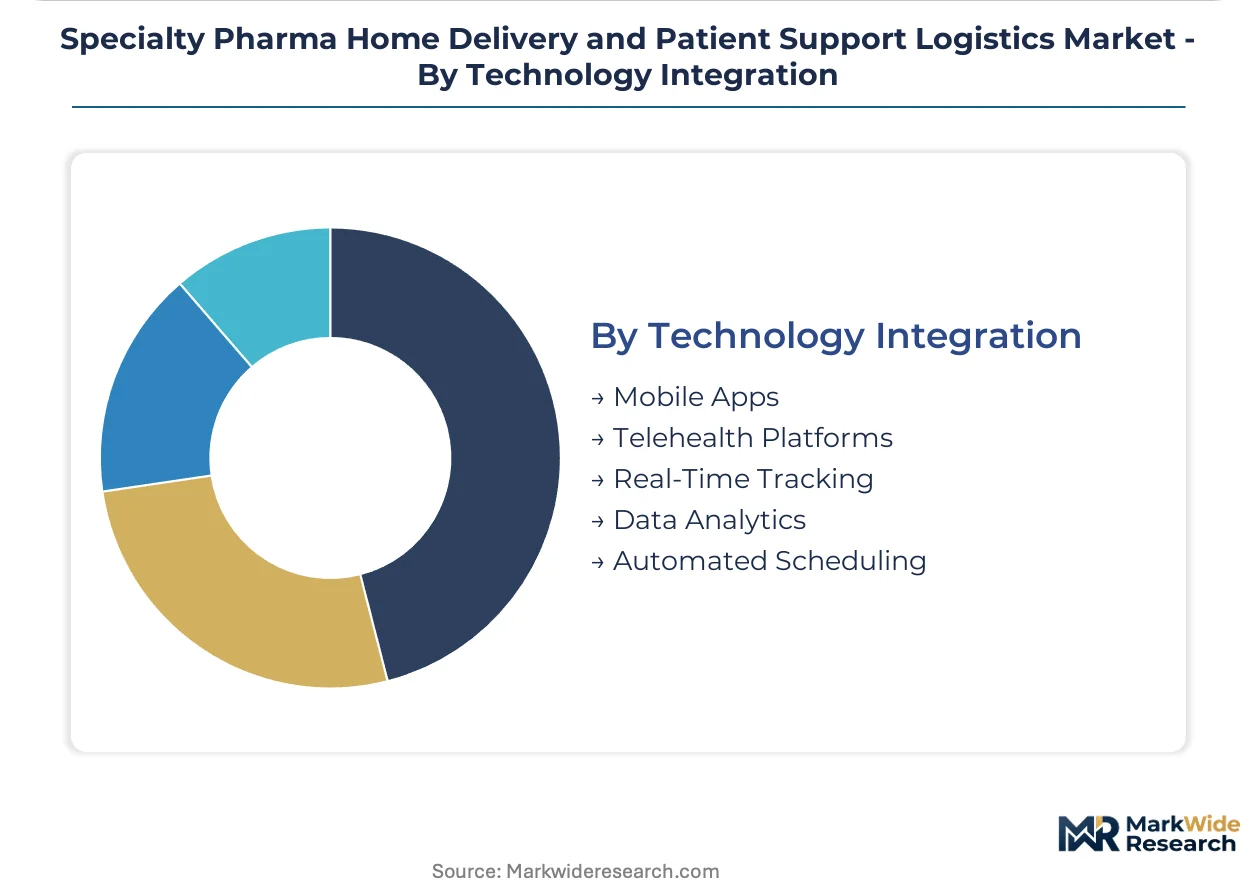
Technology deployment stratifies by development cost and regulatory pathway. Telehealth platforms face state medical board licensure requirements. Real-time tracking systems need FDA validation for use in regulatory submissions.
- Telehealth Platforms:Video consultation infrastructure integrated with prescription routing and clinical documentation, requiring HIPAA Business Associate Agreements and state-level telemedicine licensure compliance. United States dermatology and rheumatology practices deploy these most aggressively for follow-up visits that previously required infusion center travel.
- Real-Time Tracking:GPS and temperature sensor integration providing continuous chain-of-custody documentation with automated deviation alerts. EU GDP Annex guidelines mandate risk-based temperature monitoring, forcing wholesale distributors to upgrade from passive data loggers to active transmission systems.
- Mobile Apps:Patient-facing adherence tools with refill scheduling and educational content delivery.
- Data Analytics:Predictive models for nonadherence risk scoring and intervention targeting.
- Automated Scheduling:AI-driven delivery window optimization and courier route planning.
Widest deployment: Mobile Apps. Steepest investment trajectory: Real-Time Tracking.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand concentrates around Medicare Advantage penetration zones where risk-bearing entities seek to minimize infusion center utilization through direct-to-patient delivery models. Germany and Japan follow with mature specialty pharmacy infrastructure and distinct reimbursement frameworks for home-based biologic administration.
United States
Florida and Texas Medicare Advantage markets drive direct-to-patient volume as payers contract for home delivery of oral oncolytics and subcutaneous biologics. FDA's Drug Supply Chain Security Act mandates unit-level serialization that wholesale distributors must integrate into logistics platforms. Pennsylvania and Arizona host central fill specialty pharmacy hubs anchoring national cold chain distribution networks.
Germany
EU Good Distribution Practice Annex guidelines force wholesale distributors to deploy continuous data loggers for temperature-sensitive shipments across federal states. German industrial corridors around Cologne and Frankfurt concentrate pharmaceutical-grade dry ice production capacity for cryogenic logistics. Dutch and Belgian distributors are pooling qualification resources through shared service centers to meet cross-border compliance requirements.
Japan
Long-term care insurance reimbursement for home nursing support creates structural pull for integrated patient support services alongside specialty drug delivery. PMDA pharmacovigilance timelines require 24/7 nurse helpline staffing for adverse event reporting on biologic therapies. Tokyo and Osaka metropolitan areas concentrate specialty pharmacy infrastructure serving aging patient populations with autoimmune and oncology conditions.
United Kingdom
NHS England's specialized commissioning frameworks are expanding home delivery pathways for high-cost biologics previously administered in hospital settings. MHRA post-Brexit regulatory divergence from EU GDP guidelines creates parallel qualification requirements for cross-channel shipments. London and Southeast England anchor cold chain logistics networks serving both domestic demand and re-export flows to European markets.
Switzerland
Swissmedic's stringent import inspection protocols for temperature-sensitive biologics elevate compliance costs for logistics providers serving the Alpine market. Basel's pharmaceutical manufacturing cluster generates outbound cold chain volumes for global distribution of oncology and immunology therapies. Geneva and Zurich host specialized courier networks handling hand-carried orphan drug deliveries with chain-of-identity documentation.
Specialty Pharma Home Delivery and Patient Support Logistics Market Competitive Landscape
Strategic partnerships dominate the current landscape as wholesale distributors, specialty pharmacies, and third-party logistics providers converge capabilities to capture integrated service contracts. Market structure tilts toward consolidation among vertically integrated health systems and pharmacy benefit managers, with pure-play logistics operators occupying specialized niches in cryogenic and white-glove delivery. Three archetypes define competitive positioning: integrated healthcare conglomerates with captive pharmacy networks, global courier organizations with validated healthcare divisions, and regional specialty pharmacy operators with deep payer relationships. M&A activity and cold chain infrastructure partnerships represent the primary competitive vectors as players seek to control last-mile touchpoints for high-value biologics.
Among integrated healthcare conglomerates, Cencora and McKesson exemplify the wholesale-to-specialty-pharmacy vertical model, leveraging distribution infrastructure to anchor last-mile delivery commitments for complex therapies. FedEx represents the global courier archetype, competing through dedicated healthcare divisions with validated cold chain corridors. These three entities occupy positions spanning the infrastructure ownership spectrum from asset-heavy wholesale networks to asset-light platform operators, illustrating the strategic tension between capital deployment in owned cold chain assets and third-party logistics partnerships.
| Leading Market Players |
|---|
| Cencora |
| McKesson |
| CVS Health |
| UnitedHealth Group |
| The Cigna Group |
| Cardinal Health |
| Option Care Health |
| DHL Group |
| FedEx |
| Others |
Pricing and Supply Chain Analysis
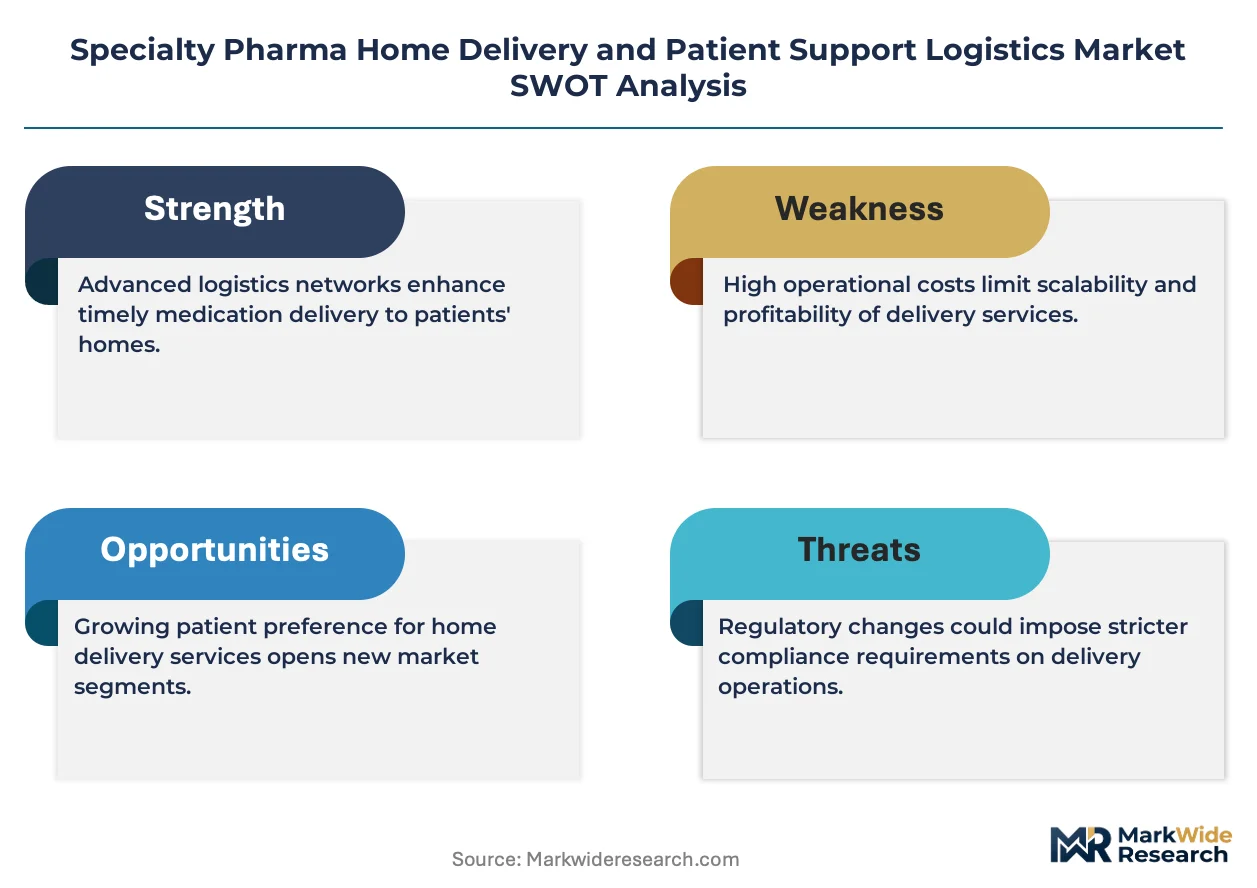
Certification-grade divergence between GDP-validated cold chain corridors and standard pharmaceutical distribution creates tiered economics where thermal packaging qualification costs propagate into per-shipment premiums. This bifurcation concentrates margin capture among operators with in-house validation infrastructure while compressing returns for asset-light intermediaries dependent on third-party qualification.
Pricing Analysis
Volume-margins split sharply between high-frequency oral oncolytic subscriptions and low-volume orphan drug white-glove deliveries. Three-tier pricing structure across premium, standard, and economy levels reflects cold chain validation intensity, with FDA 21 CFR Part 11 compliance commanding substantial premiums over basic temperature monitoring. Pricing pressure stems from qualified thermal shipper scarcity extending packaging qualification timelines beyond biologics launch schedules. Medicare Advantage payers exhibit highest price sensitivity as they internalize infusion center avoidance savings.
Supply Chain Analysis
Phase-change material supply rests on German chemical manufacturers and United States Gulf Coast industrial gas producers with carbon dioxide capture infrastructure. Pharmaceutical-grade dry ice production draws from concentrated feedstock clusters around Cologne and Houston, while reusable thermal packaging fabrication centers on Dutch and Belgian contract manufacturers. Single-source vulnerability runs through dry ice supply given carbon capture facility geographic concentration. Distribution runs through hub-and-spoke specialty pharmacy networks anchored by Pennsylvania and Arizona central fill operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified packaging capacity constraints prop pricing power for validated cold chain operators as biologics volumes outstrip thermal shipper qualification throughput.
For Market Incumbents: Acquire reusable thermal packaging fleets with established ISTA 7E validation protocols to lock in capacity ahead of cell and gene therapy launches. Consolidate regional specialty pharmacy networks in Florida and Texas Medicare Advantage penetration zones to capture direct-to-patient volume shifting from infusion centers. Cencora and McKesson face emerging pressure from pure-play logistics operators unbundling clinical support from dispensing. For New Entrants and Emerging Players: Enter via cryogenic logistics corridors for negative one hundred fifty degrees Celsius cell and gene therapy distribution where incumbent capacity remains underdeveloped. Target Japan's home nursing support reimbursement pathway under long-term care insurance, where integrated patient support services face limited domestic competition. Deploy blockchain-enabled chain-of-custody documentation as a compliance differentiation wedge against legacy operators with paper-based protocols. For Investors and Strategic Acquirers: Re-rating potential sits with regional specialty pharmacy operators possessing deep payer relationships and captive cold chain infrastructure given consolidation pressure from vertically integrated health systems. Long-term viability favors platforms combining logistics execution with real-world evidence generation capabilities as manufacturers seek adherence data for value-based contracts. Watch FDA DSCSA enforcement timelines as an inflection indicator for serialization infrastructure investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Reusable Thermal Packaging Network Deployment | GDP-compliant closed-loop container pools reduce per-shipment costs seventy percent after five rotation cycles in German pilot programs. |
| Continuous Data Logger Integration | Active transmission systems satisfy EU GDP Annex risk-based monitoring mandates displacing passive loggers across wholesale distributors. |
| Specialty Pharmacy Network Consolidation | Central fill hub concentration in Pennsylvania and Arizona anchors national cold chain coverage for oral oncolytic direct-to-patient delivery. |
| Cryogenic Logistics Capability Buildout | Negative one hundred fifty degrees Celsius distribution infrastructure captures cell and gene therapy pipeline volumes requiring chain-of-identity protocols. |
| Real-World Evidence Platform Development | Adherence data integration with telehealth platforms creates outcomes research revenue streams beyond logistics fees for risk-bearing contracts. |
Research Methodology
Independent corroboration across specialty pharmacy operations directors, cold chain logistics engineers, FDA regulatory affairs consultants, and Medicare Advantage formulary managers underwrites the qualitative findings. Primary fieldwork combined with secondary validation from FDA DSCSA guidance documents, EU GDP Annex technical interpretations, ISTA thermal testing protocols, and pharmaceutical wholesale trade association filings established demand-side parameters. Bottom-up shipment volume modeling and top-down market sizing triangulated around service type revenue segmentation.
Comparable-period anchoring to historical cold chain infrastructure investment cycles informed the projection horizon across the analysis window. Segmentation dimensions modeled include service type infrastructure ownership, patient support program clinical labor intensity, distribution channel margin capture position, and technology integration regulatory pathway complexity. CAGRs derived from shipment volume growth rates adjusted for pricing dynamics in qualified packaging-constrained environments. Cryogenic logistics pipeline maturation and connected device telehealth convergence served as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU GDP cross-border enforcement divergence and dry ice feedstock supply disruptions. Forecasts reflect documented assumptions regarding DSCSA serialization timeline adherence and Medicare Advantage penetration trajectories. FDA enforcement intensity, PMDA pharmacovigilance staffing requirements, and carbon capture infrastructure investment warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Surgical Fluid Disposal Market
Healthcare Services
Funeral and Cremation Services Market
Healthcare Services
Eastern Europe Online Pharmacy Market
Healthcare Services
Hospice Market
Healthcare Services
Healthcare Logistics Market
Healthcare Services
US Long Term Care Market
Healthcare Services
Global Infusion Pharmacy Management Market
Healthcare Services
Global Medical Affairs Outsourcing Market
Healthcare Services
Healthcare CRO Services Market
Healthcare Services
Acute Care Market
Healthcare Services
Metabolomics Services Market
Healthcare Services
US Hospice Care Market
Healthcare Services
Global Ambulatory Services Market
Healthcare Services
Assisted Living Market
Healthcare Services
Global Value Based Healthcare Services Market
Healthcare Services
Healthcare Physician Staffing Market