
 Robotic Surgery System Haptic Feedback Test Platforms Market | 2026-2036
Robotic Surgery System Haptic Feedback Test Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Surgery System Haptic Feedback Test Platforms Market Insights
North American precision instrument producers is restructuring supply chains for electromechanical haptic test rigs. Intuitive Surgical leverages captive validation labs in California to accelerate controller certification cycles. Medtronic anchors its test platform procurement through dedicated supplier agreements with electromechanical actuator specialists. Force Dimension competes on European optical force-sensing architectures that reduce calibration drift.
Robotic surgery system haptic feedback test platforms comprise electromechanical, pneumatic, and optical instrumentation that quantifies force resolution, latency thresholds, and tactile fidelity across simulated tissue interfaces. These systems validate surgeon-console feedback loops before clinical deployment, ensuring mechanical arms translate hand motions within millisecond response windows. Multi-modal feedback systems command premium positioning due to their integration complexity across force, tactile, and vibrotactile channels. Minimally invasive surgery applications dominate current procurement volumes, while neurosurgery segments attract concentrated R&D investment from platform developers seeking sub-millimeter precision certification.
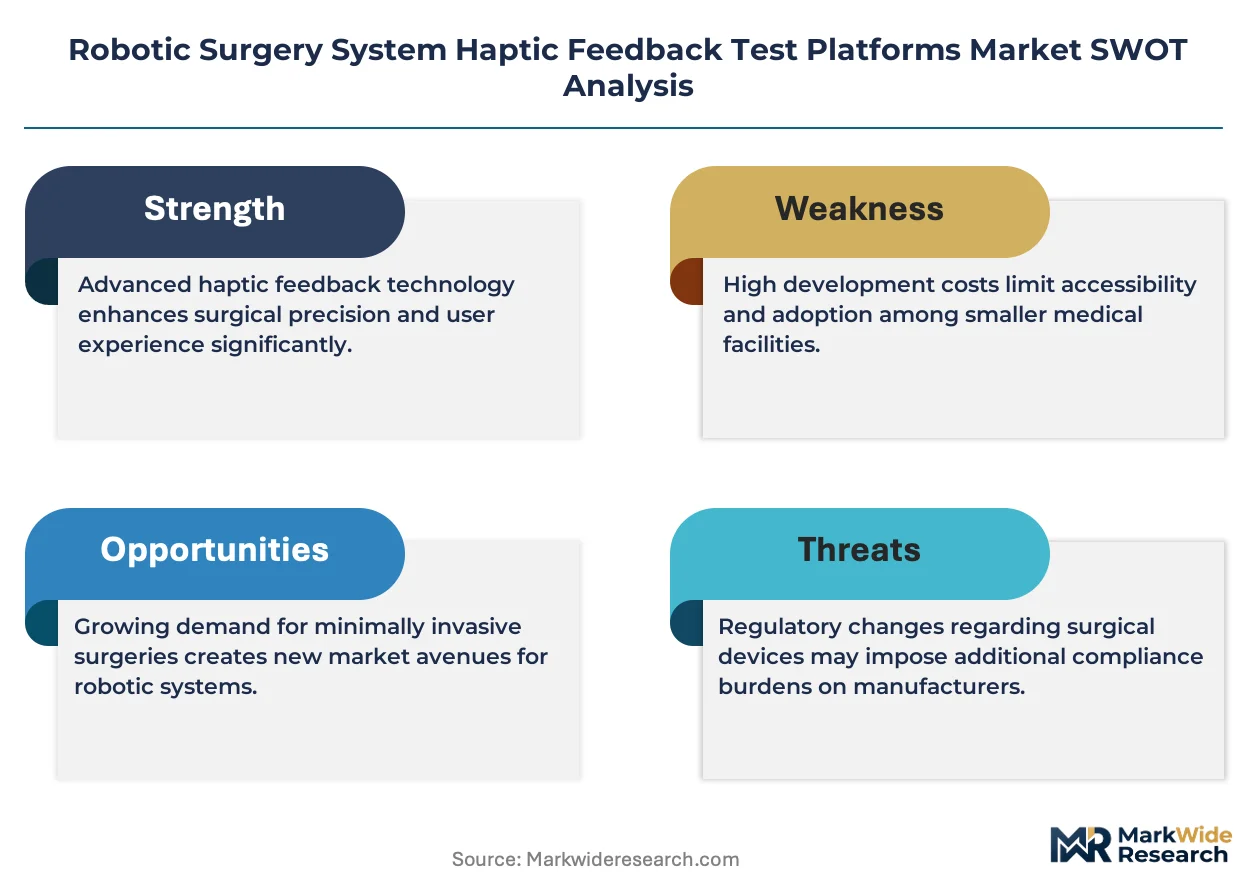
FDA 510(k) premarket notifications and EU MDR conformity assessments govern test protocol stringency for haptic-enabled surgical systems. ISO 13485 quality management standards and IEC 60601 electrical safety requirements further constrain platform design specifications for manufacturers targeting dual-market registration. Stakeholders must track evolving FDA guidance on simulated-use testing as predicate device comparisons give way to patient-specific phantom validation models.
Market Dynamics
Validation protocol convergence between FDA 510(k) and EU MDR is compressing test platform development cycles, forcing manufacturers to design for dual-market certification from initial prototyping stages rather than sequential regulatory submissions.
Growth Catalysts
- EU MDR conformity assessment:Stricter post-market surveillance requirements for haptic-enabled surgical systems are expanding recurring validation service contracts for test platform operators.
- Sub-millimeter precision certification:Neurosurgery applications are demanding force resolution thresholds below 0.1 newtons, creating specialized test rig procurement from academic medical centers.
- Electromechanical actuator miniaturization:Advances in piezoelectric force feedback mechanisms are enabling portable test platforms for distributed validation environments.
Market Restraints
- Optical force-sensing component concentration:European suppliers dominate high-fidelity optical encoder production, exposing test platform manufacturers to single-source supply risk.
- Calibration drift in multi-modal systems:Force-tactile-vibrotactile integration complexity extends recertification intervals, elevating total cost of ownership for validation labs.
- Phantom tissue standardization gaps:Absence of ISO-recognized synthetic tissue analogs forces redundant validation across predicate device comparisons.
Strategic Opportunities
- India CDSCO regulatory harmonization:Emerging local production requirements for imported surgical robotics are creating demand for domestic test platform infrastructure.
- Digital twin convergence:Physics-based simulation software paired with physical test rigs is enabling predictive validation before hardware prototyping.
- Leasing-based validation services:Capital-constrained mid-tier hospitals are adopting subscription access to certified test environments rather than equipment ownership.
Industry Challenges
- Haptic engineer scarcity:Cross-disciplinary expertise spanning mechanical engineering, neuroscience, and regulatory science commands premium compensation, constraining R&D team scaling.
- ISO 13485 documentation burden:Design history file requirements for test platform software revisions extend release cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Surgery System Haptic Feedback Test Platforms Market |
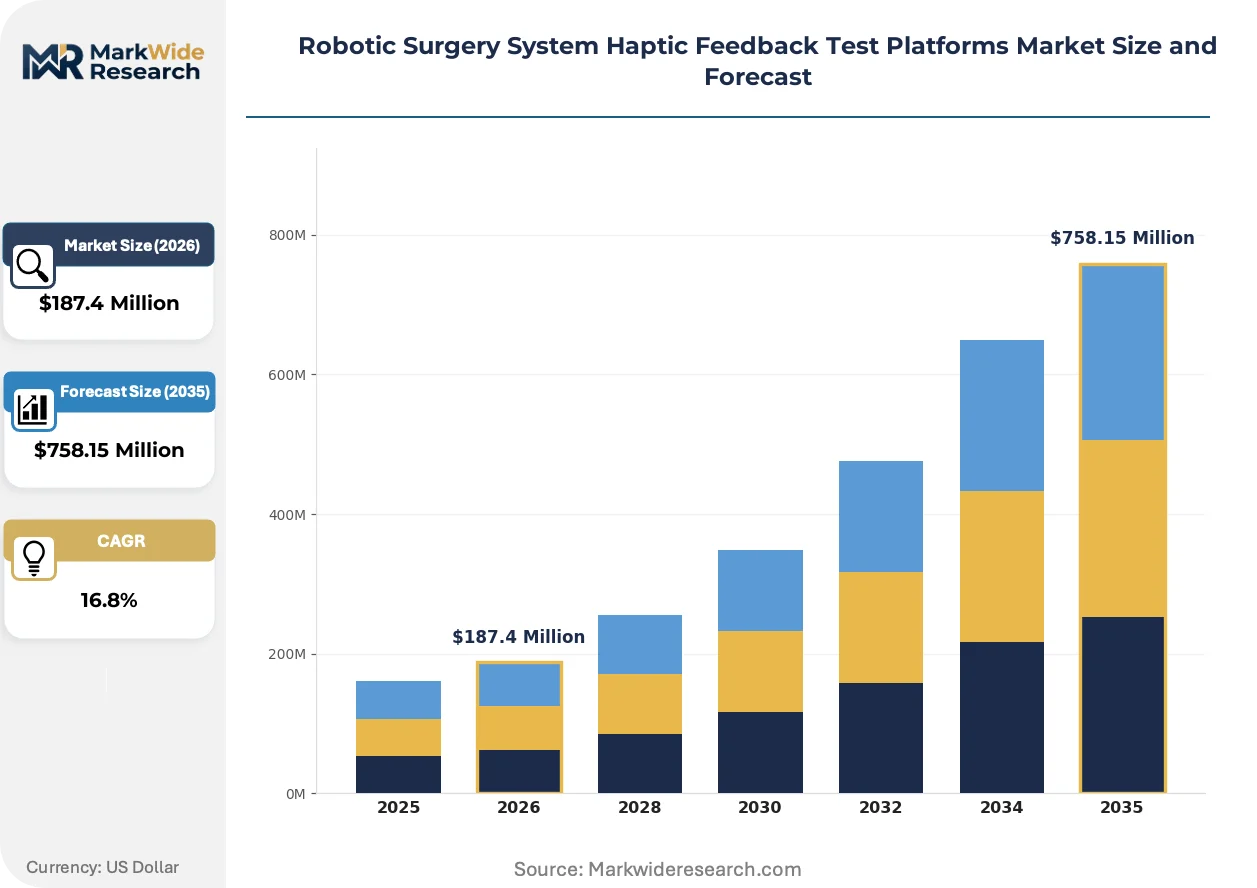
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $758.15 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Force Feedback, Tactile Feedback, Vibrotactile Feedback, Multi-Modal Feedback Technology: Electromechanical, Pneumatic, Hydraulic, Optical, Ultrasonic Application: Minimally Invasive Surgery, Neurosurgery, Orthopedic Procedures, Urologic Surgery, Gynecologic Surgery End User: Surgical Centers, Research Laboratories, Medical Device Manufacturers, Academic Institutions |
| Companies Covered | Intuitive Surgical, Medtronic, CMR Surgical, Distalmotion, 3D Systems, HAPTION, Force Dimension, Neocis, FUTEK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Surgery System Haptic Feedback Test Platforms Market Trends and Innovations
Machine learning inference at the edge is reshaping real-time force signal processing, compressing latency thresholds while complicating electromagnetic compatibility validation for test platform manufacturers.
Optical coherence tomography force sensing is automating sub-surface tissue property detection during simulated procedures. Academic medical centers in Germany and Japan are piloting these systems for neurosurgical phantom validation. The technology is automating calibration protocols that previously required manual technician intervention, reducing test cycle variability.
FDA guidance on simulated-use testing is hardening evidentiary requirements for haptic feedback verification. Predicate device comparisons now require patient-specific phantom models with documented mechanical property variance. Cardiac surgery applications face the steepest compliance burden due to tissue anisotropy complexity.
Consolidated procurement through group purchasing organizations is displacing direct manufacturer relationships for test platform acquisition. Academic medical center networks in the United States are centralizing validation infrastructure investment decisions. This concentration elevates vendor qualification barriers while compressing pricing negotiation cycles.
Robotic Surgery System Haptic Feedback Test Platforms Market Segmentation
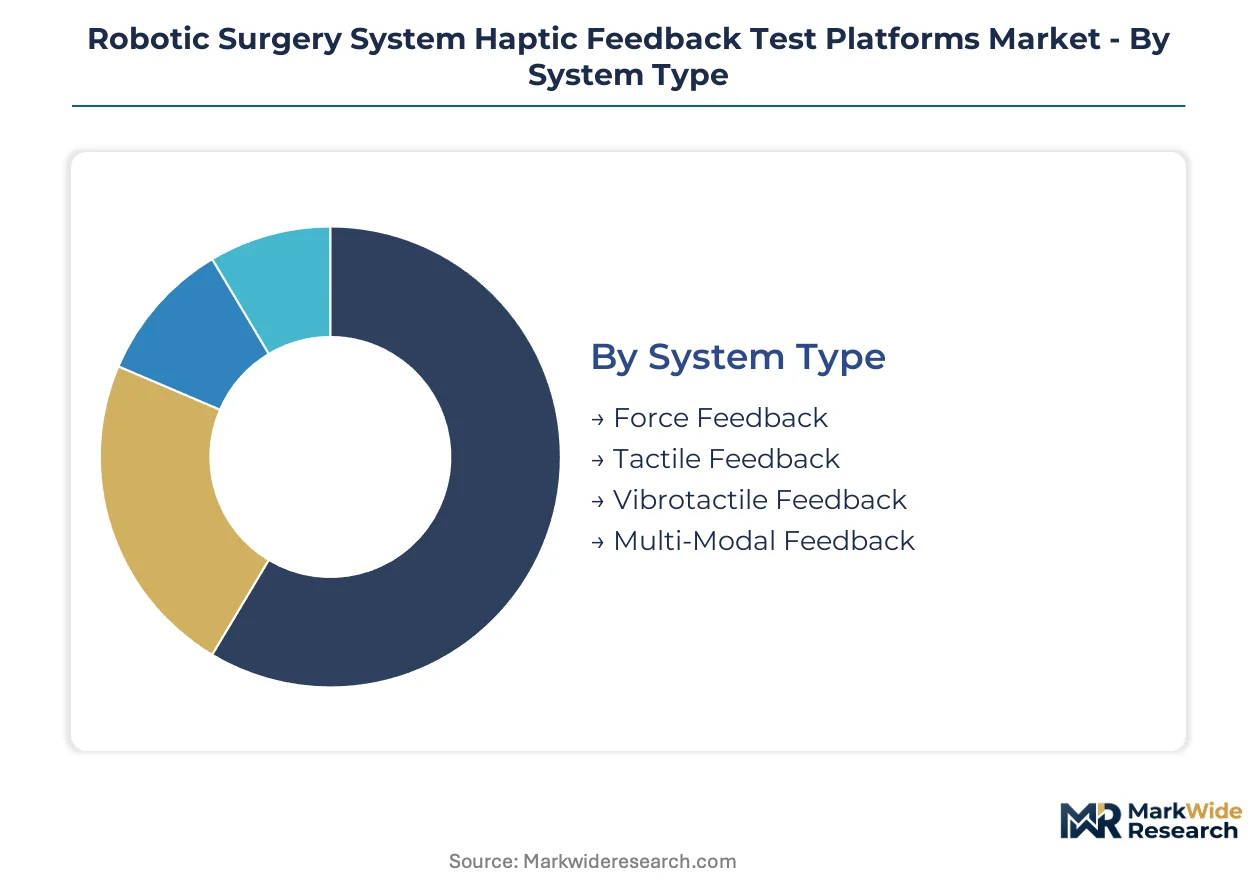
Haptic feedback test platforms segment across functional modalities, underlying physics, surgical disciplines, and procurement entities. Each dimension shapes validation protocol design, calibration complexity, and regulatory documentation burden differently.
System Type:
Customization intensity varies sharply across this spectrum, from standardized force-channel rigs to bespoke multi-modal integrations requiring synchronized signal architecture.
- Multi-Modal Feedback:Combines force, tactile, and vibrotactile channels into unified validation environments. Academic medical centers in the United States commission these systems for neurosurgical phantom studies where sub-millimeter precision certification demands correlated multi-sensory verification.
- Force Feedback:Quantifies kinesthetic resistance through electromechanical actuators. Medical device manufacturers in California anchor procurement volumes here, driven by FDA 510(k) requirements for documented force resolution thresholds prior to surgical console deployment.
- Tactile Feedback:Simulates surface texture discrimination through distributed pressure arrays. Research laboratories favor these platforms for tissue property characterization studies.
- Vibrotactile Feedback:Replicates high-frequency oscillations from instrument-tissue contact. Surgical centers deploy these for laparoscopic instrument validation.
Leading the category by volume: Force Feedback. Growing fastest: Multi-Modal Feedback.
Technology:
Cost tier stratification separates precision instrumentation from commodity pneumatic alternatives, with optical and ultrasonic systems commanding development-stage premiums.
- Optical:Employs interferometric force sensing to eliminate electromagnetic interference in high-precision validation. German academic centers pilot these systems for cardiac surgery phantom studies where tissue anisotropy complicates mechanical property measurement.
- Electromechanical:Leverages piezoelectric actuators and strain gauge arrays for portable, calibrated force generation. Medical device manufacturers dominate procurement, compelled by EU MDR conformity assessment requirements for documented electromechanical safety under IEC 60601.
- Pneumatic:Uses compressed air bellows for cost-effective force rendering. Mid-tier surgical centers in India adopt these for CDSCO-mandated pre-import validation.
- Hydraulic:Delivers high-force output for orthopedic instrument testing. Research laboratories maintain limited installed base.
- Ultrasonic:Integrates acoustic radiation force for non-contact tissue characterization. Japanese medical centers experiment with these for sub-surface phantom property detection.
Highest installed base: Electromechanical. Steepest expansion trajectory: Optical.
Application:
Customer type determines specification stringency, with commercial manufacturers demanding reproducible protocols versus academic investigators prioritizing experimental flexibility.
- Minimally Invasive Surgery:Validates laparoscopic and endoscopic instrument feedback across general surgery procedures. Medical device manufacturers concentrate procurement here, driven by volume certification requirements for da Vinci-compatible instrument lines.
- Neurosurgery:Demands force resolution below 0.1 newtons for sub-millimeter precision certification. Academic institutions in Germany and Japan commission specialized test rigs, compelled by institutional review board requirements for phantom-based skill assessment prior to cadaveric training.
- Orthopedic Procedures:Requires high-force validation for arthroscopic shavers and drills. Surgical centers maintain dedicated platforms for joint replacement instrument verification.
- Urologic Surgery:Focuses on prostate and renal procedure simulation. Research laboratories develop procedure-specific phantom models.
- Gynecologic Surgery:Validates hysteroscopic and laparoscopic feedback systems. Medical device manufacturers address this segment through targeted 510(k) submissions.
Dominant procurement volume: Minimally Invasive Surgery. Gaining share fastest: Neurosurgery.
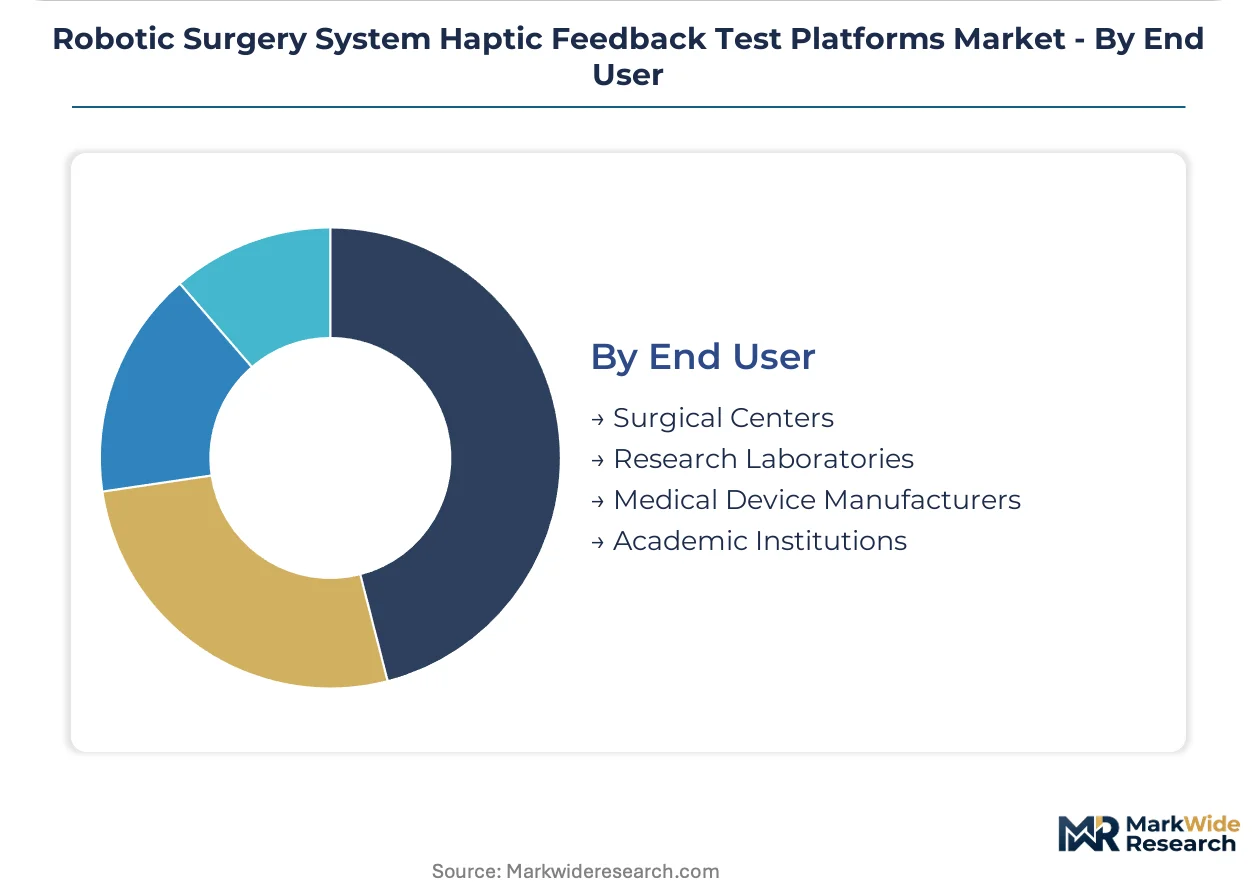
End User:
Geographic concentration of validation infrastructure shapes regional demand patterns, with original equipment manufacturer co-location driving United States market depth.
- Medical Device Manufacturers:Operate captive validation labs for regulatory submission documentation. Intuitive Surgical and Medtronic anchor California and Minnesota test platform procurement, compelled by FDA premarket notification timelines and predicate device comparison requirements.
- Academic Institutions:Pursue NIH-funded research into haptic rendering algorithms. Johns Hopkins and Stanford maintain specialized neurosurgical phantom facilities.
- Research Laboratories:Develop next-generation force sensing modalities. Fraunhofer Institute and Tokyo Institute of Technology lead optical coherence tomography force sensing pilots.
- Surgical Centers:Adopt leasing-based validation services for instrument recertification. Mid-tier hospitals in Texas and Florida subscribe to shared test infrastructure rather than capital ownership.
Largest installed base: Medical Device Manufacturers. Expanding most quickly: Academic Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's electromechanical actuator cluster anchors North American test platform development, while German optical encoder manufacturers supply precision instrumentation to academic validation centers worldwide.
United States
FDA 510(k) premarket notification timelines compel medical device manufacturers to maintain captive validation laboratories. Intuitive Surgical operates dedicated test facilities in California's Bay Area to compress controller certification cycles. Academic medical centers in Texas and Florida are adopting leasing-based validation services rather than capital equipment ownership.
Germany
EU MDR conformity assessment requirements for haptic-enabled surgical systems are expanding recurring validation contracts for test platform operators. Fraunhofer Institute pilots optical coherence tomography force sensing for neurosurgical phantom studies in Munich. The country's automotive precision engineering base supplies piezoelectric actuator components to electromechanical rig manufacturers.
Japan
PMDA regulatory harmonization with FDA standards is accelerating dual-market certification protocols for surgical robotics exporters. Tokyo Institute of Technology maintains specialized facilities for sub-millimeter precision certification in neurosurgery applications. METI funding programs support domestic test infrastructure for next-generation force sensing modalities.
India
CDSCO local production requirements for imported surgical robotics are creating demand for domestic test platform infrastructure. Maharashtra-based surgical centers adopt pneumatic validation systems for cost-effective pre-import compliance. The country's medical device PLI scheme incentivizes captive validation laboratory construction by multinational manufacturers.
China
NMPA innovation pathway approvals for robotic surgical systems are expanding third-party validation service demand. Yangtze River Delta medical device clusters in Shanghai and Suzhou are investing in multi-modal feedback test rigs for 510(k) predicate device comparisons. Domestic actuator manufacturers are developing optical force-sensing alternatives to reduce European component dependency.
Robotic Surgery System Haptic Feedback Test Platforms Market Competitive Landscape
Global majors compete with regional champions across regulatory certification expertise and actuator technology specialization. The market exhibits tiered concentration, with integrated surgical robotics manufacturers operating captive validation divisions alongside independent electromechanical test rig specialists. Three archetypes dominate: vertically integrated surgical system OEMs, precision actuator component suppliers, and academic spin-off technology developers. Competitive dynamics center on strategic partnerships between test platform vendors and medical device manufacturers, plus geographic expansion into emerging regulatory jurisdictions.
Among integrated surgical robotics manufacturers, Intuitive Surgical and Medtronic occupy positions exemplifying captive validation laboratory strategies, while Force Dimension represents the European precision instrumentation archetype specializing in optical force-sensing architectures. These entities anchor distinct competitive vectors—OEMs leveraging regulatory submission speed, independent specialists competing on calibration stability and multi-modal integration depth.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Medtronic |
| CMR Surgical |
| Distalmotion |
| 3D Systems |
| HAPTION |
| Force Dimension |
| Neocis |
| FUTEK |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between FDA 510(k) predicate-validated rigs and CDSCO-compliant pneumatic alternatives manifests in both capital expenditure thresholds and component sourcing strategies. Premium multi-modal systems command three-tier pricing structures across validation-grade, research-grade, and compliance-grade tiers, with electromechanical actuator provenance determining warranty coverage and calibration service bundling.
Pricing Analysis
Warranty and calibration service bundling separates premium European optical platforms from unbundled Asian pneumatic alternatives. The dominant pricing model runs through subscription-based validation services for mid-tier surgical centers, while manufacturers pay premium rates for captive laboratory certification. Price differentiation hinges on ISO 13485 documentation depth and EU MDR conformity assessment tier. Pricing pressure stems from group purchasing organization consolidation in United States academic medical center networks. Mid-tier hospitals in India exhibit highest price sensitivity, whereas California-based OEMs prioritize submission speed over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and California anchor hub-and-spoke fulfillment patterns for precision actuator components. Geographic supply concentrates in Germany for optical encoders, Japan for piezoelectric materials, and California for electromechanical integration. Raw material dependencies include interferometric sensors, strain gauge arrays, and compressed air bellows. Single-source vulnerability in European optical encoder production elevates supply risk for multi-modal platform manufacturers. Distribution runs through direct supplier agreements for OEM captive labs and leasing-service intermediaries for hospital subscribers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over electromechanical actuator supply determines certification cycle compression. Players are pursuing backward integration into piezoelectric component manufacturing to secure calibration stability.
For Market Incumbents: Anchor defensive positioning through captive validation laboratory expansion in California and Minnesota to compress FDA 510(k) timelines. Consolidate supplier agreements with German optical encoder manufacturers to mitigate single-source exposure. Prioritize ISO 13485 documentation automation to reduce software revision release cycles by four to six months. Threat substitution from digital twin simulation platforms demands physical-digital hybrid certification offerings. For New Entrants and Emerging Players: Direct-to-academic-channel routes through NIH-funded research laboratory partnerships offer lowest competitive density. Target neurosurgery phantom validation segments where sub-millimeter precision certification commands premium positioning and incumbent presence remains thin. Pursue CDSCO harmonization consulting services as Indian domestic production requirements expand. Go-to-market leverage rests on leasing-based validation service models for capital-constrained mid-tier hospitals. For Investors and Strategic Acquirers: Re-rating potential sits with academic spin-off technology developers given FDA guidance hardening on simulated-use testing evidentiary requirements. Long-term viability across a five-to-ten year window favors entities controlling optical force-sensing intellectual property alongside regulatory submission expertise. Acquisition target archetype: European precision instrumentation specialists with calibration-stable multi-modal integration capabilities. Signal to watch: patient-specific phantom model standardization progress through ISO recognition pathways.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Captive validation laboratories in California compress controller certification cycles for Intuitive Surgical. |
| EU MDR Conformity Assessment Investment | German academic centers expand recurring validation service contracts for test platform operators. |
| Optical Force-Sensing Technology Licensing | Fraunhofer Institute pilots enable sub-surface tissue property automation for neurosurgical phantoms. |
| Backward Integration into Actuator Components | Piezoelectric supply control reduces calibration drift exposure in multi-modal feedback systems. |
| Leasing-Based Validation Service Launch | Mid-tier hospitals in Texas and Florida adopt subscription access over capital equipment ownership. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with biomedical engineers, hospital purchasing committees, GPO contracts managers, and regulatory affairs specialists at medical device manufacturers. FDA 510(k) premarket notification databases, EU MDR conformity assessment registries, CDSCO import compliance records, and academic medical center procurement databases supplied quantitative validation. Bottom-up test platform shipment analysis triangulated against top-down surgical robotics deployment forecasts.
Data-stream reconciliation across electromechanical, optical, pneumatic, and ultrasonic technology categories informed segmentation-level projections. The analytical framework modeled system type, underlying physics, surgical discipline application, and end-user procurement entity dimensions throughout the forecast period. CAGRs derived from regression analysis of historical validation infrastructure investment against robotic surgical system deployment trajectories. Industry-specific inputs included phantom tissue standardization progress and haptic engineer compensation inflation.
Inputs from FDA premarket notification databases and EU MDR assessment registries were available through the study window; gaps in ISO-recognized synthetic tissue analog development introduce uncertainty bands around neurosurgery segment projections. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and calibration stability improvements. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Global Cold Plasma in Healthcare Market
Diagnostic and Therapeutic Devices
Germany Smart Healthcare Market
Diagnostic and Therapeutic Devices
Global Smart Inhaler Technology Market
Diagnostic and Therapeutic Devices
Therapeutic Support Surface Market
Diagnostic and Therapeutic Devices
Therapeutic Catheters Market
Diagnostic and Therapeutic Devices
Disposable Negative Pressure Wound Therapy Devices Market
Diagnostic and Therapeutic Devices
Pelvic Congestion Syndrome Treatment Market
Diagnostic and Therapeutic Devices
Microneedle Drug Delivery Systems Market
Diagnostic and Therapeutic Devices
Therapeutic Hypothermia Systems Market
Diagnostic and Therapeutic Devices
US Cancer Contrast Media Market
Diagnostic and Therapeutic Devices
Smart Drug Delivery Systems Market
Diagnostic and Therapeutic Devices
Vacuum Therapy Devices Market
Diagnostic and Therapeutic Devices
Automated Immunoassay Analyzers Market
Diagnostic and Therapeutic Devices
Pressure Ulcer Relief Products Market
Diagnostic and Therapeutic Devices
Global Far Infrared Therapy Device Market
Diagnostic and Therapeutic Devices
Cruciate Ligament Diagnosis Treatment Market