
 Radiofrequency (RF) Ablation System Market | 2026-2036
Radiofrequency (RF) Ablation System Market Size, Share, and Industry Trends Forecast 2026-2036
Radiofrequency (RF) Ablation System Market Analytics
Hospital procurement channels for electrophysiology equipment is tilting toward bundled service contracts that span capital equipment, disposables, and remote monitoring. Medtronic leverages its integrated catheter and mapping system portfolio to capture multi-year agreements with integrated delivery networks. Boston Scientific Corporation anchors its position through specialized sales forces embedded in high-volume cardiac centers. Abbott differentiates via physician training ecosystems that lock in loyalty across the ablation workflow.
Radiofrequency ablation systems deliver thermal energy at 460–480 kHz through specialized electrodes to destroy pathological tissue while sparing adjacent structures, serving primarily cardiac arrhythmia treatment and tumor reduction. Temperature-controlled RF dominates installed base economics due to predictable lesion formation and established reimbursement codes, while pulsed RF gains traction in pain management for its non-thermal neural modulation mechanism. Catheter-based delivery mode leads cardiology revenue pools, though needle-based systems capture margin concentration in interventional oncology and chronic pain clinics.
FDA premarket notification requirements and EU MDR technical documentation obligations shape product development timelines and clinical evidence thresholds for manufacturers seeking market access. Japan's PMDA enforces stringent electrical safety and biocompatibility standards under JIS frameworks that filter out lower-specification entrants. Stakeholders must weigh regulatory capital requirements against the margin compression risk from ambulatory surgery center migration and value-based care contracting.
Market Dynamics
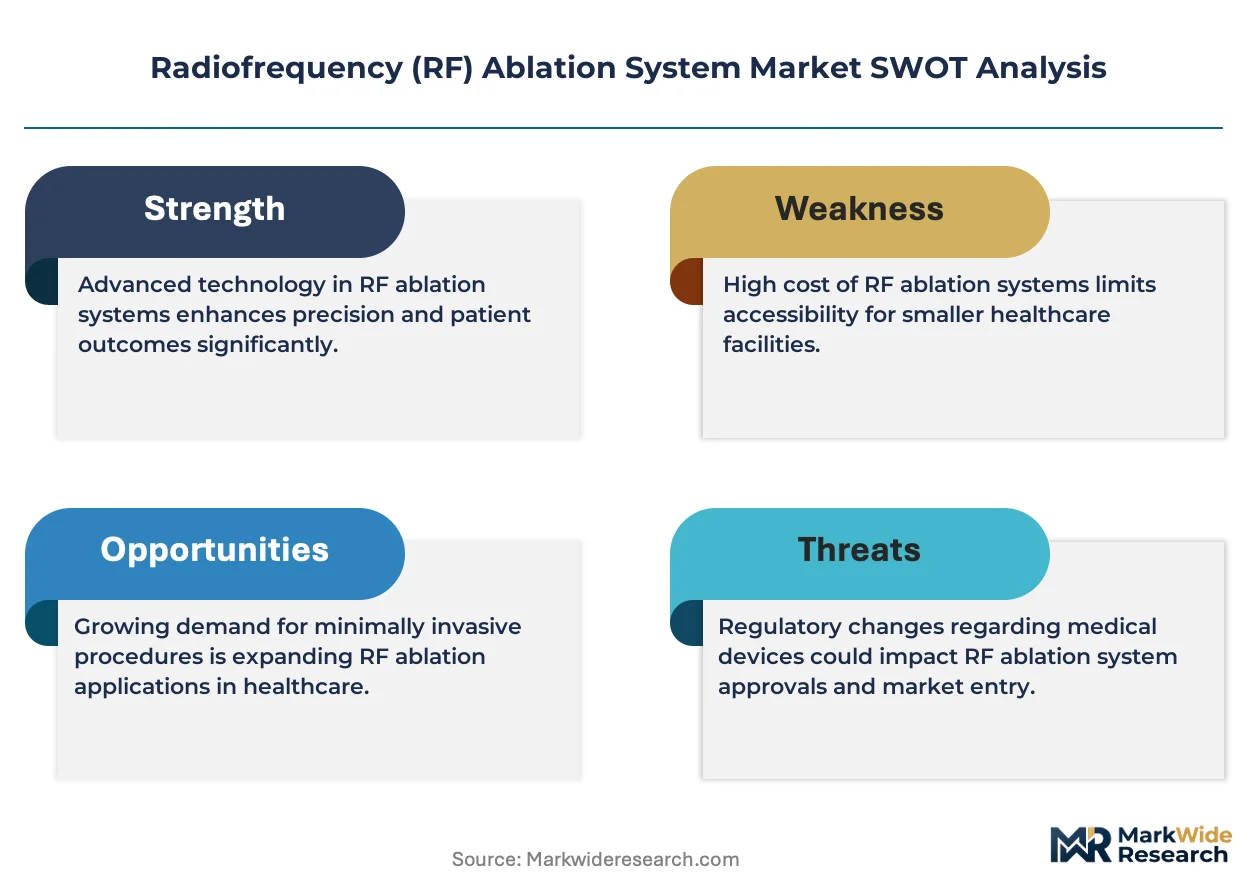
Bundled service contracts spanning capital equipment, disposables, and remote monitoring are restructuring hospital procurement economics for electrophysiology systems, compressing standalone equipment margins while locking in multi-year vendor relationships.
Growth Catalysts
- Atrial fibrillation procedure volumes:Tertiary hospital cardiology departments are expanding electrophysiology lab capacity to address rising arrhythmia prevalence, particularly in markets with established reimbursement frameworks.
- Temperature-controlled RF catheter technology:Predictable lesion formation characteristics are accelerating physician adoption and supporting favorable coverage determinations from payers.
- EU MDR transition:Stricter technical documentation and clinical evidence requirements for Class III devices are filtering out lower-specification competitors and consolidating compliant manufacturers.
Market Restraints
- Capital equipment intensity:Three-dimensional electroanatomic mapping systems require substantial upfront investment, limiting penetration in resource-constrained healthcare systems.
- Pulsed RF substitution in pain management:Non-thermal neural modulation mechanisms are capturing share from traditional thermal RF in chronic pain clinics, fragmenting the installed base.
- EU MDR compliance costs:Extended clinical evaluation timelines and notified body capacity constraints are delaying market access for new catheter iterations.
Strategic Opportunities
- Interventional oncology expansion:Needle-based RF systems for liver and lung tumor ablation remain underpenetrated in outpatient settings relative to cardiac applications.
- Japan's aging demographic:PMDA's streamlined priority review pathways for innovative cardiovascular devices create favorable regulatory terrain for next-generation catheter platforms.
- Remote monitoring integration:Convergence of RF ablation systems with cloud-based arrhythmia surveillance enables recurring revenue models beyond procedural disposables.
Industry Challenges
- Electrophysiologist training pipelines:Procedural complexity and extended learning curves for advanced mapping integration are constraining qualified operator supply.
- Legacy system interoperability:Catheter compatibility across competing generator platforms requires ongoing engineering investment to maintain hospital flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiofrequency (RF) Ablation System Market |
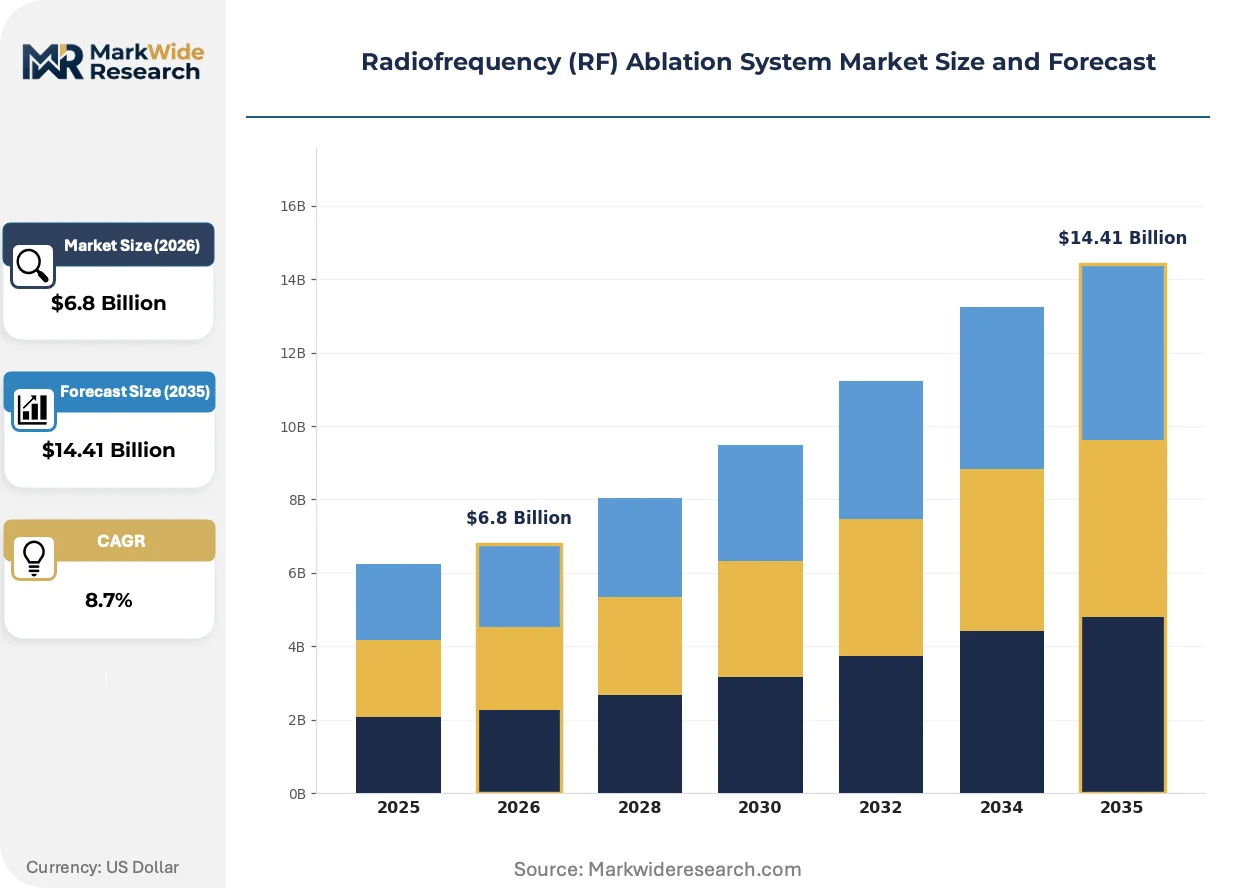
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature-Controlled RF, Pulsed RF, Cryoablation Systems, Accessories Therapy Area: Cardiology, Oncology, Pain Management, Gastroenterology End User: Hospitals, Ambulatory Surgery Centers, Clinics, Research Institutions Delivery Mode: Catheter-Based, Needle-Based, Balloon-Based, Others |
| Companies Covered | Medtronic, Boston Scientific Corporation, Johnson & Johnson Services, Inc., Abbott, Stryker, AngioDynamics, AtriCure, Inc., Avanos Medical, Smith & Nephew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiofrequency (RF) Ablation System Market Evolving Landscape
Force-sensing catheter technology is compressing procedure times and improving lesion consistency, while regulatory frameworks on both sides of the Atlantic are elevating clinical evidence thresholds for market access.
Contact-force sensing integrated into RF ablation catheters is rendering obsolete empirically guided lesion delivery that relied solely on temperature and impedance feedback. High-volume cardiac centers in Germany and the United States are standardizing force-guided workflows within eighteen-month capital replacement cycles. This capability shift is rendering obsolete standalone temperature-controlled systems that lack real-time tissue contact quantification, pressuring manufacturers to bundle force sensors as baseline features.
MDR technical documentation requirements for electrophysiology devices are extending premarket approval timelines and expanding post-market surveillance obligations. Manufacturers must now generate prospective clinical data for catheter iterations that previously cleared through equivalence pathways. Temperature-controlled RF catheter portfolios face the steepest compliance burden, with notified body backlogs in Germany and the Netherlands delaying certificates of conformity.
Integrated delivery networks are consolidating electrophysiology equipment purchasing through multi-year managed service agreements that unbundle capital ownership from procedural utilization. Standalone equipment vendors are losing access to catheter purchasing committees as hospital systems prioritize total cost-per-procedure metrics. This contract structure transformation is most visible in United States metropolitan markets where three-hospital systems dominate arrhythmia service line planning.
Radiofrequency (RF) Ablation System Market Segmentation
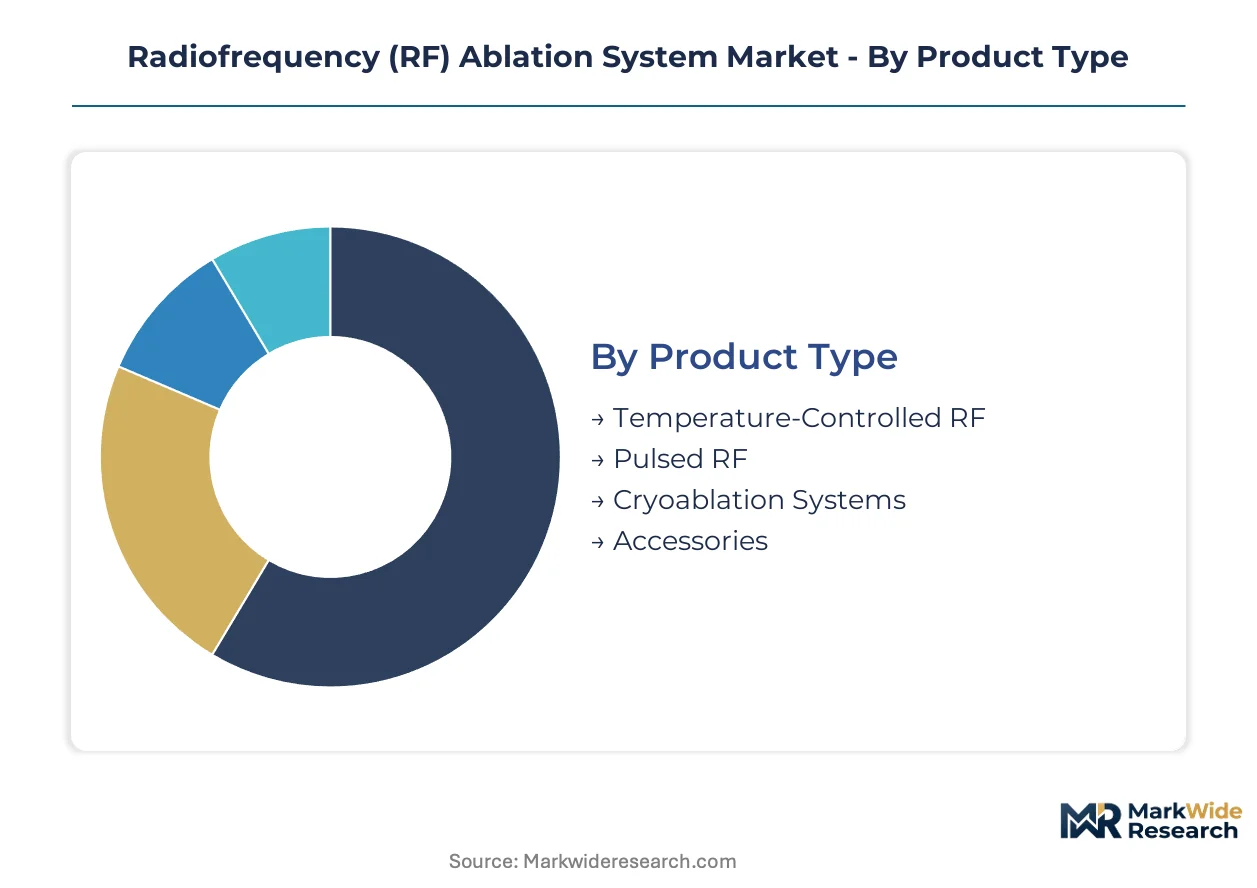
Segmentation in the RF ablation market reveals divergent equipment lifecycles and procurement economics across therapeutic domains. Replacement cycles stretch from eighteen-month catheter platform upgrades to seven-year generator installations, creating distinct vendor revenue rhythms.
Product Type:
Equipment refresh cycles vary dramatically across this category, with disposable catheter platforms turning over fastest and capital-intensive generators anchoring long-term vendor relationships.
- Temperature-Controlled RF:Thermal energy delivery at precisely regulated temperatures enables predictable lesion formation in cardiac tissue. Tertiary hospital cardiology departments in the United States concentrate demand here, driven by established CPT reimbursement codes for atrial fibrillation ablation.
- Pulsed RF:Non-thermal neural modulation through pulsed electrical fields spares adjacent tissue while disrupting pain signaling. Pain management clinics in Germany are adopting these systems fastest, constrained only by limited long-term outcome data in chronic neuropathy cases.
- Cryoablation Systems:Balloon-based freezing technology competes directly with thermal RF in pulmonary vein isolation procedures.
- Accessories:Irrigation tubing, grounding pads, and connector cables complete procedural setups with recurring purchase requirements.
Temperature-Controlled RF anchors the volume base while Pulsed RF gains share at the steepest rate.
Therapy Area:
Clinical evidence thresholds and reimbursement maturity create starkly different margin profiles across therapeutic applications.
- Cardiology:Electrophysiology labs generate the highest procedure volumes, with force-sensing catheter technology now standard in high-volume German and Japanese centers.
- Oncology:Percutaneous tumor ablation for liver and lung malignancies operates on thinner margins, with needle-based systems dominating interventional radiology suites.
- Pain Management:Chronic back and neuropathic pain applications are expanding fastest in ambulatory settings, though pulsed RF substitution is fragmenting traditional thermal RF demand.
- Gastroenterology:Barrett's esophagus and gastric antral vascular ectasia represent niche applications with limited dedicated catheter development.
Cardiology commands the revenue concentration while Pain Management climbs fastest outside traditional hospital procurement channels.
End User:
Site-of-care migration is restructuring purchasing authority and contract structures across the customer base.
- Hospitals:Tertiary cardiac centers consolidate electrophysiology service lines through multi-year managed equipment agreements spanning generators, mapping systems, and catheter supplies.
- Ambulatory Surgery Centers:Outpatient arrhythmia procedures are accelerating fastest in United States metropolitan markets, though capital equipment intensity limits independent ASC penetration.
- Clinics:Pain management and interventional oncology procedures concentrate in physician-owned settings with lower overhead structures.
- Research Institutions:Academic medical centers drive force-sensing and pulsed RF technology validation through prospective clinical trials.
Hospitals retain the installed base dominance while Ambulatory Surgery Centers expand most quickly where regulatory and reimbursement conditions permit.
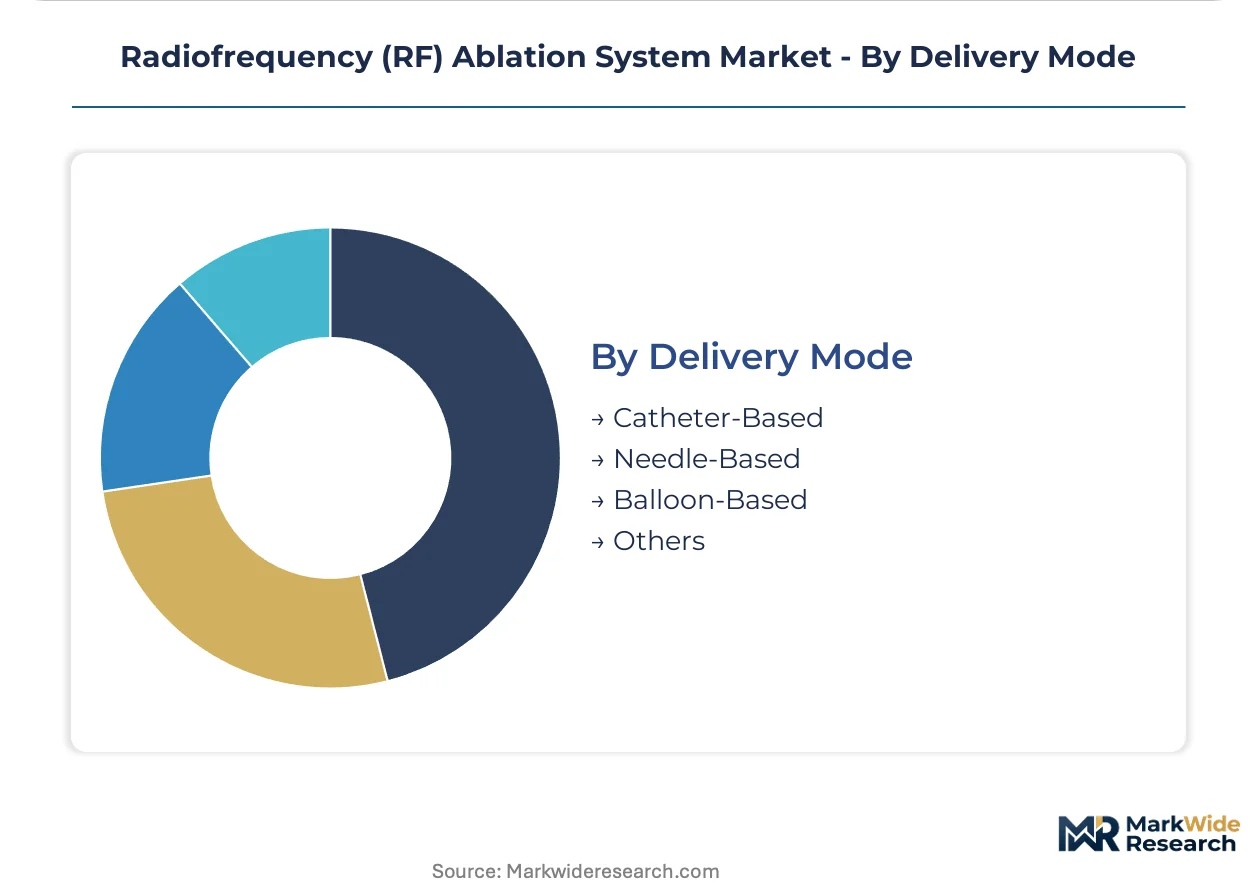
Delivery Mode:
Physical access mechanisms determine compatibility requirements and cross-platform interoperability challenges.
- Catheter-Based:Steerable, multi-electrode designs integrate with three-dimensional electroanatomic mapping systems for cardiac ablation workflows.
- Needle-Based:Percutaneous probes target solid organ tumors and neural structures with direct image guidance.
- Balloon-Based:Cryothermal balloon platforms compete in pulmonary vein isolation with single-shot lesion delivery advantages.
- Others:Microwave and irreversible electroporation modalities occupy adjacent thermal and non-thermal ablation categories.
Catheter-Based systems anchor procedural volume while Needle-Based platforms capture margin concentration in interventional oncology expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical device logistics hub underwrites Europe's distribution centrality for electrophysiology equipment, while the Trans-Pacific submarine cable network enables real-time remote procedure support from United States cardiac centers to Asia-Pacific training sites.
United States
Tertiary hospital cardiology departments in Cleveland Clinic and Mayo Clinic networks drive catheter demand through expanded electrophysiology lab capacity. FDA 510(k) clearance pathways for temperature-controlled RF systems maintain stringent clinical evidence thresholds. The Minneapolis-St. Paul medical device cluster anchors generator manufacturing and force-sensing catheter R&D.
Germany
Charité Berlin and Heidelberg University Hospital standardize force-sensing workflows within accelerated capital replacement cycles. EU MDR notified body backlogs in Munich and Stuttgart delay certificates of conformity for catheter iterations. The Baden-Württemberg precision engineering corridor concentrates mapping system component fabrication.
Japan
PMDA priority review pathways for innovative cardiovascular devices accelerate next-generation catheter platform approvals. JIS electrical safety standards filter lower-specification competitors from hospital procurement tenders. The Tokyo-Osaka medical corridor dominates high-volume cardiac center concentration and physician training ecosystem development.
China
NMPA Class III device registration reforms streamline market access for multinational temperature-controlled RF portfolios. National reimbursement catalog expansions for atrial fibrillation ablation procedures drive hospital procurement volume. The Shanghai-Suzhou medical technology zone concentrates domestic catheter manufacturing and electrophysiology equipment assembly.
United Kingdom
NHS England specialized commissioning frameworks for complex arrhythmia procedures concentrate demand in London and Manchester cardiac centers. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR clinical evidence standards. The Cambridge-Oxford medical research triangle validates pulsed RF applications through prospective clinical trials.
Radiofrequency (RF) Ablation System Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in catheter electrode and sensor supply. The vendor base concentrates around three structural tiers: diversified medical technology conglomerates with full electrophysiology portfolios, mid-scale cardiovascular device firms with mapping-integrated offerings, and niche pain management equipment suppliers. Strategic archetypes include bundled service contract providers, force-sensing technology specialists, and ambulatory surgery center-focused disposables vendors. Competitive moves center on multi-year managed equipment agreements with integrated delivery networks and physician training ecosystem investments that lock procedural workflow loyalty.
Among diversified medical technology conglomerates, Medtronic, Boston Scientific Corporation, and Abbott exemplify platform integrators that anchor the competitive structure through catheter-generator-mapping system bundles. These entities occupy positions defined by installed base scale and integrated service contract penetration rather than standalone product differentiation. Their geographic footprints span United States, European, and Asia-Pacific hospital procurement channels with equivalent regulatory compliance infrastructure.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Johnson & Johnson Services, Inc. |
| Abbott |
| Stryker |
| AngioDynamics |
| AtriCure, Inc. |
| Avanos Medical |
| Smith & Nephew |
| Others |
Value Network & Pricing Analysis
Overcapacity in generator manufacturing across the Minneapolis-St. Paul medical device cluster is compressing capital equipment margins while catheter disposables retain pricing power through proprietary connector interfaces and bundled service contract lock-in.
Pricing Analysis
Three-tier pricing structure across premium force-sensing, standard temperature-controlled, and economy non-sensor catheter levels stratifies hospital procurement committees by procedure volume and EP lab sophistication. Price differentiation hinges on FDA 510(k) clearance tier and real-time contact-force data integration, with premium tiers commanding substantial markups for lesion consistency guarantees. Pricing pressure stems from ambulatory surgery center migration and GPO-negotiated volume discounts that erode standalone equipment margins. Integrated delivery networks exhibit lowest price sensitivity due to total cost-per-procedure contracting, while independent pain management clinics drive hardest bargain on needle-based RF systems.
Supply Chain Analysis
Upstream feedstock for catheter electrodes draws from platinum-iridium alloy suppliers concentrated in Germany and Japan, with sensor microfabrication anchored in Taiwan semiconductor foundries. Raw material dependencies center on biocompatible polymers for catheter shafts, precision-wound coil electrodes, and force-sensing strain gauge arrays. Supply chain risk crystallizes around single-source vulnerability for force-sensor MEMS chips subject to foundry allocation constraints. Distribution runs through specialized medical device logistics hubs—Rotterdam for European hospital systems, Memphis for United States integrated delivery networks—with temperature-controlled cold chain requirements for certain biologic-integrated catheter platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cryoablation balloon systems and pulsed RF neural modulation platforms constitute the substitution frontier that thermal RF incumbents must neutralize through workflow integration and outcome data superiority.
For Market Incumbents: Insulate catheter-generator installed bases by embedding force-sensing technology as standard features before competitors achieve regulatory parity, and deepen backward integration into sensor microfabrication to neutralize foundry allocation risks. Priority investments should target cloud-based arrhythmia surveillance platforms that convert procedural disposables into recurring SaaS revenue streams, locking hospital systems into multi-year managed service agreements that raise switching costs against cryoablation substitutes. For New Entrants and Emerging Players: Pursue needle-based RF oncology applications in United States metropolitan ambulatory surgery centers where capital equipment intensity limits incumbent penetration, and target pulsed RF pain management clinics in Germany where reimbursement frameworks favor non-thermal alternatives. Go-to-market positioning should emphasize per-procedure disposable economics over capital ownership, bypassing three-dimensional mapping system compatibility requirements that gate cardiac catheter segments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform integrators with cloud-connected generator fleets and catheter subscription models, suggesting superior cash flow quality relative to standalone equipment vendors. Long-term viability across the analysis window favors acquisition targets with force-sensor IP portfolios and established physician training ecosystems. The signal to watch is EU MDR certificate of conformity backlog resolution—accelerated approvals for next-generation catheter platforms will separate compliant manufacturers from stranded legacy product lines.| Strategic Initiative | Industry Significance |
|---|---|
| Force-Sensor Integration | Real-time contact quantification from Biosense Webster and Abbott catheters is rendering temperature-only systems obsolete within eighteen-month replacement cycles. |
| Cloud-Based Arrhythmia Surveillance | Remote monitoring platforms from Medtronic enable recurring revenue models beyond procedural disposables, tightening hospital system lock-in. |
| EU MDR Compliance Acceleration | Notified body backlog clearance in Germany and Netherlands will determine which catheter portfolios maintain European market access. |
| ASC-Focused Disposable Economics | Needle-based RF systems with lower capital intensity capture margin concentration as outpatient oncology procedures migrate from hospital settings. |
| PMDA Priority Review Pathway | Japan's streamlined cardiovascular device approvals create first-mover advantages for next-generation catheter platforms in aging demographic markets. |
Research Methodology
Initial hypotheses were tested against primary input from electrophysiologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers, and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, and hospital procurement contract registries. Bottom-up triangulation across catheter shipment volumes and generator installation records was cross-checked with top-down spending estimates from integrated delivery network capital expenditure disclosures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across product type, therapy area, end user, and delivery mode dimensions plus regulatory approval tier as an industry-specific stratifier. CAGRs were derived from procedure volume elasticity to reimbursement coverage expansion and electrophysiologist supply constraints. Forecast inputs incorporated PMDA priority review pathway throughput rates and EU MDR notified body capacity constraints as supply-side moderators.
Sensitivities concentrate around reimbursement coverage determinations for atrial fibrillation ablation, EU MDR certificate of conformity issuance timelines, and pulsed RF substitution rates in pain management clinics. Forecasts reflect documented assumptions regarding electrophysiology lab capacity expansion and physician training pipeline throughput. Cross-checking against hospital capital equipment purchasing cycle databases and GPO contract award registries is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pelvic Muscle Probes Market
Medical Devices
Europe Sternal Closure Systems Market
Medical Devices
Global Vein Illuminator Market
Medical Devices
Spinal Stenosis Implant Market
Medical Devices
Mexico Artificial Organs and Bionic Implants Market
Medical Devices
Wearable Bioelectronic Skin Patches Market
Medical Devices
Global Cast Saw Devices Market
Medical Devices
Depression Devices Market
Medical Devices
Adjustable Speed Vortex Mixer Market
Medical Devices
North America 3D Printing in Healthcare Market
Medical Devices
Trial Prostheses Market
Medical Devices
Laparoscopic Electrodes Market
Medical Devices
Global Vascular Embolization Devices Market
Medical Devices
Pleural Cavity Drainage Market
Medical Devices
Global Blood Banking Devices Market
Medical Devices
Electromagnetic Navigation Bronchoscopy Market