
 Intracranial Pressure Monitors Market | 2026-2036
Intracranial Pressure Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
Intracranial Pressure Monitors Market Outlook
EU MDR recertification deadlines for Class III neurological devices is consolidating supplier lists across European neurosurgical centers. Medtronic leverages its broad neurosurgery portfolio to sustain hospital contracting relationships across multiple continents. Integra LifeSciences anchors its position through specialized cranial access and monitoring product lines. RAUMEDIC AG competes with precision-engineered pressure measurement systems designed for critical care environments.
Intracranial pressure monitors measure cerebrospinal fluid dynamics and parenchymal pressure through invasive or semi-invasive interfaces, typically operating within 0–100 mmHg measurement ranges with catheter or sensor-based architectures for real-time neurocritical care decision support. External Ventricular Drains dominate procedural volume due to their dual therapeutic and diagnostic utility in acute hydrocephalus management, while Fiber Optic Sensors command premium positioning through drift-resistant calibration and miniaturized insertion profiles. Trauma applications generate the highest absolute case volumes, though Brain Surgery segments sustain superior reimbursement per procedure.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and clinical evidence thresholds for manufacturers seeking commercial access. Japan's PMDA enforces stringent biocompatibility and electrical safety standards through JIS harmonization that extends validation burdens for imported neurological devices. Stakeholders must monitor evolving reimbursement codes for continuous ICP monitoring across public and private payer systems to anticipate adoption inflection points.
Market Dynamics
EU MDR recertification deadlines for Class III neurological devices are consolidating supplier lists across European neurosurgical centers, compressing the vendor base while elevating compliance burdens for remaining participants.
Growth Catalysts
- Trauma center density:United States emergency medicine networks are mandating continuous ICP monitoring protocols for severe traumatic brain injury cases, expanding device utilization in Level I and II trauma facilities.
- EU MDR harmonization:The Medical Device Regulation's unified technical documentation requirements are streamlining cross-border commercialization for compliant manufacturers, reducing fragmentation in European procurement.
- Fiber optic miniaturization:Drift-resistant calibration technologies are enabling longer implantation durations in neurocritical care units, reducing replacement frequency and associated infection risks.
Market Restraints
- Platinum-iridium alloy costs:Sensor electrode materials face price volatility tied to precious metal markets, compressing gross margins for catheter-based monitor manufacturers.
- Single-source sterilization:Ethylene oxide sterilization capacity concentrates in contracted third-party facilities, creating bottlenecks for batch release timelines.
- Invasive procedure substitution:Transcranial Doppler ultrasound and non-invasive optical monitoring are capturing select low-acuity cases in step-down units.
Strategic Opportunities
- German university hospital networks:Tertiary neurosurgical centers are consolidating purchasing through regional procurement alliances, creating volume contract entry points for qualified suppliers.
- Ambulatory surgery center expansion:Japan's PMDA is evaluating streamlined approval pathways for same-day cranial procedures, potentially extending monitoring applications beyond traditional inpatient settings.
- Wireless telemetry convergence:Integration of Bluetooth Low Energy transmission with implantable pressure sensors is eliminating tethered bedside configurations and reducing nursing workflow interruptions.
Industry Challenges
- Neurocritical care specialist scarcity:Trained intensivists capable of interpreting continuous ICP waveforms are concentrated in academic medical centers, limiting protocol expansion to community hospitals.
- ISO 14155 clinical trial complexity:Prospective safety studies for novel sensor materials require extended follow-up periods, delaying regulatory submissions and commercialization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intracranial Pressure Monitors Market |
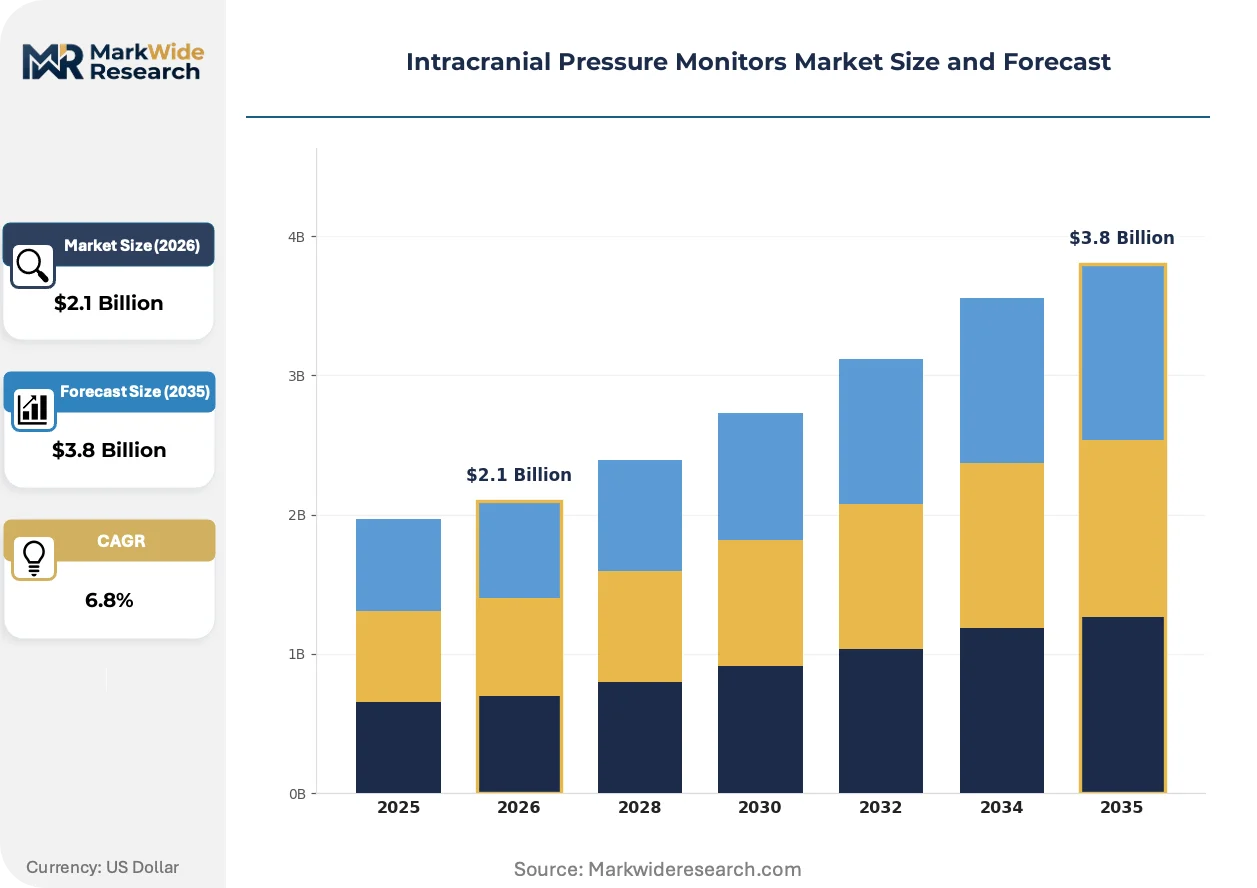
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: External Ventricular Drains, Intracerebral Monitors, Subdural Monitors, Intrathecal Monitors Application: Trauma, Stroke, Hydrocephalus, Brain Surgery End User: Hospitals, Neurology Clinics, Rehabilitation Centers, Emergency Departments Technology: Fiber Optic Sensors, Microelectromechanical Systems, Electromagnetic Sensors, Pressure Transducers |
| Companies Covered | Medtronic, Integra LifeSciences, RAUMEDIC AG, Sophysa, Spiegelberg GmbH & Co. KG, Natus Medical, NeuraSignal, Inc., Sense Neuro, IRRAS AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intracranial Pressure Monitors Market Strategic Shifts
Real-time waveform analytics and machine learning classification algorithms are transforming raw pressure data into actionable clinical decision support, shifting competitive advantage toward software-integrated hardware platforms.
Miniaturized fiber optic sensors with biocompatible polymer coatings are expanding into parenchymal monitoring applications previously dominated by fluid-coupled catheter systems. Neurocritical care units in German and Japanese trauma centers are adopting these platforms for extended monitoring beyond seventy-two hours. The technology is expanding into long-term intracranial pressure management for idiopathic intracranial hypertension patients, creating new ambulatory care revenue streams.
Japan's PMDA has harmonized biocompatibility testing requirements with ISO 10993-5 cytotoxicity standards, eliminating redundant validation studies for imported neurological devices. Manufacturers seeking Japanese market access must now submit consolidated biological safety documentation rather than jurisdiction-specific test reports. Fiber optic sensor suppliers with existing ISO certification are accelerating PMDA submissions, compressing time-to-market relative to competitors requiring supplemental testing.
Hospital procurement committees are unbundling device acquisition from technical service agreements, forcing suppliers to compete on capital expenditure terms rather than bundled lifetime contracts. Neurosurgical departments in United States academic medical centers are separating monitor hardware purchases from calibration and repair service lines. This disintermediation is most visible in California and Texas health systems, where group purchasing organizations are standardizing device specifications while allowing competitive bidding for maintenance services.
Intracranial Pressure Monitors Market Segmentation
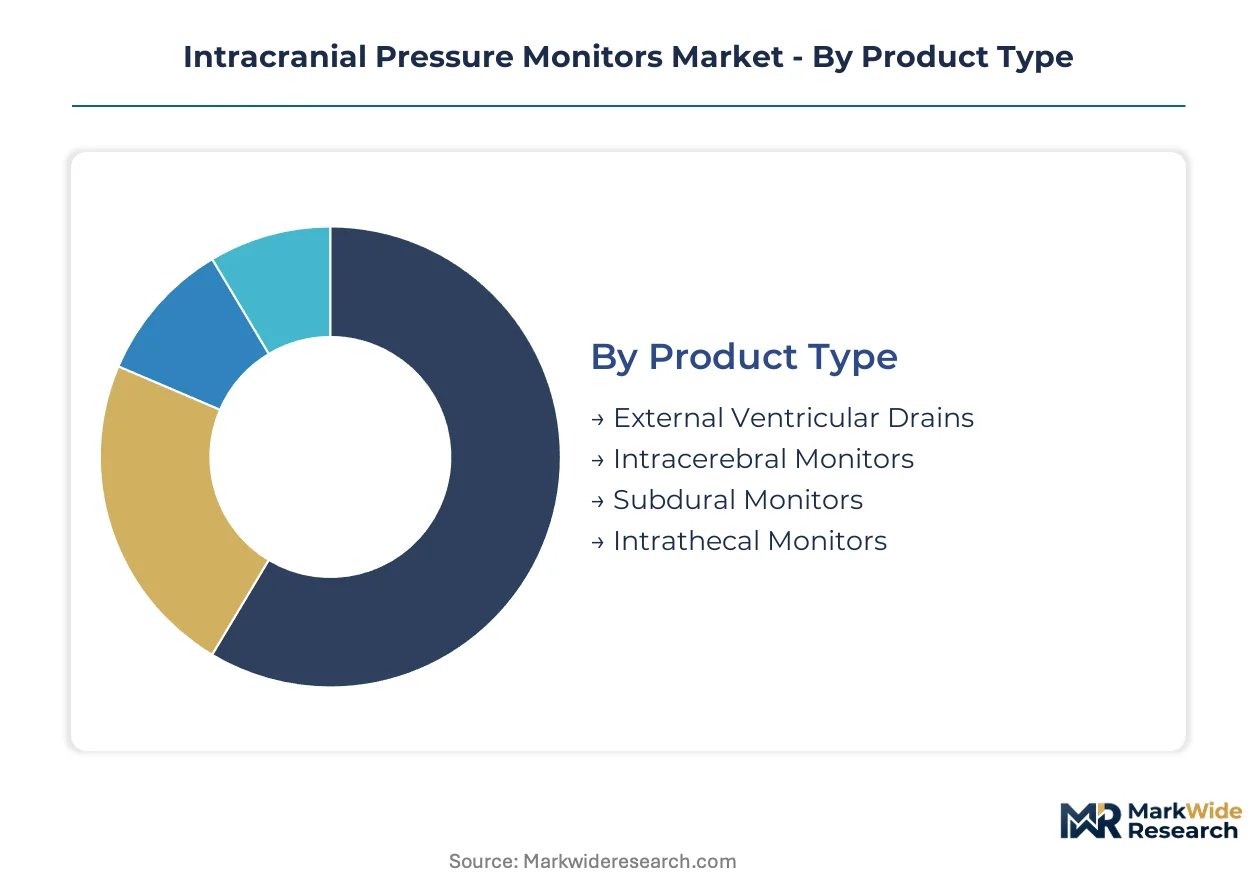
Intracranial pressure monitoring devices serve distinct clinical workflows across acute neurocritical care, elective neurosurgery, and step-down rehabilitation. Product architecture, signal fidelity requirements, and procedural setting drive purchasing decisions more than unit economics alone.
Product Type:
Hospital procurement committees weight therapeutic versatility against infection risk profiles when selecting catheter systems.
- External Ventricular Drains:Fluid-coupled catheter systems enable simultaneous CSF drainage and pressure measurement. Demand concentrates in United States Level I trauma centers where dual-function devices reduce line placements in severe TBI protocols.
- Intracerebral Monitors:Parenchymal sensors deliver localized pressure readings through bolt-mounted microtransducers. German university hospitals favor these platforms for craniotomy cases requiring targeted parenchymal surveillance without ventricular cannulation.
- Subdural Monitors:Epidural placement configurations suit postoperative monitoring after decompressive craniectomy.
- Intrathecal Monitors:Lumbar catheter systems serve specialized hydrocephalus management and intrathecal drug delivery monitoring.
Volume sits with External Ventricular Drains; growth tilts toward Intracerebral Monitors.
Application:
Reimbursement intensity varies sharply across indication severity and procedural complexity tiers.
- Trauma:Severe traumatic brain injury protocols mandate continuous ICP surveillance per Brain Trauma Foundation guidelines. United States emergency medicine networks generate the highest absolute case volumes through mandated monitoring in Level I and II trauma facilities.
- Brain Surgery:Elective craniotomy and tumor resection cases command premium device specifications with extended monitoring durations. Japanese tertiary centers sustain superior per-procedure reimbursement through specialized neurosurgical coding.
- Stroke:Hemorrhagic stroke management drives demand for rapid ICP escalation detection in intensive care settings.
- Hydrocephalus:Shunt malfunction evaluation and CSF dynamic assessment create recurring monitoring needs in pediatric and adult populations.
Trauma captures procedure volume leadership; Brain Surgery delivers margin expansion.
End User:
Care setting determines device portability requirements, nursing training intensity, and technical service contract structures.
- Hospitals:Academic medical centers and community hospitals with neurosurgical capabilities deploy comprehensive monitoring suites across ICU, OR, and step-down environments. United States health systems bundle ICP monitors into capital equipment cycles with multi-year service agreements.
- Emergency Departments:Rapid-deployment configurations serve initial stabilization and triage decision support before neurosurgical transfer.
- Neurology Clinics:Outpatient settings utilize non-invasive or brief invasive monitoring for diagnostic workups and shunt evaluations.
- Rehabilitation Centers:Extended care facilities adopt portable telemetry for post-acute intracranial pressure surveillance during recovery protocols.
Device concentration clusters in Hospitals; ambulatory expansion targets Emergency Departments.
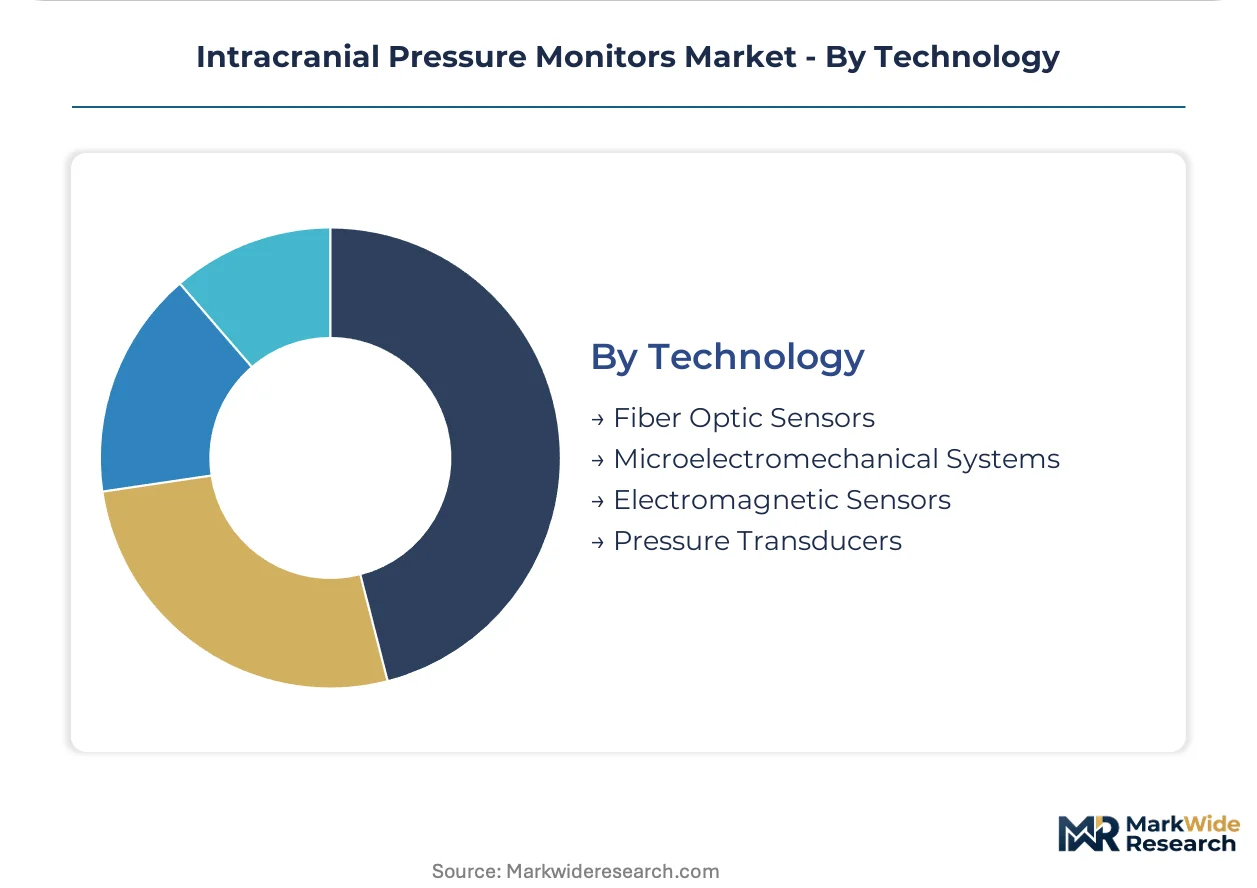
Technology:
Signal stability, drift characteristics, and electromagnetic interference resistance separate premium from standard-tier platforms.
- Fiber Optic Sensors:Photonic pressure transduction eliminates electrical artifacts and thermal drift in extended monitoring scenarios. Japanese and German trauma centers adopt these systems for implantation durations exceeding seventy-two hours.
- Microelectromechanical Systems:Silicon-based MEMS transducers enable miniaturized catheter profiles for minimally invasive insertion. Manufacturing scale advantages position MEMS platforms for cost-sensitive hospital procurement segments.
- Electromagnetic Sensors:Inductive coupling architectures serve specialized applications requiring wireless telemetry integration.
- Pressure Transducers:Conventional strain-gauge systems maintain installed base presence through compatibility with legacy monitoring infrastructure.
Installed base favors Pressure Transducers; technology transition accelerates for Fiber Optic Sensors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing clusters concentrate in Germany and the United States while trauma center density and aging demographics drive consumption across Japan and select European markets. Production capabilities align with neurosurgical infrastructure investments rather than raw material proximity.
United States
Level I and II trauma centers mandate continuous ICP monitoring protocols under Brain Trauma Foundation guidelines, sustaining procedure volumes in emergency medicine networks. FDA 510(k) clearance pathways shape product development timelines for invasive neurological devices. Neurosurgical departments in California and Texas health systems are unbundling device acquisition from technical service agreements.
Germany
University hospital networks consolidate purchasing through regional procurement alliances, creating volume contract entry points for qualified suppliers. EU MDR recertification deadlines for Class III neurological devices are compressing the vendor base across European neurosurgical centers. Tertiary centers in Bavaria and North Rhine-Westphalia favor parenchymal sensors for craniotomy cases requiring targeted surveillance.
Japan
Aging populations and trauma center density sustain procedure volumes in tertiary neurosurgical centers. PMDA harmonization with ISO 10993-5 cytotoxicity standards eliminates redundant validation studies for imported neurological devices. Tokyo and Osaka medical centers adopt fiber optic systems for implantation durations exceeding seventy-two hours.
United Kingdom
National Health Service neurosurgical units balance cost containment against clinical guideline compliance for severe traumatic brain injury management. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical documentation requirements. London and Manchester academic medical centers deploy comprehensive monitoring suites across ICU and step-down environments.
Switzerland
Swissmedic enforces stringent performance validation standards for invasive neurological devices that exceed baseline EU requirements. Precision engineering capabilities in the Basel and Zurich regions support sensor manufacturing for critical care applications. University hospitals integrate continuous ICP monitoring into standardized neurocritical care protocols.
Intracranial Pressure Monitors Market Competitive Environment
The competitive structure tilts toward diversified medical technology conglomerates with established neurosurgery portfolios. Medtronic leverages broad hospital contracting relationships across multiple continents while specialized cranial access manufacturers anchor positions through dedicated monitoring product lines. Three archetypes dominate: integrated neurosurgery platforms, precision sensor specialists, and regional contract manufacturers. Consolidation through M&A and geographic expansion into German university hospital networks represent the dominant competitive moves.
Among diversified medical technology conglomerates, Medtronic and Integra LifeSciences occupy positions exemplifying integrated neurosurgery platform strategies. RAUMEDIC AG represents the precision-engineered sensor specialist archetype, competing through critical care-focused measurement systems. These three entities anchor the competitive landscape across North American, European, and Asia-Pacific procurement channels.
| Leading Market Players |
|---|
| Medtronic |
| Integra LifeSciences |
| RAUMEDIC AG |
| Sophysa |
| Spiegelberg GmbH & Co. KG |
| Natus Medical |
| NeuraSignal, Inc. |
| Sense Neuro |
| IRRAS AB |
| Others |
Value Chain & Pricing Dynamics
Fiber-optic-to-electromagnetic performance divergence separates premium drift-resistant systems from commodity strain-gauge platforms, with that bifurcation manifesting in platinum-iridium electrode sourcing strategies and tiered FDA 510(k) validation burdens across German and United States manufacturing footprints.
Pricing Analysis
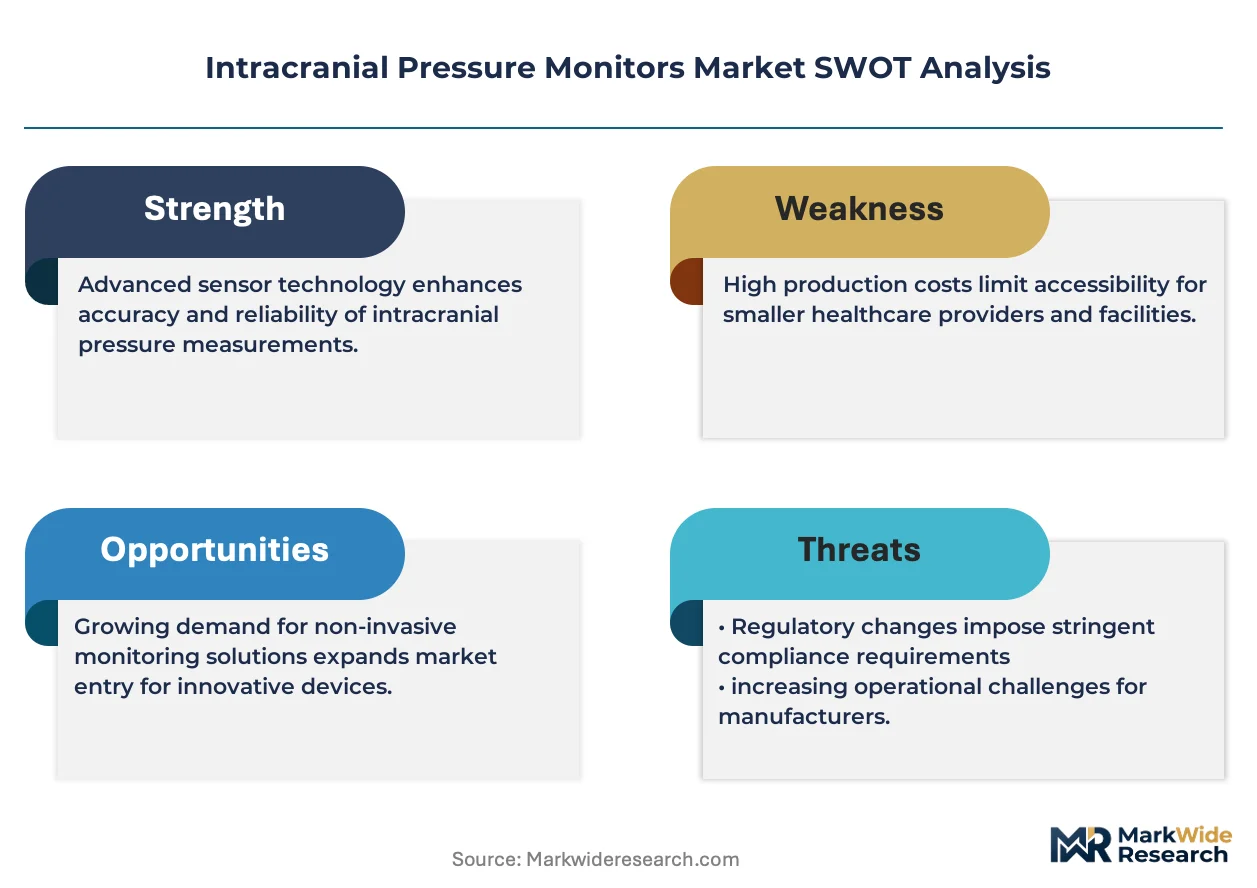
Margin tightening in catheter-based tiers reflects platinum-iridium alloy spot volatility and contracted ethylene oxide sterilization bottlenecks. Three-tier pricing structure across premium, standard, and economy levels stratifies by signal fidelity specifications and EU MDR certification completeness. Cost-down pressure on electromagnetic sensor lines accelerates because hospital procurement committees now unbundle hardware from service contracts. Academic medical centers in California and Texas health systems exhibit lowest price sensitivity; community hospitals with limited neurocritical care volumes drive commoditization.
Supply Chain Analysis
ISO 13485 and FDA 21 CFR Part 820 quality system certification gates component sourcing for invasive neurological devices. Precision sensor manufacturing concentrates in Germany, Switzerland, and the United States; biocompatible polymer coatings draw from Japanese and Swiss specialty chemical suppliers. Single-source sterilization capacity creates vulnerability to batch release delays. Distribution runs through regional hospital procurement alliances in German university networks and group purchasing organizations in United States health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR Class III recertification deadlines erect a cost-of-compliance barrier that consolidates vendor lists and protects entrenched players with validated technical documentation.
For Market Incumbents: Deploy backward integration into platinum-iridium electrode supply to defend against precious metal volatility and sterilization bottlenecks. Fortify hospital contracting relationships through bundled software analytics platforms that raise switching costs for neurocritical care units facing non-invasive optical monitoring substitution threats.
For New Entrants and Emerging Players: Direct-to-hospital digital procurement channels bypass consolidated GPO gatekeepers for standardized catheter components. Target ambulatory surgery center expansion in Japan's PMDA streamlined approval pathways for same-day cranial procedures, where wireless telemetry integration creates differentiation against tethered legacy configurations.
For Investors and Strategic Acquirers: Re-rating potential sits with precision sensor specialists possessing ISO 10993-5 harmonization and existing PMDA submission momentum given Japanese market acceleration. Monitor EU MDR recertification failure announcements as inflection indicators for distressed acquisition opportunities among non-compliant vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Class III neurological device recertification protects market access across German and United Kingdom hospital networks. |
| Wireless Telemetry Platform Development | Bluetooth Low Energy integration eliminates tethered configurations and reduces nursing workflow interruptions in neurocritical care. |
| Hospital System Partnership | Regional procurement alliances in Bavaria and North Rhine-Westphalia create volume contract entry points for qualified suppliers. |
| Software Companion Development | Real-time waveform analytics and machine learning classification transform raw pressure data into actionable clinical decision support. |
| Reimbursement Strategy | Continuous ICP monitoring code expansion across Medicare and private payer systems accelerates adoption inflection points. |
Study Parameters
FDA 510(k) premarket notification databases, EU MDR technical documentation registries, and Japanese PMDA approval filings formed the secondary backbone. Primary interviews with neurocritical care intensivists, hospital biomedical engineers, GPO contracts managers, and neurosurgical department heads validated procedural volume assumptions and procurement pattern shifts. Bottom-up device shipment analysis and top-down healthcare expenditure triangulation anchored market sizing across the analysis window.
Historical trendline analysis of trauma center density expansion and neurosurgical procedure coding changes informed projection frameworks. Segmentation modeling incorporated product architecture tiers, application severity gradients, end-user care settings, and signal transduction technologies. CAGRs derived from procedure volume elasticity to trauma center mandates and reimbursement code expansion trajectories. Forecast inputs included Brain Trauma Foundation guideline adoption curves and EU MDR recertification timeline compressions.
The model holds under stable regulatory harmonization and trauma center infrastructure investment; deviation in sterilization capacity constraints or non-invasive monitoring substitution rates would shift volume projections. A model refresh is warranted upon material change in FDA 510(k) clearance pathway timelines or Japanese PMDA streamlined approval implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Glass Syringe Market
Medical Devices
Stethoscope Hygiene Devices Market
Medical Devices
US Contact Lenses Market
Medical Devices
Transcranial Magnetic Stimulation System Market
Medical Devices
Asia-Pacific Respiratory Devices Market
Medical Devices
Portable Medical Devices Market
Medical Devices
LAMEA Breast Pumps Market
Medical Devices
Global Bone Screw System Market
Medical Devices
Artificial Pancreas Market
Medical Devices
External Pacemakers Market
Medical Devices
Actigraphy Sensors and Polysomnography Devices Market
Medical Devices
Subcutaneous Drug Delivery Devices Market
Medical Devices
Carpal Tunnel Release Systems Market
Medical Devices
MRI Guided Drug Delivery Market
Medical Devices
Global Medical Dynamometer Market