
 Traditional Ceramic Market | 2026-2036
Traditional Ceramic Market Size, Share, and Industry Trends Forecast 2026-2036
Traditional Ceramic Market Analytics
Digital printing technology is fragmenting traditional ceramic decoration methods, enabling mass customization of tile surfaces without conventional glaze lines. RAK Ceramics leverages its integrated manufacturing footprint across the UAE and India to control raw material sourcing for porcelain tile production. Saint-Gobain anchors its competitive position through sustained R&D investment in high-performance ceramic formulations for architectural applications.
Traditional ceramics encompass clay-based materials shaped and fired at temperatures ranging from 900°C to 1,400°C to achieve structural density, chemical stability, and surface durability for functional or decorative use. Porcelain dominates flooring applications due to its low water absorption and mechanical strength, while sanitary ware generates concentrated margin pools from specification-driven commercial construction projects. Stoneware competes in tableware segments where durability and microwave compatibility command premium positioning against earthenware alternatives.
EPA emission standards in the United States and REACH chemical registration requirements in Europe constrain kiln fuel choices and glaze composition across export-oriented manufacturers. China's GB standards and evolving MEE enforcement on particulate emissions are reshaping production economics for tile and sanitary ware producers supplying domestic and overseas markets. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate compliance costs and certification barriers that will determine factory location and product formulation decisions.
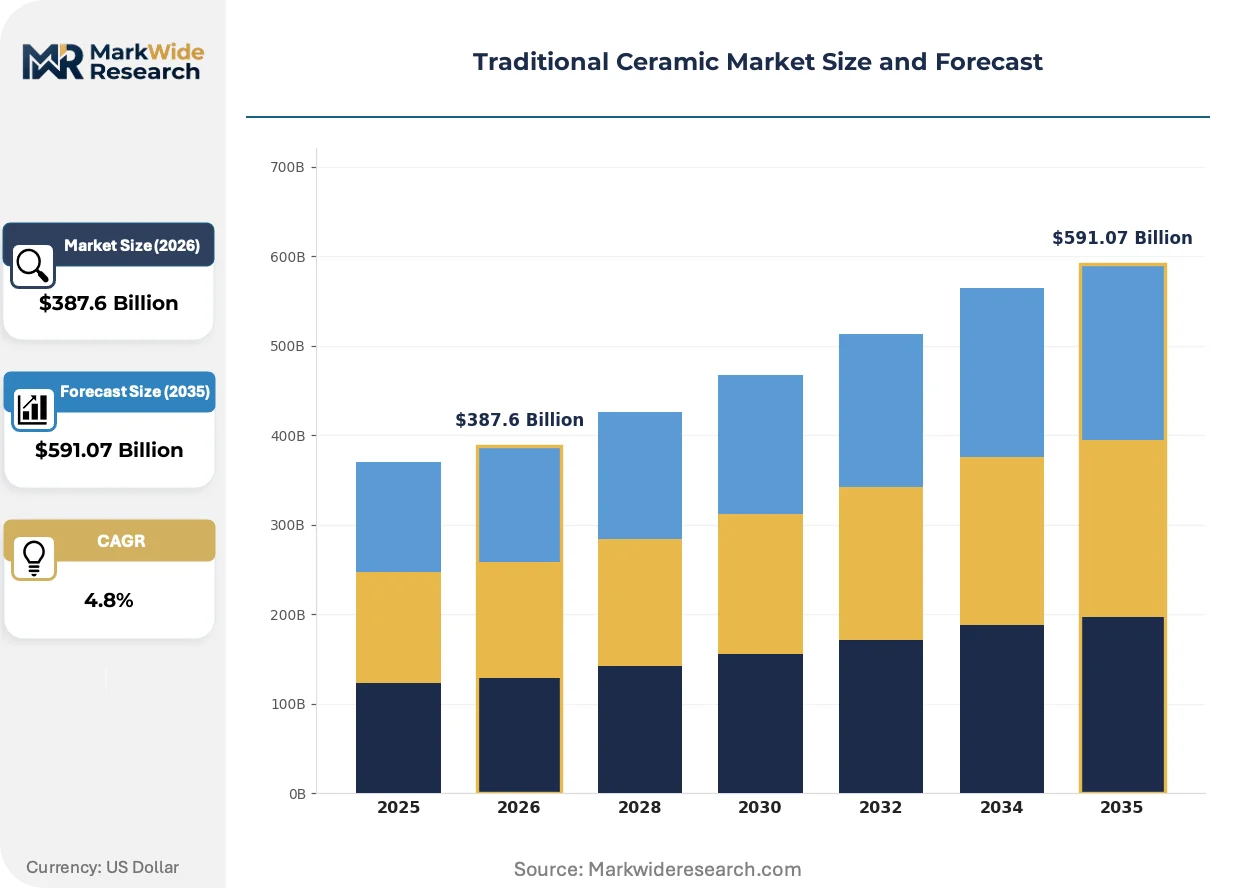
Market Dynamics
Kiln electrification and natural gas price volatility are compressing margins for traditional ceramic manufacturers while digital printing technology reconfigures decoration economics across tile and sanitary ware segments.
Growth Catalysts
- India's Housing for All schemes:Government-subsidized urban housing programs in India are accelerating procurement of ceramic flooring and bathroom fixtures for low-income residential developments.
- REACH compliance differentiation:European REACH chemical registration requirements for glaze formulations are creating certification premiums for compliant exporters serving EU construction markets.
- Porcelain tile substitution:Mechanical strength and water absorption advantages of porcelain are displacing natural stone and vinyl flooring in commercial real estate specifications.
Market Restraints
- Feldspar supply concentration:Turkey and India control approximately three-quarters of global feldspar exports, exposing tile manufacturers to geopolitical supply interruptions and export licensing delays.
- Natural gas price volatility:Kiln operations remain dependent on natural gas for 900°C to 1,400°C firing cycles, with European manufacturers facing sustained input cost pressure from pipeline supply disruptions.
- Technical limitation of thin-walled sanitary ware:Conventional slip-casting methods cannot achieve sub-4mm wall thicknesses required for lightweight water closets without sacrificing structural integrity.
Strategic Opportunities
- Saudi Arabia's giga-project pipeline:NEOM and Red Sea tourism developments are generating concentrated demand for high-specification porcelain tile and designer sanitary ware with accelerated delivery timelines.
- Electrification incentives under EU Green Deal:Carbon border adjustment mechanisms and renewable energy subsidies are creating first-mover advantages for manufacturers investing in electric kiln retrofits.
- 3D printing-conventional firing convergence:Additive manufacturing of complex ceramic geometries combined with traditional sintering is enabling mass customization of architectural facade elements.
Industry Challenges
- Digital decoration technician scarcity:Tile manufacturers face recruitment gaps for operators capable of calibrating inkjet printing systems and color-managing variable glaze deposition.
- GB standard certification timelines:China's evolving national standards for ceramic product safety and emission testing are extending product approval cycles for export-oriented manufacturers.
- Legacy kiln integration complexity:Retrofitting existing tunnel kilns with hydrogen-ready burners or electric heating elements requires extended production shutdowns and specialized refractory engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traditional Ceramic Market |
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $591.07 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Porcelain, Stoneware, Earthenware, Bone China Application: Tableware, Decorative Items, Flooring, Sanitary Ware End User: Households, Restaurants, Hotels, Artisans Distribution Channel: Online Retail, Specialty Stores, Wholesalers, Craft Fairs |
| Companies Covered | Noritake, Wedgwood, RAK Ceramics, HAC International, Royal Doulton, Mohawk Industries, Villeroy & Boch, Saint-Gobain, Kajaria Ceramics Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traditional Ceramic Market Evolving Landscape
Digital workflows are compressing design-to-production cycles while regulatory emission thresholds and procurement consolidation reshape competitive requirements across ceramic manufacturing.
Inkjet digital printing systems are virtualizing traditional screen-printing and rotary decoration methods in tile manufacturing. Commercial real estate developers and hospitality chains are specifying digitally printed surfaces for mass-customized interior schemes. This virtualization is collapsing minimum order quantities and enabling single-batch production economics previously unattainable with conventional glaze lines.
China's GB standards and MEE enforcement on particulate emissions are tightening discharge thresholds for ceramic kiln operations. Manufacturers must install baghouse filtration and wet scrubber systems to achieve compliance, raising capital intensity for mid-scale producers. Export-oriented factories in Guangdong and Fujian provinces are accelerating compliance investments to maintain overseas market access.
Specification-driven procurement is consolidating purchasing authority among architecture and design firms serving commercial construction. Tile distributors are losing direct relationships with end clients as design consultants centralize material selection and negotiate master service agreements. This concentration is most visible in North American and European commercial real estate development where sustainability certification requirements drive centralized vendor qualification.
Traditional Ceramic Market Segmentation
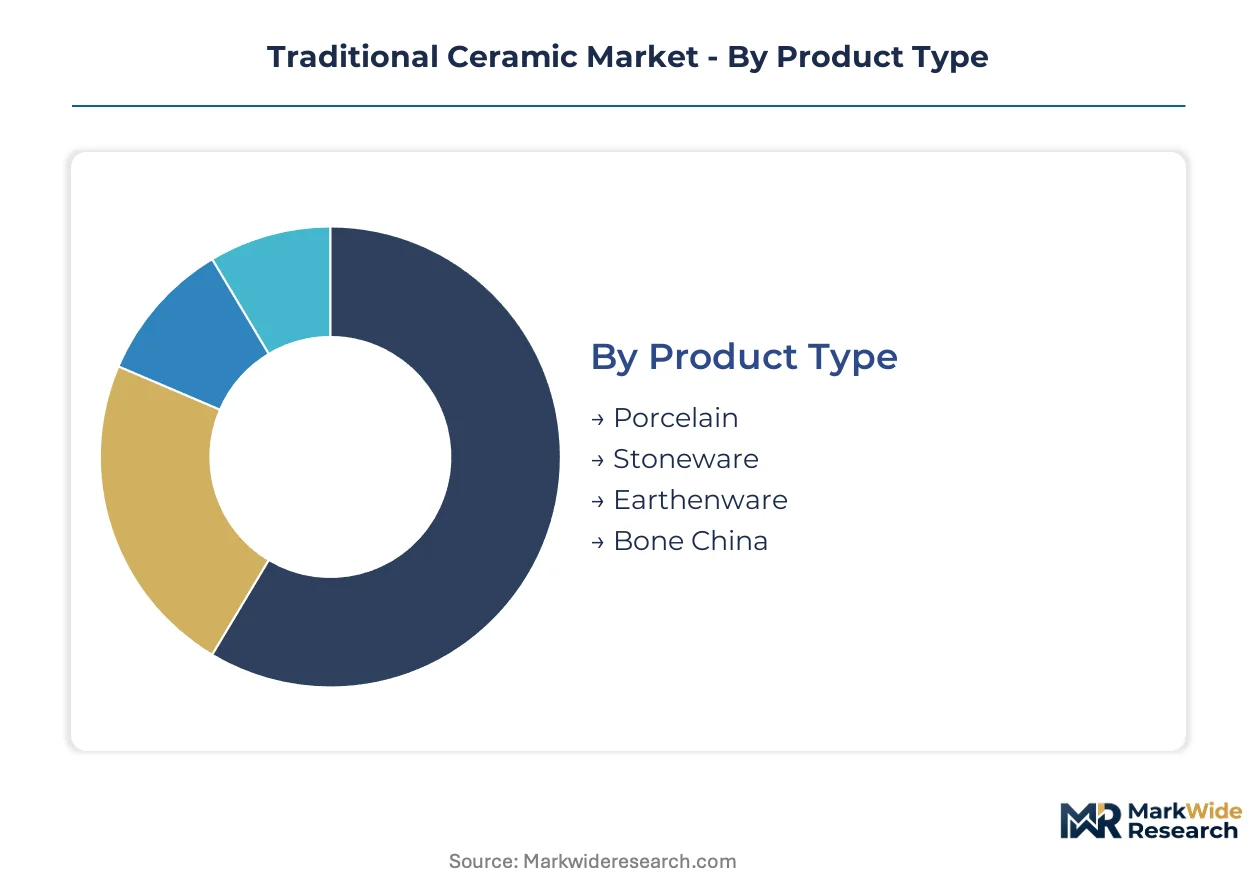
Segmentation in traditional ceramics reveals divergent margin structures and specification requirements across product categories. Kiln capacity allocation, glaze formulation complexity, and after-sales service intensity vary substantially between architectural and consumer segments, shaping manufacturer portfolio strategies.
Product Type:
After-sales service intensity escalates with product fragility and specification complexity, driving differentiated warranty and replacement policies across ceramic categories.
- Porcelain:Fired at 1,200°C to 1,400°C with vitrified body structure achieving near-zero water absorption. Demand concentrates in Saudi Arabia's NEOM and Red Sea tourism developments where accelerated delivery timelines for high-specification flooring dominate procurement. REACH-compliant exporters capture certification premiums in EU commercial real estate specifications.
- Stoneware:Mid-range firing temperatures of 1,100°C to 1,300°C produce durable, non-porous tableware with microwave compatibility. Restaurants and hospitality chains in India specify stoneware for operational durability under high-frequency use, displacing earthenware in institutional procurement.
- Earthenware:Low-fire ceramics at 900°C to 1,100°C retain porous body structure requiring glaze sealing for liquid containment. Artisans and craft-oriented households drive demand through specialty retail and direct studio sales channels.
- Bone China:Bone ash incorporation creates distinctive translucency and strength for premium tableware. Hotel banqueting departments and luxury residential specifications in the UAE sustain import-dependent supply chains.
Porcelain holds the largest share; momentum sits with stoneware as institutional procurement standardizes on durability specifications.
Application:
Cost tier segmentation separates commodity volume plays from specification-driven margin pools, with architectural applications commanding premium positioning through certification requirements.
- Tableware:Functional dining ceramics spanning mass-market stoneware to artisanal porcelain place settings. India's restaurant sector expansion and hotel chain standardization programs are concentrating procurement volume with certified suppliers capable of batch consistency.
- Flooring:Large-format porcelain tiles with digital-printed surfaces replacing natural stone in commercial developments. Digital printing technology enables mass customization for hospitality interior schemes without conventional glaze line minimums.
- Sanitary Ware:Water closets, basins, and bathroom fixtures with specification-driven commercial margins. GB standards compliance timelines in China extend product approval cycles for export-oriented manufacturers targeting EU markets.
- Decorative Items:Sculptural and ornamental ceramics with artisanal production economics. Craft fairs and gallery retail sustain small-batch producers outside industrial manufacturing scale.
Flooring commands the highest volume; sanitary ware delivers the steepest expansion trajectory as housing programs accelerate in India and Saudi Arabia.
End User:
Customer type determines order scale, specification complexity, and relationship durability, with institutional accounts consolidating purchasing authority through design consultant intermediation.
- Households:Residential consumers purchasing through retail and online channels for kitchen and bathroom renovation. India's Housing for All schemes are accelerating ceramic flooring and fixture procurement for low-income urban developments.
- Hotels:Hospitality chains specifying mass-customized interior schemes with accelerated replacement cycles. Design consultants centralize material selection and negotiate master service agreements, displacing distributor relationships.
- Restaurants:Foodservice operators prioritizing durability and microwave compatibility in high-turnover environments. Stoneware specifications dominate institutional procurement for operational reliability.
- Artisans:Studio potters and craft producers sourcing raw materials and equipment for small-batch production. Specialty supply channels serve this fragmented demand base with technical support and kiln maintenance services.
Households represent the broadest base; hotels are gaining share fastest as tourism infrastructure investment concentrates in the Middle East and Asia-Pacific.
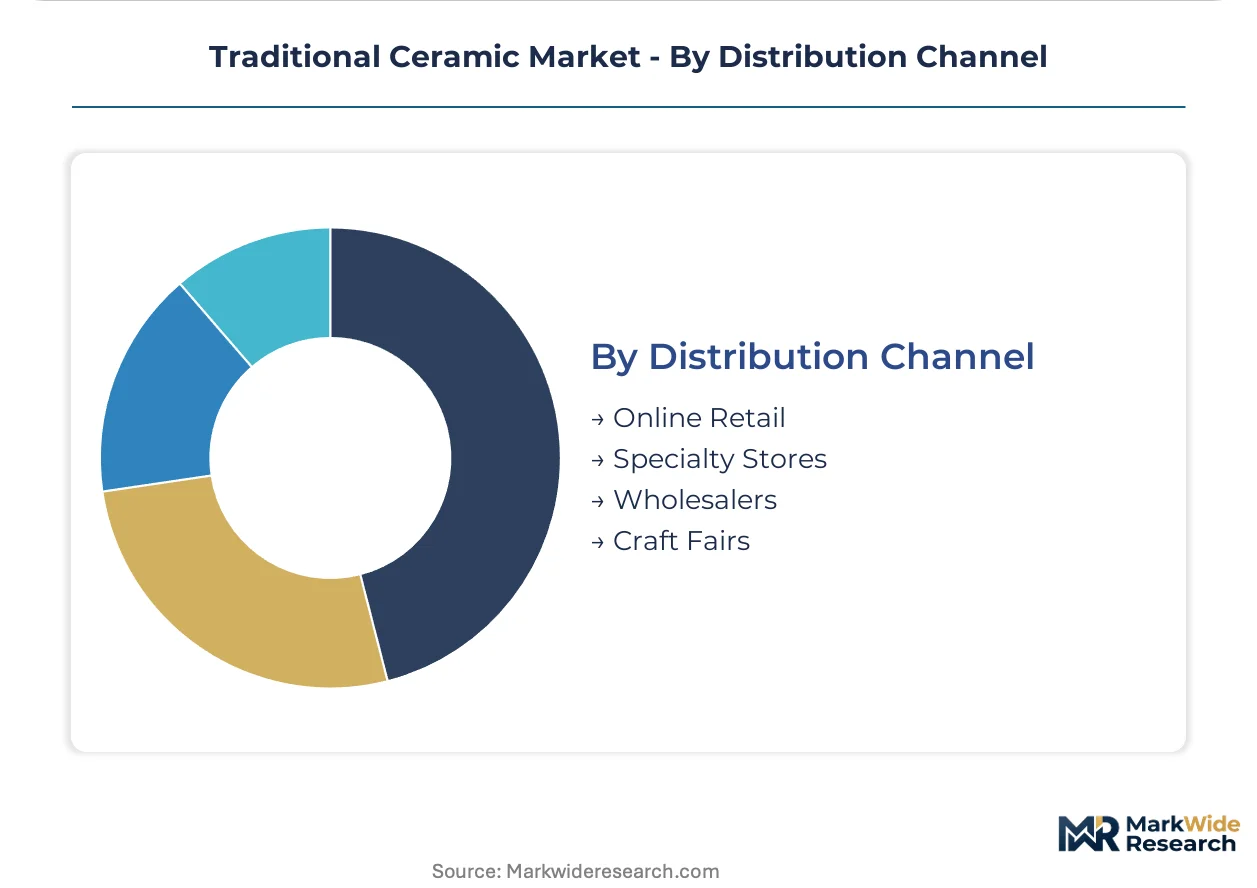
Distribution Channel:
Supply concentration in feldspar sourcing and kiln manufacturing shapes channel economics, with digital workflows compressing design-to-delivery timelines for specification-driven segments.
- Specialty Stores:Tile showrooms and bathroom fixture retailers with technical consultation and sample libraries. European REACH compliance differentiation creates certification premiums for compliant exporters serving these channels.
- Online Retail:E-commerce platforms enabling direct manufacturer-to-consumer sales with virtual visualization tools. Standardized product categories with established specifications dominate this channel.
- Wholesalers:Volume distributors serving contractor and developer accounts with inventory positioning and logistics coordination. Procurement consolidation among architecture firms is compressing wholesaler margins in commercial construction.
- Craft Fairs:Direct artisan-to-consumer events sustaining small-batch decorative and studio pottery sales. Regional craft traditions in India and China sustain localized production ecosystems outside industrial scale.
Specialty stores retain the largest share; online retail is climbing the fastest as digital workflows virtualize traditional specification processes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian porcelain tile exports to Saudi Arabia's NEOM and Red Sea tourism developments are accelerating procurement cycles for high-specification flooring and sanitary ware. This trade corridor exemplifies how supplier geographies align with concentrated demand clusters in Gulf construction markets.
China
Guangdong and Fujian provinces host export-oriented tile manufacturers installing baghouse filtration systems to meet MEE particulate emission thresholds. GB standards compliance timelines are extending product approval cycles for factories targeting EU markets. Foshan's ceramic industrial cluster is consolidating capacity as smaller producers exit under environmental enforcement pressure.
India
Gujarat and Morbi's tile manufacturing belt supplies porcelain flooring for Housing for All urban schemes and Saudi giga-projects. BIS certification requirements are tightening quality benchmarks for export-bound sanitary ware. Morbi's 800-plus kiln cluster is capturing share from Chinese competitors in Middle East procurement tenders.
Saudi Arabia
NEOM and Red Sea tourism developments are generating concentrated demand for designer sanitary ware with accelerated delivery requirements. SFDA product safety registrations govern ceramic imports for hospitality specifications. Jeddah's logistics corridor is positioning as a regional distribution hub for Gulf ceramic procurement.
Germany
REACH chemical registration requirements for glaze formulations are creating certification premiums for compliant exporters serving EU commercial real estate. The country's central bank monitors construction sector credit flows that drive tile and fixture demand. North Rhine-Westphalia's industrial ceramics R&D clusters are advancing high-performance architectural formulations.
United States
EPA emission standards constrain kiln fuel choices for domestic tile manufacturers serving commercial flooring specifications. The Southeast's construction recovery is concentrating porcelain demand in Florida and Georgia residential developments. Tennessee's distribution networks are capturing logistics efficiencies for Gulf Coast and Atlantic seaboard project deliveries.
Traditional Ceramic Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. The vendor base organizes around scale-driven manufacturers, design-forward brands, and regional fabricators serving localized procurement. Three archetypes dominate: integrated producers controlling raw material sourcing, specification-driven brands capturing commercial margins, and contract manufacturers serving private-label retail. Capacity expansion and certification differentiation represent the dominant competitive moves as regulatory barriers reshape factory economics.
Within the integrated producer tier, RAK Ceramics and Saint-Gobain exemplify archetypes of manufacturing footprint control and high-performance formulation investment respectively. Kajaria Ceramics Limited represents the India-based specialist capturing share in government housing programs and Gulf export markets. These three anchors demonstrate how geographic positioning and compliance capability determine competitive access in specification-driven segments.
| Leading Market Players |
|---|
| Noritake |
| Wedgwood |
| RAK Ceramics |
| HAC International |
| Royal Doulton |
| Mohawk Industries |
| Villeroy & Boch |
| Saint-Gobain |
| Kajaria Ceramics Limited |
| Others |
Value Network & Pricing Analysis
Morbi's 800-plus kiln cluster running at sustained overcapacity in Gujarat is compressing export pricing for Indian porcelain tile manufacturers while simultaneously accelerating raw material procurement cycles to maintain utilization rates. This utilization-pressure dynamic rewards backward-integrated producers with captive feldspar sourcing and punishes merchant buyers exposed to Turkish export licensing delays.
Pricing Analysis
Digital printing technology has opened a pronounced pricing gap between conventional screen-printed tile, mid-tier inkjet systems, and next-generation single-pass industrial inkjet lines capable of mass customization. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant EU-export grades from BIS-certified domestic Indian product and unbranded Morbi commodity output. Pricing pressure stems from natural gas volatility in European kiln operations and Chinese environmental enforcement raising compliance costs for Guangdong exporters. Specifiers in Saudi giga-projects demonstrate lowest price sensitivity, while India's Housing for All procurement concentrates volume with aggressive tender pricing.
Supply Chain Analysis
Turkey's export licensing regime for strategic minerals constrains feldspar flows to Indian and Chinese tile manufacturers, fragmenting raw material security planning across the industry. Supply concentrates in Turkey, India, and China for feldspar and kaolin inputs, with Italian and Spanish producers holding residual high-grade reserves for premium porcelain formulations. Kiln manufacturing and digital printing equipment depend on German and Italian engineering centers, creating single-source vulnerability for technology upgrades. Distribution runs through Jeddah's emerging Gulf logistics hub for Saudi project deliveries, while European REACH compliance documentation extends order-to-delivery timelines for specification-driven commercial flooring.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The traditional ceramic market sits at an electrification inflection as EU Green Deal subsidies and carbon border adjustments restructure kiln economics for export-oriented manufacturers. Digital printing virtualization and REACH compliance differentiation are concentrating margin capture among technology-advantaged producers.
For Market Incumbents: Insulate margin structures by securing captive feldspar positions in Turkey or Rajasthan before export licensing tightens further. Accelerate electric kiln pilot programs in Morbi and Guangdong to capture EU Green Deal first-mover subsidies and preempt carbon border adjustment exposure. Prioritize REACH certification maintenance as EU commercial real estate consolidates purchasing authority with design consultants qualifying compliant vendor pools.
For New Entrants and Emerging Players: Build out additive manufacturing capabilities for architectural facade elements where 3D printing-conventional firing convergence enables mass customization without legacy screen-printing equipment investment. Target Saudi Arabia's NEOM and Red Sea tourism pipeline with accelerated delivery commitments, as established Indian and Chinese producers struggle with GB standard certification timelines and extended product approval cycles. Pursue direct relationships with hospitality design consultants to bypass consolidated distributor channels.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electric kiln retrofit and MEE-compliant filtration installations, favoring scaled producers with balance sheet capacity to absorb extended production shutdowns. Acquire India-based specialists with BIS certification and established Gulf export relationships, as Morbi's cluster consolidation eliminates smaller non-compliant competitors. Monitor EU carbon border adjustment implementation timelines as the signal for accelerated electric kiln investment decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Kiln Retrofit | EU Green Deal subsidies create first-mover cost advantages for compliant exporters serving REACH-regulated markets. |
| Backward Integration into Feldspar | Turkish export licensing volatility rewards captive raw material sourcing for Indian porcelain manufacturers. |
| Digital Printing Capacity Expansion | Single-pass inkjet systems collapse minimum order quantities for hospitality mass-customization specifications. |
| REACH Compliance Certification | Chemical registration documentation opens premium pricing tiers in EU commercial real estate procurement. |
| Gulf Distribution Hub Establishment | Jeddah logistics positioning captures NEOM and Red Sea project delivery acceleration requirements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the traditional ceramic value chain, including kiln operations managers at Morbi and Foshan manufacturing clusters, procurement leads at Saudi giga-project developers, ceramic tile distributors serving European commercial real estate, and technical directors at digital printing equipment suppliers. Secondary validation drew from MEE emission disclosure filings, BIS certification registries, EU REACH substance databases, and customs trade flow records for feldspar and finished tile movements. Bottom-up capacity utilization estimates from regional kiln clusters were triangulated against top-down construction sector demand projections.
Calibration approaches anchored volume and value outputs to observed capacity expansions, regulatory compliance investments, and procurement contract announcements across the analysis window. Segmentation dimensions modeled encompassed product type, application, end user, and distribution channel, with additional granularity on firing temperature tiers and glaze formulation complexity. CAGRs were derived from production capacity buildout schedules, housing program procurement timelines, and tourism infrastructure investment pipelines. Forecast inputs incorporated natural gas price trajectory assumptions and EU carbon border adjustment implementation sequencing.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-supported producers or accelerated electrification subsidies from EU member states would shift outcomes beyond modeled ranges. Material shifts in Turkish feldspar export policy, MEE enforcement intensity in Guangdong, or Saudi giga-project suspension would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Advanced Ceramic Additives Market
Ceramics
Graphite Crucibles Market
Ceramics
United States Ceramics Tableware Market
Ceramics
Ceramic Setter Plate Market
Ceramics
Calcium Silicate Boards Market
Ceramics
Mexico Ceramic Tiles Market
Ceramics
Low Density Ceramic Proppant Market
Ceramics
Feldspar and Nepheline Syenite Market
Ceramics
South Korea Ceramic Tiles Market
Ceramics
Heat-Resistant Ceramic Tableware Market
Ceramics
Solid-Ion Conductors Market
Ceramics
Calcined Kaolin Market
Ceramics
Global Thermal Ceramics Market
Ceramics
Pottery Ceramics Market
Ceramics
Europe Activated Alumina Market
Ceramics
White Fused Alumina Market