
 China Clay Market | 2026-2036
China Clay Market Size, Share, and Industry Trends Forecast 2026-2036
China Clay Market Outlook
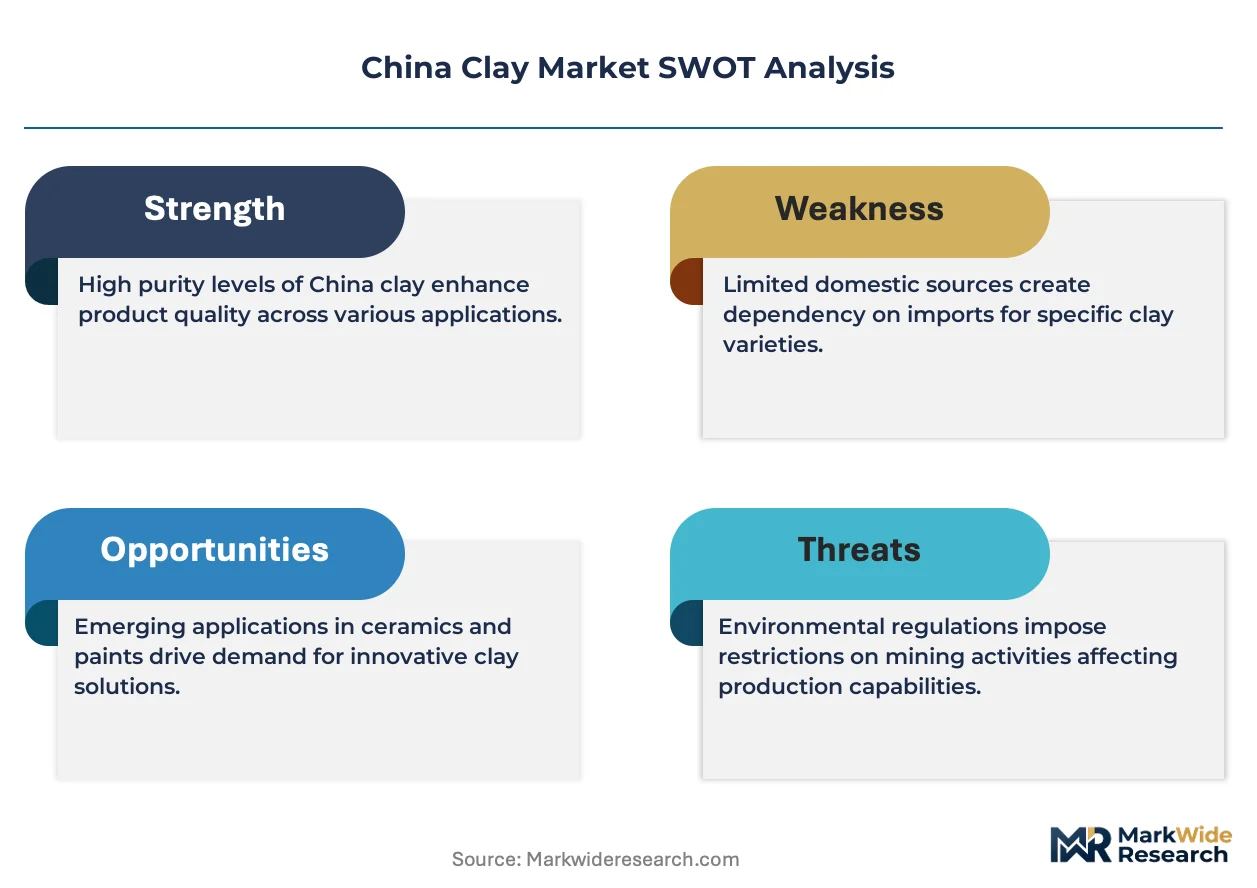
EU REACH compliance on extracted minerals is hardening purity requirements for kaolin entering coatings and consumer goods supply chains. Imerys S.A. leverages its integrated refining network across European extraction sites to sustain premium-grade output for specialty applications. KaMin LLC anchors North American supply through controlled deposits in Georgia, while Ashapura Group competes on volume scale across Indian ceramics corridors.
China clay encompasses hydrous aluminum silicates extracted from weathered feldspar deposits, with particle sizes typically below two microns and brightness values measured via ISO 2469 standards; manufacturers refine raw ore through blunging, classification, and magnetic separation to yield engineered fillers for surface coating, reinforcement, and rheology control. Kaolin dominates product type revenue due to its ubiquity in paper coating and ceramics body formulations, whereas calcined clay commands margin premiums in automotive underhood rubber compounds where low moisture absorption matters. Ceramics applications retain structural volume leadership, though paints and coatings segments attract reformulation investment as waterborne systems displace solvent-based alternatives.
China's Ministry of Ecology and Environment enforces GB standards on mining wastewater discharge, while SAMR monitors product safety declarations for clay entering consumer goods channels; these frameworks elevate compliance costs for unrefined exporters and favor processors with captive laboratory certification. India's BIS grading system for ceramic raw materials similarly constrains informal pit operators. Stakeholders must track how regulatory escalation in extraction jurisdictions reshapes long-term offtake agreements and capital allocation toward beneficiation assets.
Market Dynamics
China's dual carbon goals and stricter mining rehabilitation rules are tightening feedstock access for kaolin processors, forcing ceramic manufacturers toward captive beneficiation assets and long-term offtake contracts with certified refiners.
Growth Catalysts
- GB standards on mining wastewater discharge:China's Ministry of Ecology and Environment enforcement elevates compliance costs for informal pit operators, consolidating volume toward integrated processors with captive laboratory certification.
- High-grade tile and sanitary ware production:Ceramic manufacturers in Guangdong Province are expanding kaolin consumption as clusters of processors source refined material from nearby Maoming deposits.
- Waterborne coatings reformulation:Paints and coatings segments attract investment as solvent-based alternatives face displacement, pulling engineered kaolin fillers for rheology control and surface coating applications.
Market Restraints
- Feedstock access concentration:Maoming deposits and Georgia controlled deposits anchor premium-grade supply, creating geographic chokepoints for unintegrated ceramic processors.
- Calcined clay substitution economics:Automotive underhood rubber compounds favor low-moisture absorption alternatives where calcined kaolin commands margin premiums over hydrous grades.
- EU REACH compliance friction:Hardering purity requirements for kaolin entering coatings and consumer goods supply chains disadvantage unrefined exporters lacking integrated refining networks.
Strategic Opportunities
- Indian ceramics corridor expansion:Ashapura Group volume-scale positioning indicates underpenetrated capacity for BIS-graded ceramic raw materials beyond traditional extraction jurisdictions.
- Specialty automotive applications:Low-moisture absorption kaolin grades for underhood rubber compounds represent margin-rich white space distinct from commoditized paper coating volumes.
- SAMR product safety tailwinds:China's State Administration for Market Regulation monitoring of clay entering consumer goods channels favors processors with established laboratory certification infrastructure.
Industry Challenges
- Magnetic separation capex intensity:Refining raw ore through blunging, classification, and magnetic separation to yield engineered fillers requires significant capital allocation toward beneficiation assets.
- ISO 2469 brightness certification timelines:Laboratory verification of particle sizes below two microns and brightness values creates compliance bottlenecks for pit operators seeking coatings market entry.
- Legacy wet-process integration:Ceramic processors with established hydrous kaolin workflows face reconfiguration friction when adopting calcined clay production for specialty rubber applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Clay Market |
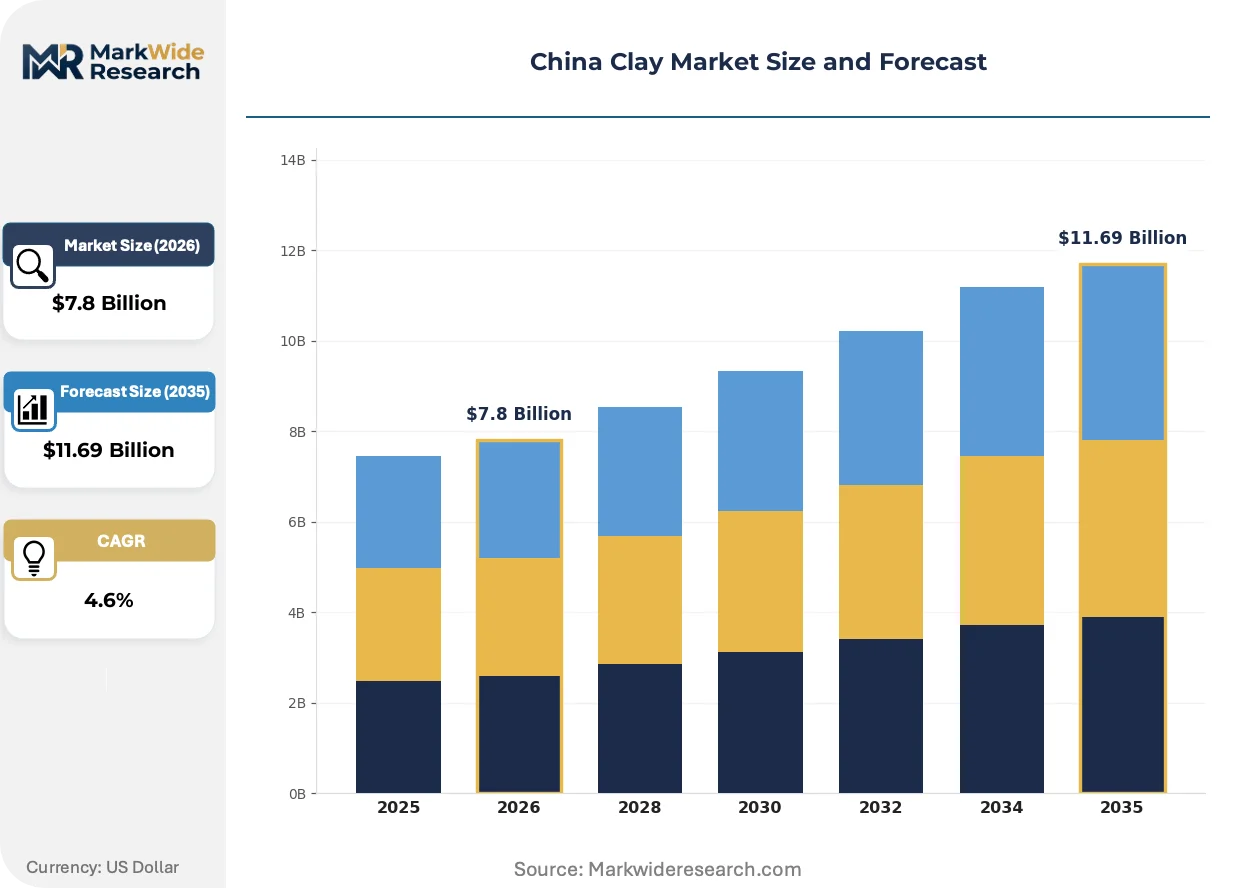
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $11.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Clay, Kaolin, Calcined Clay, High-Strength Clay Application: Ceramics, Paints, Paper, Rubber End User: Construction, Coatings, Consumer Goods, Automotive Packaging Type: Bulk Bags, Sacks, Containers, Drums |
| Companies Covered | KaMin LLC, Ashapura Group, Imerys S.A., Maoming Xingli Kaolin Co. Ltd., EICL Limited, BASF SE, Sibelco, Jiangxi Sincere Mineral Industry Co., Ltd., Thiele Kaolin Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Clay Market Strategic Shifts
Active reformulation across waterborne coatings and tightening extraction compliance are compressing traditional supply hierarchies, rewarding processors with integrated beneficiation and certified laboratory infrastructure.
Dry-process calcination technology for low-moisture kaolin grades is decentralizing specialty filler production away from centralized wet-refining hubs. Automotive rubber compounders in Germany and Japan are adopting these grades at accelerated pace for underhood applications. The structural consequence is compressing geographic premiums previously captured by Maoming and Georgia deposit holders.
EU REACH registration requirements for extracted minerals entering coatings supply chains are hardening purity documentation obligations. Industrial consequence falls heaviest on unrefined ore exporters lacking ECHA-compliant characterization data. Specialty coatings segments in France and Italy are responding by consolidating procurement toward integrated European refiners with captive laboratory networks.
Buyer concentration among Guangdong ceramic clusters is compressing switching cycles for kaolin suppliers. Long-term offtake contracts with volume-tier pricing are displacing spot-market procurement for high-grade tile and sanitary ware feedstock. This pattern is most visible in Maoming deposit supply corridors where processor integration with downstream ceramic manufacturers has deepened.
China Clay Market Segmentation
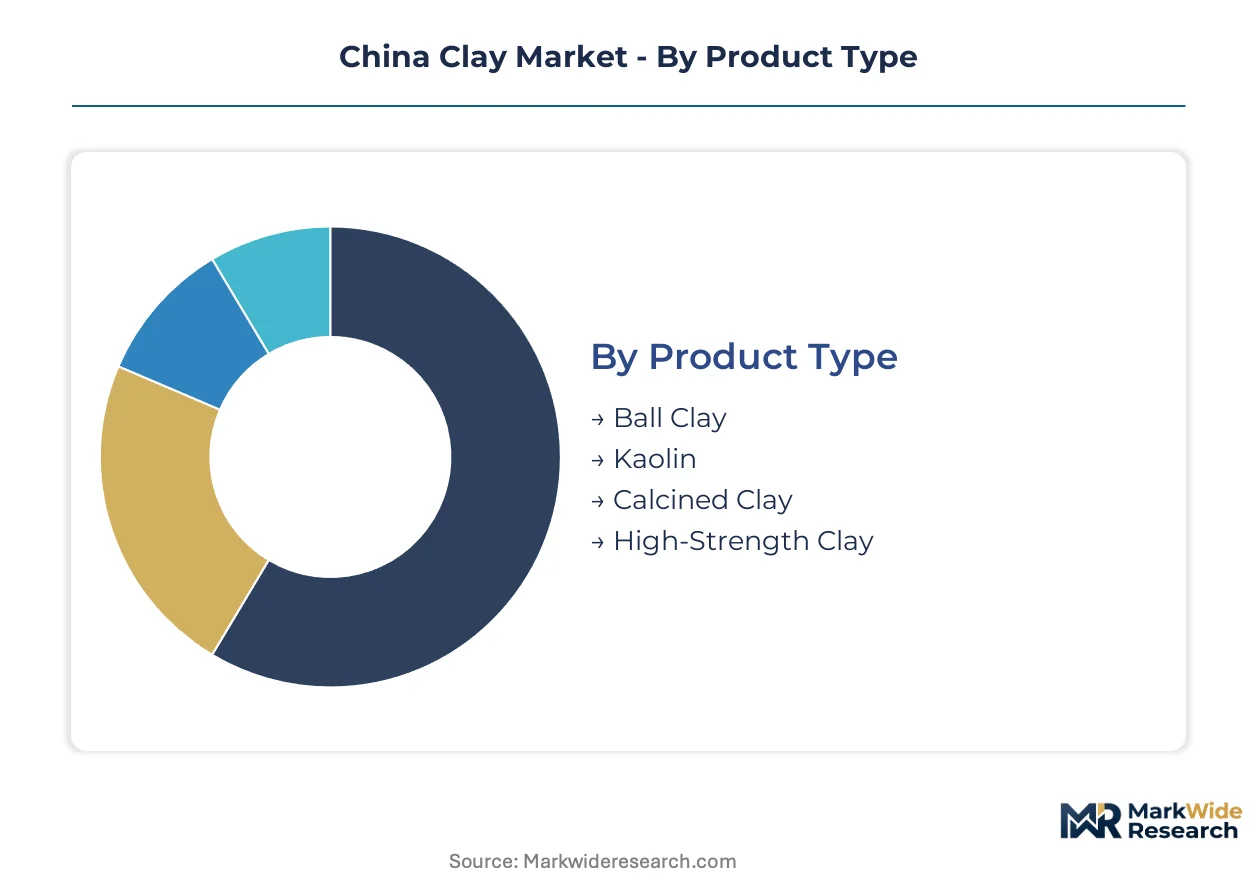
China clay segmentation reveals a market bifurcated between high-volume commodity grades and engineered specialty variants. Processors configure beneficiation assets differently across product tiers, with brightness certification and particle size distribution determining access to premium coatings and ceramics channels.
Product Type:
Kaolin commands structural volume leadership while calcined variants capture margin premiums through energy-intensive processing.
- Kaolin:Hydrous aluminum silicate with particle sizes below two microns and ISO 2469 brightness certification. Guangdong Province ceramic clusters source refined material from Maoming deposits for high-grade tile and sanitary ware production.
- Calcined Clay:Thermally treated at controlled temperatures to drive off hydroxyl groups, yielding low-moisture absorption grades. Automotive underhood rubber compounders in Germany and Japan adopt these at accelerated pace for thermal stability requirements.
- Ball Clay:Plastic sedimentary clay with high organic content, valued for binding properties in ceramic body formulations.
- High-Strength Clay:Engineered grades with enhanced green strength for demanding structural ceramic applications.
Mature deployment sits with kaolin across paper coating and ceramics. Newer deployment is concentrated in calcined clay for specialty automotive and industrial rubber segments.
Application:
End-use concentration patterns reflect divergent purity requirements and certification burdens across supply chains.
- Ceramics:Body and glaze formulations consuming hydrous kaolin with controlled rheology. China clay provides plasticity and fired strength for tile, sanitary ware, and tableware production.
- Paints:Waterborne coating systems displace solvent-based alternatives, pulling engineered kaolin for titanium dioxide extension and sheen control. EU REACH compliance hardens purity documentation for coatings market entry.
- Paper:Coating and filler applications requiring high brightness and controlled particle geometry for printability.
- Rubber:Reinforcement and barrier properties in tire and mechanical goods, with calcined grades penetrating underhood applications.
Volume concentration remains in ceramics. Reformulation investment flows fastest into paints as environmental regulations accelerate coating chemistry shifts.
End User:
Customer segmentation tracks regulatory exposure and procurement sophistication across industrial and consumer channels.
- Construction:Ceramic tile and sanitary ware manufacturers sourcing BIS-graded or GB-compliant raw materials for building product certification.
- Coatings:Industrial and decorative paint formulators requiring ECHA-compliant characterization data for EU market access.
- Consumer Goods:SAMR-monitored channels where product safety declarations elevate laboratory certification requirements for clay processors.
- Automotive:Rubber compounders specifying low-moisture absorption grades for thermal management in engine compartment applications.
Procurement standardization is most advanced in automotive. Compliance complexity is expanding fastest in consumer goods as market regulators tighten safety surveillance.
Packaging Type:
Logistics configuration varies with customer scale, material sensitivity, and supply chain integration depth.
- Bulk Bags:Ton-scale flexible intermediate bulk containers for integrated ceramic processors with captive milling capacity.
- Sacks:Multi-wall paper or woven polypropylene bags for mid-tier coatings and ceramics customers without bulk handling infrastructure.
- Containers:Intermodal shipping units for export-oriented refined kaolin moving to coatings and paper customers.
- Drums:Sealed steel or fiber containers for specialty calcined grades requiring moisture protection during extended storage.
Containerized shipment dominates export-oriented refined material. Drum packaging is gaining share in specialty calcined segments where moisture sensitivity commands protective logistics investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China dominates global kaolin consumption through Guangdong Province ceramic clusters, while the United States and India anchor production capacity through controlled deposits in Georgia and BIS-graded corridors. Extraction regulations in these jurisdictions are reshaping supply access and procurement patterns.
China
Guangdong Province ceramic manufacturers consume refined kaolin from Maoming deposits for high-grade tile and sanitary ware production. MEE enforces GB standards on mining wastewater discharge, elevating compliance costs for informal pit operators. Maoming deposit corridors now favor integrated processors with captive laboratory certification infrastructure.
United States
Georgia deposits anchor North American premium-grade supply for paper coating and specialty filler applications. EPA mining waste regulations under RCRA constrain unbeneficiated ore exports, consolidating volume toward integrated refiners with magnetic separation capacity. Sandersville and Macon processing hubs serve coatings compounders with ISO 2469-certified brightness grades.
India
Gujarat and Rajasthan ceramic corridors expand consumption of BIS-graded kaolin for sanitary ware and tableware production. BIS grading system for ceramic raw materials constrains informal pit operators lacking laboratory verification. Bhuj and Vadodara industrial zones attract investment in beneficiation assets serving domestic tile manufacturers.
Germany
Automotive rubber compounders in Bavaria and Baden-Württemberg adopt calcined kaolin grades for underhood thermal management applications. ECHA REACH registration requirements harden purity documentation for kaolin entering coatings supply chains. Cologne and Hamburg refining hubs consolidate procurement toward integrated European processors with captive laboratory networks.
Brazil
São Paulo and Minas Gerais ceramics manufacturers source hydrous kaolin for construction tile body formulations. ANVISA monitors product safety declarations for clay entering consumer goods channels, favoring processors with established certification infrastructure. Piracicaba and Uberlândia industrial zones develop beneficiation capacity for export-oriented refined material.
China Clay Market Competitive Environment
The competitive structure tilts toward integrated refiners with captive laboratory certification and geographic concentration around premium deposits. Tiered positioning separates volume-scale operators serving commodity ceramics from specialty-grade producers capturing margin premiums in automotive and coatings segments. Dominant archetypes include deposit-integrated multinationals, regional beneficiation specialists, and captive processors serving downstream ceramic manufacturers. Competitive moves concentrate on backward integration into mining assets and long-term offtake contracting with certified refiners.
Within the deposit-integrated tier, Imerys S.A. and KaMin LLC exemplify archetypes leveraging controlled extraction sites in Europe and North America respectively. Ashapura Group occupies a position representing volume-scale positioning across Indian ceramics corridors. Maoming Xingli Kaolin Co. Ltd. anchors the China-based specialist segment with proximity to Guangdong ceramic clusters. These three named entities collectively illustrate how geographic chokepoints around Maoming and Georgia deposits structure competitive access, while laboratory certification infrastructure separates premium-grade suppliers from unrefined ore exporters.
| Leading Market Players |
|---|
| KaMin LLC |
| Ashapura Group |
| Imerys S.A. |
| Maoming Xingli Kaolin Co. Ltd. |
| EICL Limited |
| BASF SE |
| Sibelco |
| Jiangxi Sincere Mineral Industry Co., Ltd. |
| Thiele Kaolin Company |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap processors in Guangdong Province anchor supply discipline through captive beneficiation assets, translating feedstock concentration near Maoming deposits into pricing leverage over unintegrated ceramic manufacturers lacking laboratory certification infrastructure.
Pricing Analysis
Margin tightening in standard-grade hydrous kaolin reflects buyer consolidation among Guangdong ceramic clusters and their migration toward long-term offtake contracts with volume-tier pricing. Three-tier pricing structure across ISO 2469-certified premium, BIS-graded standard, and unrefined economy levels separates processors with magnetic separation capacity from informal pit operators. Cost-down pressure on economy grades accelerates because MEE wastewater enforcement is forcing uncertified exporters out of coatings supply chains. Construction ceramic manufacturers exhibit highest price sensitivity, while automotive rubber compounders accept premium calcined clay pricing for thermal stability specifications.
Supply Chain Analysis
ISO 2469 brightness certification and ECHA REACH registration requirements gate market access, concentrating refined material flows through integrated processors with captive laboratory networks. Geographic supply centers on China, the United States, and India, with Maoming deposits, Georgia controlled sites, and Gujarat-Rajasthan corridors anchoring premium-grade output. Raw material extraction draws from weathered feldspar formations, requiring energy-intensive calcination for low-moisture specialty grades. Single-source vulnerability concentrates around Maoming deposit corridors where processor integration with downstream ceramic manufacturers has deepened. Distribution runs through long-term offtake contracts displacing spot-market procurement for high-grade tile and sanitary ware feedstock.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dry-process calcination technology is displacing legacy wet-refining hubs, compressing geographic premiums previously captured by traditional deposit holders and rewarding processors with decentralized specialty filler production capacity.
For Market Incumbents: Anchor premium positioning through backward integration into Maoming or Georgia mining assets while accelerating SAMR-compliant laboratory certification for consumer goods channels. Defend against calcined clay substitution in automotive segments by securing thermal stability specifications with German and Japanese rubber compounders. Prioritize long-term offtake contracting with Guangdong ceramic clusters to lock volume-tier pricing structures. For New Entrants and Emerging Players: Regional beneficiation specialists in Indian ceramics corridors offer the most penetrable white-space target, as Ashapura Group volume-scale positioning indicates underpenetrated BIS-graded capacity beyond traditional extraction jurisdictions. Specialty automotive applications for low-moisture absorption kaolin grades represent margin-rich entry points distinct from commoditized paper coating volumes. Partner with coatings formulators in France and Italy consolidating procurement toward ECHA-compliant European refiners. For Investors and Strategic Acquirers: Distressed-cycle entries favor unintegrated mid-cap processors in China facing MEE compliance cost escalation but possessing established Guangdong customer relationships and laboratory infrastructure. Long-term viability centers on beneficiation asset ownership in jurisdictions with tightening extraction regulations. Watch for inflection when SAMR product safety enforcement accelerates laboratory certification requirements for clay entering consumer goods channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mining Assets | Captive Maoming or Georgia deposit access secures feedstock certainty against tightening rehabilitation rules. |
| Laboratory Certification Investment | SAMR and ECHA compliance infrastructure opens coatings and consumer goods channels to premium pricing. |
| Dry-Process Calcination Capacity | Decentralized thermal treatment capability captures automotive rubber compounder demand in Germany and Japan. |
| Long-Term Offtake Contracting | Volume-tier pricing structures with Guangdong ceramic clusters displace spot-market volatility. |
| Specialty Grade Development | Low-moisture absorption kaolin for underhood applications commands margin premiums over hydrous grades. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with ceramic plant managers, coatings procurement leads, mining operation directors, and laboratory certification specialists. Bottom-up volume modeling triangulated against top-down macroeconomic indicators from MEE discharge records, BIS grading registries, and ECHA REACH submission databases.
Reconciliation of production capacity disclosures, import-export flows, and end-use consumption surveys shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, application industry, end-user regulatory exposure, and regional production hub classification. CAGRs derived from trend extrapolation of historical volume movements adjusted for policy-driven supply constraints and technology substitution patterns in automotive rubber formulations.
Caveats apply where MEE enforcement intensity, ECHA purity documentation expansion, or calcined clay adoption curves in German automotive supply chains could materially shift the outlook. Forecasts reflect assumptions about regulatory continuity and ceramic processor integration timelines. A model refresh is warranted upon material change in SAMR product safety surveillance protocols or dry-process calcination technology cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Global Alumina Trihydrate Market
Ceramics
Zeolite 4A Market
Ceramics
Cordierite Market
Ceramics
Advanced Ceramic Additives Market
Ceramics
Cement Castables Market
Ceramics
Asia-Pacific Activated Alumina Market
Ceramics
Tetra-N-Butyl Titanate Market
Ceramics
Europe Activated Alumina Market
Ceramics
High Temperature Ceramics Market
Ceramics
United Kingdom Ceramic Tiles Market
Ceramics
Colloidal Alumina Market
Ceramics
Engineering Ceramics Market
Ceramics
Calcium Silicate Boards Market
Ceramics
Co-Fired Ceramic Market
Ceramics
South Korea Ceramic Sanitaryware Market
Ceramics
Philippines Ceramic Tiles Market