
 United Kingdom Ceramic Tiles Market | 2026-2036
United Kingdom Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Ceramic Tiles Market Analytics
Specialist tile retail networks is tilting toward direct-to-contractor and builder-merchant channels across the United Kingdom. Johnson Tiles leverages its Stoke-on-Trent manufacturing base to sustain domestic supply reliability for large housing developers. Porcelanosa Grupo competes through design-led showroom positioning in premium London catchments. CTD Tiles anchors volume distribution through national branch networks serving trade professionals.
Ceramic tiles are clay-based surfacing materials fired at temperatures exceeding 1,000 degrees Celsius, forming dense, water-resistant slabs used for protective and decorative interior and exterior finishes. Porcelain and vitrified categories command structural attention due to lower water absorption rates suited to high-traffic commercial flooring. The hospitality end user segment shows fastest trajectory as hotel operators specify large-format tiles for accelerated installation cycles. Wall application margins outpace flooring in refurbishment projects where vertical surfaces dominate material budgets.
BSI Kitemark standards, CE marking under retained EU law, and UKCA conformity requirements collectively govern product safety and performance claims for ceramic tiles sold in Britain. These frameworks elevate compliance costs for smaller importers while rewarding manufacturers with certified test-house partnerships. Stakeholders must monitor potential divergence between UKCA and EU harmonised standards as post-Brexit regulatory autonomy matures.
Market Dynamics
Residential renovation cycles across England and Scotland are compressing replacement timelines, while BSI Kitemark certification requirements for slip resistance and durability are tightening product standards and elevating compliance burdens for smaller suppliers.
Growth Catalysts
- BSI Kitemark Certification Mandates:Slip resistance and durability standards under retained EU law are forcing specification upgrades in commercial flooring, particularly within hospitality refurbishment projects.
- Hospitality Sector Acceleration:Hotel operators in London and the South East are specifying large-format tiles to compress installation cycles and minimize operational downtime.
- Stoke-on-Trent Manufacturing Concentration:Domestic production clusters sustain supply reliability for large housing developers, reducing lead-time exposure from continental European imports.
Market Restraints
- Natural Gas Input Volatility:Firing temperatures exceeding 1,000 degrees Celsius create acute energy cost sensitivity for domestic manufacturers, compressing margin buffers during price spikes.
- Import Dependency for Porcelain Grades:Lower water absorption porcelain and vitrified categories rely heavily on Italian and Spanish supply chains, concentrating sourcing risk.
- UKCA-EU Harmonisation Uncertainty:Potential divergence between UKCA and retained EU conformity requirements threatens dual-certification costs for products serving both British and continental markets.
Strategic Opportunities
- Wales and Northern England Underpenetration:Regional housing stock outside London-South East corridor presents volume expansion potential for trade-anchored distribution networks.
- Digital Specification Platforms:Architect and interior designer procurement is migrating toward visualisation tools that compress sample-to-order cycles and reduce showroom dependency.
- Circular Economy Incentives:Emerging waste reduction mandates for construction materials are creating certification premiums for recycled-content tile formulations.
Industry Challenges
- Technical Ceramics Skill Shortage:Stoke-on-Trent and traditional manufacturing bases face retiring craft expertise gaps in glaze chemistry and kiln operation.
- UKCA Testing Timeline Compression:Certification backlogs at notified bodies are extending product launch windows for new porcelain and vitrified introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Ceramic Tiles Market |
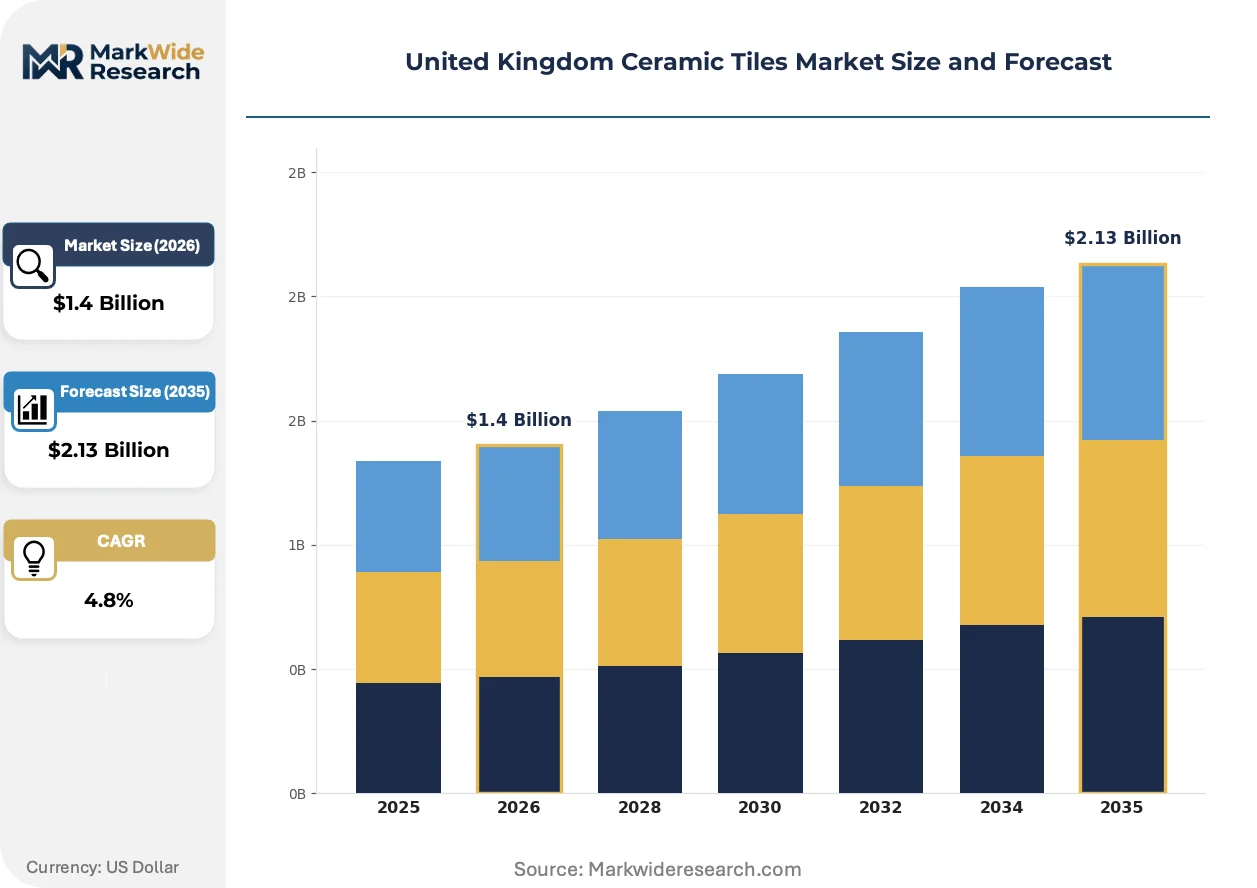
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glazed, Porcelain, Matte, Vitrified End User: Residential, Commercial, Industrial, Hospitality Size: Small, Medium, Large, Custom Application: Flooring, Wall, Outdoor, Countertops |
| Companies Covered | CTD Tiles, Ecotile Flooring Ltd, Johnson Tiles, Domus Tiles, Craven Dunnill, Porcelanosa Grupo, H&E Smith Ltd, Original Style Ltd, British Ceramic Tile, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Ceramic Tiles Market Evolving Landscape
Digital inkjet decoration and thin-profile large-format manufacturing are compressing traditional tile economics, while regulatory pressure on embodied carbon is reshaping material specification priorities across British construction.
Thin-profile large-format porcelain slabs are replacing traditional thick-body ceramic in commercial flooring specifications. Hotel operators and retail fit-out contractors are adopting these materials for accelerated installation and reduced substrate preparation. The technology is rendering obsolete conventional 10-12mm thickness standards that dominated British commercial projects for decades.
UKCA conformity requirements are diverging from retained EU harmonised standards as post-Brexit regulatory autonomy matures. Manufacturers serving both British and continental markets face escalating dual-certification testing costs at UKAS-accredited laboratories. Domestic housing developers and merchant distributors are prioritising UKCA-marked stock to de-risk specification liability.
Trade professional procurement is consolidating through builder-merchant channels and direct-to-contractor platforms. Specialist tile retail networks are losing specification influence as volume concentrates with national branch networks serving housing developers. Scotland and Northern England exhibit the fastest channel migration, where merchant consolidation has outpaced independent showroom retention.
United Kingdom Ceramic Tiles Market Segmentation
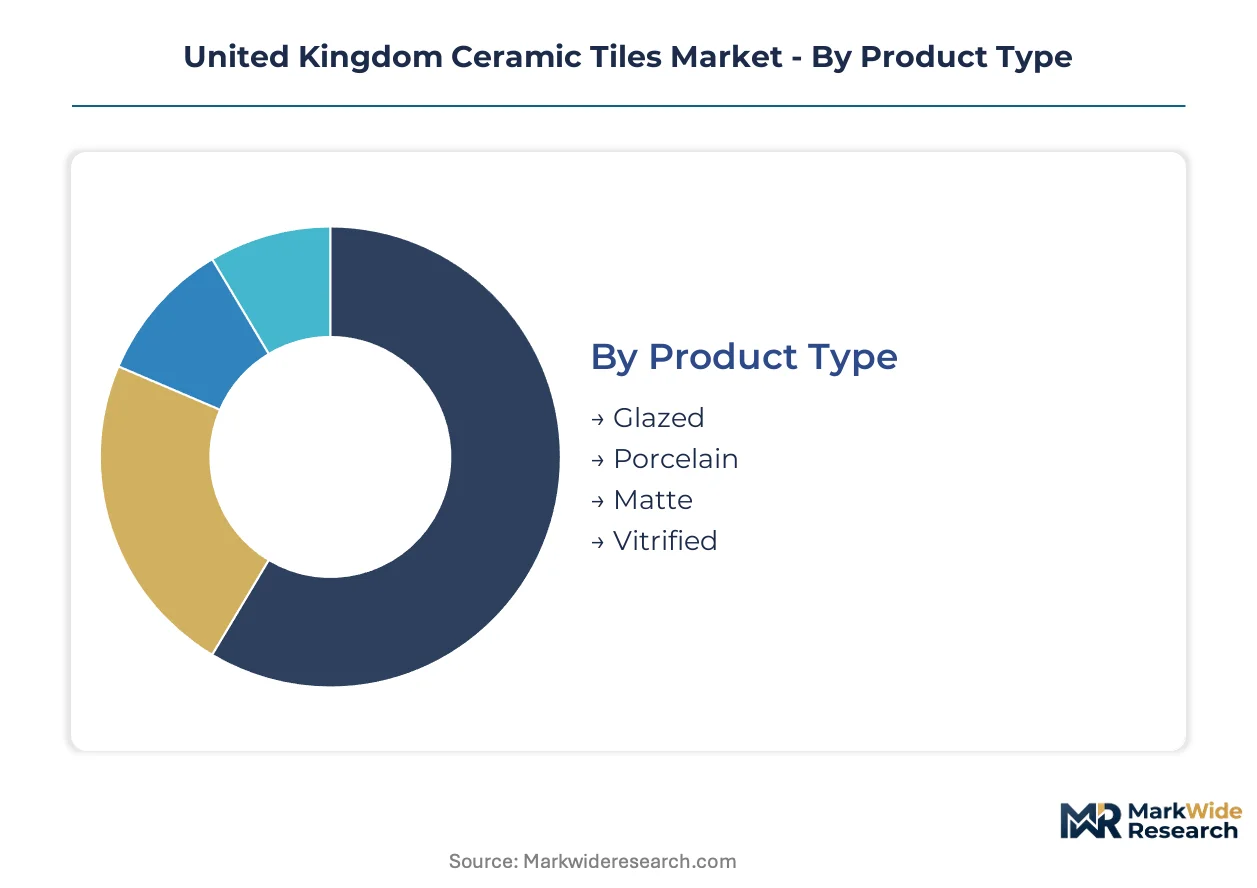
Ceramic tile specification in the United Kingdom follows distinct technical and application logics that shape procurement patterns across housing developers, hospitality operators, and trade professionals. Segmentation reveals how firing temperatures, water absorption rates, and format dimensions translate into divergent margin structures and supply chain requirements.
Product Type:
The use-case spectrum spans decorative surfacing to structural load-bearing applications, with water absorption thresholds and surface finish durability determining specification authority.
- Glazed:Clay bodies coated with glass-forming minerals create decorative surfaces with moderate slip resistance. Residential renovation across England favors these tiles for kitchen and bathroom walls where aesthetic variety outweighs structural demands.
- Porcelain:Fired at temperatures exceeding 1,200 degrees Celsius, these dense slabs exhibit water absorption below 0.5 percent. Commercial flooring in London hospitality projects specifies large-format porcelain for durability under sustained foot traffic.
- Matte:Unglazed or minimally processed surfaces deliver enhanced slip resistance for wet-area applications. Pool surrounds and spa facilities in the South East specify matte finishes for safety compliance.
- Vitrified:Full-body color-through composition eliminates glaze layer dependency. Industrial warehousing in the Midlands specifies vitrified tiles for abrasion resistance under heavy machinery loads.
Established volume favors glazed tiles; emerging adoption favors porcelain as commercial specifications tighten durability requirements.
End User:
Customer type segmentation tracks procurement scale and specification authority, from fragmented household decision-making to centralized commercial procurement.
- Residential:Individual homeowners and private landlords drive replacement cycles through merchant branch networks. Scotland's housing stock renewal concentrates demand in bathroom and kitchen refurbishment.
- Commercial:Office fit-out contractors and retail developers specify through direct-to-contractor platforms. BSI Kitemark certification requirements elevate compliance burdens for flooring specifications.
- Industrial:Manufacturing facilities and logistics operators prioritize chemical resistance and load-bearing capacity. Northern England's warehousing expansion sustains volume demand for heavy-duty formats.
- Hospitality:Hotel operators in London and the South East are specifying large-format tiles to compress installation cycles and minimize operational downtime. This segment is expanding most quickly as refurbishment timelines compress.
Procurement scale separates residential fragmentation from hospitality concentration; specification authority shifts toward commercial procurement teams.
Size:
Format dimensions determine installation economics and substrate preparation requirements across British construction.
- Small:Traditional formats below 300mm suit intricate patterning and heritage restoration. Period property renovation in conservation areas sustains artisan demand.
- Medium:Standard 300-600mm formats balance handling efficiency with design flexibility. Volume housing developers in the South East specify these for cost-controlled installation.
- Large:Slabs exceeding 600mm reduce grout lines and accelerate coverage rates. Premium residential and commercial projects in London favor large formats for seamless aesthetics.
- Custom:Bespoke dimensions serve architectural specifications and irregular spatial configurations. High-end hospitality fit-outs commission custom sizes for signature interiors.
Installation efficiency favors large formats; design flexibility sustains medium-format dominance in volume housing.
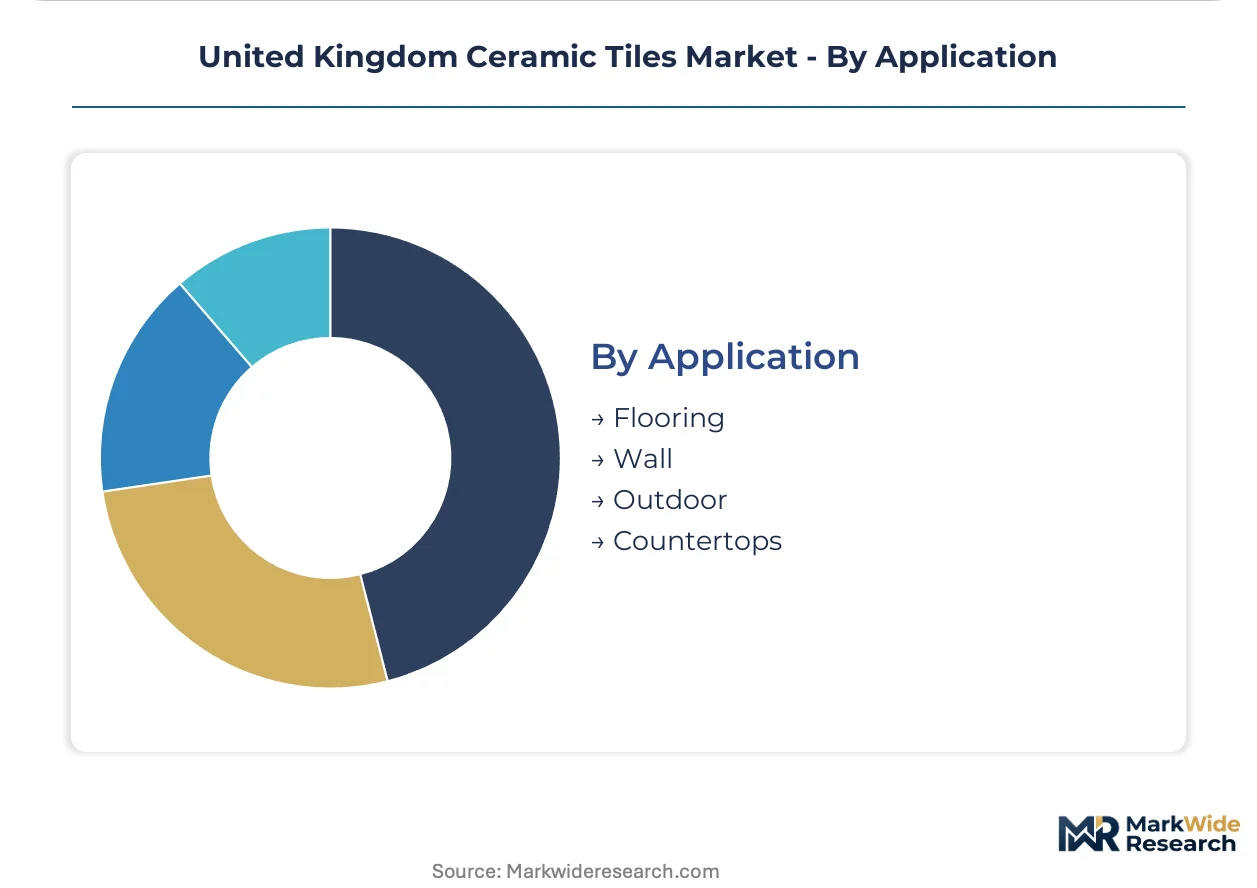
Application:
Surface orientation and exposure conditions determine material performance requirements and margin structures.
- Flooring:Load-bearing applications demand slip resistance certification and impact durability. Commercial specifications in England concentrate procurement attention on BSI Kitemark-rated products.
- Wall:Vertical surfacing prioritizes weight limits and adhesive compatibility. Refurbishment projects allocate disproportionate material budgets to wall applications where visual impact dominates.
- Outdoor:Frost resistance and UV stability govern external specifications. Patio and terrace construction in the South East drives seasonal demand for porcelain pavers.
- Countertops:Work surface applications require stain resistance and edge fabrication capability. Kitchen designers in premium residential markets specify large-format porcelain for seamless integration.
Margin concentration favors wall applications in refurbishment; volume expansion centers on outdoor porcelain as residential landscaping investment rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BSI Kitemark certification anchors specification authority across England, Scotland, Wales, and Northern Ireland. Regional housing cycles and refurbishment intensity create divergent demand patterns. Local manufacturing clusters and import dependencies shape supply reliability.
London and the South East
Hotel operators and premium residential developers drive large-format porcelain adoption for accelerated installation cycles. UKCA marking requirements at UKAS-accredited laboratories elevate compliance costs for continental suppliers. The M25 corridor concentrates merchant distribution hubs serving trade professionals.
Midlands
Stoke-on-Trent manufacturing sustains domestic supply reliability for volume housing developers. BSI Kitemark slip resistance standards govern commercial flooring specifications in Birmingham office fit-outs. The Potteries cluster retains craft expertise in glaze chemistry despite retiring workforce pressures.
Scotland
Housing stock renewal compresses bathroom and kitchen replacement timelines in Glasgow and Edinburgh. Scottish Building Standards integrate durability requirements aligned with retained EU technical specifications. Merchant consolidation outpaces independent showroom retention in Aberdeen and Dundee.
North England
Industrial warehousing expansion sustains heavy-duty vitrified tile demand in Manchester and Leeds logistics corridors. Underpenetration relative to London-South East levels presents volume expansion potential for trade-anchored networks. Northern Powerhouse infrastructure commitments influence commercial flooring procurement.
Wales
Regional housing stock outside the London-South East corridor offers growth potential for national branch networks. Welsh construction procurement guidelines emphasize UKCA-marked materials for public sector projects. Cardiff and Swansea merchant channels serve fragmented residential renovation demand.
United Kingdom Ceramic Tiles Market Competitive Landscape
Domestic manufacturers and continental importers split the market across certification tiers. Stoke-on-Trent production clusters compete with Italian and Spanish supply chains for porcelain specification. Three archetypes dominate: heritage-anchored domestic producers, design-led continental brands, and volume-optimized merchant distributors. Capacity reliability and dual-certification cost management constitute primary competitive vectors.
Among heritage-anchored domestic producers, Johnson Tiles occupies a position exemplifying manufacturing-base resilience. Porcelanosa Grupo represents the design-led continental import archetype through premium showroom positioning. CTD Tiles anchors the volume-optimized merchant distributor tier with national branch network coverage. These three exemplars illustrate how certification compliance, supply reliability, and channel access stratify competitive positioning.
| Leading Market Players |
|---|
| CTD Tiles |
| Ecotile Flooring Ltd |
| Johnson Tiles |
| Domus Tiles |
| Craven Dunnill |
| Porcelanosa Grupo |
| H&E Smith Ltd |
| Original Style Ltd |
| British Ceramic Tile |
| Others |
Value Network & Pricing Analysis
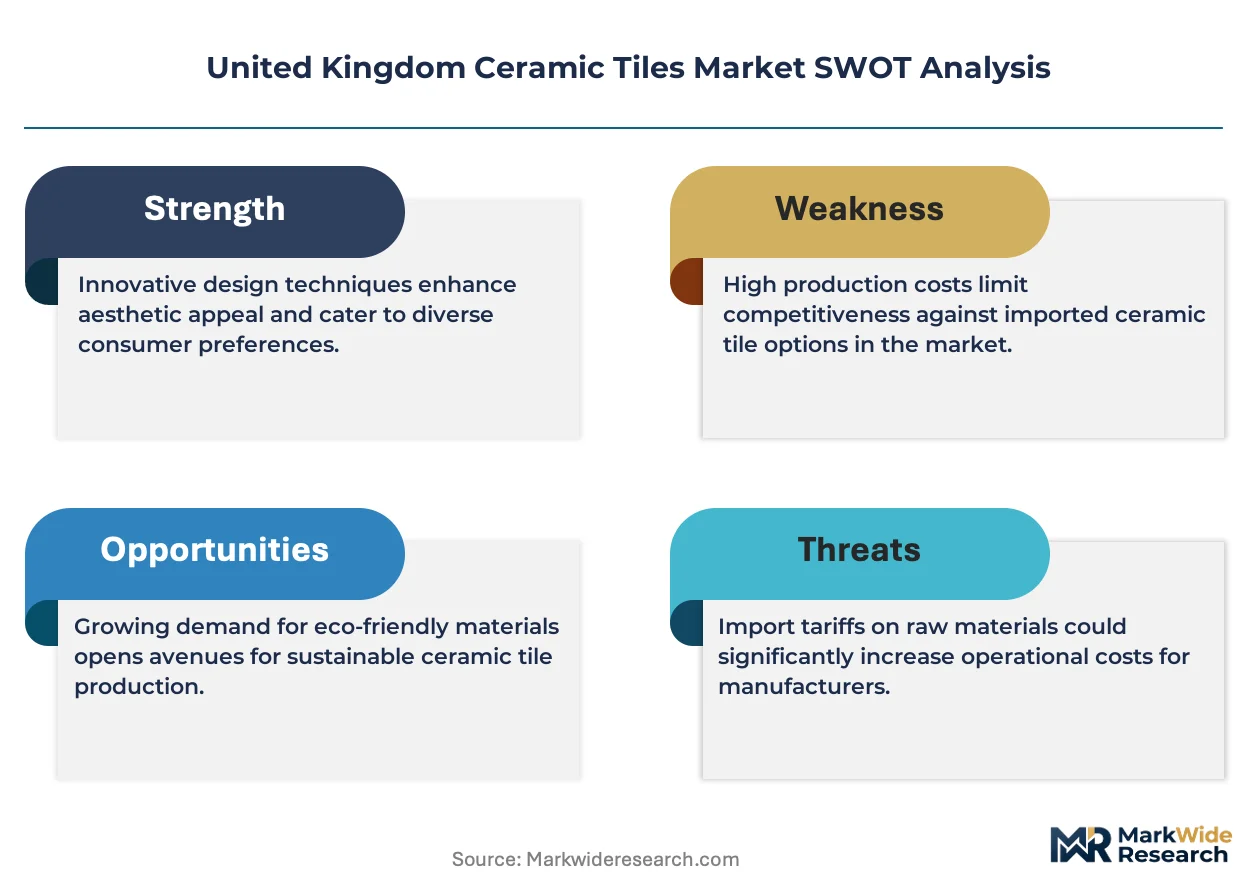
Overcapacity in Italian and Spanish porcelain production is compressing export pricing into British merchant channels while simultaneously elevating bargaining leverage for large housing developers. This utilization asymmetry between continental supply and UK demand concentrates margin pressure on domestic Stoke-on-Trent manufacturers facing elevated natural gas firing costs.
Pricing Analysis
Geographic price spreads between Italian-imported large-format porcelain and domestically manufactured glazed ceramic exceed thirty percent at merchant wholesale tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by BSI Kitemark certification grade and water absorption performance. Cost compression in standard-grade glazed tiles is intensifying because merchant buyers are consolidating purchase volumes with national branch networks. Housing developers represent the most price-sensitive segment, while premium hospitality operators in London exhibit lowest sensitivity due to specification authority and operational downtime costs.
Supply Chain Analysis
Tariff exposure between the United Kingdom and European Union member states dominates supply chain risk calculus for porcelain and vitrified categories. Manufacturing concentrates in Italy, Spain, and Turkey for premium large-format grades, while domestic Stoke-on-Trent production serves volume glazed and wall-tile demand. Raw material dependencies encompass Devon ball clay, Cornish kaolin, and imported feldspar from Scandinavian sources. Distribution runs through builder-merchant branch networks and direct-to-contractor platforms, bypassing traditional specialist tile retail showrooms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom ceramic tiles market operates as a substitution defense against luxury vinyl tile and engineered stone surfacing alternatives that are compressing specification share in commercial flooring. Incumbents must navigate this threat through certification differentiation and supply reliability positioning.
For Market Incumbents: Harden UKCA certification pipelines at UKAS-accredited laboratories to accelerate product launch windows against continental competitors facing dual-certification burdens. Deepen captive supply of Cornish kaolin and Devon ball clay through long-term mineral lease agreements to insulate margin buffers from raw material volatility. This defensive posture neutralizes emerging Spanish and Italian entrants while reinforcing specification authority with merchant distributors.
For New Entrants and Emerging Players: Mid-market commercial refurbishment in Northern England and Wales represents the most penetrable entry point given underpenetration relative to London-South East corridor density. Digital specification platforms serving architects and interior designers offer channel bypass opportunities that reduce showroom infrastructure requirements. A go-to-market angle anchored in rapid sample-to-order cycle compression can dislodge incumbent merchant relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated domestic producers with captive mineral reserves and established UKCA testing partnerships. Long-term viability across a five-to-ten year horizon hinges on regulatory divergence between British and continental conformity frameworks. The signal to watch is UKCA-EU harmonisation policy announcements from the Department for Business and Trade that would either entrench dual-certification cost advantages or erode them.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Reserves | Cornish kaolin and Devon ball clay captive supply insulates margin buffers from raw material volatility. |
| UKCA Certification Pipeline Expansion | UKAS-accredited laboratory partnerships compress product launch windows against continental competitors. |
| Digital Specification Platform Partnership | Architect and designer procurement migration reduces showroom dependency and sample-to-order cycles. |
| Regional Distribution Network Expansion | Northern England and Wales branch coverage captures underpenetrated housing stock renewal demand. |
| Large-Format Thin-Profile Manufacturing Investment | Hotel operator specifications for accelerated installation cycles drive hospitality segment adoption. |
Research Methodology
Desk research of British Ceramic Confederation production statistics, UK trade customs data, and BSI certification registries preceded structured interviews with Stoke-on-Trent plant managers, merchant procurement directors, hospitality facilities managers, and architectural specification consultants. Secondary validation drew from UKAS laboratory accreditation records, Office for National Statistics construction output indices, and retained EU technical documentation. Bottom-up volume modeling across product categories triangulated against top-down market sizing from housing completion forecasts and commercial refurbishment expenditure patterns.
Assumptions regarding natural gas price normalisation, UKCA-EU regulatory divergence trajectory, and hospitality refurbishment cycle intensity were held fixed across baseline scenarios while sensitivity analysis varied these inputs. Segmentation modeling incorporated product type, end user procurement scale, format dimension, and surface application orientation. CAGRs were derived from regression analysis of historical construction output correlations with tile consumption intensity, supplemented by housing developer and merchant distributor order book assessments.
Practitioners should monitor UKCA testing backlog durations, Italian-Spanish export price movements, and hospitality sector occupancy recovery indicators for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Global Thermal Ceramics Market
Ceramics
Europe Ceramic Coatings Market
Ceramics
Ceramic Binders Market
Ceramics
Transparent Ceramics Market
Ceramics
China Ceramic Tiles Market
Ceramics
High Temperature Ceramics Market
Ceramics
ME K-Feldspar Market
Ceramics
Philippines Ceramic Tiles Market
Ceramics
South Korea Ceramic Tiles Market
Ceramics
Brazil Ceramic Tiles Market
Ceramics
United States Ceramic Tiles Market
Ceramics
Zirconia Ceramic Balls Market
Ceramics
Calcite Market
Ceramics
Global Ceramic Coating Market
Ceramics
Lithium Silicate Market
Ceramics
Global Ceramic Balls Market