
 Global Residue Testing Market | 2026-2036
Global Residue Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Residue Testing Market Foresight
Modular instrument bundling is realigning procurement patterns in residue testing. Eurofins Scientific leverages integrated chromatography-software packages to lock in multi-year service contracts with food manufacturers. SGS SA anchors its competitive position through geographic dominance in agricultural export corridors, while Bureau Veritas differentiates via specialized environmental contaminant protocols that exceed baseline regulatory requirements.
Residue testing encompasses the analytical detection and quantification of chemical contaminants—including pesticides, veterinary drugs, mycotoxins, and heavy metals—within food, environmental, and pharmaceutical matrices using chromatographic separation coupled with mass spectrometric detection at parts-per-billion sensitivity thresholds. Its primary purpose is to verify compliance with maximum residue limits and protect consumer health across regulated supply chains. Chromatography systems occupy the largest installed base due to regulatory mandates for confirmatory testing, while mass spectrometers represent the fastest-expanding product category as laboratories pursue multi-residue panels in single analytical runs. Among applications, food safety commands the deepest margin pools because export certification requirements create sticky, recurring testing volumes with limited price elasticity.
The EPA and FDA enforce divergent tolerance frameworks that shape instrument configuration requirements for laboratories serving dual-jurisdiction markets. EFSA's ongoing reassessment of legacy pesticide approvals under the EU Green Deal is forcing method redevelopment cycles that drive consumables demand and equipment replacement. REACH compliance adds another layer of analytical obligation for environmental matrices, particularly in groundwater monitoring applications. Stakeholders must monitor how regulatory convergence or divergence between the United States and European Union reshapes the economic viability of unified versus region-specific testing platforms.
Market Dynamics
The EU Green Deal's Farm to Fork Strategy is compressing maximum residue limits for pesticides, forcing laboratories to upgrade chromatography sensitivity and triggering a wave of equipment replacement across European food safety infrastructure.
Growth Catalysts
- EFSA reassessment protocols:Ongoing re-evaluation of legacy pesticide approvals under EU Green Deal mandates drives method redevelopment cycles and consumables demand.
- Export certification requirements:Food manufacturers serving dual-jurisdiction markets must maintain parallel testing capabilities for FDA and EPA tolerance frameworks.
- Munich-Darmstadt analytical cluster:Germany's concentrated instrumentation ecosystem enables rapid technology transfer to contract research organizations serving pan-European exporters.
Market Restraints
- Helium supply volatility:Gas chromatography systems depend on helium carrier gas, with price spikes and allocation disruptions constraining laboratory operating budgets.
- Mass spectrometer component concentration:Critical ion source and detector manufacturing concentrates among a handful of specialized suppliers in Germany and Japan.
- REACH environmental compliance:Extended registration timelines and testing cost burdens for novel chemistries delay new analytical method validation.
Strategic Opportunities
- India FSSAI modernization:India's food safety regulator is expanding pesticide monitoring infrastructure, creating demand for chromatography-mass spectrometry bundles in domestic laboratories.
- Multi-residue panel convergence:Single-run detection of pesticides, veterinary drugs, and mycotoxins compresses per-sample costs and expands service margins.
- Groundwater monitoring mandates:REACH-driven environmental obligations generate recurring testing volumes for agricultural runoff and industrial discharge.
Industry Challenges
- Mass spectrometry operator scarcity:Laboratories face acute shortages of technicians capable of method development and troubleshooting for high-resolution systems.
- Legacy LIMS integration:New chromatography-software packages require costly middleware development to connect with entrenched laboratory information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Residue Testing Market |
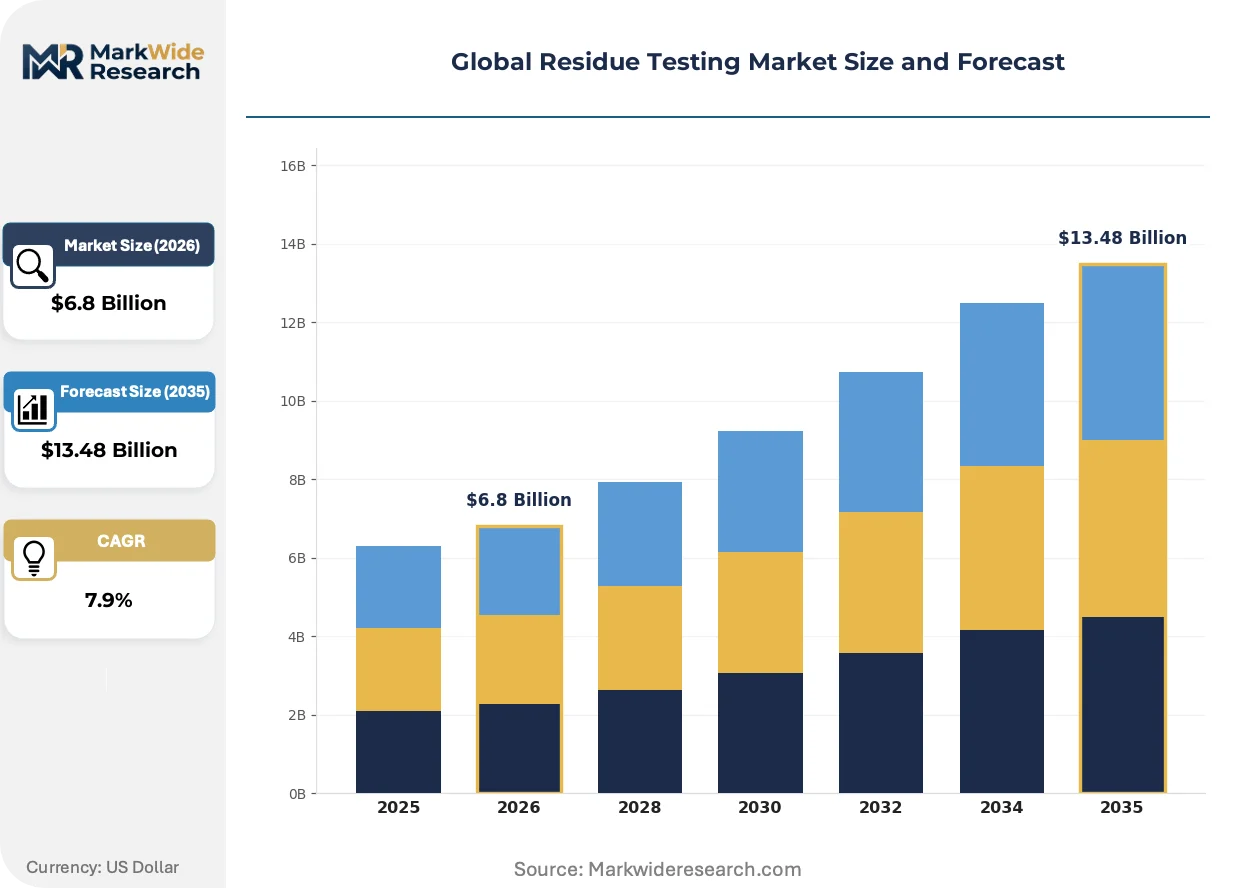
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.48 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chromatography Systems, Spectroscopy Instruments, Immunoassay Kits, Sample Preparation Devices, Mass Spectrometers Application: Food Safety, Environmental Analysis, Pharmaceutical Quality, Agricultural Monitoring, Cosmetics Testing End User: Quality Control Labs, Contract Research Organizations, Regulatory Agencies, Academic Institutions, Private Testing Facilities Deployment: Online Monitoring Systems, Portable Analyzers, Laboratory Testing, Field Testing Units, Automated Systems |
| Companies Covered | Eurofins Scientific, SGS SA, Bureau Veritas, Intertek Group plc, ALS Limited, Waters Corporation, Shimadzu Corporation, Thermo Fisher Scientific, Mérieux Nutrisciences Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Residue Testing Market Shifts & Advancements
Modular instrument architectures are reconfiguring how laboratories acquire and upgrade analytical capabilities. Bundled hardware-software-service packages now dominate capital planning, with vendors locking in multi-year relationships through integrated performance guarantees.
High-resolution mass spectrometry is consolidating pesticide screening workflows. Food safety laboratories in Germany and the Netherlands are replacing quadrupole systems with Orbitrap and time-of-flight platforms. This consolidation enables simultaneous quantification and identification of unknown metabolites, compressing the need for separate confirmatory testing.
REACH compliance deadlines are accelerating environmental matrix testing obligations. Industrial facilities near agricultural zones must document pesticide runoff in groundwater monitoring programs. Contract laboratories in Belgium and the Netherlands are expanding dedicated environmental chromatography capacity to capture this regulatory-driven volume.
Service contract unbundling is fragmenting traditional procurement relationships. Large food manufacturers now separate instrument acquisition from maintenance and consumables sourcing, pitting specialized service providers against original equipment vendors. This shift is most visible in France and Italy, where pan-European exporters negotiate multi-site testing standardization.
Global Residue Testing Market Segmentation
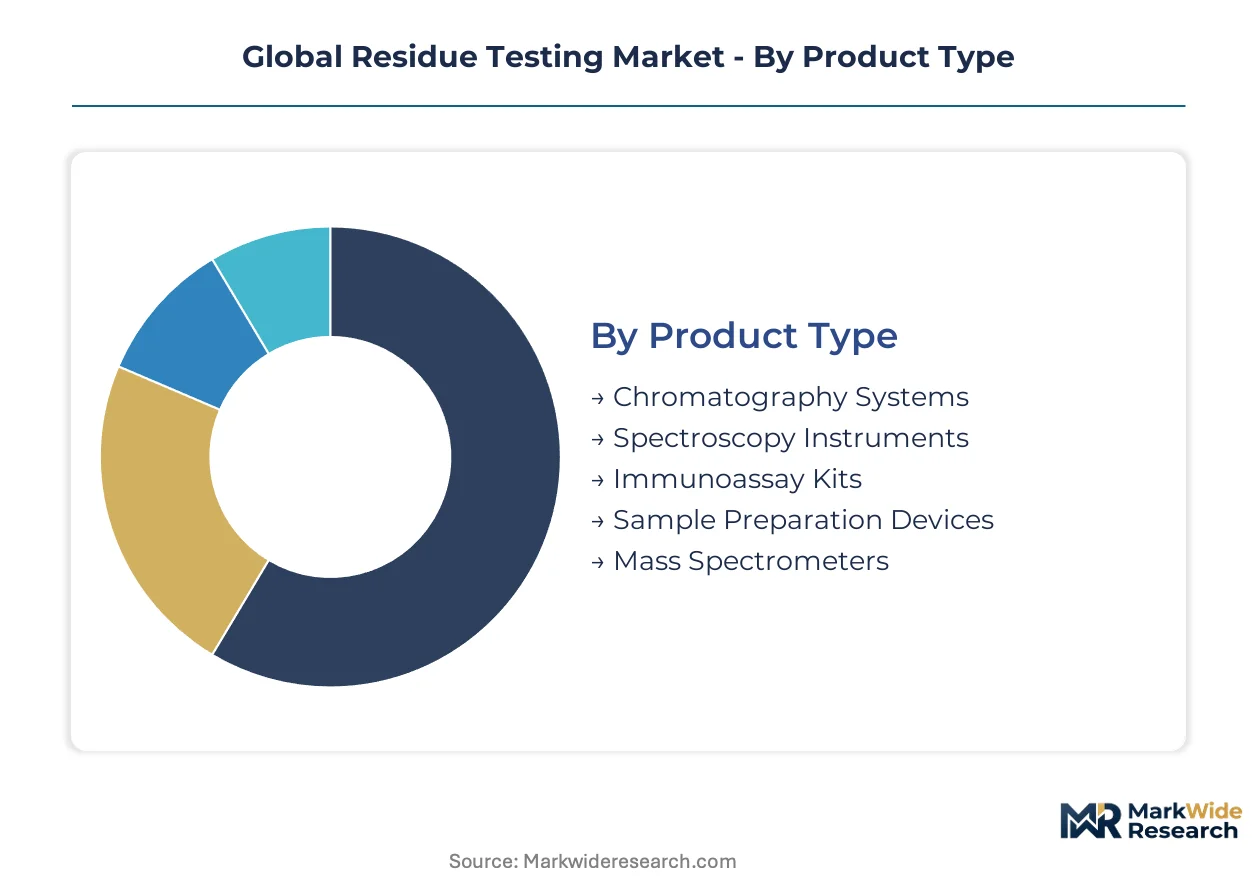
Segmentation in residue testing reveals how regulatory certification burdens concentrate demand across instrument configurations and service delivery models. Laboratories configure procurement around specific approval pathways—EFSA pesticide panels, EPA tolerance verification, or FSSAI modernization mandates—each demanding distinct analytical capabilities and sensitivity thresholds.
Product Type:
Certification requirements vary sharply across product categories, with confirmatory testing mandates dictating capital allocation toward chromatography and mass spectrometry platforms.
- Chromatography Systems:Gas and liquid chromatography platforms separate complex matrices prior to detection, achieving parts-per-billion resolution for regulated contaminants. Demand clusters in Germany's Munich-Darmstadt analytical corridor, where contract research organizations serve pan-European food exporters facing tightened EU Green Deal limits.
- Mass Spectrometers:High-resolution Orbitrap and time-of-flight systems enable simultaneous quantification and unknown metabolite identification in single analytical runs. Laboratories in the Netherlands and Belgium are replacing legacy quadrupole systems to compress confirmatory testing workflows and expand multi-residue panel capacity.
- Spectroscopy Instruments:Atomic absorption and inductively coupled plasma systems target heavy metal detection in environmental and food matrices.
- Immunoassay Kits:Enzyme-linked immunosorbent assays provide rapid screening for mycotoxins and veterinary drugs at lower capital cost.
- Sample Preparation Devices:Solid-phase extraction and QuEChERS kits standardize pre-analytical workflows across high-throughput laboratories.
Leading the category by volume: Chromatography Systems. Growing fastest: Mass Spectrometers.
Application:
Margin structures diverge across applications, with export certification creating sticky recurring volumes and limited price elasticity in food safety relative to environmental monitoring.
- Food Safety:Pesticide, veterinary drug, and mycotoxin screening for domestic consumption and cross-border trade certification. Laboratories serving dual-jurisdiction markets maintain parallel FDA and EPA method libraries, with Eurofins Scientific and SGS SA anchoring pan-European service networks.
- Environmental Analysis:Groundwater, soil, and agricultural runoff testing driven by REACH compliance and industrial discharge permits. Belgium and Dutch contract laboratories are expanding dedicated chromatography capacity to capture regulatory-driven monitoring volumes.
- Pharmaceutical Quality:Residual solvent and process impurity verification for active pharmaceutical ingredient batches.
- Agricultural Monitoring:Pre-harvest pesticide screening and post-harvest storage contaminant surveillance.
- Cosmetics Testing:Heavy metal and preservative residue analysis for personal care product safety dossiers.
Deepest margin pools concentrate in Food Safety. Steepest expansion trajectory appears in Environmental Analysis.
End User:
Procurement authority and method development capability separate institutional buyers from outsourced service consumers, reshaping vendor relationship structures.
- Contract Research Organizations:Full-service analytical providers managing multi-site standardization for multinational food manufacturers. Eurofins leverages integrated chromatography-software-service bundles to lock in multi-year relationships with guaranteed performance metrics.
- Quality Control Labs:Captive testing facilities at food and pharmaceutical manufacturers verifying inbound raw materials and finished goods.
- Regulatory Agencies:National reference laboratories establishing official methods and proficiency testing schemes.
- Academic Institutions:Research-focused installations advancing metabolomics and non-targeted screening methodologies.
- Private Testing Facilities:Independent laboratories competing on turnaround time and specialized environmental protocols.
Dominant procurement volume flows through Contract Research Organizations. Capability investment concentrates in Quality Control Labs.
Deployment:
Capital intensity and regulatory acceptance criteria fragment deployment choices between fixed laboratory infrastructure and field-mobile configurations.
- Laboratory Testing:Centralized high-sensitivity analysis using chromatography-mass spectrometry workflows in controlled environments. Germany's instrumentation cluster enables rapid technology transfer from manufacturers to end-users.
- Automated Systems:Robotic sample handling and data processing reducing operator intervention for high-throughput pesticide panels.
- Portable Analyzers:Immunoassay and simplified spectroscopy for preliminary screening at collection points.
- Field Testing Units:Mobile laboratories deployed for emergency response and remote agricultural monitoring.
- Online Monitoring Systems:Continuous analyzers for industrial discharge and water treatment facility compliance.
Largest installed base resides in Laboratory Testing. Fastest capability expansion occurs in Automated Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of analytical instrumentation concentrates in Germany's Munich-Darmstadt corridor, while consumption spreads across food-exporting nations facing divergent regulatory mandates. Laboratories in importing countries configure procurement around specific certification pathways.
Germany
EFSA reassessment protocols under the EU Green Deal drive method redevelopment cycles among contract research organizations. REACH compliance deadlines accelerate environmental matrix testing for industrial discharge monitoring. Bavaria's analytical cluster around Munich anchors technology transfer to pan-European food exporters.
United States
FDA and EPA tolerance frameworks require parallel testing capabilities for laboratories serving dual-jurisdiction markets. Export certification demands from trading partners force domestic food manufacturers to maintain chromatography-mass spectrometry bundles. California's agricultural laboratories lead adoption of high-resolution Orbitrap platforms for pesticide panels.
India
FSSAI modernization expands pesticide monitoring infrastructure across domestic food safety laboratories. Import rejection data from EU and US markets pressures exporters to upgrade detection sensitivity. Maharashtra's pharmaceutical quality control hubs drive residual solvent testing demand for active ingredient batches.
Netherlands
REACH-driven groundwater monitoring mandates generate recurring testing volumes for agricultural runoff near industrial zones. Rotterdam's contract laboratories expand dedicated environmental chromatography capacity. Belgian and Dutch facilities capture regulatory-driven volumes from cross-border industrial discharge permits.
China
SAMR tightening of maximum residue limits for domestic food safety forces laboratory equipment upgrades. Export certification to EU and US markets requires parallel method validation under divergent tolerance frameworks. Yangtze River Delta food manufacturers invest in automated multi-residue screening systems.
Global Residue Testing Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across service and instrumentation segments. Testing service providers concentrate in agricultural export corridors, while analytical instrument manufacturers cluster near Germany's research infrastructure. Three archetypes dominate: integrated service bundlers, geographic corridor specialists, and technology platform vendors. Consolidation pressures favor multi-year service contracts and automated workflow integration over discrete equipment sales.
Among diversified testing service providers, Eurofins Scientific, SGS SA, and Bureau Veritas occupy positions exemplifying distinct strategic vectors. Eurofins represents the integrated bundling archetype through chromatography-software-service packages. SGS SA anchors geographic dominance in agricultural export corridors. Bureau Veritas exemplifies specialized protocol differentiation exceeding baseline regulatory requirements.
| Leading Market Players |
|---|
| Eurofins Scientific |
| SGS SA |
| Bureau Veritas |
| Intertek Group plc |
| ALS Limited |
| Waters Corporation |
| Shimadzu Corporation |
| Thermo Fisher Scientific |
| Mérieux Nutrisciences Corporation |
| Others |
Supply & Pricing Matrix
Mass spectrometry operator scarcity in Germany's Munich-Darmstadt corridor widens labor-cost differentials between premium method-development laboratories and economy-tier screening facilities, compressing mid-market pricing spreads as buyers arbitrage capability against turnaround requirements.
Pricing Analysis
Price erosion across standard-tier chromatography services traces to helium supply volatility and consumables bundling shifts. Three-tier pricing structure across premium, standard, and economy levels separates laboratories offering EFSA-validated confirmatory methods from those running EPA-compliant screening panels. Cost-down pressure on economy-tier immunoassay screening accelerates because food manufacturers unbundle service contracts to pit specialized providers against OEM vendors. Contract research organizations serving dual-jurisdiction markets exhibit lowest price sensitivity, while independent environmental laboratories face acute margin compression.
Supply Chain Analysis
Freight cost spikes for helium cylinder logistics from Qatar and Algeria strain gas chromatography operating budgets across European laboratories. Manufacturing of critical ion source and detector components concentrates in Germany and Japan, with solid-phase extraction consumables sourcing from China and India. Single-source vulnerability in high-resolution Orbitrap platform production feeds from Thermo Fisher Scientific's concentrated assembly footprint. Distribution runs through authorized distributor networks serving national laboratory clusters, bypassing direct procurement for capital equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-resolution mass spectrometry is displacing legacy quadrupole systems across food safety workflows, compressing confirmatory testing timelines and reshaping vendor competitive positioning.
For Market Incumbents: Hedge helium dependency by securing long-term carrier gas supply agreements with Qatari distributors before allocation constraints deepen. Backward integration into consumables manufacturing insulates margin pools from third-party extraction kit price volatility. Prioritize software-hardware bundling to lock in multi-year relationships as service contract unbundling fragments traditional procurement. For New Entrants and Emerging Players: Launch via automated multi-residue panel platforms targeting India's FSSAI modernization infrastructure, where import rejection data pressures domestic laboratories to upgrade sensitivity. Capture white-space in REACH-driven groundwater monitoring by positioning specialized environmental chromatography capacity near Belgium's industrial discharge corridors. Pursue outcome-based pricing tied to regulatory certification success rates rather than per-sample transactional models. For Investors and Strategic Acquirers: The window for entry favors contract research organizations with validated dual-jurisdiction method libraries spanning EFSA and EPA frameworks. Long-term viability rests on consolidation plays that aggregate pan-European testing volumes to amortize high-resolution platform capital costs. Watch helium supply contract renegotiation cycles as inflection indicators for laboratory operating margin stress.| Strategic Initiative | Industry Significance |
|---|---|
| Helium Supply Diversification | Long-term carrier gas agreements with Algerian and Qatari suppliers reduce GC-MS operational disruption risk. |
| Multi-Residue Panel Convergence | Single-run detection of pesticides, veterinary drugs, and mycotoxins compresses per-sample costs for Eurofins-tier laboratories. |
| Software-Hardware Bundling | Integrated chromatography-software-service packages lock in multi-year relationships with guaranteed performance metrics. |
| India FSSAI Infrastructure Capture | Chromatography-mass spectrometry bundles positioned in Maharashtra and Gujarat laboratories serve export certification demand. |
| Environmental Chromatography Capacity Expansion | Belgian and Dutch contract laboratories capture REACH-driven groundwater monitoring volumes from cross-border industrial permits. |
Research Methodology
Regulatory filing databases, customs trade records for analytical instrumentation imports, and EFSA pesticide reassessment documentation formed the secondary backbone for market sizing and competitive positioning. Primary interviews with food safety laboratory directors, chromatography platform engineers at instrument manufacturers, contract research organization procurement leads, and REACH compliance officers at industrial facilities validated secondary estimates. Bottom-up triangulation across installed base counts and consumables throughput data converged with top-down expenditure analysis from national food safety agency budgets.
Bottom-up modeling of chromatography system shipments, mass spectrometer placements, and consumables volumes across product type, application, end user, and deployment configuration fed into CAGR derivation over the projection horizon. Segmentation dimensions included instrument technology tier, regulatory certification pathway, laboratory ownership structure, and geographic regulatory cluster. Industry-specific forecast inputs incorporated EFSA method redevelopment cycle timelines and FSSAI infrastructure expansion commitments.
Helium supply disruption, EFSA tolerance limit compression schedules, and REACH compliance deadline shifts are the dominant revision risks that could alter instrument replacement trajectories. Forecasts reflect documented assumptions regarding regulatory convergence patterns and technology substitution rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Lactose Assay Kit Market
Testing Equipment
Global Liquid Chromatography Systems Market
Testing Equipment
Heavy Metal Testing Market
Testing Equipment
Corrosion Testing Services Market
Testing Equipment
Laboratory Mixer Market
Testing Equipment
Solar Testing Equipment Market
Testing Equipment
Global Chromatography Instruments Market
Testing Equipment
Paint Tester Market
Testing Equipment
Liquid Chromatography Market
Testing Equipment
Chemical Reaction Monitoring Equipment Market
Testing Equipment
Elemental Analysis Market
Testing Equipment
Carbon Black Content Tester Market
Testing Equipment
Geochemical Services Market
Testing Equipment
Supercritical Fluid Chromatography Market
Testing Equipment
Global Distillate Oil Testing Service Market
Testing Equipment
Durability Testing Systems Market